
 Europe Bulk Acoustic Wave Sensors Market | 2026-2036
Europe Bulk Acoustic Wave Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Bulk Acoustic Wave Sensors Market Foresight
Automotive tier-one suppliers is unwinding legacy capacitive sensing contracts in favor of BAW-based tire pressure and engine monitoring modules. Teledyne Defense Electronics leverages its European foundry footprint to anchor military-spec resonator supply. Broadcom competes through in-house GaN integration, while Qorvo sustains RF filter dominance for 5G base station deployments.
Bulk Acoustic Wave sensors employ piezoelectric substrates—typically quartz or lithium niobate—that convert mechanical acoustic energy into electrical signals at resonant frequencies ranging from megahertz to gigahertz, enabling precise measurement of pressure, temperature, mass, and viscosity in harsh environments. Quartz sensors dominate European industrial automation for their thermal stability in furnace and pipeline installations, whereas lithium niobate variants capture expanding share in medical diagnostics due to higher electromechanical coupling coefficients for biosensing applications. Polymer sensors remain nascent but attract R&D investment for flexible wearable form factors in remote patient monitoring.
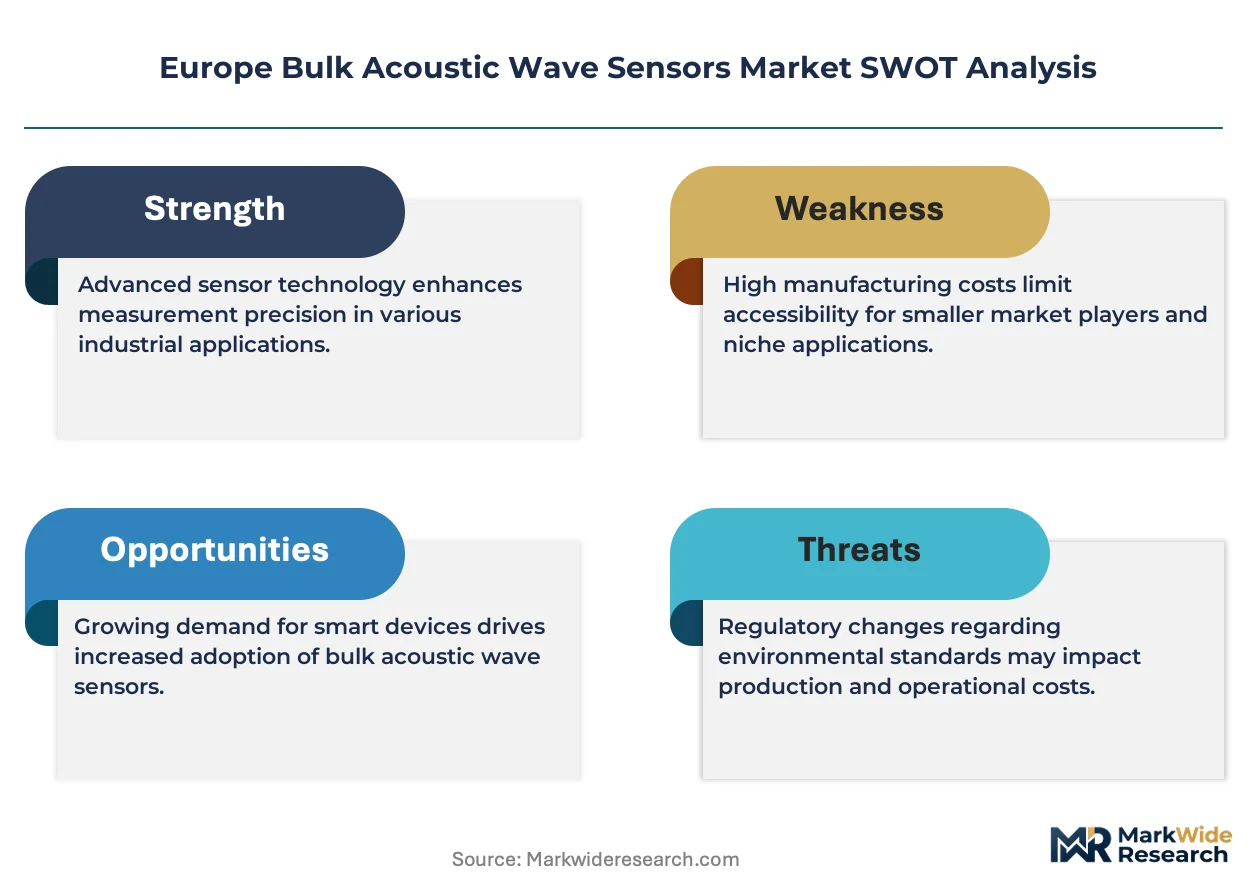
REACH and the EU Green Deal restrict hazardous substances in piezoelectric material supply chains, compelling substrate vendors to certify lead-free formulations and document full material provenance. EMA and national notified bodies enforce medical device performance standards that elevate BAW sensor accuracy requirements for in-vitro diagnostic platforms. Stakeholders must weigh certification timelines against the pace of automotive electrification and telecommunications infrastructure refresh cycles.
Market Dynamics
REACH compliance and the EU Green Deal are tightening material disclosure rules for piezoelectric substrates, forcing substrate vendors to certify lead-free formulations and document full material provenance across European supply chains.
Growth Catalysts
- Aerospace OEM procurement:German and French aerospace manufacturers are expanding orders for quartz-based BAW devices in avionics pressure sensing applications.
- Automotive electrification:Tier-one suppliers are unwinding legacy capacitive sensing contracts in favor of BAW-based tire pressure and engine monitoring modules.
- REACH material mandates:The EU's hazardous substance restrictions are accelerating certified lead-free piezoelectric substrate adoption among European component vendors.
Market Restraints
- Raw material concentration:High-purity quartz crystal supply concentrates among a limited set of certified European foundries, creating input vulnerability.
- Technical bandwidth ceilings:Lithium niobate substrates face thermal drift limitations above 500°C that constrain high-temperature industrial deployment.
- Substitution pressure:MEMS-based pressure sensors from Asian manufacturers compete on unit cost in automotive volume segments.
Strategic Opportunities
- Medical diagnostics expansion:Lithium niobate variants with higher electromechanical coupling coefficients are capturing share in European in-vitro diagnostic platforms.
- Polymer substrate R&D:Flexible polymer BAW sensors attract investment for wearable remote patient monitoring form factors in German healthcare corridors.
- 5G infrastructure refresh:RF filter demand from European telecommunications operators sustains resonator volume for base station deployments.
Industry Challenges
- EMA certification timelines:Medical device performance standards elevate BAW sensor accuracy requirements, extending approval cycles for diagnostic platform integration.
- Foundry capacity allocation:European semiconductor foundries face competing demands from automotive and telecommunications customers, constraining dedicated BAW production slots.
- Legacy system integration:Industrial automation customers in German manufacturing clusters require backward-compatible sensor interfaces, complicating new BAW module deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Bulk Acoustic Wave Sensors Market |
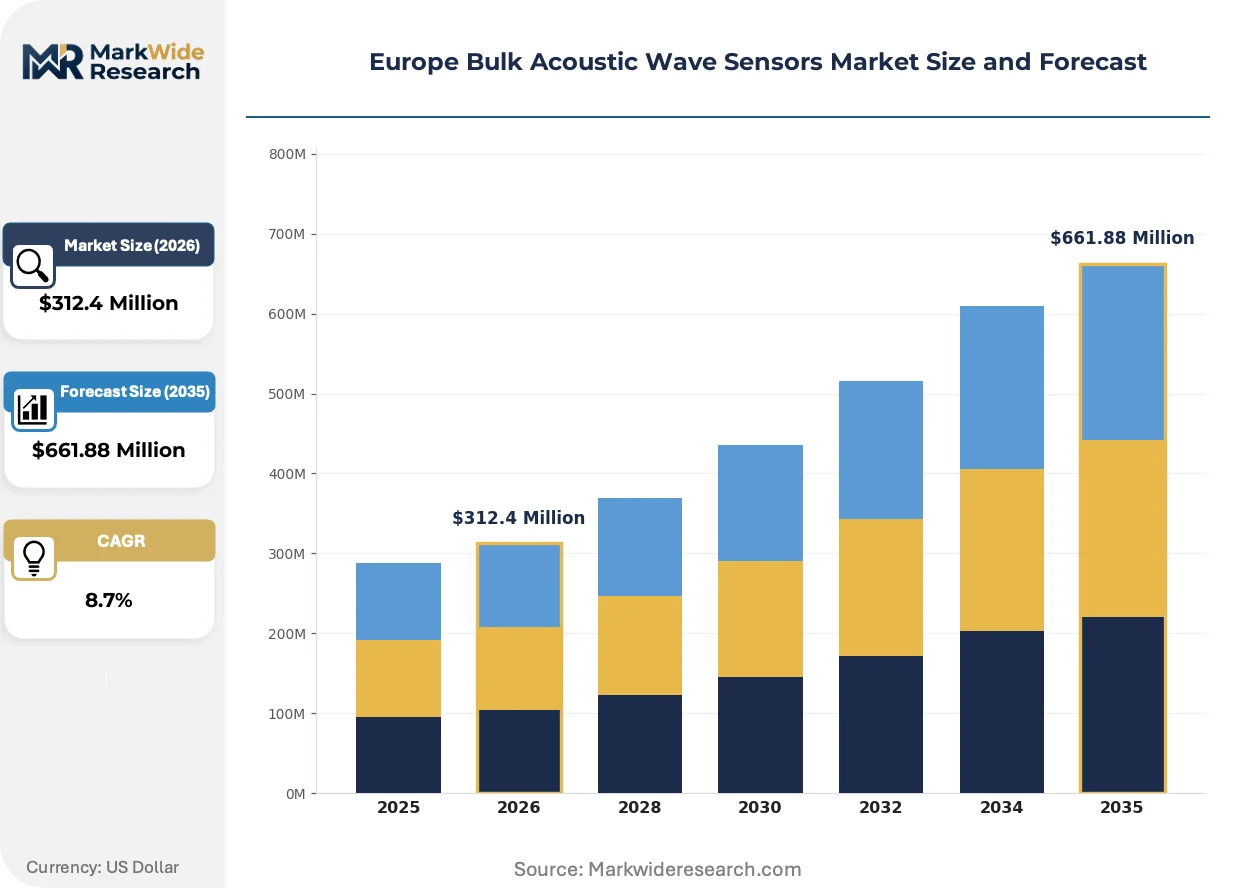
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quartz Sensors, Lithium Niobate Sensors, Polymer Sensors, Composite Sensors Application: Environmental Monitoring, Medical Diagnostics, Industrial Automation, Consumer Electronics Technology: Surface Acoustic Wave, Thickness Shear Mode, Epitaxial Wafer, Bulk Wave End User: Aerospace, Automotive, Healthcare, Telecommunications |
| Companies Covered | Teledyne Defense Electronics, Nihon Dempa Kogyo, Broadcom, Balluff, MACOM, Qorvo, Taiyo Yuden, Akoustis Technologies, Texas Instruments, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Bulk Acoustic Wave Sensors Market Shifts & Advancements
Material science advances and regulatory compliance requirements are actively restructuring how European BAW sensor manufacturers design substrates, select foundry partners, and qualify end-use applications across industrial and medical segments.
Lithium niobate thin-film processing is fragmenting traditional quartz dominance in high-frequency resonator applications. French aerospace clusters and German medical device manufacturers are adopting lithium niobate variants at accelerating pace for biosensing and precision timing. This substrate shift is fragmenting established supply relationships and creating new qualification requirements for European foundry networks.
REACH substance restrictions and the EU Green Deal's material provenance mandates are compelling substrate vendors to restructure supply chain documentation. Industrial consequence includes mandatory third-party certification for lead-free piezoelectric formulations and full lifecycle traceability. German industrial automation corridors and French aerospace manufacturing zones are responding fastest, with tier-one suppliers already demanding certified material passports from substrate vendors.
Automotive procurement patterns are compressing traditional component qualification cycles as electrification timelines accelerate. Tier-one suppliers in German automotive manufacturing zones are consolidating sensor vendor lists and demanding concurrent engineering support, displacing transactional component purchasing. This concentration is most visible in Stuttgart and Munich industrial corridors where powertrain electrification programs are driving BAW sensor specification changes.
Europe Bulk Acoustic Wave Sensors Market Segmentation
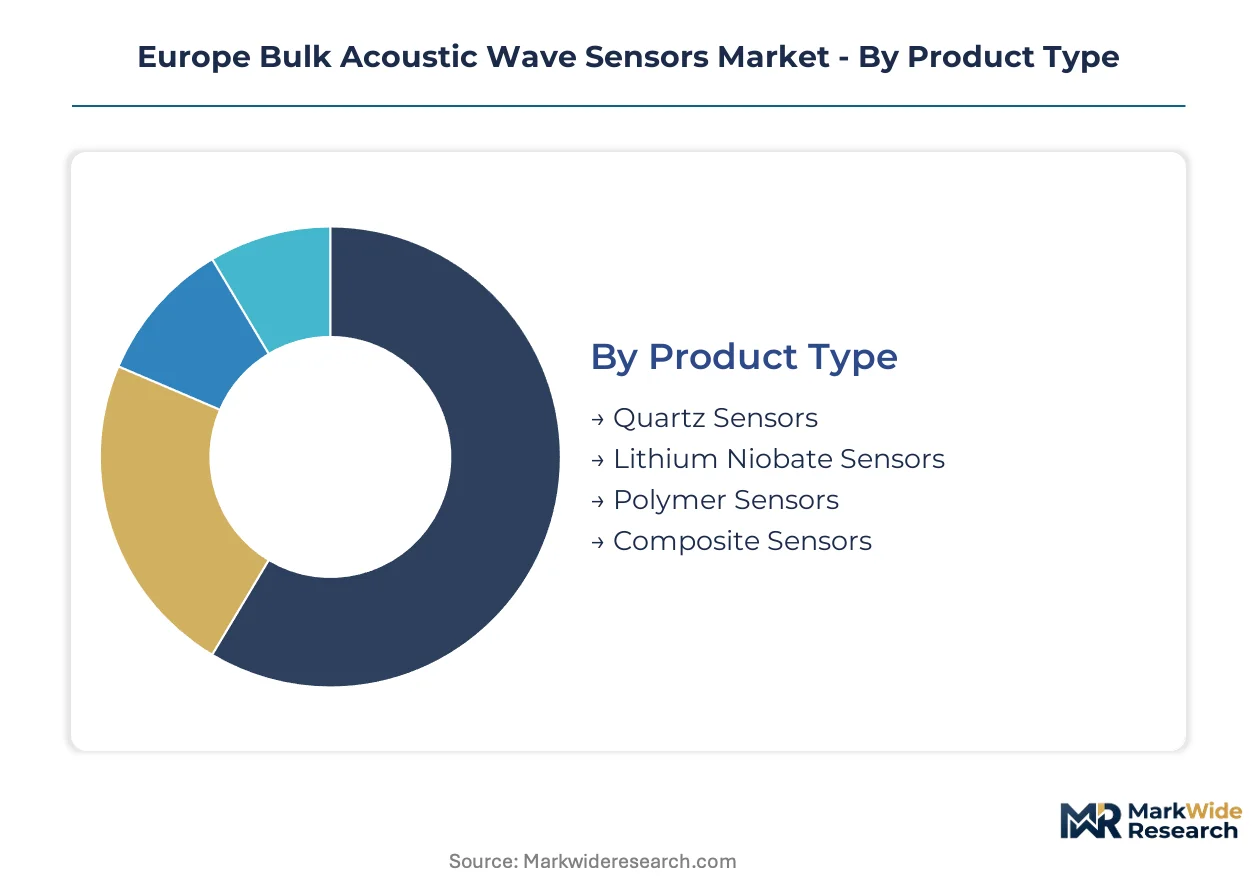
BAW sensor procurement patterns diverge sharply across substrate technologies and end-use verticals, with substitution pressures from MEMS alternatives reshaping competitive dynamics in cost-sensitive automotive tiers. Material science differentiation and regulatory compliance requirements fragment vendor positioning across European supply chains.
Product Type:
MEMS-based pressure sensors from Asian manufacturers exert the strongest substitution pressure on polymer and composite variants, while quartz and lithium niobate maintain defensible positions through thermal stability and electromechanical performance.
- Quartz Sensors:Crystalline silicon dioxide substrates deliver exceptional thermal stability across furnace and pipeline installations in German industrial automation corridors. Stuttgart manufacturing clusters specify quartz for avionics pressure sensing where drift tolerance below 0.1 ppm defines procurement criteria. REACH-certified lead-free formulations now dominate European foundry output.
- Lithium Niobate Sensors:Pyroelectric crystals with higher electromechanical coupling coefficients enable biosensing applications in French medical diagnostics clusters. Paris and Lyon device manufacturers specify lithium niobate for in-vitro diagnostic platforms requiring mass sensitivity at picogram resolution. Thermal drift above 500°C constrains deployment in high-temperature industrial settings.
- Polymer Sensors:Flexible substrates attract R&D investment for wearable remote patient monitoring in German healthcare corridors.
- Composite Sensors:Hybrid material constructions target niche applications balancing cost and performance in industrial automation.
Quartz sensors anchor the volume base while lithium niobate sensors gain share at the steepest rate.
Application:
Cost tier differentiation separates premium-certified medical diagnostics from price-pressured consumer electronics, with industrial automation occupying the intermediate margin band.
- Industrial Automation:Furnace monitoring, pipeline pressure sensing, and process control systems in German manufacturing clusters specify quartz BAW devices for thermal resilience. Munich automation OEMs demand backward-compatible sensor interfaces complicating new module deployment. ECHA substance restrictions elevate material documentation requirements.
- Medical Diagnostics:In-vitro diagnostic platforms and biosensing applications concentrate demand in French and German healthcare manufacturing zones. EMA performance standards extend approval cycles for diagnostic platform integration. Lithium niobate variants capture expanding specification share.
- Environmental Monitoring:Air quality and water treatment sensors deploy across European industrial zones with REACH compliance mandates.
- Consumer Electronics:Smartphone and wearable integration faces intense MEMS substitution pressure on unit economics.
Industrial automation commands the largest revenue pool while medical diagnostics expands most quickly.
Technology:
Foundry capacity allocation across European semiconductor networks concentrates Thickness Shear Mode and Bulk Wave production, while Surface Acoustic Wave competes for wafer starts.
- Thickness Shear Mode:Resonant frequency operation in the megahertz to gigahertz range enables precise pressure and temperature measurement in harsh environments. German aerospace manufacturers specify TSM architecture for avionics pressure sensing requiring frequency stability under mechanical stress. Teledyne Defense Electronics anchors European foundry supply.
- Bulk Wave:Fundamental acoustic mode propagation delivers highest Q-factor performance for telecommunications RF filter applications. 5G base station deployments across European networks sustain resonator volume demand. Broadcom and Qorvo compete through substrate integration strategies.
- Surface Acoustic Wave:Interdigital transducer configurations target lower frequency applications with reduced fabrication complexity.
- Epitaxial Wafer:Thin-film deposition processes enable lithium niobate integration on silicon substrates for hybrid device architectures.
Bulk Wave technology secures the dominant volume position while Thickness Shear Mode climbs the fastest.
End User:
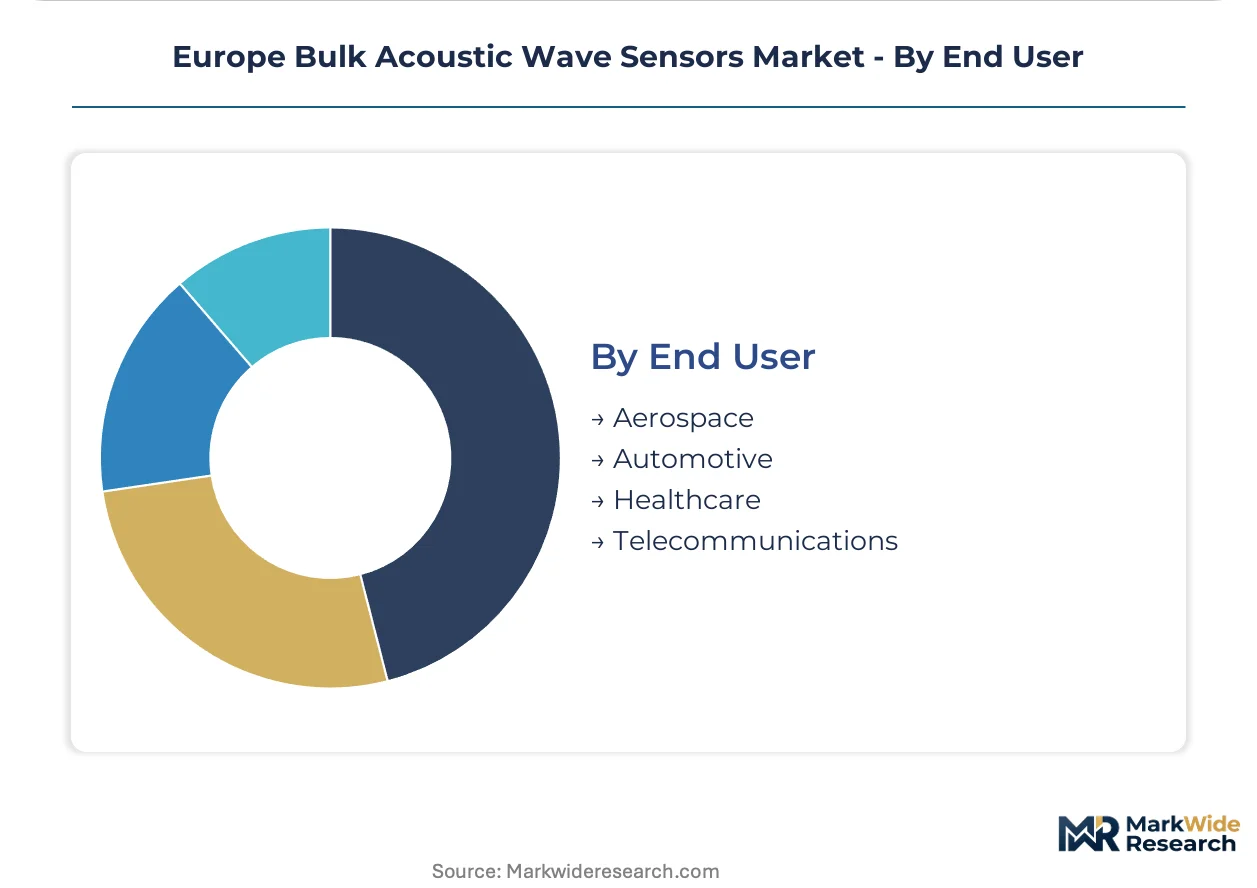
Customer type concentration in German automotive and French aerospace creates procurement leverage, while telecommunications operators sustain RF filter demand through infrastructure refresh cycles.
- Aerospace:Avionics pressure sensing and precision timing applications concentrate procurement among German and French OEMs expanding quartz BAW orders. Toulouse and Hamburg manufacturing clusters specify certified material passports from substrate vendors. EU Green Deal provenance mandates accelerate supplier consolidation.
- Automotive:Tire pressure monitoring and powertrain sensing drive tier-one supplier migration from capacitive to BAW-based modules. Stuttgart and Munich electrification programs compress component qualification timelines. Concurrent engineering support demands displace transactional purchasing.
- Healthcare:Diagnostic platform manufacturers in German and French medical device corridors specify lithium niobate for biosensing accuracy.
- Telecommunications:5G base station operators across European markets sustain resonator demand for RF filter deployment.
Automotive anchors the volume base while aerospace gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central European industrial sensor distribution, connecting Bavarian manufacturing clusters to North Sea ports and Black Sea markets. This infrastructure backbone positions Germany as the primary demand anchor, with France, Italy, the United Kingdom, and Switzerland forming secondary concentration zones. Each national market exhibits distinct procurement patterns tied to aerospace, automotive, and medical device specialization.
Germany
Stuttgart and Munich automotive electrification programs compress BAW sensor qualification timelines for tire pressure and powertrain monitoring modules. ECHA substance restrictions mandate certified lead-free piezoelectric formulations across supplier networks. The Baden-Württemberg industrial corridor concentrates quartz BAW procurement for furnace and pipeline installations requiring thermal stability below 0.1 ppm drift tolerance.
France
Toulouse aerospace manufacturing clusters expand quartz-based BAW orders for avionics pressure sensing applications in next-generation aircraft programs. EU Green Deal material provenance mandates accelerate supplier consolidation among substrate vendors. Lyon and Paris medical device manufacturers specify lithium niobate variants for in-vitro diagnostic platforms requiring picogram-scale mass sensitivity.
Italy
Lombardy-based industrial automation OEMs integrate BAW sensors into process control systems for European manufacturing export markets. CE marking and MDR compliance frameworks elevate performance documentation requirements for sensor module suppliers. The Emilia-Romagna machinery corridor demands backward-compatible interfaces complicating new BAW deployment in legacy installations.
United Kingdom
Scottish aerospace supply chains source certified quartz resonators for defense avionics programs requiring military-spec performance standards. UKCA marking transitions post-Brexit create parallel certification pathways for substrate vendors serving British OEMs. Greater London telecommunications infrastructure operators sustain RF filter demand through 5G base station refresh cycles.
Switzerland
Swiss precision instrument manufacturers in the Zurich-Basel corridor specify high-Q BAW resonators for timing and frequency control applications. Swissmedic medical device standards align with EMA requirements, streamlining diagnostic platform approvals for lithium niobate biosensing modules. The country's pharmaceutical equipment export sector drives premium-tier sensor procurement for cleanroom manufacturing environments.
Europe Bulk Acoustic Wave Sensors Market Competitive Landscape
Concentration sits with diversified semiconductor conglomerates and defense-electronics specialists rather than pure-play BAW fabricators. The vendor base stratifies across three tiers: integrated device manufacturers with captive substrate capabilities, European foundry-anchored defense suppliers, and fabless design houses outsourcing resonator production. Strategic moves center on foundry capacity allocation contests and concurrent engineering partnerships with automotive tier-ones.
Among defense-electronics specialists, Teledyne Defense Electronics exemplifies the European foundry-anchored archetype, leveraging continental fabrication assets for military-spec resonator supply. Broadcom and Qorvo represent integrated device manufacturers competing through substrate integration strategies and RF filter portfolio breadth. These three companies occupy positions across the telecommunications infrastructure and aerospace procurement vectors, with each anchoring distinct competitive positioning in 5G base station and avionics sensing applications.
| Leading Market Players |
|---|
| Teledyne Defense Electronics |
| Nihon Dempa Kogyo |
| Broadcom |
| Balluff |
| MACOM |
| Qorvo |
| Taiyo Yuden |
| Akoustis Technologies |
| Texas Instruments |
| Others |
Supply & Pricing Matrix
Foundry utilization rates above 85 percent across German and French semiconductor fabrication networks concentrate substrate pricing power among a limited set of certified European suppliers. This scale concentration elevates price floors for quartz and lithium niobate wafers while compressing margins for fabless design houses competing on resonator integration.
Pricing Analysis
Volume-discount tiering structures separate aerospace procurement bundles from automotive spot purchasing, with telecommunications operators occupying intermediate contract positions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and REACH documentation completeness. Cost compression in automotive tiers intensifies because MEMS substitution from Asian manufacturers erodes unit economics. Tier-one automotive suppliers exhibit highest price sensitivity, whereas Swiss precision instrument manufacturers accept premium positioning for medical-grade material passports.
Supply Chain Analysis
Germany and France anchor high-purity quartz crystal production for avionics and industrial automation applications, while Switzerland concentrates precision resonator finishing operations. Raw material flows draw from Nordic mining operations for silicon dioxide feedstock and Japanese suppliers for lithium niobate ingots. Single-source vulnerability concentrates in certified lead-free substrate formulations where REACH compliance documentation creates qualification bottlenecks. Distribution runs through Rhine-Main-Danube waterway corridors connecting Bavarian manufacturing clusters to North Sea ports and Black Sea markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among German automotive tier-ones and French aerospace OEMs shifts bargaining power toward buyers with volume commitment leverage. This concentration fragments supplier pricing autonomy across substrate and resonator tiers.
For Market Incumbents: Secure captive quartz substrate supply through backward integration into Nordic mining partnerships or long-term offtake agreements with certified European foundries. Defend against MEMS substitution in automotive volume segments by embedding concurrent engineering teams within Stuttgart and Munich electrification programs. Certification investment in REACH-compliant lead-free formulations represents the critical retention lever for aerospace procurement contracts.
For New Entrants and Emerging Players: Differentiate on lithium niobate thin-film processing capabilities for French medical diagnostics corridors where picogram-scale mass sensitivity commands specification premium. Target polymer substrate R&D partnerships with German healthcare wearable manufacturers as the most penetrable white-space segment. Go-to-market execution should anchor in EMA regulatory consulting bundled with sensor module supply to compress approval timelines for diagnostic platform integration.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors European foundry-anchored defense suppliers with military-spec qualification depth and telecommunications RF filter exposure. Long-term viability across the projection horizon rests on substrate material flexibility and concurrent engineering service capabilities. The signal to watch is automotive tier-one supplier consolidation events that displace transactional component vendors from approved supplier lists.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Substrate Certification | Mandatory material passports from ECHA-registered vendors unlock aerospace procurement eligibility. |
| Concurrent Engineering Partnership | Embedded technical support with Stuttgart automotive OEMs compresses qualification cycles for electrification programs. |
| Lithium Niobate Thin-Film Scale-Up | Paris and Lyon diagnostic manufacturers specify higher electromechanical coupling for biosensing platforms. |
| Rhine-Main-Danube Logistics Optimization | Waterway distribution reduces transit friction for Bavarian manufacturing cluster supply. |
| Telecommunications RF Filter Expansion | 5G base station refresh cycles across European operators sustain resonator volume demand. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ECHA substance registration databases, EU customs trade records, and semiconductor foundry capacity disclosures. Primary interviews engaged substrate procurement managers at German automotive tier-ones, regulatory affairs leads at French medical device manufacturers, and resonator design engineers at European defense electronics suppliers. Secondary validation drew from EMA medical device filings, CE marking certification registries, and telecommunications infrastructure deployment announcements. Bottom-up sensor unit demand estimates triangulate against top-down substrate wafer consumption figures across the analysis window.
Segmentation dimensions modeled include substrate technology type, end-use vertical application, resonator architecture, and national regulatory compliance cluster. CAGRs derive from fitted growth curves applied to historical procurement patterns and forward-projected electrification and infrastructure refresh timelines. Industry-specific forecast inputs incorporate REACH substance restriction phase-in schedules and EMA diagnostic platform approval cycle durations throughout the forecast period.
The analysis sits within stated boundaries; outcomes outside sustained automotive electrification momentum or telecommunications infrastructure investment levels would require recalibration. Forecasts reflect documented assumptions regarding substrate supply expansion and regulatory compliance timeline adherence. Specific risk factors include lithium niobate thermal drift constraints above 500°C and MEMS substitution acceleration in cost-sensitive automotive tiers. Recalibration cycles align with material shifts in EU Green Deal provenance mandate enforcement and automotive OEM supplier consolidation events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Anemometer Market
Sensors and Controls
Off-Highway Machine Position and Angle Sensor Components Market
Sensors and Controls
Environmental Noise Cancellation Microphones Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
United States Gas Sensors Market
Sensors and Controls
High-Voltage Isolation and Leakage Sensor Components Market
Sensors and Controls
Wireless Ph Monitoring Systems Market
Sensors and Controls
Magnetometer Sensor Market
Sensors and Controls
Europe Digital Thermometer Market
Sensors and Controls
Control Knobs for Panel Potentiometer Market
Sensors and Controls
Europe Human Machine Interface Market
Sensors and Controls
Global Multi-Turn Potentiometer Market
Sensors and Controls
Reservoir Monitoring System Market
Sensors and Controls
Biopotential Sensor Market
Sensors and Controls
United States Scintillator Market
Sensors and Controls
Infrared Sensors Market