
 Electronic Wipe Market | 2026-2036
Electronic Wipe Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Wipe Market Insights
ISO 14644 cleanroom certification is collapsing the supplier base for electronics-grade wipes, disqualifying commodity converters that lack particulate-controlled manufacturing. Techspray leverages its aerospace-derived contamination control protocols to anchor North American supply for precision electronics. Henkel AG competes through adhesive chemistry expertise that extends into specialty wipe coatings for sensitive displays. 3M Company dominates high-purity substrate development with captive nonwoven manufacturing that sustains consistent lot-to-lot performance.
Electronic wipes are engineered nonwoven or woven substrates, typically polyester or microfiber constructions with controlled basis weights between 50-150 gsm, designed to remove particulates, oils, and ionic residues from sensitive electronic surfaces without generating static or leaving fibrous debris. Pre-moistened formulations incorporate semiconductor-grade isopropyl alcohol or deionized water solutions filtered to sub-micron purity levels. Dry wipe demand leads volume in industrial machinery maintenance where operators perform frequent degreasing of control panels and sensors. Wet wipe formulations represent the fastest-expanding margin pool as medical equipment manufacturers adopt single-use sterile protocols for endoscope housings and diagnostic housings. Antibacterial wipes remain mature in consumer electronics retail channels where price competition compresses differentiation opportunities.
EPA regulates volatile organic compound emissions from wipe-impregnated solvents under 40 CFR 59, forcing reformulation of alcohol-based products toward lower-VOC alternatives. REACH restricts perfluorinated compounds and certain glycol ethers used in legacy electronic cleaning formulations, reshaping European supplier chemistries and import compliance burdens. FDA device sanitation requirements for medical equipment wipes create parallel qualification pathways that overlap with electronics-grade standards. Stakeholders must monitor evolving dual-use classification thresholds where medical and electronics wipe specifications converge, as this boundary determines which qualification investments unlock adjacent revenue pools.
Market Dynamics
ISO 14644 cleanroom certification requirements are collapsing the supplier base for electronics-grade wipes, disqualifying commodity converters that lack particulate-controlled manufacturing environments and forcing consolidation around qualified substrate producers.
Growth Catalysts
- Semiconductor Fab Expansion:Taiwan and South Korea fabs are expanding procurement of pre-moistened polyester wipes for advanced node cleanroom protocols, creating sustained demand pull for contamination control substrates.
- REACH Chemical Restrictions:ECHA restrictions on perfluorinated compounds and certain glycol ethers are pushing European manufacturers toward water-based and isopropyl alcohol formulations, opening reformulation service revenue.
- Medical-Electronics Convergence:FDA device sanitation requirements for diagnostic equipment housings are creating dual-use qualification pathways that overlap with electronics-grade standards.
Market Restraints
- Substrate Concentration Risk:Captive nonwoven manufacturing by dominant substrate developers limits second-source availability for precision electronics converters.
- VOC Compliance Friction:EPA 40 CFR 59 regulations on volatile organic compound emissions from wipe-impregnated solvents force costly reformulation of alcohol-based products.
- Technical Performance Ceiling:Static control limitations in legacy polyester constructions constrain adoption in next-generation flexible electronics assembly.
Strategic Opportunities
- Underpenetrated Medical Equipment:Endoscope and diagnostic housing manufacturers in Germany and Switzerland are adopting single-use sterile protocols, expanding addressable market for qualified wipe suppliers.
- Channel Innovation:Direct procurement platforms are disintermediating industrial distributors for high-volume electronics manufacturers, compressing margin capture by intermediaries.
- EU Green Deal Alignment:Biodegradable substrate development aligned with EU circular economy mandates creates preferential positioning for sustainability-certified suppliers.
Industry Challenges
- Certification Timeline Compression:ISO 14644-1 cleanroom validation cycles extend 18-24 months, delaying new entrant qualification for semiconductor supply chains.
- Capex Intensity for Particulate Control:HEPA filtration and laminar flow infrastructure requirements for electronics-grade manufacturing demand substantial facility investment.
- Cross-Border Compliance Complexity:Divergent EPA, REACH, and emerging MEE chemical restrictions require parallel formulation tracks for multi-regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Wipe Market |
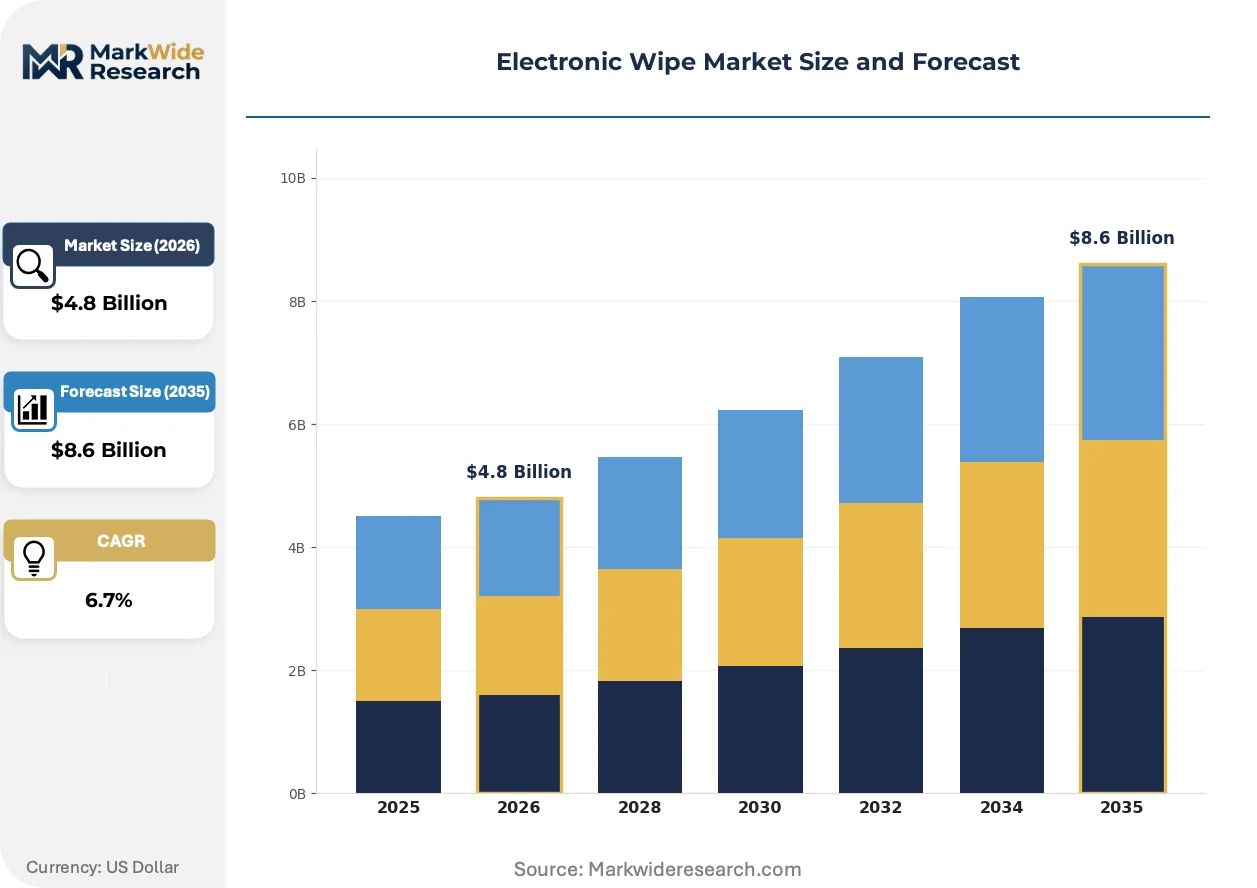
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Wipe, Wet Wipe, Pre-moistened Wipe, Antibacterial Wipe Material: Polyester, Cotton, Microfiber, Viscose Application: Consumer Electronics, Medical Equipment, Industrial Machinery, Automotive Packaging Type: Single Pack, Bulk Pack, Canister, Dispenser |
| Companies Covered | 3M Company, Techspray, Illinois Tool Works Inc., Henkel AG, Antec, Inc., iCloth, Weiman Products, LLC, Georgia-Pacific LLC, Essentra plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Wipe Market Trends and Innovations
Substrate engineering and regulatory chemistry are converging to reshape competitive positioning, with contamination control protocols migrating from aerospace heritage into precision electronics applications.
Microfiber constructions with sub-micron filament diameters are supplanting traditional polyester wipes in display panel manufacturing. Korean and Taiwanese OLED producers are adopting these substrates for edge-deposition cleaning. The shift is compressing market share for commodity nonwoven converters lacking fine-denier spinning capabilities.
REACH restrictions on perfluorinated compounds are forcing solvent formulation changes across European electronics manufacturing. Industrial consequence includes accelerated qualification of aqueous and isopropyl alcohol alternatives. German automotive electronics suppliers are most affected, with reformulation timelines compressed to maintain CE marking compliance.
Single-use sterile protocols are displacing reusable cleaning systems in medical equipment manufacturing. Original equipment manufacturers are unbundling after-sales service contracts to specify qualified wipe suppliers directly. This pattern is most visible in Swiss and German diagnostic equipment clusters where FDA and MDR dual qualification is becoming standard.
Electronic Wipe Market Segmentation
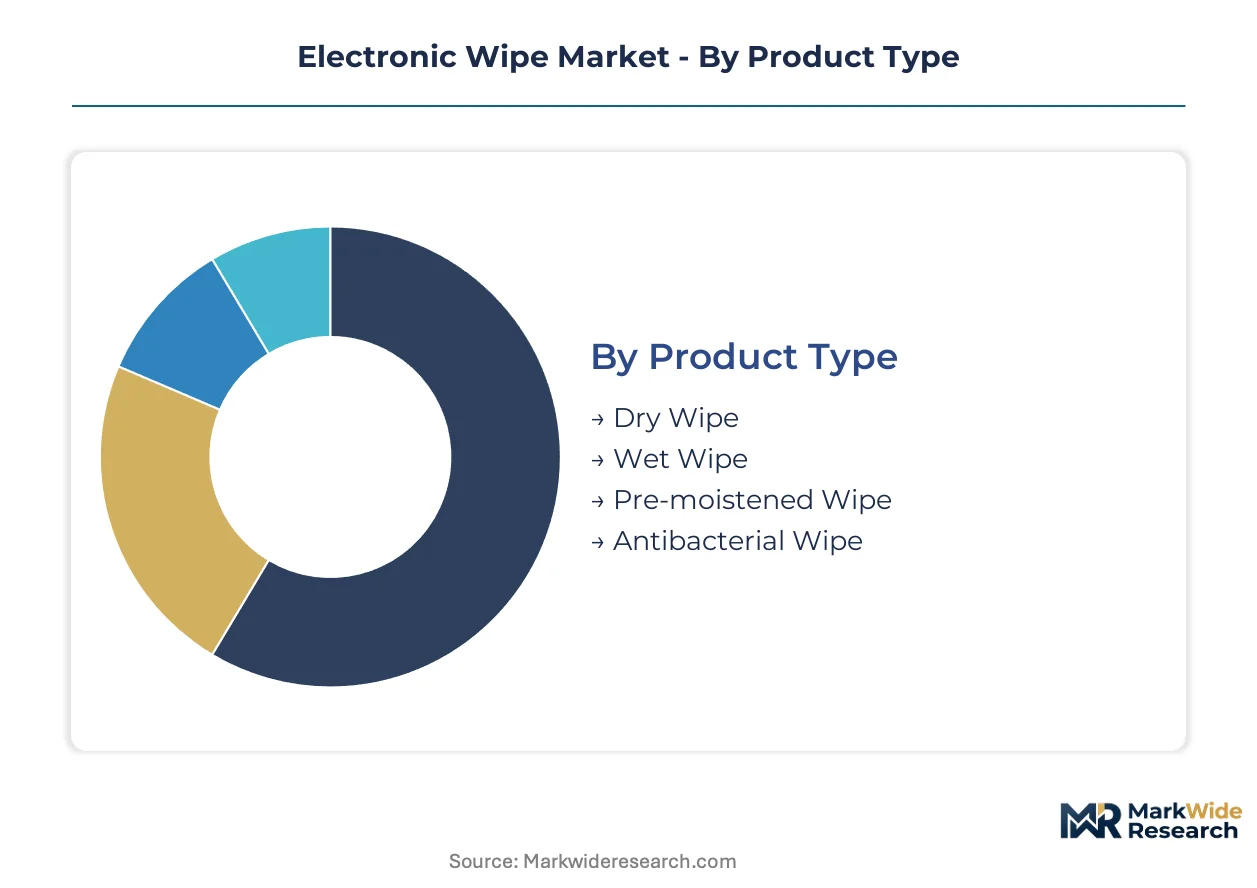
Segmentation in electronic wipes reveals how substrate chemistry, moisture content, and packaging format determine qualification pathways for distinct end-use environments. Each category carries different margin profiles and regulatory exposure that reshape supplier priorities.
Product Type:
Dry wipes dominate domestic procurement for industrial maintenance, while pre-moistened formats drive export-led growth into semiconductor manufacturing clusters.
- Dry Wipe:Unimpregnated polyester or microfiber substrates engineered for operator-controlled solvent application. Demand concentrates in German and US automotive electronics facilities where technicians perform frequent degreasing of control panels and sensors without moisture-sensitive component risk.
- Pre-moistened Wipe:Substrates impregnated with semiconductor-grade isopropyl alcohol or deionized water filtered to sub-micron purity. Taiwanese and South Korean fabs are expanding procurement for advanced node cleanroom protocols, creating sustained demand pull for contamination control substrates with validated lot-to-lot consistency.
- Wet Wipe:Higher moisture content formulations for heavy residue removal in post-assembly cleaning.
- Antibacterial Wipe:Biocidal formulations for surface sanitation in shared device environments.
Dry wipes hold the largest share; momentum sits with pre-moistened formats.
Material:
Cost tiers separate commodity natural fibers from engineered synthetics with certified particulate control.
- Polyester:Spunbond or hydroentangled constructions with controlled basis weights between 50-150 gsm. ISO 14644 cleanroom certification requirements are collapsing the supplier base for electronics-grade polyester, disqualifying commodity converters that lack particulate-controlled manufacturing environments.
- Microfiber:Sub-micron filament diameters below 1 denier that trap particulates through mechanical action rather than chemical binding. Korean and Taiwanese OLED producers are adopting these substrates for edge-deposition cleaning, compressing market share for commodity nonwoven converters lacking fine-denier spinning capabilities.
- Cotton:Natural fiber for non-critical cleaning where lint generation is acceptable.
- Viscose:Regenerated cellulose with high absorbency for aqueous formulations.
Polyester commands volume leadership; microfiber is climbing the fastest on display panel adoption.
Application:
Customer type determines whether procurement flows through industrial distributors or direct specification by original equipment manufacturers.
- Consumer Electronics:Retail and post-purchase cleaning for smartphones, laptops, and peripherals. Price competition compresses differentiation opportunities in this mature channel where antibacterial wipes dominate shelf placement.
- Medical Equipment:Single-use sterile protocols for endoscope housings and diagnostic equipment. Swiss and German diagnostic equipment clusters are unbundling after-sales service contracts to specify qualified wipe suppliers directly, with FDA and MDR dual qualification becoming standard.
- Industrial Machinery:Control panel and sensor maintenance in manufacturing environments.
- Automotive:Infotainment and ADAS component cleaning during assembly and service.
Consumer electronics holds the largest share; medical equipment is gaining share fastest on regulatory convergence.
Packaging Type:
Volume scale separates high-throughput manufacturing procurement from intermittent retail consumption.
- Bulk Pack:Large-format packaging for high-volume electronics manufacturers with established cleanroom protocols. Direct procurement platforms are disintermediating industrial distributors for these customers, compressing margin capture by intermediaries.
- Canister:Resealable containers with saturated substrate stacks for point-of-use access. Medical equipment manufacturers in Germany and Switzerland specify canister formats for endoscope reprocessing stations where single-use sterile protocols displace reusable cleaning systems.
- Single Pack:Individual sachets for field service and travel applications.
- Dispenser:Wall-mounted or benchtop units for controlled consumption in production environments.
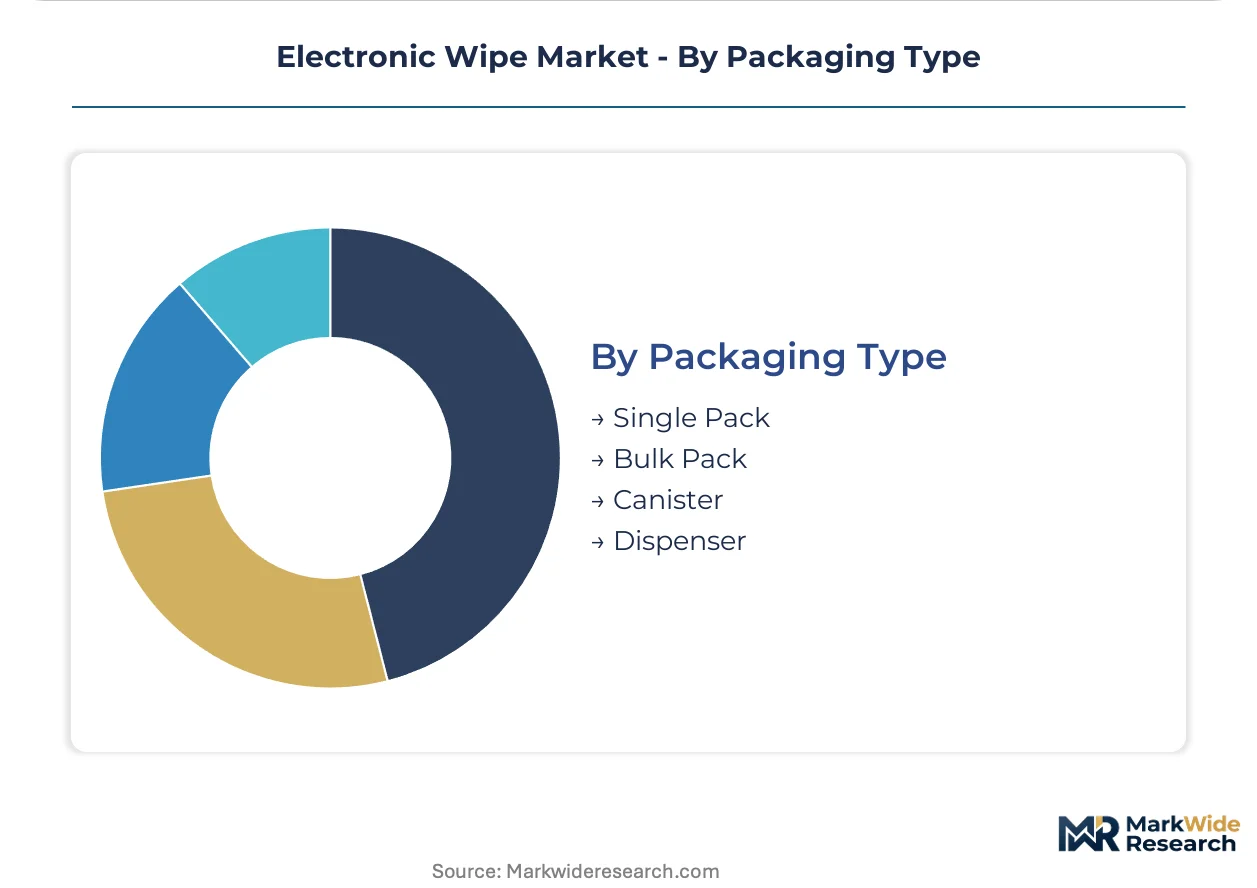
Bulk packs hold the largest share; canisters show the steepest expansion trajectory on medical adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor fabs and medical equipment manufacturers concentrate procurement in East Asian electronics clusters and Central European precision manufacturing corridors. Taiwan and South Korea dominate advanced node cleanroom demand. Germany and Switzerland anchor medical-electronics dual qualification requirements. The United States sustains aerospace-derived contamination control protocols.
Taiwan
TSMC and UMC fabs drive pre-moistened polyester wipe procurement for sub-7nm cleanroom protocols. The National Development Council subsidizes domestic supply chain localization for contamination control materials. Hsinchu Science Park hosts the densest concentration of ISO 14644-1 certified wipe suppliers serving semiconductor backend processes.
South Korea
Samsung Foundry and SK Hynix expansion at Pyeongtaek and Yongin sustains demand for sub-micron purity substrates. MFDS medical device regulations overlap with electronics-grade standards for diagnostic equipment housings. Seoul metropolitan area suppliers qualify simultaneously for semiconductor and medical OEM specifications.
Germany
Automotive electronics and diagnostic equipment manufacturers adopt REACH-compliant aqueous formulations. ECHA restrictions on perfluorinated compounds force reformulation of legacy solvent-impregnated products. Munich-Stuttgart corridor suppliers serve both automotive infotainment and medical device clusters with dual-qualified substrates.
United States
Aerospace and defense contractors anchor demand for contamination control protocols migrating into precision electronics. EPA 40 CFR 59 VOC regulations push alcohol-based product reformulation toward lower-emission alternatives. Greater Boston and Pacific Northwest cleanroom infrastructure supports satellite and semiconductor equipment manufacturing.
Switzerland
Swissmedic and FDA dual qualification requirements shape procurement for diagnostic equipment manufacturers. Roche and Siemens Healthineers specify single-use sterile protocols for endoscope reprocessing stations. Basel-Zurich corridor suppliers specialize in medical-electronics convergence applications with validated lot-to-lot consistency.
Electronic Wipe Market Competitive Landscape
Player mix skews toward diversified materials conglomerates with captive nonwoven manufacturing and specialized contamination control specialists with aerospace heritage. Three archetypes dominate: substrate-integrated conglomerates controlling upstream fiber production, precision cleaning specialists leveraging cleanroom certification barriers, and medical device suppliers extending into electronics-grade specifications. Capacity expansion and strategic partnerships represent the primary competitive vectors as qualification timelines stretch 18-24 months.
Among diversified materials conglomerates, 3M Company and Henkel AG exemplify substrate-integrated positioning with in-house control over fiber development and coating chemistry. Techspray occupies a specialist tier leveraging aerospace-derived protocols for North American precision electronics supply. Illinois Tool Works Inc. represents the industrial diversified archetype with cross-segment contamination control capabilities spanning automotive and medical end-uses.
| Leading Market Players |
|---|
| 3M Company |
| Techspray |
| Illinois Tool Works Inc. |
| Henkel AG |
| Antec, Inc. |
| iCloth |
| Weiman Products, LLC |
| Georgia-Pacific LLC |
| Essentra plc |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four month ISO 14644-1 validation cycles concentrate supply-side leverage among qualified substrate producers, translating certification scarcity into sustained pricing power for electronics-grade wipe manufacturers serving Taiwanese and South Korean semiconductor fabs.
Pricing Analysis
Cost-plus contracts with polyester fiber indexation dominate procurement between substrate-integrated conglomerates and high-volume electronics manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 14644-1 certified suppliers from commodity converters lacking particulate-controlled manufacturing. Pricing pressure stems from REACH-compliant reformulation costs as European manufacturers absorb ECHA restrictions on perfluorinated compounds. Consumer electronics retail channels exhibit highest price sensitivity, while medical equipment manufacturers prioritize lot-to-lot consistency over unit economics.
Supply Chain Analysis
Fine-denier microfiber spinning capacity in South Korea, Taiwan, and Japan anchors substrate supply for display panel manufacturers adopting sub-micron filament constructions. Supply chains draw from semiconductor-grade isopropyl alcohol feedstocks and hydroentangled nonwoven roll goods. Single-source vulnerability concentrates in captive nonwoven manufacturing by dominant substrate developers. Distribution runs through direct procurement platforms disintermediating industrial distributors for bulk-pack customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic wipe market fragmentation creates entry niches as medical-electronics convergence splinters qualification requirements across FDA, MDR, and ISO 14644-1 standards, rewarding specialized contamination control specialists over diversified materials conglomerates.
For Market Incumbents: Compound certification barriers by extending ISO 14644-1 validation into medical device dual-qualification pathways before emerging substrate developers close capability gaps. Add captive microfiber spinning capacity in East Asian electronics clusters to defend against Korean and Taiwanese OLED producers backward integrating into substrate supply.
For New Entrants and Emerging Players: Lead with biodegradable substrate development aligned with EU Green Deal circular economy mandates, targeting Swiss and German diagnostic equipment manufacturers unbundling after-sales service contracts. White-space opportunity concentrates in canister-format sterile protocols for endoscope reprocessing stations where FDA and MDR dual qualification remains underpenetrated.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because ISO 14644-1 validation timelines and HEPA filtration capex requirements structurally prevent rapid supply-base expansion. Target mid-cap contamination control specialists with aerospace heritage and existing cleanroom infrastructure. Watch MFDS medical device regulation harmonization with electronics-grade standards as inflection signal for medical-electronics convergence acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 14644-1 Certification Investment | Validates particulate-controlled manufacturing for TSMC and Samsung Foundry supply qualification. |
| Biodegradable Substrate Development | Aligns with EU Green Deal mandates to capture preferential positioning in German automotive electronics. |
| Direct Procurement Platform Launch | Disintermediates industrial distributors for high-volume electronics manufacturers in Shenzhen cluster. |
| Medical-Electronics Dual Qualification | Unlocks Roche and Siemens Healthineers specifications through FDA and MDR standard convergence. |
| Microfiber Spinning Capacity Addition | Supplies sub-micron filament substrates for Korean and Taiwanese OLED edge-deposition cleaning. |
Research Methodology
Initial hypotheses were tested against primary input from cleanroom operations managers, semiconductor procurement leads, medical device quality directors, and nonwoven substrate R&D heads, and refined through secondary validation against SEC 10-K filings, ECHA restriction updates, FDA device sanitation guidance, and customs trade data for polyester nonwoven imports. Bottom-up segment sizing triangulated with top-down market reconstruction across substrate chemistry, moisture content, and packaging format dimensions.
Variance decomposition structured the analytical framework across the projection horizon, with CAGRs derived from segment-level elasticity modeling against semiconductor fab capital expenditure cycles and medical equipment sterilization protocol adoption curves. Segmentation dimensions included product type, material construction, end-use application, and regional regulatory cluster. Forecast inputs incorporated REACH chemical restriction timelines and EPA 40 CFR 59 VOC compliance trajectories.
The analysis sits within stated boundaries; outcomes outside sustained semiconductor node advancement or abrupt regulatory divergence between FDA and MDR standards would require recalibration. Forecasts reflect documented assumptions regarding cleanroom certification timeline stability and substrate concentration persistence. Practitioners should keep alternative scenarios live as ECHA perfluorinated compound restrictions and MEE emerging chemical standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Asia-Pacific USB Retimer Market
Electronic Components
Electric Vehicle (EV) Electronic Components Market
Electronic Components
Digital Pulse Mixer Market
Electronic Components
Cordless Phone Battery Market
Electronic Components
Data Acquisition Hardware Market
Electronic Components
IF Digital Attenuator Market
Electronic Components
Radiation Hardened Electronics Market
Electronic Components
5G Base Station BAW Filters Market
Electronic Components
Data Bus Market
Electronic Components
Electronic Shelf Label Market
Electronic Components
US Frequency Control and Timing Devices Market
Electronic Components
Microcontroller Socket Market
Electronic Components
Dual Relay Board Market
Electronic Components
Pneumatic Components Market
Electronic Components
Wireless Charging Stand Market
Electronic Components
Coaxial Coupler Market