
 Semiconductor Micro Components Market | 2026-2036
Semiconductor Micro Components Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Micro Components Market Outlook
Project finance for advanced foundry builds is reconfiguring competitive entry barriers across the semiconductor micro components landscape. TSMC leverages government-backed capital pools to sustain multi-billion-dollar fab commitments in Arizona and Japan. Samsung Electronics anchors its position through captive memory-to-logic integration. Intel competes via process-technology leadership in advanced nodes while navigating capital intensity demands.
Semiconductor micro components are miniature electronic elements—resistors, capacitors, inductors, and diodes—fabricated through thin-film deposition, photolithography, and precision etching to manage current, voltage, and signal integrity in circuits. These devices operate across analog, digital, mixed-signal, and power technologies to enable embedded systems, signal processing, power management, and networking functions. Capacitors lead volume demand due to ubiquity in decoupling and energy storage roles, while mixed-signal technology captures expanding margin pools at analog-digital boundaries. Power technology segments are accelerating fastest as electric vehicles and renewable energy inverters multiply high-voltage switching requirements.
The EPA enforces hazardous substance restrictions affecting component material selection in the United States, while REACH and RoHS in Europe mandate substance transparency and restricted chemical thresholds for market access. Japan's METI coordinates supply chain resilience policies that shape procurement security for automotive and industrial buyers. Stakeholders must monitor how dual-use export controls and carbon-border adjustments restructure sourcing economics for critical micro component categories.
Market Dynamics
Automotive electrification and renewable energy expansion are compressing design cycles for power-dense micro components while foundry concentration in East Asia locks in supply-side leverage. Tier-1 suppliers now face qualification timelines that outpace traditional automotive development schedules.
Growth Catalysts
- EU Green Deal industrial mandates:Battery-electric vehicle production quotas in Germany and France are multiplying demand for high-voltage capacitors and gate drivers in traction inverters.
- Thin-film passive integration:Embedded dielectric processes are shrinking component footprints for wearable medical devices and AR headsets.
- Taiwan-Japan packaging corridor:Advanced substrate capacity concentration is accelerating flip-chip and fan-out wafer-level package adoption for 5G mmWave modules.
Market Restraints
- Palladium and ruthenium price volatility:Thin-film electrode materials face supply pressure from South African mining concentration and automotive catalyst competition.
- 300mm silicon wafer tightness:Foundry allocation priority for logic ICs is constraining analog and power discrete substrate availability.
- REACH substance authorization delays:ECHA screening of novel dielectric chemistries extends qualification timelines by 18-24 months for European-qualified parts.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Component assembly incentives are attracting passive and discrete packaging investments for domestic mobile and appliance supply chains.
- Silicon carbide-gallium nitride convergence:Wide-bandgap power device proliferation is creating demand for matched high-temperature capacitors and magnetic components.
- Direct OEM procurement platforms:Automotive and industrial buyers are bypassing distribution layers through qualified vendor list digitization.
Industry Challenges
- Compound semiconductor process engineering talent:Foundries and IDMs compete for specialists in heterogenous integration and thermal-mechanical co-design.
- AEC-Q200 revision compliance:Automotive passive component qualification cycles now require 3,000-hour high-temperature operational life testing that strains validation capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Micro Components Market |
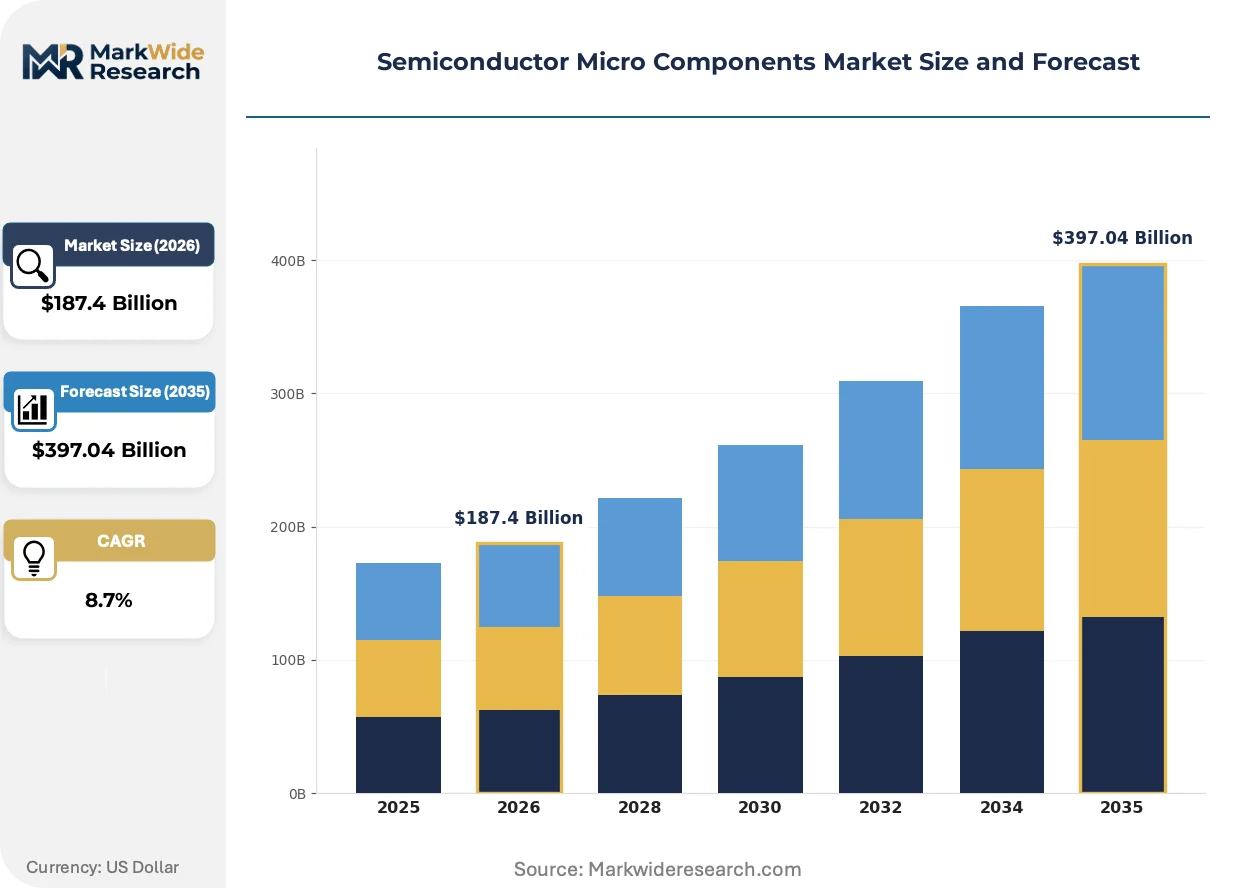
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resistors, Capacitors, Inductors, Diodes Technology: Analog, Digital, Mixed-Signal, Power End User: Consumer Electronics, Automotive Systems, Industrial Automation, Telecommunications Application: Embedded Systems, Signal Processing, Power Management, Networking |
| Companies Covered | NVIDIA Corporation, Analog Devices, Taiwan Semiconductor Manufacturing Company (TSMC), NXP Semiconductors, STMicroelectronics, Samsung Electronics, Texas Instruments, Infineon Technologies, Intel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Micro Components Market Strategic Shifts
Process-material convergence and regulatory substance restrictions are redefining competitive advantage in micro component manufacturing. Device architects now optimize for thermal, electrical, and compliance performance simultaneously rather than sequentially.
Embedded multi-layer ceramic capacitor (MLCC) arrays in organic substrates are virtualizing discrete component placement. Smartphone and notebook OEMs in South Korea and Taiwan are adopting substrate-integrated passives at 40% of new flagship designs. This integration is virtualizing traditional surface-mount assembly steps and compressing bill-of-material line counts by 30-50%.
EPA hazardous substance reporting under TSCA Section 8(a) is tightening disclosure requirements for per- and polyfluoroalkyl substances in semiconductor process chemicals. Fabrication facilities in Arizona and Oregon are reformulating photoresist strippers and etchant chemistries to maintain import and use authorizations. Specialty chemical suppliers are accelerating fluorine-free alternative qualification to preserve defense and aerospace customer access.
Automotive tier-1 suppliers are consolidating passive component vendor lists from 15-20 qualified sources to 5-7 strategic partnerships. Bosch, Continental, and Denso are driving this concentration through long-term pricing agreements and co-development contracts. This consolidation is most visible in Germany and Japan, where just-in-sequence manufacturing requirements favor suppliers with localized technical support and failure analysis capabilities.
Semiconductor Micro Components Market Segmentation
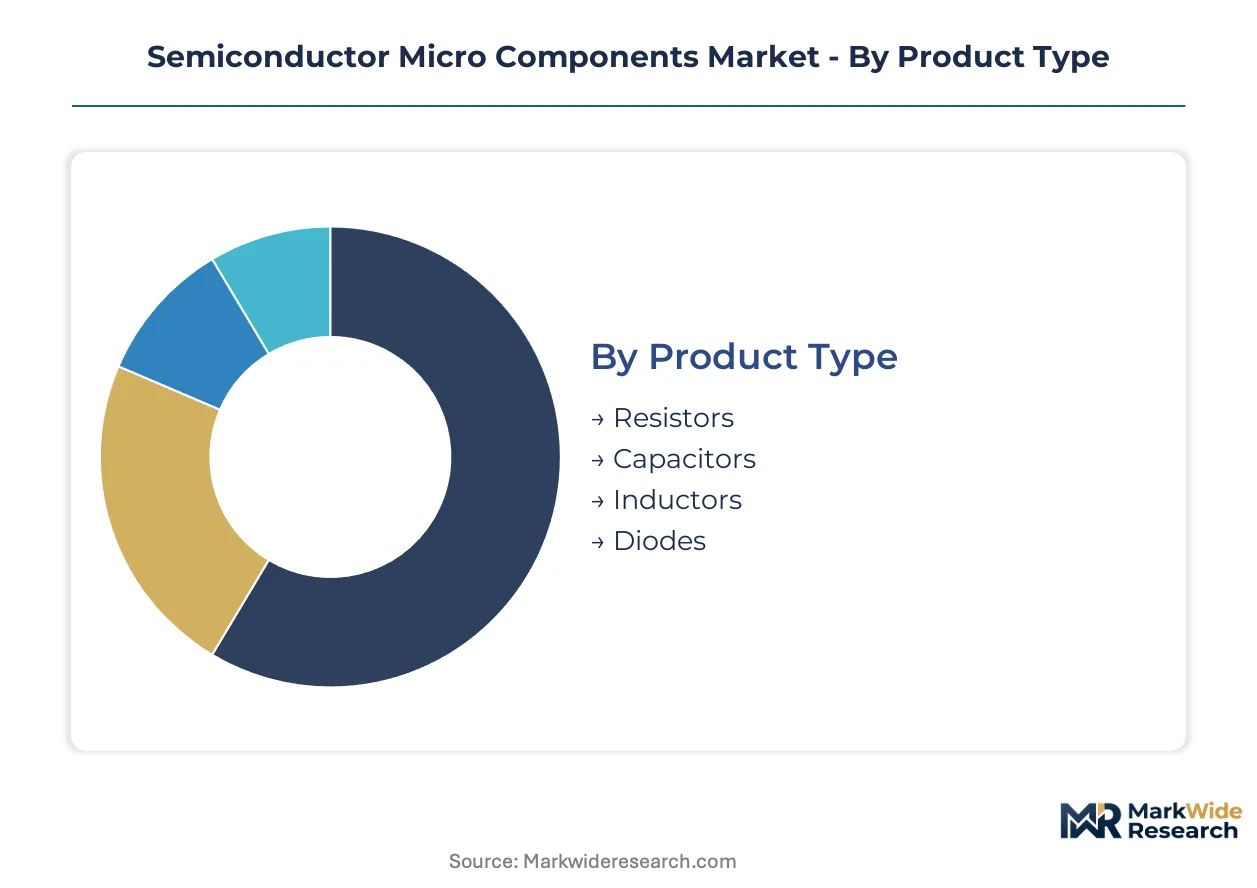
Semiconductor micro components fragment across multiple technical and commercial dimensions, with each axis revealing distinct margin structures and qualification barriers. Product type and technology classifications determine capital intensity, while end-user and application segments dictate reliability standards and procurement cycles.
Product Type:
Mature commodity categories coexist with emerging precision formats across the four product families.
- Capacitors:MLCCs and tantalum devices dominate decoupling and energy storage functions in high-density assemblies. Smartphone OEMs in South Korea and Taiwan consume massive volumes for flagship launches, while automotive traction inverters in Germany multiply demand for high-voltage film capacitors with AEC-Q200 certification.
- Resistors:Thick-film chip resistors handle current limiting and voltage division across billions of units annually. Industrial automation controllers in Japan specify tight-tolerance thin-film variants for sensor signal conditioning, with procurement consolidating around suppliers offering localized failure analysis.
- Inductors:Power inductors manage current ripple in DC-DC converters for wearables and AR headsets.
- Diodes:Schottky and Zener configurations protect against reverse polarity and overvoltage in automotive body electronics.
Capacitors handle the majority of throughput; power inductors are expanding most quickly on share as switching frequencies rise.
Technology:
Cost tier stratification separates legacy process nodes from advanced integration platforms.
- Power:Wide-bandgap device proliferation in electric vehicles and solar inverters demands matched high-temperature passives with enhanced thermal cycling endurance. Bosch and Continental in Germany now specify 175°C-rated components for under-hood placement, compressing traditional automotive qualification timelines.
- Mixed-Signal:Analog-digital boundary devices capture expanding margin pools as data converters and sensor interfaces proliferate. Medical imaging equipment in the United States requires precision passive networks for ADC reference circuits, with FDA device regulations extending validation documentation requirements.
- Analog:Linear signal conditioning remains essential for industrial process control and audio systems.
- Digital:Logic-level termination and bus isolation support high-speed interface standards.
Power technology commands premium pricing; mixed-signal formats are gaining share fastest at the analog-digital interface.
End User:
Application maturity varies dramatically across the four vertical demand pools.
- Automotive Systems:Electrification mandates in the EU Green Deal multiply component counts per vehicle while tightening reliability specifications. Battery-electric platforms in France and Germany require 3-5x more capacitors than internal combustion equivalents, with gate drivers and DC-link capacitors seeing steepest volume acceleration.
- Consumer Electronics:Smartphone and notebook OEMs drive miniaturization through substrate-integrated passive adoption. Flagship designs from South Korean and Taiwanese manufacturers now embed 40% of passive functions directly into organic substrates, virtualizing traditional surface-mount placement.
- Industrial Automation:Factory robotics and process controllers demand extended temperature range components with decade-long supply guarantees.
- Telecommunications:5G mmWave infrastructure requires precision passive networks for beamforming modules.
Consumer electronics moves the highest absolute volumes; automotive systems are climbing the fastest on electrification tailwinds.
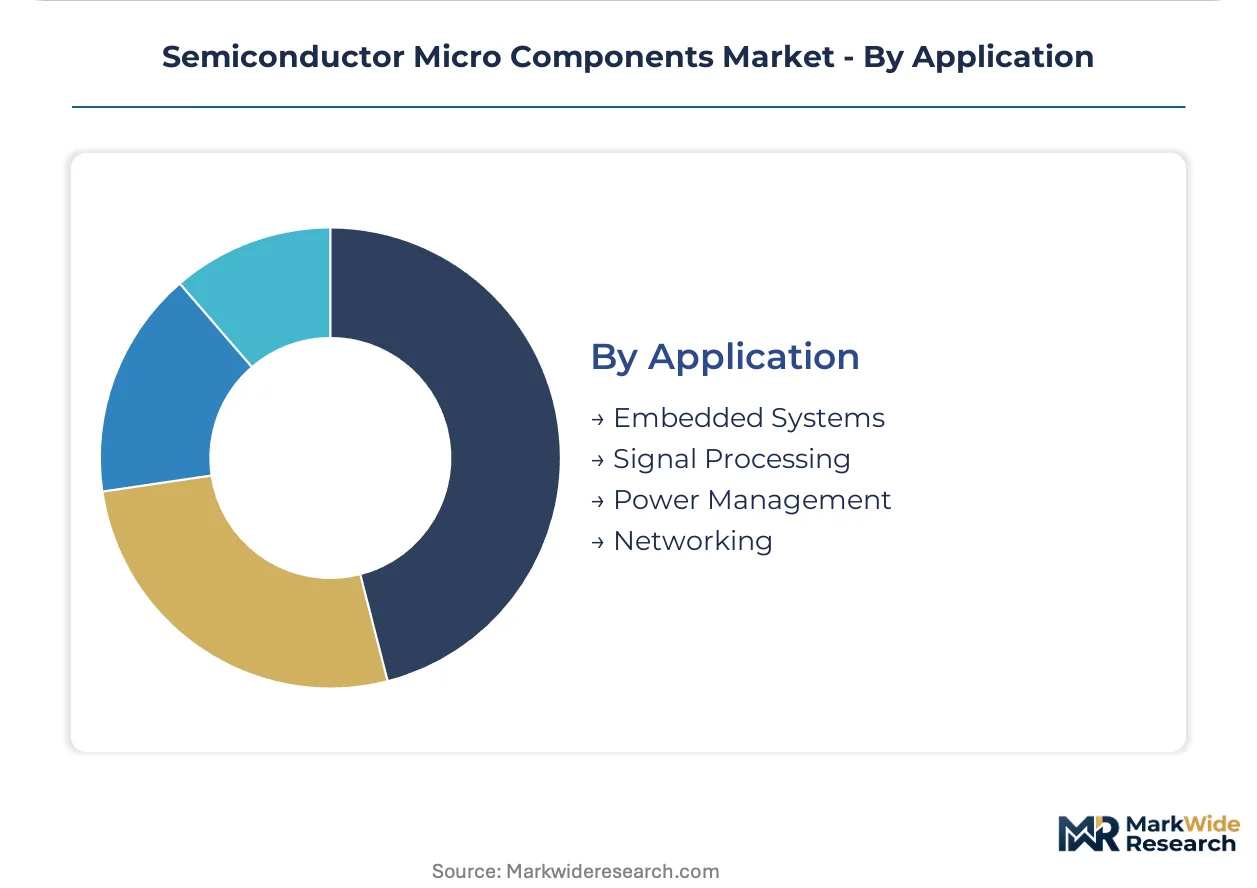
Application:
Functional specialization creates divergent technical requirements across the four use cases.
- Power Management:Voltage regulation and energy conversion circuits in renewable energy inverters and EV chargers demand high-ripple-current capacitors and low-loss magnetic components. String inverters for solar installations in China specify 20-year operational life ratings, with metallized film capacitors replacing electrolytic formats for reliability.
- Embedded Systems:Microcontroller peripheral support requires dense passive integration in space-constrained IoT endpoints. Medical wearables in the United States combine EPA TSCA-compliant materials with ISO 13485 quality systems for FDA submission pathways.
- Signal Processing:Filter networks and impedance matching condition sensor and communication signals.
- Networking:Ethernet and optical transceivers utilize termination and coupling components for signal integrity.
Power management absorbs the greatest component value per system; embedded systems are expanding most rapidly on IoT endpoint proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for advanced packaging substrates tilts the trade balance toward East Asian suppliers, while regional fab incentives in North America and Europe attempt to rebuild captive capacity. The geographic distribution of semiconductor micro component demand reflects automotive electrification clusters, consumer electronics manufacturing hubs, and renewable energy deployment zones.
United States
Electric vehicle battery plants in Michigan and Tennessee multiply demand for high-voltage DC-link capacitors and gate driver modules. The EPA enforces TSCA Section 8(a) reporting for per- and polyfluoroalkyl substances in fabrication chemistries. Arizona's Phoenix-Tucson corridor hosts advanced foundry builds backed by CHIPS Act capital pools, compressing substrate lead times for defense and aerospace buyers.
Germany
Bosch and Continental traction inverter programs in Stuttgart and Wolfsburg accelerate consumption of AEC-Q200-qualified film capacitors and power inductors. The EU Green Deal mandates battery-electric vehicle production quotas that triple passive component counts per platform. Bavaria's Munich-Ingolstadt automotive cluster concentrates qualification laboratories and failure analysis capabilities for tier-1 supplier consolidation.
China
String inverter manufacturers in Jiangsu and Zhejiang provinces specify 20-year-rated metallized film capacitors for solar installations. MIIT coordinates domestic substitution policies for high-reliability automotive passives under the dual carbon goals framework. The Yangtze River Delta packaging corridor anchors flip-chip and fan-out wafer-level capacity for 5G mmWave module integration.
Japan
Industrial automation controllers in Osaka and Nagoya specify tight-tolerance thin-film resistors for sensor signal conditioning. METI coordinates supply chain resilience policies that shape procurement security protocols for automotive and industrial buyers. Kyushu's Kumamoto-Oita region concentrates advanced substrate fabrication for embedded passive integration in wearable medical devices.
South Korea
Smartphone OEMs in Seoul and Suwon embed 40% of passive functions directly into organic substrates for flagship launches. The MFDS regulates medical device quality systems for wearables combining EPA-compliant materials with ISO 13485 pathways. The Busan-Ulsan corridor hosts advanced MLCC manufacturing for automotive and consumer electronics convergence.
Semiconductor Micro Components Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in process-technology niches. The vendor base stratifies across three tiers: IDMs with captive fabrication, fabless designers leveraging foundry partnerships, and specialized passive manufacturers with materials science differentiation. Dominant competitive moves include long-term pricing agreements with automotive tier-1 suppliers and co-development contracts for AEC-Q200-qualified portfolios.
Among Taiwan-based foundry operators, Taiwan Semiconductor Manufacturing Company occupies a position exemplifying government-backed capital deployment for multi-billion-dollar fab commitments. Analog Devices and Texas Instruments represent the integrated device manufacturer archetype, anchoring analog-digital boundary portfolios through in-house wafer fabrication and precision process control. These three entities illustrate the competitive tension between foundry-scale capital intensity and IDM technology integration.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Analog Devices |
| Taiwan Semiconductor Manufacturing Company (TSMC) |
| NXP Semiconductors |
| STMicroelectronics |
| Samsung Electronics |
| Texas Instruments |
| Infineon Technologies |
| Intel |
| Others |
Value Chain & Pricing Dynamics
300mm silicon wafer undercapacity in East Asian foundries drives aggressive allocation priority for logic ICs, squeezing analog and power discrete substrate availability while compressing margin structures for automotive-qualified passive suppliers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with three-tier pricing stratification across AEC-Q200-certified premium, industrial-grade standard, and commercial-economy tiers. Price differentiation hinges on certification grade and volume scale, with automotive tier-1 suppliers locking in 3-5 year agreements to secure allocation. Pricing pressure stems from palladium and ruthenium electrode material volatility, with spot buyers in consumer electronics showing highest sensitivity while medical device OEMs absorb premium tier stability.
Supply Chain Analysis
Palladium and ruthenium feedstock draws from South African mining concentration and automotive catalyst competition, creating raw material dependencies for thin-film electrode fabrication. Taiwan, South Korea, and Japan concentrate advanced packaging substrate capacity, with single-source vulnerability around 300mm silicon wafer supply from Japanese and Taiwanese producers. Distribution runs through authorized distributor networks for high-reliability segments, while direct OEM procurement platforms digitize qualified vendor lists for automotive and industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor micro components form a defensive-moat market anchored by AEC-Q200 certification entrenchment, where switching costs for automotive tier-1 suppliers exceed 18-24 month qualification timelines.
For Market Incumbents: Entrench position through captive backward integration into ceramic powder and electrode material supply, while expanding AEC-Q200 revision compliance laboratories in Germany and Japan to match Bosch and Continental consolidation demands. Threat from wide-bandgap power device substitution demands matched high-temperature passive co-development contracts.
For New Entrants and Emerging Players: Build out substrate-integrated passive capabilities for smartphone OEMs in South Korea and Taiwan, where 40% embedded function adoption creates white-space below established MLCC giants. Target India's PLI scheme electronics manufacturing incentives for domestic mobile and appliance packaging investments, leveraging component assembly subsidies as go-to-market entry.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automotive-qualified passive specialists with long-term pricing agreements, offering 5-10 year visibility through electrification mandates. Acquisition target archetype: mid-cap materials-science differentiated players with localized failure analysis capabilities. Signal to watch: REACH substance authorization delays compressing European-qualified part timelines as inflection for regulatory-entrenchment value.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Feedstock | Secures palladium and ruthenium electrode supply against South African mining volatility for AEC-Q200 portfolios. |
| AEC-Q200 Revision Compliance Investment | Positions suppliers for Bosch and Continental vendor list consolidation in Stuttgart and Wolfsburg traction inverter programs. |
| Substrate-Integrated Passive Capacity Buildout | Captures 40% embedded function demand from Samsung and flagship smartphone OEMs in Seoul and Suwon. |
| India PLI Scheme Manufacturing Footprint | Accesses domestic mobile and appliance supply chain incentives for packaging assembly cost positioning. |
| Wide-Bandgap Power Device Co-Development | Creates matched high-temperature capacitor and magnetic component demand from silicon carbide-gallium nitride convergence. |
Study Parameters
A spread of perspectives from foundry operations executives, automotive tier-1 procurement directors, passive component R&D leads, and specialty chemical supplier technical directors converged on the working assumptions. Primary fieldwork combined with secondary validation from SEC 10-K filings, ECHA REACH substance authorization databases, MIIT policy coordination notices, and customs trade flow records. Bottom-up segment sizing and top-down macroeconomic cross-checks triangulated volume and value estimates.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by capacitors, resistors, inductors, and diodes; technology tiers spanning power, mixed-signal, analog, and digital; and end-user verticals including automotive systems, consumer electronics, industrial automation, and telecommunications. CAGRs derived from segment-level growth trajectory analysis, with inputs including electric vehicle battery-electric platform penetration, renewable energy inverter deployment, and 5G mmWave infrastructure buildout.
Stress conditions across palladium price volatility bands, 300mm wafer allocation priority shifts, and REACH authorization timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on electrification mandate compliance and dual-use export control evolution. Cross-checking against IHS Markit vehicle production databases and EIA renewable energy installation benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Passive Attenuator Market
Electronic Components
Conductive Polymer Capacitor Market
Electronic Components
Audio Amplifier Market
Electronic Components
Asia-Pacific USB Retimer Market
Electronic Components
Docking Station Market
Electronic Components
Metal Oxide Varistor (MOV) Market
Electronic Components
High Temperature Capacitor Market
Electronic Components
Solder Paste for Mini LED Market
Electronic Components
Capacitor Kits Market
Electronic Components
AC Adapter Market
Electronic Components
China Data Converter Market
Electronic Components
USB Wall Charger Market
Electronic Components
Motherboard Battery Market
Electronic Components
Capacitive Stylus Pen Market
Electronic Components
Primary Charge Roller Market
Electronic Components
Coin Battery Holder Market