
 Thermoplastic Polyurethane (TPU) Films Market | 2026-2036
Thermoplastic Polyurethane (TPU) Films Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoplastic Polyurethane (TPU) Films Market Intelligence
The displacement of polyvinyl chloride (PVC) in sensitive applications is repositioning the value of Thermoplastic Polyurethane (TPU) films. Their superior safety profile and flexibility make them a preferred material in medical and consumer electronics. The Lubrizol Corporation leverages its material science to penetrate high-margin medical device applications. Covestro AG sustains a strong position in the European automotive sector, while BASF SE competes globally through its extensive production and distribution network.
Thermoplastic polyurethane films are high-performance elastomers known for exceptional abrasion resistance, elasticity, and transparency. They are produced via processes like extrusion or calendering, resulting in films with specific thicknesses and surface properties for industrial use. Extruded films constitute the largest product type segment by volume due to manufacturing scalability. Applications in automotive interiors and electronic protective covers, however, represent significant value pools due to stringent performance specifications.
Regulatory frameworks significantly influence material selection and market access for TPU films. The European Union's REACH regulation restricts hazardous substances, creating an advantage for compliant TPU formulations over older plastics. Similarly, materials used in medical applications must meet US FDA guidelines, while components for vehicles sold in China adhere to GB standards. Producers must navigate these varied compliance landscapes while balancing performance against cost pressures.
Market Dynamics
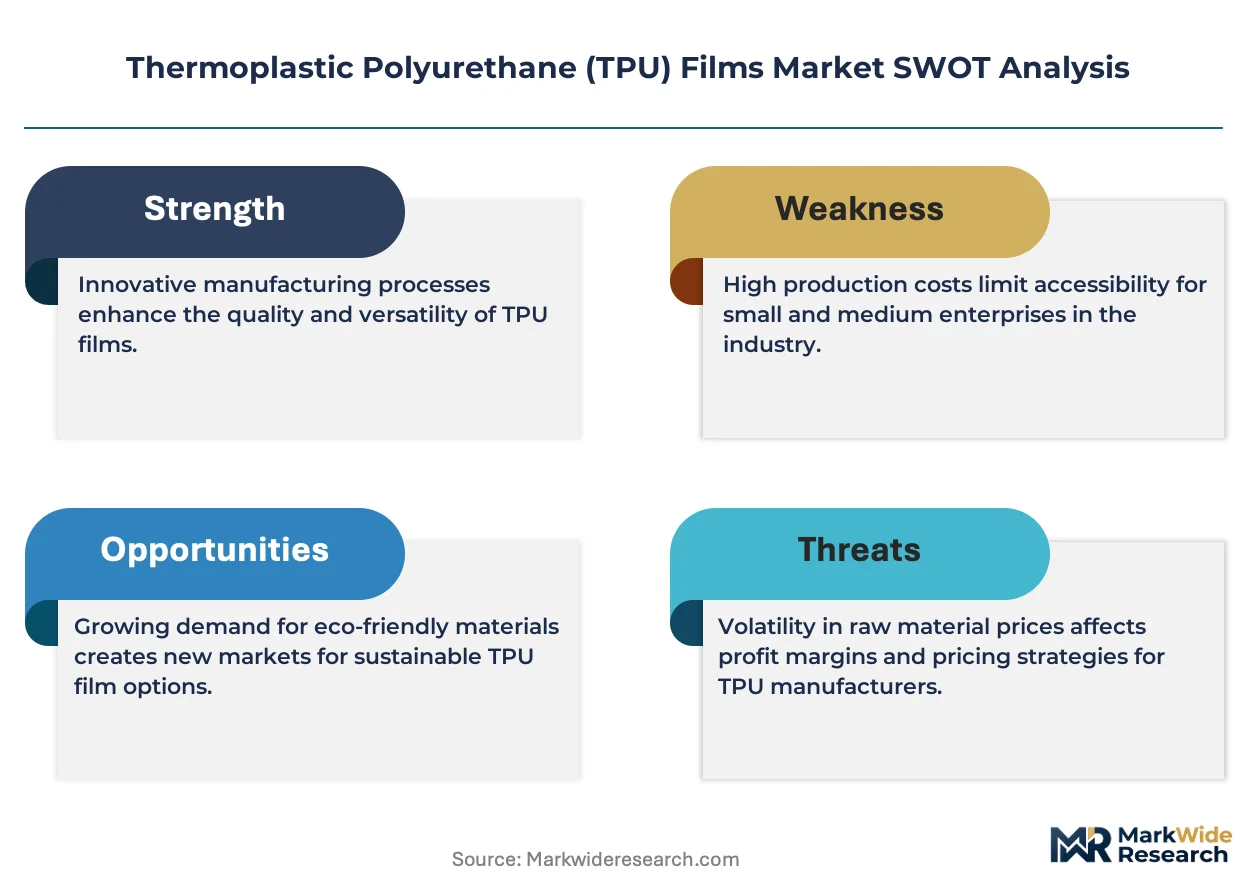
The primary structural force governing the Thermoplastic Polyurethane Films market is the regulatory-driven substitution of legacy materials like PVC. Mandates such as the EU's REACH regulation are creating non-negotiable demand for safer, compliant polymers in high-value automotive and medical applications.
Growth Catalysts
- Regulatory Pressure on PVC:The EU's REACH framework, which restricts certain phthalates common in PVC, compels manufacturers of consumer goods and medical tubing to adopt TPU as a safer, more flexible alternative.
- Automotive Interior Upgrades:Demand for enhanced cabin aesthetics and durability in vehicles is driving the adoption of TPU films for soft-touch surfaces, instrument panels, and door trims, replacing traditional hard plastics.
- Electronics Miniaturization:China's electronics sector requires ultra-thin, durable films for applications like flexible printed circuits and protective layers for foldable screens, a performance profile where TPU excels.
Market Restraints
- Raw Material Price Volatility:The cost of TPU is directly linked to its primary chemical precursors, MDI and polyols, whose prices are subject to fluctuations in the global petrochemical market, impacting producer margins.
- Competition from TPEs:In less demanding, cost-sensitive applications, other thermoplastic elastomers (TPEs) such as thermoplastic olefins (TPOs) present a viable, lower-cost alternative to TPU films.
- Processing Complexity:Manufacturing high-performance TPU films requires specialized extrusion or calendering equipment and precise process control, representing a significant capital and technical barrier for new entrants.
Strategic Opportunities
- Wearable Technology Integration:The expansion of wearable medical devices and smart textiles creates an opportunity for biocompatible, skin-contact-safe TPU films that can encapsulate sensitive electronics while providing flexibility.
- Expansion in Southeast Asia:Rising manufacturing activity in countries like Vietnam and Thailand presents an underpenetrated market for TPU films, particularly in footwear, apparel, and electronics assembly sectors.
- Bio-Based Formulations:Developing and scaling bio-based TPU derived from renewable feedstocks offers a path to capture demand from brands focused on sustainability and reducing their carbon footprint.
Industry Challenges
- Navigating Global Compliance:Producers face the complex task of ensuring their products simultaneously meet disparate regulatory standards, such as the EU's Medical Device Regulation (MDR) and China's GB standards for vehicle components.
- Recycling Infrastructure Gaps:The absence of widespread, dedicated collection and recycling streams for post-consumer TPU products hinders circularity efforts and can be a competitive disadvantage against materials with established recycling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoplastic Polyurethane (TPU) Films Market |
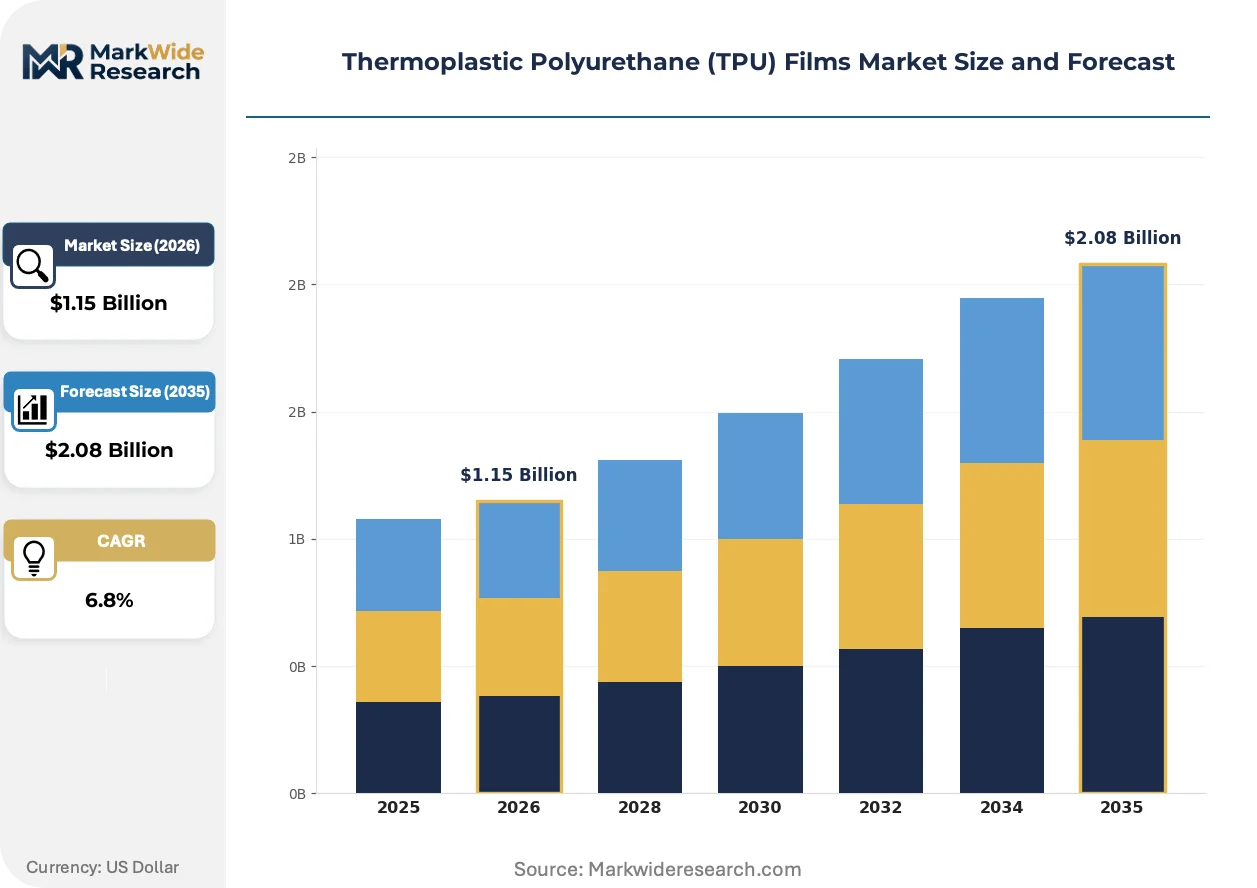
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $2.08 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extruded Films, Calendered Films, Coated Films, Laminated Films, Cast Films Application: Footwear Components, Automotive Interiors, Electronic Protective Covers, Medical Devices, Outdoor Gear End User Industry: Apparel Manufacturers, Vehicle Assemblers, Medical Equipment Makers, Electronics Producers, Sporting Goods Companies Film Thickness: Below 50 Microns, 50-100 Microns, 101-200 Microns, Above 200 Microns |
| Companies Covered | The Lubrizol Corporation, Covestro AG, BASF SE, Huntsman Corporation, Permali Gloucester Limited, PAR Group, American Polyfilm Inc., 3M, Avery Dennison Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoplastic Polyurethane (TPU) Films Market Strategic Shifts & Innovations
Material science advancements are reshaping the TPU films market, enabling formulations that meet stringent performance criteria while aligning with sustainability mandates. This evolution allows TPU to penetrate applications previously dominated by other polymers, driven by specific end-user requirements for safety and functionality.
Bio-based TPU formulations, which utilize renewable feedstocks, provide a lower carbon footprint compared to their petroleum-based counterparts. Footwear and consumer electronics brands are progressively adopting these materials to meet corporate sustainability targets and appeal to environmentally conscious consumers. Bio-based TPU is overtaking conventional grades in premium product lines where green credentials are a significant market differentiator.
The European Union's REACH regulation continues to tighten restrictions on hazardous substances, directly impacting material selection in countless industries. This forces a move away from materials like flexible PVC containing certain plasticizers, creating a regulatory tailwind for compliant TPU films. The medical device and children's toy segments are most affected, actively designing out non-compliant plastics.
A notable behavioral shift is occurring in automotive design, with a clear preference for premium haptic qualities and soft-touch interior surfaces. This trend disrupts the use of traditional rigid plastics for dashboards and consoles, favoring laminated TPU films that offer superior feel and durability. This shift is especially pronounced within the electric vehicle sector, where interior quality is a critical competitive element.
Thermoplastic Polyurethane (TPU) Films Market Segmentation
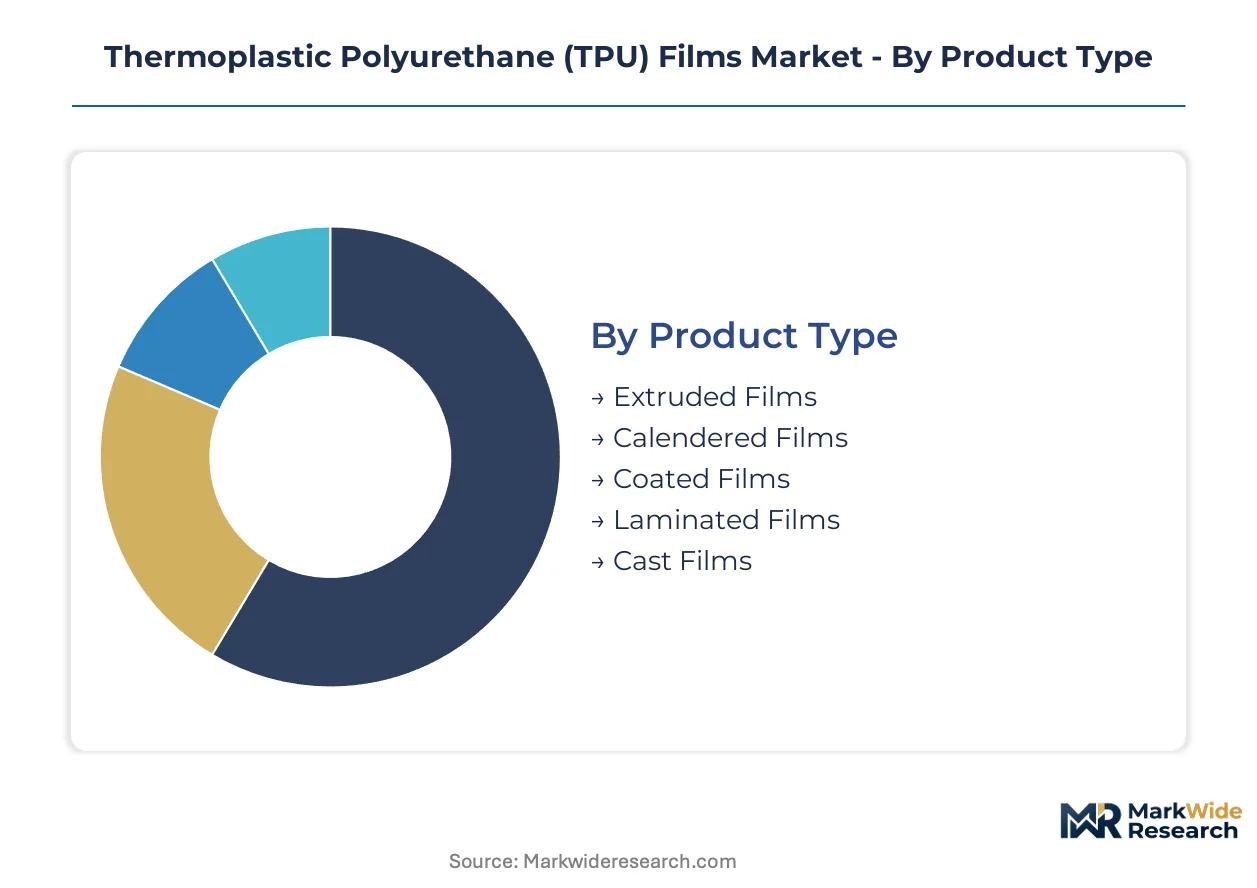
The Thermoplastic Polyurethane (TPU) films market is analyzed across several key segments, reflecting the diverse material properties and end-use requirements. Understanding these distinctions helps identify where value concentrates and how specific product attributes drive adoption. Varied processing methods and application demands shape the competitive landscape.
Product Type:
The manufacturing process employed significantly differentiates the properties and end-use suitability of TPU films within this segment.
- Extruded Films:These films are produced by forcing molten TPU through a die, offering high uniformity and cost-effectiveness for large-volume applications. Demand concentrates in general industrial and automotive interior components, driven by their scalability and consistent quality.
- Laminated Films:Created by bonding multiple layers of TPU or other materials, these films provide enhanced barrier properties and aesthetic finishes. Value accumulates in automotive interiors and high-performance protective covers, where multi-functional layers are required for durability and feel.
- Calendered Films:Produced by pressing TPU through heated rollers, these films offer precise thickness control for applications like medical tubing.
- Coated Films:These films feature a TPU layer applied to a substrate, enhancing surface properties for textiles and protective gear.
- Cast Films:Formed by spreading liquid TPU onto a surface, cast films achieve exceptional clarity for optical applications.
Volume sits with Extruded Films; growth tilts toward Laminated Films.
Application:
Application-specific performance requirements dictate material choices across this segment.
- Automotive Interiors:TPU films provide soft-touch surfaces, abrasion resistance, and aesthetic appeal for dashboards, door panels, and seating components. Demand is particularly strong in European vehicle manufacturing, driven by consumer preference for premium cabin experiences and durability standards.
- Electronic Protective Covers:These films offer impact resistance, flexibility, and transparency for smartphone screens, tablets, and wearable devices. China's electronics sector drives significant volume, requiring ultra-thin, durable layers for foldable and flexible displays.
- Footwear Components:TPU films enhance durability, flexibility, and waterproofing in athletic shoe uppers and structural elements.
- Medical Devices:Biocompatible TPU films are crucial for medical tubing, wound dressings, and sterile barrier systems due to their safety profile.
- Outdoor Gear:These films provide waterproofing and abrasion resistance for tents, backpacks, and inflatable equipment.
This segment is experiencing its steepest expansion trajectory in Electronic Protective Covers.
End User Industry:
Customer type and their unique manufacturing processes shape demand within this segment.
- Vehicle Assemblers:These manufacturers integrate TPU films into interior components for enhanced aesthetics, durability, and compliance with safety standards. European and Chinese automotive companies are significant consumers, driven by stringent quality requirements and design trends.
- Electronics Producers:Companies in this sector utilize TPU films for protective layers, flexible circuits, and encapsulants in consumer electronics. Manufacturers in China and Southeast Asia represent substantial demand for high-performance, thin-gauge films.
- Apparel Manufacturers:These companies use TPU films for waterproof breathable membranes in activewear and fashion items.
- Medical Equipment Makers:Producers of medical devices rely on TPU films for their biocompatibility and chemical resistance in critical applications.
- Sporting Goods Companies:TPU films are incorporated into sports equipment for durability, flexibility, and impact protection.
The largest share of volume is consumed by Vehicle Assemblers, while Electronics Producers exhibits the most dynamic expansion.
Film Thickness:
The functional demands of the final product largely determine the film thickness required.
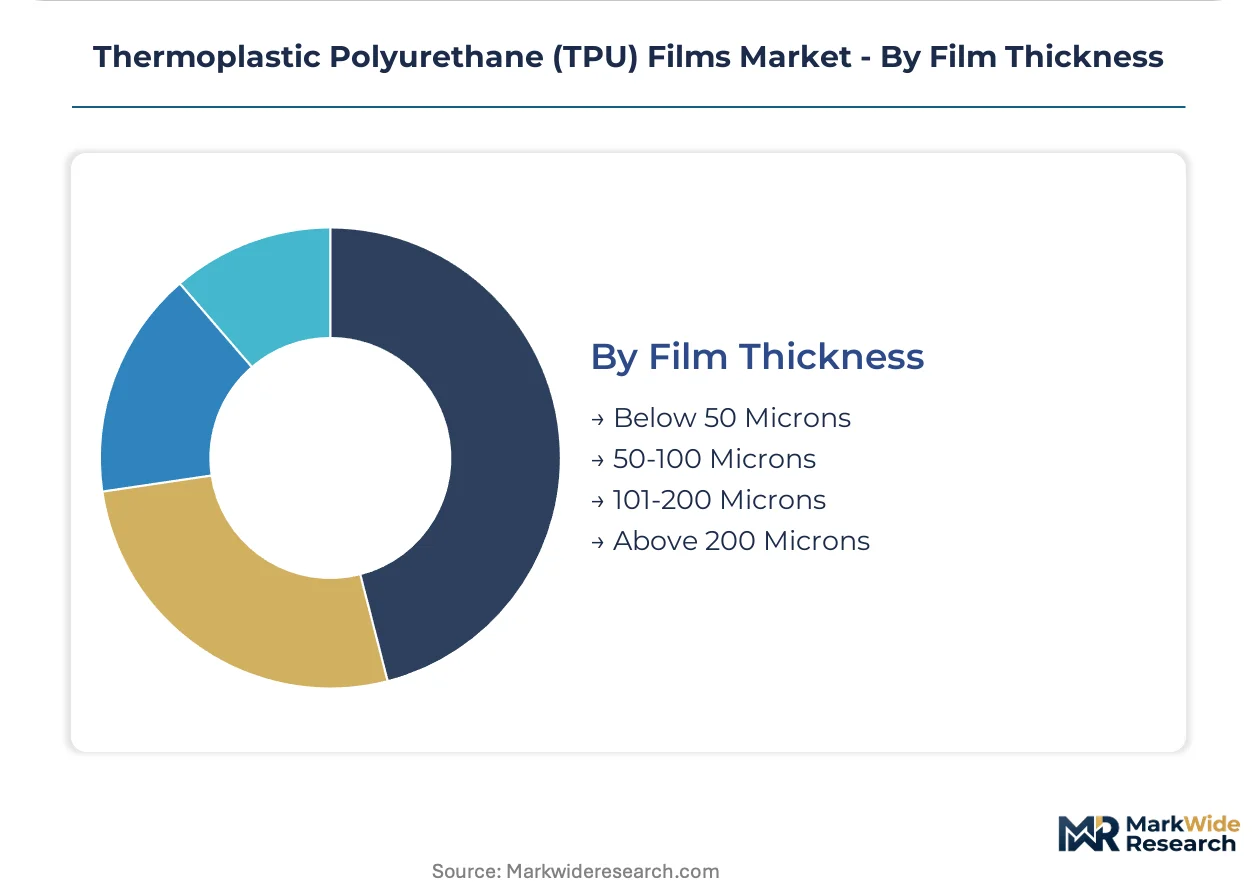
- Below 50 Microns:Ultra-thin TPU films are critical for flexible electronics, protective screen covers, and delicate medical applications. Chinese electronics manufacturers require these films for miniaturized components and foldable display technologies.
- 101-200 Microns:These mid-range thickness films offer a balance of durability, flexibility, and processing ease for automotive interiors and industrial protective overlays. European automotive suppliers frequently specify films within this range for instrument panels.
- 50-100 Microns:Films in this range are widely used for general protective applications and certain footwear components, balancing strength and flexibility.
- Above 200 Microns:Thicker TPU films provide superior abrasion resistance and impact protection for heavy-duty industrial and outdoor gear applications.
While 50-100 Microns represents a foundational volume, Below 50 Microns is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Special Economic Zones, particularly in coastal manufacturing hubs, drive significant demand for Thermoplastic Polyurethane (TPU) films. These zones attract massive electronics and automotive production, concentrating the need for advanced material solutions. Global manufacturers establish operations within these areas to capitalize on market access and supply chain efficiencies for high-volume production.
China
Demand for TPU films in China stems from its vast electronics manufacturing sector and rapidly expanding electric vehicle production. The Ministry of Industry and Information Technology (MIIT) actively supports domestic material innovation to meet stringent performance requirements for these critical industries. Major industrial clusters in the Yangtze River Delta actively integrate TPU films into flexible displays, protective covers, and automotive interiors.
Germany
German automotive manufacturers increasingly specify TPU films for premium interior surfaces, protective laminates, and advanced functional components. The EU's REACH regulation mandates the use of safer polymers, significantly favoring compliant TPU formulations over traditional plastics like PVC. Production hubs in Bavaria and North Rhine-Westphalia focus on high-performance TPU film development for luxury vehicles and specialized industrial applications.
United States
US medical device manufacturers and automotive suppliers actively seek high-performance TPU films for critical, sensitive applications requiring durability and biocompatibility. The FDA guidelines for medical materials ensure strict adherence to safety and performance profiles, boosting TPU adoption in healthcare. Silicon Valley and Detroit's automotive corridor are centers for material research and integration into advanced consumer and automotive products.
Japan
Japanese electronics and automotive industries require advanced TPU films for miniaturized components, high-clarity displays, and aesthetic vehicle upgrades. METI initiatives actively promote innovation in sustainable materials and high-durability films to enhance product lifespan and environmental compliance. Industrial zones around Tokyo and Osaka concentrate on developing ultra-thin TPU films for next-generation foldable displays and high-value automotive parts.
Thermoplastic Polyurethane (TPU) Films Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the Thermoplastic Polyurethane (TPU) films market, reflecting varied customer needs. The competitive structure features a mix of large, diversified chemical conglomerates and specialized film producers focused on niche applications. Major players frequently pursue strategic partnerships and targeted capacity expansions to secure raw material supply and broaden their application reach. Portfolio diversification into bio-based formulations also represents a common competitive move, aligning with global sustainability mandates.
Global chemical giants such as Covestro AG and BASF SE exemplify the archetype of diversified material science companies within this market. These entities leverage extensive research and development capabilities to offer a broad portfolio of TPU film grades, serving multiple high-value industries like automotive and medical devices with specialized formulations. Their global production and distribution networks allow them to compete across diverse geographic markets, often providing integrated solutions to major end-users. The Lubrizol Corporation also occupies a significant position, particularly in specialized, high-margin applications requiring advanced material properties and stringent compliance.
| Leading Market Players |
|---|
| The Lubrizol Corporation |
| Covestro AG |
| BASF SE |
| Huntsman Corporation |
| Permali Gloucester Limited |
| PAR Group |
| American Polyfilm Inc. |
| 3M |
| Avery Dennison Corporation |
| Others |
Cost & Logistics Intelligence
European vehicle assemblers largely rely on contract-based long-term offtake agreements for TPU films. This model ensures material availability and stable pricing for high-volume automotive production.
Pricing Analysis
Premium pricing for short lead times often applies to specialized TPU film orders, while large-volume customers utilize contract-based long-term offtake agreements. Price differentiation stems from material grade certification, particularly FDA or REACH compliance, and the volume scale of the order. Upward pricing pressure stems from fluctuations in MDI and polyol costs. Medical device manufacturers exhibit the least price sensitivity, contrasting with cost-sensitive footwear and apparel brands.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for TPU films in automotive and electronics. Geographic supply concentration centers on China, Germany, and the United States, reflecting major production hubs. The supply chain draws from primary chemical precursors like MDI and polyols. Commodity price volatility for these raw materials represents a significant structural risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Thermoplastic Polyurethane (TPU) films market presents a cost-of-compliance story, where the EU's REACH regulation creates a significant barrier-to-entry moat for compliant material producers. This regulatory environment favors established players with certified formulations.
For Market Incumbents: Cement market leadership by expanding capacity in regions with robust regulatory frameworks like Germany and the US. Invest in advanced material science for bio-based TPU formulations to counter raw material price volatility and TPE competition. Deepen vertical integration into key chemical precursors to secure supply and optimize costs. Prioritize R&D into high-performance grades for medical and automotive applications, leveraging existing certification investments.
For New Entrants and Emerging Players: Digital marketplace platforms offer a direct route for new entrants to target niche applications in wearable technology. Focus on underpenetrated markets in Southeast Asia for footwear and apparel components by offering specialized, cost-effective TPU films. A go-to-market strategy emphasizing sustainability credentials of bio-based formulations can attract environmentally conscious brands. Target flexible electronics in China with ultra-thin, high-durability film solutions.
For Investors and Strategic Acquirers: The window for entry favors specialized film producers with proven R&D capabilities in bio-based TPU. Long-term viability over the next 5-10 years depends on strategic acquisitions of companies holding critical intellectual property for sustainable materials. Target mid-cap manufacturers with strong regional distribution networks in high-growth areas like China. Watch for widespread adoption of bio-based TPU in premium consumer electronics as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increases supply of compliant TPU films for European automotive manufacturers. |
| Green Manufacturing Transition | Reduces carbon footprint, appealing to footwear and electronics brands. |
| Long-term Supply Agreement | Secures stable raw material input for polyols, mitigating price volatility. |
| Bio-based Product Launch | Captures demand from consumer electronics companies focused on sustainability. |
| Certification Investment | Ensures compliance with US FDA guidelines for critical medical device applications. |
Research Approach
Independent corroboration across customs/trade data, SEC 10-K filings, and industry association reports underwrites the qualitative findings. This involved primary interviews with R&D directors, procurement leads, material scientists, and regulatory affairs specialists across the value chain. Bottom-up data collection and top-down market sizing provided robust triangulation.
The forecast window was anchored to historical reference periods, establishing a baseline for market evolution. The analytical framework modeled growth across product type, application, end-user industry, film thickness, and regional regulatory clusters. Compound Annual Growth Rates were derived from historical trends and projected future demand. Petrochemical feedstock prices and regulatory enforcement timelines served as key industry-specific forecast inputs.
The model holds under current petrochemical supply stability; deviation in geopolitical shifts or rapid material substitution would shift market dynamics. Forecasts reflect assumptions regarding continued regulatory pressure on PVC and sustained demand for high-performance elastomers. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Silicone-Coated PET Films Market
Poly film
Peelable and Resealable Films Market
Poly film
Global Biaxially Oriented Polypropylene (BOPP) in Films and Sheets Market
Poly film
PCR Bubble Films Market
Poly film
Polylaminate Capsules Market
Poly film
Polyolefin Films Market
Poly film
North America Plastic Film Packaging Market
Poly film
Craft Plastic Films Market
Poly film
PCR Lidding Films Market
Poly film
US Cleanroom Film and Bags Market
Poly film
North America Polyimide Films Market
Poly film
Morocco Plastic Packaging Films Market
Poly film
North America BOPP Films Market
Poly film
Bopet Films Market
Poly film
Global Specialty Films Polymer Market
Poly film
United Kingdom Plastic Packaging Films Market