
 Cast Films Market | 2026-2036
Cast Films Market Size, Share, and Industry Trends Forecast 2026-2036
Cast Films Market Outlook
Multi-source resin procurement is expanding across the cast films value chain as converters buffer against polyolefin price volatility. Profol Kunststoffe GmbH leverages captive compounding capabilities in Europe to sustain margin stability across specialty polypropylene grades. Taghleef Industries LLC anchors its competitive position through global manufacturing scale spanning the Americas, Europe, and Asia-Pacific. Amcor Plc differentiates via integrated design-to-recyclability services that extend its influence beyond commodity film supply into brand-owner sustainability programs.
Cast films are polymer sheets manufactured by extruding molten resin through a flat die onto a chilled roll, producing gauges typically ranging from twelve to two hundred fifty microns with controlled optical clarity and mechanical uniformity. The process yields substrates engineered for thermoformability, print receptivity, and heat-seal performance in downstream converting operations. Polyethylene formulations dominate volume flows into food packaging applications where barrier extension and seal integrity command premium positioning. Polypropylene grades compete aggressively in medical and industrial segments where stiffness and temperature resistance define specification compliance. PVC retains niche occupancy in pharmaceutical blister formats despite sustainability-driven substitution pressures across European healthcare supply chains.
FDA food contact regulations and EU REACH chemical authorization frameworks govern monomer migration limits and additive permissibility, directly constraining formulation flexibility for suppliers serving transatlantic consumer goods brands. EPA emissions standards and OSHA workplace exposure thresholds further shape extrusion plant capital allocation toward enclosed resin handling and solvent-free coating investments. Stakeholders must monitor evolving extended producer responsibility mandates and recycled content thresholds as these compliance architectures restructure raw material sourcing economics and customer qualification protocols.
Market Dynamics
Polyolefin price volatility is forcing converters to restructure resin procurement strategies while EU REACH chemical restrictions and FDA food contact mandates tighten formulation compliance requirements across transatlantic supply chains.
Growth Catalysts
- EU Green Deal packaging mandates:Circular economy targets for recyclable flexible packaging are pulling cast polyethylene films into higher-specification barrier grades across European converter networks.
- India's flexible packaging expansion:Domestic biaxial and cast line capacity scaling by UFlex and Jindal Poly Films is concentrating regional demand growth in South Asian food and consumer goods sectors.
- Medical-grade polypropylene substitution:Temperature resistance and stiffness specifications in pharmaceutical blister and sterile barrier applications are displacing PVC despite sustainability-driven substitution pressures.
Market Restraints
- Propylene feedstock volatility:Crude oil and naphtha price swings compress margin stability for specialty polypropylene grade producers without captive compounding capabilities.
- European substrate compliance concentration:REACH chemical authorization frameworks and ECHA monomer migration limits constrain formulation flexibility for suppliers serving EU healthcare supply chains.
- Mechanical recycling contamination thresholds:Technical limitations in sorting multi-layer cast film structures limit post-consumer recycled content integration in food-contact applications.
Strategic Opportunities
- Extended producer responsibility tailwinds:EU packaging waste directives and emerging state-level mandates in the US are creating compliance-service revenue streams for integrated design-to-recyclability providers.
- Thermoformable high-clarity segments:Convergence of optical uniformity control and heat-seal performance engineering is opening premium positioning in fresh produce and ready-meal packaging formats.
- Industrial distribution channel innovation:Direct-to-converter digital procurement platforms are compressing traditional distributor markups in North American and European mid-volume segments.
Industry Challenges
- Extrusion technician skill scarcity:Specialized die gap control and chill roll temperature profiling expertise is concentrating among aging workforce cohorts in mature manufacturing regions.
- Multi-jurisdiction certification timelines:Simultaneous FDA food contact notification and EU REACH authorization processes extend product qualification cycles by twelve to eighteen months for new additive packages.
- Legacy solvent-based coating integration:Capital-intensive transition to water-based and solvent-free barrier coating lines creates stranded asset risk for mid-scale European converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cast Films Market |
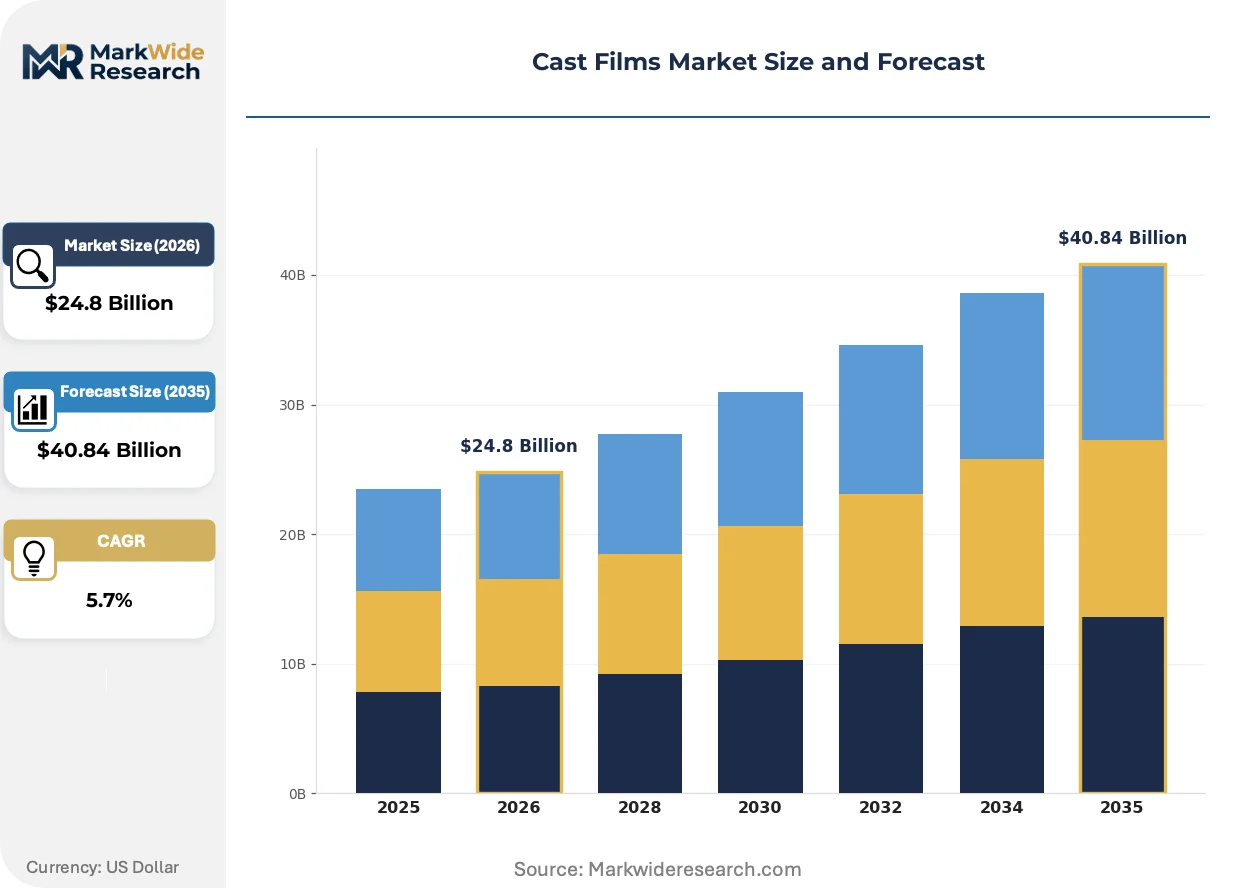
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $40.84 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, PET Application: Packaging, Agriculture, Industrial, Medical End User: Food & Beverage, Healthcare, Electronics, Consumer Goods Distribution Channel: Direct Sales, Online Retail, Distributors, Others |
| Companies Covered | Polyplex Corporation Ltd, Profol Kunststoffe GmbH, Taghleef Industries LLC, Winpak Ltd., Amcor Plc, UFlex Ltd., Berry Global, Inc., Scientex Berhad, Jindal Poly Films Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cast Films Market Strategic Shifts
Digital process control systems and closed-loop extrusion automation are compressing gauge tolerance bands while regulatory frameworks restructure permissible chemistries and recycled content claims across major demand centers.
Machine vision-equipped thickness profiling is automating real-time die bolt adjustment in cast film extrusion lines. Food packaging converters in Germany and the Netherlands are adopting these systems at replacement-cycle pace. The technology is automating labor-intensive manual calibration while reducing raw material giveaway by tightening gauge distribution curves.
REACH authorization list expansion is restricting phthalate plasticizers and certain antioxidant packages in EU pharmaceutical and food-contact films. Industrial consequence includes accelerated reformulation cycles and qualification costs for additive suppliers. Medical device packaging segments in France and Germany are responding with pre-emptive substitution to bio-based stabilizer systems ahead of sunset date enforcement.
Brand-owner sustainability scorecards are compressing supplier qualification criteria toward mass-balance certified and mechanically recycled content verification. Large-format retail chains in the United Kingdom and Nordic markets are displacing traditional commodity film tenders with circularity-audited procurement frameworks. This behavioral shift is most visible in private-label fresh food packaging where recycled content thresholds now gate commercial relationships.
Cast Films Market Segmentation
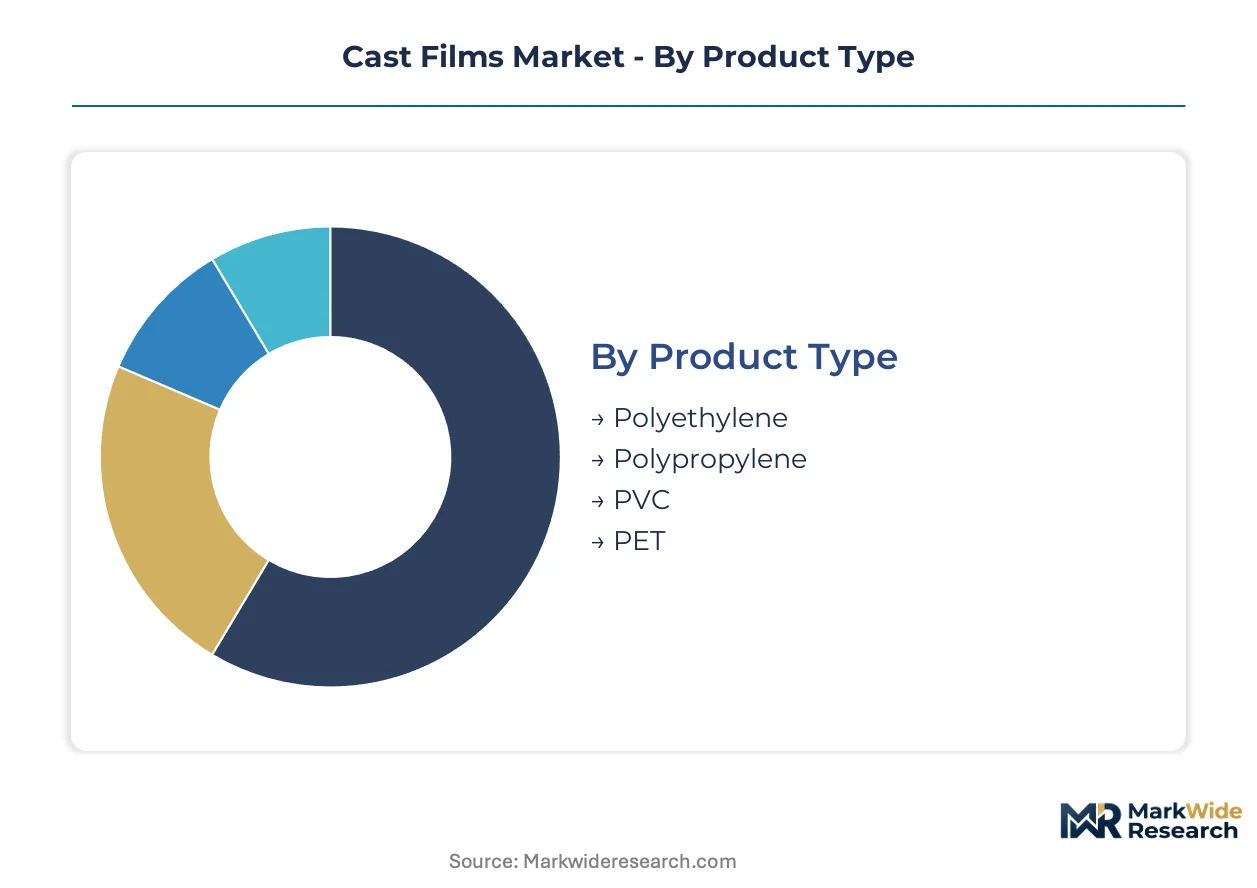
Cast films serve divergent performance requirements across food protection, medical sterility, and industrial durability. Segmentation reveals where resin chemistry investments concentrate and which compliance frameworks govern customer qualification.
Product Type:
Polyethylene commands volume flows while polypropylene captures premium positioning through temperature resistance and stiffness specifications.
- Polyethylene:Linear low-density and metallocene grades dominate food packaging where seal integrity and barrier extension command specification compliance. Demand concentrates in European converter networks responding to EU Green Deal recyclable packaging mandates.
- Polypropylene:Cast homopolymer and random copolymer formulations deliver thermoformability and optical clarity for medical blister and sterile barrier applications. Temperature resistance specifications are displacing PVC in pharmaceutical formats despite reformulation costs.
- PVC:Retains niche occupancy in pharmaceutical blister packs where European healthcare supply chains face sustainability-driven substitution pressures.
- PET:High-clarity grades serve premium fresh produce and ready-meal formats requiring dimensional stability and print receptivity.
Mature deployment sits with polyethylene. Newer deployment is concentrated in polypropylene as medical-grade substitution accelerates.
Application:
Packaging absorbs capacity investments while medical applications generate margin premiums through qualification barriers.
- Packaging:Food-contact films require FDA notification and EU REACH compliance for monomer migration limits. Barrier coating integration and heat-seal performance engineering differentiate supplier positioning in fresh produce and ready-meal segments.
- Medical:Sterile barrier and pharmaceutical blister specifications demand ISO 11607 compliance and EMA device regulation adherence. Temperature resistance and optical clarity requirements sustain specialty grade premiums.
- Agriculture:Greenhouse and mulch films prioritize UV stabilization and mechanical durability over optical precision.
- Industrial:Surface protection and lamination substrates emphasize gauge uniformity and tensile consistency for automated converting lines.
Volume concentration favors packaging. Steepest expansion trajectory belongs to medical as regulatory substitution mandates reshape material selection.
End User:
Food and beverage procurement scales drive resin volume commitments while healthcare qualification timelines protect incumbent positions.
- Food & Beverage:Private-label retail chains in the United Kingdom and Nordic markets now gate supplier relationships on mass-balance certified recycled content verification.
- Healthcare:Pharmaceutical manufacturers in France and Germany are pre-emptively substituting bio-based stabilizer systems ahead of REACH sunset date enforcement.
- Electronics:Anti-static and cleanroom packaging specifications prioritize particulate control and surface resistivity compliance.
- Consumer Goods:Brand-owner sustainability scorecards compress supplier qualification criteria toward circularity-audited procurement frameworks.
Food and beverage anchors capacity utilization. Healthcare delivers the most defensible margin structure.
Distribution Channel:
Direct relationships dominate specification-heavy segments while digital platforms compress markups in commoditized flows.
- Direct Sales:Technical service integration and collaborative formulation development sustain converter loyalty in medical and high-barrier food segments.
- Distributors:Inventory pooling and logistics consolidation serve mid-volume North American and European converters without captive compounding capabilities.
- Online Retail:Digital procurement platforms are compressing traditional distributor markups in standardized industrial and agricultural film grades.
- Others:Agent networks and cooperative purchasing arrangements retain relevance in fragmented regional markets.
Direct sales capture the most complex specifications. Online retail is gaining share fastest in commoditized gauge ranges.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene and propylene feedstock availability from the US Gulf Coast petrochemical corridor anchors North American cast film production economics. Naphtha-based resin supply chains in Western Europe and the Middle East shape converter procurement patterns across transatlantic trade lanes.
United States
Shale gas economics sustain polyethylene resin cost advantages for domestic food packaging converters. FDA food contact notification requirements govern monomer migration limits for suppliers serving transatlantic consumer goods brands. The Gulf Coast petrochemical corridor from Houston to Lake Charles concentrates extrusion capacity investments responding to flexible packaging demand from CPG manufacturers.
Germany
REACH chemical authorization frameworks and EU Green Deal circular economy mandates are accelerating reformulation investments across converter networks. ECHA monomer migration limits constrain additive packages for pharmaceutical blister film applications. The Rhine-Ruhr industrial region and Bavarian chemical clusters host specialized compounding operations serving medical-grade polypropylene specifications.
China
Domestic polyolefin capacity expansions are reducing import dependence for flexible packaging substrates. GB standards and SAMR food contact regulations tighten formulation compliance for exporters serving Western brand owners. The Yangtze River Delta around Shanghai and the Pearl River Delta manufacturing belt concentrate cast line investments serving regional consumer goods production.
India
UFlex and Jindal Poly Films are scaling domestic biaxial and cast line capacity to capture flexible packaging growth in food and consumer goods sectors. BIS certification requirements and FSSAI food contact standards govern substrate qualification for domestic and export markets. The Gujarat industrial corridor and Maharashtra packaging belt around Mumbai are emerging as primary capacity hubs.
Japan
High-clarity cast polypropylene specifications for premium fresh produce packaging sustain technology leadership in optical uniformity control. METI circular economy roadmaps and JIS standards drive recycled content integration requirements. The Chubu region around Nagoya maintains specialized extrusion expertise serving pharmaceutical and electronics packaging segments.
Cast Films Market Competitive Environment
Global majors compete with regional champions across resin compounding capabilities and converter technical service integration. The vendor base stratifies into three tiers: integrated multinationals with captive polymer supply, regional specialists with formulation expertise, and commodity converters competing on scale economics. Strategic archetypes include backward-integrated resin producers, design-to-recyclability service providers, and digital procurement platform operators. Dominant competitive moves center on M&A for geographic footprint expansion and capacity investments in high-barrier coating integration.
Among Asia-Pacific-based fabricators, UFlex Ltd. and Jindal Poly Films Limited exemplify regional scale champions concentrating investments in domestic cast and biaxial line capacity. Profol Kunststoffe GmbH represents the European specialist archetype with compounding capabilities sustaining margin stability across specialty polypropylene grades. Taghleef Industries LLC anchors the multinational integrated tier through manufacturing scale spanning the Americas, Europe, and Asia-Pacific.
| Leading Market Players |
|---|
| Polyplex Corporation Ltd |
| Profol Kunststoffe GmbH |
| Taghleef Industries LLC |
| Winpak Ltd. |
| Amcor Plc |
| UFlex Ltd. |
| Berry Global, Inc. |
| Scientex Berhad |
| Jindal Poly Films Limited |
| Others |
Value Chain & Pricing Dynamics
Barrier-grade certification divergence between food-contact compliant and industrial-grade cast films manifests in both pricing premiums and supply chain sourcing configurations, with EU REACH-authorized additive packages commanding dedicated compounding runs and captive resin handling investments.
Pricing Analysis
Technical service bundling separates integrated design-to-recyclability providers from commodity converters competing on unbundled per-kilogram rates. Three-tier pricing structure across premium, standard, and economy levels tracks FDA notification status, REACH authorization completeness, and recycled content verification tiers. Cost compression in commodity polyethylene grades is intensifying because of naphtha feedstock volatility and Indian domestic capacity scaling. Mid-volume converters without captive compounding capabilities exhibit highest price sensitivity, while pharmaceutical manufacturers accept premium positioning for ISO 11607-compliant sterile barrier specifications.
Supply Chain Analysis
Containerized freight cost differentials between US Gulf Coast ethylene corridors and European naphtha-based resin networks shape converter procurement economics across transatlantic lanes. Supply concentrates in the United States, Germany, and India, with feedstock availability from shale gas economics and domestic polyolefin expansions anchoring regional cost structures. Raw material flows draw from linear low-density polyethylene, metallocene catalyst systems, and specialty polypropylene homopolymer grades. Single-source vulnerability sits with antioxidant and stabilizer additive packages facing REACH sunset date enforcement. Distribution runs through direct technical service relationships in medical segments and digital procurement platforms compressing markups in standardized industrial grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty-grade capacity scarcity props pricing power for converters with captive compounding and barrier coating integration, creating defensible margin structures as commodity polyethylene faces oversupply pressure from Indian domestic scaling.
For Market Incumbents: Anticipate REACH authorization list expansion by accelerating bio-based stabilizer system qualification ahead of sunset date enforcement. Secure backward integration into metallocene catalyst supply or specialty polypropylene compounding to defend margin position against naphtha feedstock volatility. Prioritize barrier coating line investments in Germany and the US Gulf Coast to capture EU Green Deal circular economy mandate tailwinds. For New Entrants and Emerging Players: Mid-volume North American converters seeking digital procurement alternatives represent the most penetrable buyer archetype for platform-based market entry. Target thermoformable high-clarity segments in fresh produce packaging where optical uniformity control commands specification premiums. Pursue direct-to-converter technical service partnerships rather than distributor markups to establish initial converter relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated multinationals seeking geographic footprint expansion and barrier coating capabilities. Long-term viability favors regional specialists with formulation expertise and mass-balance certification infrastructure over commodity converters exposed to resin price volatility. Monitor EU packaging waste directive implementation timelines as inflection indicator for compliance-service revenue stream valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating Line Investment | Captures EU Green Deal recyclable packaging mandates across German and Dutch converter networks. |
| Backward Integration into Compounding | Insulates margin stability from propylene feedstock volatility via captive specialty grade production. |
| Digital Procurement Platform Launch | Compresses traditional distributor markups in North American mid-volume industrial film segments. |
| Bio-based Stabilizer Qualification | Pre-empts REACH sunset date enforcement for pharmaceutical blister film applications in France. |
| Mass-balance Certification Infrastructure | Gates commercial relationships with UK and Nordic private-label retail sustainability scorecards. |
Study Parameters
Trade databases, customs records, and SEC filings formed the secondary backbone, cross-referenced with primary interviews across extrusion plant managers, flexible packaging procurement leads at consumer goods manufacturers, distribution channel partners, and technical R&D directors at additive suppliers. Bottom-up and top-down triangulation validated resin volume flows and converter capacity utilization estimates.
Analytical lens combined bottom-up extrusion line capacity modeling with top-down end-use demand segmentation across food packaging, medical sterile barrier, and industrial protection applications. Modeled dimensions spanned resin chemistry tier, barrier specification level, geographic production hub, and regulatory compliance cluster. CAGRs derived from weighted average of historical capacity expansion patterns and brand-owner sustainability procurement mandate diffusion curves, incorporating polyolefin price elasticity and REACH reformulation cost pass-through assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU extended producer responsibility mandate implementation pacing and mechanical recycling contamination threshold technical breakthroughs. Forecasts reflect documented assumptions regarding feedstock cost trajectories and regulatory enforcement timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Europe Single-Use Plastic Packaging Market
Plastic Packaging
Plastic Medicine Bottles Market
Plastic Packaging
Plastic Canister Market
Plastic Packaging
Blow Molded Bottles Market
Plastic Packaging
United States Plastic Packaging Films Market
Plastic Packaging
Plant-Based Plastic Packaging Market
Plastic Packaging
Cast Stretch Films Market
Plastic Packaging
Packaging Industry in South Africa Market
Plastic Packaging
Vacuum Forming Plastic Market
Plastic Packaging
PE Blow Molded Products Market
Plastic Packaging
Thermoforming Plastic Market
Plastic Packaging
Plastic Packaging Market
Plastic Packaging
Corrugated Plastic Box Market
Plastic Packaging
Malaysia and Thailand Thermoformed Plastic Market
Plastic Packaging
Europe Plastic Packaging Films Market
Plastic Packaging
PCR Plastic Packaging Market