
 Inflatable Bags Packaging Market | 2026-2036
Inflatable Bags Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Inflatable Bags Packaging Market Foresight
North American film extrusion capacity is restructuring as resin suppliers redirect output toward protective packaging grades. Sealed Air Corporation leverages integrated bubble and air pillow manufacturing across multiple US states. Pregis Corporation anchors Midwest distribution through automated fulfillment equipment paired with consumables. Storopack Hans Reichenecker GmbH competes with regionalized European production and reusable inflatable systems.
Inflatable bags packaging consists of air-filled chambers formed from extruded thermoplastic films, typically 30-80 microns in thickness, heat-sealed into pillows, cushions, or custom geometries to absorb shock during transit. The primary commercial purpose centers on replacing molded foam and loose-fill materials with lightweight, on-demand void fill that reduces dimensional weight shipping costs. Air pillow configurations dominate e-commerce fulfillment due to high-speed inflation compatibility with automated packing stations, while air bag formats capture automotive component shipping where puncture resistance requirements exceed standard cushion performance. Polyethylene formulations sustain margin pools through established recycling infrastructure, though polypropylene blends are gaining traction in electronics for their stiffer cell structure.
FDA guidelines for pharmaceutical contact materials and EU REACH compliance on plasticizer content shape material selection for inflatable packaging serving regulated end uses. The EPA's emphasis on recycled content thresholds and California's SB 54 extended producer responsibility framework are pressuring converters to certify post-consumer resin incorporation. Stakeholders must monitor how state-level packaging EPR laws proliferate and whether on-site inflation equipment economics continue displacing pre-filled alternatives in mid-volume fulfillment operations.
Market Dynamics
E-commerce fulfillment velocity requirements are compressing packaging decision cycles, forcing converters to integrate on-site inflation equipment with warehouse management systems rather than shipping pre-filled inventory.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Material recovery mandates across member states are accelerating adoption of recyclable polyethylene formulations in automotive and electronics logistics corridors.
- Automotive component shipping:German OEMs and tier suppliers are specifying air bag formats with enhanced puncture resistance for powertrain and sensor modules, displacing molded foam in just-in-time delivery networks.
- On-demand inflation systems:Mid-volume fulfillment operations are deploying automated packing stations that generate void fill at line speed, eliminating dimensional weight penalties from pre-filled cushion inventory.
Market Restraints
- Resin price volatility:Ethylene and propylene feedstock swings compress converter margins on fixed-price annual contracts with e-commerce platforms.
- Film extrusion concentration:North American capacity restructuring leaves protective packaging grades dependent on a narrowing supplier base with divergent polymer allocation priorities.
- Mechanical recycling limitations:Multi-layer barrier films and adhesive laminates in reusable inflatable systems face infrastructure gaps in municipal sorting facilities, limiting closed-loop claims.
Strategic Opportunities
- India e-commerce logistics:Fulfillment center buildouts by domestic and cross-border retailers are creating first-mover advantages for equipment-and-consumables bundling models.
- California SB 54 EPR framework:Extended producer responsibility laws are incentivizing post-consumer resin certification that commands premium positioning in sustainability-driven procurement.
- RFID-enabled smart packaging:Integration of pressure sensors and track-and-trace tags is unifying protective function with supply chain visibility for high-value pharmaceutical shipments.
Industry Challenges
- Automation integration:Legacy warehouse management systems require middleware development to synchronize inflation equipment with order-picking workflows, extending deployment timelines.
- REACH compliance documentation:EU chemical safety data sheet maintenance for plasticizer content creates ongoing regulatory overhead for converters serving pharmaceutical and food contact applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inflatable Bags Packaging Market |
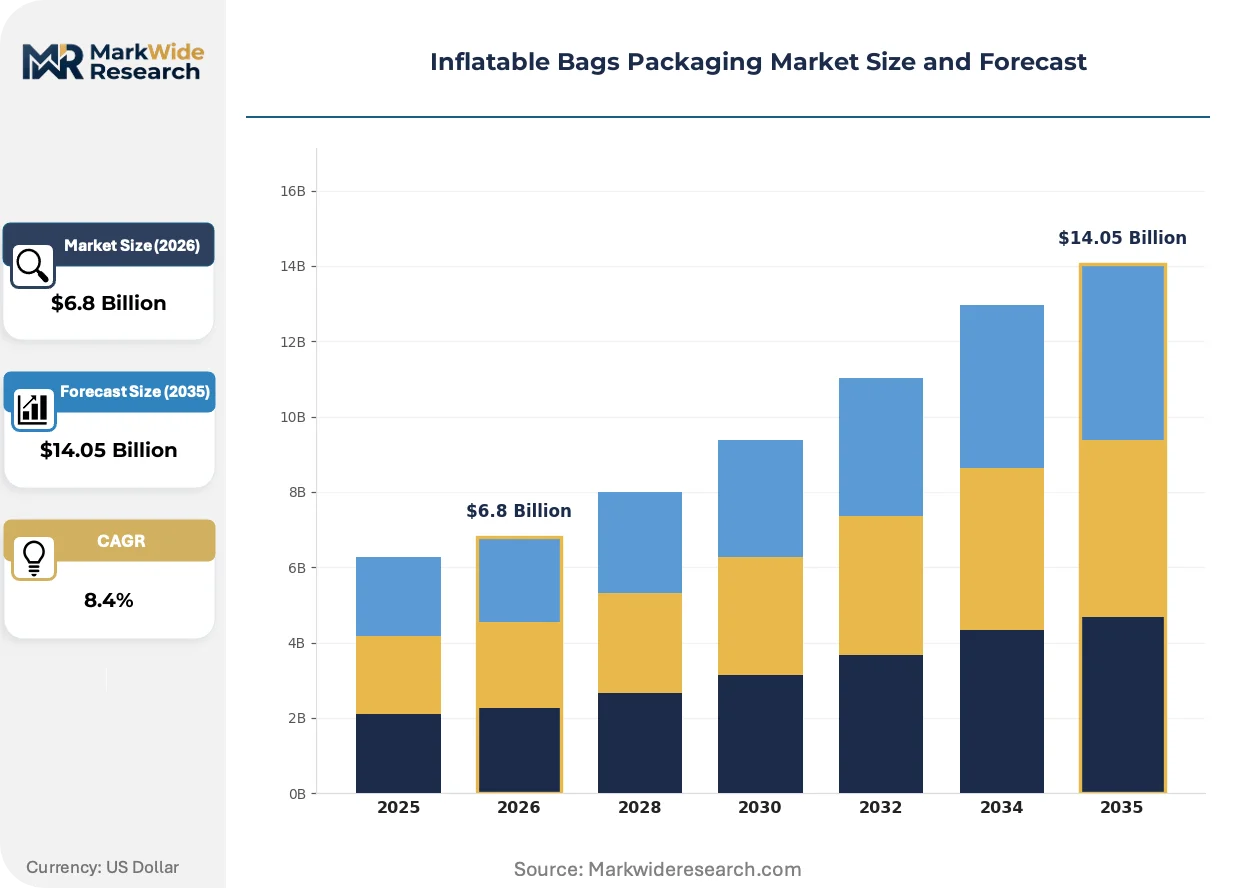
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Pillows, Air Bags, Air Cushions, Bubble Wrap Material: Polyethylene, Polypropylene, PVC, EVA End User: E-commerce, Electronics, Automotive, Pharmaceuticals Application: Product Protection, Void Fill, Shipping, Logistics |
| Companies Covered | Sealed Air Corporation, Pregis Corporation, Storopack Hans Reichenecker GmbH, Fromm Packaging Systems Inc., Polyair Inter Pack Inc., Smurfit Kappa, Automated Packaging Systems, Aeris Protective Packaging Inc., Inflatable Packaging Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inflatable Bags Packaging Market Shifts & Advancements
Material science advances and regulatory pressure are converging to redefine performance specifications and recovery pathways across inflatable packaging formats.
Mono-material polyethylene films with enhanced seal integrity are unifying puncture resistance and recyclability in a single substrate architecture. Automotive logistics buyers in Stuttgart and Wolfsburg are specifying these grades for powertrain component shipments, compressing the historical trade-off between protection performance and circularity certification.
REACH restrictions on phthalate plasticizers are forcing reformulation of flexible film compounds for pharmaceutical and food contact applications. German converters are accelerating migration to bio-based plasticizer alternatives ahead of ECHA sunset dates, with medical device packaging representing the most affected segment due to FDA parallel compliance requirements.
Subscription-based equipment financing is displacing capital purchase models for automated inflation systems. Third-party logistics providers in the Netherlands and Belgium are adopting per-package pricing structures that bundle machinery, maintenance, and consumables, shifting balance sheet exposure from operators to packaging suppliers.
Inflatable Bags Packaging Market Segmentation
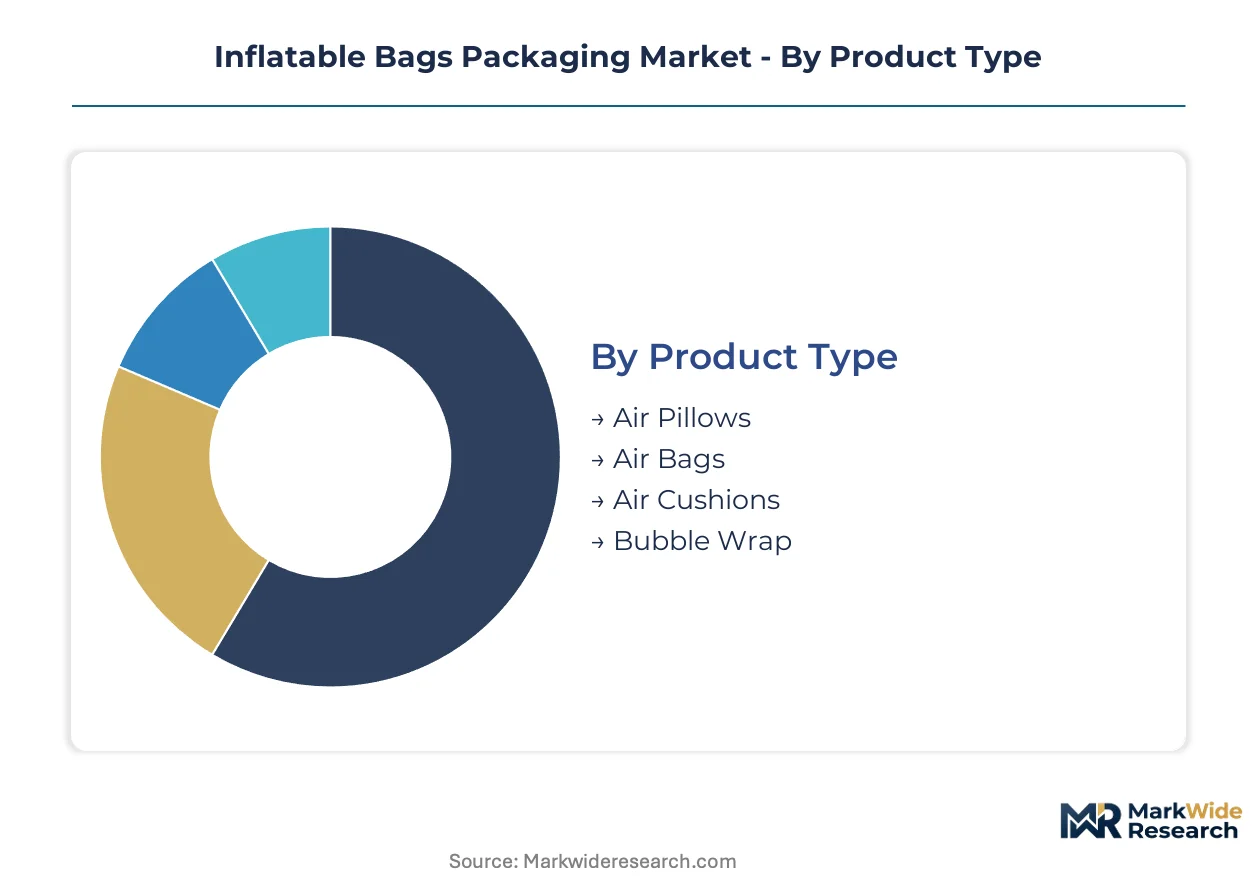
Segmentation in inflatable bags packaging separates volume-driven commodity formats from precision-engineered protective solutions. Material selection and end-use specifications determine margin structures, recycling pathways, and equipment compatibility requirements across converter portfolios.
Product Type:
Film extrusion capacity concentrates disproportionately toward high-throughput formats that integrate with automated fulfillment infrastructure.
- Air Pillows:Continuous-seam polyethylene chambers inflated on-demand through venturi systems, typically 200-400mm in length. E-commerce fulfillment centers in Germany and the Netherlands deploy these at line speeds exceeding 15 meters per minute, displacing pre-filled alternatives to eliminate dimensional weight penalties.
- Air Bags:Multi-chamber geometries with heat-sealed baffles providing puncture resistance for sharp-edged components. Stuttgart automotive clusters specify these for powertrain module shipping, where cell integrity must survive 72-hour just-in-time delivery cycles.
- Air Cushions:Pre-formed quilted films requiring offline inflation, common in mid-volume operations lacking capital for integrated systems.
- Bubble Wrap:Legacy format with trapped-air hemispheres, still prevalent in electronics refurbishment and secondary packaging tiers.
Air pillows absorb the bulk of installed capacity; air bags are expanding most quickly.
Material:
Cost tier positioning separates established recycling infrastructure from emerging performance grades.
- Polyethylene:Linear low-density formulations dominate through established mechanical recycling streams and FDA compliance for food contact. German converters leverage this substrate for pharmaceutical logistics serving EU REACH documentation requirements.
- Polypropylene:Stiffer cell structures with higher temperature resistance, gaining share in electronics packaging where dimensional stability under warehouse heat matters. California SB 54 EPR frameworks complicate recovery claims due to sorting infrastructure gaps.
- PVC:Declining adoption restricted to specialized chemical resistance applications; plasticizer content triggers REACH sunset date pressures.
- EVA:Premium co-polymer for medical device cushioning, commanding price multiples due to ethylene-vinyl acetate supply concentration.
Polyethylene commands the volume base; polypropylene climbs the fastest on electronics specification shifts.
End User:
Customer type determines equipment bundling models versus consumables-only supply relationships.
- E-commerce:Third-party logistics providers drive subscription-based equipment financing, with per-package pricing structures displacing capital purchases in Netherlands and Belgium fulfillment networks.
- Electronics:OEM packaging engineers specify mono-material films to satisfy EPEAT and TCO certification requirements for circularity claims.
- Automotive:Tier suppliers in Wolfsburg and Munich corridors require air bag formats with documented puncture resistance testing under VDA standards.
- Pharmaceuticals:FDA validation and EU GMP Annex 1 compliance create documentation overhead that favors incumbent converters with established master file submissions.
E-commerce absorbs dominant capacity share; automotive is gaining share fastest on just-in-time network expansion.
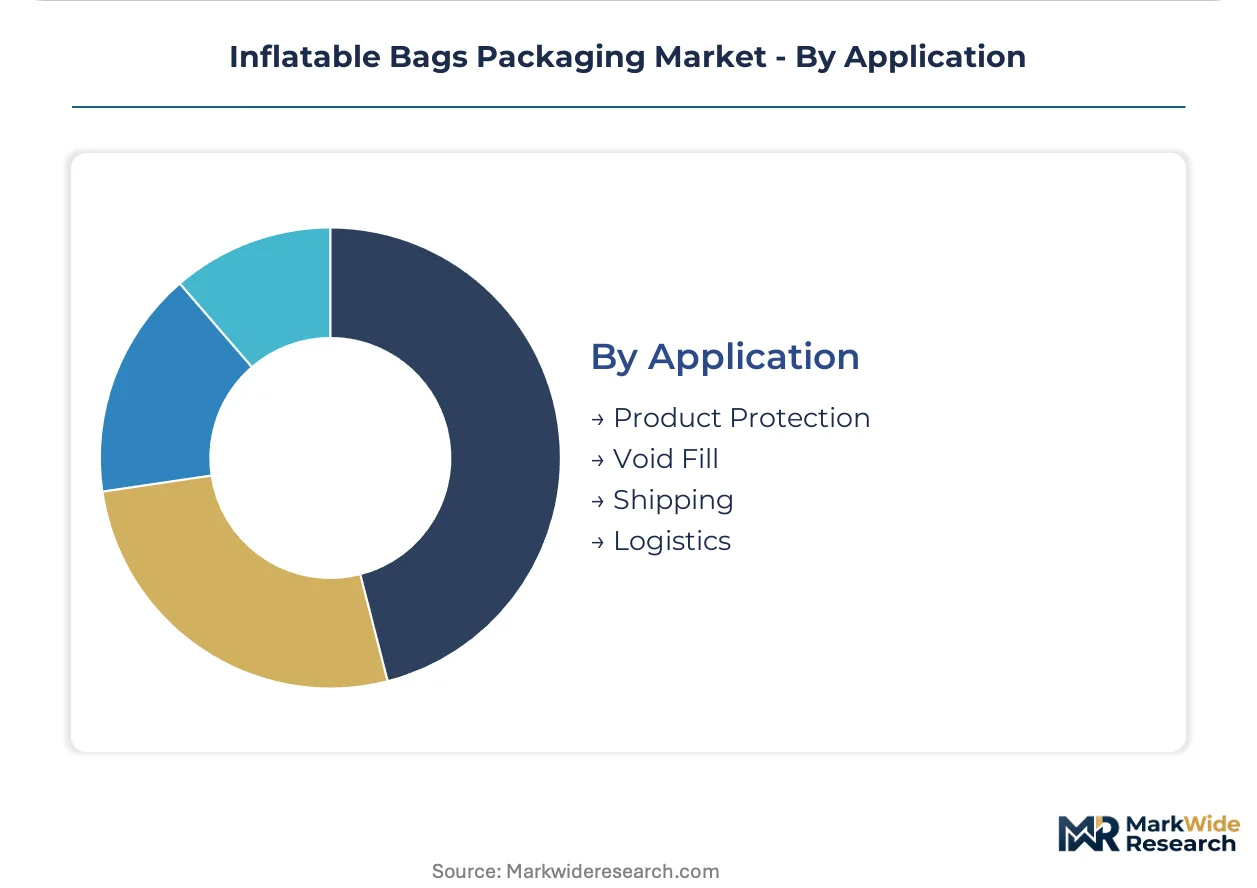
Application:
Functional purpose separates commodity void displacement from engineered shock absorption specifications.
- Product Protection:Surface-conforming geometries with pressure distribution mapping for fragile electronics, glass, and precision instruments.
- Void Fill:Dimensional stabilization of mixed-carton shipments, the largest volume application driven by e-commerce carton optimization algorithms.
- Shipping:External dunnage for palletized freight, requiring higher burst strength than internal cushioning formats.
- Logistics:Reusable inflatable systems for closed-loop automotive component circuits between assembly plants and sequencing centers.
Void fill anchors volume deployment; logistics represents the steepest expansion trajectory on reusable system adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene feedstock availability along the US Gulf Coast anchors North American film extrusion capacity for protective packaging grades. Converter operations concentrate in Texas and Louisiana corridors with pipeline access to petrochemical supply.
United States
E-commerce fulfillment velocity drives automated packing station deployment across Midwest distribution hubs. EPA recycled content thresholds pressure converters toward post-consumer resin certification. Sealed Air Corporation operates integrated bubble and air pillow manufacturing across multiple states to serve Amazon and Walmart logistics networks.
Germany
Automotive component shipping specifications from Stuttgart OEMs demand air bag formats with VDA-standard puncture resistance. EU REACH compliance on plasticizer content shapes material selection for pharmaceutical logistics. Wolfsburg and Munich corridors host dense tier-supplier clusters adopting just-in-time inflatable systems.
China
Domestic e-commerce platform expansion creates demand for high-speed inflation equipment in Yangtze River Delta fulfillment centers. NMPA medical device packaging regulations align with international standards for export-oriented manufacturing. Shenzhen electronics clusters specify mono-material polyethylene films for circularity claims in EU-bound shipments.
India
Flipkart and Amazon India fulfillment center buildouts drive first-mover opportunities for equipment-and-consumables bundling. BIS certification requirements for food-contact materials shape converter compliance investments. Maharashtra and Karnataka logistics corridors concentrate mid-volume operations transitioning from pre-filled to on-demand inflation.
Netherlands
Third-party logistics providers pioneer subscription-based equipment financing with per-package pricing structures. EU Packaging and Packaging Waste Regulation mandates accelerate recyclable polyethylene adoption in Rotterdam-Antwerp logistics hubs. Automated packing stations in Eindhoven distribution centers achieve line speeds exceeding 15 meters per minute.
Inflatable Bags Packaging Market Competitive Landscape
Global majors compete with regional champions across equipment integration and consumables supply. The vendor base separates into consolidated film extruders with captive machinery divisions, specialized equipment manufacturers licensing technology, and regional converters focused on reusable system logistics. Three archetypes dominate: integrated packaging systems providers, standalone inflation equipment specialists, and reusable inflatable logistics operators. Capacity expansion and strategic partnerships constitute the primary competitive moves, with M&A activity concentrating in automated fulfillment technology.
Within the integrated systems tier, Sealed Air Corporation and Pregis Corporation exemplify the equipment-consumables bundling model that compresses customer acquisition costs in high-volume e-commerce channels. Storopack Hans Reichenecker GmbH occupies a position among European reusable inflatable specialists competing through regionalized production networks. These three anchors illustrate how geographic proximity to automotive and electronics clusters shapes competitive positioning in protective packaging supply.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Pregis Corporation |
| Storopack Hans Reichenecker GmbH |
| Fromm Packaging Systems Inc. |
| Polyair Inter Pack Inc. |
| Smurfit Kappa |
| Automated Packaging Systems |
| Aeris Protective Packaging Inc. |
| Inflatable Packaging Inc. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up film extrusion specialists have consolidated North American capacity, tightening supply discipline and compressing margin pools for converters serving e-commerce platforms. This ownership concentration feeds directly into pricing power dynamics, as resin allocation priorities favor protective packaging grades with long-term contract structures over spot-market sales.
Pricing Analysis
Warranty and preventive maintenance bundling separates subscription-based equipment financing from bare-metal capital sales in automated inflation systems. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and post-consumer resin content, with California SB 54 compliance commanding measurable premiums. Pricing pressure stems from ethylene feedstock volatility on fixed-price annual contracts. E-commerce third-party logistics providers exhibit highest price sensitivity; pharmaceutical converters with FDA master file submissions show least.
Supply Chain Analysis
Single-source vulnerability sits with US Gulf Coast ethylene crackers supplying linear low-density polyethylene feedstock for protective packaging grades. Manufacturing concentrates in Texas, Louisiana, and Germany, drawing from naphtha and ethane feedstocks. Mechanical recycling infrastructure gaps for multi-layer barrier films create circularity certification bottlenecks. Distribution runs through regional converter networks with just-in-time delivery to automotive clusters in Stuttgart and Wolfsburg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The inflatable bags packaging sector sits in a technology-transition phase, as on-demand inflation systems displace pre-filled inventory models across mid-volume fulfillment operations. Automated packing station integration with warehouse management systems represents the core displacement technology reshaping competitive dynamics.
For Market Incumbents: Cement equipment-consumables bundling relationships through subscription financing models that shift balance sheet exposure to packaging suppliers. Deepen captive film extrusion capacity in Texas and Louisiana corridors to defend margin pools against resin price volatility. Prioritize middleware development for legacy warehouse management system integration to extend deployment timeline advantages against emerging automation specialists.
For New Entrants and Emerging Players: The premium-economy price-point gap in Indian e-commerce logistics offers white-space entry through equipment-and-consumables bundling targeting Flipkart and Amazon India fulfillment buildouts. Maharashtra and Karnataka corridors present the most penetrable geography for first-mover positioning. Pursue BIS certification for food-contact materials as a compliance moat against unqualified regional converters.
For Investors and Strategic Acquirers: Distressed-cycle entries favor European reusable inflatable logistics operators with established closed-loop automotive component circuits. Long-term viability across the projection horizon hinges on circularity certification capabilities and regional production proximity to dense manufacturing clusters. Monitor EU Packaging and Packaging Waste Regulation enforcement timelines as the critical inflection signal for recyclable polyethylene formulation demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captive resin supply from US Gulf Coast crackers insulates converters against ethylene price volatility. |
| Subscription-Based Equipment Financing | Per-package pricing structures shift balance sheet exposure from logistics operators to packaging suppliers in Netherlands corridors. |
| Post-Consumer Resin Certification | California SB 54 compliance enables premium positioning in sustainability-driven procurement from e-commerce platforms. |
| RFID-Enabled Smart Packaging Integration | Pressure sensors and track-and-trace tags unify protective function with supply chain visibility for pharmaceutical shipments. |
| Regional Production Footprint Expansion | Proximity to Stuttgart and Wolfsburg automotive clusters reduces just-in-time delivery risk for air bag formats. |
Research Methodology
Multi-period observation of equipment deployment rates, resin allocation patterns, and regulatory compliance timelines anchored the trend analysis, supplemented by interviews with film extrusion plant managers, e-commerce fulfillment center operations directors, automotive tier supplier procurement leads, and packaging converter technical R&D directors. Secondary validation drew from EPA recycled content threshold documentation, EU REACH substance restriction filings, SEC 10-K disclosures from integrated packaging systems providers, and customs trade data on polyethylene film imports. Bottom-up segmentation modeling and top-down macroeconomic anchoring provided cross-verification.
Input-output matrices mapped film extrusion capacity, inflation equipment installations, and end-use demand across product type, material formulation, end user vertical, and geographic production cluster dimensions. CAGRs were derived through exponential smoothing of annualized growth trajectories against resin price elasticity assumptions and e-commerce fulfillment velocity benchmarks. Industry-specific forecast inputs included automated packing station penetration rates and EU Packaging and Packaging Waste Regulation implementation schedules.
Underlying measurement precision varies by segment; air pillow volume estimates carry tighter precision than reusable inflatable system adoption curves due to equipment financing disclosure gaps. Forecasts reflect documented assumptions on resin price stabilization and regulatory enforcement timelines. Deviation in EU member state transposition schedules or ethylene feedstock cost trajectories would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Vacuum Sealer Bags Market
Bags and Containers
Woven Bags Market
Bags and Containers
Mattress and Furniture Bags Market
Bags and Containers
Ziplock Food Bags Market
Bags and Containers
Cross Bottom Bags Market
Bags and Containers
Self-Sealing Bags Market
Bags and Containers
FIBC Market
Bags and Containers
Bag in Drum Market
Bags and Containers
Craft Bags Market
Bags and Containers
Breathable Bags Market
Bags and Containers
Carry Bag Market
Bags and Containers
Quad Seal Bag Market
Bags and Containers
Twin Seal Bags Market
Bags and Containers
Disposable Garbage Bags Market
Bags and Containers
Non-Barrier Bag Market
Bags and Containers
Global PP Jumbo Bags Market