
 Global Biaxially Oriented Polypropylene (BOPP) in Films and Sheets Market | 2026-2036
Global Biaxially Oriented Polypropylene (BOPP) in Films and Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biaxially Oriented Polypropylene (BOPP) in Films and Sheets Market Analysis
China's BOPP film capacity expansion is reshaping trade flows across Southeast Asia. Toray Plastics leverages its Japanese technology base to sustain premium positioning in optical-grade films. Taghleef Industries anchors European supply through its Italian and Spanish production hubs. Jindal Poly Films dominates Indian domestic demand with integrated resin-to-film operations.
Biaxially Oriented Polypropylene in Films and Sheets denotes polypropylene resin stretched in perpendicular machine and transverse directions to achieve molecular orientation, yielding films with tensile strength exceeding 150 MPa, clarity above 90% haze, and moisture vapor transmission rates below 1.0 g/m²/day for barrier packaging. The process generates thin-gauge substrates that thermoform, print, and seal across high-speed converting lines for food, pharmaceutical, and consumer goods protection. Flexible Films command the largest volume share as snack and bakery converters prioritize downgauging for material cost control, while Labels represent the fastest value-growth segment driven by pressure-sensitive adhesive compatibility and shelf-appeal requirements in personal care. Packaging Sheets retain mature margin pools in industrial wrapping where thickness tolerance and roll consistency outweigh innovation premiums.
FDA food-contact notifications and EU REACH substance restrictions govern monomer purity and additive migration limits for BOPP films serving consumer applications, while China's GB standards and India's BIS certification create parallel compliance tracks for regional market access. The EU Packaging and Packaging Waste Regulation tightens recyclability thresholds that favor single-material polypropylene structures over multi-layer alternatives. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and reformulation costs.
Market Dynamics
Asian converter capacity expansion is compressing European export margins while pulling resin supply chains toward integrated petrochemical hubs in India and China. This geographic rebalancing forces Western producers to defend premium positioning through optical-grade specialization and pharmaceutical-grade certification.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Single-material polypropylene structures gain preference over multi-layer alternatives as recyclability thresholds tighten, accelerating mono-web BOPP adoption in food-contact applications.
- India's PLI scheme for specialty chemicals:Domestic resin production incentives reduce import dependency for converter operations serving FMCG sector expansion in Maharashtra and Gujarat.
- Pressure-sensitive adhesive compatibility:Label stock demand from personal care brands drives value migration toward printable, high-clarity film grades with enhanced shelf-appeal performance.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracking economics and regional refinery maintenance cycles inject margin instability into film extrusion operations.
- China supply concentration:Domestic capacity additions in Zhejiang and Jiangsu provinces displace import demand across Southeast Asian markets.
- Technical thickness floors:Barrier performance requirements prevent downgauging beyond 12-micron thresholds in modified atmosphere meat packaging.
Strategic Opportunities
- Indonesia converter underpenetration:Snack food sector growth in Java and Sumatra outpaces local film supply, creating import substitution potential for regional producers.
- Pharmaceutical blister pack migration:PVC-aluminum replacement with barrier-coated BOPP aligns with DEHP elimination mandates in pediatric dosing applications.
- Digital printing substrate readiness:Water-based ink compatibility and corona treatment consistency enable short-run label production for craft beverage brands.
Industry Challenges
- Tenter frame operator scarcity:Biaxial stretching process expertise concentrates among aging workforces in European and Japanese engineering centers.
- REACH SVHC notification timelines:Substance of very high concern candidate list updates force reformulation cycles that compress product certification windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biaxially Oriented Polypropylene (BOPP) in Films and Sheets Market |
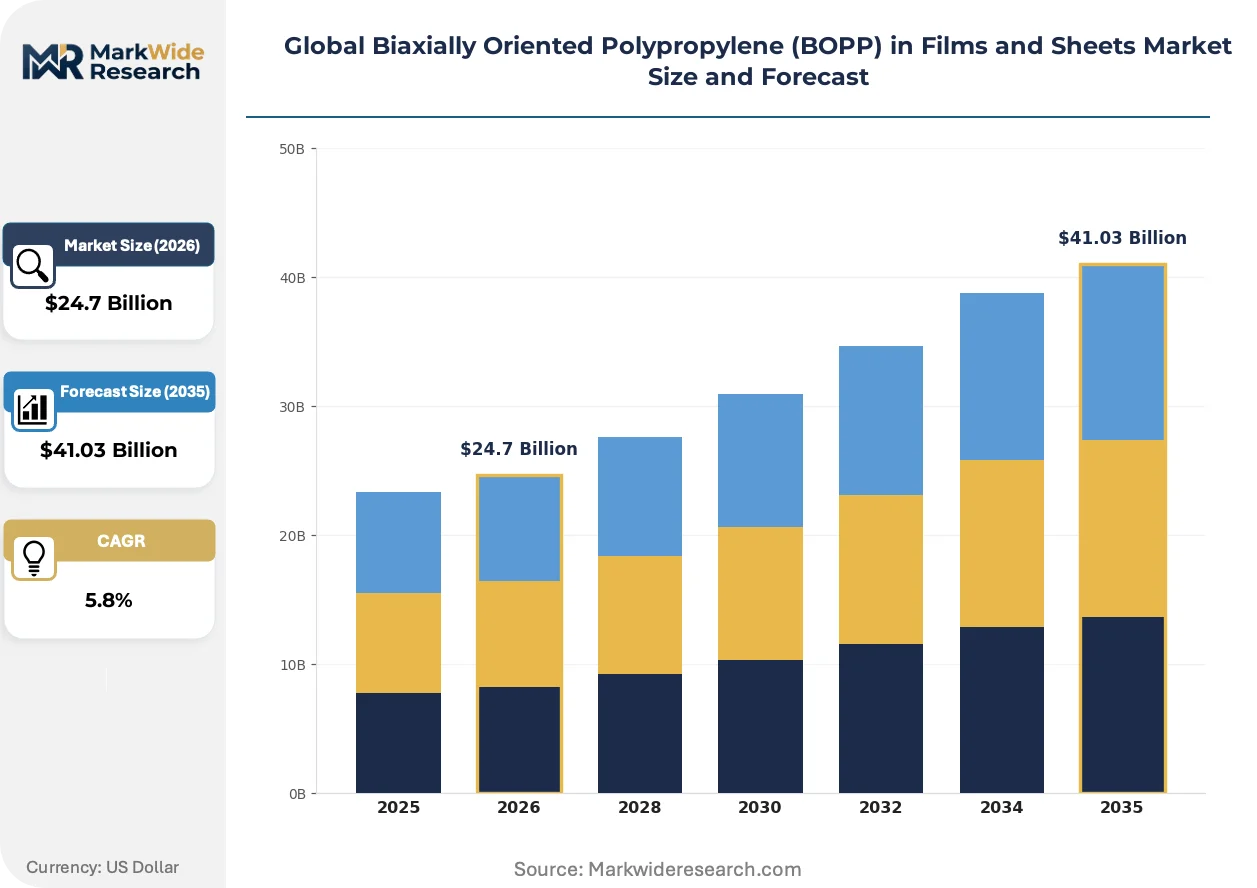
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $41.03 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Films, Labels, Packaging Sheets, Decorative Films Application: Food Packaging, Personal Care, Industrial Packaging, Stationery End User: FMCG, Electronics, Pharmaceuticals, Agriculture Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | Inteplast Group, Polinas, Cosmo Films, Mitsui Chemicals, Toray Plastics, Taghleef Industries, Uflex Ltd., CCL Industries, Jindal Poly Films, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biaxially Oriented Polypropylene (BOPP) in Films and Sheets Market Emerging Trajectories
Process intensification and material redesign are converging to redefine competitive advantage in film manufacturing. Equipment automation and barrier coating chemistry now determine margin capture more than scale economics alone.
Metallized barrier coatings are migrating from vacuum-deposited aluminum toward silicon oxide and aluminum oxide transparent variants. Organic and natural food brands in Germany and the Netherlands adopt these microwaveable, metal-detector-compatible structures for ready-meal packaging. The shift is compressing demand for conventional metallized films in premium segments while opening retort pouch applications previously closed to polypropylene.
REACH substance restrictions on perfluorinated compounds are forcing additive package redesigns for slip and anti-block agents. ECHA evaluation of long-chain perfluorinated substances threatens incumbent masterbatch formulations across European food-contact applications. Converter operations in Italy and Spain accelerate testing of vegetable-derived wax alternatives to maintain compliance timelines.
Brand-owner sustainability scorecards now weight recycled content and end-of-life pathways in film supplier selection. Major FMCG procurement teams in France and the UK unbundle traditional price-volume contracts to incorporate mass-balance certification and mechanical recycling feedstock guarantees. This behavioral shift favors producers with ISCC PLUS or equivalent chain-of-custody documentation over legacy spot-market suppliers.
Global Biaxially Oriented Polypropylene (BOPP) in Films and Sheets Market Segmentation
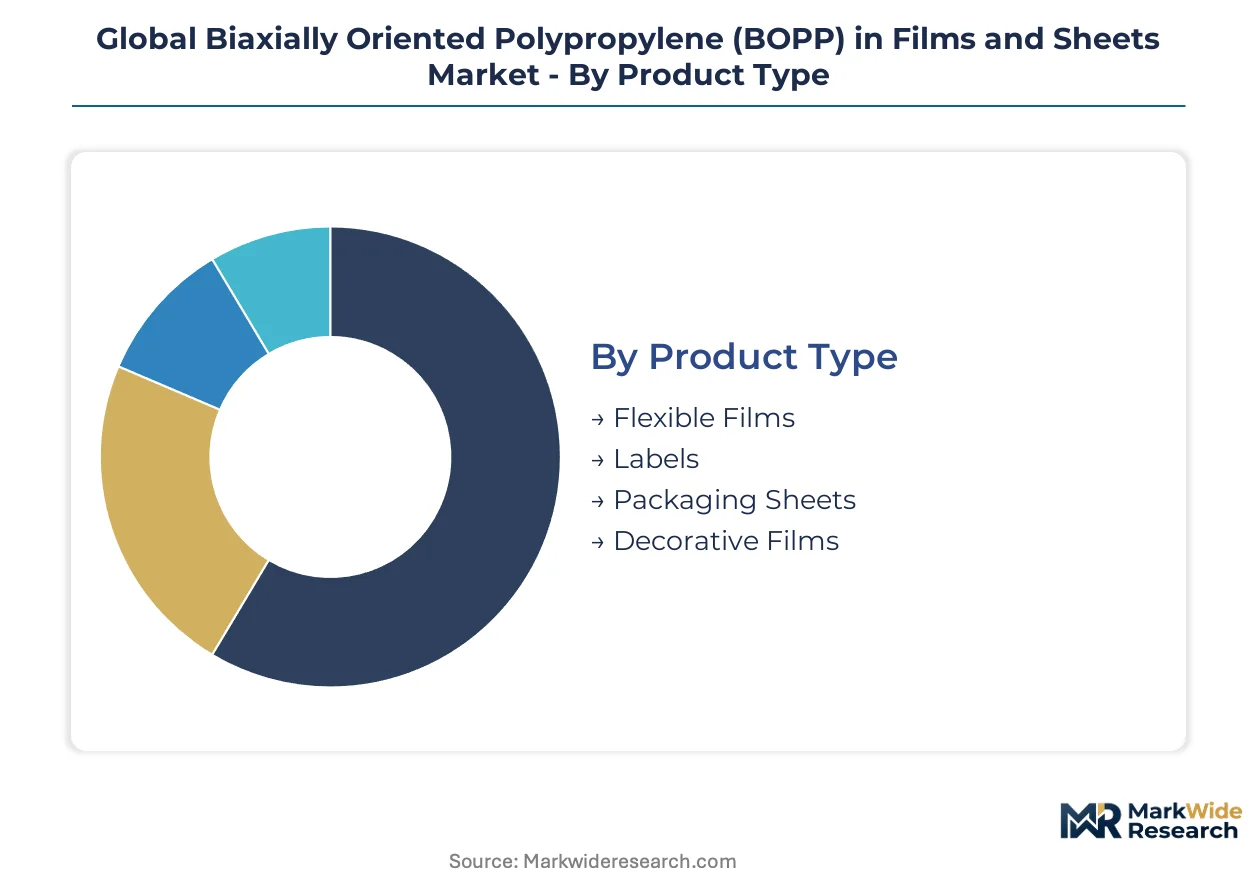
BOPP film manufacturers configure product portfolios around thickness tolerance, barrier specification, and converting line compatibility. Segment boundaries reflect divergent margin pools between commodity food packaging and certified pharmaceutical grades.
Product Type:
Cost tier stratification separates high-volume commodity films from value-added specialty substrates.
- Flexible Films:Thin-gauge substrates ranging 12-40 microns deliver tensile strength above 150 MPa and moisture vapor transmission below 1.0 g/m²/day. Snack and bakery converters in India and China prioritize downgauging to offset propylene feedstock volatility.
- Labels:Pressure-sensitive adhesive-compatible grades with clarity exceeding 90% haze serve personal care brands demanding shelf-appeal differentiation. Craft beverage procurement teams specify corona-treated surfaces for digital printing compatibility.
- Packaging Sheets:Thicker industrial wrapping substrates where roll consistency outweighs innovation premiums.
- Decorative Films:Metallized and holographic variants for consumer goods aesthetics.
Flexible Films commands the established base. The steepest expansion runs through Labels.
Application:
End-use performance requirements dictate barrier coating chemistry and regulatory certification pathways.
- Food Packaging:Modified atmosphere meat applications require 12-micron technical floors to maintain oxygen barrier integrity. EU Packaging and Packaging Waste Regulation recyclability thresholds favor mono-web polypropylene structures over multi-layer alternatives.
- Personal Care:High-clarity label stock and shrink-sleeve applications pressure-sensitive adhesive compatibility requirements from beauty brands in France and the UK.
- Industrial Packaging:Heavy-duty wrapping for textile and metal coil protection.
- Stationery:Transparent film overlays and lamination substrates.
Food Packaging retains volume concentration. Personal Care climbs the fastest on value-per-ton metrics.
End User:
Customer procurement sophistication separates spot-market buyers from integrated converter operations.
- FMCG:Mass-balance certification and ISCC PLUS chain-of-custody documentation now factor into supplier selection alongside unit economics.
- Electronics:Anti-static and release film specifications for component protection.
- Pharmaceuticals:DEHP elimination mandates in pediatric dosing accelerate PVC-aluminum replacement with barrier-coated BOPP blister packs.
- Agriculture:Mulch films and crop protection substrates.
FMCG anchors procurement volume. Pharmaceuticals gains share fastest on certification premiums.
Distribution Channel:
Supply chain configuration reflects order scale predictability and technical service intensity.
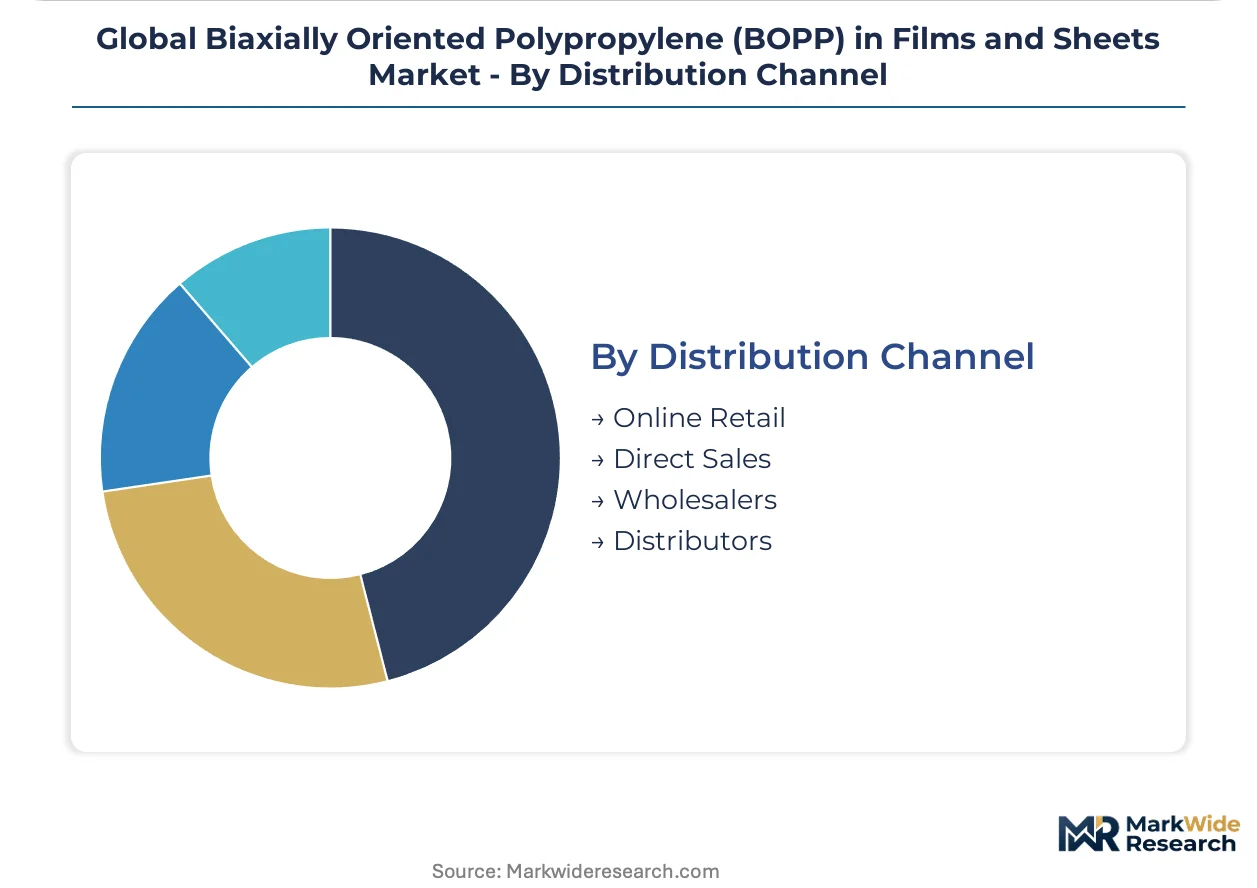
- Direct Sales:Large converter accounts in Maharashtra and Gujarat negotiate resin-to-film integration contracts with domestic producers.
- Distributors:Regional inventory positioning for mid-tier converters requiring just-in-time delivery.
- Online Retail:Standardized gauge products for small-format buyers.
- Wholesalers:Bulk aggregation for industrial packaging segments.
Direct Sales captures the largest contract value. Distributors expands most quickly in underpenetrated regional markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated converter operations in India and China pull resin supply chains eastward while European producers defend premium positioning through optical-grade specialization. Western margins compress as Asian capacity additions displace traditional export flows.
China
Zhejiang and Jiangsu provinces host aggressive capacity additions that displace import demand across Southeast Asian markets. GB standards on food-contact materials create parallel compliance tracks distinct from Western regulatory frameworks. Domestic converter clusters in the Yangtze River Delta serve snack and bakery brands expanding FMCG distribution.
India
Maharashtra and Gujarat converter operations leverage PLI scheme incentives to reduce import dependency for resin supply. BIS certification requirements govern regional market access for food-contact applications. Jindal Poly Films anchors domestic demand through integrated resin-to-film operations serving western industrial corridors.
Germany
Organic and natural food brands in Bavaria and Baden-Württemberg adopt transparent oxide barrier coatings for ready-meal packaging. REACH substance restrictions on perfluorinated compounds force additive package redesigns for slip and anti-block agents. Converter operations in the Rhine-Ruhr industrial region accelerate testing of vegetable-derived wax alternatives.
United States
FDA food-contact notifications govern monomer purity and additive migration limits for consumer-facing applications. Evolving standards tighten material purity requirements for flexible food packaging. Converter clusters in the Midwest and Southeast prioritize downgauging strategies to offset propylene feedstock volatility.
Indonesia
Snack food sector growth in Java and Sumatra outpaces local film supply, creating import substitution potential. Domestic converter underpenetration leaves regional demand exposed to external supply chains. Emerging industrial zones around Jakarta and Surabaya attract investment from regional producers seeking market entry.
Global Biaxially Oriented Polypropylene (BOPP) in Films and Sheets Market Vendor Landscape
Integrated petrochemical conglomerates and specialized film converters split the market between scale-driven commodity supply and certification-heavy premium segments. Toray Plastics leverages Japanese technology licensing to sustain optical-grade positioning. Taghleef Industries anchors European supply through Italian and Spanish production hubs. Jindal Poly Films dominates Indian domestic demand with captive resin operations. Competitive moves concentrate on backward integration into propylene feedstock and pharmaceutical-grade certification acquisition.
Among Asia-Pacific-based producers, Cosmo Films and Uflex Ltd. occupy positions within the flexible packaging specialist tier, while Mitsui Chemicals represents the diversified chemical conglomerate archetype with integrated material science capabilities. Toray Plastics exemplifies the technology-licensing premium player, and Taghleef Industries sits within the regional hub-and-spoke supply structure. Jindal Poly Films anchors the emerging-market integrated producer model. These named entities illustrate how geographic origin and corporate structure shape strategic positioning without prescribing specific product-market combinations.
| Leading Market Players |
|---|
| Inteplast Group |
| Polinas |
| Cosmo Films |
| Mitsui Chemicals |
| Toray Plastics |
| Taghleef Industries |
| Uflex Ltd. |
| CCL Industries |
| Jindal Poly Films |
| Others |
Supply Flow & Price Mechanics
Zhejiang and Jiangsu provinces anchor global BOPP film capacity expansion, and their resin-to-film integration economics compress export pricing power for European and Japanese specialty producers serving Southeast Asian converters.
Pricing Analysis
EU REACH substance restrictions dictate the pricing tier structure across European food-contact applications, separating pharmaceutical-grade certified films from commodity packaging substrates. Three-tier pricing structure across premium optical grades, standard barrier films, and economy commodity rolls reflects certification investment and thickness tolerance capabilities. Cost compression in standard-grade segments is intensifying because Chinese domestic capacity additions displace import demand. Spot-market buyers in Indonesia and Vietnam exhibit highest price sensitivity, while pharmaceutical blister-pack converters in Germany and Japan accept certification premiums.
Supply Chain Analysis
Tariff exposure between China and Southeast Asian markets dominates supply chain risk calculus as regional trade flows reconfigure around domestic converter clusters. Propylene feedstock supply concentrates in integrated petrochemical hubs across China, India, and Saudi Arabia. Raw material dependencies rest on naphtha-cracking economics, refinery maintenance cycles, and regional propylene monomer availability. Single-source vulnerability concentrates in European tenter frame engineering expertise. Distribution runs through direct sales contracts with large converter accounts and regional distributor networks for mid-tier buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biaxial stretching process expertise concentrates among aging workforces in European and Japanese engineering centers, creating a capability scarcity that will constrain capacity expansion and inflate specialist labor premiums.
For Market Incumbents: Harden pharmaceutical-grade certification portfolios against PVC-aluminum substitution demand in pediatric dosing applications. Deepen backward integration into propylene feedstock through captive resin operations or long-term offtake agreements with Zhejiang and Jiangsu petrochemical complexes. Channel control through direct converter relationships in Maharashtra and Gujarat defends margin pools against spot-market erosion. For New Entrants and Emerging Players: Mid-market label stock converters in Indonesia represent the most penetrable entry point, as snack food sector growth in Java and Sumatra outpaces local film supply. Barrier-coated BOPP for pharmaceutical blister packs offers certification-premium capture with lower capital intensity than optical-grade film lines. Go-to-market positioning should emphasize water-based ink compatibility and corona treatment consistency for digital printing substrate readiness. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because tenter frame operator scarcity and REACH SVHC notification timelines compress product certification windows for sub-scale producers. Target acquisition archetype: regional European converters with established ISCC PLUS chain-of-custody documentation and vegetable-derived wax additive testing capabilities. Monitor ECHA candidate list updates for long-chain perfluorinated substances as inflection indicator for reformulation-driven M&A activity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Feedstock | Captive resin supply insulates margin volatility from naphtha-cracking economics in Zhejiang hubs. |
| Pharmaceutical-Grade Certification Acquisition | DEHP elimination mandates in pediatric dosing accelerate PVC-aluminum replacement demand. |
| Barrier Coating Chemistry R&D Investment | Silicon oxide transparent variants open retort pouch applications previously closed to polypropylene. |
| ISCC PLUS Chain-of-Custody Documentation | Mass-balance certification satisfies FMCG procurement scorecards in France and the UK. |
| Regional Converter Joint Venture | Local film supply partnerships capture import substitution potential in Indonesian snack food markets. |
Methodological Framework
The analysis maps flexible films, labels, packaging sheets, and decorative film sub-sectors, each validated through film extrusion plant managers, procurement leads at FMCG converters, distribution channel partners, and technical R&D directors specializing in barrier coatings. Primary interviews combined with secondary validation from customs and trade data, BIS certification records, SEC 10-K filings, and ECHA substance restriction updates. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Assumptions held fixed include regulatory compliance timelines for REACH SVHC notifications and FDA food-contact material standards, while propylene feedstock volatility and Asian capacity addition rates varied across scenarios. Segmentation dimensions modeled encompass product type, application end-use, and regional production hub clustering. CAGRs derived from elasticity-adjusted demand projections and capacity utilization trajectories. Forecast inputs incorporated PLI scheme incentive disbursement patterns in Maharashtra and Gujarat and GB standards evolution for food-contact materials.
Practitioners should monitor ECHA candidate list expansion and China's dual carbon policy implementation for early signals of reformulation cost inflation and capacity relocation. Forecasts reflect these documented assumptions and risk factors including tenter frame operator retirement waves and regional refinery maintenance cycle disruptions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Germany Plastic Packaging Films Market
Poly film
Polymer Waterproof Rolls Market
Poly film
Polystyrene Films Market
Poly film
Middle East and Africa Plastic Packaging Films Market
Poly film
Twist Wrap Film Market
Poly film
Biaxially Oriented Polyethylene Terephthalate (BOPET) Films Market
Poly film
Foamed Polypropylene Films Market
Poly film
India Plastic Packaging Film Market
Poly film
High Density Polyethylene Film Market
Poly film
Polyurethane (PU) Film Market
Poly film
Global Blown Stretch Packaging Films Market
Poly film
Polyolefin (POF) Shrink Film Market
Poly film
Polyethylene Cast Film Market
Poly film
PCR Lidding Films Market
Poly film
United States Polycarbonate Sheets and Films Market
Poly film
Lidding Films Market