
 Screen Print Label Market | 2026-2036
Screen Print Label Market Size, Share, and Industry Trends Forecast 2026-2036
Screen Print Label Market Analytics
China is reshaping competitive dynamics in screen print label supply through expanded converting capacity and integrated ink manufacturing. Fort Dearborn Company leverages its food and beverage specialization to anchor North American contract label demand. Mondi PLC sustains European supply security through integrated pulp-to-label operations across multiple substrates. CCL Industries Inc. dominates healthcare and specialty applications through global manufacturing scale and regulatory certification depth.
Screen print labels are graphic overlays produced by forcing ink through a mesh stencil onto substrates such as vinyl, polyester, or polypropylene, achieving thicknesses of 4–12 mils with abrasion resistance exceeding 1,000 Taber cycles. The process serves industrial and consumer applications requiring durability, opacity, and tactile dimensionality where digital or flexographic methods fall short. Product labels command the largest value share within label type segmentation, sustained by premium cosmetics and craft beverage branding requirements. Pressure sensitive adhesive formats lead volume across adhesive type categories, though water-activated variants gain traction in sustainable packaging lines. Vinyl and polyester materials capture disproportionate margin pools due to outdoor durability specifications in automotive and electronics end uses.
REACH in Europe and FDA indirect food contact regulations in the United States constrain ink chemistry and substrate selection, elevating compliance costs for non-integrated converters. EPA VOC emission thresholds in US printing facilities drive capital expenditure toward enclosed screen systems and solvent recovery infrastructure. Stakeholders must monitor evolving state-level extended producer responsibility frameworks and assess backward integration into ink formulation or substrate extrusion to preserve margin structures.
Market Dynamics
REACH compliance in Europe and EPA VOC thresholds in the United States are compressing ink formulation flexibility while elevating capital requirements for solvent recovery systems and enclosed screen infrastructure.
Growth Catalysts
- Craft beverage branding surge:Small-batch breweries and distilleries specify tactile, high-opacity labels that flexographic methods cannot replicate. Screen print thickness delivers the premium shelf presence these brands require.
- REACH low-VOC mandates:European converters accelerate adoption of water-based and UV-curable ink systems to meet ECHA emission limits. This drives equipment refresh cycles and technical service revenue for press manufacturers.
- Automotive electronics labeling:Under-hood component manufacturers specify polyester and vinyl substrates with abrasion resistance exceeding 1,000 Taber cycles. Screen print remains the only viable process for these durability specifications.
Market Restraints
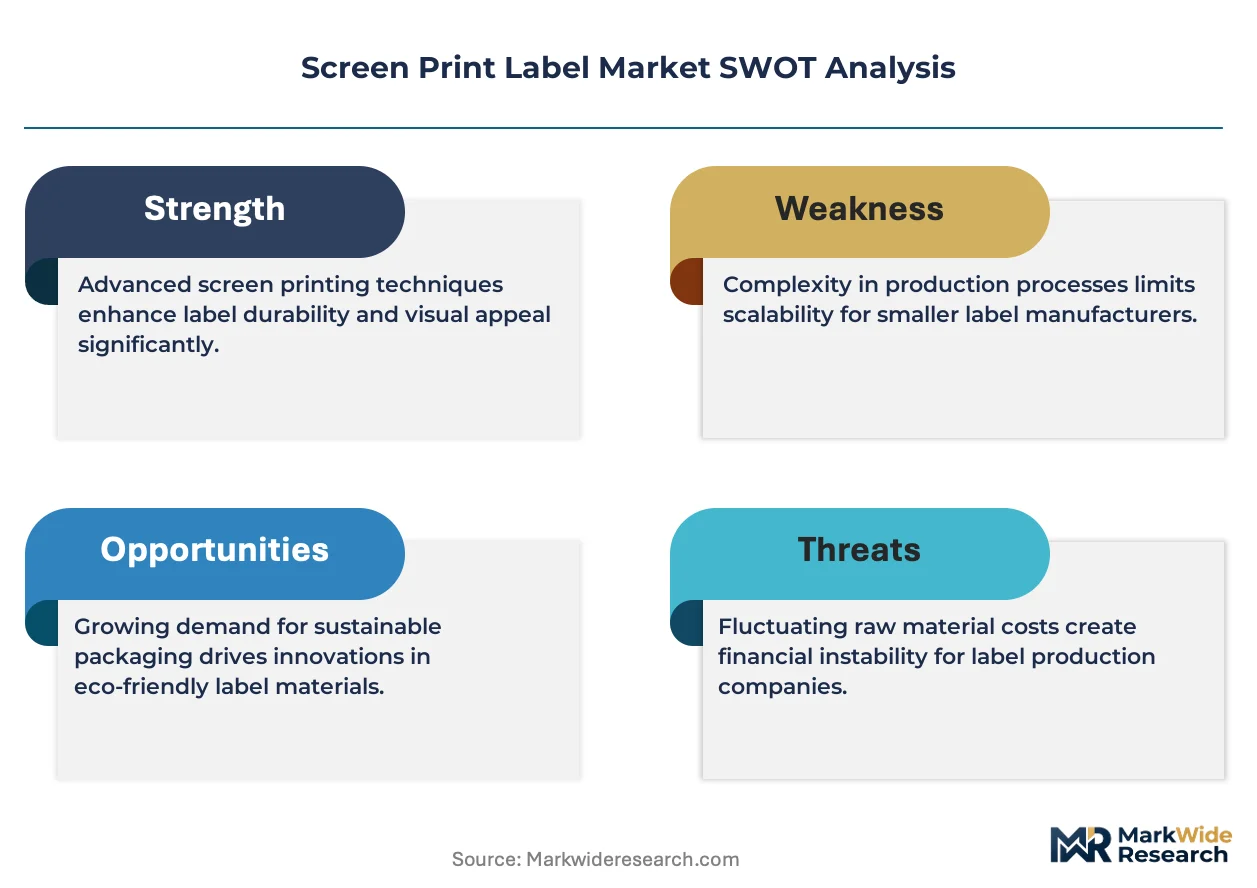
- Petrochemical input volatility:Polyester and vinyl substrate prices fluctuate with crude oil derivatives. Converters without backward integration into extrusion face margin compression during feedstock spikes.
- Digital print substitution in short runs:UV inkjet systems capture runs below 500 units with faster turnaround. Screen print equipment utilization rates decline in commercial print shops serving promotional segments.
- China supply concentration:Domestic ink manufacturing and substrate extrusion capacity concentrates in coastal provinces. Western converters face extended lead times and tariff exposure on imported materials.
Strategic Opportunities
- Extended producer responsibility frameworks:EU member states implement packaging waste directives that reward recyclable mono-material constructions. Screen print labels on single-substrate films qualify for premium sustainability certifications.
- India consumer goods manufacturing:Domestic appliance and electronics production scales under PLI scheme incentives. Local converting capacity remains underdeveloped, creating first-mover advantages for technical specialists.
- UV-LED curing convergence:Instant polymerization technology eliminates thermal drying infrastructure. Converters reduce energy consumption and footprint while expanding substrate compatibility to heat-sensitive films.
Industry Challenges
- Skilled press operator scarcity:Mesh tensioning, squeegee angle control, and ink viscosity management require tacit knowledge. Vocational training pipelines in North America and Europe fail to replenish retiring workforces.
- FDA indirect food contact certification timelines:Substrate and adhesive combinations for beverage labels require migration testing protocols. Approval cycles stretch 12-18 months, delaying product launches for converters serving craft spirits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Screen Print Label Market |
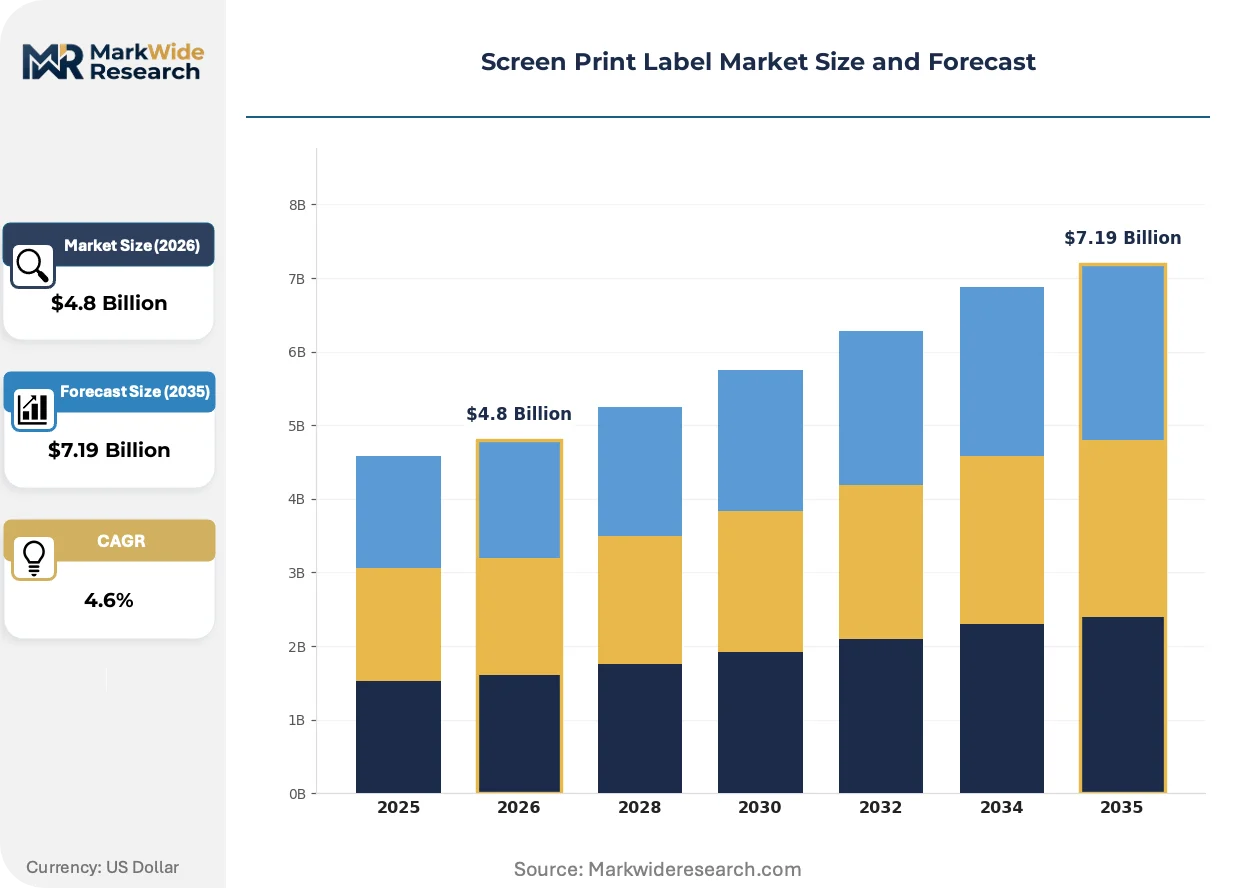
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
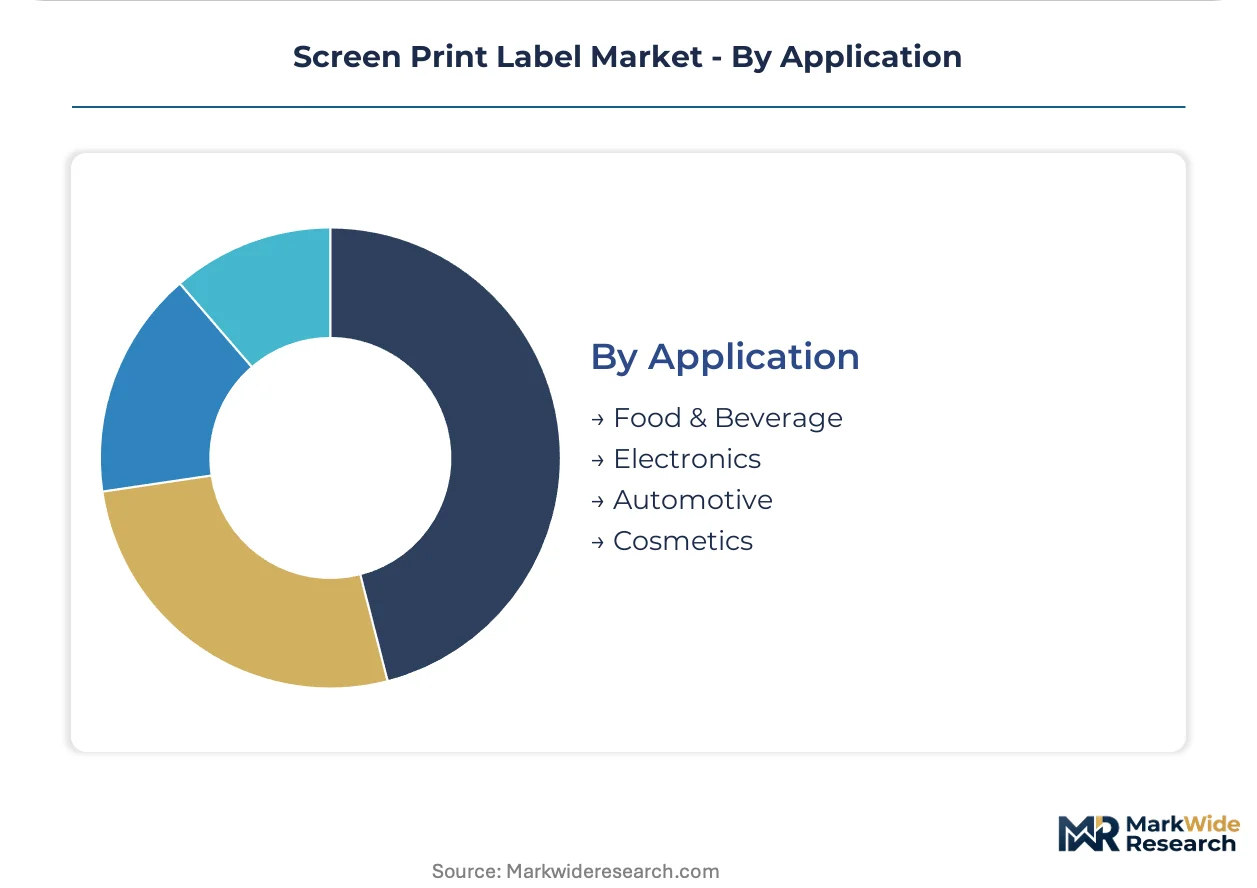
| Segmentation | Label Type: Product Labels, Warning Labels, Instruction Labels, Decorative Labels Adhesive Type: Permanent, Removable, Pressure Sensitive, Water-Activated Material: Vinyl, Polyester, Paper, Polypropylene Application: Food & Beverage, Electronics, Automotive, Cosmetics |
| Companies Covered | Fort Dearborn Company, Mondi PLC, Ahlstrom-Munksjo Oyj, Autajon Group, CCL Industries Inc., Constantia Flexibles Group GmbH, 3M Company, Coveris Inc., Gallus Ferd. Rüesch AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Screen Print Label Market Evolving Landscape
Material science advances and regulatory chemistry constraints are forcing simultaneous evolution in ink systems, curing methods, and substrate specifications across industrial and consumer applications.
Hybrid UV-LED curing systems are migrating from narrow-web specialty presses to mid-format converting lines. Automotive and electronics contract manufacturers adopt these systems to process heat-sensitive polycarbonate and thermoplastic elastomer substrates. The technology is migrating from premium tier applications toward mainstream industrial labeling, compressing the performance gap between screen and digital alternatives while preserving screen print's opacity and thickness advantages.
EPA VOC emission thresholds in US printing facilities now mandate enclosed screen systems with solvent recovery rates above 95 percent. Capital expenditure for compliance infrastructure ranges from $200,000 to $800,000 per production line depending on throughput. Contract label converters serving food and beverage brands in California and New York face the most acute compliance pressure, with many pursuing geographic consolidation to shared-service facilities with centralized recovery infrastructure.
Brand procurement teams now specify mono-material constructions compatible with mechanical recycling streams. This behavioral shift displaces multi-layer laminates and pressure-sensitive adhesives that contaminate PET and HDPE reprocessing. European cosmetics and personal care brands lead this specification change, with German and French retailers demanding cradle-to-cradle certification for primary packaging components including labels.
Screen Print Label Market Segmentation

Screen print label segmentation reveals how durability requirements, regulatory constraints, and branding specifications fragment demand across incompatible technical specifications. Each dimension carries distinct margin profiles and capital intensity requirements that shape converter specialization strategies.
Label Type:
Application context determines the thickness, opacity, and tactile specifications that separate commercial segments across consumer and industrial end uses.
- Product Labels:These 4–12 mil graphic overlays deliver premium shelf presence through dimensional ink deposits and abrasion resistance exceeding 1,000 Taber cycles. Craft breweries and cosmetics brands in Germany and France specify these constructions for tactile branding that flexographic methods cannot replicate, though FDA indirect food contact certification timelines stretch 12–18 months for beverage applications.
- Warning Labels:Regulatory-mandated constructions combine high-visibility color standards with solvent-resistant formulations for industrial safety compliance. Demand concentrates in automotive under-hood applications and chemical packaging where polyester substrates withstand hydrocarbon exposure and thermal cycling.
- Instruction Labels:Multi-language technical specifications require precise registration across repeated screen passes for appliance and electronics assembly guidance.
- Decorative Labels:Metallic and specialty ink effects serve promotional and gift packaging segments with shorter run lengths.
Product labels command the established base. The steepest expansion runs through warning labels as industrial safety regulations tighten across manufacturing jurisdictions.
Adhesive Type:
Substrate bonding chemistry determines environmental resistance, removability, and compatibility with automated application equipment across converting lines.
- Pressure Sensitive:These pre-coated constructions dominate volume through immediate tack and repositionability on high-speed packaging lines. European cosmetics brands specify solvent-free acrylic formulations to satisfy REACH low-VOC mandates, driving converter investment in UV-curable adhesive coating infrastructure.
- Permanent:Aggressive bonding systems anchor asset tags and industrial equipment markings where removal would constitute tampering or safety violation.
- Removable:Low-tack formulations serve promotional labels and temporary signage where clean removal preserves substrate resale value.
- Water-Activated:Repulpable adhesives gain specification in sustainable packaging lines compatible with mechanical recycling streams and EU extended producer responsibility frameworks.
Pressure sensitive formats anchor the installed base. Water-activated systems are climbing the fastest as mono-material recyclability becomes a procurement priority.
Material:
Substrate selection trades off outdoor durability, chemical resistance, print receptivity, and unit economics across environmental exposure profiles.
- Vinyl:Calendered and cast formulations deliver 5–7 year outdoor durability for fleet graphics and marine applications where UV stability and conformability to compound curves are mandatory. Automotive OEMs in the US specify these constructions for warning and branding overlays on exterior components.
- Polyester:Biaxially oriented films provide dimensional stability and thermal resistance for electronics and under-hood automotive labels. Chinese substrate extrusion capacity concentrates in coastal provinces, exposing Western converters to tariff volatility and extended lead times.
- Paper:Uncoated and coated stocks serve indoor short-term applications where moisture exposure is minimal and cost sensitivity dominates.
- Polypropylene:Oriented films balance chemical resistance with lower density for squeezable personal care packaging.
Vinyl and polyester capture premium positioning. Polypropylene is expanding most quickly in personal care as squeezable tube formats proliferate.
Application:
End-use industry specifications dictate ink chemistry, substrate durability, and regulatory compliance requirements that segment converter capabilities.
- Food & Beverage:Indirect food contact regulations from FDA and EFSA constrain adhesive migration limits and substrate purity. Craft distilleries specify tactile screen print constructions for premium shelf differentiation, though approval cycles delay product launches for non-integrated converters.
- Electronics:Flame-retardant specifications and thermal cycling resistance dominate requirements for appliance and device labeling. Under-hood automotive electronics manufacturers specify polyester constructions with abrasion resistance thresholds that exclude alternative print methods.
- Automotive:Exterior and interior component markings require weathering resistance and hydrocarbon exposure tolerance validated to OEM specifications.
- Cosmetics:Premium brands in Germany and France lead specification of mono-material recyclable constructions with cradle-to-cradle certification requirements.
Food and beverage anchors volume demand. Cosmetics is gaining share fastest as sustainability certification becomes a retail gatekeeping requirement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese coastal provinces concentrate substrate extrusion and ink manufacturing capacity, exposing Western converters to tariff volatility and extended lead times. Domestic consumer goods production scales drive demand concentration in Shanghai and Guangdong industrial corridors. European REACH mandates and US EPA thresholds reshape regional compliance costs.
United States
Craft beverage branding specifications from small-batch distilleries in Kentucky and Tennessee drive tactile label demand. EPA VOC emission thresholds mandate enclosed screen systems with solvent recovery rates above 95 percent in California and New York facilities. Contract label converters in the Midwest pursue geographic consolidation to shared-service facilities with centralized recovery infrastructure.
Germany
Premium cosmetics brands in Hamburg and Düsseldorf specify mono-material recyclable constructions with cradle-to-cradle certification requirements. ECHA REACH low-VOC mandates accelerate converter adoption of water-based and UV-curable ink systems. Industrial label demand concentrates in Baden-Württemberg automotive clusters serving under-hood component manufacturers.
China
Domestic appliance and electronics production scales in Guangdong and Jiangsu provinces under MIIT industrial upgrading directives. SAMR food contact material regulations constrain adhesive migration limits for beverage label applications. Yangtze River Delta converting clusters integrate backward into substrate extrusion to preserve margin structures against petrochemical volatility.
India
Consumer goods manufacturing expands under PLI scheme incentives for domestic appliance production in Maharashtra and Gujarat. FSSAI food packaging regulations constrain ink chemistry for beverage label applications. Technical converting capacity remains underdeveloped in Bangalore electronics corridors, creating first-mover positioning opportunities.
Japan
Automotive electronics labeling specifications from Nagoya and Tokyo OEMs demand polyester substrates with thermal cycling resistance. METI carbon neutrality targets drive UV-LED curing adoption to eliminate thermal drying infrastructure. Kansai region industrial clusters maintain specification authority for flame-retardant appliance labeling standards.
Screen Print Label Market Competitive Landscape
Integrated pulp-to-label operators and specialized contract converters split the market across divergent capital intensity models. Tier-one players sustain margin structures through captive substrate supply and regulatory certification depth, while mid-scale specialists compete on technical service velocity for craft beverage and cosmetics segments. Three archetypes dominate: vertically integrated material-science conglomerates, food-and-beverage-specialized contract label converters, and healthcare-focused regulatory certification specialists. Competitive dynamics center on M&A consolidation for geographic coverage and backward integration into ink formulation to offset petrochemical input volatility.
Among North American food-and-beverage specialists, Fort Dearborn Company anchors contract label demand through technical service depth for craft spirits branding requirements. Mondi PLC exemplifies the integrated pulp-to-label archetype with European supply security across multiple substrate specifications. CCL Industries Inc. occupies the healthcare and specialty certification tier, leveraging global manufacturing scale for FDA and EFSA compliance-intensive applications. These three entities represent distinct strategic postures rather than direct substitution competitors.
| Leading Market Players |
|---|
| Fort Dearborn Company |
| Mondi PLC |
| Ahlstrom-Munksjo Oyj |
| Autajon Group |
| CCL Industries Inc. |
| Constantia Flexibles Group GmbH |
| 3M Company |
| Coveris Inc. |
| Gallus Ferd. Rüesch AG |
| Others |
Value Network & Pricing Analysis
Petrochemical input volatility in polyester and vinyl substrates compresses margin structures for non-integrated converters while simultaneously widening pricing tier spreads between captive-supply leaders and spot-market dependent operators. REACH compliance costs and EPA VOC mandates layer regulatory premiums onto European and North American delivered prices, reshaping procurement geography toward integrated Yangtze River Delta clusters.
Pricing Analysis
EPA VOC emission thresholds dictate the pricing tier structure across North American contract label converters, separating enclosed-system operators with solvent recovery infrastructure from legacy open-line competitors. Three-tier pricing structure across premium, standard, and economy levels aligns with certification depth—FDA indirect food contact approval cycles, ECHA REACH compliance verification, and automotive OEM specification authority. Cost compression in mid-tier water-based ink formulations is intensifying because European cosmetics brands now mandate mono-material recyclability premiums. Craft beverage brands in Kentucky and Tennessee show least price sensitivity for tactile dimensional labels, while promotional commercial print shops face acute pressure from UV inkjet substitution below 500-unit runs.
Supply Chain Analysis
Export-control scrutiny on advanced UV-LED curing equipment limits technology transfer to certain converting jurisdictions, constraining capacity expansion timelines for mid-format lines outside established manufacturing corridors. Substrate extrusion concentrates in China, South Korea, and Germany, with Chinese coastal provinces dominating vinyl calendering and polyester biaxial orientation. Ink formulation rests on petrochemical derivatives, photoinitiator chemicals, and specialty pigment supply chains anchored in Basel and Shanghai chemical clusters. Single-source vulnerability runs through Yangtze River Delta port congestion and tariff exposure on imported materials. Distribution runs through regional converting hubs serving just-in-time packaging lines for food and beverage, electronics, and automotive OEM contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Screen print label demand sits at an early-cycle expansion phase as craft beverage branding specifications and automotive electronics durability requirements outpace digital print substitution limits in premium tactile applications.
For Market Incumbents: Insulate margin structures through backward integration into substrate extrusion or captive ink formulation capacity, particularly in Yangtze River Delta and Midwest industrial corridors where petrochemical volatility most compresses converter economics. Pursue geographic consolidation of solvent recovery infrastructure to shared-service facilities in California and New York EPA enforcement zones, reducing per-line compliance capital burden while maintaining specification authority for FDA food contact certification.
For New Entrants and Emerging Players: Pursue technical specialization in UV-LED curing system integration for heat-sensitive polycarbonate and thermoplastic elastomer substrates, where automotive and electronics contract manufacturers face capacity constraints. Target Maharashtra and Gujarat appliance manufacturing clusters in India, where PLI scheme incentives scale domestic production ahead of local converting capacity development. Lead with cradle-to-cradle certification consulting bundled with mono-material label construction to capture German and French cosmetics brand procurement committees.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors regulatory certification specialists with FDA and EFSA compliance depth over commodity spot converters. Long-term viability hinges on backward integration economics and geographic diversification beyond China supply concentration. Acquisition target archetype: mid-scale operators with established automotive OEM specification authority and underinvested solvent recovery infrastructure. Monitor EU extended producer responsibility framework implementation velocity as inflection signal for mono-material construction demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Extrusion | Captures margin pool from vinyl and polyester volatility while securing Yangtze River Delta supply continuity. |
| UV-LED Curing Technology Adoption | Eliminates thermal drying infrastructure for polycarbonate compatibility under METI carbon neutrality targets. |
| FDA Indirect Food Contact Certification Investment | Accelerates 12-18 month approval cycles for craft spirits converters serving Kentucky and Tennessee distilleries. |
| Geographic Consolidation to Shared-Service Facilities | Centralizes EPA-mandated solvent recovery infrastructure across California and New York compliance zones. |
| Cradle-to-Cradle Certification Program | Qualifies mono-material constructions for German and French retailer sustainability gatekeeping requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade records, and industry association datasets to construct validated market estimates. Primary interviews engaged ink formulation chemists, converting plant managers, procurement leads at food and beverage OEMs, automotive component specification engineers, and cosmetics brand packaging directors. Secondary sources included ECHA REACH substance registrations, EPA VOC emission compliance databases, FDA food contact material notifications, and SEC filings from publicly traded label converters. Bottom-up capacity and utilization estimates triangulated against top-down value-chain flow analysis.
Forecast inputs span label type, adhesive chemistry, substrate material, and end-use application dimensions across the projection horizon. Modeled variables include craft beverage production growth, automotive electronics content per vehicle, and EU packaging waste directive implementation trajectories. CAGRs derive from segment-level demand elasticity analysis and capacity expansion pipeline tracking. Industry-specific inputs incorporate UV-LED curing equipment shipment data and petrochemical feedstock price correlation coefficients.
Sensitivities concentrate around REACH regulatory expansion timelines, China tariff regime adjustments, and UV inkjet print quality advancement rates. Forecasts reflect documented assumptions regarding substrate substitution elasticity and certification cycle durations. Material shifts in EU extended producer responsibility enforcement or EPA VOC threshold stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Global Label Market
Labels
Global QR Code Labels Market
Labels
Shipping Label Market
Labels
Pressure Sensitive Labels Market
Labels
Global Automotive Labels Market
Labels
High Gloss Labels Market
Labels
Metallic Labels Market
Labels
Global Resealable Packaging Labels Market
Labels
Oxygen Indicator Labels Market
Labels
Europe Self Adhesives Label Market
Labels
In-Mold Labeling (IML) Market
Labels
Eco-Friendly Labels Market
Labels
Global Waterproof Labels Market
Labels
Heat Shrink Sleeve Market
Labels
Global Label Adhesive Market
Labels
Cut and Stack Labels Market