
 Morocco Plastic Packaging Films Market | 2026-2036
Morocco Plastic Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Morocco Plastic Packaging Films Market Insights
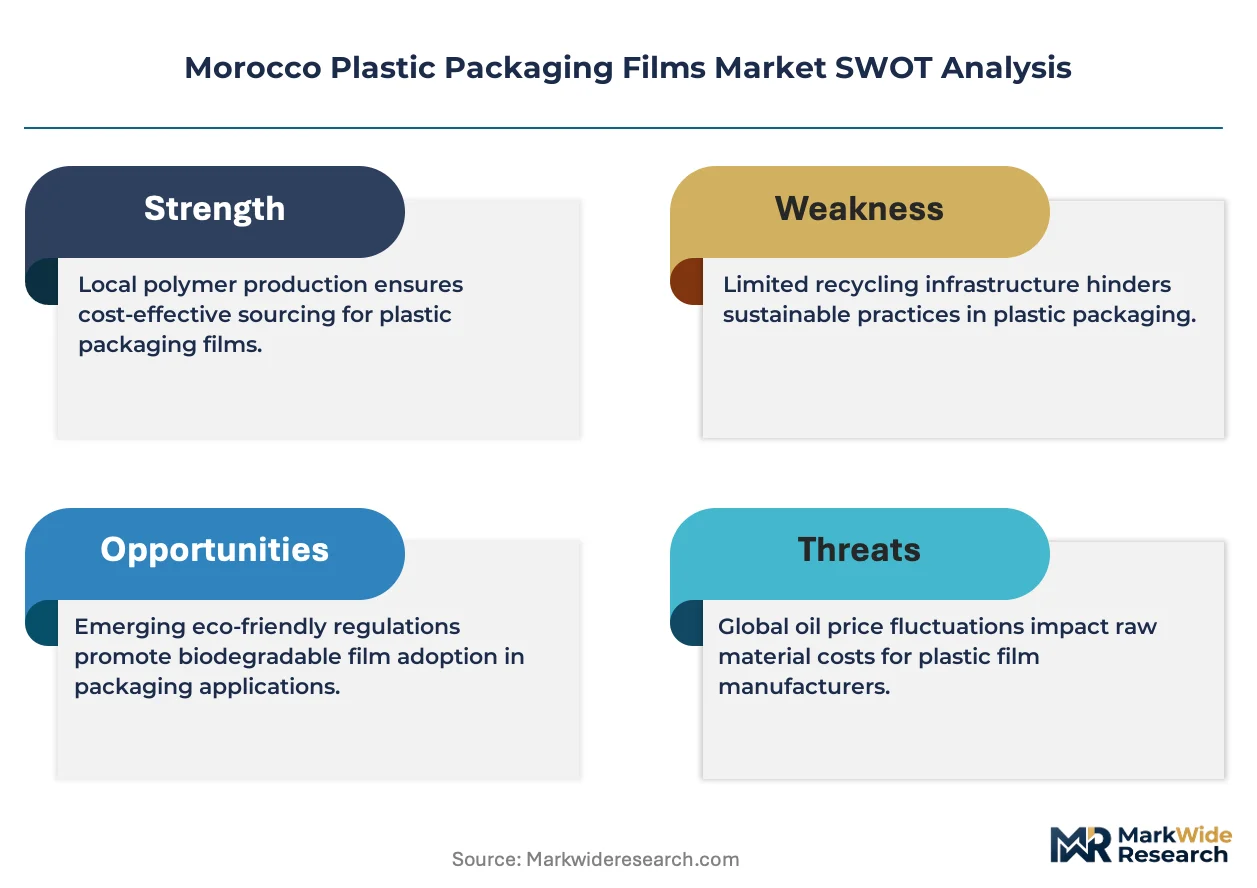
The Morocco plastic packaging films sector is rebalancing between premium barrier specifications and commodity-grade polyethylene wraps. Radiant Packaging Industry LLC leverages its domestic extrusion footprint to anchor supply for local food processors. Mondi plc competes through specialized high-performance barrier films targeting export-oriented agribusiness clients. ALPLA Morocco extends its position via integrated bottle-to-film recycling streams that differentiate its sustainability credentials.
Plastic packaging films are extruded or cast polymer sheets, typically 10 to 150 microns thick, engineered for containment, preservation, and unitization of consumer and industrial goods. Polyethylene formulations dominate volume throughput due to cost efficiency and heat-seal compatibility with Moroccan filling lines. Flexible films lead value generation across the product type dimension, as their lighter weight reduces logistics costs for cross-border food shipments to European Union markets. Barrier films represent the fastest-expanding material class, driven by oxygen and moisture transmission requirements for processed seafood and olive oil exports.
Morocco's national standardization body, the Institut Marocain de Normalisation (IMANOR), aligns polymer film specifications with EU REACH and packaging waste directives to preserve market access. The country's Ministry of Industry and Trade enforces extended producer responsibility schemes that push converters toward mono-material polyethylene structures compatible with mechanical recycling infrastructure. Stakeholders must monitor how European Union Single-Use Plastics Directive transpositions through Moroccan trade agreements reshape import specifications and domestic compliance timelines.
Market Dynamics
Extended producer responsibility frameworks are redirecting capital toward mono-material polyethylene structures, forcing converters to abandon multi-layer barrier configurations that dominate export packaging for European agri-food clients.
Growth Catalysts
- EU REACH alignment via IMANOR:Moroccan standardization body's polymer film specifications preserve duty-free market access for processed seafood and olive oil exports to European Union distribution networks.
- Agri-food processing expansion:Casablanca-Settat industrial corridor converters are scaling high-barrier flexible film capacity to serve chilled ready-meal exporters targeting French and Spanish retail chains.
- Mechanical recycling infrastructure:National waste management operators are installing sorting lines capable of handling post-consumer polyethylene films, creating closed-loop feedstock security for domestic extruders.
Market Restraints
- Ethylene feedstock import dependence:Morocco lacks naphtha cracking capacity, leaving converters exposed to CIF Northwest Europe ethylene price volatility and euro-dirham exchange rate swings.
- Multi-layer film recyclability gap:EVOH and PA barrier layers in current export-grade structures create technical incompatibility with existing mechanical recycling infrastructure.
- Competing Mediterranean suppliers:Egyptian and Tunisian converters with lower labor costs and EU association agreement access are underbidding Moroccan firms for commodity polyethylene wrap contracts.
Strategic Opportunities
- Pharmaceutical cold-chain films:Temperature-stable barrier laminates for vaccine distribution represent an underpenetrated application as Moroccan logistics operators expand pharmaceutical handling capabilities.
- Chemical recycling partnerships:Pyrolysis-based polyethylene regeneration offers a pathway to food-contact approved recycled content that mechanical methods cannot achieve.
- Domestic horticulture packaging:Citrus and berry exporters in the Souss-Massa region are converting from bulk shipping to retail-ready flexible packaging for Middle Eastern supermarket chains.
Industry Challenges
- Polymer film engineering expertise shortage:Moroccan technical universities produce limited graduates with co-extrusion die design and barrier layer adhesion optimization skills.
- Dual certification timelines:Simultaneous IMANOR national approval and EU-notified body conformity assessment for novel recyclable structures extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morocco Plastic Packaging Films Market |
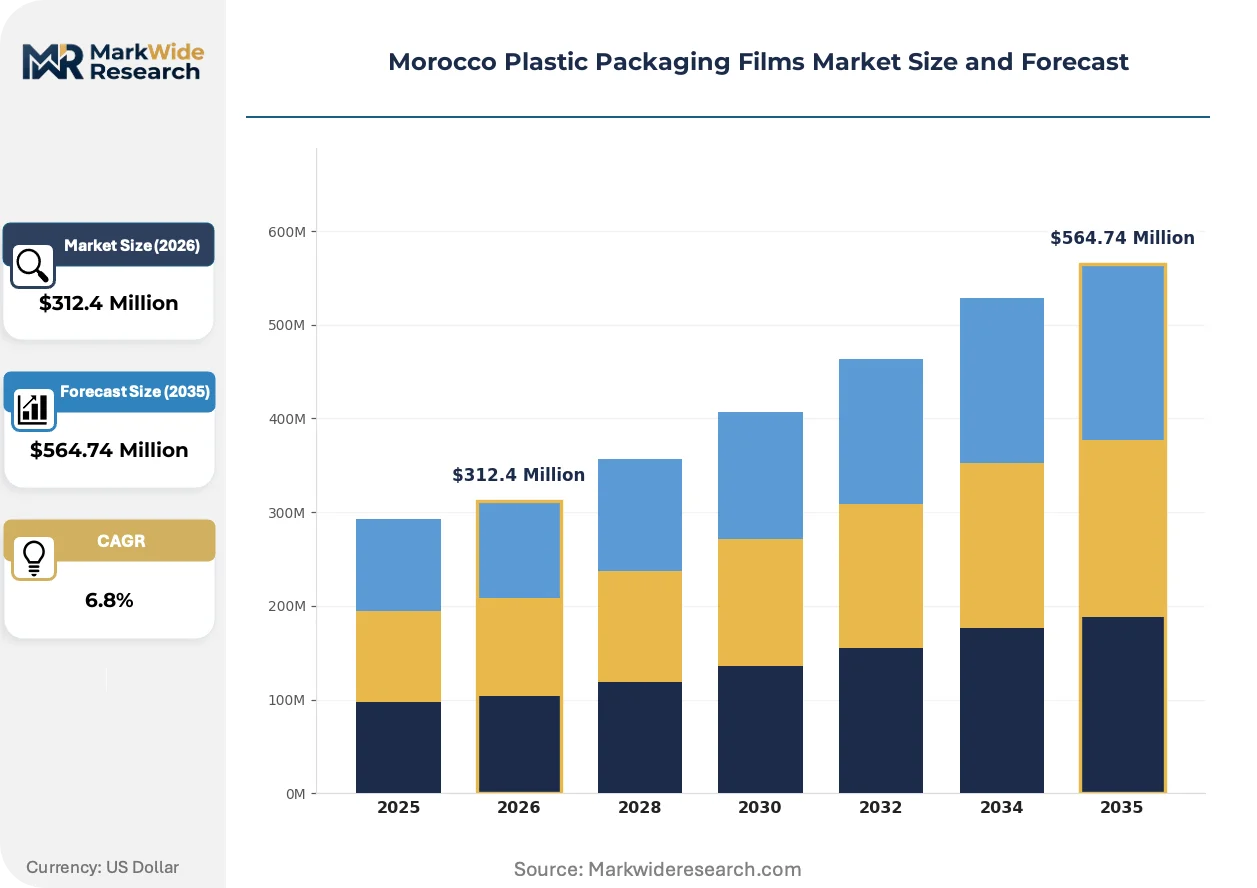
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Films, Rigid Films, Shrink Films, Barrier Films End Use Industry: Food & Beverage, Personal Care, Healthcare, Electronics Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Others Thickness: Thin Gauge, Medium Gauge, Heavy Gauge, Ultra-Thin |
| Companies Covered | Radiant Packaging Industry LLC, Amcor Group GmbH, Afrimag Glue, Mondi plc, ALPLA Morocco, Sonofet, Multisac Maroc, Ouafa Plastique, Imaplast, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morocco Plastic Packaging Films Market Trends and Innovations
Mono-material polyethylene barrier films are displacing conventional multi-layer structures as the dominant technical trajectory, with oxygen scavenging additives and surface coating technologies enabling equivalent shelf-life performance without incompatible polymer layers.
Co-extruded high-density polyethylene with plasma-deposited silicon oxide barrier coatings is overtaking EVOH-containing laminates in chilled seafood export applications. Tangier-Med port cold-chain operators are specifying these structures for trans-Mediterranean routes to Rotterdam and Hamburg. The shift is compressing demand for polyamide supply contracts while elevating technical service requirements from coating equipment vendors.
Morocco's Ministry of Industry and Trade enforcement of extended producer responsibility schemes is mandating annual recycling rate targets for packaging producers. Converters must now fund post-consumer collection infrastructure or face market exclusion. Food processors with European retail contracts are responding fastest, specifying recyclable mono-material structures to preempt compliance verification failures.
Agri-food exporters are consolidating film procurement through converter-direct contracts rather than distributor intermediaries. Large Casablanca-based processors are negotiating multi-year supply agreements with extruders who commit to dedicated production lines and inventory buffers. The Souss-Massa berry cooperative federation pioneered this model, and olive oil bottlers in Fès-Meknès are adopting similar arrangements to secure specification consistency.
Morocco Plastic Packaging Films Market Segmentation
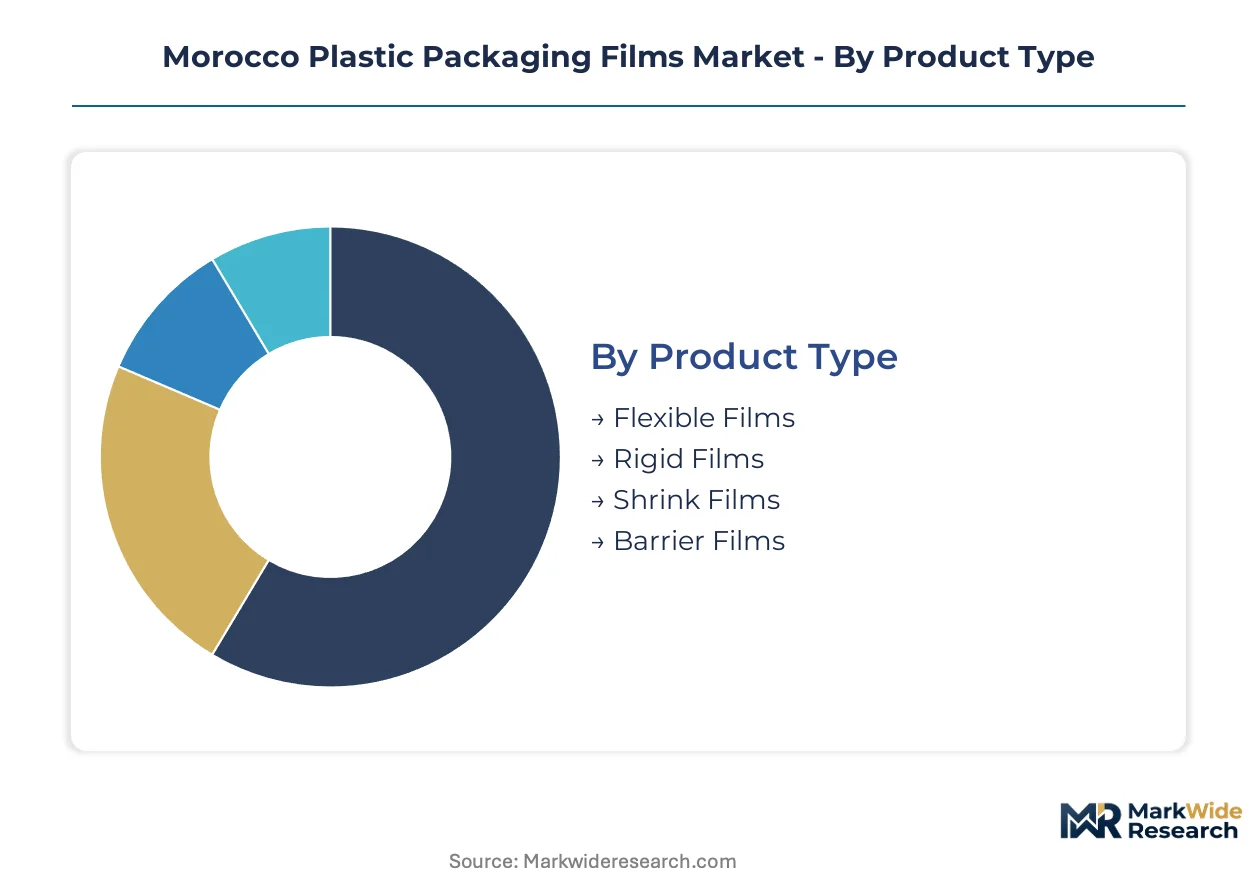
Converters in the Casablanca-Settat corridor are reconfiguring extrusion lines to match shifting procurement specifications from European agri-food exporters. Segmentation reveals where technical upgrades command premium pricing versus commodity substitution pressures.
Product Type:
Upgrade cycles vary dramatically by film construction, with barrier performance requirements driving replacement timelines in export-oriented applications.
- Flexible Films:Co-extruded polyethylene structures dominate throughput due to heat-seal compatibility with Moroccan filling lines and weight advantages for cross-border logistics. Casablanca-based seafood processors specify these for chilled distribution to French retail chains where reduced freight costs offset material premiums.
- Barrier Films:Oxygen and moisture transmission specifications for processed seafood and olive oil exports are accelerating adoption of high-performance laminates. Souss-Massa berry cooperatives are converting procurement to these structures for Middle Eastern supermarket shelf-life requirements.
- Shrink Films:Polyolefin formulations serve secondary packaging for unitized pallet loads at Tangier-Med port logistics operators.
- Rigid Films:Thermoformed polystyrene and PET structures concentrate in dairy and ready-meal tray applications for domestic retail chains.
Volume placements concentrate in Flexible Films; the faster expansion belongs to Barrier Films.
End Use Industry:
Customer procurement sophistication separates specification-driven exporters from price-sensitive domestic distributors.
- Food & Beverage:Agri-food processors in the Fès-Meknès olive oil belt and Casablanca seafood sector negotiate multi-year converter contracts with dedicated production line commitments. Extended producer responsibility compliance deadlines are forcing rapid specification shifts toward mono-material recyclable structures.
- Healthcare:Temperature-stable barrier laminates for vaccine cold-chain distribution represent emerging demand as Moroccan logistics operators expand pharmaceutical handling capabilities.
- Personal Care:Flexible pouches for shampoo and cosmetic products serve domestic retail and North African export markets with lower barrier requirements.
- Electronics:Anti-static films for component packaging concentrate in Tangier free zone assembly operations serving European automotive supply chains.
Food & Beverage commands the dominant revenue share; Healthcare posts the steepest expansion trajectory.
Material:
Feedstock sourcing economics and recycling infrastructure compatibility are reordering material preferences across converter portfolios.
- Polyethylene:Low-density and linear low-density formulations anchor domestic production due to heat-seal performance and mechanical recycling compatibility. IMANOR alignment with EU REACH specifications preserves market access for export-grade structures.
- Polypropylene:Cast and oriented films serve snack food and textile packaging applications where clarity and stiffness outweigh seal strength requirements.
- Polyvinyl Chloride:Cling film and blister pack applications persist in pharmaceutical and fresh produce wrapping despite recycling infrastructure limitations.
- Others:Biodegradable starch blends and bio-based polyesters occupy niche positions in premium export packaging for European organic product lines.
Polyethylene dominates extruder throughput; polypropylene is climbing fastest on snack food packaging demand.
Thickness:
Downgauging initiatives and barrier performance requirements are creating divergent specification trends across end-use applications.
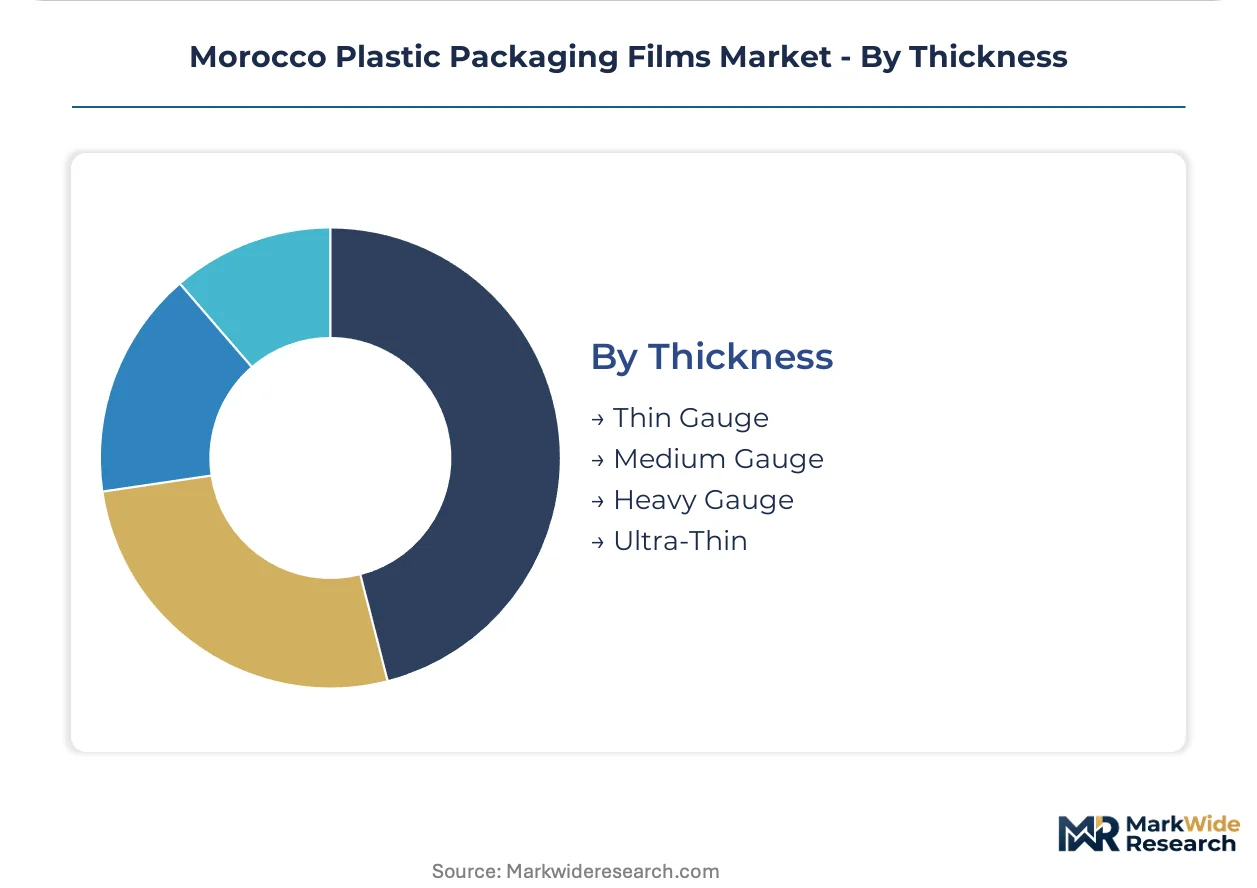
- Thin Gauge:10-30 micron polyethylene structures serve overwrap and lightweight pouch applications where material minimization reduces unit costs for high-volume domestic consumption goods.
- Medium Gauge:30-80 micron films balance puncture resistance and seal integrity for frozen food and agricultural chemical packaging across Moroccan retail distribution.
- Heavy Gauge:80-150 micron constructions protect industrial components and bulk chemical shipments through Tangier-Med port handling operations.
- Ultra-Thin:Sub-10 micron oriented films enable source reduction for European export compliance while maintaining optical properties in premium cosmetic applications.
Medium Gauge films capture the largest volume placement; Ultra-Thin specifications are gaining share fastest on European sustainability compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Casablanca-Settat anchors Morocco's plastic packaging films demand through its concentration of agri-food processing exporters and converting capacity clustered around the port industrial zone.
Casablanca-Settat
Seafood processors and olive oil bottlers drive specification-intensive procurement for European Union distribution. IMANOR alignment with REACH directives preserves duty-free access for these exporters. The Mohammedia industrial corridor hosts extrusion lines dedicated to high-barrier flexible films for French retail chains.
Fès-Meknès
Olive oil cooperatives are consolidating film procurement through direct converter contracts rather than distributor channels. Extended producer responsibility enforcement from the Ministry of Industry and Trade accelerates shifts toward mono-material polyethylene structures. Meknès converting facilities are retooling for recyclable specifications demanded by German organic product importers.
Souss-Massa
Berry and citrus exporters are converting from bulk shipping to retail-ready flexible packaging for Middle Eastern supermarket chains. The regional cooperative federation pioneered multi-year supply agreements with dedicated production line commitments. Agadir port cold-chain operators are specifying medium-gauge polyethylene films for trans-Mediterranean routes.
Tanger-Tetouan-Al Hoceima
Tangier-Med port logistics generate demand for shrink films and heavy-gauge industrial packaging serving automotive component assembly in the free zone. Temperature-stable barrier laminates for pharmaceutical cold-chain distribution represent emerging demand as logistics operators expand vaccine handling capabilities. Tetouan-based converters serve northern Moroccan retail distribution with commodity-grade polyethylene wraps.
Morocco Plastic Packaging Films Market Competitive Landscape
Premium-margin players sit above commodity-margin players across barrier technology and sustainability certification dimensions, with the former capturing dedicated supply contracts from export-oriented agri-food processors while the latter compete on price for domestic retail channels. The market exhibits moderate concentration around integrated extrusion-converting operations and specialized barrier film specialists. Three archetypes dominate: domestic extruders with mechanical recycling integration, European multinationals with high-performance barrier portfolios, and regional commodity converters competing on labor cost. Capacity expansion and strategic partnerships with waste management operators for feedstock security represent the dominant competitive moves.
Among domestic integrated players, Radiant Packaging Industry LLC and ALPLA Morocco exemplify the recycling-forward archetype through their positioning around circular economy compliance. Mondi plc represents the multinational specialist tier with European technical standards alignment. These three companies anchor the competitive structure without dominating volume share, leaving room for commodity converters like Multisac Maroc and Ouafa Plastique to serve price-sensitive domestic segments.
| Leading Market Players |
|---|
| Radiant Packaging Industry LLC |
| Amcor Group GmbH |
| Afrimag Glue |
| Mondi plc |
| ALPLA Morocco |
| Sonofet |
| Multisac Maroc |
| Ouafa Plastique |
| Imaplast |
| Others |
Pricing and Supply Chain Analysis
Extended producer responsibility enforcement by Morocco's Ministry of Industry and Trade gates qualified supply access for converters seeking premium-tier pricing with European agri-food exporters. Compliance-certified mono-material polyethylene structures command substantial premiums over commodity-grade alternatives while locking out non-compliant competitors from specification-intensive procurement channels.
Pricing Analysis
Yield-guaranteed shelf-life performance anchors value-based pricing for high-barrier flexible films serving Casablanca seafood processors exporting to French retail chains. Three-tier pricing structure across premium barrier-certified, standard IMANOR-compliant, and economy-grade polyethylene levels separates converters by technical capability and recycling integration depth. Cost compression in commodity wraps intensifies because Egyptian and Tunisian competitors exploit labor arbitrage for bulk polyethylene contracts. Domestic retail distributors exhibit highest price sensitivity, while export-oriented agri-food processors prioritize specification consistency over unit cost.
Supply Chain Analysis
Skilled co-extrusion technicians concentrate in the Casablanca-Settat and Mohammedia industrial corridors, creating workforce-access bottlenecks for converters expanding barrier film capacity. Ethylene feedstock draws from CIF Northwest Europe import contracts, mechanical recycling feedstock sources from national waste management operators, and silicon oxide coating equipment hinges on German and Italian vendor relationships. Single-source vulnerability permeates the ethylene supply channel given Morocco's absent naphtha cracking infrastructure. Distribution runs through converter-direct contracts with large agri-food processors and distributor networks serving fragmented domestic retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domestic mechanical recycling capacity constraints prop pricing premiums for circular-economy-compliant converters, locking supply-constrained margins for qualified players across the projection horizon.
For Market Incumbents: Deepen backward integration into post-consumer polyethylene collection infrastructure to secure feedstock volume guarantees under extended producer responsibility frameworks. Expand co-extrusion capacity in the Mohammedia corridor to capture dedicated supply contracts from Casablanca seafood processors facing IMANOR compliance deadlines. Certification investment in EU-notified body conformity assessment represents the critical defensive lever against emerging barrier film specialists. For New Entrants and Emerging Players: Enter via pharmaceutical cold-chain film applications where temperature-stable barrier laminates face limited domestic competition and European technical standards create qualification barriers for established commodity converters. Target Souss-Massa berry cooperatives converting from bulk shipping to retail-ready flexible packaging for Middle Eastern supermarket chains. Partner with Tangier-Med port logistics operators on vaccine distribution specifications as the anchor go-to-market angle. For Investors and Strategic Acquirers: IMANOR's publication of draft mono-material recyclability standards is the leading indicator that premium-tier pricing power will consolidate among early-compliant integrated extruders. Five-to-ten-year viability favors converters with captive mechanical recycling streams and established European retail channel relationships. Acquisition focus should center on mid-scale extrusion operations with underutilized barrier film capacity and pending EU-notified body certification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Recycling Integration | Captures feedstock security under Morocco's extended producer responsibility enforcement by the Ministry of Industry and Trade. |
| Mono-Material Barrier Film Development | Preserves European retail channel access as EVOH-containing laminates face technical incompatibility with sorting infrastructure. |
| Converter-Direct Contract Consolidation | Locks specification consistency for Casablanca seafood processors negotiating multi-year supply agreements with inventory buffers. |
| Chemical Recycling Partnership Formation | Enables food-contact approved recycled content pathways that mechanical methods cannot achieve for olive oil export packaging. |
| Plasma Coating Technology Adoption | Displaces polyamide-dependent EVOH structures in chilled seafood applications serving Rotterdam and Hamburg routes. |
Research Methodology
Document review covered customs and trade data, IMANOR regulatory filings, EU REACH directive transposition records, and SEC disclosures from listed packaging multinationals, complemented by interviews with extrusion plant managers, procurement leads at Casablanca agri-food processors, distribution channel partners, and technical R&D directors at coating equipment vendors. Bottom-up capacity and demand modeling triangulated against top-down trade flow analysis validated volume estimates across polyethylene, polypropylene, and barrier film categories.
Segment-level projections across flexible films, barrier films, shrink films, and rigid films by thickness tier, material formulation, and end-use industry generated the value trajectory over the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating ethylene price volatility and euro-dirham exchange rate sensitivity. Industry-specific inputs included Tangier-Med port cold-chain expansion timelines and Souss-Massa agricultural cooperative packaging conversion rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ethylene supply disruption scenarios or accelerated EU Single-Use Plastics Directive transposition through Moroccan trade agreements. Material deviation in IMANOR enforcement intensity, European retail chain recyclability mandate timing, or chemical recycling partnership commercialization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Stretch Films Packs Market
Poly film
PCR Lidding Films Market
Poly film
Polyvinyl Alcohol (PVA) Films Market
Poly film
Vinyl Films Market
Poly film
Timber Wrap Films Market
Poly film
Asia Pacific Plastic Packaging Film Market
Poly film
Polycoated Packaging Market
Poly film
UAE Plastic Packaging Films Market
Poly film
India Plastic Packaging Film Market
Poly film
Europe Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market
Poly film
Blown Film Extruder Market
Poly film
Tube Laminating Films Market
Poly film
Japan Plastic Packaging Film Market
Poly film
Global BOPP Films Market
Poly film
PVC Cling Film Market
Poly film
Soft Touch Lamination Film Market