
 United Kingdom Plastic Packaging Films Market | 2026-2036
United Kingdom Plastic Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Plastic Packaging Films Market Insights
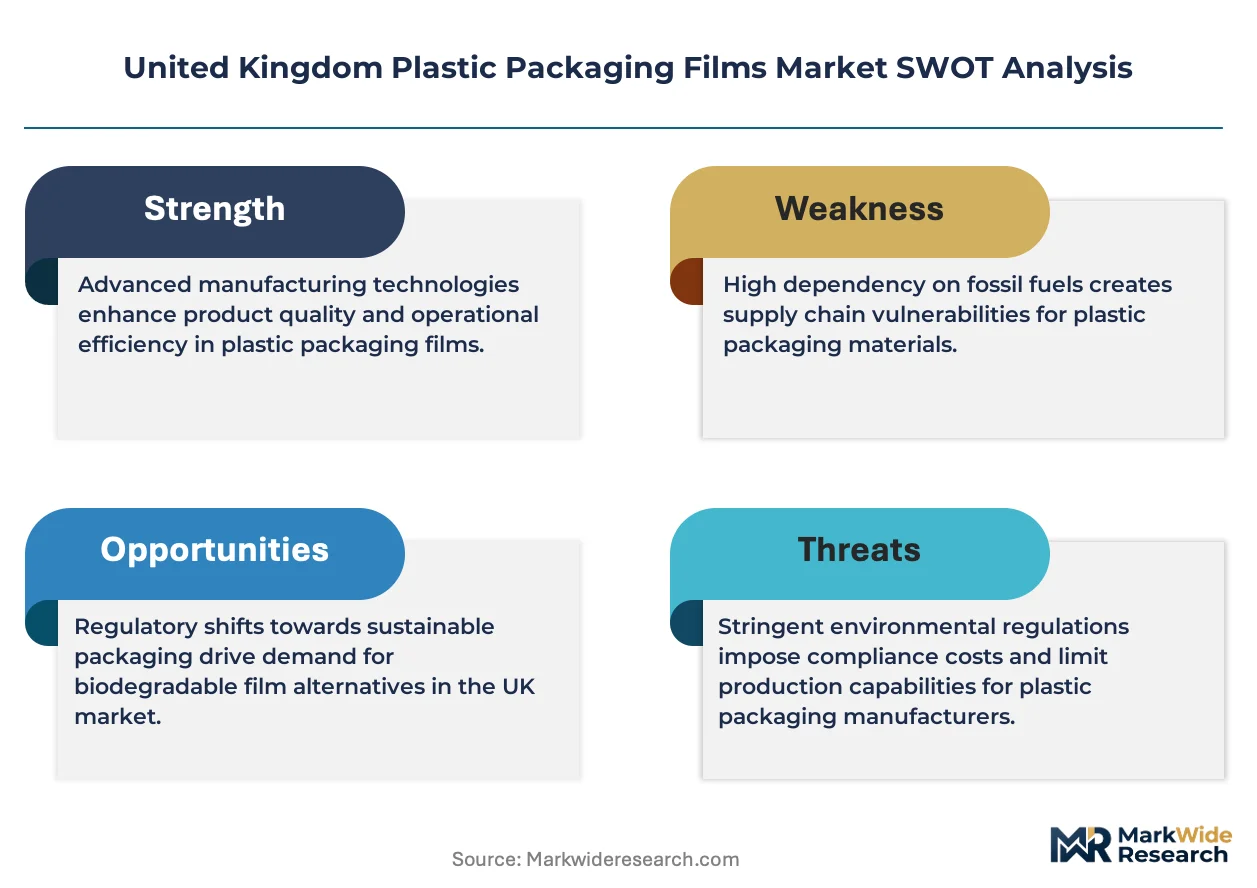
Domestic blown film extruders in the Midlands and Yorkshire is repositioning capacity toward mono-material streams compatible with mechanical recycling infrastructure. Amcor PLC leverages its European technical center near Manchester to develop thin-gauge barrier solutions for protein packaging. Berry Global Inc. sustains volume leadership through its integrated resin-to-roll operations serving major UK grocery retailers. Innovia Films specializes in cellulose-based alternatives that target premium confectionery and tobacco overwrap segments.
United Kingdom plastic packaging films comprise thermoplastic polymer sheets, typically 12 to 150 microns thick, manufactured through cast or blown extrusion and oriented via tenter frame or bubble processes to deliver controlled tensile strength, clarity, and barrier performance for product protection and unitization. PE films dominate fresh produce and frozen food wrapping due to cost efficiency and heat-seal compatibility, while barrier films command premium positioning in pharmaceutical blister packs and modified-atmosphere meat trays where oxygen transmission rates below 1 cc/m²/day are specified. The 20-50 micron thickness band anchors the highest shipment volumes across stretch wrap and industrial bundling applications.
The UK Environment Agency enforces the Plastic Packaging Tax at £210.82 per tonne for products with less than 30% recycled content, compelling compounders to certify post-consumer feedstock chains under HMRC registration protocols. Extended Producer Responsibility regulations coming through DEFRA mandate modulated fees that reward mono-material designs and penalize multi-layer constructions incompatible with UK sorting infrastructure. Stakeholders must track how the British Standards Institution develops PAS 5050 recyclability assessment criteria, as this will determine which film structures retain market access versus face displacement by paper or aluminum alternatives.
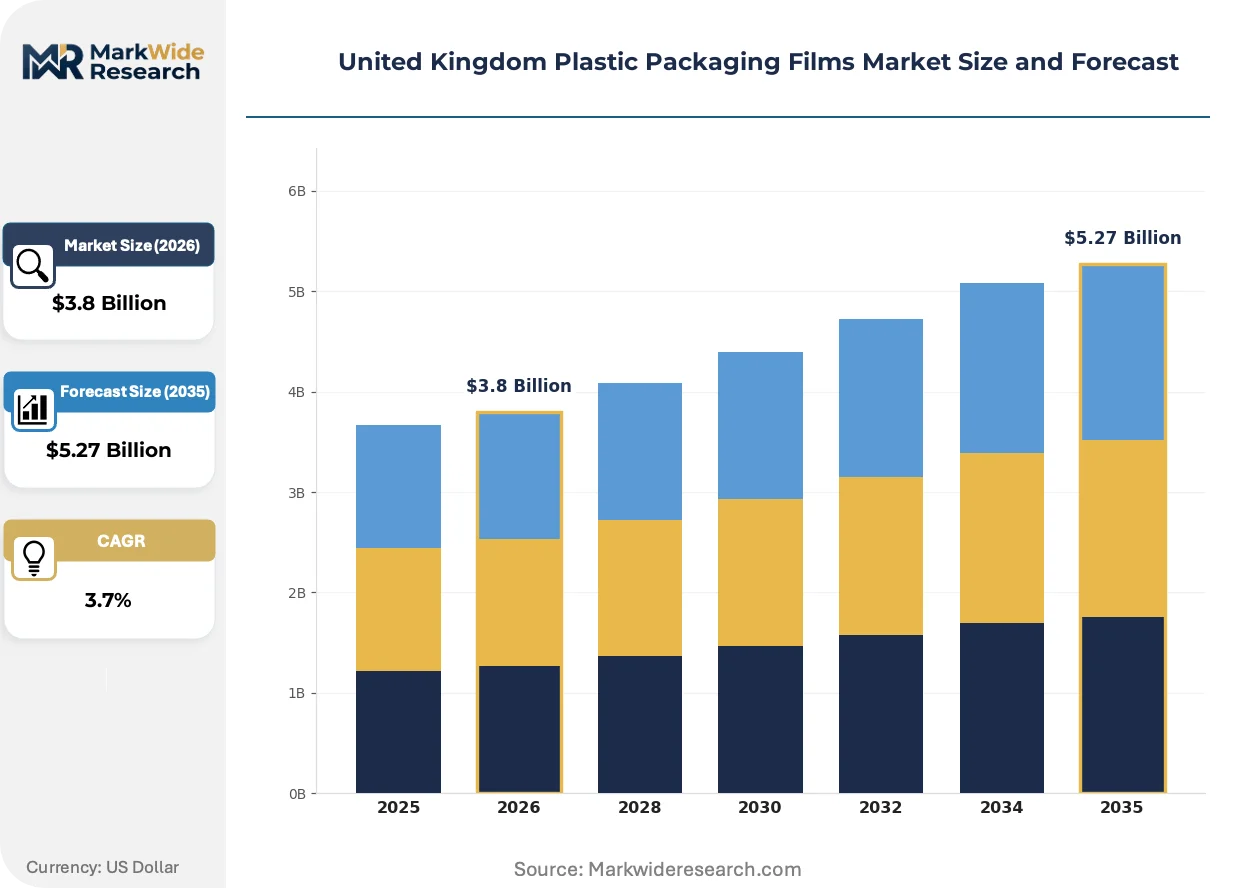
Market Dynamics
The UK Plastic Packaging Tax at £210.82 per tonne is compressing demand for virgin resin formulations while mechanically recycled feedstock struggles to meet volume and optical quality specifications simultaneously.
Growth Catalysts
- Extended Producer Responsibility (EPR):DEFRA's modulated fee structure rewards mono-material PE and PP designs with lower compliance costs, accelerating converter migration away from multi-layer barrier constructions.
- E-commerce fulfillment expansion:Automated stretch-wrapping systems in Greater London distribution centers consume machine-grade films at throughput rates exceeding conventional hand-wrap operations by significant multiples.
- Modified-atmosphere protein packaging:High-barrier EVOH and PA coextrusions for fresh meat retail chains in England and Scotland extend shelf life while reducing food waste metrics tracked by major grocery retailers.
Market Restraints
- Post-consumer recycled (PCR) resin shortage:UK mechanical recycling infrastructure yields insufficient food-grade rPE and rPP volumes to satisfy 30% content thresholds under HMRC certification protocols.
- Multi-layer incompatibility:Current UK sorting and reprocessing plants cannot separate PET/PE/PA laminates, rendering complex barrier films non-recyclable and subject to full tax liability.
- Energy cost volatility:Blown film extrusion in the Midlands and Yorkshire faces compressed margins from natural gas price swings affecting resin polymerization and processing energy inputs.
Strategic Opportunities
- Chemical recycling scale-up:Pyrolysis and depolymerization investments targeting mixed plastic waste streams could unlock food-contact compliant recycled content exempt from Plastic Packaging Tax penalties.
- Pharmaceutical serialization compliance:Tamper-evident and track-and-trace films for blister packs align with MHRA requirements for unit-level verification in NHS supply chains.
- Scottish circular economy hubs:Industrial clusters near Grangemouth petrochemical infrastructure offer integrated resin production, film conversion, and mechanical recycling co-location advantages.
Industry Challenges
- HMRC registration complexity:Mass balance accounting for recycled content requires compounders to maintain auditable feedstock chain documentation across multiple supplier tiers.
- Thin-gauge barrier engineering:Downgauging below 20 microns for material reduction conflicts with oxygen transmission rate specifications in sensitive protein and pharmaceutical applications.
- Legacy equipment retrofit costs:Mono-material transition demands extruder die and cooling line modifications incompatible with existing multi-layer coextrusion assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Plastic Packaging Films Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.27 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PE Films, PP Films, PVC Films, PET Films End User: Food Packaging, Beverage Packaging, Personal Care, Pharmaceutical Thickness: Below 20 Micron, 20-50 Micron, 51-100 Micron, Above 100 Micron Application: Stretch Films, Shrink Films, Lamination Films, Barrier Films |
| Companies Covered | Elite Plastics Limited, Innovia Films, Berry Global Inc., Klöckner Pentaplast, Cosmo Films, Amcor PLC, Coveris Holding, Sealed Air Corporation, Constantia Flexibles, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Plastic Packaging Films Market Trends and Innovations
Film converters across the UK are reengineering product architectures to satisfy simultaneous demands for barrier performance, mechanical recyclability, and tax-efficient recycled content incorporation.
Mono-material barrier technology is consolidating market preference as EVOH and PA tie-layers get redesigned for compatibility with PE or PP dominant layers. Major grocery retailers in England and Scotland now specify mono-material flow-wrap for private-label produce. This consolidation is compressing demand for conventional multi-layer constructions that fail UK sorting infrastructure compatibility tests.
The Plastic Packaging Tax enforcement by HMRC is mandating certified recycled content verification through third-party audit trails. Compounders must register feedstock sources and maintain mass balance documentation across conversion steps. Fresh food retail chains face the steepest compliance burden as they balance shelf-life extension requirements against mono-material design constraints.
Automated stretch-hood and pallet-wrapping systems in Yorkshire and Midlands fulfillment centers are displacing manual hand-wrap operations. Third-party logistics providers specify pre-stretched machine films with consistent cling and puncture resistance. This equipment transition concentrates procurement volumes with film suppliers capable of technical service support and just-in-time delivery coordination.
United Kingdom Plastic Packaging Films Market Segmentation
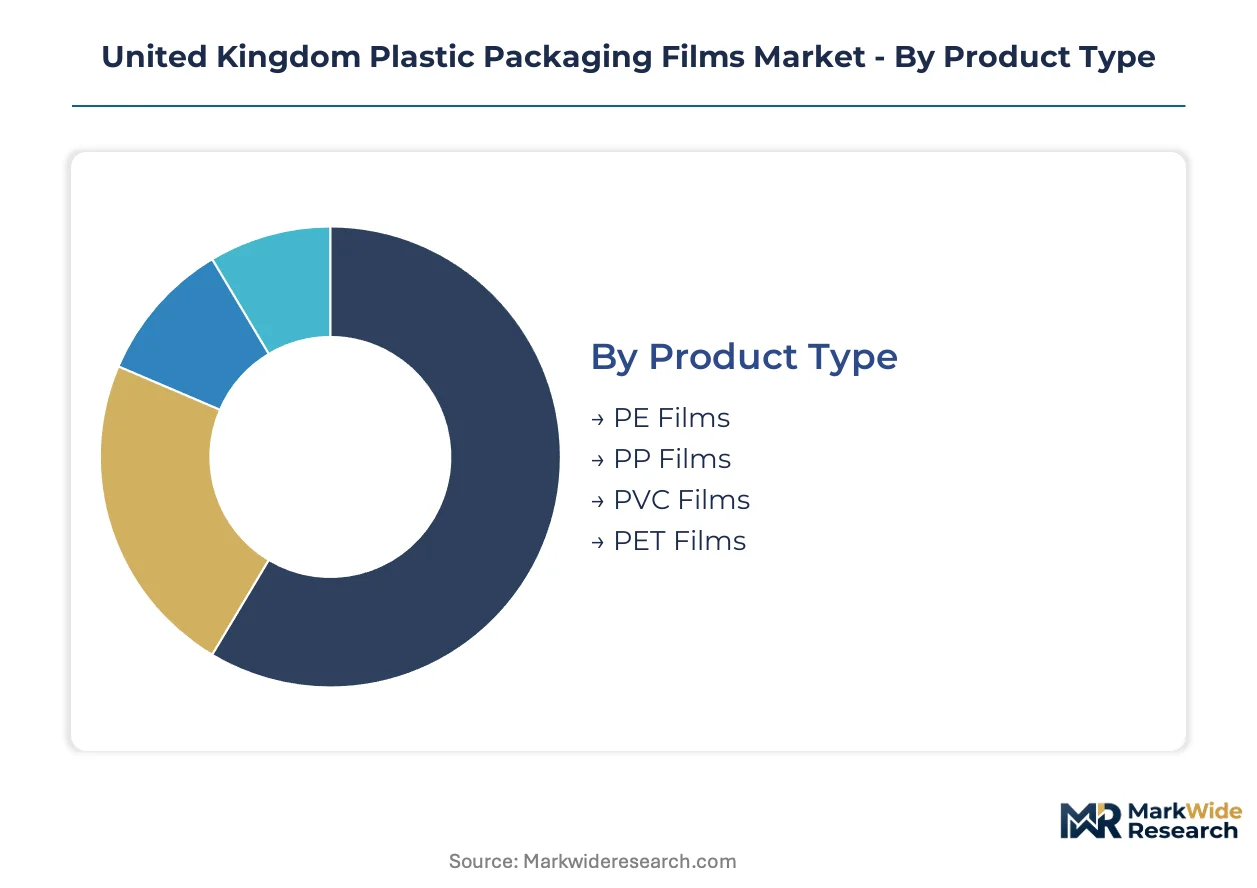
United Kingdom plastic packaging films demand fragments across material chemistries, end-use specifications, and thickness bands that each carry distinct tax implications under HMRC certification protocols. Converters must align segment selection with mechanical recycling compatibility to avoid Plastic Packaging Tax penalties.
Product Type:
Standardization dominates commodity grades while specialty resins require customized compounding for barrier and optical specifications.
- PE Films:Linear low-density and high-density polyethylene formulations anchor fresh produce wrapping and stretch wrap applications across Midlands fulfillment centers. Major grocery retailers in England specify mono-material PE flow-wrap to satisfy DEFRA modulated fee structures. Most installed capacity flows through PE Films. Expansion is steepest in recycled-content LDPE as compounders scale food-grade rPE supply chains.
- PP Films:Biaxially oriented polypropylene delivers stiffness and clarity for confectionery overwrap and tobacco packaging where dimensional stability matters. Yorkshire converters favor cast PP for high-speed form-fill-seal lines serving Scottish retail chains. Cast PP films serve pharmaceutical blister pack lidding where moisture vapor transmission rates below 0.5 g/m²/day are mandatory.
- PVC Films:Plasticized formulations retain niche positioning in medical device overwrap and cling film segments despite regulatory pressure from UK REACH restrictions on phthalate plasticizers.
- PET Films:Biaxially oriented polyester provides metallization substrates and high-temperature stability for ready-meal lidding in Greater London food manufacturing clusters.
PE and PP together absorb the majority of extrusion capacity. PET films are gaining share fastest in premium barrier applications.
End User:
Volume concentrates in food-contact applications where shelf-life extension competes with mono-material recyclability mandates.
- Food Packaging:Modified-atmosphere meat trays and fresh produce bags consume the largest film tonnages across English retail supply chains. High-barrier EVOH coextrusions for protein packaging face displacement pressure as supermarkets enforce single-polymer specifications. Food Packaging represents the dominant installed base. Pharmaceutical applications are climbing the fastest as MHRA serialization requirements expand tamper-evident film demand.
- Beverage Packaging:Shrink sleeves and collation films for bottled water and soft drinks operate at high line speeds in automated Greater London bottling facilities.
- Personal Care:Decorative printed films for cosmetics and toiletries prioritize surface gloss and scuff resistance over barrier performance.
- Pharmaceutical:Cold-form foil laminates and PVC/PVDC blister packs require exacting cleanliness standards and MHRA-compliant traceability documentation.
Food and beverage applications command the deepest converter relationships. Pharmaceutical films carry the steepest qualification barriers.
Thickness:
Thickness selection trades material cost reduction against mechanical integrity and barrier performance specifications.
- Below 20 Micron:Ultra-thin stretch films and hand-wrap grades minimize resin consumption for cost-sensitive logistics operations. Downgauging below this threshold conflicts with puncture resistance requirements in automated pallet-wrapping systems.
- 20-50 Micron:Machine-grade stretch wrap and industrial bundling films dominate shipment volumes across Yorkshire and Midlands distribution infrastructure. The 20-50 Micron band anchors the highest tonnage throughput. Below 20 Micron grades are expanding most quickly as pre-stretched film technology spreads.
- 51-100 Micron:Heavy-duty shrink films and agricultural silage wrap require elevated puncture resistance and UV stabilization for extended outdoor exposure.
- Above 100 Micron:Thick-gauge construction films and temporary protective sheeting serve building and infrastructure projects with lower performance specifications.
Mid-range thicknesses absorb the majority of resin volume. Thin-gauge expansion depends on pre-stretch equipment penetration.
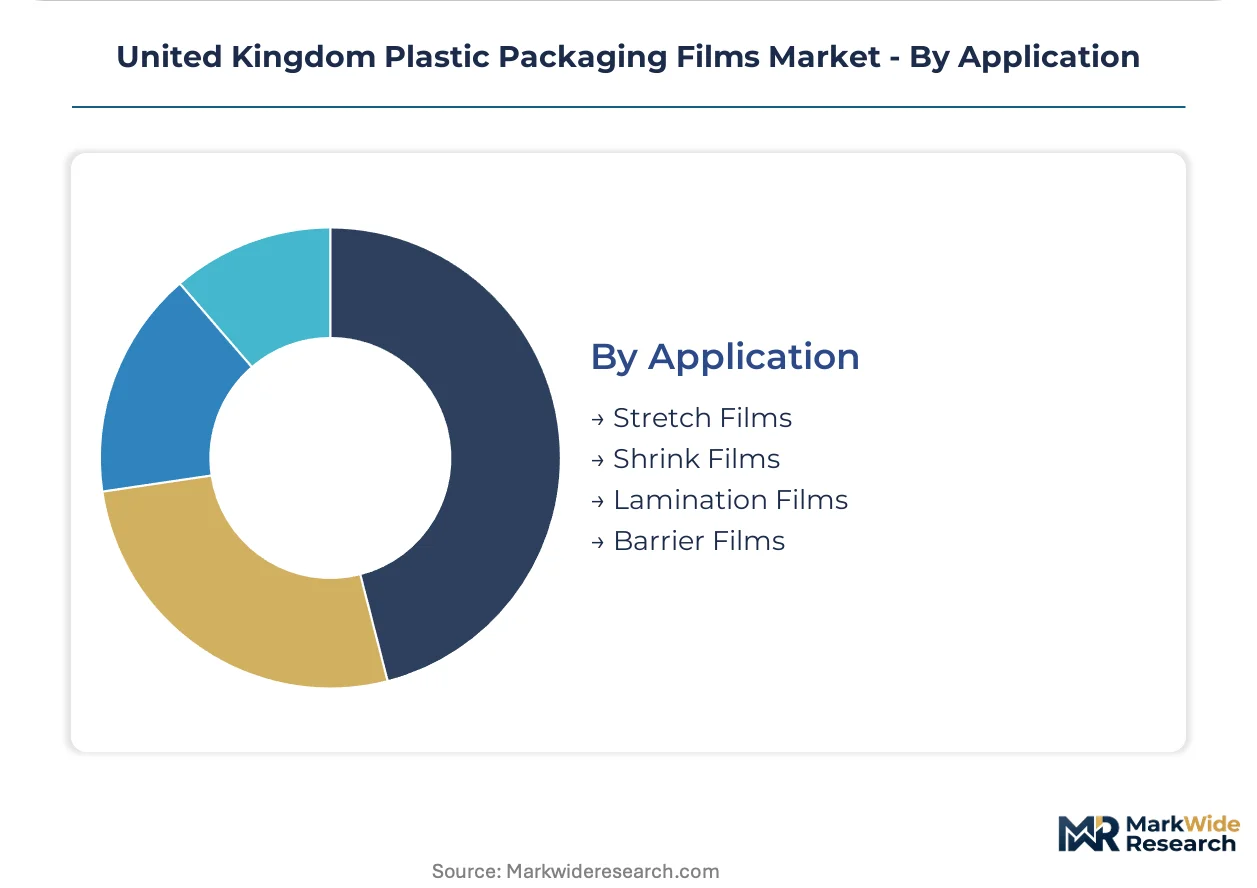
Application:
Functional requirements determine whether films prioritize unitization, containment, surface protection, or gas barrier performance.
- Stretch Films:Cast and blown LLDPE formulations with cling additives secure pallet loads in automated warehouse environments. Greater London e-commerce fulfillment centers specify machine films with consistent elongation properties for robotic wrapping systems. Stretch Films represent the largest installed application base. Barrier films are gaining share fastest as protein packaging shelf-life requirements tighten.
- Shrink Films:Cross-linked and non-cross-linked polyolefin formulations provide printed decoration and product collation for retail-ready packaging.
- Lamination Films:Adhesive and extrusion laminates bond dissimilar substrates for flexible pouches and sachets facing multi-layer recycling incompatibility challenges.
- Barrier Films:EVOH and PA coextrusions with oxygen scavenger layers extend red meat and smoked fish shelf life in Scottish retail distribution.
Stretch and shrink films together constitute the majority of extrusion output. Barrier film growth depends on mono-material redesign success.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between UK nations are redirecting film conversion capacity toward zones with integrated recycling infrastructure and lower compliance friction. The Plastic Packaging Tax enforcement varies in administrative burden across HMRC regional offices, creating localized arbitrage opportunities for compounders seeking mass balance certification efficiency.
Greater London and Southeast England
E-commerce fulfillment centers in Enfield, Dartford, and Milton Keynes consume machine-grade stretch films at automated throughput rates exceeding 200 pallets per hour. DEFRA's Extended Producer Responsibility modulated fees penalize multi-layer designs, pushing retailers toward mono-material specifications. The Thames Valley logistics corridor anchors the densest concentration of pre-stretched film procurement, with third-party logistics providers consolidating supplier relationships around technical service capabilities.
Midlands
Blown film extruders in Birmingham, Leicester, and Coventry are retrofitting lines for recycled-content LDPE formulations to satisfy the 30% threshold under HMRC protocols. The region's mechanical recycling plants struggle to yield food-grade rPE volumes, creating feedstock competition between compounders. Derbyshire and Nottinghamshire host the largest cluster of resin-to-roll integrated operations serving major grocery retail chains with private-label produce films.
Yorkshire and North England
Stretch-hood pallet-wrapping systems in Sheffield, Leeds, and Bradford distribution centers displace manual hand-wrap operations at accelerating rates. The British Standards Institution's PAS 5050 recyclability assessment criteria development in Manchester influences converter engineering decisions across the Pennine corridor. Hull and Grimsby seafood processors drive demand for high-barrier EVOH coextrusions, though mono-material redesign pressures threaten conventional multi-layer supply relationships.
Scotland
Fresh meat retail chains in Glasgow and Edinburgh extend shelf-life specifications for modified-atmosphere packaging, sustaining demand for oxygen barrier films despite recycling incompatibility challenges. The Scottish Government's circular economy strategy supports Grangemouth petrochemical infrastructure integration with mechanical recycling co-location. Aberdeen and Dundee converters specialize in agricultural silage wrap requiring UV stabilization for extended Highland exposure.
Wales
Pharmaceutical blister pack manufacturers in Cardiff and Newport face MHRA serialization compliance deadlines that expand tamper-evident film specifications. The Welsh Government's plastics roadmap targets single-use reduction, pressuring converters toward reusable transit packaging films. Wrexham and Deeside industrial zones leverage proximity to North West England resin distribution networks for cost-competitive compound supply.
United Kingdom Plastic Packaging Films Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue chemical recycling partnerships and mono-material barrier patents as differentiation vectors. The vendor base stratifies across three maturity levels: integrated resin-to-roll operators with captive polymerization, independent converters reliant on merchant resin supply, and specialty compounders focused on certified recycled-content formulations. Strategic archetypes include tax-optimized recyclability engineers, high-throughput logistics film suppliers, and pharmaceutical-grade barrier specialists. Competitive dynamics center on backward integration into resin compounding and selective technology licensing for thin-gauge barrier solutions.
Among integrated packaging conglomerates, Amcor PLC and Berry Global Inc. exemplify scale-driven positioning through European technical center proximity and resin-to-roll operations respectively. Innovia Films occupies a distinct specialization tier as a cellulose-based alternative developer targeting premium confectionery and tobacco overwrap segments where dimensional stability and optical clarity command price premiums. These three anchors illustrate the competitive spectrum from commodity volume leadership through material science differentiation.
| Leading Market Players |
|---|
| Elite Plastics Limited |
| Innovia Films |
| Berry Global Inc. |
| Klöckner Pentaplast |
| Cosmo Films |
| Amcor PLC |
| Coveris Holding |
| Sealed Air Corporation |
| Constantia Flexibles |
| Others |
Pricing and Supply Chain Analysis
Ethylene and propylene price indices on the London Metal Exchange cascade through UK resin distribution networks, compressing margins for independent converters while rewarding integrated resin-to-roll operators with captive polymerization capacity. The Plastic Packaging Tax at £210.82 per tonne for sub-30% recycled content creates a three-tier cost structure that separates HMRC-certified compounders from merchant resin buyers and virgin-only formulators.
Pricing Analysis
Distributor margins on merchant PE and PP resins absorb the steepest compression as compounders bypass wholesale channels for direct mill relationships. Pricing stratifies across premium, standard, and economy tiers based on recycled content certification grade and volume scale commitments. Cost compression in standard-grade films is intensifying because Midlands extruders compete for limited food-grade rPE supply. Logistics operators purchasing stretch films through third-party distributors exhibit the highest price sensitivity, while pharmaceutical blister pack buyers prioritize MHRA compliance over unit cost.
Supply Chain Analysis
Freight costs from Grangemouth petrochemical infrastructure to Midlands conversion plants anchor landed resin pricing for Yorkshire and North England extruders. Raw material supply draws from Saudi Arabian and Norwegian ethylene feedstock, UK North Sea natural gas for polymerization energy, and domestic mechanical recycling output. Single-source vulnerability concentrates in food-grade rPE certification chains subject to HMRC mass balance audit requirements. Distribution runs through resin distributors in the Thames Valley corridor serving Greater London fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in UK plastic packaging films rests on successful migration toward mono-material architectures that unlock DEFRA modulated fee savings and command premium positioning in protein packaging applications.
For Market Incumbents: Lock in resin supply security through backward integration into mechanical recycling partnerships or long-term offtake agreements with certified compounders. Berry Global and Amcor must defend against cellulose-based substitution in confectionery overwrap by accelerating thin-gauge barrier patent filings. Channel control through direct technical service relationships with Tesco and Sainsbury's procurement teams remains the critical lever. For New Entrants and Emerging Players: The Plastic Packaging Tax in the United Kingdom opens a window for chemical recycling ventures targeting mixed plastic waste streams exempt from HMRC penalties. White-space targets include pharmaceutical serialization films for NHS supply chains and pre-stretched machine films for Yorkshire automated distribution centers. A go-to-market angle anchored by mass balance certification efficiency offers faster customer qualification than commodity resin price competition. For Investors and Strategic Acquirers: Asymmetric upside sits with mono-material barrier technology developers holding patent positions in EVOH tie-layer redesign. Long-term viability favors compounders with integrated resin production and mechanical recycling co-location near Grangemouth infrastructure. Watch for BSI PAS 5050 recyclability assessment criteria publication as the inflection signal determining which film structures retain market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mechanical Recycling | Captive rPE supply secures HMRC certification and insulates against resin price volatility. |
| Mono-Material Barrier Patent Development | Intellectual property in EVOH tie-layer compatibility unlocks premium protein packaging contracts. |
| Chemical Recycling Scale-Up Partnership | Pyrolysis capacity addresses PCR shortage and delivers tax-exempt feedstock for food-contact films. |
| Direct Technical Service Model Deployment | On-site support at Greater London fulfillment centers captures automated stretch film procurement volumes. |
| HMRC Mass Balance System Certification | Auditable documentation infrastructure enables 30% recycled content claims and avoids tax penalties. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with blown film extruder plant managers, procurement leads at major UK grocery retailers, HMRC registration specialists, and technical directors at resin compounders with secondary validation against UK Environment Agency enforcement data, British Plastics Federation trade statistics, and Companies House filing records. Bottom-up capacity estimates from Midlands and Yorkshire extrusion facilities triangulated against top-down resin consumption figures from UK polymer distributors.
Segment-weighting across material chemistry, thickness band, and end-use application dimensions shaped volume and value outputs over the projection horizon. Modeled dimensions included PE versus PP versus PET resin families, below-20-micron through above-100-micron gauge tiers, and food packaging versus pharmaceutical versus logistics applications. CAGRs derived from elasticity-adjusted demand curves incorporating Plastic Packaging Tax compliance cost pass-through assumptions and e-commerce fulfillment automation penetration rates.
Revisions become necessary when HMRC enforcement intensity shifts, BSI PAS 5050 criteria exclude multi-layer constructions, or chemical recycling capacity fails to scale against mechanical recycling shortfalls. Forecasts reflect documented assumptions about resin price transmission and regulatory compliance cost allocation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Global Fluoropolymer Films Market
Poly film
Resealable Films Market
Poly film
Formable Films Market
Poly film
Packaging Film Market
Poly film
Cellulose Film Packaging Market
Poly film
Global Reclosable Films Market
Poly film
Polystyrene Films Market
Poly film
PVC Cling Film Market
Poly film
Silicone Release Films Market
Poly film
North America Shrink and Stretch Film Market
Poly film
Australia and New Zealand Plastic Packaging Film Market
Poly film
North America Polyimide Films Market
Poly film
Polyethylene Furanoate Films Market
Poly film
Global Biaxially Oriented Polypropylene (BOPP) in Films and Sheets Market
Poly film
Surface Printed Film Market
Poly film
Easy Peel Film Packaging Market