
 Flexible Plastic Pouches Market | 2026-2036
Flexible Plastic Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Plastic Pouches Market Analysis
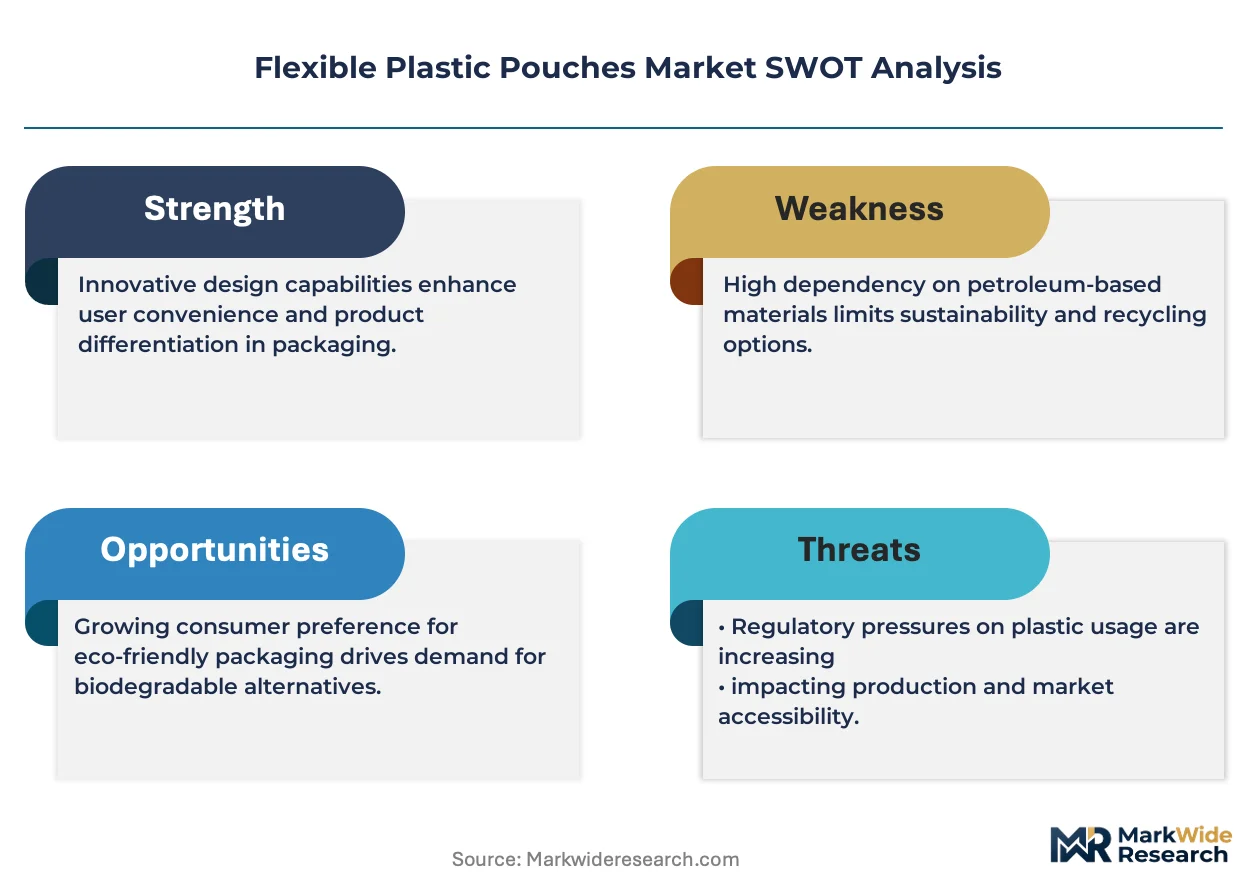
The EU Green Deal is restructuring flexible packaging demand across Europe as brands face binding recycled-content mandates. Amcor Plc leverages its global R&D network to develop mono-material structures that simplify recycling streams. Mondi anchors its competitive position through integrated paper and film operations that reduce substrate costs. Berry Global Inc. specializes in high-performance barrier films for protein and dairy applications where shelf-life extension commands premium positioning.
Flexible plastic pouches are multi-layer polymer containers, typically combining polyethylene, polyamide, or polyethylene terephthalate films through extrusion lamination or coextrusion, designed to replace rigid containers in liquid, powder, and solid product distribution. Stand-up pouches dominate value generation due to their shelf presence and reduced material intensity versus bottles or cans. Zipper pouches represent the fastest-expanding closure segment as convenience-driven consumers prioritize resealability in snacks and pet food. Food packaging absorbs the majority of volume, though healthcare applications for sterile single-use pouches are gaining share as pharmaceutical serialization requirements tighten.
REACH compliance in Europe, FDA food-contact regulations in the United States, and BIS certification requirements in India collectively shape material selection, migration limits, and market access for pouch suppliers. ECHA's evolving restrictions on per- and polyfluoroalkyl substances are forcing reformulation of grease-resistant barrier coatings. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and compliance-driven cost escalation.
Market Dynamics
Mono-material pouch structures are displacing multi-layer laminates as Extended Producer Responsibility schemes in the EU, India, and several US states mandate design-for-recycling compliance. This single technical pivot is forcing substrate suppliers, converters, and brand owners into coordinated reformulation investments that will determine competitive survival through 2035.
Growth Catalysts
- EU Green Deal recycled-content mandates:Binding targets for post-consumer recycled plastic in packaging are pulling investment into compatible pouch structures. Brand owners in Germany, France, and the Netherlands are accelerating supplier qualification timelines.
- India organized retail expansion:Modern trade formats in Mumbai, Delhi, and Bangalore are standardizing shelf-ready pouch specifications. This creates pull-through for pre-made pouch equipment and printed film supply chains.
- Zipper resealability technology:Press-to-close and slider mechanisms are penetrating snack, pet food, and home care segments. Consumers demonstrate willingness to pay packaging premiums for portion control and freshness extension.
Market Restraints
- Polyamide price volatility:Nylon resin costs fluctuate with crude oil and adipic acid feedstock markets. Barrier-dependent applications face margin compression when oil benchmarks spike.
- Recycling infrastructure gaps:Flexible film collection and sortation capacity concentrates in Germany, Italy, and select US regions. Most municipalities lack equipment to separate pouches from rigid containers.
- Per- and polyfluoroalkyl substance restrictions:ECHA proposals to limit PFAS in food-contact materials are forcing grease-resistant coating reformulations. Paper-based alternatives currently fail moisture barrier requirements.
Strategic Opportunities
- Pharmaceutical serialization compliance:EU MDR and US FDA track-and-trace mandates are creating demand for sterile single-use pouches with integrated tamper evidence. Contract packaging organizations are qualifying new pouch formats.
- Home compostable certification pathways:TUV Austria and BPI standards are opening shelf-space access in premium organic segments. Material suppliers with certified resin portfolios capture brand owner attention.
- E-commerce fulfillment optimization:Dimensional weight pricing from logistics providers favors lightweight pouch formats over bottles and jars. Subscription snack and personal care brands are redesigning primary packaging.
Industry Challenges
- Multi-layer delamination expertise shortage:Converting engineers with coextrusion and adhesive lamination experience are concentrated at established European and North American firms. Emerging market converters struggle with yield optimization.
- Migration testing timeline compression:FDA and EFSA food-contact notification reviews are extending as novel mono-material structures submit for approval. Product launch schedules face regulatory delay risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Plastic Pouches Market |
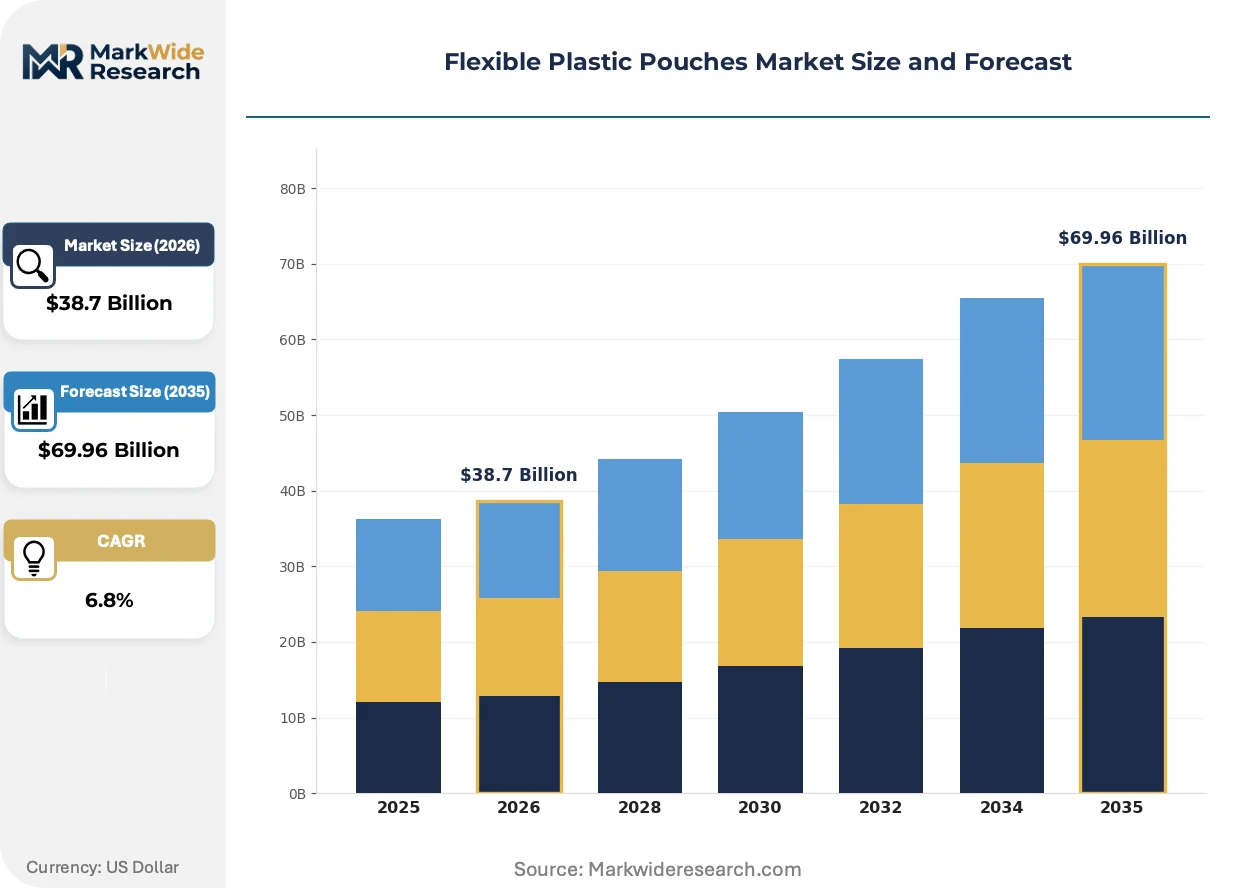
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Zipper Pouches, Vacuum Pouches Material: LDPE, HDPE, Nylon, PET End Use: Food Packaging, Healthcare, Personal Care, Industrial Closure Type: Zip Lock, Heat Seal, Easy Tear, Resealable |
| Companies Covered | Berry Global Inc., Mondi, Sealed Air Corp., Sonoco Products Company, Amcor Plc, Huhtamaki, Smurfit Kappa, Constantia Flexibles, ProAmpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Plastic Pouches Market Emerging Trajectories
Digital printing and laser scoring technologies are collapsing minimum order quantities and enabling mass customization. These capabilities are rewiring how brand owners plan packaging refresh cycles and regional variant launches.
Polyethylene-based mono-material pouches are rewriting recycling economics by eliminating incompatible polymer layers. Major retailers in Germany and the UK are adopting these structures for private-label dry goods. The simplification is enabling mechanical recycling streams that previously rejected flexible packaging.
REACH restrictions on intentionally added microplastics are forcing reformulation of tear-notch additives and anti-slip agents. Compounders serving the European market are submitting alternative chemistries for ECHA evaluation. Personal care and household product pouches face the most immediate compliance deadlines.
Direct-to-consumer subscription models are compressing packaging specification cycles from annual to quarterly reviews. Snack and supplement brands in the US and UK are A/B testing pouch designs through digital channels. This velocity is straining converter artwork management and plate-making workflows.
Flexible Plastic Pouches Market Segmentation
Flexible plastic pouches serve divergent functional requirements across food preservation, pharmaceutical sterility, and industrial logistics. Segment boundaries are blurring as mono-material designs force substrate suppliers to rebalance barrier performance against recyclability. Brand owners now specify structures by end-use performance rather than legacy product categories.
Product Type:
Customization intensity varies sharply across this category, from standardized flat formats to engineered stand-up structures with integrated fitments.
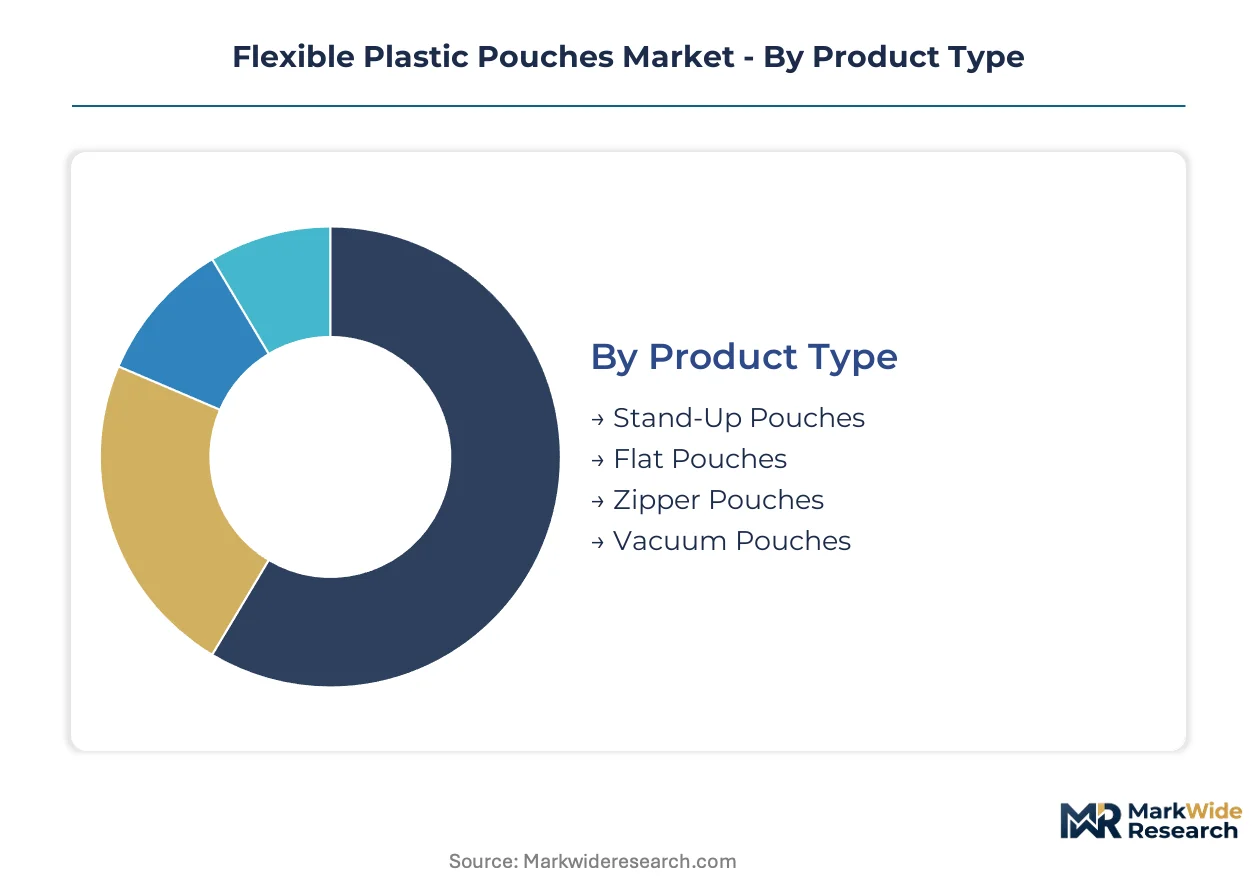
- Stand-Up Pouches:These structures incorporate gusseted bottoms that enable vertical shelf display while reducing material usage versus rigid alternatives. Demand concentrates in Germany, France, and the UK where retailers mandate shelf-ready packaging for private-label dry goods. The format commands premium positioning in snacks and pet food where brand visibility drives purchase decisions.
- Zipper Pouches:Press-to-close and slider mechanisms transform single-use packaging into multi-serve containers. Growth is steepest in US and Indian snack markets where convenience-driven consumers prioritize portion control and freshness extension between uses.
- Flat Pouches:Two-dimensional sealed bags remain the default for single-serve condiments, sample packets, and industrial components. These structures minimize material cost and shipping cube for high-volume, low-margin applications.
- Vacuum Pouches:Multi-layer barrier films with oxygen transmission rates below 1 cc/m²/day preserve protein freshness in chilled distribution. Meat processors in Italy and Spain specify these structures for extended shelf-life retail programs.
Most installed capacity flows through Stand-Up Pouches. Expansion is steepest in Zipper Pouches.
Material:
Cost tier separation in this category reflects feedstock volatility and barrier performance requirements rather than processing complexity alone.
- LDPE:Low-density polyethylene dominates mono-material pouch development due to inherent flexibility and established mechanical recycling streams. Major German retailers are specifying LDPE-only structures for private-label dry goods to meet EU Green Deal recycled-content mandates.
- PET:Polyethylene terephthalate delivers superior clarity and printability for premium food and personal care applications. The material is gaining share in Indian organized retail where Mumbai and Delhi supermarkets prioritize shelf appeal for imported brands.
- HDPE:High-density polyethylene offers stiffness and chemical resistance for industrial and agricultural chemical packaging. The material resists puncture from abrasive contents but lacks the clarity required for consumer-facing applications.
- Nylon:Polyamide provides essential oxygen and aroma barrier in coextruded structures for cheese, cured meats, and coffee. Price volatility in adipic acid feedstocks forces converters to hedge resin positions or specify alternative barrier coatings.
Volume leadership sits with LDPE. PET is climbing the fastest as premium retail formats expand.
End Use:
Application-driven specifications in this category create divergent certification requirements and margin structures across segments.
- Food Packaging:This segment absorbs the majority of flexible pouch volume across snacks, dairy, frozen produce, and ready-meal categories. FDA food-contact regulations in the US and FSSAI compliance in India govern migration limits and additive approvals for direct food contact.
- Healthcare:Sterile single-use pouches for medical devices and pharmaceutical components are gaining share as EU MDR track-and-trace mandates tighten packaging traceability. Contract packaging organizations in Germany and Switzerland are qualifying new high-barrier formats.
- Personal Care:Stand-up pouches with flip-top dispensing fitments are displacing bottles for shampoo, conditioner, and body wash in e-commerce channels. Dimensional weight pricing from logistics providers favors lightweight formats over rigid containers.
- Industrial:Heavy-duty pouches with welded seams contain adhesives, sealants, and lubricants for manufacturing supply chains. These applications prioritize puncture resistance and chemical compatibility over print quality or shelf aesthetics.
Food Packaging retains dominant volume share. Healthcare is expanding most quickly due to serialization compliance requirements.
Closure Type:
Customer type differentiation in this category separates convenience-oriented consumers from cost-optimized industrial buyers.
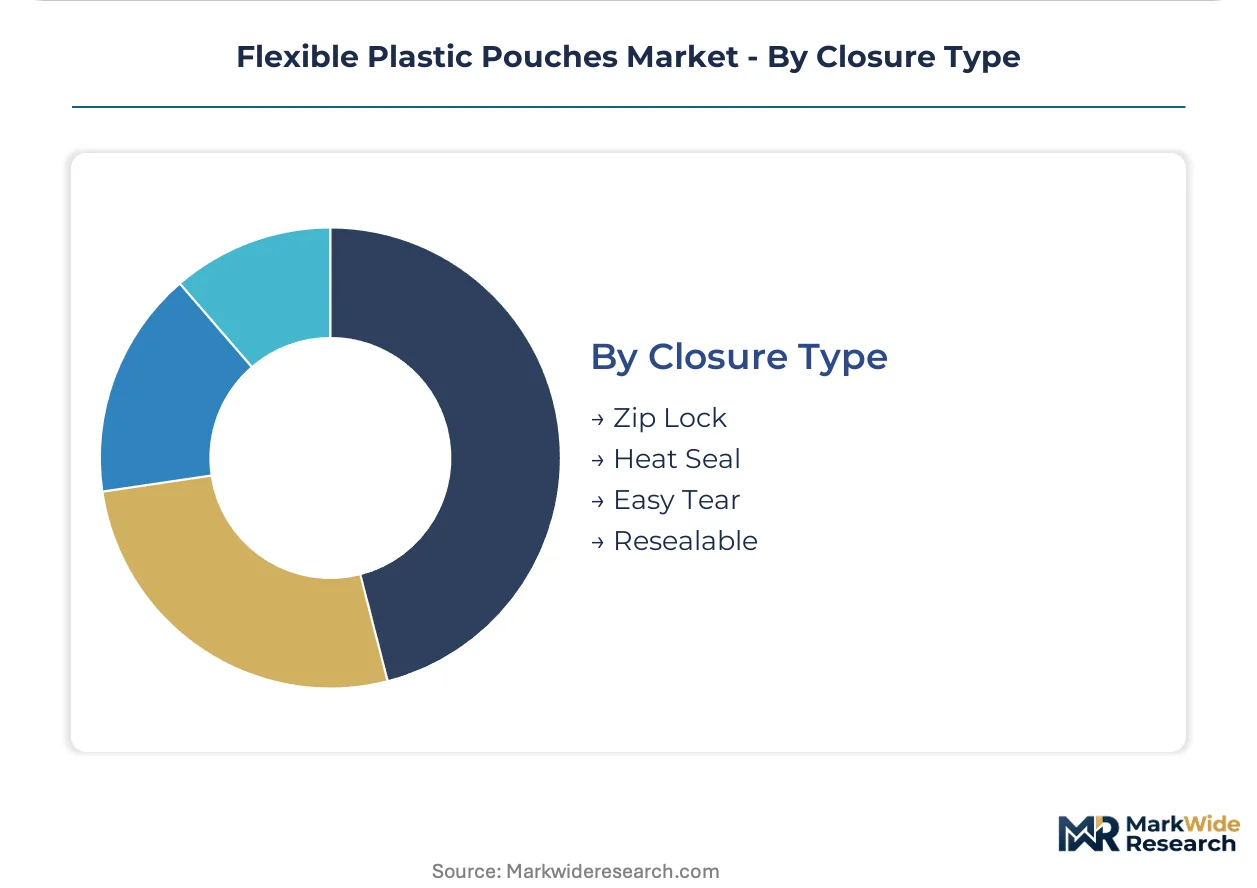
- Heat Seal:Permanent bonded seams provide tamper evidence and hermetic protection at lowest unit cost. This closure dominates single-serve food and industrial applications where resealability adds no functional value.
- Zip Lock:Interlocking plastic tracks enable repeated opening and closing without tools. The format is penetrating Indian pet food and snack markets where Bangalore and Delhi consumers demonstrate willingness to pay packaging premiums.
- Resealable:Adhesive strip systems offer intermediate convenience between permanent seals and mechanical zippers. These closures appear in European bakery and produce applications where moderate barrier protection suffices.
- Easy Tear:Laser-scored notches or directional tear propagation features improve user experience for elderly consumers and field-use scenarios. REACH restrictions on intentionally added microplastics are forcing reformulation of tear-notch additives in European markets.
Heat Seal retains the largest installed base. Zip Lock is gaining share fastest as convenience positioning intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converting engineers with coextrusion expertise cluster in Germany, Switzerland, and the United States, anchoring technical leadership for high-barrier pouch development. These talent concentrations determine where next-generation mono-material structures achieve commercial scale first.
Germany
Private-label dry goods retailers in Berlin and Hamburg are mandating LDPE-only pouch structures to meet EU Green Deal recycled-content targets. ECHA's evolving PFAS restrictions are forcing grease-resistant coating reformulations across Bavarian converting facilities. The Rhine-Ruhr industrial corridor hosts integrated film extrusion operations supplying mono-material substrates to brand owners.
United States
FDA food-contact notification reviews are extending timelines for novel mono-material structures, delaying product launches for snack and pet food brands. E-commerce subscription models in Austin and Brooklyn are compressing packaging specification cycles to quarterly reviews. The Midwest converting belt around Chicago maintains installed capacity for high-volume zipper pouch production.
India
Organized retail expansion in Mumbai, Delhi, and Bangalore is standardizing shelf-ready pouch specifications for modern trade formats. FSSAI compliance requirements govern migration limits for direct food-contact applications in dairy and ready-meal segments. Gujarat and Maharashtra host pre-made pouch equipment installations serving domestic and export markets.
Italy
Meat processors in Emilia-Romagna specify vacuum pouch structures with oxygen transmission rates below 1 cc/m²/day for extended shelf-life retail programs. REACH compliance costs are concentrating investment at larger converters with in-house migration testing capabilities. The Milan-Turin industrial axis supplies multi-layer barrier films to European protein packagers.
Switzerland
Contract packaging organizations in Zurich and Basel are qualifying sterile single-use pouch formats for EU MDR track-and-trace mandates. Swissmedic oversight shapes pharmaceutical serialization requirements for medical device packaging. The country's precision manufacturing heritage supports high-barrier healthcare pouch development.
Flexible Plastic Pouches Market Vendor Landscape
Capital-heavy producers with integrated film extrusion and converting assets compete with asset-light designers outsourcing substrate supply to specialized compounders. The vendor base separates into three tiers: multinational film suppliers with global R&D networks, regional converters serving national brand owners, and specialized equipment manufacturers enabling pouch formation. Strategic moves concentrate on mono-material structure development and pre-made pouch equipment partnerships to capture recycling-compliant demand.
Within the integrated multinational tier, Amcor Plc and Berry Global Inc. exemplify capital deployment toward mono-material R&D platforms. Mondi anchors European positioning through captive paper and film operations. Sealed Air Corp. occupies the equipment-integrated solutions vector, bundling machinery with substrate supply. These archetypes reflect divergent bets on whether recycling economics or barrier performance will dominate customer procurement criteria through 2035.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Mondi |
| Sealed Air Corp. |
| Sonoco Products Company |
| Amcor Plc |
| Huhtamaki |
| Smurfit Kappa |
| Constantia Flexibles |
| ProAmpac |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between EU Green Deal-compliant mono-material structures and legacy multi-layer laminates manifests in divergent pricing power and supply chain sourcing patterns. Premium LDPE-only pouches command structural premiums through captive resin supply agreements with German compounders, while commodity converters in India and Vietnam compete on polyethylene spot pricing with minimal barrier performance guarantees.
Pricing Analysis
Bundled equipment-substrate packages from Sealed Air Corp. and integrated converters trade at 15-25% premiums over unbundled film-and-converter sourcing. Three-tier pricing structure across premium, standard, and economy levels separates FDA-notified healthcare pouches from FSSAI-compliant food packaging and uncertified industrial formats. Pricing pressure stems from adipic acid volatility forcing nylon hedge costs onto protein packaging customers. Brand owners in Indian organized retail demonstrate highest price sensitivity, while Swiss pharmaceutical contract packers absorb premiums for serialization-ready sterile formats.
Supply Chain Analysis
EU MDR and FDA food-contact qualification gating concentrates approved substrate supply among German, Swiss, and US resin compounders with in-house migration testing. Raw material flows draw from Saudi and Qatari polyethylene feedstocks, Chinese PET resin operations, and Belgian adipic acid production for polyamide barrier layers. Single-source vulnerability sits with European PFAS-free coating alternatives, where TUV Austria-certified grease barriers remain capacity-constrained. Distribution runs through regional converting hubs in Chicago, Milan-Turin, and Gujarat, with finished pouches shipping direct to brand owner co-packing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by pharmaceutical serialization mandates pulling demand toward medical-grade barrier specifications. Premium pouch structures with integrated track-and-trace features capture disproportionate margin expansion as compliance requirements tighten.
For Market Incumbents: Hedge resin exposure through backward integration into LDPE compounding or long-term offtake agreements with Middle Eastern feedstock suppliers. Defend margin position by accelerating mono-material R&D platforms ahead of ECHA's evolving PFAS restrictions, which threaten stranded inventory for grease-resistant coating dependent converters.
For New Entrants and Emerging Players: Regional Indian brand owners underserved by multinational converters present the most penetrable white-space target, particularly in Bangalore and Mumbai modern trade formats. Home compostable certification pathways for organic snack segments offer second entry vector. A co-packing partnership model with domestic equipment installers bypasses capital-heavy extrusion asset requirements.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier converters possessing EU MDR-qualified cleanroom capacity but lacking global brand owner relationships. Long-term viability through the next decade hinges on mono-material structure portfolios and pharmaceutical serialization capabilities. Watch for inflection when German retailers mandate LDPE-only specifications across private-label dry goods categories.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Structure Development | Enables mechanical recycling compliance with EU Green Deal recycled-content mandates. |
| Pharmaceutical Serialization Investment | Captures EU MDR and FDA track-and-trace mandate demand from contract packagers. |
| Pre-Made Pouch Equipment Partnership | Accelerates speed-to-market for Indian organized retail shelf-ready specifications. |
| Home Compostable Certification | Opens premium organic segment shelf-space through TUV Austria and BPI standards. |
| Digital Printing Capability Addition | Collapses minimum order quantities for subscription snack brand quarterly refresh cycles. |
Methodological Framework
Direct dialogue with resin compounders, converting engineers, brand owner packaging directors, and pharmaceutical contract packaging managers grounded qualitative assessment in operational reality. Secondary validation drew from ECHA restriction proposals, FDA food-contact notification databases, FSSAI additive approval registers, and EU MDR implementation guidance documents. Bottom-up capacity estimates from German and Indian extrusion installations were triangulated against top-down demand projections from retail format expansion data.
Segment-level value and volume trajectories across the projection horizon reflect modeled interactions between material substitution rates, regulatory compliance timelines, and end-use adoption curves. Segmentation dimensions included product type, material substrate, closure mechanism, end-use application, and geographic regulatory cluster. CAGRs were derived from elasticity-adjusted demand functions incorporating EPR scheme implementation schedules and organized retail penetration rates in India.
Underlying measurement precision varies by segment; pharmaceutical and healthcare applications carry tighter precision than industrial chemical packaging given clearer regulatory boundaries. Forecasts reflect assumptions about PFAS restriction timelines, mechanical recycling infrastructure buildout, and adipic acid feedstock stability. A model refresh is warranted upon material change in ECHA's final PFAS restriction scope or German retailer private-label mandate acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Asia-Pacific Retort Pouch Market
Pouch
Kraft Paper Pouch Market
Pouch
GCC Retort Pouches Market
Pouch
Egypt Pouch Packaging Market
Pouch
Foil Pouch Packaging Market
Pouch
Child Resistant Locking Pouches Market
Pouch
Benelux Pouch Packaging Market
Pouch
Global Medical and Pharmaceutical Pouch Market
Pouch
Sterilization Pouches Market
Pouch
Heat Seal Pouch Market
Pouch
Vented Stretch Wrap Market
Pouch
Digital Printed Pouch Market
Pouch
Box Pouch Market
Pouch
Russia Pouch Packaging Market
Pouch
2 Seal Pouches Market
Pouch
Spout Pouch Market