
 North America Plastic Film Packaging Market | 2026-2036
North America Plastic Film Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Plastic Film Packaging Market Insights
The North America plastic film packaging market is recalibrating as premium multilayer barrier films and commodity monolayer wraps diverge on price, performance specifications, and sustainability credentials. Amcor leverages its integrated resin-to-film manufacturing footprint to sustain margin control across both tiers. Berry Global Group anchors its position through geographic density in US Southeast conversion facilities. Sealed Air Corporation differentiates via active and intelligent packaging technologies embedded within film structures.
Plastic film packaging comprises extruded or cast polymer sheets, typically ranging from 12 to 150 microns in thickness, engineered to protect, contain, and preserve goods through controlled permeability, seal integrity, and mechanical strength. The primary commercial purpose centers on reducing product loss, extending shelf stability, and enabling automated handling across manufacturing and distribution networks. Polyethylene formulations dominate volume flows given their cost position and versatility in stretch and shrink applications, while bioplastics represent the fastest-expanding material category as brand owners face Scope 3 emissions accounting pressures. Barrier film architectures command superior margin pools due to coextrusion complexity and food safety certification requirements that limit supplier proliferation.
The US EPA, California's Department of Resources Recycling and Recovery under SB 54, and the FDA's food contact notification framework collectively reshape resin selection, recycled content verification, and market access conditions across North America. FDA compliance for post-consumer recycled content in food-contact films demands extensive extraction and testing protocols that favor larger compounders with dedicated regulatory affairs capacity. Stakeholders must monitor evolving extended producer responsibility fee structures and recycled content thresholds to determine whether to invest in mechanical recycling integration or advanced chemical recycling partnerships.
Market Dynamics
California's SB 54 implementation timeline is forcing resin sourcing shifts across the entire value chain, compelling converters to requalify supply chains for post-consumer recycled content while maintaining FDA food contact compliance. This regulatory compression is splitting the market between mechanical recycling integrators and advanced chemical recycling partners.
Growth Catalysts
- Extended Shelf-Life Proteins:Food and beverage processors are expanding film-based packaging for ready-to-eat formats, driving demand for high-barrier coextruded structures that reduce protein spoilage.
- US EPA Recycled Content Mandates:Advancing federal requirements for post-consumer resin incorporation are accelerating capital deployment into extraction and decontamination infrastructure.
- Gulf Coast Feedstock Proximity:Polymer production clustering near Texas and Louisiana ethane supply is concentrating conversion capacity in the US Southeast, reducing inbound logistics costs for regional processors.
Market Restraints
- Ethane Price Volatility:Natural gas liquid feedstock swings compress margin predictability for polyethylene resin producers serving film converters.
- Mechanical Recycling Contamination Limits:FDA extraction testing protocols for post-consumer content in food-contact applications favor larger compounders with dedicated regulatory affairs capacity, excluding mid-tier competitors.
- Paperboard Substitution Pressure:Brand owner Scope 3 emissions accounting is accelerating pilot programs for fiber-based barrier packaging in dry goods segments.
Strategic Opportunities
- Active and Intelligent Packaging Integration:Oxygen scavenging and time-temperature indicator films represent underpenetrated premium tiers in protein and pharmaceutical cold chains.
- Mexico Nearshoring Expansion:US brand owners are qualifying Mexican conversion facilities to reduce trans-Pacific supply chain exposure and duty exposure.
- Chemical Recycling Partnerships:Pyrolysis and depolymerization of mixed polyolefin waste streams enables food-grade resin output without mechanical recycling purity constraints.
Industry Challenges
- Coextrusion Operator Shortage:Seven-layer barrier film production requires specialized technicians with polymer rheology expertise that vocational programs have not scaled to match demand.
- Legacy Equipment Retrofit Costs:Converting cast film lines to handle post-consumer recycled resin without gels or optical defects demands capital outlays that stretch mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Plastic Film Packaging Market |
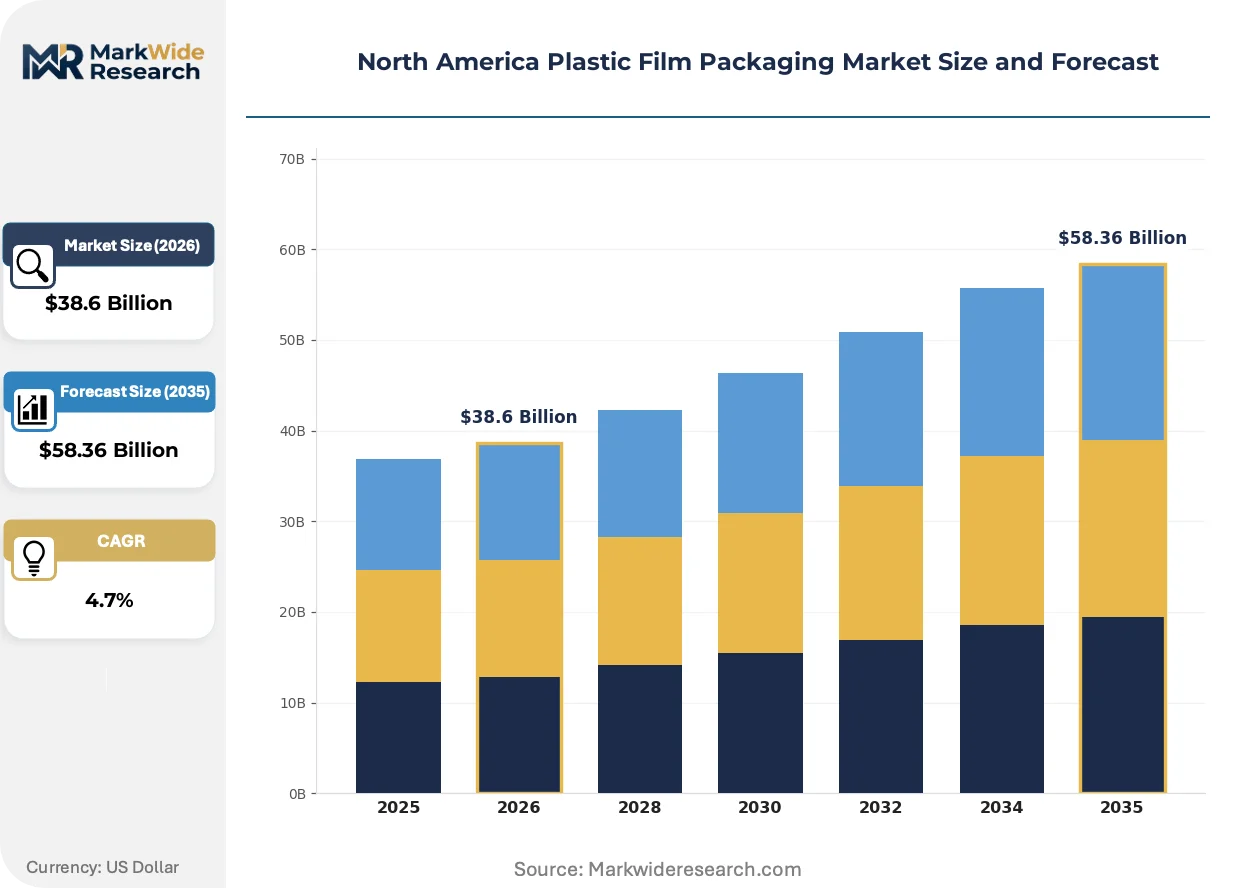
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.36 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Film, Shrink Film, Barrier Film, Pallet Wrap Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Bioplastics End Use Industry: Food & Beverage, Healthcare, Consumer Goods, Electronics Packaging Type: Roll Stock, Pouches, Bags, Sheets |
| Companies Covered | Amcor, Berry Global Group, Sealed Air Corporation, Profol Americas Inc., TEKRA LLC, Cosmo Films Inc., Taghleef Industries Inc., Winpak Ltd, Transcontinental Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Plastic Film Packaging Market Trends and Innovations
Film packaging is undergoing material architecture transformation as sustainability compliance and functional performance requirements diverge. Three distinct vectors are reshaping competitive positioning and investment priorities.
Barrier film structures are converging with bio-based sealant layers to maintain oxygen and moisture protection while reducing fossil-derived content. Premium protein packagers in the US Northeast are piloting these hybrid architectures for refrigerated distribution. The structural consequence is compressing margin pools for commodity monolayer converters unable to fund coextrusion line upgrades.
California's Department of Resources Recycling and Recovery is enforcing SB 54 extended producer responsibility fee structures that scale with virgin resin intensity. This industrial consequence is redirecting procurement budgets toward mechanically recycled content verification systems. Food-contact film segments are responding by consolidating supplier relationships around compounders with FDA pre-submitted food contact notifications.
Brand owner sustainability scorecards are compressing supplier qualification cycles from annual reviews to quarterly data submissions. Retail and foodservice channels are displacing traditional spot purchasing with multi-year indexed contracts tied to recycled content thresholds. This pattern is most visible in US Southeast poultry and prepared meal segments where Walmart and Kroger procurement teams have implemented supplier sustainability dashboards.
North America Plastic Film Packaging Market Segmentation
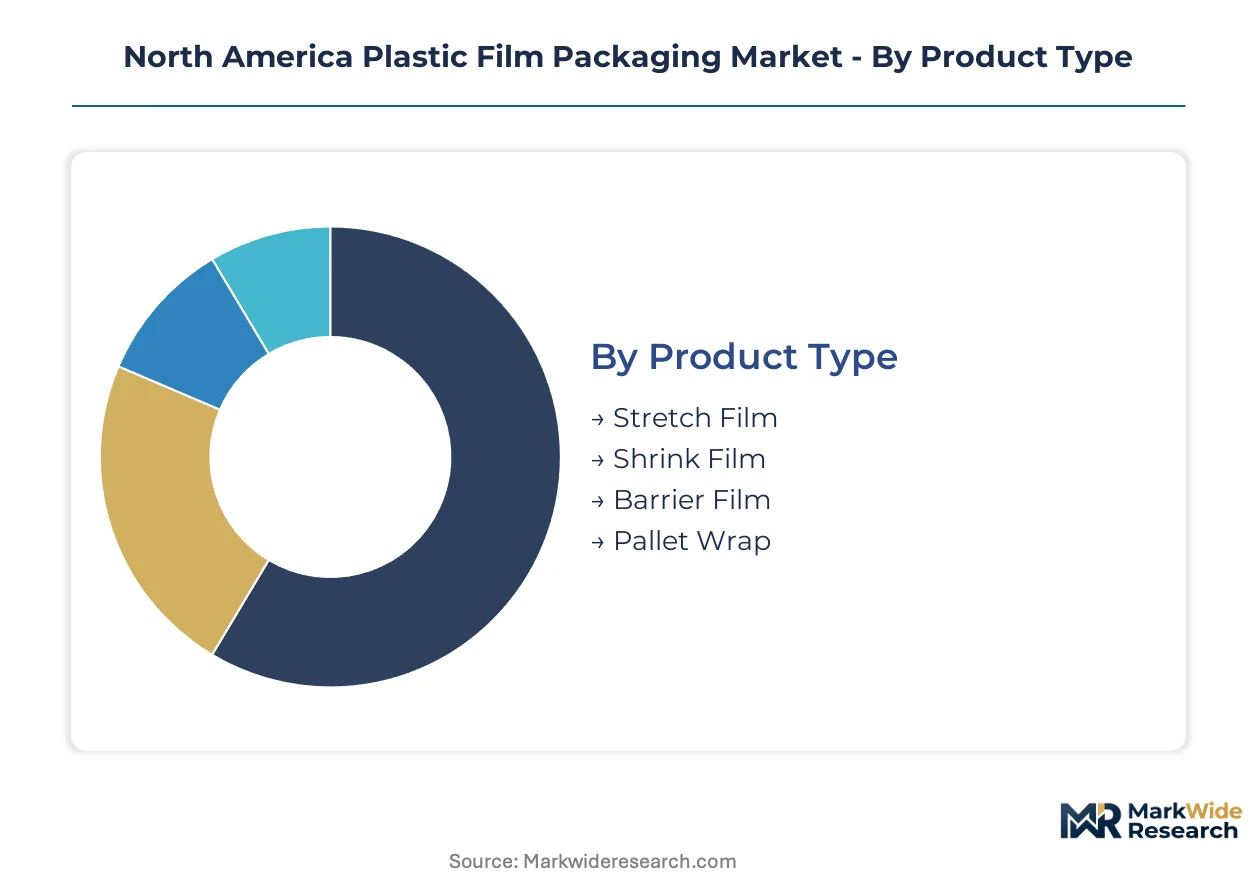
Plastic film packaging segments diverge sharply on technical complexity and margin structure. Standalone commodity films compete on scale economics, while embedded barrier systems command premium positioning through coextrusion expertise and food safety certification.
Product Type:
Integration depth separates films deployed as standalone wrapping systems from those embedded within multilayer packaging architectures.
- Stretch Film:Linear low-density polyethylene formulations dominate manual and machine-wrap applications. US Southeast distribution centers and third-party logistics providers are standardizing on 20-micron cast films to reduce pallet unit costs while maintaining load containment.
- Barrier Film:Seven-layer coextruded structures incorporating ethylene vinyl alcohol or polyamide cores deliver oxygen transmission rates below 1 cc/m²/day. Premium protein packagers in the US Northeast specify these for vacuum-packed beef and poultry to extend retail case life.
- Shrink Film:Cross-linked polyolefin formulations provide optical clarity and puncture resistance for retail multipack display. Beverage bottlers favor this format for shelf-ready secondary packaging.
- Pallet Wrap:High-performance blends with reinforced edges target automated stretch wrapping lines in California produce distribution hubs facing SB 54 compliance pressures on virgin resin content.
Stretch film leads volumes today; barrier film is gaining share fastest.
Material:
Cost tier stratification runs from commodity polyolefins through engineering polymers to nascent bio-based alternatives with divergent margin profiles.
- Polyethylene:Low-density and linear low-density grades constitute the volume backbone, extruded at 12-50 microns for general-purpose containment. Gulf Coast ethane feedstock proximity sustains cost advantages for Texas and Louisiana-based converters.
- Bioplastics:Polylactic acid and polyhydroxyalkanoate formulations address Scope 3 emissions accounting pressures from brand owners. Pilot programs at US Northeast prepared meal processors are qualifying these for refrigerated distribution with modified atmosphere requirements.
- Polypropylene:Biaxially oriented films deliver stiffness and heat resistance for retort pouch applications. Healthcare sterilization packaging relies on cast polypropylene for autoclave compatibility.
- Polyvinyl Chloride:Plasticized formulations persist in specific medical device overwrap and blister pack applications where clarity and thermoformability outweigh substitution pressures.
Polyethylene dominates current output; bioplastics show the steepest expansion trajectory.
End Use Industry:
Application-specific performance requirements drive formulation customization and certification burden variation across customer verticals.
- Food & Beverage:Modified atmosphere packaging for extended shelf-life proteins demands high-barrier coextrusion with FDA food contact notification compliance. US Southeast poultry processors are consolidating supplier relationships around compounders with pre-submitted extraction protocols.
- Healthcare:Sterile barrier systems for medical devices require ISO 11607 compliance and validated seal integrity. Tyvek-film combinations dominate Class II and III device packaging.
- Consumer Goods:Shrink-wrapped multipacks and printed overwrap prioritize optical properties and graphic reproduction for retail shelf impact.
- Electronics:Static-dissipative films and moisture barrier bags protect semiconductor components through distribution.
Food & Beverage anchors demand today; Healthcare is climbing the fastest on regulatory compliance premiums.
Packaging Type:
Supply chain position distinguishes converter inputs from finished formats ready for filling and distribution.
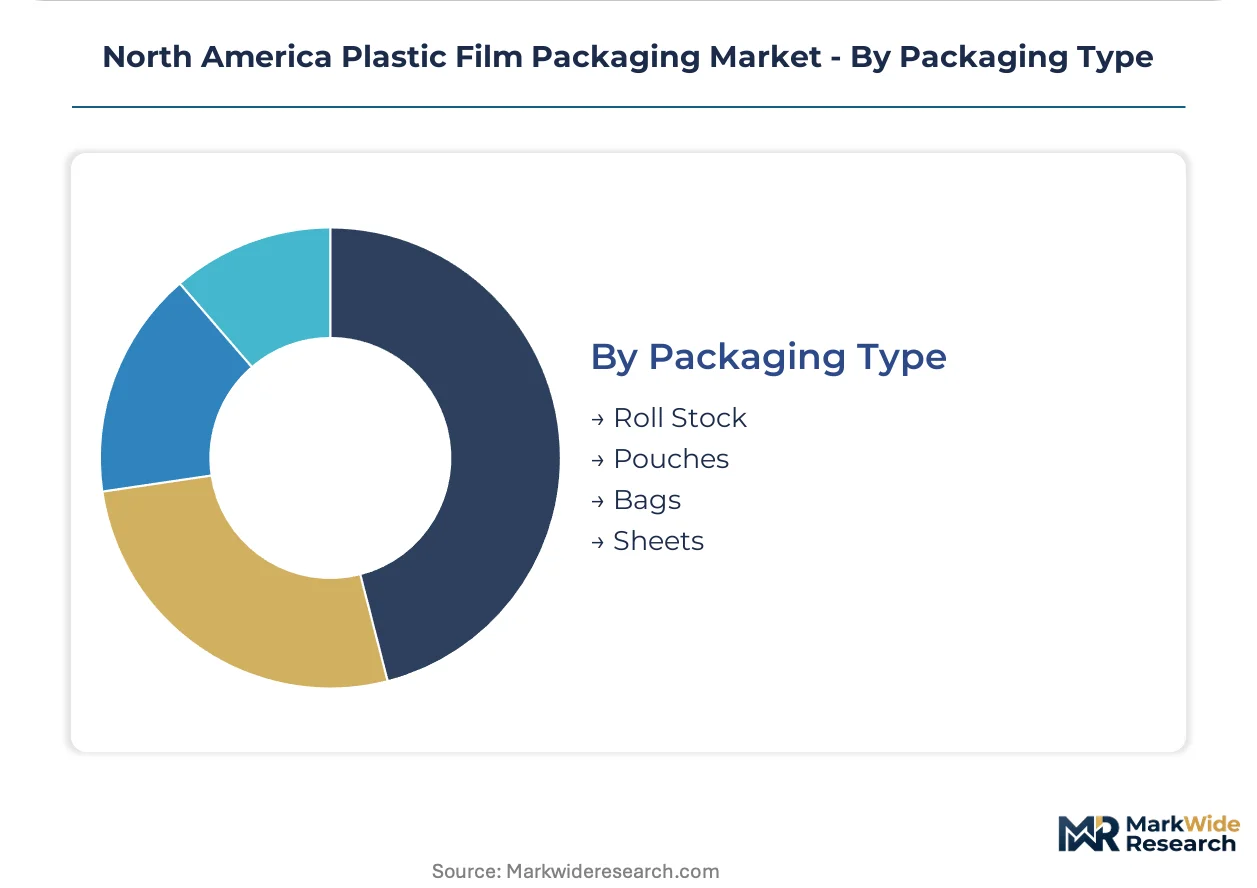
- Roll Stock:Unconverted film webs supplied to downstream form-fill-seal operations. US Midwest contract packagers favor 48-inch wide polyethylene roll stock for high-speed vertical bagging lines.
- Pouches:Pre-formed stand-up and flat pouches with fitment integration target premium single-serve and refill applications. California beverage startups are qualifying domestic pouch converters to reduce trans-Pacific lead times.
- Bags:Side-seal and bottom-gusseted configurations serve industrial and retail merchandise containment. T-shirt bags face substitution pressure from paper and reusable tote mandates in municipal jurisdictions.
- Sheets:Cut-to-size film layers for pallet interleaving and surface protection in manufacturing operations.
Roll stock leads volumes today; pouches are expanding most quickly on convenience format conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer engineering talent clusters along the Gulf Coast ethane corridor anchor North American film packaging capacity. Regional demand splits between protein processing centers in the Southeast and sustainability-mandated procurement in California.
United States
Food and beverage processors in Georgia and Alabama are expanding high-barrier film specifications for extended shelf-life poultry distribution. The EPA's advancing recycled content mandates are forcing Gulf Coast resin producers to requalify mechanical recycling streams for FDA food contact compliance. Houston and Corpus Christi polymer production facilities are integrating post-consumer resin extraction infrastructure to serve regional converters.
Canada
Ontario-based prepared meal manufacturers are qualifying domestic barrier film suppliers to reduce cross-border logistics exposure. Health Canada's PMRA and food contact notification frameworks are tightening extraction testing protocols for recycled content in protein packaging. Toronto-area converters are consolidating supplier relationships around compounders with pre-submitted regulatory documentation.
Mexico
Nearshoring programs by US brand owners are accelerating qualification of Mexican conversion facilities for shrink and stretch film production. The country's federal consumer protection agency is aligning with California SB 54 extended producer responsibility timelines for imported packaging. Nuevo León and Jalisco industrial corridors are attracting capital for coextrusion line installations serving Texas and California distribution networks.
California
SB 54 implementation is compressing procurement timelines for post-consumer recycled content verification in food-contact films. The Department of Resources Recycling and Recovery is enforcing fee structures that scale with virgin resin intensity. Los Angeles and Central Valley produce distribution hubs are standardizing on high-performance pallet wraps with certified recycled content thresholds.
US Southeast
Poultry and ready-to-eat protein processors are consolidating film supplier relationships around Gulf Coast resin access points. Georgia and North Carolina vocational programs are scaling coextrusion technician training to address seven-layer barrier film operator shortages. Charleston and Savannah port facilities are expanding cold chain infrastructure linking film converters to Latin American protein export markets.
North America Plastic Film Packaging Market Competitive Landscape
Capital-heavy integrated resin producers compete with asset-light specialty converters for margin pools in barrier film segments. Market structure tilts toward consolidation at the resin compounding tier and fragmentation among regional conversion specialists. Three archetypes dominate: Gulf Coast-anchored integrated producers, multilayer coextrusion specialists, and active packaging technology integrators. Dominant competitive moves include mechanical recycling infrastructure partnerships and FDA food contact notification pre-submission races.
Among integrated packaging conglomerates, Amcor plc and Berry Global Group exemplify scale-driven positions spanning commodity and premium film tiers. Sealed Air Corporation occupies the functional technology vector with embedded active and intelligent packaging architectures. These three anchors represent distinct strategic postures: captive resin supply, geographic density in conversion assets, and differentiated barrier functionality.
| Leading Market Players |
|---|
| Amcor |
| Berry Global Group |
| Sealed Air Corporation |
| Profol Americas Inc. |
| TEKRA LLC |
| Cosmo Films Inc. |
| Taghleef Industries Inc. |
| Winpak Ltd |
| Transcontinental Inc. |
| Others |
Pricing and Supply Chain Analysis
Barrier-to-commodity film divergence splits North American plastic film packaging into parallel pricing architectures with distinct supply chain footprints. Premium multilayer coextrusion commands certification-linked premiums while commodity monolayer wraps compete on Gulf Coast resin proximity and volume throughput.
Pricing Analysis
Bundled technical service contracts separate FDA-compliant barrier film suppliers from unbundled commodity resin traders. Three-tier pricing structure across premium, standard, and economy levels reflects coextrusion complexity, with seven-layer barrier films carrying food-contact notification premiums and stretch films competing on ethane-indexed spot benchmarks. Cost compression in commodity polyethylene tiers intensifies because Gulf Coast resin oversupply pressures converter margins. Brand owner procurement teams exhibit highest price sensitivity in pallet wrap and T-shirt bag segments, while pharmaceutical and premium protein packers prioritize seal integrity over unit cost.
Supply Chain Analysis
Warehouse-distribution layer consolidation concentrates film inventory at regional distribution centers across Texas, Georgia, and California to serve just-in-time converter operations. Raw material flows draw from Louisiana and Texas ethane crackers, Alberta petrochemical complexes, and Mexican resin import terminals. Single-source vulnerability sits with Gulf Coast hurricane exposure disrupting linear low-density polyethylene supply to Southeast poultry processors. Distribution runs through hub-and-spoke networks anchored by Houston polymer terminals and Chicago rail interchanges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American plastic film packaging represents a late-cycle quality story as protein processors and pharmaceutical packagers upgrade specifications toward extended shelf-life and sterile barrier performance. This demand shift favors converters with coextrusion mastery and regulatory pre-certification.
For Market Incumbents: To counter mid-tier mechanical recycling entrants, Amcor and Berry Global should deepen captive resin supply through Gulf Coast extraction infrastructure partnerships while accelerating FDA food contact notification pre-submissions for post-consumer content streams. Seven-layer barrier film operator training programs at Georgia and North Carolina technical colleges address capability scarcity before wage inflation erodes margin control. For New Entrants and Emerging Players: California SB 54 opens a window for chemical recycling specialists to qualify pyrolysis-derived resins for food-contact film without mechanical contamination constraints. Mexico nearshoring corridors in Nuevo León offer the most penetrable geography for stretch and shrink film qualification serving Texas distribution networks. Go-to-market positioning should emphasize SB 54 compliance verification services rather than commodity price competition. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap coextrusion specialists possessing FDA pre-submitted barrier film portfolios and underutilized seven-layer line capacity. Five-to-ten year viability hinges on successful navigation of recycled content mandates without sacrificing food safety certification. The inflection signal to watch is California Department of Resources Recycling and Recovery enforcement action accelerating virgin resin fee structures beyond current compliance cost assumptions.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Recycling Integration | EPA mandates and California SB 54 fees force Gulf Coast resin producers to qualify post-consumer streams for FDA food contact. |
| Seven-Layer Coextrusion Capacity Expansion | Georgia and Alabama protein processors demand barrier films with oxygen transmission rates below 1 cc/m²/day. |
| Chemical Recycling Partnership | Pyrolysis of mixed polyolefin waste enables food-grade resin output without mechanical purity constraints. |
| Active Packaging Technology Embedding | Oxygen scavenging and time-temperature indicators command premium positioning in pharmaceutical cold chains. |
| Mexico Nearshoring Qualification | US brand owners reduce trans-Pacific exposure by certifying Nuevo León converters for shrink film production. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each market gathered through structured interviews with resin procurement directors, coextrusion plant managers, FDA regulatory affairs specialists, and protein processor packaging engineers. Secondary validation draws from EPA enforcement databases, California Department of Resources Recycling and Recovery fee schedules, FDA food contact notification filings, and American Chemistry Council resin production statistics. Bottom-up volume modeling triangulates against top-down value estimates derived from trade flow analysis.
Granularity-level modeling operates at the intersection of film type, material formulation, end-use industry, and state-level regulatory cluster. Segment-specific CAGRs derive from ethane feedstock cost trajectories, recycled content mandate phase-in schedules, and protein processing capacity expansion pipelines across the analysis window. Industry-specific forecast inputs include coextrusion line installation rates at US Southeast vocational training centers and California SB 54 compliance cost pass-through elasticities.
Revisions become necessary when EPA recycled content thresholds accelerate beyond current mechanical recycling capacity buildout timelines or when Gulf Coast hurricane disruption exceeds historical frequency assumptions. Forecasts reflect documented assumptions around resin price pass-through coefficients and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Australia and New Zealand Plastic Packaging Film Market
Poly film
Waste Wrap Film Market
Poly film
Recyclable Lidding Films Market
Poly film
Global PVDC Coated Films Market
Poly film
Polymer Dispersed Liquid Crystal (PDLC) Film Market
Poly film
MDO-PE Films Market
Poly film
Polymer Waterproof Rolls Market
Poly film
Thermoforming Films Market
Poly film
Asia-Pacific Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market
Poly film
India Plastic Packaging Film Market
Poly film
Polyethylene Terephthalate (PET) Shrink Films Market
Poly film
Wrap Around Label Films Market
Poly film
PCR Bubble Films Market
Poly film
China Plastic Packaging Film Market
Poly film
United Kingdom Plastic Packaging Films Market
Poly film
Craft Plastic Films Market