
 US Cleanroom Film and Bags Market | 2026-2036
US Cleanroom Film and Bags Market Size, Share, and Industry Trends Forecast 2026-2036
US Cleanroom Film and Bags Market Insights
Consolidation among contract drug manufacturers is repositioning procurement leverage toward fewer, larger buyers with stringent contamination specifications. Tekni-Plex, Inc. leverages multi-layer extrusion capabilities to serve these consolidated pharmaceutical accounts with customized barrier solutions. Nelipak Corporation anchors its position through dedicated cleanroom manufacturing sites that compete on validated sterile supply chains rather than commodity pricing.
US cleanroom film and bags are engineered polymer enclosures manufactured under ISO 14644-1 Class 5-8 conditions, typically extruded from low-density polyethylene or laminated coextrusions with controlled particulate and ionic contamination below specified thresholds, designed to protect sensitive components from airborne particles, electrostatic discharge, and moisture ingress during transport and storage. Polyethylene bags dominate current volume owing to their cost position in standard pharmaceutical applications, while barrier film commands disproportionate margin pools in cell therapy and gene therapy logistics where oxygen and moisture ingress must be held to parts-per-million levels. Static-control film is gaining fastest in the electronics end user segment as domestic semiconductor fabrication expands, though laminated film retains structural importance in multi-dose biologics packaging where puncture resistance and seal integrity must coexist.
FDA Current Good Manufacturing Practice regulations and ISO 14644 cleanroom standards shape material selection, validation documentation, and supplier qualification requirements across all end user segments. The EPA's evolving guidance on per- and polyfluoroalkyl substances is forcing converters to reformulate certain high-performance barrier films, creating compliance-driven demand for next-generation cleanroom materials. Stakeholders must monitor how state-level clean energy manufacturing incentives reshape the geographic distribution of electronics and biotechnology facilities, as these location decisions directly determine regional cleanroom packaging procurement patterns and logistics requirements.
Market Dynamics
Semiconductor fabs in Arizona and Texas are expanding procurement of ultra-clean packaging to meet stricter contamination protocols, creating a demand pull that restructures supplier relationships across the value chain. This geographic concentration of advanced manufacturing is the dominant force reshaping competitive positioning in US cleanroom film and bags.
Growth Catalysts
- Domestic Semiconductor Expansion:CHIPS Act incentives are accelerating fab construction in Phoenix and Austin, generating concentrated demand for ISO Class 5-7 packaging materials with electrostatic discharge control.
- FDA Sterile Manufacturing Guidance:Evolving Current Good Manufacturing Practice regulations for parenteral drugs are pushing pharmaceutical converters toward higher-grade barrier materials with validated sterile supply chains.
- Cell Therapy Logistics:Cryogenic storage requirements for autologous cell therapies are creating specialized demand for multi-layer coextrusions that maintain seal integrity at ultra-low temperatures.
Market Restraints
- Fluoropolymer Reformulation Costs:EPA guidance on per- and polyfluoroalkyl substances is forcing converters to redesign high-performance barrier films, raising R&D expenditure without immediate price recovery mechanisms.
- Resin Supply Concentration:Specialty low-density polyethylene grades for cleanroom applications source from a limited Gulf Coast petrochemical base, exposing converters to hurricane-related disruption risk.
- Validation Timeline Compression:Pharmaceutical customers demand six-month supplier qualification cycles that strain smaller converters lacking dedicated quality infrastructure.
Strategic Opportunities
- Massachusetts Biotechnology Corridor:Underpenetrated demand from gene therapy startups in Cambridge and Worcester offers first-mover advantage for converters with flexible small-batch capabilities.
- North Carolina Research Triangle:Contract manufacturing organization consolidation in Raleigh-Durham is creating procurement leverage for suppliers offering validated sterile supply chains with dedicated cleanroom sites.
- Multi-Dose Biologics Packaging:Puncture-resistant laminated films for combination products represent an emerging application where seal integrity and barrier performance command premium positioning.
Industry Challenges
- Cleanroom Technician Scarcity:ISO 14644-1 certified operators are concentrated in legacy pharmaceutical regions, constraining expansion into emerging semiconductor clusters.
- Legacy Equipment Retrofit Burden:Converters with 1990s-vintage extrusion lines face capital-intensive upgrades to meet particulate contamination thresholds for Class 5 applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Cleanroom Film and Bags Market |
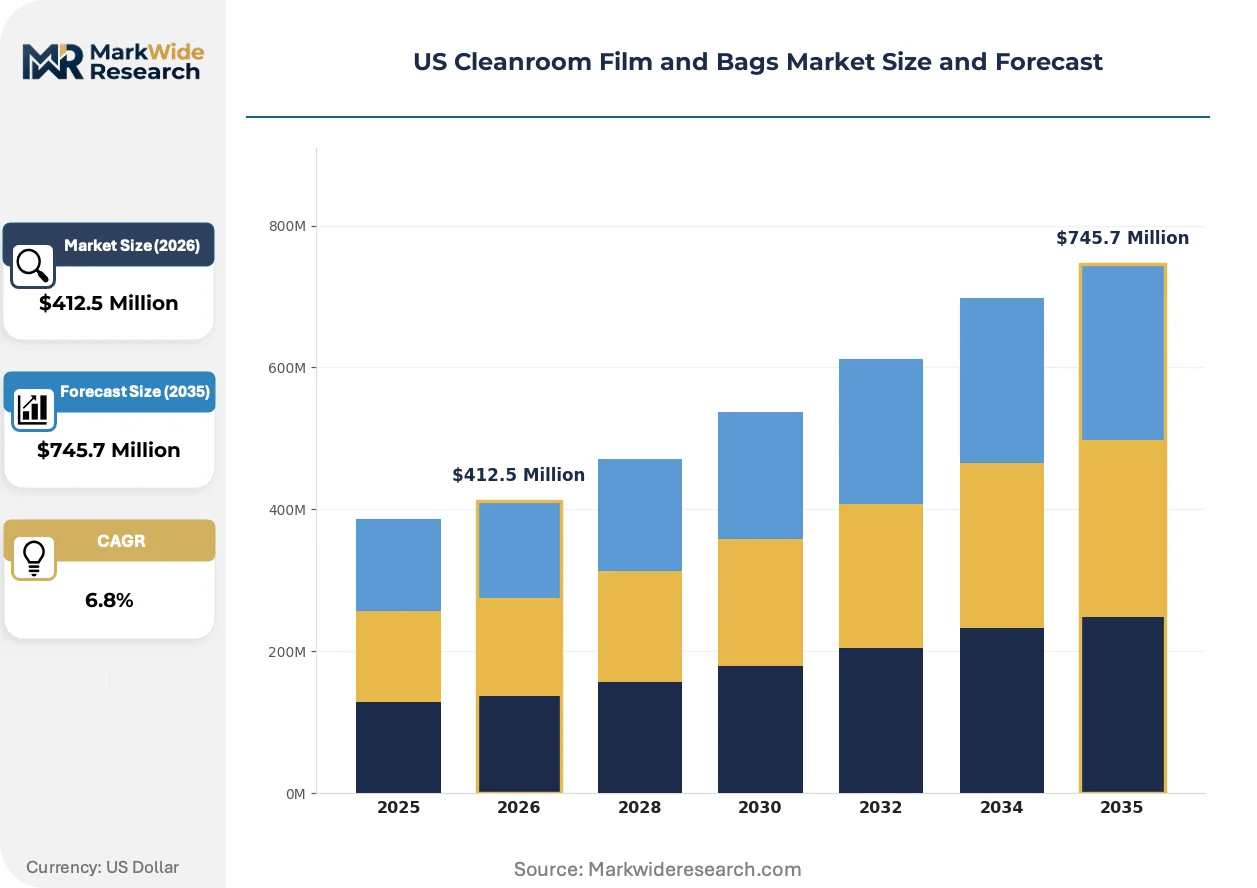
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Bags, Barrier Film, Laminated Film, Static-Control Film End User: Pharmaceuticals, Biotechnology, Electronics, Healthcare Thickness: Thin, Medium, Thick, Ultra-Thin Distribution Channel: Online Retailers, Distributors, Direct Sales, Specialty Stores |
| Companies Covered | CFB Cleanroom Film and Bags (C-P Flexible Packaging), Tekni-Plex, Inc., AeroPackaging, Inc., Fruth Custom Packaging, Pristine Clean Bags, Nelipak Corporation, PPC Flexible Packaging LLC, Degage Corp., Plitek, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Cleanroom Film and Bags Market Trends and Innovations
Material science advances and regulatory recalibration are converging to redefine performance benchmarks across pharmaceutical and electronics end uses. Three developments are restructuring how cleanroom packaging is specified, validated, and procured.
Multi-layer coextrusion technology is converging with static-control additives to produce films that simultaneously manage particulate contamination, electrostatic discharge, and moisture ingress. Semiconductor fabs in Arizona are adopting these hybrid materials at accelerated pace to protect advanced node wafers during inter-facility transport. The structural consequence is compression of single-function film categories as buyers consolidate specifications around performance-integrated solutions.
EPA per- and polyfluoroalkyl substances guidance is forcing reformulation of fluoropolymer barrier layers that historically provided oxygen and moisture protection for cell therapies. Converters are responding with silicone oxide and aluminum oxide vapor-deposited alternatives that meet barrier requirements while satisfying emerging chemical restrictions. Pharmaceutical logistics providers in the biotechnology corridor spanning Massachusetts and North Carolina are most affected, as they must revalidate entire cold chain packaging systems.
Buyer concentration among consolidated contract drug manufacturers is compressing supplier qualification timelines and shifting specification authority toward procurement functions with Six Sigma cost targets. Direct distribution relationships are displacing distributor intermediaries for high-volume accounts with validated sterile supply chain requirements. This pattern is most visible in the Research Triangle, where three contract manufacturers now control majority procurement volume for regional biologics packaging.
US Cleanroom Film and Bags Market Segmentation
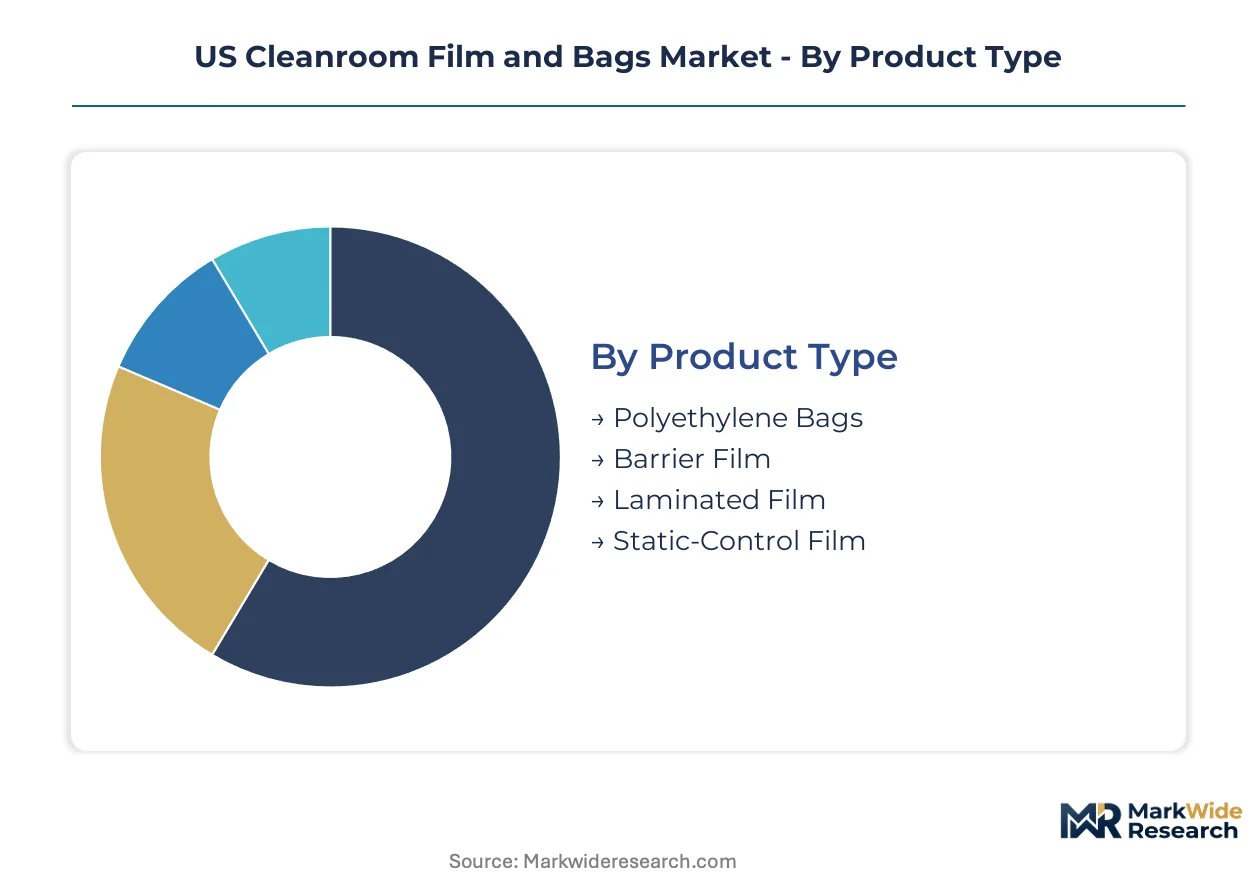
Cleanroom film and bags segmentation reflects divergent technical requirements across pharmaceutical sterility protocols and semiconductor contamination thresholds. Material specifications, thickness tolerances, and distribution pathways vary sharply by end-use validation standards.
Product Type:
Polyethylene bags dominate shipment volume through cost positioning in standard pharmaceutical applications, while barrier film commands disproportionate margin pools in advanced therapeutic logistics.
- Polyethylene Bags:Extruded from low-density polyethylene under ISO 14644-1 Class 5-8 conditions with controlled particulate below specified thresholds. Demand concentrates in standard pharmaceutical packaging across the Massachusetts biotechnology corridor where cost-sensitive generic drug manufacturers prioritize procurement efficiency.
- Barrier Film:Multi-layer coextrusions or vapor-deposited structures holding oxygen and moisture ingress to parts-per-million levels. Cell therapy and gene therapy logistics in North Carolina's Research Triangle drive specification intensity as cryogenic storage requirements mandate seal integrity validation.
- Laminated Film:Puncture-resistant constructions for multi-dose biologics where structural integrity competes with barrier performance.
- Static-Control Film:Fastest-expanding category as Arizona and Texas semiconductor fabs adopt electrostatic discharge protection for advanced node wafer transport.
Mature deployment sits with polyethylene bags in legacy pharmaceutical operations. Newer deployment is concentrated in static-control film serving domestic semiconductor expansion.
End User:
Customer concentration patterns split between consolidated contract manufacturers with validated supply chain requirements and fragmented research institutions with flexible batch needs.
- Pharmaceuticals:Parenteral drug manufacturers under FDA Current Good Manufacturing Practice regulations specifying particulate contamination limits and supplier qualification documentation. Procurement leverage has shifted toward fewer, larger buyers following contract manufacturing organization consolidation in Raleigh-Durham.
- Electronics:Semiconductor fabs in Phoenix and Austin expanding ISO Class 5-7 packaging procurement to meet stricter contamination protocols for advanced node production. CHIPS Act incentives accelerate facility construction and associated cleanroom material demand.
- Biotechnology:Gene therapy startups in Cambridge and Worcester generating underpenetrated demand for flexible small-batch capabilities.
- Healthcare:Medical device sterilization and hospital supply chain applications with moderate barrier requirements.
Specification authority concentrates with pharmaceutical procurement functions. Electronics buyers are gaining fastest in absolute volume terms.
Thickness:
Thickness selection trades off material cost against puncture resistance and barrier performance across temperature extremes.
- Medium:Standard pharmaceutical applications balance cost and structural integrity for room-temperature storage and transport.
- Thick:Cryogenic storage for autologous cell therapies demands puncture resistance at ultra-low temperatures.
- Thin:Cost-minimized applications where barrier requirements are secondary to procurement efficiency.
- Ultra-Thin:Emerging specifications for weight-sensitive aerospace and satellite component packaging.
Volume deployment centers on medium thickness for standard pharmaceutical use. Thick specifications are climbing fastest in cell therapy cold chain logistics.
Distribution Channel:
Channel structure reflects the tension between validated sterile supply chain requirements and procurement cost optimization.
- Distributors:Traditional intermediaries serving fragmented research and smaller pharmaceutical accounts without dedicated quality infrastructure.
- Direct Sales:Displacing distributor relationships for high-volume contract manufacturers demanding validated sterile supply chains with dedicated cleanroom site verification.
- Online Retailers:Standard-grade polyethylene bags for healthcare and research applications with minimal validation requirements.
- Specialty Stores:Regional converters serving localized semiconductor and pharmaceutical clusters with customized specifications.
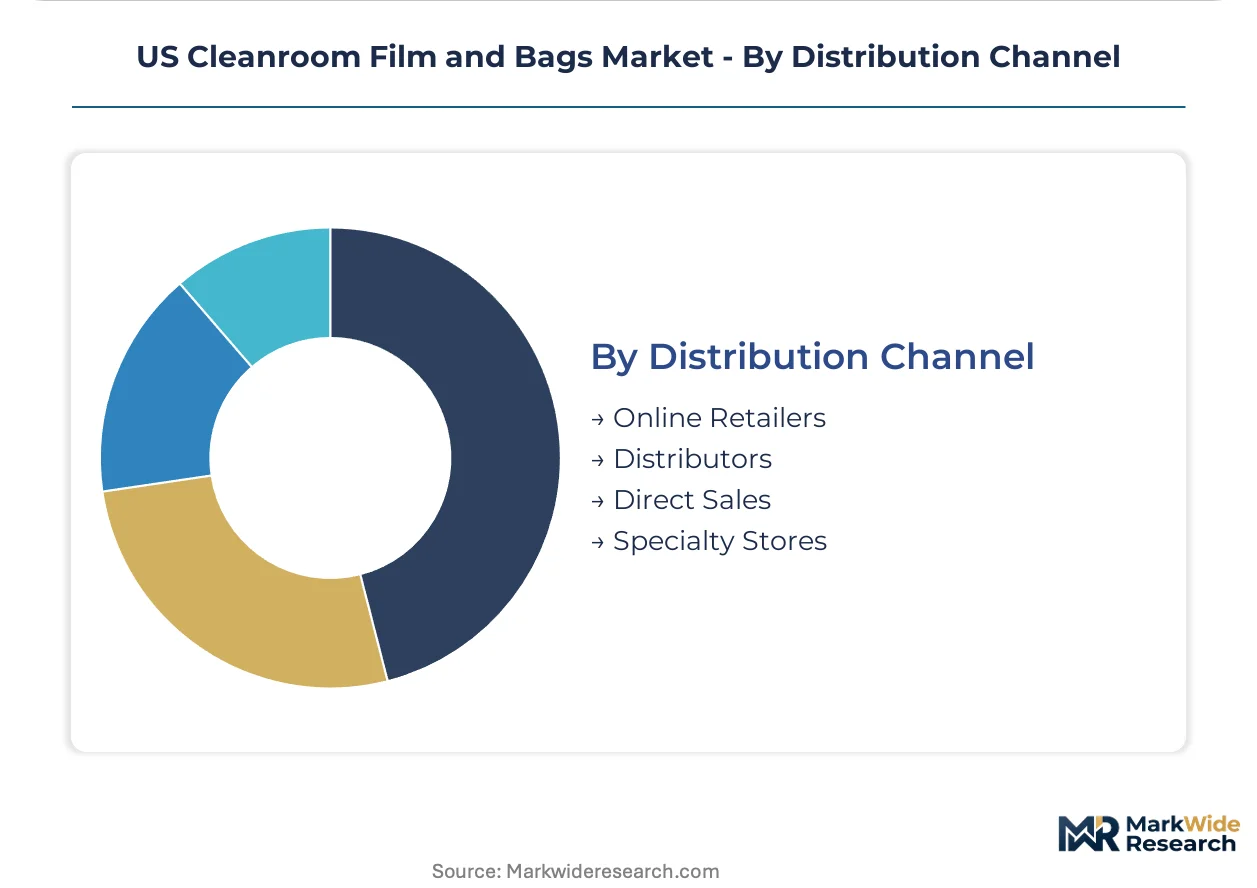
Direct sales relationships are expanding share with consolidated pharmaceutical buyers. Distributor intermediaries retain position in research and development procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic semiconductor fabrication and pharmaceutical manufacturing concentrate demand in distinct geographic clusters, each imposing specialized contamination protocols on packaging procurement. State-level clean energy incentives and biotechnology investment programs are redistributing facility location decisions across sub-regional markets.
Arizona
Phoenix-area fabs under CHIPS Act incentives are scaling ISO Class 5-7 packaging procurement for advanced node wafer protection. EPA regional offices coordinate per- and polyfluoroalkyl substances compliance timelines with semiconductor manufacturers. Electrostatic discharge control specifications from Phoenix fabs are migrating into supplier qualification standards nationwide.
Texas
Austin and Dallas semiconductor clusters are expanding cleanroom film demand alongside emerging battery manufacturing facilities. State manufacturing tax abatements accelerate facility construction timelines and compress supplier onboarding cycles. Houston's petrochemical base supplies specialty low-density polyethylene grades, though hurricane exposure creates resin availability risk.
Massachusetts
Cambridge and Worcester gene therapy startups generate fragmented demand for flexible small-batch barrier film capabilities. FDA's Boston district office enforces evolving Current Good Manufacturing Practice documentation requirements for sterile drug packaging. The Route 128 biotechnology corridor concentrates procurement specification authority among consolidated contract manufacturers.
North Carolina
Raleigh-Durham contract manufacturing organization consolidation is shifting procurement leverage toward fewer buyers with validated sterile supply chain requirements. State biotechnology center grants support facility expansion by pharmaceutical packaging converters. The Research Triangle's cleanroom technician labor pool constrains converter expansion timelines.
California
Bay Area cell therapy developers demand cryogenic-grade multi-layer coextrusions for autologous therapy logistics. California Air Resources Board regulations on manufacturing emissions intersect with EPA fluoropolymer guidance to accelerate barrier film reformulation. San Diego's medical device cluster maintains moderate-volume demand for standard-grade polyethylene bags.
US Cleanroom Film and Bags Market Competitive Landscape
Northeast and Midwest producers anchor one tier; Southwest specialists hold differentiated positions in semiconductor-facing applications. The vendor base organizes around three strategic archetypes: diversified packaging conglomerates with cleanroom divisions, dedicated cleanroom converters with validated sterile supply chains, and regional specialists serving single-state pharmaceutical clusters. Capacity expansion and portfolio diversification toward multi-layer coextrusion capabilities represent the dominant competitive moves as end-users consolidate specifications.
Within the dedicated cleanroom tier, Tekni-Plex, Inc. and Nelipak Corporation occupy positions shaped by multi-layer extrusion capabilities and dedicated manufacturing site validation respectively. AeroPackaging, Inc. represents the regional specialist archetype. These three entities exemplify how competitive positioning in US cleanroom film and bags depends on matching geographic facility presence to concentrated demand clusters rather than commodity scale.
| Leading Market Players |
|---|
| CFB Cleanroom Film and Bags (C-P Flexible Packaging) |
| Tekni-Plex, Inc. |
| AeroPackaging, Inc. |
| Fruth Custom Packaging |
| Pristine Clean Bags |
| Nelipak Corporation |
| PPC Flexible Packaging LLC |
| Degage Corp. |
| Plitek |
| Others |
Pricing and Supply Chain Analysis
Specialty low-density polyethylene resin costs cascade through three distinct pricing tiers as Gulf Coast petrochemical output feeds converter operations in Texas and Arizona, with hurricane-driven supply disruptions compressing margins at the standard-grade tier while premium barrier film commands recovery power through validated sterile supply chain documentation.
Pricing Analysis
Volume concentrates in polyethylene bags where procurement efficiency drives thin margins, while barrier film captures disproportionate returns in cell therapy logistics. Pricing stratifies across ISO Class 5-7 certification grades, with electrostatic discharge specifications from Phoenix fabs adding cost premiums to static-control variants. Cost compression in standard pharmaceutical tiers is intensifying because generic drug manufacturers consolidate purchasing volume. Contract drug manufacturers exhibit lowest price sensitivity due to validated supply chain requirements, whereas research institutions prioritize procurement flexibility over unit economics.
Supply Chain Analysis
Freight costs from Gulf Coast resin producers to Southwest semiconductor clusters are reshaping converter location decisions as Arizona fabs demand just-in-time delivery windows. Raw material supply draws from Texas petrochemical infrastructure, with specialty grades tethered to limited domestic production. Hurricane exposure along the Houston Ship Channel creates single-source vulnerability for cleanroom-grade polyethylene. Distribution runs through direct sales relationships with consolidated pharmaceutical buyers, displacing traditional distributor intermediaries for high-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into resin compounding and forward integration into sterile supply chain validation services is restructuring competitive economics as players race to capture margin pools across the value chain.
For Market Incumbents: Anticipate EPA fluoropolymer guidance acceleration by securing alternative barrier film formulations before pharmaceutical revalidation cycles lock in supplier relationships. Defend position by expanding dedicated cleanroom manufacturing sites in the Research Triangle to match contract manufacturing organization procurement leverage. Prioritize multi-layer coextrusion capacity additions that serve both semiconductor electrostatic discharge and biologics barrier requirements. For New Entrants and Emerging Players: Capture underpenetrated demand from Massachusetts gene therapy startups by building flexible small-batch capabilities with rapid qualification timelines. Target North Carolina contract manufacturing organization procurement consolidation by offering validated sterile supply chains with dedicated site verification. Enter through specialty static-control film for Arizona semiconductor fabs where incumbent capacity constraints create onboarding opportunities. For Investors and Strategic Acquirers: FDA sterile manufacturing guidance acceleration is the leading indicator that validated supply chain documentation capabilities will command acquisition premiums across the analysis window. Focus on mid-cap converters with ISO 14644-1 Class 5 certification and established pharmaceutical customer relationships. Monitor CHIPS Act fab construction permit approvals as the signal for regional cleanroom packaging demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Layer Coextrusion Capacity Expansion | Enables hybrid films serving both semiconductor ESD and pharmaceutical barrier requirements. |
| Fluoropolymer-Free Barrier Reformulation | Positions converters ahead of EPA enforcement timelines for cell therapy packaging. |
| Dedicated Cleanroom Site Validation | Meets contract drug manufacturer procurement requirements in Raleigh-Durham consolidation. |
| Direct Distribution Relationship Development | Displaces distributor intermediaries for high-volume pharmaceutical accounts with sterile supply chain needs. |
| ISO 14644-1 Class 5 Certification Investment | Unlocks advanced node semiconductor packaging procurement from Phoenix and Austin fabs. |
Research Methodology
Independent corroboration across converter operations managers, pharmaceutical procurement directors, and semiconductor fab supply chain leads underwrites the qualitative findings in this study. Primary fieldwork with cleanroom technicians, regulatory affairs specialists at FDA district offices, and resin procurement managers at Gulf Coast petrochemical facilities combined with secondary validation from EPA guidance documents, ISO 14644 certification records, and CHIPS Act facility announcement databases. Bottom-up shipment estimates from converter sites triangulate against top-down demand modeling from end-user procurement surveys.
Rate-of-change decomposition across product type, end user, thickness specification, and distribution channel dimensions structures the analytical framework over the projection horizon. CAGRs derive from segment-level growth rate blending weighted by base-year value shares. Forecast inputs incorporate semiconductor fab construction timelines under CHIPS Act incentives, FDA sterile manufacturing guidance implementation pace, and EPA per- and polyfluoroalkyl substances compliance deadlines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to hurricane-related resin supply disruptions, cleanroom technician labor availability constraints, and pharmaceutical customer consolidation pace. Forecasts reflect documented assumptions about regulatory implementation timelines and facility construction schedules. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Polyethylene Terephthalate (PET) Shrink Films Market
Poly film
MOPP Packaging Films Market
Poly film
North America Shrink and Stretch Film Market
Poly film
Polysaccharide Films Market
Poly film
Polyolefin Films Market
Poly film
Global EVOH Films for Packaging Market
Poly film
Global PVDC Coated Films Market
Poly film
Printed Plastic Films Market
Poly film
Thermoforming Films Market
Poly film
Polypropylene Film Market
Poly film
Global Reclosable Films Market
Poly film
Indonesia Plastic Packaging Films Market
Poly film
UAE Plastic Packaging Films Market
Poly film
Silicone-Coated PET Films Market
Poly film
Synthetic and Bio Thermoplastic Polyurethane (TPU) Films Market
Poly film
Europe Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market