
 3D Printed Packaging Market | 2026-2036
3D Printed Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printed Packaging Market Analysis
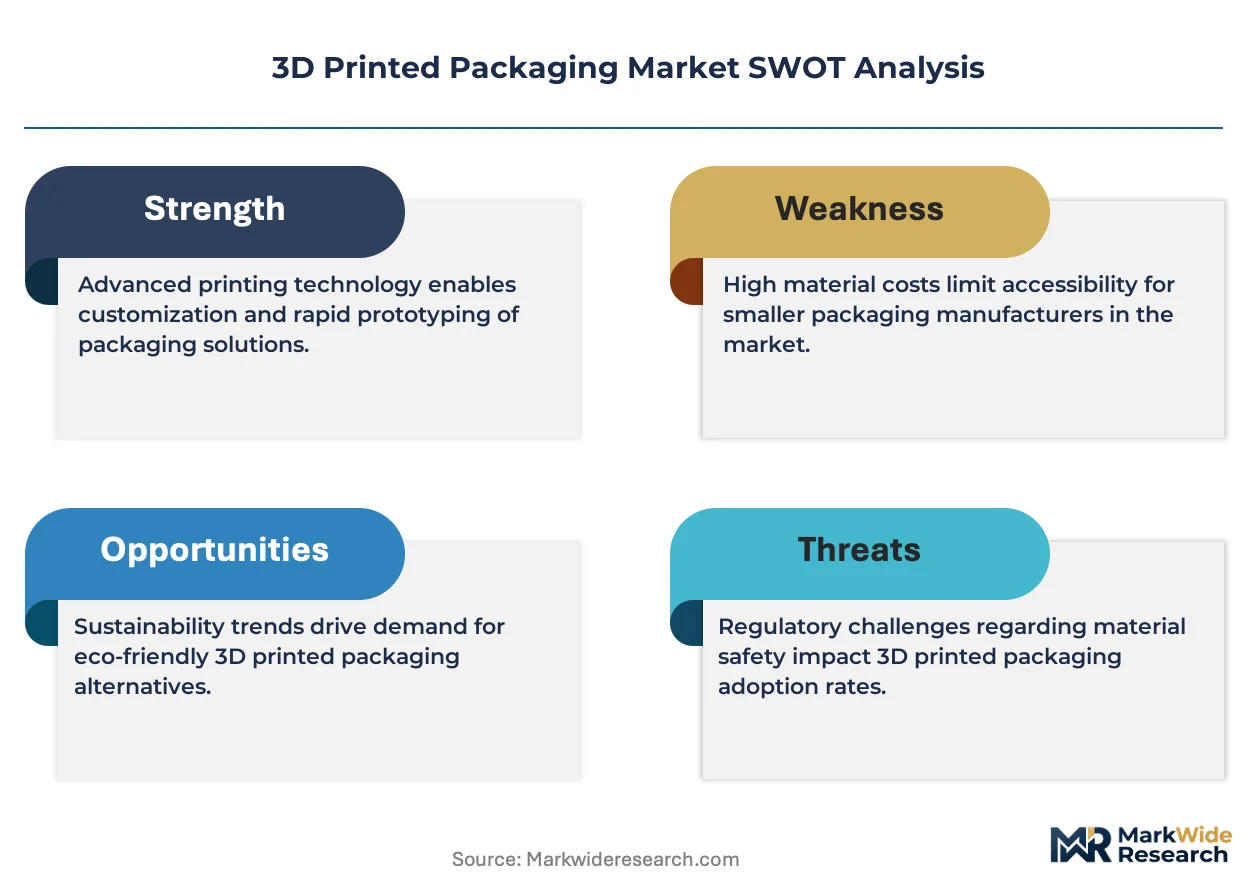
Subscription-based design software and cloud-managed print fleets is repositioning how packaging converters monetize their capabilities. HP Inc. leverages its Multi-Jet Fusion ecosystem to anchor industrial-scale production workflows for protective electronics enclosures. Stratasys sustains leadership in material-certified packaging through its validated polymer libraries for food-contact applications. EOS GmbH dominates metal-adjacent tooling segments where printed mold inserts enable short-run custom container production.
3D printed packaging encompasses additively manufactured protective and presentation structures formed through layer-by-layer deposition of thermoplastic or photopolymer materials, typically achieving wall thicknesses between 0.8 mm and 4 mm with internal lattice geometries that reduce material use by 30-60% compared to solid equivalents. Its primary commercial purpose centers on producing low-to-medium volume customized containers, inserts, and protective formats without hard tooling lead times. Fused Deposition Modeling leads in installed base and unit economics for standard corrugated replacements, while Multi-Jet Fusion captures margin pools in high-throughput electronics and pharmaceutical serialization where surface finish and dimensional tolerance command premium positioning. Selective Laser Sintering in nylon 12 occupies the durable industrial dunnage segment where repeated-use returnable packaging justifies higher per-unit production costs.
FDA food-contact substance notifications and EU REACH compliance on polymer additives shape which materials gain commercial traction in consumer-facing applications, with the EU Packaging and Packaging Waste Regulation directly mandating recyclability design standards that filter allowable resin selections. The US EPA industrial emissions framework and state-level extended producer responsibility bills in California and Maine add compliance layers for domestic manufacturing footprints. Stakeholders must monitor how regulatory convergence on recyclability certification interacts with material innovation cycles to determine which technology-platform bets warrant scaled capital commitment.
Market Dynamics
The EU Packaging and Packaging Waste Regulation mandates recyclability design standards that filter allowable resin selections, forcing converters to requalify material libraries and accelerating consolidation around certified polymer platforms.
Growth Catalysts
- Food-contact compliance pathways:FDA food-contact substance notifications create material validation frameworks that enable direct-to-consumer packaging applications. Brands leverage these certifications for premium positioning.
- Automotive supplier network density:Germany's industrial packaging clusters accelerate adoption of on-demand protective formats for just-in-sequence component delivery. Supplier co-location reduces logistics lead times.
- Cloud-managed print fleet economics:Subscription-based design software lowers capital barriers for mid-volume converters. Pay-per-use models align cost structures with intermittent demand patterns.
Market Restraints
- Photopolymer resin cost volatility:Acrylate and epoxy feedstock prices fluctuate with petrochemical cycles. Margins compress when oil benchmarks spike without corresponding price pass-through mechanisms.
- Build-plate throughput ceilings:Fused Deposition Modeling layer deposition rates cap hourly output regardless of part complexity. High-volume contracts require parallel machine arrays that multiply floor space requirements.
- REACH additive restrictions:EU ECHA substance candidate listings eliminate certain photoinitiators and stabilizers from food-contact applications. Reformulation cycles extend certification timelines by 12-18 months.
Strategic Opportunities
- Pharmaceutical serialization mandates:Track-and-trace regulations in multiple jurisdictions drive demand for individually marked primary containers. 3D printing integrates serialization at the point of manufacture.
- Lattice topology optimization convergence:Generative design algorithms paired with selective laser sintering enable mass-customized protective geometries. Electronics and medical device segments adopt these for drop-test performance.
- Extended producer responsibility expansion:California and Maine state-level EPR bills create compliance-driven replacement cycles for non-recyclable legacy formats. On-demand production aligns with localized recycling infrastructure.
Industry Challenges
- Post-processing labor intensity:Support removal, surface finishing, and dyeing operations require skilled technicians. Workforce availability constrains effective machine utilization rates.
- Multi-jet fusion powder management:Nylon 12 refresh ratios and particle size distribution control demand specialized material handling systems. Contamination events scrap entire build volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printed Packaging Market |
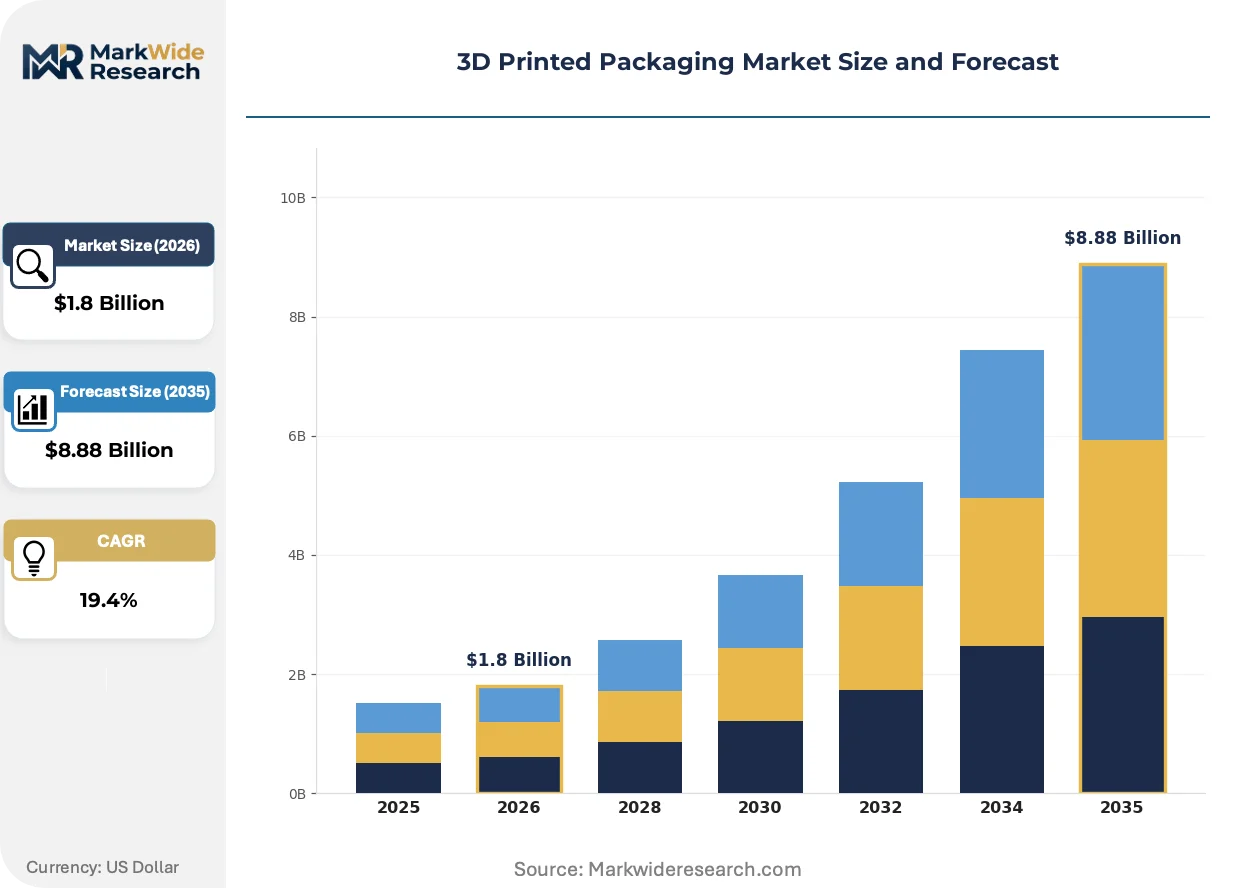
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Containers, Trays, Wraps Material: PLA, PETG, TPU, ABS End User: Food & Beverage, Electronics, Consumer Goods, Pharmaceuticals Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Multi-Jet Fusion |
| Companies Covered | HP Inc., Stratasys, 3D Systems, Materialise, EOS GmbH, Markforged, Carbon, Desktop Metal, Xometry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printed Packaging Market Emerging Trajectories
Material science advances and regulatory convergence are compressing development cycles for certified packaging formats. Digital manufacturing platforms now integrate compliance documentation directly into production workflows.
Multi-Jet Fusion technology deposits fusing and detailing agents across nylon powder beds to produce isotropic mechanical properties. Electronics manufacturers adopt these enclosures for thermal management and electromagnetic shielding. The platform is expanding into pharmaceutical cold-chain packaging where dimensional precision ensures insulation cavity fit.
EU REACH compliance on polymer additives restricts certain plasticizers and flame retardants from consumer-facing applications. Packaging converters reformulate photopolymer libraries to maintain food-contact approvals. German industrial clusters lead this transition due to proximity to ECHA technical guidance and testing infrastructure.
Brand procurement teams now specify design-for-recyclability scores in supplier scorecards. Converters without certified circular material pathways lose preferred vendor status. Food and beverage verticals in Nordic markets enforce these criteria most stringently due to national deposit-return system integration requirements.
3D Printed Packaging Market Segmentation
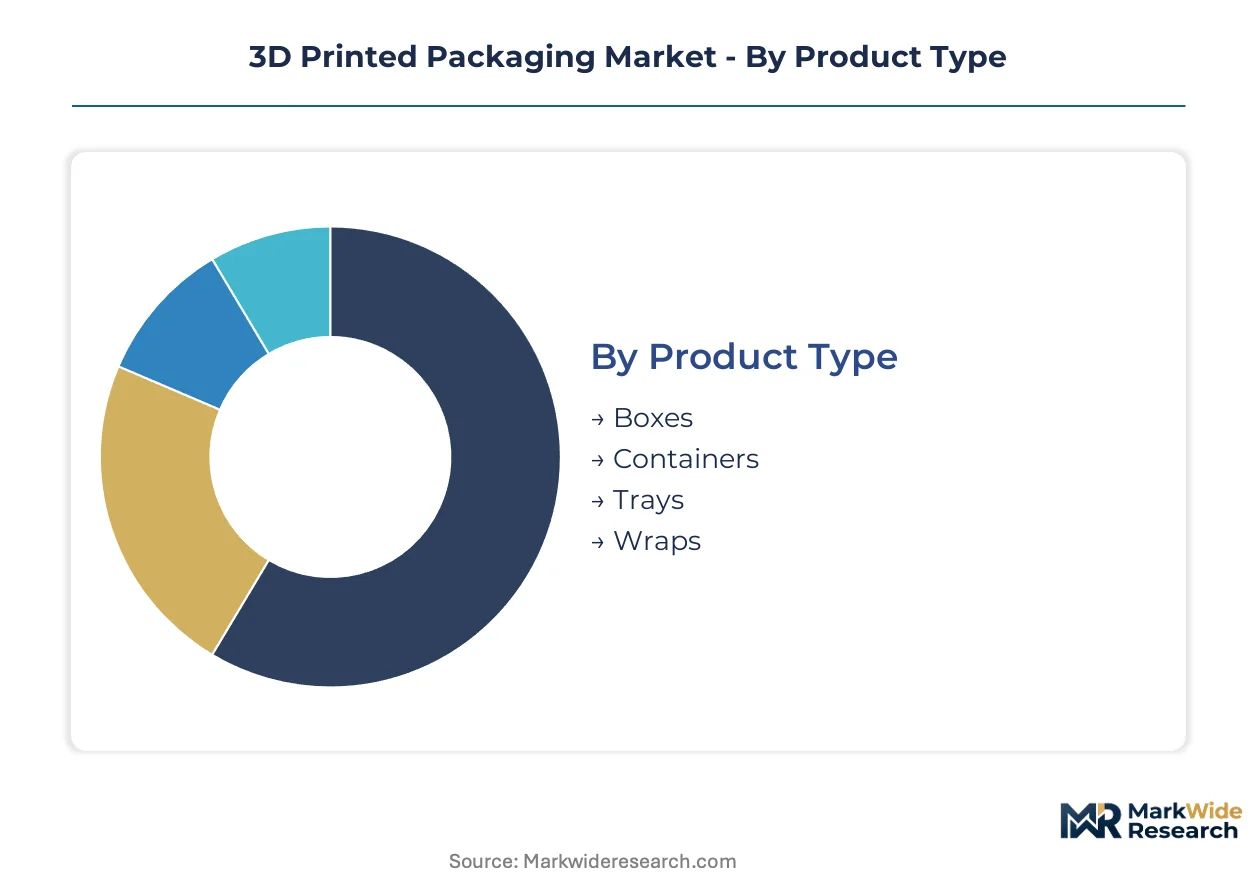
3D printed packaging segments slice across manufacturing depth, from standalone protective shells to embedded functional systems. Each dimension reveals where capital concentrates and where margin pools form.
Product Type:
Integration depth varies sharply—standalone containers dominate unit volumes while embedded trays and wraps penetrate highest-value electronics workflows.
- Boxes:Rigid cubic structures with 0.8-2 mm wall thicknesses and internal lattice reinforcement. Electronics manufacturers in Germany specify these for just-in-sequence component delivery where dimensional repeatability protects circuit boards during multimodal transit.
- Containers:Cylindrical or rectangular formats with threaded closures and sealing geometries. Food-contact certified variants concentrate in Nordic markets where deposit-return systems mandate design-for-recyclability compliance.
- Trays:Shallow formed structures with pocketed cavities for part nesting. Automotive suppliers adopt these for returnable dunnage programs.
- Wraps:Conformal protective skins with variable thickness deposition. Medical device sterilization workflows drive specification here.
Boxes lead volumes today; containers are gaining share fastest.
Material:
Cost tiering separates commodity biopolymers from engineered thermoplastics, with certification premiums widening price spreads.
- PLA:Polylactic acid derived from corn starch or sugarcane. Compostability certifications attract food-service disposables buyers in California and Maine where extended producer responsibility bills create compliance-driven replacement cycles.
- PETG:Glycol-modified polyethylene terephthalate with clarity and chemical resistance. Pharmaceutical serialization mandates drive demand for transparent primary containers with integrated track-and-trace markings.
- TPU:Thermoplastic polyurethane with Shore hardness ranging from 85A to 95A. Repeated-use industrial packaging favors this for abrasion resistance.
- ABS:Acrylonitrile butadiene styrene with higher heat deflection temperatures. Electronics thermal management applications specify this for enclosures near power components.
PETG commands the steepest expansion trajectory as pharmaceutical serialization spreads.
End User:
Application maturity determines whether 3D printing replaces conventional formats or captures net-new customized demand.
- Food & Beverage:Direct-contact packaging with FDA food-contact substance notifications or EU REACH compliance. Portion-controlled formats and shelf differentiation drive brand adoption.
- Electronics:Protective enclosures with electromagnetic shielding and thermal management features. HP Inc. anchors industrial-scale production workflows here through Multi-Jet Fusion ecosystems.
- Consumer Goods:Presentation packaging with mass-customized geometries. Subscription-based design software lowers capital barriers for mid-volume converters serving this segment.
- Pharmaceuticals:Primary containers with integrated serialization and cold-chain insulation cavities. Dimensional precision requirements favor Multi-Jet Fusion adoption.
Electronics leads volumes today; pharmaceuticals is climbing the fastest.
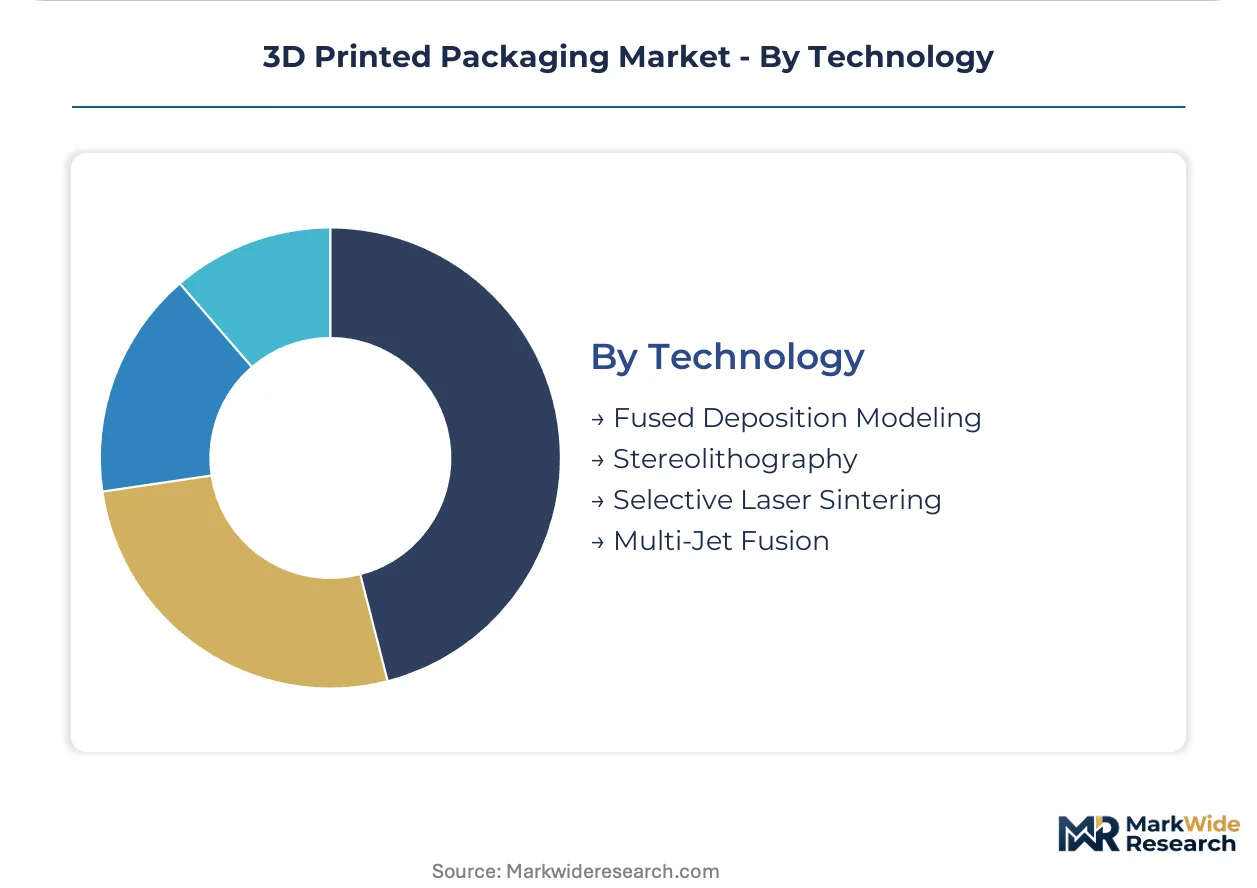
Technology:
Volume throughput and surface finish requirements segment equipment selection across end-use price points.
- Fused Deposition Modeling:Thermoplastic extrusion through heated nozzles depositing 0.1-0.4 mm layers. Standard corrugated replacements favor this for installed base scale and unit economics.
- Stereolithography:Photopolymer resin cured by UV laser or projector. Fine-featured presentation packaging specifies this where surface finish commands premium positioning.
- Selective Laser Sintering:CO2 laser fusion of nylon powder beds. Durable industrial dunnage with repeated-use returnable packaging justifies higher per-unit production costs here.
- Multi-Jet Fusion:Fusing and detailing agents deposited across powder beds for isotropic mechanical properties. High-throughput electronics and pharmaceutical serialization capture margin pools here.
Fused Deposition Modeling leads volumes today; Multi-Jet Fusion is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where 3D printed packaging production concentrates, with manufacturers migrating toward jurisdictions offering streamlined certification pathways and proximity to end-use demand clusters.
Germany
Automotive supplier networks and industrial packaging clusters drive adoption of on-demand protective formats for just-in-sequence component delivery. REACH compliance mandates from ECHA filter allowable resin selections, accelerating material requalification cycles. Bavaria's Munich-Stuttgart corridor hosts dense concentrations of HP Inc. Multi-Jet Fusion deployments serving electronics manufacturers.
United States
Pharmaceutical serialization requirements and FDA food-contact substance notifications create dual certification pathways for primary container applications. EPA industrial emissions frameworks and state-level EPR bills in California and Maine add compliance layers for domestic manufacturing footprints. Greater Boston's medical device corridor specializes in sterilization-grade tray formats with integrated track-and-trace markings.
China
Electronics manufacturing scale and domestic consumer brand growth generate demand for customized presentation packaging. NMPA medical device regulations and evolving GB standards on polymer additives shape material selection for healthcare applications. The Yangtze River Delta's Shanghai-Suzhou cluster concentrates Fused Deposition Modeling capacity for export-oriented protective formats.
India
Food-contact packaging for quick-service restaurant chains and pharmaceutical primary containers represent fastest-growing application vectors. FSSAI safety standards and CDSCO medical device rules create tiered compliance requirements across consumer-facing segments. Maharashtra's Mumbai-Pune industrial belt hosts emerging converter networks serving both domestic brands and contract manufacturing for export markets.
Japan
High-precision electronics enclosures and medical device sterilization workflows command premium positioning for dimensional tolerance-critical applications. METI industrial policy and PMDA pharmaceutical regulations enforce stringent material traceability requirements. The Kanto region's Tokyo-Yokohama corridor concentrates selective laser sintering capacity for repeated-use returnable dunnage programs serving automotive and semiconductor supply chains.
3D Printed Packaging Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with technology-platform owners capturing margin pools in high-throughput serialization while service bureaus dominate mid-volume customized demand. The vendor base organizes around equipment manufacturers, material suppliers, and digital manufacturing platforms rather than consolidated end-to-end integrators. Three archetypes predominate: powder-bed fusion specialists, material science innovators, and cloud-managed production networks. Capacity expansion through distributed print fleet deployment and strategic partnerships for regulatory certification represent the dominant competitive vectors.
Among technology-platform anchors, HP Inc. exemplifies the industrial-scale equipment archetype through its Multi-Jet Fusion ecosystem, while Stratasys occupies a position within material-certified packaging validated for food-contact applications. EOS GmbH represents the metal-adjacent tooling segment where printed mold inserts enable short-run custom container production. These three companies illustrate how competitive positioning concentrates around distinct technology-platform bets rather than overlapping segment coverage.
| Leading Market Players |
|---|
| HP Inc. |
| Stratasys |
| 3D Systems |
| Materialise |
| EOS GmbH |
| Markforged |
| Carbon |
| Desktop Metal |
| Xometry |
| Others |
Supply Flow & Price Mechanics
Multi-Jet Fusion adoption across pharmaceutical serialization workflows simultaneously compresses per-unit production economics and concentrates supply capability among equipment anchor tenants with certified material libraries. This technology-platform transition rewards converters with cloud-managed print fleet scale while marginalizing service bureaus lacking REACH-compliant polymer pathways.
Pricing Analysis
Distributor markups on photopolymer resins and certified polymer powders widen spreads between raw feedstock and finished container pricing. Three-tier pricing structure across premium certification, standard industrial, and economy prototyping tiers separates FDA food-contact validated formats from general protective applications. Cost compression in Fused Deposition Modeling filament tiers is intensifying because petrochemical volatility outpaces converter pass-through mechanisms. Mid-volume electronics manufacturers exhibit highest price sensitivity, while pharmaceutical serialization buyers prioritize dimensional tolerance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for just-in-sequence automotive component packaging, while digital manufacturing platforms aggregate fragmented mid-volume demand. Manufacturing concentrates in Germany, the United States, and China, with Bavaria's Munich-Stuttgart corridor anchoring Multi-Jet Fusion deployment density. Nylon 12 powder, photopolymer resins, and food-contact certified PLA feedstocks draw from petrochemical and agricultural processing streams. Single-source vulnerability in specialty photoinitiator supply chains amplifies REACH reformulation risk. Distribution runs through equipment manufacturer-certified partner networks and cloud-managed production platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory convergence on recyclability certification creates a stable compounder profile, with EU Packaging and Packaging Waste Regulation mandates driving replacement cycles that sustain converter revenue visibility.
For Market Incumbents: Extend material certification libraries ahead of ECHA substance candidate listings to capture pharmaceutical serialization margins. HP Inc. and Stratasys anchor positions through Multi-Jet Fusion ecosystem lock-in and validated food-contact polymer platforms respectively. Capacity addition in Germany's automotive supplier corridors defends share against emerging cloud-managed print fleet competitors. For New Entrants and Emerging Players: Quick-service restaurant chains in India seeking FSSAI-compliant food-contact packaging represent an underserved buyer archetype with limited incumbent penetration. California and Maine extended producer responsibility bills create compliance-driven replacement demand for compostable PLA formats. White-space capture favors subscription-based design software partnerships with mid-volume converters lacking capital for owned equipment. For Investors and Strategic Acquirers: Valuations sit cheapest among material science innovators with certified polymer libraries but limited print fleet deployment scale. Long-term viability over the mid-decade horizon rests on regulatory certification moats rather than equipment installed base. Acquisition targets with ECHA pre-registered substance dossiers and FDA food-contact substance notification pathways offer defensive positioning. Watch pharmaceutical serialization mandate expansion across ASEAN markets as inflection signal for premium technology-platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| Material Certification Investment | ECHA REACH pre-registration and FDA food-contact notifications defend premium tier positioning against reformulation delays. |
| Cloud-Managed Print Fleet Expansion | Subscription-based design software lowers capital barriers and aligns converter cost structures with intermittent pharmaceutical demand. |
| Automotive Supplier Corridor Proximity | Co-location with Germany's just-in-sequence component networks reduces logistics lead times for protective format delivery. |
| Lattice Topology Optimization Partnership | Generative design algorithm integration with Selective Laser Sintering enables mass-customized drop-test performance for electronics. |
| Extended Producer Responsibility Compliance | Deposit-return system integration in Nordic markets enforces design-for-recyclability scores that filter supplier scorecards. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down equipment deployment tracking forms the analytical core. Primary interviews with packaging converters, pharmaceutical procurement managers, automotive supplier logistics directors, and food-contact certification specialists combined with secondary validation from ECHA substance registrations, FDA food-contact substance notifications, EU Packaging and Packaging Waste Regulation implementation guidance, and trade customs data on polymer feedstock flows. Triangulation across stakeholder inputs and regulatory filings ensures segmentation integrity.
Input-output matrices map technology-platform adoption rates against material certification timelines and end-use demand clusters across the projection horizon. Segmentation dimensions include product type integration depth, material certification tier, end-use application maturity, and technology-platform throughput economics. CAGRs derive from equipment installed base growth curves, material qualification cycle durations, and regulatory mandate implementation schedules. Forecast inputs incorporate REACH substance candidate listing trajectories and pharmaceutical serialization mandate geographic expansion patterns.
Inputs from ECHA technical guidance documents and FDA pre-submission meeting records were available through the study window; gaps in emerging market regulatory implementation timelines introduce uncertainty bands around Asia-Pacific adoption curves. Forecasts reflect assumptions on certification cycle compression and material innovation convergence that periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Kraft Packaging Market
Packaging Materials
Thermal Lamination Films Market
Packaging Materials
Vacuum Thermoformed Packaging Market
Packaging Materials
Cast Polypropylene (CPP) Films Market
Packaging Materials
Mylar Market
Packaging Materials
Cement Packaging Market
Packaging Materials
Chemical Packaging Market
Packaging Materials
Cold Seal Films Market
Packaging Materials
Europe Consumer Packaging Market
Packaging Materials
New Packages and Materials for Power Devices Market
Packaging Materials
Non-Plastic Punnets Market
Packaging Materials
Thermoformed Tubs Market
Packaging Materials
Standard Liner Market
Packaging Materials
Postal Packaging Market
Packaging Materials
Cork Packaging Market
Packaging Materials
Thermal Insulation Packaging Market