
 North America BOPP Films Market | 2026-2036
North America BOPP Films Market Size, Share, and Industry Trends Forecast 2026-2036
North America BOPP Films Market Analytics
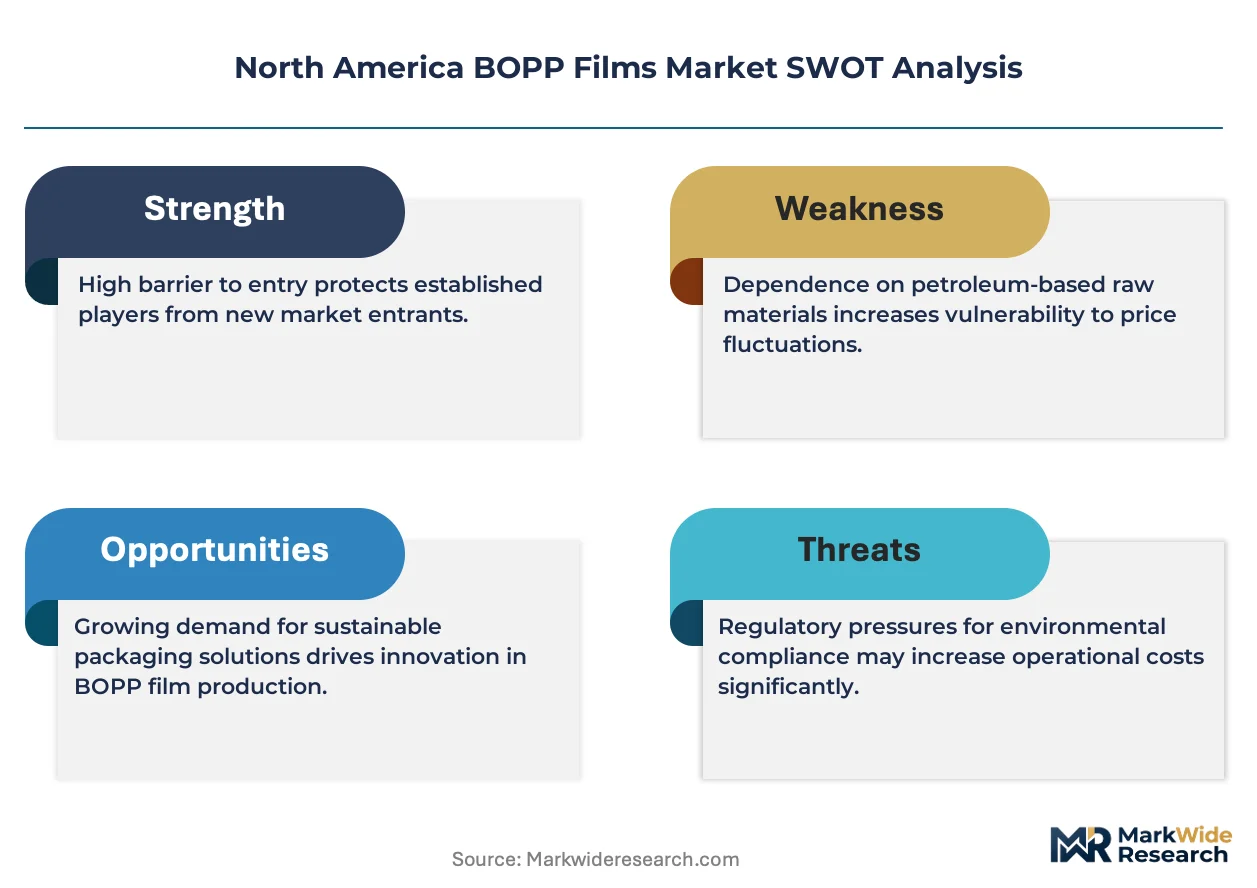
Aftermarket technical service and film specification consulting is tilting margin pools away from commodity roll sales toward value-added customer partnerships. Transcendia Inc. leverages its coating and converting capabilities to capture specification-driven accounts in medical and electronics packaging. Toray Plastics (America) Inc. anchors the premium barrier segment through its Massachusetts-based manufacturing campus with integrated metallization lines. Inteplast Group competes on vertical integration depth, controlling resin compounding through finished film slitting across its Texas and Pennsylvania operations.
Biaxially oriented polypropylene films are thermoplastic polymer sheets stretched in machine and transverse directions to achieve tensile strength, optical clarity, and moisture barrier performance; the tenter-frame stretching process typically yields films between 12 and 50 microns for flexible packaging and label substrates. Clear BOPP dominates volume throughput in snack and bakery packaging where printability and heat-seal latitude matter most. Metalized BOPP with barrier properties commands the fastest expansion as brand owners pursue extended shelf life without aluminum foil laminates. The thickness segmentation clusters around 20 and 30 micron specifications for labels and overwrap, with 40 and 50 micron grades retaining strength-critical applications in adhesive tapes and industrial bundling.
The U.S. FDA regulates food-contact BOPP under 21 CFR 177.1520 for olefin polymers, while Health Canada's PMRA and Consumer Product Safety provisions govern pesticide-resistant packaging and child-resistant flexible structures. The EPA's evolving extended producer responsibility frameworks in California and several Northeastern states are reshaping recyclability requirements for mono-material versus multi-layer film constructions. Stakeholders must monitor state-level packaging EPR legislation and FDA food-contact notification pathways to determine capital allocation between commodity extrusion and certified barrier film capacity.
Market Dynamics
Mono-material BOPP structures are displacing multi-layer laminates across North American food packaging as extended producer responsibility frameworks in California and Northeastern states mandate design-for-recycling compliance. This substrate transition concentrates margin capture among converters with certified barrier capabilities and integrated metallization assets.
Growth Catalysts
- EPR Legislation:California's SB 54 and pending Northeastern state packaging laws mandate recyclable mono-material structures, accelerating converter investment in certified BOPP barrier grades.
- Food Processing Cluster Proximity:Demand concentrates in the U.S. Midwest and Southeast manufacturing corridors where extrusion capacity overlaps with protein and snack processing facilities.
- FDA Notification Pathways:Updated food-contact substance notifications under 21 CFR 177.1520 pressure brands toward pre-certified barrier films with documented olefin polymer compliance.
Market Restraints
- Propylene Feedstock Volatility:Polymer-grade propylene supply tied to refinery and steam cracker economics creates margin compression for non-integrated film producers.
- Metallization Capacity Concentration:Premium barrier film supply depends on a limited number of integrated metallization lines, creating bottleneck risk for extended shelf-life applications.
- Aluminum Foil Substitution Ceiling:Ultra-high barrier applications in retort and pharmaceutical packaging retain technical requirements that metalized BOPP cannot fully satisfy.
Strategic Opportunities
- Canadian Market Underpenetration:Health Canada's PMRA pesticide-resistant packaging standards create specification-driven demand in agricultural chemical flexible packaging.
- Medical Device Packaging Convergence:Sterilization-compatible BOPP structures combined with Tyvek lamination capture share in Class II device sterile barrier systems.
- Electronics Anti-Static Grades:Semiconductor and lithium-ion battery packaging requirements for electrostatic discharge protection open specialty film specification windows.
Industry Challenges
- Barrier Certification Timelines:FDA food-contact notification pathways for novel coextrusion structures require 12-18 month validation cycles, delaying product commercialization.
- Recyclability Testing Infrastructure:APR (Association of Plastic Recyclers) design-for-recyclability certification demands capital-intensive pilot line access that mid-tier converters lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America BOPP Films Market |
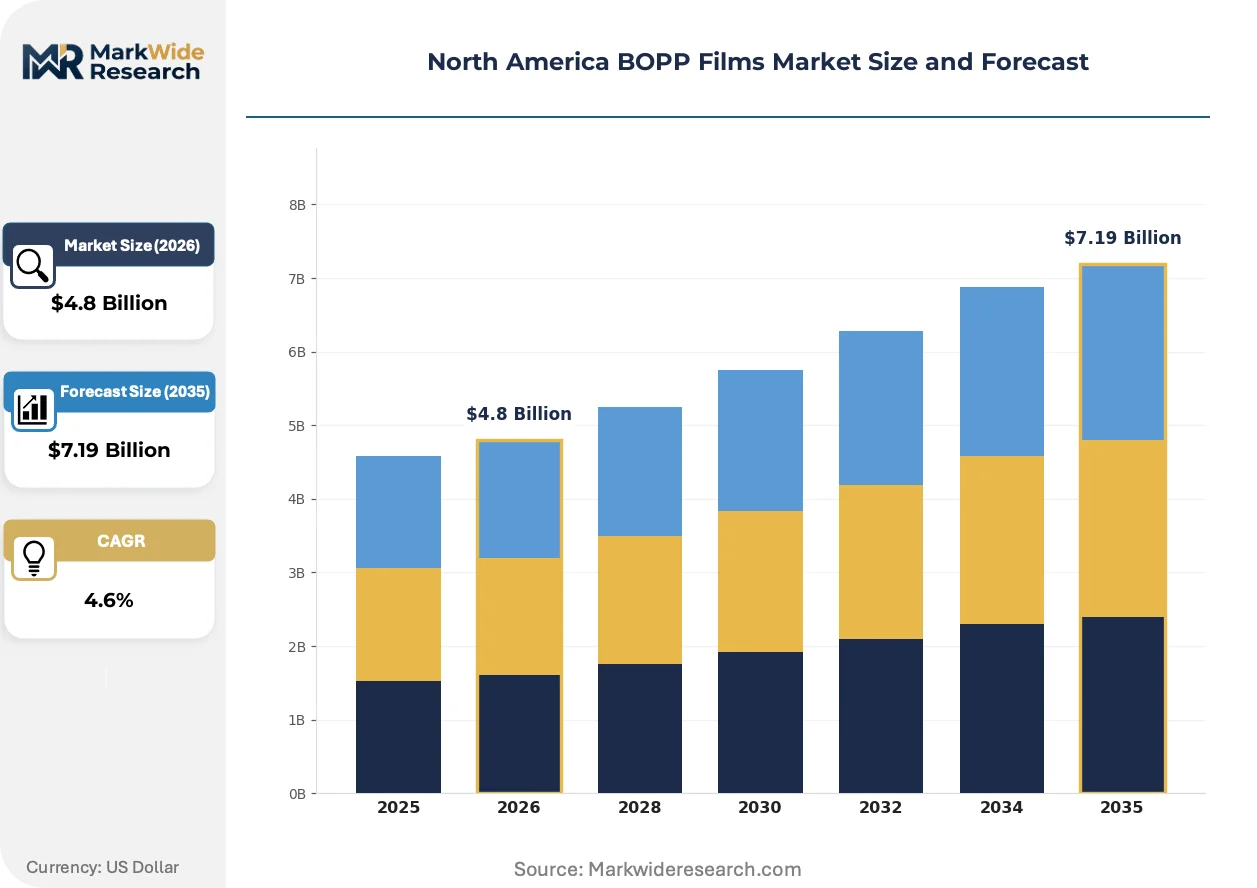
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear BOPP, Metalized BOPP, Pearlized BOPP, BOPP with Barrier Properties Application: Packaging, Labels, Adhesive Tapes, Stationery End User: Food & Beverage, Consumer Goods, Healthcare, Electronics Thickness: 20 Micron, 30 Micron, 40 Micron, 50 Micron |
| Companies Covered | Transcendia Inc., Flex Films Inc., Toray Plastics (America) Inc., Cosmo Films Ltd., Jindal Poly Films Ltd, Winpak Ltd., Taghleef Industries, Treofan Group, Inteplast Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America BOPP Films Market Evolving Landscape
Coextrusion and coating technologies are converging to produce mono-material barrier structures that satisfy both shelf-life requirements and emerging recyclability mandates. Equipment suppliers and resin formulators now coordinate development cycles around EPR compliance deadlines.
Water-based coating chemistry is migrating from niche applications to mainstream snack and bakery packaging as brand owners accelerate laminate-to-mono-material transitions. Major CPG procurement teams now specify pre-qualified water-based barrier coatings in RFP documents. This chemistry shift compresses demand for solvent-based adhesive laminations and associated volatile organic compound compliance costs.
The EPA's evolving extended producer responsibility frameworks in California, Oregon, and several Northeastern states are reshaping capital allocation between commodity extrusion and certified barrier capacity. Converters must document recyclability through APR-designated testing protocols to maintain preferred supplier status. Food and personal care brands in these jurisdictions now require design-for-recyclability certification as a gate for contract renewal.
Specification-driven procurement is consolidating supplier relationships around converters with integrated technical service capabilities. Brand technical teams now embed film specification consultants in packaging development workflows rather than sourcing commodity rolls through distributor channels. This behavior shift is most visible in medical device and premium food segments where barrier performance documentation carries liability implications.
North America BOPP Films Market Segmentation
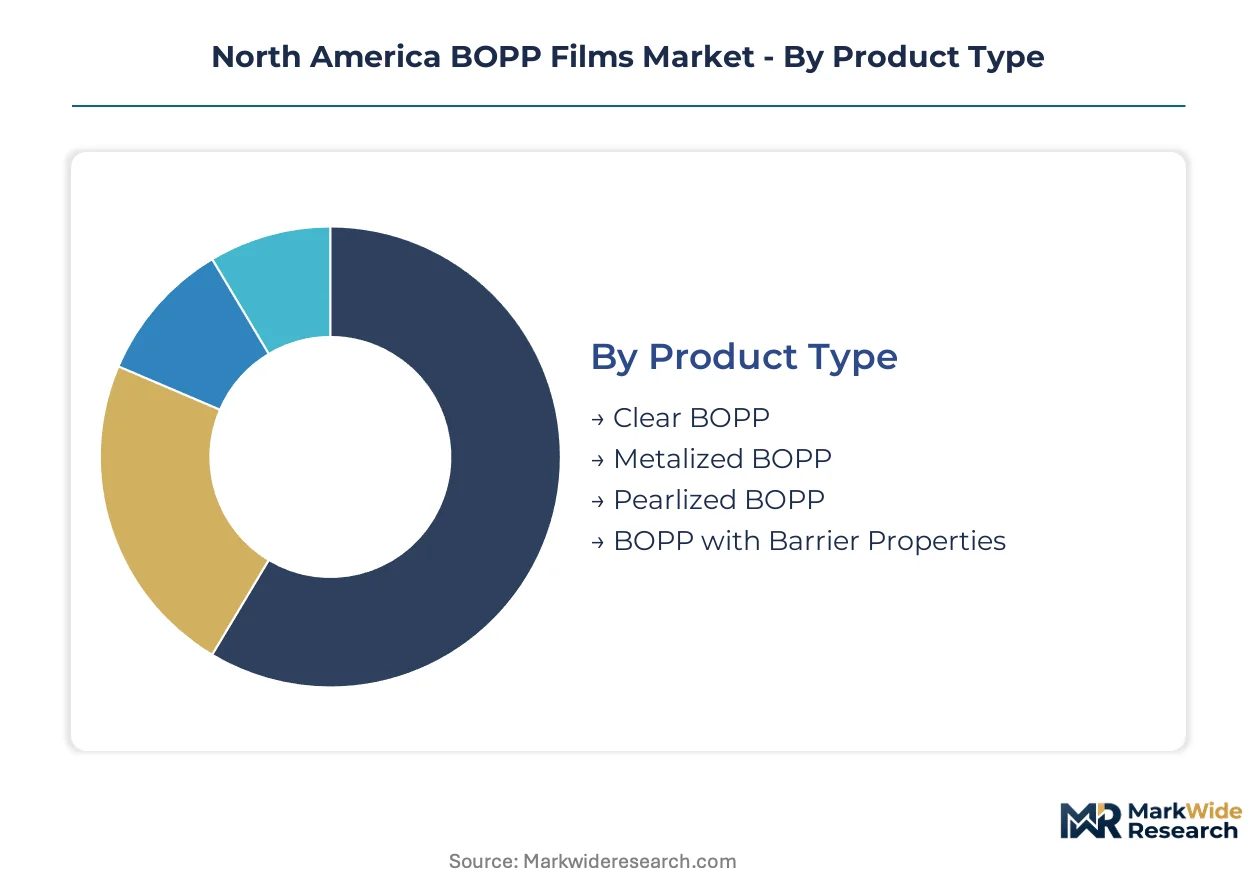
Segmentation in the North America BOPP Films Market reveals how specification requirements fragment across end-use liability tiers and processing constraints. Understanding these divides exposes where margin pools concentrate and where commoditization pressures operate most intensely.
Product Type:
Cost tier differentiation separates commodity clarity grades from engineered barrier specifications requiring metallization or coating investments.
- Clear BOPP:Unmodified polypropylene sheet delivers optical transparency and heat-seal performance for high-speed form-fill-seal operations. Snack and bakery packaging across the U.S. Midwest absorbs the majority of volume, with brand owners prioritizing print registration accuracy over barrier sophistication.
- Metalized BOPP:Vacuum-deposited aluminum layer creates oxygen and moisture barriers rivaling foil laminates at reduced caliper. Extended shelf-life specifications in premium snack and pet food segments drive specification growth, though California EPR mandates now require mono-material recyclability validation.
- Pearlized BOPP:Cavitated core layer produces white opaque appearance without titanium dioxide loading. Confectionery and personal care labels in the U.S. Southeast utilize this grade for premium aesthetic differentiation.
- BOPP with Barrier Properties:Coextruded or coated structures incorporating EVOH or PVDC layers achieve ultra-high barrier performance. FDA food-contact notification pathways under 21 CFR 177.1520 govern commercialization timelines for these grades.
Clear BOPP commands the established base. The steepest expansion runs through Metalized BOPP.
Application:
Application segmentation tracks how functional requirements diverge across converting processes and end-use performance standards.
- Packaging:Flexible formats including bags, pouches, and overwrap structures constitute the dominant demand channel. Protein processing clusters in Nebraska, Iowa, and Georgia source specification-certified grades for modified atmosphere applications.
- Labels:Pressure-sensitive and shrink-sleeve substrates require dimensional stability and ink adhesion across aqueous and UV curing systems. Beverage bottling facilities in Texas and Wisconsin drive regional demand concentration.
- Adhesive Tapes:High-tensile grades with corona-treated surfaces serve carton sealing and industrial bundling. Tape manufacturers in Ohio and Pennsylvania specify 40-50 micron calipers for strength-critical applications.
- Stationery:Low-gloss, writable surfaces for book covering and document lamination represent a mature, price-sensitive segment. School supply distributors in the U.S. Northeast maintain seasonal procurement patterns.
Packaging absorbs the dominant volume share. Labels are climbing the fastest as beverage SKU proliferation accelerates substrate consumption.
End User:
Customer type segmentation exposes how liability exposure and certification requirements stratify procurement behavior across industries.
- Food & Beverage:The largest consumption segment spanning snack, bakery, frozen, and processed meat categories. FDA compliance documentation and APR recyclability certification now gate contract awards with major CPG procurement teams.
- Consumer Goods:Personal care, household products, and apparel packaging applications prioritize shelf appeal and sustainability messaging. Brand owners in California and New York mandate post-consumer recycled content minimums.
- Healthcare:Sterile barrier systems for medical devices and pharmaceutical packaging require Tyvek lamination compatibility and sterilization resistance. Massachusetts and Minnesota device manufacturing corridors concentrate specification-driven demand.
- Electronics:Anti-static and electrostatic discharge protective films serve semiconductor and lithium-ion battery logistics. Cleanroom packaging requirements in Arizona and Oregon fabs create specialty grade opportunities.
Food & Beverage retains the volume anchor position. Healthcare is gaining share fastest as device packaging specifications tighten.
Thickness:
Calier specification clusters reflect the mechanical and optical trade-offs governing converting equipment compatibility and end-use performance.
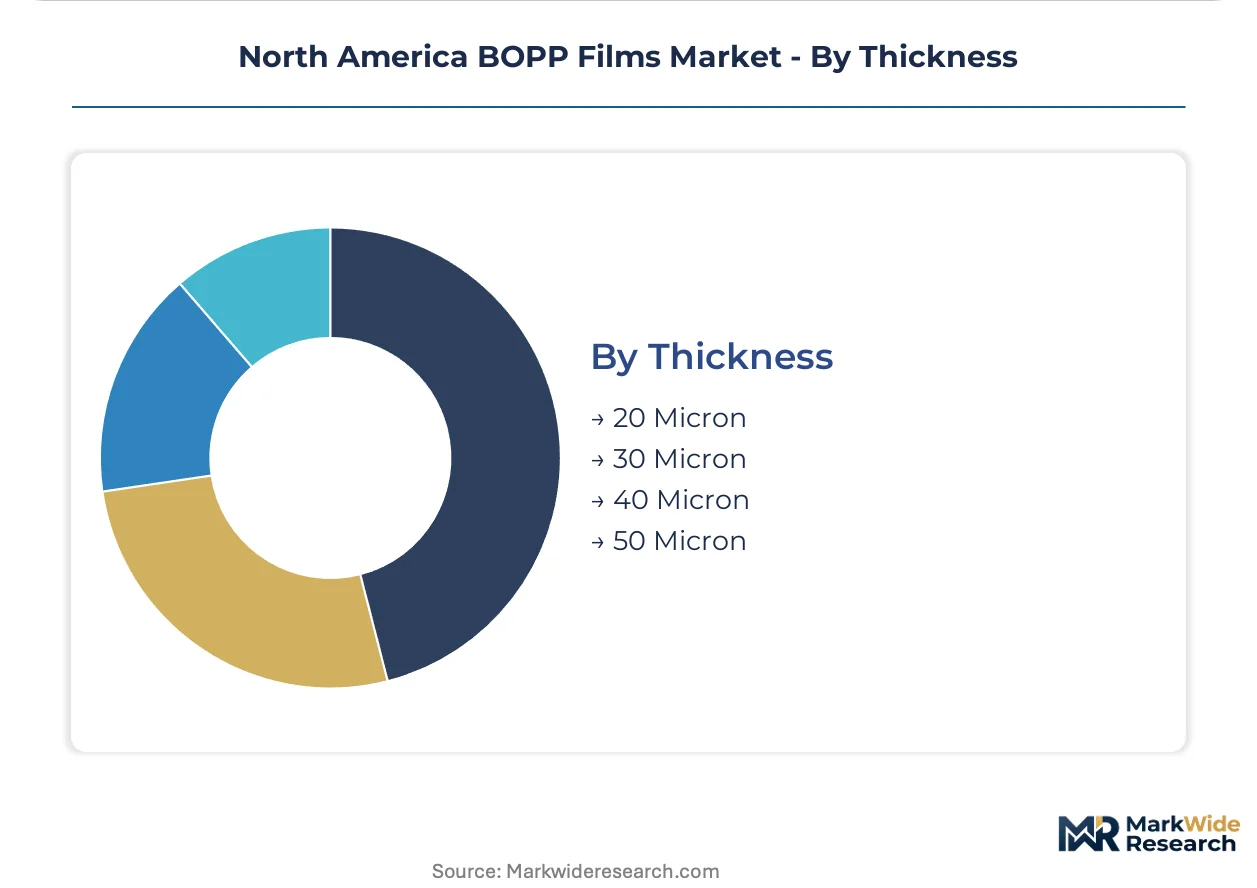
- 20 Micron:Ultra-thin grades optimize yield for label face stocks and lightweight overwrap. High-speed labeling lines in Illinois and New Jersey beverage facilities specify this caliper for cost efficiency.
- 30 Micron:The workhorse specification balancing stiffness and conformability for general-purpose packaging. Snack food converters across the U.S. Southeast standardize on this grade for vertical form-fill-seal operations.
- 40 Micron:Enhanced puncture resistance serves heavier-duty packaging and industrial tape backings. Adhesive tape manufacturers in Ohio specify this caliper for carton sealing applications requiring tensile strength.
- 50 Micron:Maximum rigidity for heavy-load bundling, agricultural baling, and specialized industrial applications. Agricultural chemical packaging in the Canadian prairies utilizes this grade for pesticide-resistant structures meeting PMRA standards.
30 Micron dominates current throughput. The 20 Micron tier is expanding most quickly as lightweighting mandates penetrate beverage and personal care segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across North America: the United States drives specification-intensive food packaging demand, while Canada emphasizes agricultural chemical and pharmaceutical applications with distinct regulatory compliance requirements.
United States
Food processing clusters in Nebraska, Iowa, and Georgia source certified barrier grades for modified atmosphere protein packaging. The EPA's evolving extended producer responsibility frameworks in California and Northeastern states mandate APR recyclability certification for contract eligibility. Midwest and Southeast manufacturing corridors concentrate extrusion capacity alongside snack and bakery processing facilities.
Canada
Agricultural chemical packaging in the Prairie Provinces utilizes heavy-gauge BOPP for pesticide-resistant structures meeting Health Canada PMRA standards. Health Canada's Consumer Product Safety provisions govern child-resistant flexible packaging specifications. Ontario and Quebec device manufacturing corridors concentrate demand for sterilization-compatible sterile barrier systems.
Mexico
Beverage bottling expansion in Jalisco and Nuevo León drives label substrate consumption for export-oriented production. Mexico's COFEPRIS pharmaceutical packaging regulations align with FDA standards for cross-border supply chains. Northern Border States concentrate maquiladora operations integrating BOPP converting for US-bound consumer goods.
North America BOPP Films Market Competitive Landscape
Capability concentration sits with integrated metallization and coating specialists; scale advantage sits with resin-backward extrusion networks. The vendor base organizes around three strategic archetypes: premium barrier specialists with FDA-certified grades, commodity volume producers serving regional food processors, and technical service integrators capturing specification-driven medical and electronics accounts. Dominant competitive moves include backward integration into resin compounding and capacity expansion in Midwest manufacturing corridors overlapping protein processing clusters.
Among North American-based specialists, Transcendia Inc. and Toray Plastics (America) Inc. exemplify the premium-tier positioning through integrated coating and metallization capabilities. Inteplast Group represents the scale-driven archetype with captive resin operations across Texas and Pennsylvania. These three anchors demonstrate how competitive positioning fragments between specification depth and vertical integration breadth.
| Leading Market Players |
|---|
| Transcendia Inc. |
| Flex Films Inc. |
| Toray Plastics (America) Inc. |
| Cosmo Films Ltd. |
| Jindal Poly Films Ltd |
| Winpak Ltd. |
| Taghleef Industries |
| Treofan Group |
| Inteplast Group |
| Others |
Value Network & Pricing Analysis
Undercapacity in integrated metallization lines across the U.S. Midwest and Southeast manufacturing corridors is concentrating pricing power among converters with captive barrier film capacity, while spot-market buyers face escalating premiums for FDA-certified grades.
Pricing Analysis
Long-term offtake agreements dominate procurement between major CPG brands and integrated extrusion-metallization converters, locking in volume commitments that insulate premium-tier suppliers from propylene feedstock volatility. Price differentiation rests on FDA food-contact notification status and APR design-for-recyclability certification, with certified barrier grades commanding substantial premiums over commodity clarity films. Cost compression in standard-grade clear BOPP is intensifying as non-integrated extruders compete for regional snack processor contracts. Brand technical teams demonstrate lowest price sensitivity in medical device and pharmaceutical packaging segments where barrier documentation carries liability exposure.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard practice among resin suppliers serving the North American BOPP value chain, squeezing working capital for mid-tier converters lacking supply-chain finance facilities. Polymer-grade propylene feedstock draws from U.S. Gulf Coast refinery and steam cracker operations, with resin compounding concentrated in Texas and Pennsylvania. Single-source vulnerability runs through vacuum metallization equipment suppliers, where lead times for deposition chamber components create bottleneck risk. Distribution runs through direct mill relationships with major food processors and regional converting distributors serving mid-market label and tape manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service and film specification consulting represent the fastest-expanding revenue layer in North American BOPP, with aftermarket attach rates climbing faster than commodity roll volumes as brand technical teams embed consultants in packaging development workflows.
For Market Incumbents: Harden specification-lock through FDA notification pathway investments and integrated metallization capacity additions in Nebraska and Georgia protein processing corridors. Defend against emerging water-based coating specialists by securing exclusive barrier coating partnerships with major CPG procurement teams. Prioritize backward integration into resin compounding to offset propylene feedstock volatility exposure. For New Entrants and Emerging Players: Establish a beachhead in Canadian agricultural chemical packaging, where Health Canada PMRA pesticide-resistant standards create specification-driven demand with limited incumbent specialization. Target electronics anti-static grades for semiconductor and lithium-ion battery logistics in Arizona and Oregon cleanroom corridors. Lead with rapid APR recyclability certification to unlock California and Northeastern state EPR-mandated procurement channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across metallization-integrated barrier film capacity, favoring acquisition of mid-tier converters with untapped coating asset utilization. Long-term viability centers on converters bridging resin compounding through specification consulting. Monitor California SB 54 implementation timelines as the critical signal for mono-material BOPP demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive propylene supply insulates margins from Gulf Coast refinery volatility. |
| FDA Food-Contact Notification Investment | Pre-certified barrier grades unlock CPG procurement team contract eligibility. |
| APR Recyclability Certification | Design-for-recycling validation gates preferred supplier status in California EPR jurisdictions. |
| Integrated Metallization Capacity Expansion | Vacuum deposition assets capture premium barrier specifications in protein packaging clusters. |
| Technical Service Organization Buildout | Specification consulting embeds converters in brand packaging development workflows. |
Research Methodology
Initial hypotheses were tested against primary input from film extrusion plant managers, CPG packaging development engineers, FDA regulatory affairs consultants, and APR recyclability testing facility directors, and refined through secondary validation against SEC 10-K filings of listed packaging converters, U.S. Census Bureau trade data for polypropylene film imports, FDA food-contact substance notification databases, and state-level EPR legislative tracking. Bottom-up volume estimates from extrusion capacity utilization rates were triangulated against top-down demand projections from food processing cluster output data.
Demand-supply balance modeling across the analysis window incorporated product type segmentation by barrier performance tier, application segmentation by converting process requirements, end-user segmentation by liability exposure level, and thickness segmentation by equipment compatibility constraints. CAGRs were derived from regression analysis of historical capacity expansion patterns against EPR implementation timelines. Forecast inputs included propylene feedstock cost trajectories and FDA notification approval cycle durations.
Stress conditions across propylene price volatility bands, FDA notification approval delays, and California EPR enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EPR adoption timelines and metallization capacity expansion schedules. Macroeconomic contraction, regulatory enforcement deviation, or breakthrough barrier coating technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Latin America Polypropylene (PP) Packaging Film Market
Poly film
India Plastic Packaging Film Market
Poly film
Resealable Films Market
Poly film
Thermoforming Films Market
Poly film
Blown Film Extruder Market
Poly film
North America Polyimide Films Market
Poly film
Packaging Film Market
Poly film
Global Polyethylene Packaging Market
Poly film
Germany Plastic Packaging Films Market
Poly film
Polypropylene Film Market
Poly film
Brazil Plastic Packaging Films Market
Poly film
PVC Film for Medical Market
Poly film
Australia and New Zealand Plastic Packaging Film Market
Poly film
Polyurethane (PU) Film Market
Poly film
Polystyrene Films Market
Poly film
PP Film Blowing Machine Market