
 Silicone-Coated PET Films Market | 2026-2036
Silicone-Coated PET Films Market Size, Share, and Industry Trends Forecast 2026-2036
Silicone-Coated PET Films Market Analysis
Skilled polymer chemists with silicone-PET interface expertise is reorganizing how Asian manufacturers scale coating operations. Dow leverages its integrated silicone feedstock position to anchor North American supply chains. Shin-Etsu Chemical Co., Ltd. sustains technology leadership through proprietary catalyst systems for controlled release chemistry. Toray Group competes by dominating high-clarity optical-grade segments for electronics laminates.
Silicone-coated PET films consist of polyethylene terephthalate substrates laminated with crosslinked polydimethylsiloxane layers, typically applied through solvent-based or solventless coating processes at thicknesses ranging from twelve to seventy-five micrometers, functioning primarily as release surfaces for pressure-sensitive adhesives in industrial converting operations. Specialty grades command premium positioning due to custom release force specifications demanded by medical device sterilization protocols. Electronics applications represent the fastest-expanding consumption pool, driven by flexible printed circuit board fabrication and display component protection requirements.
FDA medical device regulations and EPA volatile organic compound emission standards constrain coating formulation choices and facility location decisions for US-based producers. The EU REACH framework and F-Gas Regulation impose substance registration burdens and restrict certain silicone precursor chemistries across European manufacturing footprints. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions that could displace fluorinated release agents and redirect demand toward advanced silicone alternatives.
Market Dynamics
East Asian electronics manufacturers are consolidating procurement of release liner grades for flexible circuit protection, compressing supplier margins while accelerating specifications for sub-25 micrometer coating uniformity.
Growth Catalysts
- EU REACH substance registration:Tightening silicone chemical safety protocols are redirecting European converters toward certified low-VOC coating suppliers with validated supply chains.
- Flexible printed circuit board fabrication:Display component protection requirements in East Asian electronics clusters are expanding consumption of optical-grade silicone-PET laminates.
- Jiangsu province extrusion concentration:Domestic adhesive tape producers in this Chinese manufacturing hub are scaling captive coating capacity to serve regional converting demand.
Market Restraints
- Silicone precursor cost volatility:Chlorosilane feedstock price swings constrain margin predictability for solventless coating operators.
- East Asian supply concentration:Over-dependence on Shin-Etsu and Dow for controlled-release catalyst systems creates single-source vulnerability.
- EPA VOC emission thresholds:Facility location decisions for US-based producers face restrictive air quality permitting timelines.
Strategic Opportunities
- India PLI scheme for electronics:Domestic component manufacturing incentives are attracting silicone-PET film investment toward Gujarat and Tamil Nadu clusters.
- Solventless UV-curing convergence:Energy-curable polydimethylsiloxane formulations combined with inline PET extrusion are enabling toll-coating service models.
- Medical device sterilization protocols:Custom release force specifications for gamma-stable grades command premium positioning in FDA-regulated supply chains.
Industry Challenges
- Silicone-PET interface chemistry expertise:Skilled polymer chemists capable of tuning crosslink density for controlled release are scarce across Asian coating operations.
- ISO 13485 certification timelines:Medical-grade qualification cycles extend 18-24 months, delaying revenue conversion for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicone-Coated PET Films Market |
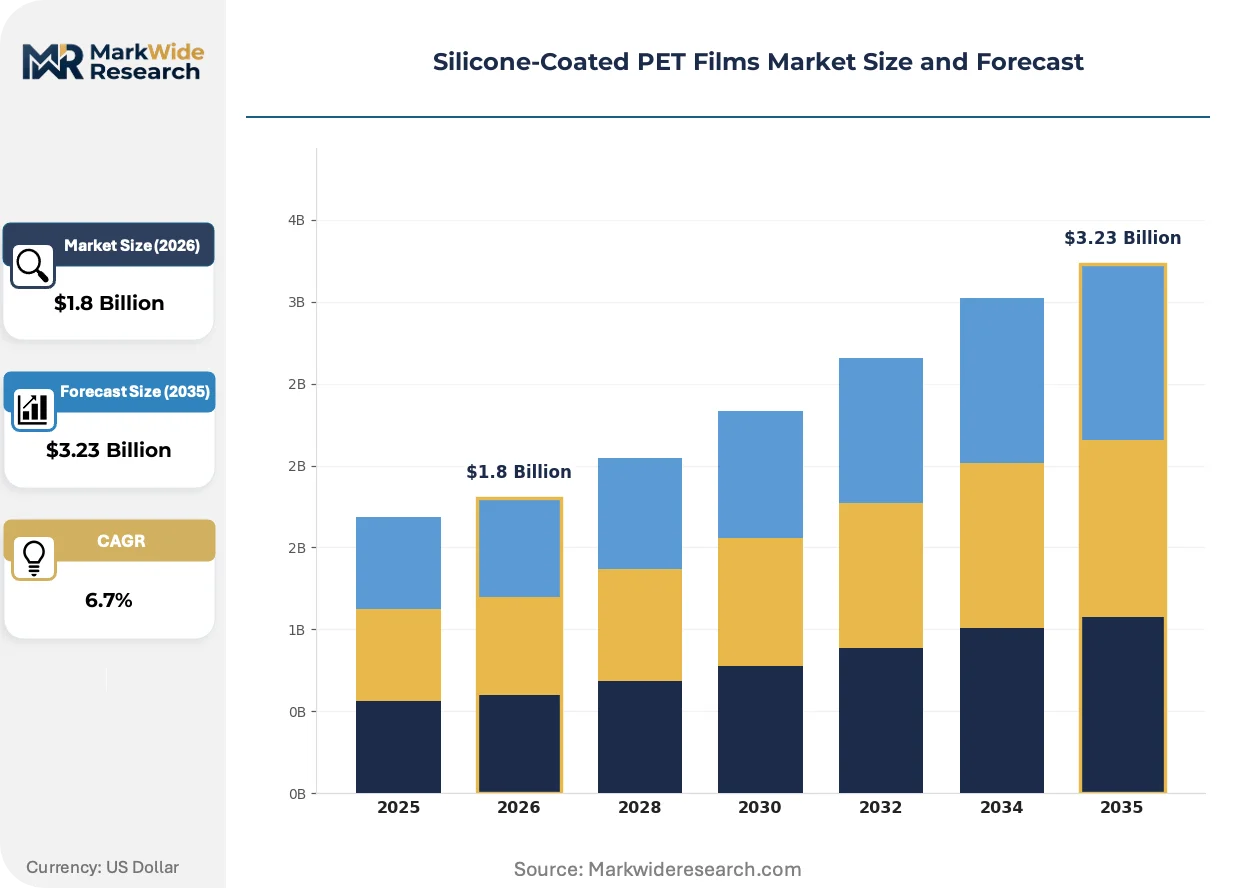
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, Release Liner, Specialty Application: Medical, Electronics, Food Packaging, Automotive End User: Manufacturers, Distributors, Retailers, OEMs Distribution Channel: Online, Offline, Direct Sales, Wholesale |
| Companies Covered | Wacker Chemie AG, Dow, Shin-Etsu Chemical Co., Ltd., Polyplex Corporation Limited, Loparex, Mondi Group, Mitsubishi Polyester Film, Inc., Jindal Poly Films, Toray Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicone-Coated PET Films Market Emerging Trajectories
Coating technology evolution and regulatory chemistry constraints are fragmenting competitive advantage across solvent-based, solventless, and energy-curable process routes.
Plasma-enhanced chemical vapor deposition of organosilicon precursors onto PET substrates is decomposing the traditional solvent-coating equipment lock-in. Electronics laminators in South Korea and Taiwan are piloting inline PECVD systems at 50-meter-per-minute line speeds. This process architecture is decomposing capital barriers for mid-scale entrants while compressing incumbent solvent-coating margins.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are eliminating perfluorinated release agent options for European converters. Medical device manufacturers face reformulation deadlines for sterilization pouch release liners. German and Swiss packaging suppliers are accelerating silicone alternative validation programs to maintain CE-marked product continuity.
Consolidated specification-setting by East Asian electronics original equipment manufacturers is compressing supplier qualification cycles. Tier-one flexible circuit board fabricators in Japan and China now mandate 90-day material certification turnaround. This procurement compression is favoring coating operations with captive polymer synthesis and in-house release testing laboratories.
Silicone-Coated PET Films Market Segmentation
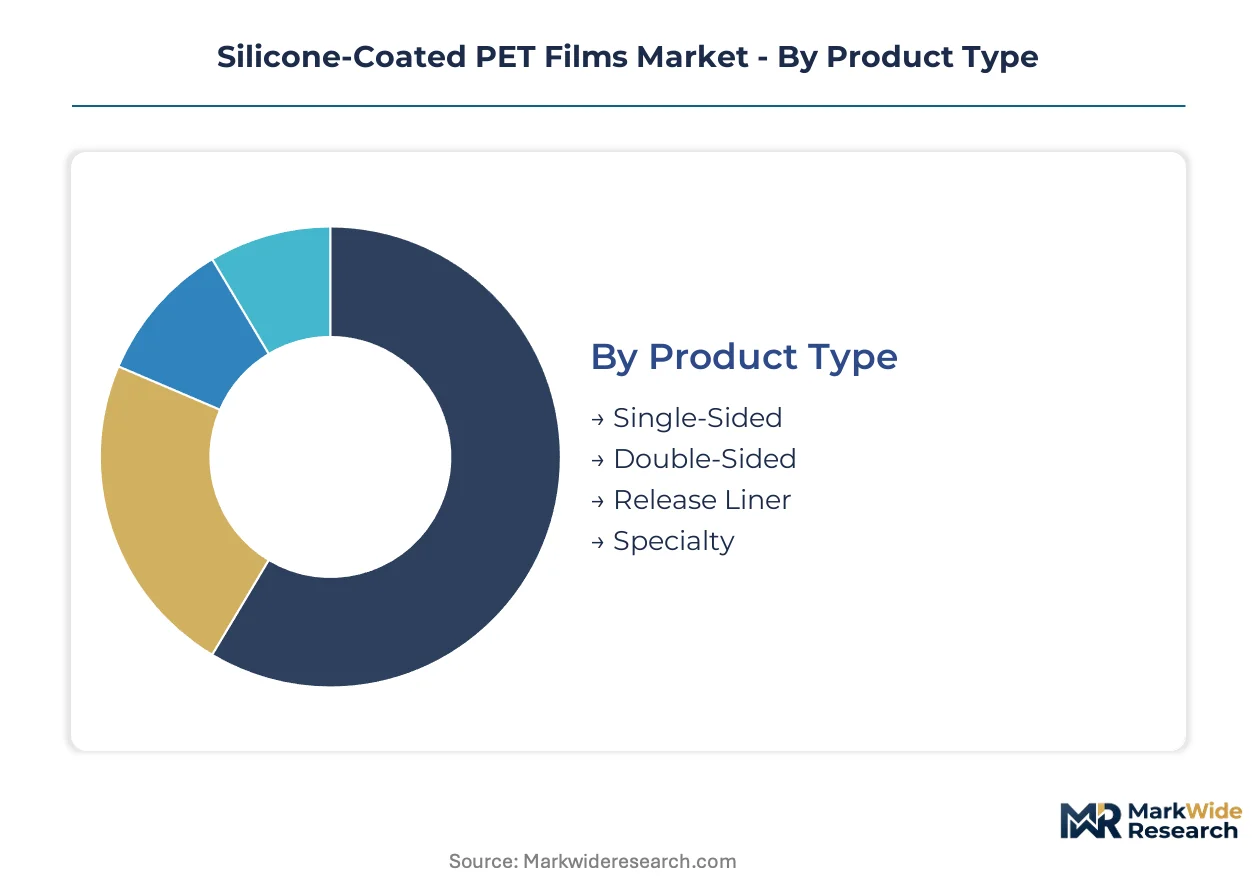
Silicone-coated PET films fragment across four structural dimensions that determine pricing power, regulatory exposure, and supply chain configuration. Product type and application segments concentrate value capture, while end-user and distribution channel structures dictate margin compression risks.
Product Type:
Domestic consumption in China's Jiangsu province drives volume for standard grades, while export-led specialty segments command premium positioning in European and North American medical supply chains.
- Single-Sided:Polydimethylsiloxane coating applied to one PET substrate surface, typically at 12-38 micrometer thicknesses. Electronics laminators in South Korea and Taiwan specify sub-25 micrometer uniformity for flexible circuit protection, compressing supplier qualification cycles to 90 days.
- Double-Sided:Symmetrical silicone layers on both PET faces enable dual-release functionality for adhesive tape converting. Medical device sterilization pouch manufacturers in Germany and Switzerland validate these grades under EU REACH substance registration protocols, extending certification timelines.
- Release Liner:Controlled-release chemistry for pressure-sensitive adhesive applications.
- Specialty:Custom release force specifications including gamma-stable medical grades.
Single-sided holds the largest share; momentum sits with specialty grades.
Application:
Cost tier stratification separates FDA-regulated medical applications from commodity food packaging, with electronics occupying the mid-premium positioning.
- Medical:Sterilization pouch release liners and wound care substrates requiring ISO 13485 certification. Gamma-stable silicone-PET interfaces for radiation sterilization command three-tier pricing differentiation across premium, standard, and economy certification grades.
- Electronics:Flexible printed circuit board fabrication and display component protection. Optical-grade clarity specifications from Japan and China OEMs are accelerating consumption of solventless UV-curable coating formulations.
- Food Packaging:Bakery release films and tray liners for high-temperature applications.
- Automotive:Interior trim adhesive carriers and noise-dampening laminate substrates.
Electronics represents the fastest-expanding consumption pool; medical commands the steepest margin structure.
End User:
Volume concentration favors direct manufacturer procurement, while distributor intermediation persists in fragmented converting segments.
- Manufacturers:Captive coating operations at PET film extrusion sites in Jiangsu province serve domestic adhesive tape producers. In-house polymer synthesis and release testing laboratories defend margin position against toll-coating competitors.
- Distributors:Regional inventory positioning for small-batch converting operations.
- Retailers:Consumer-grade adhesive product private label sourcing.
- OEMs:Consolidated specification-setting by East Asian electronics original equipment manufacturers.
Manufacturers hold the largest share; momentum sits with OEM direct procurement.
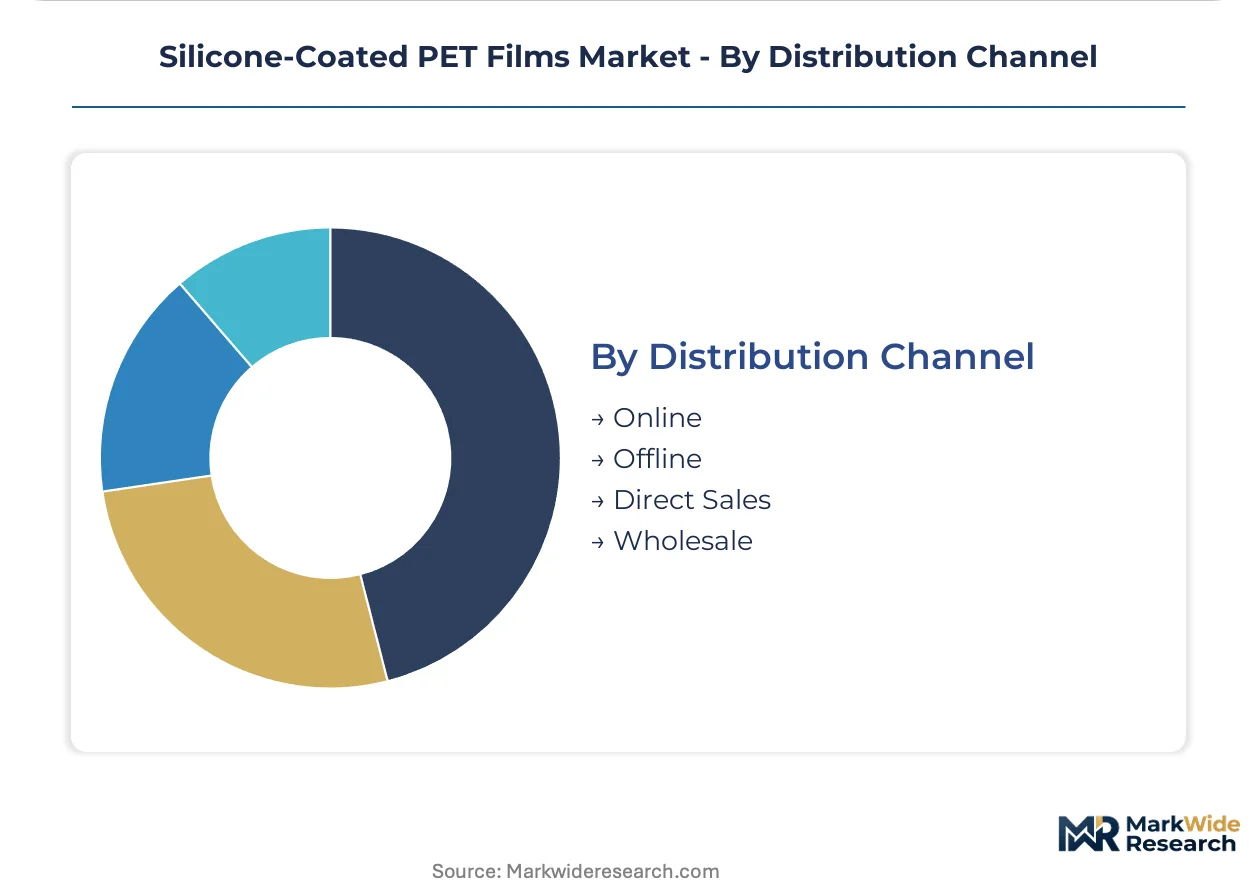
Distribution Channel:
Supply chain configuration separates high-volume direct sales from fragmented wholesale intermediation.
- Online:Digital procurement platforms for standard release liner specifications.
- Offline:Traditional distributor relationships in European converting markets.
- Direct Sales:Long-term supply agreements with tier-one flexible circuit board fabricators. Dow and Shin-Etsu Chemical anchor North American and Asian supply chains through integrated silicone feedstock positions.
- Wholesale:Regional stocking for mid-scale adhesive converters.
Direct sales holds the largest share; momentum sits with online standard-grade procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Ministry of Ecology and Environment anchors the regulatory gravity for silicone-coated PET film manufacturing through dual carbon goals and volatile organic compound emission controls that reshape coating facility siting decisions.
China
Jiangsu province extrusion clusters serve domestic adhesive tape producers scaling captive coating capacity. The Ministry of Ecology and Environment enforces dual carbon goals that constrain solvent-based coating expansion. Suzhou and Wuxi manufacturing hubs concentrate PET film extrusion lines feeding regional converting demand.
United States
Flexible circuit board fabricators in California and Texas drive consumption of optical-grade release liners. The EPA volatile organic compound emission standards restrict coating facility location decisions and air quality permitting timelines. Midwest industrial corridors host toll-coating operations serving medical device sterilization pouch manufacturers.
Germany
Medical device sterilization pouch release liner manufacturers validate gamma-stable grades under tightening EU REACH substance registration protocols. The EU F-Gas Regulation eliminates perfluorinated release agent options, accelerating silicone alternative validation. Bavarian packaging suppliers maintain CE-marked product continuity through reformulation programs.
Japan
Tier-one flexible circuit board fabricators mandate 90-day material certification turnaround for sub-25 micrometer coating uniformity. METI industrial standards govern electronics laminate optical clarity specifications. Kanto and Kansai electronics clusters consolidate procurement of release liner grades for display component protection.
South Korea
Electronics laminators pilot plasma-enhanced chemical vapor deposition systems at 50-meter-per-minute line speeds. The Ministry of Trade, Industry and Energy supports advanced materials manufacturing through national R&D programs. Seoul-Incheon industrial corridors concentrate flexible printed circuit board fabrication driving silicone-PET laminate consumption.
Silicone-Coated PET Films Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated silicone feedstock operators anchor supply chain security against specialized coating converters competing on formulation agility. Three archetypes dominate: multinational chemical conglomerates with captive silicone synthesis, regional PET film extruders with toll-coating partnerships, and niche medical-grade specialists with ISO 13485 certification. Capacity expansion and strategic technology licensing represent the dominant competitive moves as players reposition between solvent-based and energy-curable process routes.
Among integrated chemical conglomerates, Dow and Shin-Etsu Chemical Co., Ltd. occupy positions exemplifying upstream control over chlorosilane feedstock and proprietary catalyst systems. Toray Group represents the optical-grade specialization archetype, competing through high-clarity segments for electronics laminates. These three companies anchor distinct competitive vectors: feedstock integration, controlled-release chemistry, and premium optical performance.
| Leading Market Players |
|---|
| Wacker Chemie AG |
| Dow |
| Shin-Etsu Chemical Co., Ltd. |
| Polyplex Corporation Limited |
| Loparex |
| Mondi Group |
| Mitsubishi Polyester Film, Inc. |
| Jindal Poly Films |
| Toray Group |
| Others |
Supply Flow & Price Mechanics
EU REACH substance registration protocols gate both supplier qualification and price differentiation simultaneously, compressing uncertified converters into commodity tiers while rewarding validated low-VOC coating operations with premium positioning in European medical supply chains.
Pricing Analysis
Geographic price spreads separate Jiangsu province standard-grade output from German and Swiss gamma-stable medical grades by certification tier rather than raw material cost alone. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 13485 validation status and FDA master file submission depth. Pricing pressure stems from East Asian electronics OEMs consolidating procurement and compressing supplier margins to sub-25 micrometer uniformity specifications. Small-batch converting distributors exhibit highest price sensitivity; medical device sterilization pouch manufacturers demonstrate lowest sensitivity due to regulatory switching costs.
Supply Chain Analysis
China and Japan anchor PET film extrusion and silicone coating chemistry respectively, with South Korea piloting plasma-enhanced chemical vapor deposition equipment at commercial line speeds. Chlorosilane feedstock draws from Dow's North American integrated positions and Shin-Etsu's Japanese catalyst systems, creating dual-source concentration risk. Single-source vulnerability sits with proprietary controlled-release catalyst formulations from incumbent chemical conglomerates. Distribution runs through direct long-term agreements with tier-one flexible circuit board fabricators and regional wholesale stocking for mid-scale adhesive converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against fluorinated release agent alternatives as EU F-Gas Regulation eliminates perfluorinated options and redirects demand toward advanced silicone chemistries.
For Market Incumbents: Secure captive chlorosilane feedstock positions through backward integration into silicone precursor synthesis, insulating margin structures from raw material volatility. Deepen ISO 13485 certification moats to delay new entrant revenue conversion by 18-24 months. Prioritize solventless UV-curable formulation R&D to outpace regulatory VOC emission thresholds tightening across US and Chinese manufacturing footprints. For New Entrants and Emerging Players: Anchor in India's Gujarat and Tamil Nadu electronics clusters where PLI scheme incentives attract domestic component manufacturing investment with lower incumbent saturation. Target toll-coating service models combining energy-curable polydimethylsiloxane formulations with inline PET extrusion, bypassing capital-intensive solvent-coating equipment lock-in. Pursue gamma-stable medical grade validation as the most penetrable premium tier given extended certification timelines that deter rapid competitive response. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across plasma-enhanced chemical vapor deposition sub-segments as PECVD equipment decomposes barriers for mid-scale entrants. Five-to-ten year viability favors coating operations with captive polymer synthesis and in-house release testing laboratories. Acquisition target archetype: regional PET film extruders with toll-coating partnerships and pending ISO 13485 certification. Signal to watch: East Asian electronics OEM procurement compression accelerating 90-day material certification mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Precursor Synthesis | Dow and Shin-Etsu anchor supply chain security through captive chlorosilane feedstock control. |
| Solventless UV-Curable Coating Transition | Energy-curable formulations bypass EPA VOC thresholds constraining US facility expansion. |
| ISO 13485 Medical Grade Certification | German and Swiss packaging suppliers defend CE-marked product continuity through validation investment. |
| Plasma-Enhanced Chemical Vapor Deposition Scale-Up | South Korean electronics laminators pilot PECVD systems at 50-meter-per-minute commercial speeds. |
| India Electronics Cluster Capacity Buildout | Gujarat and Tamil Nadu PLI incentives attract silicone-PET film investment toward domestic converting demand. |
Methodological Framework
A spread of perspectives from polymer chemists at coating operations, procurement leads at flexible circuit board fabricators, regulatory affairs specialists navigating EU REACH protocols, and distribution channel managers converged on the working assumptions driving this analysis. Primary fieldwork combined with secondary validation from customs and trade data, SEC 10-K filings of integrated chemical conglomerates, and national R&D program disclosures from South Korea's Ministry of Trade, Industry and Energy. Bottom-up capacity assessments and top-down demand modeling triangulated volume and value outputs.
Segmentation dimensions modeled include product type architecture, application end-use stratification, certification grade tiering, and regional production hub concentration across the analysis window. CAGRs were derived from growth driver elasticity analysis applied to base-year consumption estimates. Industry-specific forecast inputs incorporated chlorosilane feedstock price trajectory assumptions and electronics OEM procurement cycle compression rates.
Decision-makers should treat outputs as directional under sustained East Asian electronics demand and stable regulatory chemistry constraints; material deviation in fluorinated release agent substitution timelines or dual carbon goal enforcement intensity would warrant model refresh. Recalibration cycles align with material shifts in EU REACH substance registration protocols and EPA VOC emission threshold revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Global PVDC Coated Films Market
Poly film
Asia-Pacific Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market
Poly film
Global EVOH Films for Packaging Market
Poly film
Multi-Layer Blown Films Market
Poly film
EVOH Encapsulation Film Market
Poly film
Peelable and Resealable Films Market
Poly film
Surface Printed Film Market
Poly film
Silicone Release Films Market
Poly film
Polyolefin Films Market
Poly film
Mexico Plastic Packaging Films Market
Poly film
Polyethylene Furanoate Films Market
Poly film
Polyethylene Terephthalate (PET) Shrink Films Market
Poly film
APET Film Market
Poly film
Polyolefin (POF) Shrink Film Market
Poly film
Bundling Film Market
Poly film
North America Polyimide Films Market