
 Global Specialty Films Polymer Market | 2026-2036
Global Specialty Films Polymer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Specialty Films Polymer Market Foresight
Modular film-laminate configurations for electric vehicle battery pouches is realigning procurement patterns among tier-one automotive suppliers. Covestro AG leverages its polycarbonate film extrusion capabilities to anchor supply relationships with European EV battery producers. BASF SE competes through differentiated polyamide-polyolefin coextrusion technologies that sustain higher thermal stability thresholds in power electronics. DuPont de Nemours, Inc. dominates the high-performance polyimide segment for flexible circuit substrates, occupying a niche where material purity specifications exceed standard industrial grades.
Specialty films polymer encompasses engineered thermoplastic and thermoset resin formulations processed into thin-gauge membranes, typically ranging from 12 micrometers to 500 micrometers thickness, designed for functional performance beyond commodity packaging barriers. These materials deliver controlled permeability, dielectric resistance, optical clarity, or flame retardancy across industrial applications. Polyethylene terephthalate and polycarbonate films lead volume consumption in electrical insulation and graphic arts applications, where biaxial orientation processes yield dimensional stability critical for precision coating operations. Polypropylene films represent the fastest-expanding category in food packaging, driven by retort-compatible coextrusion advances that displace metalized laminates in shelf-stable pouch formats.
The European Chemicals Agency enforces REACH substance restrictions that limit phthalate plasticizers in food-contact films, redirecting formulation investment toward bio-based adipate esters and citrate alternatives. China's Ministry of Ecology and Environment implements dual carbon goals that tighten emissions thresholds for solvent-based coating lines, compelling domestic producers to adopt aqueous dispersion or hot-melt lamination technologies. The US Food and Drug Administration maintains food additive regulations under 21 CFR that govern migration limits for polymer additives in direct-contact applications, creating compliance differentiation between qualified and non-qualified suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks in multiple jurisdictions, as packaging waste directives increasingly assign collection and recycling liability upstream to film manufacturers rather than downstream brand owners.
Market Dynamics
Modular film-laminate configurations for electric vehicle battery pouches are realigning procurement patterns among tier-one automotive suppliers, forcing polymer producers to reconfigure extrusion capacity toward thinner-gauge, higher-dielectric specifications.
Growth Catalysts
- REACH substance restrictions:The European Chemicals Agency limits on phthalate plasticizers in food-contact films redirect formulation investment toward bio-based adipate esters and citrate alternatives.
- Electric vehicle battery module demand:Electronics manufacturers in East Asia are expanding purchases of polycarbonate insulating films for EV battery thermal management systems.
- Jiangsu-Zhejiang extrusion clusters:Integrated film extrusion hubs in China's eastern provinces serve both domestic appliance brands and export packaging converters with coordinated supply.
Market Restraints
- Specialty resin input volatility:Bisphenol A and aromatic diacid feedstock prices fluctuate with crude oil derivatives, compressing margin predictability for film converters.
- Equipment supply concentration:Precision biaxial orientation lines for sub-25-micrometer films depend on a limited set of German and Japanese machinery suppliers.
- Halogen-free thermal ceiling:Phosphorus-nitrogen flame retardant systems in polypropylene films face upper temperature limits that constrain retort pouch applications above 135°C.
Strategic Opportunities
- India's FSSAI packaging mandates:Stricter food-contact material rules create qualified-supplier differentiation for halogen-free polymer formulations entering the subcontinent.
- Flexible circuit substrate convergence:Polyimide-polyethylene naphthalate hybrid films enable roll-to-roll processing of 5G antenna substrates for wearable electronics.
- Aqueous dispersion technology:China's Ministry of Ecology and Environment dual carbon goals compel domestic producers to adopt water-based coating lines, opening technology licensing windows.
Industry Challenges
- Migration testing certification timelines:US FDA 21 CFR food additive qualification for novel polymer additives requires 18-24 month toxicology studies that delay commercialization.
- Multi-layer coextrusion skill scarcity:Process engineers capable of tuning seven-layer barrier structures with nanocomposite interlayers command premium compensation in tight labor markets.
- Extended producer responsibility compliance:Packaging waste directives in multiple jurisdictions assign collection and recycling liability upstream to film manufacturers rather than brand owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Specialty Films Polymer Market |
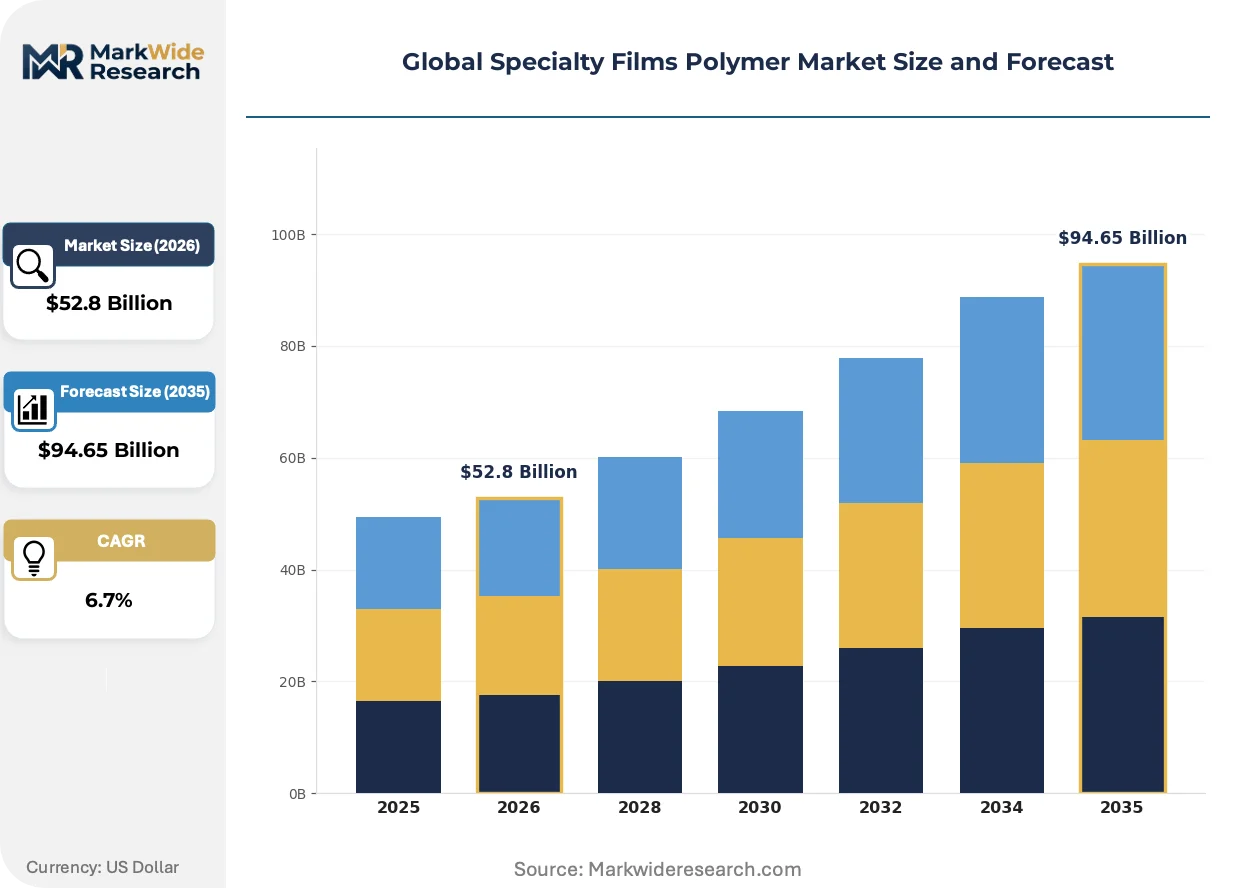
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $94.65 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Terephthalate, Polyvinyl Chloride, Polystyrene, Polycarbonate, Polypropylene Application: Packaging, Electrical Insulation, Graphic Arts, Automotive Components, Building & Construction End User Industry: Food & Beverage Manufacturers, Electronics Manufacturers, Aerospace Firms, Consumer Electronics Brands, Textile Producers Form: Films, Sheets, Coated Films, Laminates, Foam Films |
| Companies Covered | Covestro AG, 3M Company, BASF SE, Eastman Chemical Company, SABIC, DuPont de Nemours, Inc., Solvay SA, Mitsubishi Chemical Group Corporation, Toray Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Specialty Films Polymer Market Shifts & Advancements
Active materials science and regulatory chemistry are converging to redefine performance thresholds across electrical insulation, food preservation, and optical display applications.
Polypropylene retort-compatible coextrusion is expanding into shelf-stable pouch formats previously dominated by metalized laminates. Japanese and South Korean food packagers are adopting transparent high-barrier structures at accelerated trial rates. This technology is expanding into premium pet food and ready-meal segments where microwaveability and shelf visibility drive brand differentiation.
China's Ministry of Ecology and Environment enforces dual carbon goals that tighten emissions thresholds for solvent-based coating lines. Domestic producers face compulsory conversion to hot-melt lamination or aqueous dispersion technologies before 2027. Jiangsu and Zhejiang province film extrusion clusters are absorbing the highest compliance costs as they supply both domestic appliance brands and export packaging converters.
Automotive battery procurement teams now specify dielectric withstand voltage and puncture resistance as primary selection criteria rather than unit cost. Tier-one suppliers in Germany and South Korea are consolidating qualified polymer film vendors into multi-year framework agreements. This behavioral shift is most visible in electric vehicle battery pouch cell manufacturing where thermal runaway containment demands sub-50-micrometer polycarbonate layers with consistent thickness tolerance.
Global Specialty Films Polymer Market Segmentation
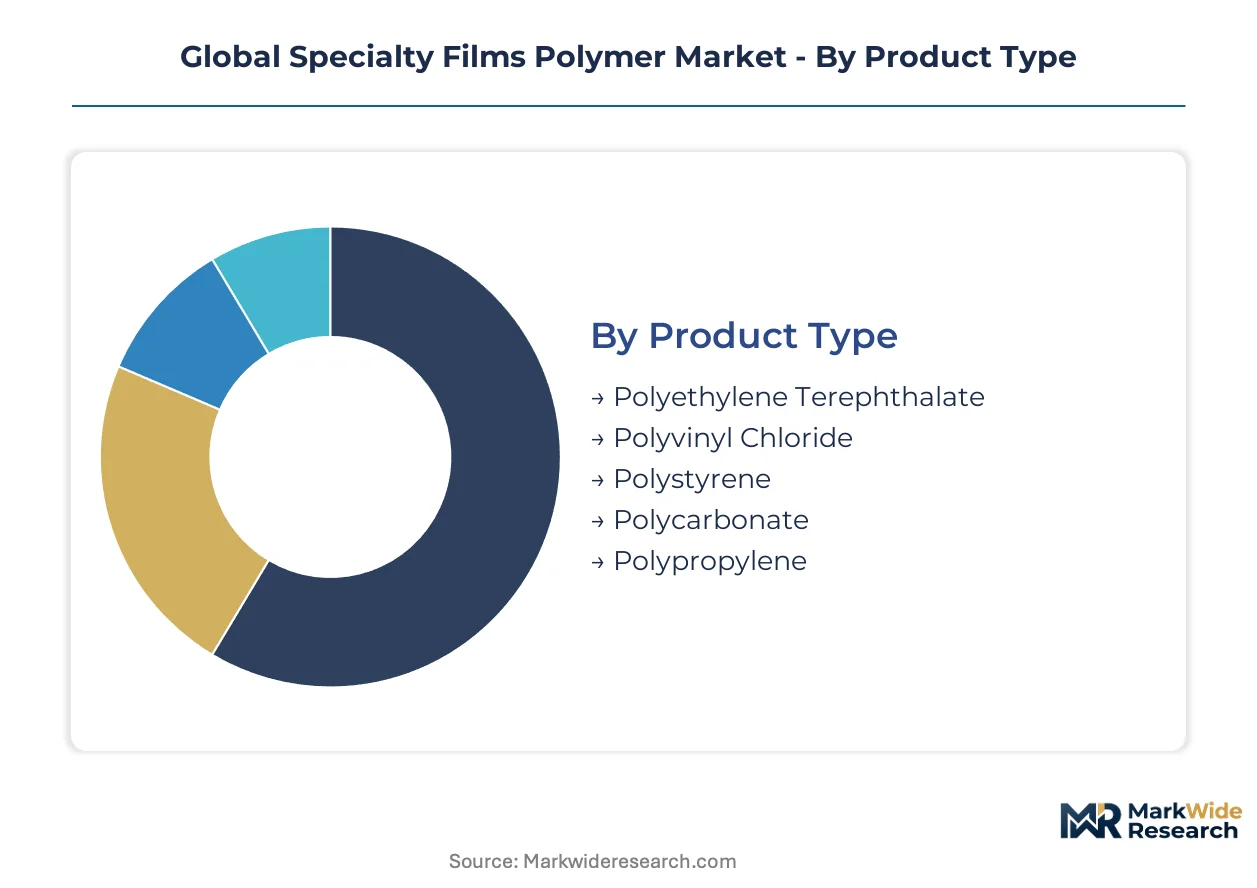
Specialty films polymer markets fragment across multiple technical dimensions where product chemistry, application requirements, and end-use specifications create distinct commercial battlegrounds. Procurement teams evaluate segments through divergent criteria — thermal stability thresholds for automotive buyers versus migration compliance for food packagers — generating asymmetric growth trajectories across categories.
Product Type:
Volume concentration clusters in commodity-grade resins while premium pricing accrues to high-performance thermoplastics with specialized dielectric or barrier properties.
- Polyethylene Terephthalate:Biaxially oriented PET films deliver dimensional stability critical for precision coating operations in flexible circuit manufacturing. Demand concentrates in East Asian electronics manufacturing zones where roll-to-roll processing of display substrates requires tight thickness tolerance.
- Polypropylene:Retort-compatible coextrusion advances displace metalized laminates in shelf-stable pouch formats. Japanese and South Korean food packagers drive trial adoption for transparent high-barrier structures in premium ready-meal segments.
- Polycarbonate:Sub-50-micrometer insulating layers with consistent dielectric withstand voltage serve electric vehicle battery thermal management systems.
- Polyvinyl Chloride:Calendered and extruded formulations retain cost-positioning in graphic arts overlaminates despite regulatory pressure on plasticizer chemistry.
- Polystyrene:Oriented polystyrene films maintain niche presence in label face stocks where stiffness and printability outweigh moisture sensitivity constraints.
Mature deployment sits with polyethylene terephthalate across established electrical and display applications. Newer deployment is concentrated in polypropylene as retort pouch specifications migrate toward halogen-free transparent barriers.
Application:
End-use specifications diverge sharply between cost-sensitive mass packaging and performance-critical industrial membranes where qualification timelines extend commercial cycles.
- Packaging:Multi-layer coextrusion with ethylene vinyl alcohol interlayers delivers oxygen transmission rates below 0.5 cc/m²/day for shelf-stable protein products. China's Jiangsu and Zhejiang extrusion clusters supply both domestic appliance brands and export converters with coordinated barrier film output.
- Electrical Insulation:Polyimide and polycarbonate films sustain dielectric breakdown thresholds above 300 kV/mm for power electronics and battery module applications. German and South Korean automotive tier-one suppliers consolidate qualified vendors into multi-year framework agreements.
- Graphic Arts:PET and PVC overlaminates protect printed substrates in outdoor signage and fleet graphics where UV resistance determines replacement cycles.
- Automotive Components:Flame-retardant polycarbonate films meet FMVSS 302 burn rate requirements for interior trim applications.
- Building & Construction:PVDF-coated polyester films deliver weatherability for architectural membrane structures and tensioned roofing systems.
Procurement consolidation is most advanced in electrical insulation where automotive qualification protocols restrict vendor pools. Packaging maintains the most fragmented supplier landscape with regional converters competing on delivery velocity.
End User Industry:
Customer technical sophistication spans from specification-driven aerospace procurement to price-sensitive commodity food packaging with minimal formulation differentiation.
- Electronics Manufacturers:Flexible circuit substrate producers demand material purity specifications exceeding standard industrial grades for 5G antenna and wearable device applications. Polyimide-polyethylene naphthalate hybrid films enable roll-to-roll processing at finer line resolutions.
- Food & Beverage Manufacturers:Extended shelf-life requirements and microwaveability specifications drive retort pouch adoption. FSSAI packaging mandates in India create qualified-supplier differentiation for halogen-free formulations entering the subcontinent.
- Consumer Electronics Brands:Display and battery module manufacturers specify optical clarity and dielectric resistance in thin-gauge membranes.
- Aerospace Firms:Flame-retardant polyimide films meet FAA flammability standards for aircraft interior insulation blankets.
- Textile Producers:Breathable waterproof laminates for performance apparel utilize thermoplastic polyurethane interlayers bonded to woven substrates.
Specification intensity peaks with electronics manufacturers where material purity and thickness tolerance command premium pricing. Textile applications represent the most price-elastic demand segment with rapid supplier switching on cost differentials.
Form:
Processing technology and downstream conversion economics favor certain physical formats over others in specific application verticals.
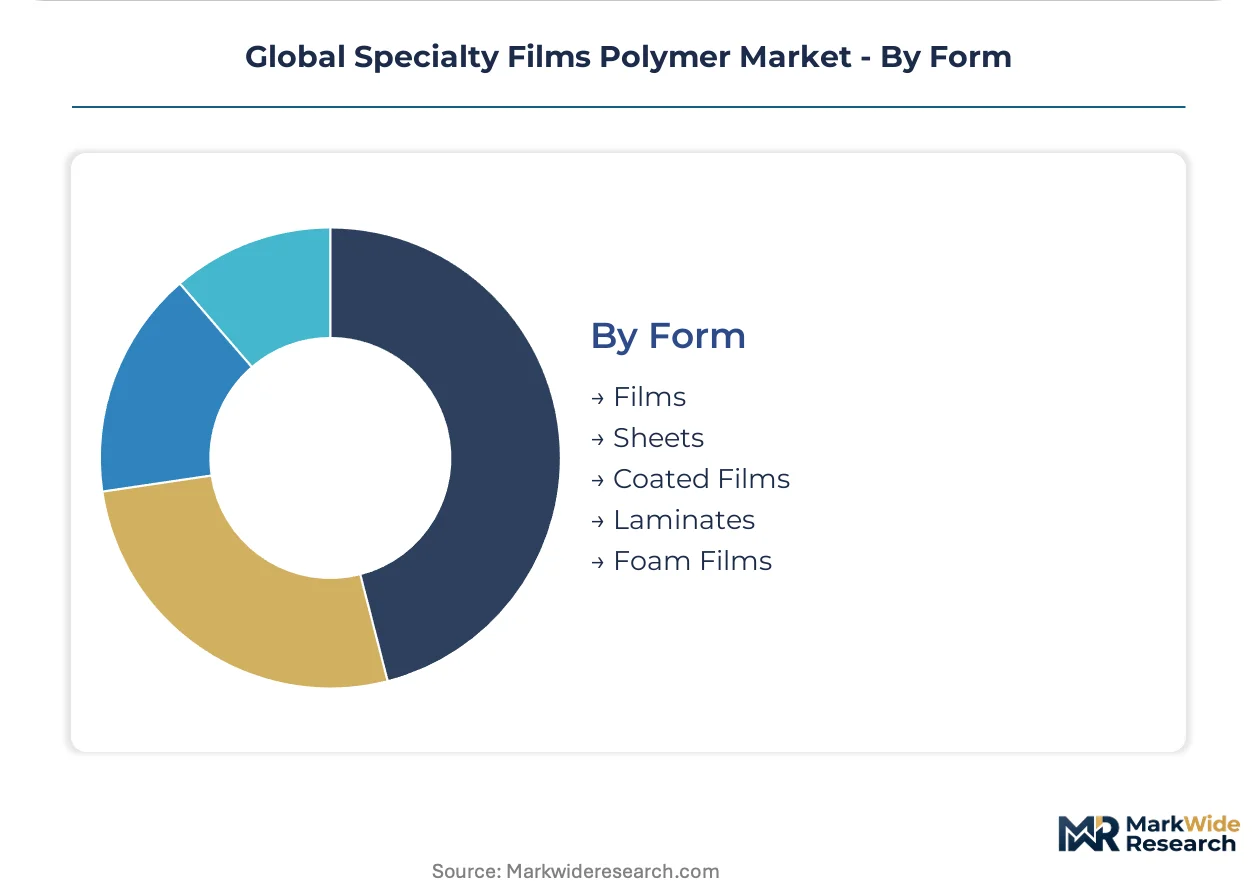
- Films:Unconverted roll stock serves high-volume packaging and lamination operations where in-line processing minimizes handling damage.
- Coated Films:Solvent-based and aqueous dispersion coatings add functional layers for adhesion promotion, barrier enhancement, or antistatic properties. China's Ministry of Ecology and Environment dual carbon goals compel domestic producers toward water-based coating lines.
- Laminates:Multi-ply structures combine incompatible polymers through adhesive or extrusion lamination for synergistic barrier and mechanical properties.
- Sheets:Thicker-gauge thermoformable substrates serve blister packaging and industrial forming applications.
- Foam Films:Cellular structures provide cushioning and thermal insulation in automotive interior trim and building applications.
Coated films command the steepest expansion trajectory as environmental compliance reshapes conversion technology choices. Foam films remain the most mature format with limited innovation pipeline and stable end-use penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China hosts the dominant share of specialty films polymer production capacity, while consumption spreads across automotive, electronics, and packaging end-uses in Germany, Japan, and the United States. This geographic split creates trade flows of engineered films from East Asian extrusion clusters toward European and North American manufacturing centers.
China
Jiangsu and Zhejiang provinces concentrate integrated film extrusion infrastructure serving domestic appliance brands and export packaging converters. The Ministry of Ecology and Environment enforces dual carbon goals that compel solvent-based coating lines to convert toward aqueous dispersion technologies before 2027. Shanghai and Suzhou-based producers absorb the highest compliance costs as they retool lamination equipment.
Germany
Automotive tier-one suppliers in Baden-Württemberg and Bavaria consolidate qualified polymer film vendors into multi-year framework agreements for EV battery module specifications. REACH substance restrictions from the European Chemicals Agency limit phthalate plasticizers in food-contact applications, redirecting formulation investment toward bio-based alternatives. The Rhine-Main industrial corridor hosts precision biaxial orientation equipment for sub-25-micrometer electrical insulation films.
United States
Flexible circuit substrate producers in California and Texas demand material purity specifications exceeding standard industrial grades for 5G antenna applications. The Food and Drug Administration maintains 21 CFR food additive regulations governing migration limits for polymer additives in direct-contact packaging. Midwestern converters in Ohio and Illinois serve graphic arts and industrial lamination markets with PET and polycarbonate roll stock.
Japan
Food packagers in the Kanto and Kansai regions accelerate trial adoption of transparent high-barrier polypropylene structures for premium ready-meal segments. The Ministry of Economy, Trade and Industry promotes advanced materials development through coordinated industry-academia programs. Nagoya-based film processors supply retort-compatible coextrusion technologies displacing metalized laminates in shelf-stable pouch formats.
South Korea
Display and battery module manufacturers in Gyeonggi Province specify optical clarity and dielectric resistance in thin-gauge polycarbonate membranes. The Ministry of Food and Drug Safety aligns food-contact material rules with international standards, creating qualified-supplier differentiation for halogen-free formulations. Busan-Ulsan petrochemical complexes feed integrated film extrusion operations serving domestic electronics brands and export markets.
Global Specialty Films Polymer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct technology tiers in the specialty films polymer market. Consolidation patterns favor multi-material platforms capable of spanning electrical insulation, barrier packaging, and optical display applications. Three strategic archetypes dominate: integrated chemical producers with captive resin supply, precision extrusion specialists with equipment-locked process knowledge, and application-focused converters with formulation partnerships. Capacity expansion and technology licensing represent the dominant competitive moves as players seek to anchor supply relationships with automotive and electronics OEMs.
Within the integrated chemical producer tier, Covestro AG and BASF SE exemplify European-based material science platforms with polycarbonate and polyamide-polyolefin extrusion capabilities. DuPont de Nemours, Inc. occupies a position among North American high-performance polymer specialists serving dielectric and thermal management applications. These three companies represent divergent strategic postures: resin-backward integration, coextrusion technology differentiation, and premium polyimide segment concentration.
| Leading Market Players |
|---|
| Covestro AG |
| 3M Company |
| BASF SE |
| Eastman Chemical Company |
| SABIC |
| DuPont de Nemours, Inc. |
| Solvay SA |
| Mitsubishi Chemical Group Corporation |
| Toray Industries, Inc. |
| Others |
Supply & Pricing Matrix
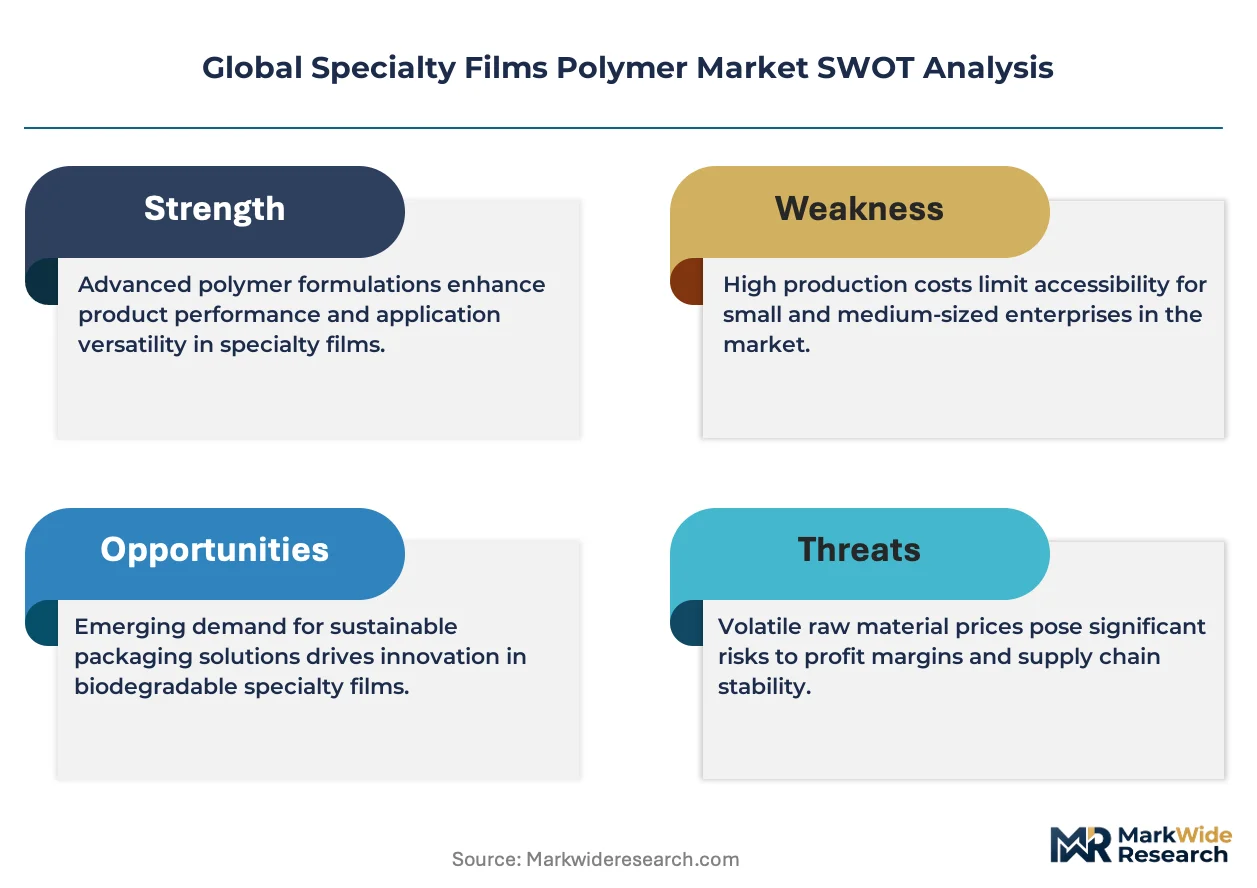
Captive resin supply through backward integration into bisphenol A and aromatic diacid feedstocks anchors pricing power for integrated chemical producers while forcing merchant converters into volatile spot-market exposure for specialty resin inputs.
Pricing Analysis
Margin tightening in standard-grade polyethylene terephthalate reflects biaxial orientation equipment oversupply in China's Jiangsu province. Three-tier pricing structure across automotive-qualified, food-contact certified, and industrial commodity grades separates dielectric-specification polycarbonate from packaging-grade polypropylene. REACH compliance costs and FDA 21 CFR migration testing timelines add certification premiums that commodity buyers resist. Electronics manufacturers in Germany and South Korea show lowest price sensitivity, accepting multi-year framework premiums for thermal stability guarantees.
Supply Chain Analysis
Freight cost differentials between German precision machinery imports and domestic Chinese extrusion lines widen total cost gaps for sub-25-micrometer film specifications. Production gravity centers on China, Germany, and Japan, with Jiangsu-Zhejiang clusters feeding export converters in Ohio and Illinois. Raw material flows draw from Saudi petrochemical complexes for polypropylene resin and Belgian bisphenol A supply for polycarbonate film. Single-source vulnerability concentrates in Japanese and German biaxial orientation equipment suppliers. Distribution runs through regional master distributors holding qualified-supplier inventory for automotive and food-contact tier-one buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around multi-material platform capabilities, with REACH compliance timelines and automotive qualification protocols forcing sub-scale formulators toward exit or acquisition.
For Market Incumbents: Anticipate halogen-free formulation mandates by securing bio-based adipate ester supply agreements before 2027 conversion deadlines. Deepen captive resin supply through backward integration into aromatic diacid feedstocks to compress margin exposure. Defend automotive vendor pool position by accelerating polycarbonate thickness-tolerance certification with Baden-Württemberg tier-one suppliers.
For New Entrants and Emerging Players: The premium-economy price gap in Indian food-contact films creates entry space for FSSAI-qualified halogen-free polypropylene suppliers. Target aqueous dispersion coating technology licensing to Jiangsu province converters facing Ministry of Ecology and Environment dual carbon deadlines. Lead with toll-coating partnerships rather than capital-intensive extrusion capacity.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated chemical conglomerates seeking polyimide or polycarbonate film capabilities. Five-to-ten-year viability favors precision extrusion specialists with equipment-locked process knowledge over commodity converters. Monitor automotive battery pouch cell procurement consolidation rates as inflection signal for qualified-supplier scarcity premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bisphenol A Feedstock | Covestro AG and BASF SE anchor margin control against crude derivative volatility. |
| Aqueous Dispersion Technology Licensing | Domestic Chinese producers absorb Ministry of Ecology and Environment compliance costs through technology transfer. |
| Long-term Supply Agreement with Automotive Tier-Ones | German and South Korean battery module manufacturers consolidate qualified vendor pools into multi-year frameworks. |
| Joint Venture for Polyimide-PEN Hybrid Film Capacity | DuPont de Nemours and Toray Industries target 5G antenna substrate roll-to-roll processing demand. |
| Green Manufacturing Transition to Halogen-Free Formulations | European Chemicals Agency REACH restrictions redirect formulation investment toward phosphorus-nitrogen systems. |
Research Methodology
Trade databases, European Chemicals Agency REACH substance restriction filings, and SEC 10-K disclosures from diversified chemical producers formed the secondary backbone. Primary interviews with plant managers at Jiangsu and Zhejiang extrusion clusters, procurement leads at German automotive tier-one suppliers, and technical R&D directors at polyimide specialists combined with bottom-up and top-down triangulation. Customs records for biaxial orientation equipment imports and food-contact migration testing certification timelines provided volume and qualification pipeline validation.
Bottom-up modeling aggregated segment-level consumption across packaging, electrical insulation, and automotive applications, while top-down cross-checks validated aggregate market scale against petrochemical feedstock demand indicators. Segmentation dimensions included polymer chemistry grade, end-use industry qualification tier, coating technology format, and regional regulatory cluster. CAGRs derived from trend extrapolation of biaxial orientation capacity utilization rates and automotive battery procurement growth patterns. Forecast inputs incorporated Ministry of Ecology and Environment dual carbon compliance deadlines and FDA 21 CFR additive qualification timelines.
Inputs from equipment suppliers and trade databases were available through the study window; gaps in proprietary formulation cost structures introduce uncertainty bands around margin compression estimates. Forecasts reflect assumptions about REACH enforcement consistency and automotive qualification protocol stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Asia-Pacific Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market
Poly film
Thermoplastic Polyurethane (TPU) Films Market
Poly film
Global Blown Stretch Packaging Films Market
Poly film
Silicone-Coated PET Films Market
Poly film
Bopet Films Market
Poly film
PCR Bubble Films Market
Poly film
Middle East and Africa Plastic Packaging Films Market
Poly film
Polypropylene Film Market
Poly film
Recyclable Lidding Films Market
Poly film
US Cleanroom Film and Bags Market
Poly film
Resealable Films Market
Poly film
Cleanroom Film and Bags Market
Poly film
Global Cast Polypropylene Packaging Films Market
Poly film
Global EVOH Films for Packaging Market
Poly film
Cellulose Film Packaging Market
Poly film
Lidding Films Market