
 Peelable and Resealable Films Market | 2026-2036
Peelable and Resealable Films Market Size, Share, and Industry Trends Forecast 2026-2036
Peelable and Resealable Films Market Analytics
Subscription-based packaging redesign services is consolidating how converters sell peelable and resealable films, shifting transactions toward ongoing technical partnerships. ProAmpac leverages its vertical integration across film extrusion and lamination to control cost structures for resealable lidding. Sealed Air anchors its position through proprietary easy-open technologies deployed across North American protein packaging. Amcor competes by extending its global manufacturing footprint into Southeast Asian flexible packaging hubs.
Peelable and resealable films are multilayer polymer structures, typically coextruded with differential seal layers that fracture at controlled force while preserving reseal integrity through pressure-sensitive adhesives or interlocking zip mechanisms. These films serve primarily to extend product accessibility cycles in perishable goods packaging while reducing material waste from discarded overwraps. Polyethylene formulations dominate volume production due to cost efficiency and broad seal-range compatibility, though biodegradable alternatives are gaining fastest growth as European supermarkets enforce plastic-reduction targets. Food packaging applications command the largest margin pools, while medical supplies represent a specialized segment where sterilization barrier properties justify premium positioning.
FDA food-contact substance notifications govern material migration limits in the United States, while EFSA and REACH collectively determine acceptable polymer chemistries and additive packages across Europe. These frameworks push manufacturers toward monomaterial constructions that simplify end-of-life sorting and mechanical recycling compatibility. Stakeholders must monitor evolving extended producer responsibility schemes and recyclability labeling mandates that will determine which film constructions retain market access.
Market Dynamics
Monomaterial film constructions are forcing a wholesale redesign of multilayer supply chains as European supermarkets enforce plastic-reduction targets and mechanical recycling compatibility becomes a gating factor for shelf access.
Growth Catalysts
- EU Green Deal packaging mandates:The EU Green Deal and F-Gas Regulation are accelerating demand for biodegradable alternatives by penalizing conventional multilayer films that complicate end-of-life sorting.
- Food processing cluster concentration:Germany, France, and Italy anchor European demand as protein processors and dairy brands adopt extended shelf-life lidding solutions to reduce spoilage-related losses.
- Pressure-sensitive adhesive advances:New interlocking zip mechanisms and peel-force calibration technologies are expanding reseal integrity across broader temperature ranges for chilled distribution.
Market Restraints
- Ethylene feedstock volatility:Polyethylene formulations dominate volume production, leaving converters exposed to naphtha-linked raw material swings that compress margin predictability.
- Specialty adhesive supply concentration:Pressure-sensitive and cohesive sealant chemistries rely on a narrow base of European and Japanese specialty chemical suppliers, creating single-source vulnerability.
- Monomaterial performance ceiling:Simplified polymer constructions struggle to match barrier properties of legacy multilayer structures, limiting adoption in high-sensitivity medical and pharmaceutical applications.
Strategic Opportunities
- Medical supplies sterilization barriers:Premium positioning in healthcare packaging remains underexploited as hospitals and device manufacturers seek validated resealable solutions that maintain sterile field integrity.
- Extended producer responsibility tailwinds:Evolving EPR schemes and recyclability labeling mandates in France, Italy, and Germany will favor early movers with certified monomaterial constructions.
- Subscription-based technical partnerships:Converters can capture recurring revenue by embedding redesign services into ongoing supply agreements rather than transactional film sales.
Industry Challenges
- Multilayer equipment retooling:Transitioning extrusion and lamination lines to monomaterial-compatible configurations demands substantial capital deployment and extended downtime.
- Migration testing complexity:FDA food-contact substance notifications and EFSA compliance timelines for novel polymer chemistries extend commercialization cycles by months.
- Cross-functional formulation expertise:Bridging polymer science, adhesive chemistry, and packaging engineering skill sets remains difficult as academic programs lag industry need.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peelable and Resealable Films Market |
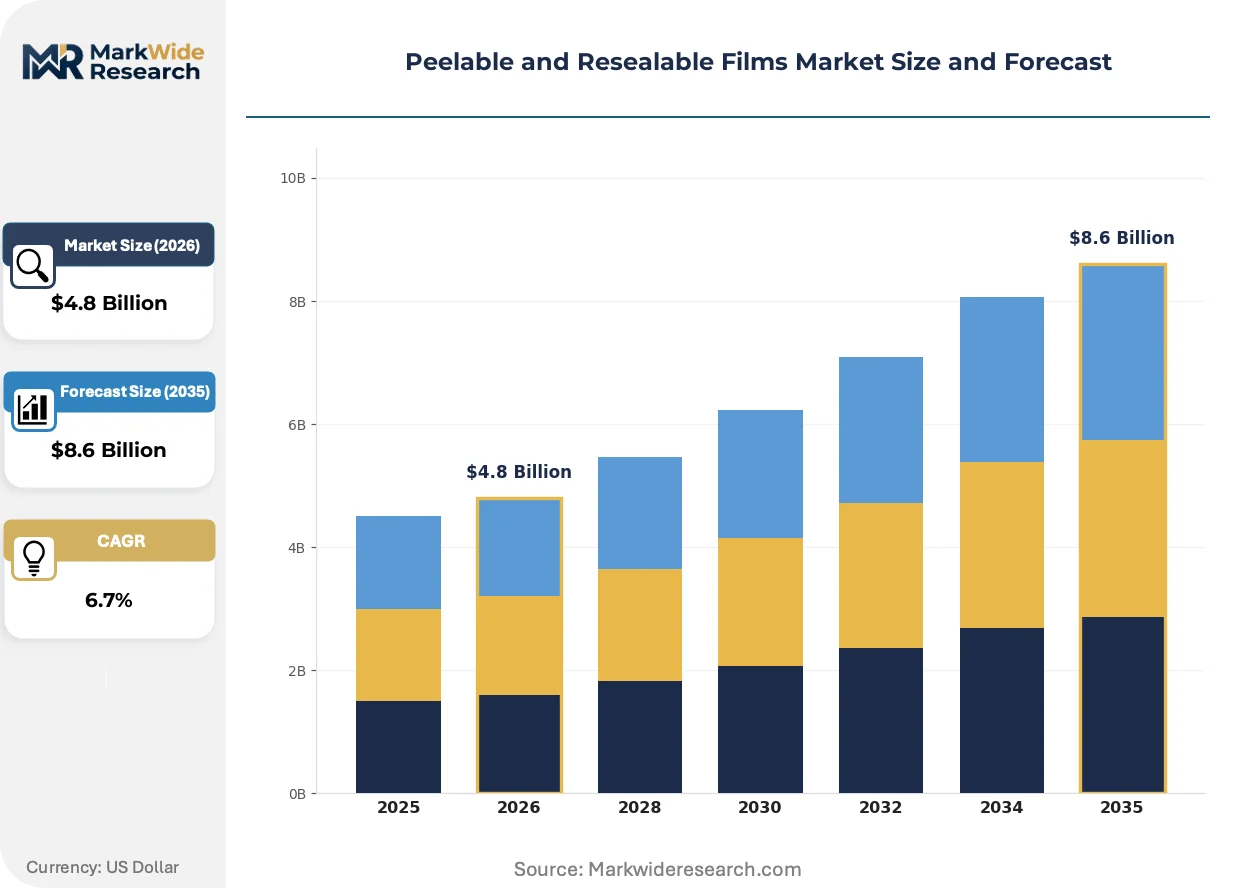
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Nylon, Biodegradable Application: Food Packaging, Medical Supplies, Consumer Products, Personal Care Form: Rolls, Sheets, Pouches, Bags End User: Manufacturers, Retailers, Distributors, E-commerce |
| Companies Covered | ProAmpac, Sealed Air, Amcor, Uflex Limited, Sappi Rockwell Solutions, Toray Plastics, Berry Global, Mondi Group, DuPont Teijin Films, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peelable and Resealable Films Market Evolving Landscape
Active and intelligent packaging functionalities are converging with resealable film platforms, creating hybrid structures that communicate freshness status while maintaining consumer accessibility. This fusion is redefining value capture models across the value chain.
Monomaterial polyethylene constructions with differential seal layers are integrating coextrusion advances to achieve controlled fracture forces without sacrificing reseal integrity. Dairy and fresh protein packagers in Germany and France are adopting these structures at accelerating rates. The technology is integrating mechanical recycling compatibility into premium food packaging tiers previously dominated by non-recyclable multilayer alternatives.
REACH and the EU F-Gas Regulation are tightening acceptable additive packages and fluorinated barrier chemistries across European polymer formulations. Industrial consequence includes accelerated R&D spending on bio-based sealants and mineral-filled barrier layers. Medical device packaging and high-acid food categories face the steepest compliance curves, with converters in Italy and Spain restructuring supplier qualification protocols.
Brand-led sustainability scorecards are compressing supplier evaluation cycles and unbundling after-sales technical support from base film pricing. Retailer consolidation in France and Germany is concentrating buying power among fewer procurement teams that demand documented recyclability credentials. This pattern is most visible in private-label dairy and prepared meals, where Lidl and Carrefour technical teams now specify monomaterial constructions as default requirements.
Peelable and Resealable Films Market Segmentation
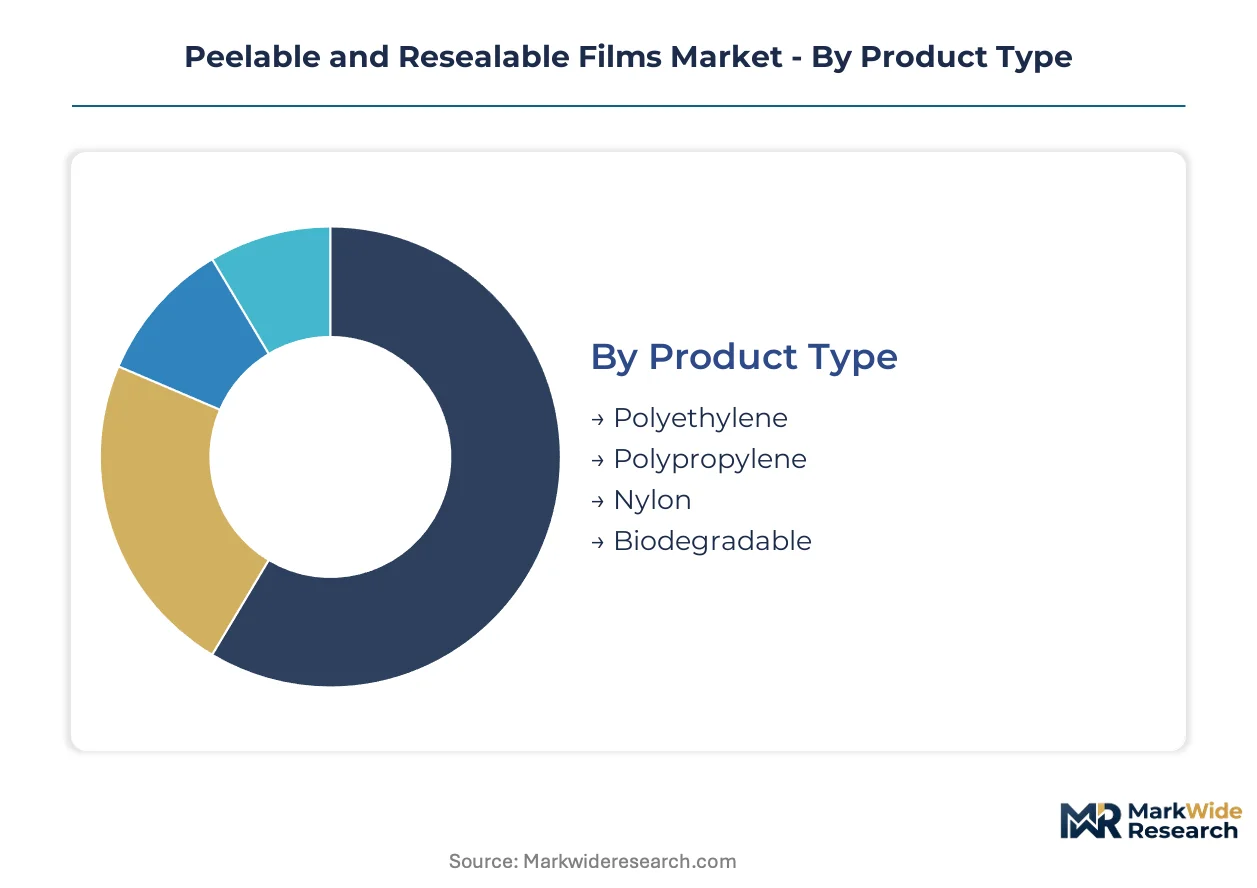
Peelable and resealable films serve heterogeneous use cases requiring distinct material specifications, barrier properties, and conversion formats. Segmentation reveals where formulation investments concentrate and which application clusters justify premium pricing tiers.
Product Type:
Material upgrade cycles are shortening as European supermarkets enforce plastic-reduction targets and mechanical recycling compatibility becomes a gating factor for shelf access.
- Polyethylene:Coextruded structures with differential seal layers dominate volume production due to cost efficiency and broad seal-range compatibility. Dairy processors in Germany and France specify these formulations for extended shelf-life lidding where controlled fracture forces preserve reseal integrity across chilled distribution.
- Biodegradable:Bio-based sealants and mineral-filled barrier layers are gaining fastest growth as the EU Green Deal and F-Gas Regulation penalize conventional multilayer films that complicate end-of-life sorting. Italian and Spanish converters are restructuring supplier qualification protocols to meet retailer sustainability scorecards.
- Polypropylene:Higher clarity and heat resistance serve prepared meal applications requiring microwave compatibility.
- Nylon:Oxygen barrier properties justify positioning in high-sensitivity medical and pharmaceutical applications where sterilization integrity is paramount.
Polyethylene sits at the top of the volume ranking, with biodegradable climbing the fastest.
Application:
Margin concentration follows spoilage sensitivity and regulatory burden, with healthcare packaging commanding premium positioning despite smaller addressable volume.
- Food Packaging:Protein processors and dairy brands adopt extended shelf-life lidding solutions to reduce spoilage-related losses. Monomaterial polyethylene constructions with differential seal layers are displacing non-recyclable multilayer alternatives in private-label programs at Lidl and Carrefour.
- Medical Supplies:Sterilization barrier properties and validated resealable solutions that maintain sterile field integrity justify premium positioning. Hospitals and device manufacturers face steep compliance curves under REACH and MDR requirements.
- Consumer Products:Pressure-sensitive adhesive advances expand reseal integrity for household goods where repeated access cycles drive purchase decisions.
- Personal Care:Aesthetic and tactile requirements influence film specification for cosmetics and hygiene products with premium brand positioning.
Food packaging captures the dominant revenue share, while medical supplies deliver the highest margin per square meter.
Form:
Conversion format selection determines equipment compatibility and downstream automation integration for packagers.
- Rolls:Continuous web formats serve high-speed form-fill-seal operations across protein and dairy processing lines in Germany, France, and Italy.
- Pouches:Pre-formed resealable structures reduce capital requirements for smaller processors and enable rapid format switching.
- Sheets:Cut-to-size formats support manual packaging operations and specialty short-run applications.
- Bags:Stand-up and lay-flat configurations with integrated zip mechanisms serve retail-ready presentation requirements.
Rolls maintain production volume leadership, with pouches expanding most quickly among mid-tier processors seeking operational flexibility.
End User:
Procurement authority is shifting from transactional film purchasing toward ongoing technical partnerships with documented recyclability credentials.
- Manufacturers:Brand-led sustainability scorecards compress supplier evaluation cycles for protein processors and dairy packagers. EPR schemes in France, Italy, and Germany favor converters with certified monomaterial constructions.
- Retailers:Consolidated buying power among Lidl and Carrefour technical teams now specifies monomaterial constructions as default requirements for private-label programs.
- Distributors:Inventory and logistics networks intermediate between converters and smaller end-users with fragmented demand patterns.
- E-commerce:Fulfillment requirements for repeated access and return logistics create specialized demand for durable reseal performance.
Manufacturers direct the largest procurement volumes, with retailers gaining fastest influence over specification standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converters are relocating production toward jurisdictions with streamlined chemical registration pathways and lower EPR compliance costs. Germany and France absorb capital from higher-regulation markets seeking mechanical recycling certification advantages. Southeast Asian hubs attract investment through flexible additive approval timelines.
Germany
Dairy processors in Bavaria and North Rhine-Westphalia specify monomaterial polyethylene lidding for extended shelf-life applications. The national packaging act implements strict EPR quotas that favor certified recyclable constructions. The Munich-Stuttgart corridor hosts converter clusters retooling extrusion lines for differential seal layer technologies.
France
Carrefour and Lidl procurement teams mandate monomaterial defaults across private-label prepared meals and fresh protein lines. EPR schemes in France impose escalating fees on non-recyclable multilayer structures. The Île-de-France and Hauts-de-France regions concentrate thermoforming operations serving Paris Basin retail distribution.
Italy
Specialty cheese and cured meat packagers adopt biodegradable sealants to meet retailer sustainability scorecards. REACH compliance timelines for novel polymer chemistries extend qualification cycles for imported materials. Emilia-Romagna and Lombardy anchor the national flexible packaging conversion base.
United States
FDA food-contact substance notifications govern migration limits for resealable lidding in protein packaging. The Chicago-Milwaukee corridor and California's Central Valley host dairy and fresh produce processing clusters. Converters prioritize polyethylene formulations to manage ethylene feedstock exposure.
China
Domestic dairy brands accelerate resealable pouch adoption for premium yogurt and fresh cheese segments. SAMR and GB standards regulate food-contact polymer additives with increasing stringency. The Yangtze River Delta and Pearl River Delta concentrate film extrusion capacity serving regional consumer goods demand.
Peelable and Resealable Films Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated converters capturing margin in high-volume food applications and independent film suppliers serving specialized medical niches. The vendor base clusters around three archetypes: vertically integrated packaging conglomerates controlling extrusion through lamination, regional specialists with captive adhesive formulation capabilities, and toll converters serving private-label programs. Consolidation pressures intensify as EPR mandates favor scale players with certified recycling streams. Competitive moves center on backward integration into resin compounding and strategic partnerships with retailer technical teams.
Among North American integrated converters, ProAmpac and Sealed Air occupy positions spanning film extrusion and value-added lamination. Amcor anchors the Asia-Pacific expansion vector through manufacturing presence in Southeast Asian flexible packaging hubs. These three exemplify the scale-driven archetype where captive supply chains and proprietary easy-open technologies defend positioning against commodity film imports.
| Leading Market Players |
|---|
| ProAmpac |
| Sealed Air |
| Amcor |
| Uflex Limited |
| Sappi Rockwell Solutions |
| Toray Plastics |
| Berry Global |
| Mondi Group |
| DuPont Teijin Films |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between monomaterial-compliant films and legacy multilayer structures manifests in both pricing stratification and supply chain reconfiguration across European and North American markets. EPR fee differentials in France and Germany compress margins on non-recyclable constructions while rewarding certified supply chains with shelf-access premiums.
Pricing Analysis
Distributor markups on specialty adhesive formulations widen spreads between commodity polyethylene lidding and monomaterial-certified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification status, with EPR-compliant monomaterials commanding tier-one positioning. Cost compression in standard-grade polyethylene runs through ethylene feedstock volatility linked to naphtha pricing. Small-to-mid dairy processors exhibit highest price sensitivity, while Carrefour and Lidl procurement teams prioritize recyclability credentials over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from German and French protein processors seeking integrated extrusion-lamination partnerships. Raw material sourcing draws from Saudi ethylene crackers, Belgian specialty adhesive compounders, and Thai biopolymer producers. Single-source vulnerability concentrates in pressure-sensitive cohesive sealant chemistries from Japanese and European suppliers. Distribution runs through converter-owned logistics networks serving Bavaria and North Rhine-Westphalia dairy clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The peelable and resealable films market functions as a stable compounder anchored by regulatory tailwinds from EU Green Deal packaging mandates that institutionalize demand for certified recyclable constructions.
For Market Incumbents: Deepen backward integration into resin compounding to offset ethylene feedstock volatility and capture EPR compliance premiums. Invest in differential seal layer R&D to defend against biodegradable substitute technologies. Prioritize captive adhesive formulation capabilities to reduce single-source exposure from Japanese specialty chemical suppliers. For New Entrants and Emerging Players: Begin with medical supplies sterilization barriers where validated resealable solutions face limited competition and justify premium positioning. Target Italian and Spanish converters restructuring supplier qualification protocols under REACH timelines. Deploy subscription-based technical partnerships rather than transactional film sales to establish recurring revenue footholds. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists possessing captive adhesive formulation and certified monomaterial production lines. Long-term viability centers on EPR scheme expansion across European jurisdictions. Watch for France and Germany escalating fees on non-recyclable multilayer structures as the inflection signal for accelerated consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive ethylene sourcing insulates ProAmpac and Sealed Air from naphtha-linked margin compression. |
| Monomaterial Certification Program | EPR-compliant constructions secure shelf access at Carrefour and Lidl private-label programs. |
| Specialty Adhesive Partnership | Collaboration with European and Japanese suppliers reduces single-source vulnerability for cohesive sealants. |
| Medical Device Packaging Validation | Sterilization barrier credentials unlock premium positioning in healthcare applications under MDR requirements. |
| Subscription-Based Technical Services | Recurring revenue models shift converter relationships from transactional film sales to ongoing redesign partnerships. |
Research Methodology
Multiple input streams — converter production data, retailer procurement specifications, and regulatory filing databases — were reconciled to construct demand estimates. Primary interviews with film extrusion plant managers, dairy procurement leads, flexible packaging R&D directors, and EPR scheme administrators informed operational assumptions. Secondary validation drew from ECHA substance registrations, EU Green Deal implementation reports, SEC 10-K disclosures from listed packaging conglomerates, and French and German packaging act compliance records. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Data-stream reconciliation across product type, application, form, and end-user dimensions shaped the analytical framework throughout the projection horizon. CAGRs were derived from segment-level growth trajectories weighted by revenue contribution. Modeled inputs included EPR fee escalation schedules in France and Germany, ethylene-naphtha spread forecasts, and REACH compliance timeline assumptions for novel polymer chemistries.
Several conditions sit outside the modeled scope, including potential F-Gas Regulation amendments, breakthrough biodegradable barrier technologies, and trade policy shifts affecting ethylene feedstock flows. Forecasts reflect assumptions about regulatory enforcement consistency and mechanical recycling infrastructure deployment. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Bi-Axially Oriented Polypropylene (BOPP) Market
Poly film
Soft Touch Lamination Film Market
Poly film
Polypropylene Film Market
Poly film
Printed Plastic Films Market
Poly film
Polyethylene Film Market
Poly film
India BOPP Films Market
Poly film
Foamed Polypropylene Films Market
Poly film
Polyethylene Furanoate Films Market
Poly film
Japan Polypropylene Packaging Films Market
Poly film
France Plastic Packaging Films Market
Poly film
Bopet Films Market
Poly film
Poly Coated Paper Market
Poly film
Silicone Release Films Market
Poly film
Europe Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market
Poly film
Easy Peel Film Packaging Market
Poly film
Latin America Polypropylene (PP) Packaging Film Market