

PCR Lidding Films Market Size, Share, and Industry Trends Forecast 2026-2036
PCR Lidding Films Market Insights
A capital-intensity divergence between coextrusion-equipped multinationals and regional converters is reorganizing competitive tiers in PCR lidding films. Amcor leverages integrated resin compounding and film extrusion across European and North American plants to sustain margin control. Constantia Flexibles anchors its position through specialized pharmaceutical-grade lidding with barrier coating expertise. Mondi Group competes via lightweighting innovations that reduce seal-layer resin volumes without compromising peel integrity.
PCR lidding films are heat-sealable multilayer structures, typically 25–75 micrometers thick, engineered from polypropylene, polyethylene, or PET substrates with sealant coextrusions or lacquer coatings to enable hermetic closure of trays, cups, and containers across modified-atmosphere and vacuum packaging lines. Polypropylene dominates film type selection due to its balanced seal initiation temperature and post-consumer recyclability profile, while laminates command premium positioning where oxygen transmission rates below 1 cc/m²/day are mandatory for protein packaging. Food packaging anchors application demand, though pharmaceutical sealing represents the fastest-expanding margin pool as blister-format compliance tightens across EU member states.
The EU Green Deal and REACH frameworks mandate escalating post-consumer recycled content thresholds in packaging substrates, directly reshaping resin sourcing strategies and film certification requirements for suppliers accessing European consumer goods channels. FDA food contact notification pathways govern US market entry for novel PCR-containing sealant layers, adding validation timelines that favor incumbent players with established regulatory dossiers. Stakeholders must monitor evolving EFSA opinions on mechanical recycling process equivalency, as these determinations will decide which PCR feedstocks qualify for broad food-contact approval without functional barrier layer requirements.
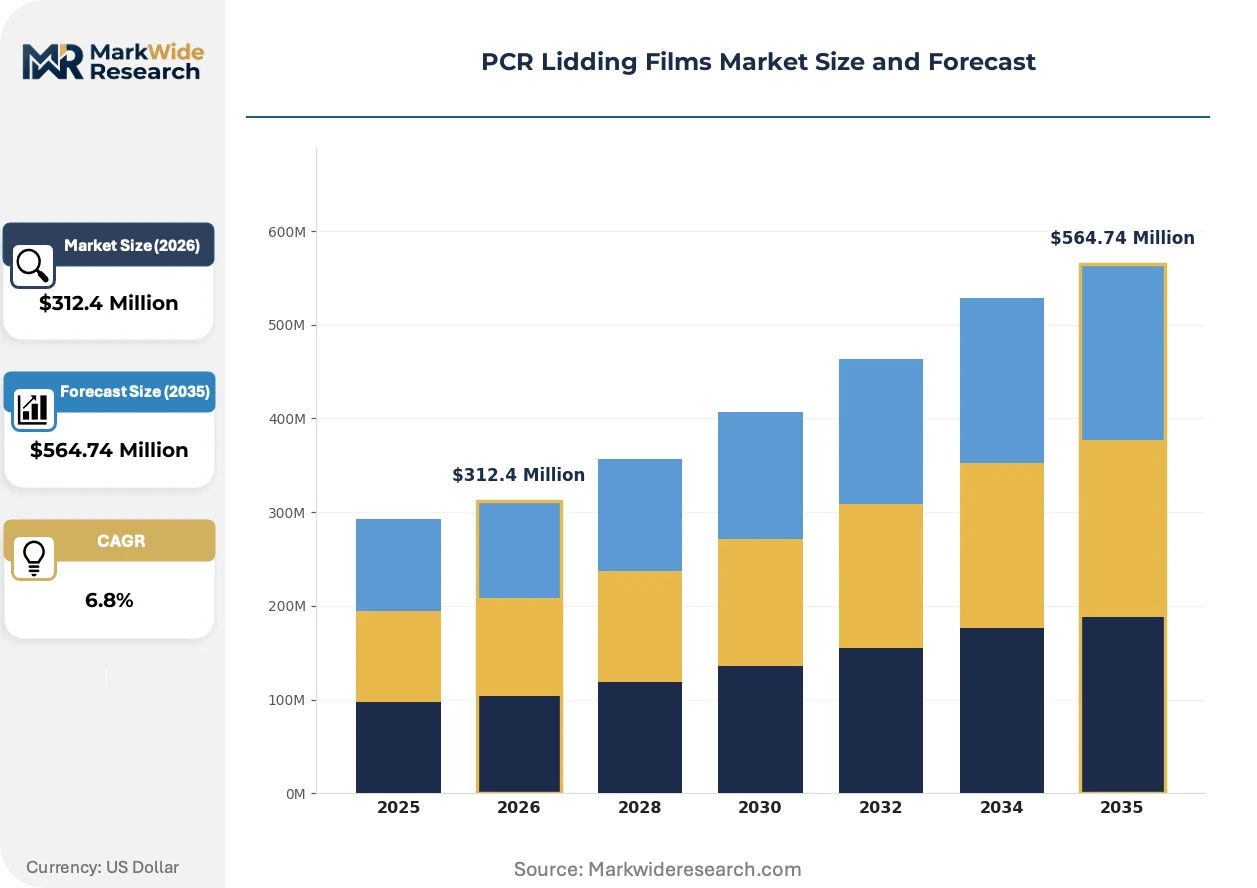
Market Dynamics
EU Green Deal recycled content mandates are forcing packaging converters to requalify entire film portfolios for post-consumer resin compatibility, compressing formulation development cycles and resin sourcing flexibility.
Growth Catalysts
- EU Green Deal recycled content mandates:Escalating thresholds for post-consumer resin in packaging substrates pull film manufacturers toward PCR-qualified sealant formulations.
- Modified-atmosphere protein packaging:Extended shelf-life requirements in fresh meat and seafood segments drive oxygen barrier specifications that favor advanced multilayer lidding structures.
- German food packaging converter concentration:Dense clustering of tray-sealing operations in Bavaria and Baden-Württemberg creates localized demand pull for high-performance peelable films.
Market Restraints
- Post-consumer resin feedstock volatility:Collection infrastructure gaps and bale quality inconsistency in Southern and Eastern Europe constrain supply predictability for film-grade PCR.
- Mechanical recycling process equivalency uncertainty:Pending EFSA opinions on which PCR streams qualify for direct food contact without functional barriers freeze investment decisions.
- Monomaterial polypropylene substitution threat:Simplified recyclable structures from competing substrate categories pressure multilayer laminate market share in non-barrier applications.
Strategic Opportunities
- Pharmaceutical blister compliance tightening:EU member state enforcement of child-resistant and senior-friendly lidding standards opens margin-rich specialized film segments.
- Lightweighting seal-layer innovation:Downgauging technologies that maintain peel integrity at reduced resin volumes address brand owner plastic reduction commitments.
- Chemical recycling feedstock integration:Pyrolysis-derived resin streams offer pathway to food-contact approved PCR outside mechanical recycling constraints.
Industry Challenges
- Coextrusion equipment capex intensity:Seven-layer blown film lines required for high-barrier structures demand capital commitments that regional converters struggle to fund.
- Multi-jurisdiction food contact notification timelines:FDA dossier preparation and EFSA scientific opinion processes extend product launch cycles by 18-36 months for novel sealant layers.
- Polymer science and regulatory affairs talent scarcity:Competition for specialists who bridge materials engineering and compliance documentation limits R&D throughput at mid-scale manufacturers.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PCR Lidding Films Market Trends and Innovations
Active developments across material science, regulatory interpretation, and buyer procurement models are compressing traditional competitive advantages and opening new capability-based differentiation paths.
Barrier coating technologies using silicon oxide or aluminum oxide deposition are decomposing the historical trade-off between oxygen transmission performance and post-consumer recyclability. Fresh protein packagers in the Netherlands and Denmark are qualifying these coated monomaterials at pace. The shift is decomposing established laminate supply relationships as converters bypass traditional multilayer suppliers.
REACH framework amendments on microplastics and the EU Packaging and Packaging Waste Regulation proposal are tightening definitions of recyclable packaging. Film manufacturers must now demonstrate compatibility with existing sorting and reprocessing infrastructure. Pharmaceutical and food segments face divergent compliance timelines, with medical device packaging converters accelerating qualification work ahead of stricter enforcement.
Brand owner procurement teams are consolidating supplier panels and demanding audited chain-of-custody documentation for PCR content claims. Direct contracting between multinational consumer goods companies and resin compounders is displacing distributor-mediated purchasing in Germany and France. This concentration is most visible in dairy and ready-meal segments where sustainability scorecards determine allocation of volume commitments.
PCR Lidding Films Market Segmentation
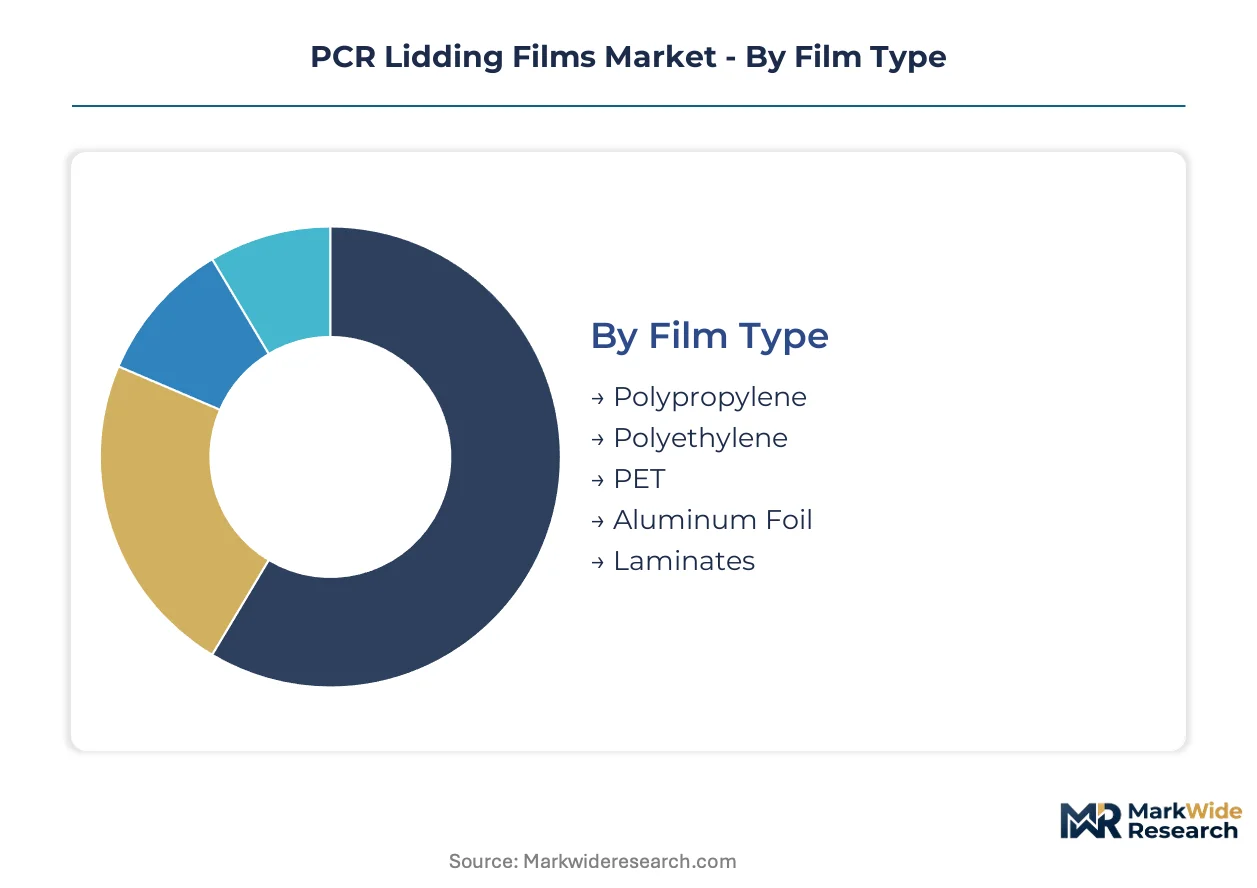
PCR lidding films serve heterogeneous sealing requirements across protein packaging, pharmaceutical compliance, and industrial containment. Segment boundaries reflect divergent technical specifications, regulatory pathways, and procurement consolidation patterns that reshape supplier competitive positioning.
Film Type:
Domestic demand in Germany and France concentrates on polypropylene and polyethylene variants, while export-oriented supply from Benelux converters favors laminates and aluminum foil for premium barrier applications.
- Polypropylene:Heat-sealable homopolymer and random copolymer grades dominate tray-sealing lines across Bavarian meat processors. Balanced seal initiation temperature and established mechanical recycling streams support EU Green Deal compliance trajectories without functional barrier layers.
- Laminates:Multilayer coextrusions with EVOH or PA tie layers achieve oxygen transmission below 1 cc/m²/day for Dutch fresh seafood exporters. Seven-layer blown film investment thresholds concentrate supply among coextrusion-equipped multinationals serving modified-atmosphere protein segments.
- Polyethylene:Linear low-density formulations serve dairy cup lidding across Baden-Württemberg converters with lower seal initiation than polypropylene alternatives.
- PET:Biaxially oriented substrates with heat-seal lacquers target pharmaceutical blister compliance in German and French packaging corridors.
- Aluminum Foil:Ultra-high barrier deadfold structures retain share in retort pouch and pharmaceutical applications despite recyclability scoring penalties under emerging PPWR frameworks.
Polypropylene holds the largest share; momentum sits with laminates as barrier specifications tighten for protein shelf-life extension.
Application:
Cost tier stratification separates commodity tray sealing from premium pharmaceutical and cosmetic segments requiring validated compliance documentation.
- Food Packaging:Modified-atmosphere tray lidding for fresh meat, seafood, and ready-meal segments consumes volume across German converter clusters. EFSA food-contact approval timelines for PCR sealant layers constrain formulation flexibility for mid-scale suppliers.
- Pharmaceutical Sealing:Child-resistant and senior-friendly peelable lidding for blister packs commands margin premiums as EU member state enforcement tightens. Barrier coating expertise and FDA notification dossiers create capability moats around specialized film manufacturers.
- Cosmetic Containers:Aesthetic peel clarity and fragrance barrier requirements drive specification diversity for French and Italian beauty brand supply chains.
- Industrial Packaging:Chemical resistance and puncture tolerance specifications serve automotive and electronics component containment with less stringent recycled content mandates.
- Chemical Bottling:Aggressive substance compatibility and induction seal integration requirements limit PCR content feasibility for hazardous material containment.
Food packaging anchors volume concentration; pharmaceutical sealing climbs fastest on compliance-driven specification premiums.
End User Industry:
Customer type fragmentation spans direct brand owner procurement consolidation and distributor-mediated purchasing for smaller cosmetic and chemical accounts.
- Consumer Goods Manufacturers:Multinational dairy and ready-meal brand owners in Germany and France demand audited chain-of-custody documentation for PCR content claims. Direct resin compounder contracting displaces traditional film distributor relationships as sustainability scorecards determine volume allocation.
- Pharmaceutical Producers:Packaging specification ownership sits with drug manufacturers rather than contract packagers, creating long qualification cycles and high switching costs for film suppliers. EMA and national competent authority oversight extends validation timelines.
- Cosmetic Brands:Premium positioning requirements prioritize aesthetic seal performance over recycled content percentages in current procurement frameworks.
- Chemical Suppliers:Functional containment specifications dominate material selection with limited PCR adoption due to aggressive substance compatibility constraints.
- Packaging Service Providers:Co-packing and toll-sealing operations in Benelux and Northern Italy aggregate fragmented demand from regional food and cosmetic brands.
Consumer goods manufacturers represent the dominant demand pool; pharmaceutical producers show steepest expansion trajectory on compliance specification premiums.
Form:
Supply concentration varies by form factor complexity, with roll stock and sheet formats serving high-volume converters while pre-cut and coated variants require specialized finishing capabilities.
- Roll Stock:Unwound directly across high-speed tray-sealing lines in German meat and dairy processing facilities. Wide-web extrusion economies and minimal downstream conversion preserve cost position for commodity applications with less stringent die-cut tolerance requirements.
- Pre-cut:Die-cut lids with registered printing and tamper-evident features serve pharmaceutical and premium cosmetic segments requiring precise dimensional tolerance. Tooling investment and changeover complexity concentrate supply among specialized converters in Switzerland and Southern Germany.
- Sheet:Cut-to-size formats for manual and semi-automatic sealing equipment serve smaller food processors and cosmetic packagers with lower capital intensity.
- Laminated:Multi-ply structures combining substrate, barrier, and sealant layers achieve performance specifications beyond monomaterial capabilities for protein shelf-life extension.
- Coated:Silicon oxide or aluminum oxide deposition on monomaterial substrates enables barrier performance with improved recyclability scores under PPWR sorting infrastructure tests.
Roll stock commands the largest volume position; pre-cut formats gain share fastest on pharmaceutical and premium cosmetic specification trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters command pricing premiums on pharmaceutical-grade specifications while Chinese suppliers undercut on commodity roll stock, creating a transatlantic margin spread that rewards barrier-coating specialists.
Germany
Bavarian meat processors and Baden-Württemberg dairy converters drive demand for high-performance peelable films with extended shelf-life specifications. The EU Green Deal's recycled content mandates force requalification of entire film portfolios for PCR compatibility. Munich and Stuttgart packaging corridors concentrate seven-layer coextrusion capacity among multinationals serving modified-atmosphere protein segments.
United States
Modified-atmosphere packaging lines across Midwest protein processing facilities pull advanced multilayer structures for retail-ready meat and seafood. FDA food contact notification pathways govern market entry for novel PCR-containing sealant layers, extending validation timelines. Chicago-area converter clusters favor established suppliers with dossier-ready regulatory documentation.
France
Paris-region dairy and ready-meal brand owners demand audited chain-of-custody documentation for PCR content claims in sustainability scorecard procurement. REACH framework amendments on microplastics tighten recyclable packaging definitions. Lyon and Lille packaging corridors see direct resin compounder contracting displace traditional film distributor relationships.
Netherlands
Fresh protein packagers in Rotterdam and Amsterdam accelerate qualification of silicon oxide coated monomaterials, bypassing traditional multilayer suppliers. EFSA opinions on mechanical recycling process equivalency pending approval freeze some investment decisions. Dutch seafood exporters specify oxygen transmission below 1 cc/m²/day for premium barrier applications.
China
Domestic consumer goods manufacturers expand PCR adoption for sustainable packaging closures amid tightening environmental enforcement. National standards on recycled plastic content in packaging substrates reshape resin sourcing strategies. Shanghai and Guangzhou converter clusters concentrate import-substitution capacity for food-grade lidding films.
PCR Lidding Films Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with coextrusion-equipped multinationals commanding premium positioning while regional converters compete on speed and customization. The vendor base organizes into three tiers: integrated resin-to-film producers with captive compounding, specialized barrier-coating specialists, and regional converters serving fragmented local demand. Two dominant competitive moves define current positioning: backward integration into resin compounding to secure PCR feedstock quality, and geographic expansion through toll-manufacturing partnerships to bypass capital-intensive equipment investments.
Within the integrated multinational tier, Amcor and Constantia Flexibles exemplify divergent specialization paths—one leveraging extrusion scale across multiple continents, the other anchoring position through pharmaceutical-grade barrier expertise. Mondi Group occupies a position emphasizing lightweighting innovation that reduces material intensity without functional compromise. These three entities represent how technology differentiation, regulatory dossier depth, and sustainability-led material science each create defensible positioning against commodity pressure.
| Leading Market Players |
|---|
| Amcor |
| Constantia Flexibles |
| Mondi Group |
| Sealed Air |
| Berry Global |
| Winpak |
| UFlex |
| Klöckner Pentaplast |
| Coveris |
| Others |
Pricing and Supply Chain Analysis
Seven-layer coextrusion capacity utilization across German and Dutch plants concentrates pricing power among integrated multinationals while compressing margin floors for regional converters lacking scale. This scale asymmetry shapes both supply concentration in Bavarian packaging corridors and the price premiums commanded by pharmaceutical-grade barrier specifications.
Pricing Analysis
Configured-to-order pricing for pharmaceutical-grade lidding with FDA notification dossiers commands substantial premiums over standard roll stock for commodity tray-sealing applications. Three-tier pricing structure across premium, standard, and economy levels stratifies by barrier performance tier and certification depth, with oxygen transmission below 1 cc/m²/day as the key quality delimiter. Pricing pressure stems from Chinese import substitution on non-barrier roll stock, compressing margins for undifferentiated converters. Consumer goods manufacturers exhibit highest price sensitivity due to sustainability scorecard procurement, while pharmaceutical producers accept premium pricing for validated compliance documentation.
Supply Chain Analysis
Inventory cycles for PCR feedstock extend lead times by 6-10 weeks as collection infrastructure gaps in Southern and Eastern Europe constrain bale quality consistency. Supply concentrates in Germany, the Netherlands, and China, with German converters anchoring pharmaceutical-grade capacity and Chinese plants serving import-substitution demand for commodity formats. Raw material dependencies center on post-consumer polypropylene bales, EVOH barrier resins, and silicon oxide deposition precursors. Single-source vulnerability sits with mechanical recycling process equivalency approvals pending EFSA opinions. Distribution runs through direct resin compounder contracting that displaces traditional film distributors in Germany and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PCR lidding films constitute a high-growth disruption as EU Green Deal recycled content mandates force immediate portfolio requalification across European packaging channels. This regulatory inflection compresses formulation development cycles and rewards early movers with qualified PCR supply chains.
For Market Incumbents: Fortify market position through backward integration into resin compounding to secure film-grade PCR feedstock quality against bale volatility. Expand seven-layer coextrusion capacity in Bavarian packaging corridors to capture modified-atmosphere protein demand. Invest in FDA food contact notification dossiers to extend regulatory moats against emerging Asian competitors. For New Entrants and Emerging Players: Technical service gaps in pharmaceutical blister compliance documentation present accessible white-space where incumbents under-serve mid-scale drug manufacturers. Target Dutch and Danish fresh protein packagers accelerating silicon oxide coated monomaterial qualification, bypassing established multilayer relationships. Pursue toll-manufacturing partnerships with underutilized coextrusion lines to bypass capital-intensive equipment investments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized barrier-coating specialists with EFSA-ready mechanical recycling equivalency submissions. Long-term viability hinges on chemical recycling feedstock integration capabilities that circumvent mechanical recycling constraints for food-contact approval. Watch EFSA scientific opinions on process equivalency as the critical inflection signal determining which PCR streams qualify for broad food-contact approval without functional barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive PCR feedstock quality control secures margin against bale volatility in European collection infrastructure. |
| Seven-Layer Coextrusion Capacity Expansion | High-barrier film investment captures modified-atmosphere protein demand in German packaging corridors. |
| Silicon Oxide Barrier Coating Qualification | Coated monomaterials bypass traditional laminate suppliers while improving PPWR recyclability scores. |
| FDA Food Contact Notification Dossier Investment | Regulatory documentation creates switching costs against emerging Asian competitors in US pharmaceutical channels. |
| Chemical Recycling Feedstock Partnership | Pyrolysis-derived resin streams enable food-contact approved PCR outside mechanical recycling EFSA constraints. |
Research Methodology
A spread of perspectives from film extrusion plant managers, pharmaceutical packaging specification owners, resin procurement leads at consumer goods manufacturers, and EFSA regulatory affairs specialists converged on the working assumptions. Primary interviews combined with secondary validation from EU Packaging and Packaging Waste Regulation draft texts, EFSA scientific opinions on recycling processes, FDA food contact substance inventories, and customs trade data for polymer film categories. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic drivers across the analysis window.
Segmentation dimensions modeled include film type substrate, application barrier specification, end-user industry procurement consolidation pattern, and geographic regulatory cluster. CAGRs derived from elasticity-adjusted volume projections and value-per-unit trends across premium and commodity tiers. Forecast inputs incorporated EU Green Deal compliance trajectory assumptions and mechanical recycling infrastructure buildout timelines.
Forecasts assume regulatory continuity in EU REACH and FDA food contact frameworks; material policy shifts on PCR content thresholds or recycling process equivalency would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.