
 Craft Plastic Films Market | 2026-2036
Craft Plastic Films Market Size, Share, and Industry Trends Forecast 2026-2036
Craft Plastic Films Market Outlook
Specialty packaging converters is rotating toward craft plastic films as artisanal food brands and boutique consumer goods producers scale output. Amcor Limited leverages its global converting footprint to supply customized film structures for premium positioning. Berry Global Inc. anchors North American supply through dedicated extrusion capacity for polyethylene and polypropylene grades. Uflex Limited competes on cost-engineered formulations targeting emerging market converters.
Craft plastic films are thermoplastic substrates, typically 12 to 150 microns in thickness, extruded from polyethylene, polypropylene, PVC, or PET resins for decorative, protective, or functional overlay applications in consumer and industrial goods. Polyethylene dominates volume throughput due to low-temperature sealability and moisture barrier performance, while PET commands margin pools in high-clarity lamination segments where optical properties justify premium positioning. The application split shows packaging absorbing the majority of film tonnage, with labeling and insulation representing faster-growing niches as brand owners demand tactile surface differentiation and thermal management in specialty goods.
REACH registration requirements and EU F-Gas Regulation constrain fluorinated additive use in European film formulations, while FDA food-contact notifications govern migration limits for U.S. food packaging applications. BIS certification in India adds compliance cost for imported film substrates serving the education and retail sectors. Stakeholders must monitor regulatory divergence between jurisdictions when designing unified product platforms for cross-border craft supply chains.
Market Dynamics
Specialty packaging converters are consolidating procurement around craft plastic films as artisanal food brands and boutique consumer goods producers scale output, creating sustained pull for customized film structures with premium tactile properties.
Growth Catalysts
- REACH Registration Requirements:ECHA's tightening chemical safety protocols are accelerating substitution toward compliant polyethylene and polypropylene formulations in European converting operations. Specialty converters in Germany's Rhine-Ruhr cluster are expanding capacity to serve artisanal food brands demanding certified substrates.
- Artisanal Food Brand Scaling:Small-batch producers across North America and Western Europe are migrating from rigid packaging to flexible film laminates for shelf differentiation and portion control. This end-use vertical is absorbing disproportionate tonnage of 25-75 micron polyethylene grades.
- Precision Converting Equipment:Advanced extrusion and coating lines installed in industrial clusters are enabling 12-micron tolerance control for high-value overlay applications. Equipment upgrades in Germany, Italy, and Japan are compressing lead times for customized film orders.
Market Restraints
- Resin Price Volatility:Ethylene and propylene feedstock costs fluctuate with crude oil benchmarks, squeezing converter margins on fixed-price contracts. Polyethylene film producers face margin compression when naphtha cracks tighten.
- Fluorinated Additive Restrictions:EU F-Gas Regulation and REACH constraints on PFAS compounds are eliminating slip and anti-fog agents historically standard in food-contact films. Reformulation cycles extend qualification timelines by 8-14 months.
- Paper and Molded Fiber Substitution:Fiber-based packaging from renewable sources is capturing shelf-space in premium dry goods segments where moisture barrier demands are moderate. Brand owners with explicit sustainability commitments are piloting fiber alternatives.
Strategic Opportunities
- Indian Education and Retail Sectors:BIS certification requirements for imported films have created supply gaps that domestic extruders can fill with locally certified polyethylene grades. Stationery and gift-wrapping applications remain underpenetrated by organized suppliers.
- Smart Packaging Integration:Convergence of printed electronics with thermoplastic substrates enables temperature-indicating labels and authentication features. RFID-enabled craft films are penetrating pharmaceutical and luxury goods segments.
- EU Green Deal Incentives:Circular economy action plan subsidies for recyclable mono-material structures are redirecting R&D budgets toward all-polyethylene laminates. Grants in Germany and France are accelerating pilot lines for chemically recyclable films.
Industry Challenges
- Migration Testing Expertise:FDA food-contact notification requirements demand specialized analytical chemistry capabilities that mid-size converters struggle to staff. Qualified toxicologists and migration study specialists command premium compensation in tight labor markets.
- Legacy Extruder Retrofitting:Converting equipment designed for multilayer structures requires capital-intensive modification to run mono-material films qualifying for recyclability certifications. Equipment finance constraints delay compliance timelines for smaller operators.
- Cross-Border Certification Complexity:Divergent migration limits between FDA, EFSA, and Japan's Food Sanitation Act force converters to maintain parallel inventory SKUs. Unified product platforms face qualification bottlenecks when serving multinational brand owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Craft Plastic Films Market |
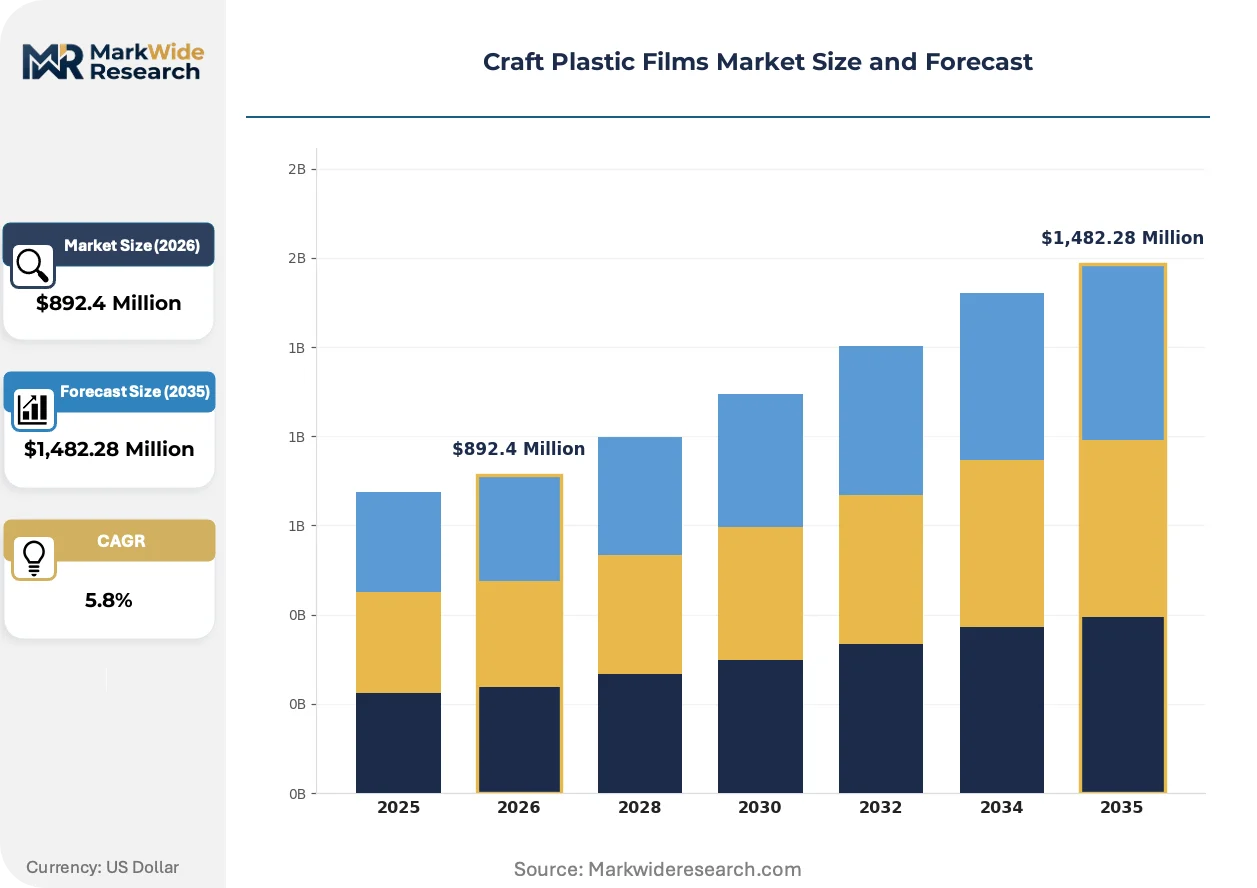
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,482.28 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, PET Application: Packaging, Lamination, Labeling, Insulation End User: Food Industry, Retail, Healthcare, Education Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | Amcor Limited, Sealed Air Corporation, Berry Global Inc., Constantia Flexibles, Uflex Limited, Winpak Ltd., Coveris Holdings S.A., Clondalkin Group, Treofan Holdings GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Craft Plastic Films Market Strategic Shifts
Material science advances and regulatory pressure are converging to reshape film formulation priorities, with sustainability certifications and functional integration becoming primary competitive differentiators rather than secondary specifications.
Mono-material polyethylene laminates are displacing traditional multilayer structures in premium packaging segments. Specialty converters in Germany and Italy are adopting these substrates at accelerated pace to meet retailer recyclability mandates. The technology is displacing legacy PET/PE combinations in high-clarity applications where optical properties previously justified complex constructions.
EU F-Gas Regulation amendments are prohibiting hydrofluorocarbon propellants and process agents in film manufacturing. Industrial consequence includes accelerated phase-out of fluorinated anti-fog and slip additives across European extrusion operations. Food-contact film segments serving fresh produce packaging are most affected, with converters reformulating around silicone and vegetable-based alternatives.
Direct brand-procurement relationships are compressing distributor intermediation in craft film supply chains. Artisanal food producers in France and California are negotiating volume commitments directly with extruders, bypassing traditional converter-distributor networks. This pattern is most visible in organic and specialty food verticals where traceability and certification documentation requirements favor direct supplier relationships.
Craft Plastic Films Market Segmentation
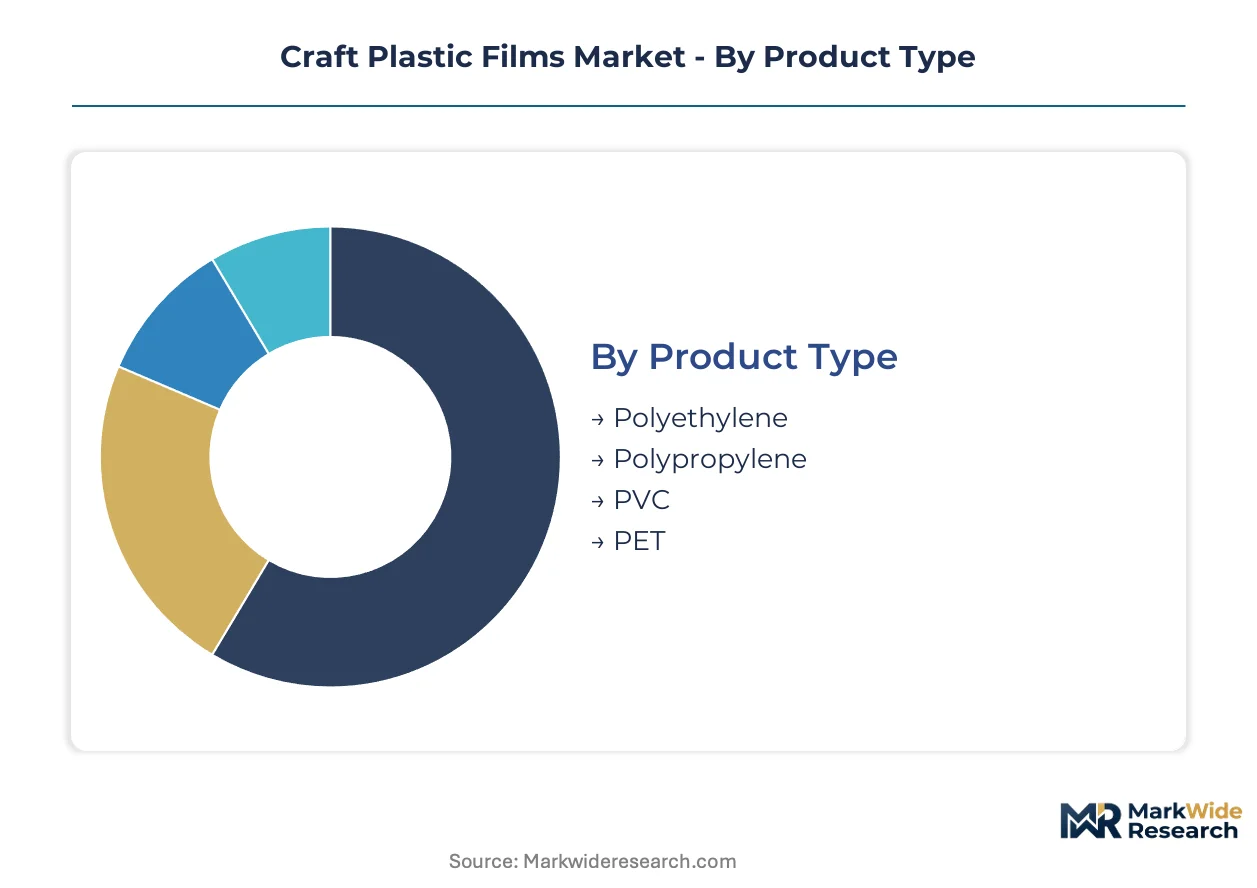
Craft plastic films demand fragments across resin chemistry, functional application, and procurement channel. Regulatory differentiation by end-use geography and certification tier creates pricing spreads that reshape competitive positioning within each segment cluster.
Product Type:
REACH registration tiers and FDA food-contact notification pathways split resin procurement strategies between commodity converters and certified specialty suppliers.
- Polyethylene:Low-density and linear-low-density grades dominate volume throughput through superior moisture barrier performance and heat-seal initiation temperatures. Artisanal food brands in Germany's Rhine-Ruhr cluster specify certified polyethylene for direct food-contact laminates under EFSA migration limits.
- Polypropylene:Cast and oriented variants command margin premiums in high-temperature filling applications where dimensional stability matters. Italian specialty converters are expanding biaxially oriented polypropylene capacity for premium labeling substrates requiring optical clarity.
- PVC:Rigid and flexible calendered grades serve decorative overlay niches where thermoformability and print receptivity justify formulation complexity. India's BIS certification requirements constrain imported PVC film penetration in education sector applications.
- PET:Polyester films anchor high-clarity lamination segments with superior tensile strength and chemical resistance. Japanese precision equipment manufacturers specify PET substrates for industrial insulation tapes requiring dielectric consistency.
Established volume favors polyethylene; emerging adoption favors polypropylene in premium positioning tiers.
Application:
Functional requirements across barrier, optical, and thermal performance dimensions determine resin selection and converting equipment configuration.
- Packaging:Flexible pouch and wrap structures absorb the majority of film tonnage through moisture and oxygen barrier specifications. Small-batch food producers in France and California are migrating from rigid containers to film laminates for shelf differentiation and portion control.
- Labeling:Pressure-sensitive and shrink-sleeve applications represent the steepest expansion trajectory as brand owners demand tactile surface differentiation. German converters are installing precision coating lines for 12-micron tolerance control in premium beverage labeling.
- Lamination:Adhesive and extrusion-laminated structures serve protective overlay functions in consumer goods and industrial components. EU Green Deal subsidies are redirecting R&D toward mono-material polyethylene laminates qualifying for recyclability certifications.
- Insulation:Dielectric and thermal barrier films penetrate electrical equipment and building material applications. Japanese industrial clusters specify PET-based insulation substrates for high-voltage cable wrapping applications.
Volume concentration sits with packaging; margin expansion concentrates in labeling and insulation.
End User:
Certification intensity and migration testing requirements fragment procurement relationships between direct extruder negotiations and distributor intermediation.
- Food Industry:Direct brand-procurement relationships are compressing traditional converter-distributor networks as traceability documentation requirements tighten. Organic and specialty food verticals in North America and Western Europe favor direct supplier relationships with certified extruders.
- Retail:Stationery, gift-wrapping, and general merchandise applications absorb commodity-grade polyethylene through wholesale distribution channels. India's retail sector presents supply gaps that domestic extruders with BIS certification can fill.
- Healthcare:Sterile barrier and pharmaceutical packaging applications demand specialized migration testing expertise that mid-size converters struggle to staff. FDA food-contact notification requirements and qualified toxicologist scarcity constrain new entrant penetration.
- Education:Laminating films for document protection and display materials serve institutional procurement through distributor networks. India's education sector BIS certification requirements have created organized supply opportunities for domestic producers.
Certification complexity favors direct procurement in food and healthcare; price sensitivity sustains distributor channels in retail and education.
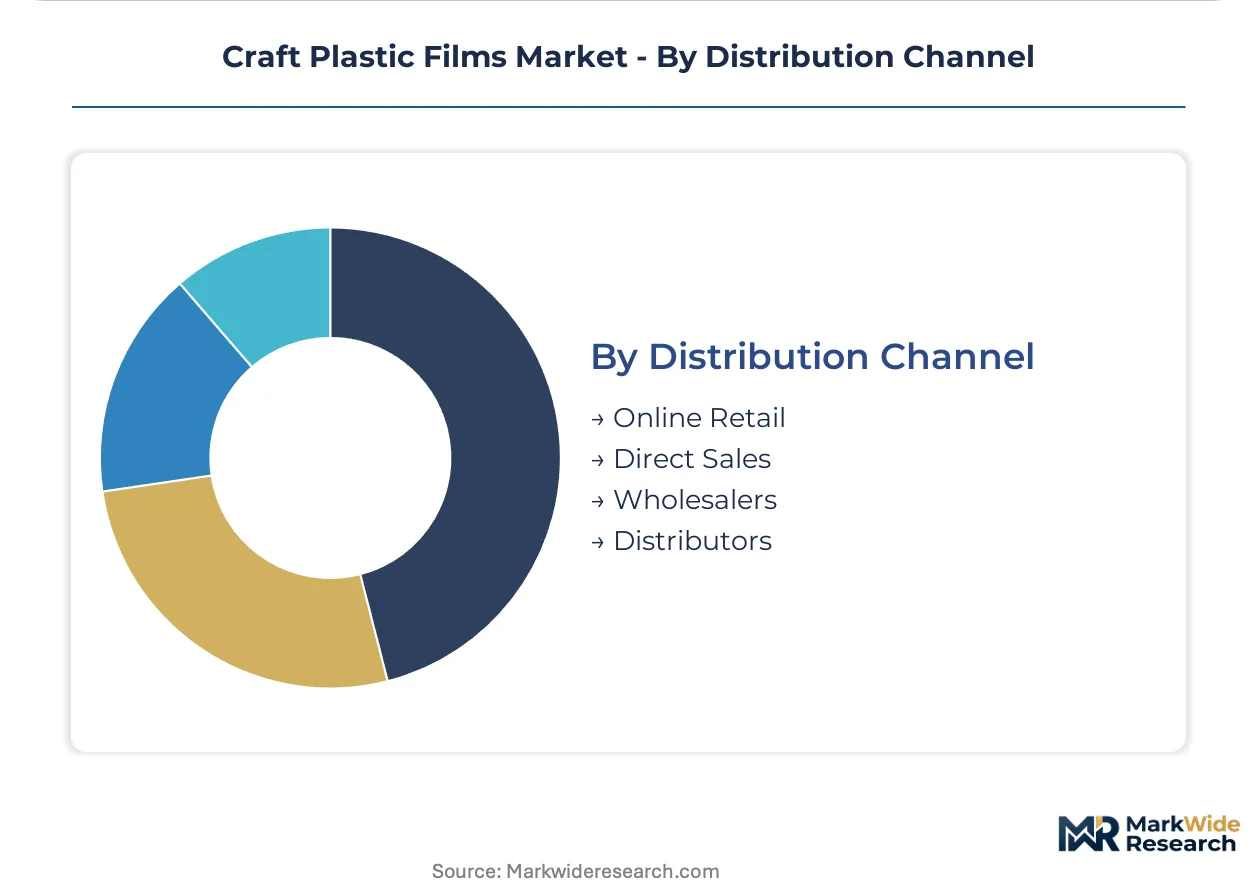
Distribution Channel:
Channel selection reflects order scale, customization depth, and documentation requirements across end-use verticals.
- Direct Sales:Volume commitments and technical collaboration agreements dominate procurement for customized film structures. Artisanal food producers in France and California negotiate directly with extruders for certified substrate supply with full traceability documentation.
- Distributors:Inventory pooling and technical service support sustain intermediary roles in fragmented end-use segments. Mid-size converters rely on distributor networks for commodity-grade polyethylene and polypropylene procurement.
- Online Retail:E-commerce penetration remains limited to standardized film products and small-lot specialty grades. Stationery and craft applications in India's retail sector show emerging online procurement patterns.
- Wholesalers:Bulk aggregation of commodity grades serves price-sensitive applications with limited certification requirements. General merchandise and education sector procurement in emerging markets flows through wholesale channels.
Relationship intensity favors direct sales in premium segments; transaction efficiency sustains distributor and wholesale channels in commodity tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German extruders export certified polyethylene laminates to artisanal food producers across France and California, while Indian domestic suppliers capture education sector demand previously served by imports.
Germany
Rhine-Ruhr precision converting equipment supports high-value film applications for artisanal food brands scaling output. REACH registration requirements under ECHA accelerate substitution toward compliant polyethylene formulations. Düsseldorf-area extruders expand capacity to serve direct procurement relationships with organic food producers.
United States
California boutique consumer goods producers migrate from rigid packaging to flexible film laminates for shelf differentiation. FDA food-contact notifications govern migration limits for food packaging applications. Midwest converting operations supply polyethylene grades to small-batch producers negotiating volume commitments directly with extruders.
India
Domestic education and retail sectors present supply gaps for BIS-certified polyethylene films in stationery and gift-wrapping applications. BIS certification requirements constrain imported film substrates serving institutional procurement. Maharashtra-based extruders capture organized supply opportunities previously filled by unorganized regional producers.
Italy
Premium labeling substrates demand optical clarity specifications that biaxially oriented polypropylene satisfies. EU Green Deal subsidies redirect R&D budgets toward mono-material structures qualifying for recyclability certifications. Northern Italian converters install precision coating lines for 12-micron tolerance control in beverage labeling applications.
Japan
Industrial insulation tapes require dielectric consistency specifications that PET substrates deliver. METI standards and JIS certification frameworks govern material performance in electrical equipment applications. Chubu industrial clusters specify polyester films for high-voltage cable wrapping in precision manufacturing supply chains.
Craft Plastic Films Market Competitive Environment
Listed leaders compete with private specialists across certification tiers and geographic coverage. The vendor base separates into three concentration levels: global converters with multi-continent extrusion networks, regional specialists with single-country certification depth, and private mid-caps serving niche application verticals. Strategic moves concentrate on backward integration into resin compounding and geographic expansion through distributor acquisition.
Within the global converter tier, Amcor Limited and Berry Global Inc. exemplify scale-driven positioning across multiple resin chemistries and end-use verticals. Uflex Limited occupies a cost-engineered specialization serving emerging market converters with formulation flexibility. These three entities represent distinct competitive archetypes: certification-heavy premium positioning, North American supply anchoring, and emerging market cost leadership.
| Leading Market Players |
|---|
| Amcor Limited |
| Sealed Air Corporation |
| Berry Global Inc. |
| Constantia Flexibles |
| Uflex Limited |
| Winpak Ltd. |
| Coveris Holdings S.A. |
| Clondalkin Group |
| Treofan Holdings GmbH |
| Others |
Value Chain & Pricing Dynamics
REACH registration tiers under ECHA simultaneously gate supplier qualification and stratify price levels across European craft plastic film procurement, with certified polyethylene formulations commanding sustained premiums over commodity grades while non-compliant imports face market exclusion.
Pricing Analysis
Legacy fluorinated additive formulations, silicone-based replacements, and next-generation vegetable-derived slip agents occupy distinct price bands across European converting operations. Three-tier pricing structure across premium certified, standard compliant, and economy non-food-contact levels reflects migration testing depth and certification documentation completeness. Pricing pressure stems from naphtha crack volatility squeezing polyethylene converter margins on fixed-price contracts. Artisanal food brands in France and California show lowest price sensitivity due to traceability requirements, while Indian education sector procurement exhibits highest elasticity.
Supply Chain Analysis
Strategic stockpiling of certified resin grades dominates procurement behavior among German and Italian specialty converters facing REACH-driven reformulation cycles, while just-in-tight inventory practices persist in commodity-grade segments. Feedstock concentration centers on Germany, Saudi Arabia, and the United States for ethylene and propylene supply. Polymer-grade naphtha, metallocene catalysts, and certified additive packages constitute critical input dependencies. Single-source vulnerability runs through specialized migration testing laboratories serving FDA notification requirements. Distribution runs through direct extruder relationships in premium food-contact tiers and wholesale channels in retail applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Migration testing expertise scarcity constrains mid-tier converter expansion and creates acquisition premiums for laboratories with qualified toxicologists on staff.
For Market Incumbents: Secure backward integration into resin compounding to control formulation flexibility amid fluorinated additive phase-outs. Anchor capacity expansion in Germany's Rhine-Ruhr cluster to serve direct procurement relationships with scaling artisanal food brands. Certification investment in BIS-compliant grades for India education sector supply gaps offers defensive positioning against emerging domestic extruders. For New Entrants and Emerging Players: FDA food-contact notification fast-track through specialized toxicology partnerships enables penetration of healthcare sterile barrier segments underserved by mid-size converters. White-space concentration sits with Indian domestic BIS-certified supply for stationery and gift-wrapping applications. Go-to-market execution through e-commerce channels for standardized small-lot grades bypasses entrenched wholesale networks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across mono-material recyclable film pilot lines eligible for EU Green Deal subsidies. Long-term viability favors vertically integrated specialists with captive resin formulation and precision converting equipment. Acquisition target archetype: mid-cap European converters with REACH-certified polyethylene capacity and direct relationships with organic food brands. Signal to watch: BIS certification backlog duration as indicator of Indian domestic supply response timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive formulation control accelerates REACH-compliant additive substitution timelines. |
| Mono-Material Pilot Line Investment | EU Green Deal subsidies in Germany and France reduce capital recovery periods for recyclable structures. |
| Direct Procurement Relationship Development | Artisanal food brands in France and California bypass distributors for traceability documentation. |
| Migration Testing Laboratory Acquisition | FDA notification expertise scarcity commands premium valuations in tight labor markets. |
| BIS Certification Pathway Establishment | Domestic Indian extruders capture education sector supply gaps from constrained imports. |
Study Parameters
A standing panel of specialty packaging converters, resin procurement managers at extrusion operations, ECHA regulatory affairs consultants, and FDA food-contact toxicologists provided ongoing calibration across primary interview cycles. Secondary validation drew from REACH registration databases, EFSA migration limit guidance documents, BIS certification records, and customs trade data for polyethylene and polypropylene film imports. Bottom-up volume estimates from converter capacity utilization triangulated against top-down resin consumption figures from European and North American petrochemical associations.
Consistency checks against external benchmarks validated projection outputs across the analysis window. Segmentation modeling incorporated resin chemistry tiers, functional application splits, certification intensity levels, and procurement channel structures. CAGRs derived from elasticity-adjusted demand curves incorporating artisanal food brand scaling rates and regulatory substitution timelines. Industry-specific inputs included fluorinated additive phase-out schedules under EU F-Gas Regulation and precision converting equipment installation pipelines in German and Italian industrial clusters.
Decision-makers should treat outputs as directional under assumptions of sustained REACH enforcement intensity and stable crude oil-naphtha price correlations; material deviation would warrant model refresh. Specific risk factors include accelerated PFAS restrictions extending beyond current F-Gas Regulation scope, fiber-based packaging substitution rates in premium dry goods, and BIS certification processing delays altering Indian competitive dynamics. Revision becomes warranted when resin price volatility crosses threshold levels that trigger contract renegotiation waves across fixed-price converter agreements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Polypropylene Packaging Films Market
Poly film
Printed Plastic Films Market
Poly film
Poly Tubing Market
Poly film
Nylon Films for Liquid Packaging Market
Poly film
Americas Polypropylene (PP) Films Market
Poly film
Polyolefin Films Market
Poly film
Colourless Polyimide Films Market
Poly film
Biaxially Oriented Polypropylene (BOPP) Films Market
Poly film
Waste Wrap Film Market
Poly film
Biaxially Oriented Polyamide (BOPA) Films Market
Poly film
China Plastic Packaging Film Market
Poly film
North America BOPP Films Market
Poly film
Global Fluoropolymer Films Market
Poly film
Polyethylene Cast Film Market
Poly film
Polycoated Packaging Market
Poly film
Biaxially Oriented Polyethylene Terephthalate (BOPET) Films Market