
 North America Polyimide Films Market | 2026-2036
North America Polyimide Films Market Size, Share, and Industry Trends Forecast 2026-2036
North America Polyimide Films Market Analytics
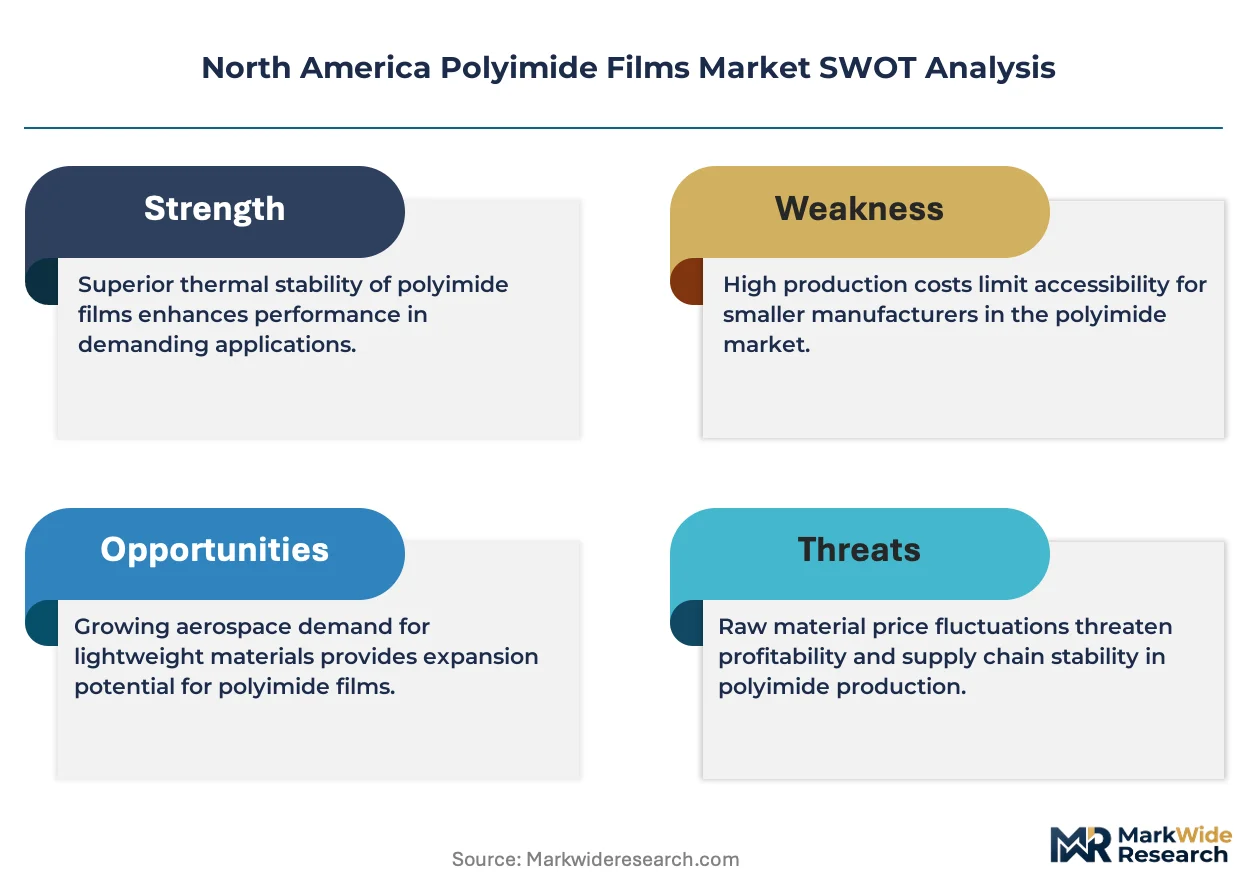
Electric vehicle battery insulation is restructuring demand patterns across the North America polyimide films landscape. DuPont leverages its Kapton heritage and fluoropolymer adjacencies to sustain pricing power in high-temperature laminates for EV power electronics. Saint-Gobain Performance Plastics anchors its position through specialized silicone-polyimide hybrids serving aerospace OEMs in the US Southeast. Kaneka Corporation competes via backward integration into monomer production, controlling cost volatility on specialty grades.
North America polyimide films are aromatic heterocyclic polymers synthesized through dianhydride-diamine condensation, typically achieving glass transition temperatures above 360°C and dielectric strengths exceeding 150 kV/mm. These thermal and electrical properties make them indispensable for flexible printed circuit substrates, motor slot liners, and thermal barrier films in electrified propulsion systems. Flexible films dominate volume consumption in electronics roll-to-roll processing, while adhesive-coated variants command premium positioning in multi-layer aerospace insulation blankets. Ultra-thin gauges below 12.5 microns are gaining traction in miniaturized medical device flex circuits, though thick-film segments retain margin pools in heavy-industrial generator applications.
The EPA regulates volatile organic compound emissions from polyimide curing operations under Clean Air Act Title V permitting, while OSHA enforces permissible exposure limits for residual solvents in film casting facilities. NHTSA's evolving EV safety standards for thermal runaway containment are tightening material certification requirements, effectively raising barriers for uncertified Asian imports. Stakeholders must monitor how the Inflation Reduction Act's domestic content thresholds reshape qualification timelines for non-US converted film.
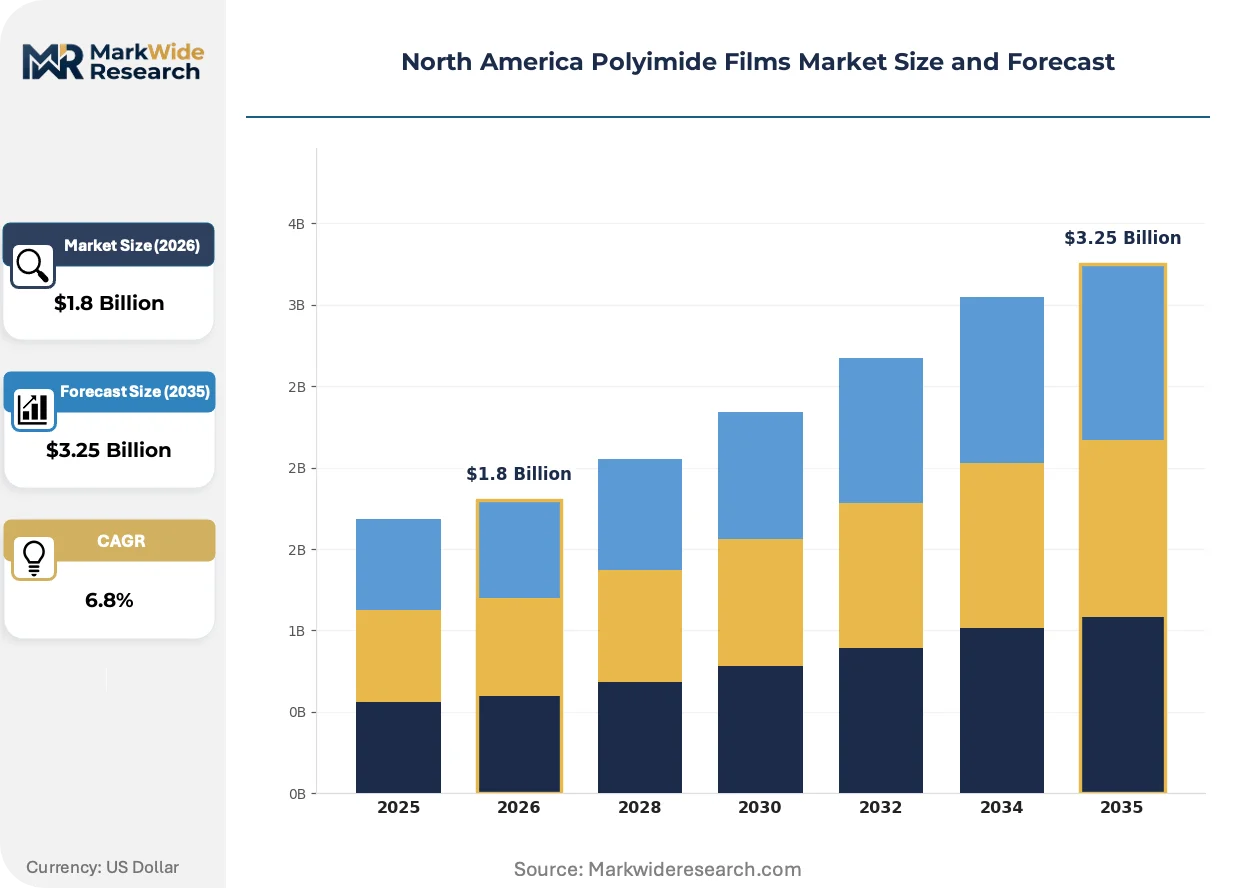
Market Dynamics
EV battery thermal management requirements are compressing qualification timelines and forcing rapid reconfiguration of polyimide film supply chains around Michigan and Ohio gigafactory clusters.
Growth Catalysts
- NHTSA thermal runaway standards:Mandates for multi-layer insulation barriers in electrified powertrains are pulling high-temperature laminate demand from aerospace into automotive applications.
- Inflation Reduction Act domestic content thresholds:Tier-one suppliers are reshoring film conversion capacity to capture federal EV tax credit benefits.
- Flexible printed circuit miniaturization:Roll-to-roll processing advances in medical device manufacturing are expanding ultra-thin gauge consumption below 12.5 microns.
Market Restraints
- Pyromellitic dianhydride cost volatility:Concentrated Asian monomer supply exposes converters to feedstock price swings and force majeure disruptions.
- EPA Title V permitting delays:Clean Air Act compliance for new curing capacity extends facility commissioning timelines by 18-24 months in most US jurisdictions.
- Polyetherimide substitution in sub-200°C applications:Lower-cost amorphous thermoplastics are capturing motor slot liner segments where thermal margins permit.
Strategic Opportunities
- Ohio-Michigan battery corridor:Proximity to Ford, GM, and LG Energy Solution plants enables just-in-time lamination services with sub-500-mile logistics loops.
- Silicone-polyimide hybrid aerospace demand:Specialized grades for next-generation satellite bus structures command 40-60% premiums over standard Kapton equivalents.
- OSHA-compliant solvent recovery systems:Captive recycling infrastructure reduces residual solvent exposure liabilities while qualifying facilities for expedited permitting.
Industry Challenges
- High-temperature polymer processing expertise:Skilled technicians capable of managing dianhydride-diamine condensation kinetics remain scarce in the US Southeast conversion hub.
- Multi-agency certification synchronization:Simultaneous NHTSA, FAA, and FDA material approvals for cross-sector suppliers create documentation bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Polyimide Films Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible, Rigid, Adhesive, Laminated End User: Aerospace, Automotive, Electronics, Healthcare Application: Insulation, Packaging, Coatings, Components Thickness: Thin, Medium, Thick, Ultra-Thin |
| Companies Covered | DuPont, 3M, PI Advanced Materials Co., Ltd., Kaneka Corporation, Kolon Industries, Inc., Toray Industries, Inc., Arkema, Saint-Gobain Performance Plastics, Flexcon Company Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Polyimide Films Market Evolving Landscape
Polyimide film manufacturing is fragmenting from centralized commodity production toward distributed, application-specific conversion nodes aligned with end-use clusters.
Solution-cast ultra-thin film production is decentralizing technical capability across regional coating operations. Battery OEMs in Michigan and Ohio now demand localized slitting and adhesive lamination within 300 miles of assembly plants. This geographic compression eliminates trans-Pacific inventory exposure and reduces working capital requirements for tier-one suppliers managing JIT delivery contracts.
The EPA's tightened VOC emission thresholds under Clean Air Act Title V are forcing solvent-based casters toward aqueous dispersion technologies or thermal imidization retrofits. Facilities without recovery infrastructure face operating permit non-renewal in California and Northeast states. Converters are responding by consolidating curing capacity in Texas and Louisiana jurisdictions with more permissive air quality frameworks.
Automotive procurement teams are compressing supplier qualification cycles from 36 months to 18 months for thermal barrier materials. Traditional distributor networks with 2-3 tier structures are losing share to direct mill relationships with film converters. This disintermediation is most pronounced in the EV battery supply chain, where OEMs bypass electronics distributors to negotiate volume commitments directly with Saint-Gobain and DuPont lamination facilities.
North America Polyimide Films Market Segmentation
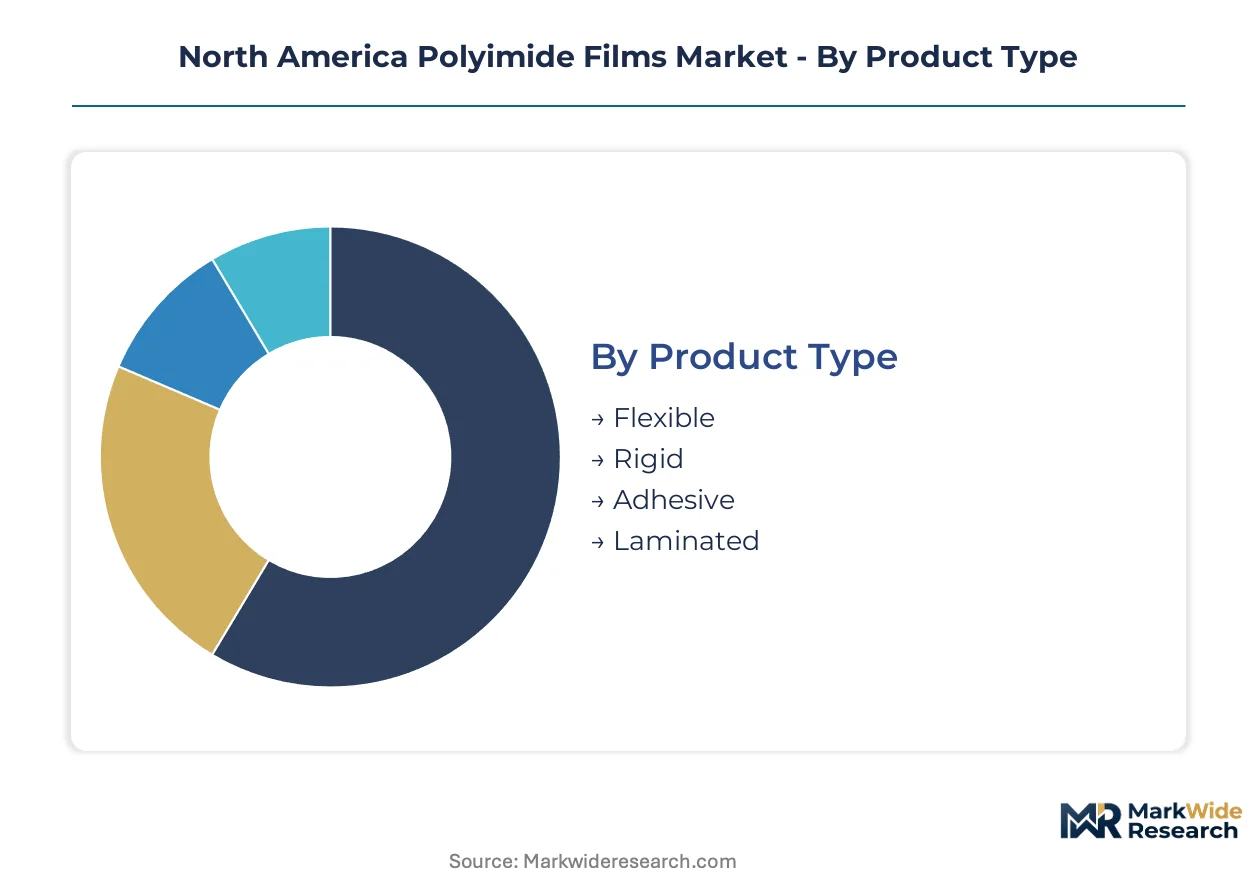
Polyimide film segmentation in North America reflects divergent technical requirements across electrification and aerospace end-uses. Each dimension carries distinct margin profiles and qualification barriers that reshape supplier positioning.
Product Type:
Supply concentration in dianhydride monomers tilts competitive advantage toward converters with captive resin production or long-term offtake agreements.
- Flexible:Roll-to-roll processed aromatic heterocyclic polymers dominate electronics substrate consumption. Michigan and Ohio battery gigafactories are pulling regional slitting capacity inward for just-in-time thermal barrier delivery.
- Laminated:Multi-layer constructions combining polyimide with fluoropolymer or silicone interlayers command premium positioning in NHTSA-certified EV battery insulation. Ford and GM procurement teams now specify direct mill relationships bypassing traditional distributor tiers.
- Adhesive:Pressure-sensitive and thermosetting coated variants serve aerospace multi-layer insulation blankets with FAA certification requirements.
- Rigid:Glass-reinforced or mineral-filled grades retain industrial generator applications where structural rigidity outweighs flexibility demands.
Today's leader: Flexible. Tomorrow's challenger: Laminated.
End User:
Customer-type fragmentation separates price-sensitive electronics assemblers from specification-locked aerospace OEMs and automotive tier-ones.
- Automotive:Electrified powertrain thermal management is compressing qualification timelines from 36 months to 18 months. EPA Title V permitting delays for new curing capacity extend facility commissioning by 18-24 months in most US jurisdictions.
- Aerospace:Specialized silicone-polyimide hybrids for satellite bus structures command 40-60% premiums over standard grades. Saint-Gobain Performance Plastics anchors supply through dedicated US Southeast conversion facilities.
- Electronics:Flexible printed circuit miniaturization in medical devices expands ultra-thin gauge consumption below 12.5 microns.
- Healthcare:FDA material approvals for implantable device flex circuits create documentation bottlenecks distinct from industrial qualifications.
Automotive represents the steepest expansion trajectory. Aerospace retains the deepest margin pools.
Application:
Volume concentration varies sharply between commodity insulation rolls and specification-driven coating formulations.
- Insulation:Multi-layer thermal barriers for EV battery packs are restructuring procurement patterns among tier-one suppliers. The Inflation Reduction Act's domestic content thresholds steer capital toward US-based film conversion capacity.
- Components:Motor slot liners and flexible printed circuit substrates span industrial and consumer electronics with divergent thermal specifications.
- Coatings:Wire enamel and high-temperature surface treatments compete with polyetherimide substitution in sub-200°C applications.
- Packaging:Niche semiconductor wafer handling and specialty electronics protection serve smaller addressable markets with lower entry barriers.
Insulation captures the fastest volume climb. Components defend the broadest installed base.
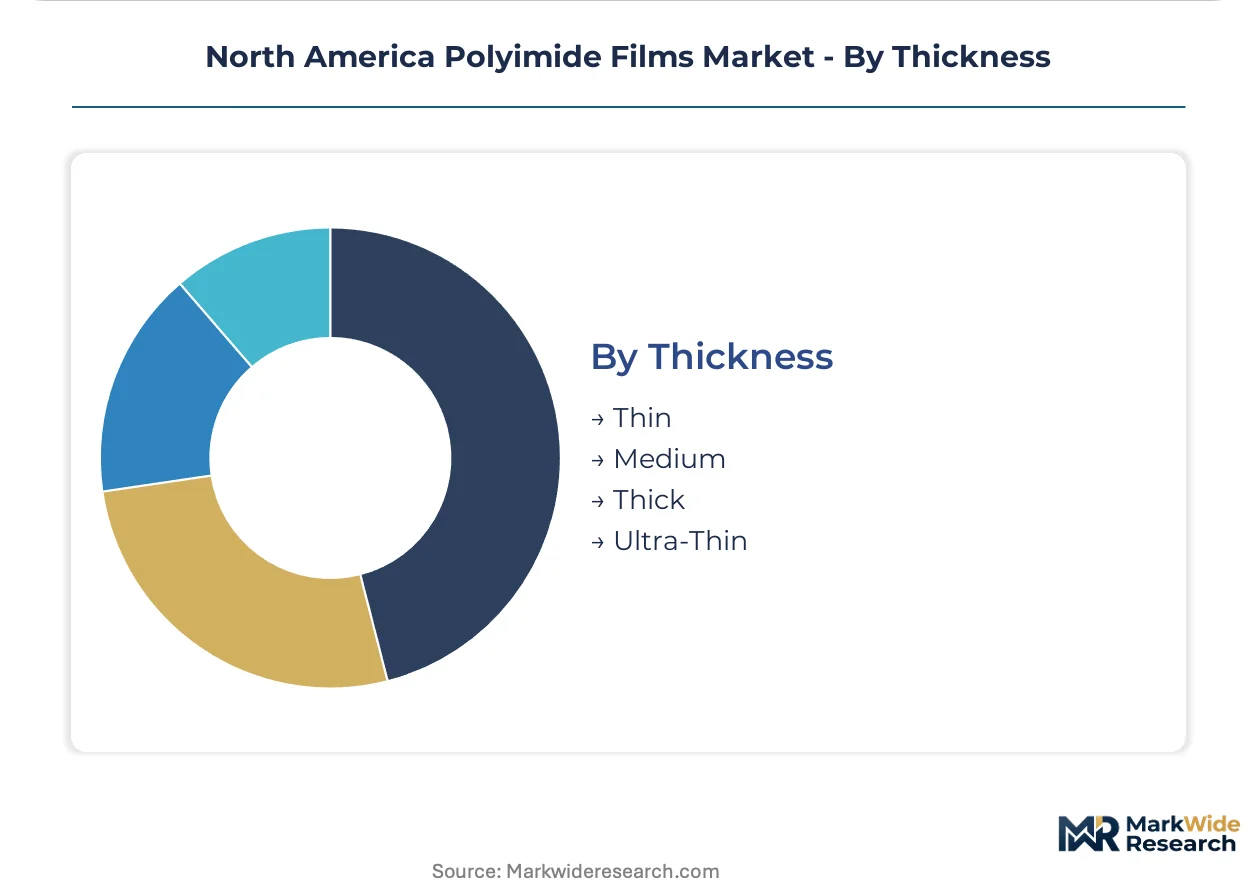
Thickness:
Margin structure inverts between high-volume medium gauges and precision ultra-thin production with yield-sensitive coating economics.
- Ultra-Thin:Sub-12.5 micron gauges for miniaturized medical device flex circuits require solution-cast precision with elevated scrap rates.
- Medium:Standard 25-50 micron rolls serve the bulk of flexible printed circuit and industrial insulation demand with mature cost curves.
- Thick:Heavy-industrial generator applications and aerospace insulation blankets retain margin pools through specification complexity rather than volume scale.
- Thin:12.5-25 micron intermediate grades bridge electronics miniaturization trends with conventional processing equipment.
Medium gauges dominate current output. Ultra-thin production is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting polyimide film conversion capacity toward jurisdictions with streamlined air permitting, compressing investment timelines for suppliers serving electrified automotive clusters.
United States
EPA Title V permitting delays in California and Northeast states are pushing curing capacity toward Texas and Louisiana. The Inflation Reduction Act's domestic content thresholds accelerate reshoring of film lamination operations. Michigan and Ohio battery gigafactories pull regional supply chains inward with sub-500-mile logistics loops.
Canada
Ontario's automotive supplier base is repositioning for EV thermal barrier demand from Detroit Three assembly plants. Health Canada and PMRA oversight of residual solvents aligns with OSHA-equivalent exposure limits. Toronto-Waterloo corridor coating operations are expanding slitting capacity for just-in-time delivery to US Midwest battery plants.
Mexico
Nuevo León and Bajío Region electronics manufacturing is absorbing medium-gauge flexible film for automotive wire harness applications. Mexican environmental regulators enforce VOC thresholds below US EPA levels in Mexico City Metro. Monterrey conversion facilities leverage NAFTA-legacy supply relationships with Texas resin distributors.
North America Polyimide Films Market Competitive Landscape
Capacity expansion dominates the current landscape as tier-one suppliers race to commission curing facilities before NHTSA thermal runaway standards fully phase in. The vendor base separates into three functional tiers: integrated resin-to-film producers, specialized converters with captive lamination technology, and regional slitting operations serving single end-use clusters. Strategic archetypes include backward-integrated monomer producers controlling feedstock volatility, aerospace-certified specialists commanding certification premiums, and automotive-focused converters optimizing logistics proximity. M&A activity targets distressed curing assets in permissive regulatory jurisdictions, while strategic partnerships between resin suppliers and regional coaters accelerate qualification timelines.
Within the integrated producer tier, DuPont and Kaneka Corporation exemplify contrasting geographic strategies. DuPont anchors North American positioning through Kapton-brand heritage and fluoropolymer adjacency. Kaneka Corporation represents Asian backward integration into dianhydride monomer production. Saint-Gobain Performance Plastics occupies the aerospace-specialist archetype with dedicated US Southeast conversion infrastructure.
| Leading Market Players |
|---|
| DuPont |
| 3M |
| PI Advanced Materials Co., Ltd. |
| Kaneka Corporation |
| Kolon Industries, Inc. |
| Toray Industries, Inc. |
| Arkema |
| Saint-Gobain Performance Plastics |
| Flexcon Company Inc. |
| Others |
Value Network & Pricing Analysis
Skilled dianhydride-diamine condensation technicians in the US Southeast command wage premiums that compress margin spreads between aerospace-certified laminates and standard flexible film tiers. Labor-cost differentials between Texas-Louisiana curing hubs and California-Northeast facilities directly map onto pricing stratification across premium, standard, and economy product levels.
Pricing Analysis
Distributor margin compression is accelerating as Ford and GM procurement teams negotiate direct mill relationships with DuPont and Saint-Gobain lamination facilities. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with NHTSA-certified EV battery insulation commanding substantial premiums over industrial grades. Cost compression in standard flexible film is intensifying because polyetherimide substitution erodes thermal-margin applications. Automotive tier-ones exhibit highest price sensitivity due to JIT delivery penalties, while aerospace OEMs locked into FAA qualification cycles remain least sensitive.
Supply Chain Analysis
Dual-sourcing requirements from tier-one automotive suppliers mandate multi-supplier qualification for pyromellitic dianhydride monomers across Japan, China, and South Korea. Raw material dependencies center on dianhydride monomers, aromatic diamines, and solvent carriers for solution-cast production. Single-source vulnerability concentrates in Asian monomer supply exposed to force majeure disruptions. Distribution runs through regional slitting operations clustered within 300 miles of Michigan and Ohio battery gigafactories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyimide film conversion capacity is a geographic-arbitrage play: EPA Title V permitting timelines in California extend 18-24 months versus streamlined air-quality frameworks in Texas and Louisiana that compress facility commissioning.
For Market Incumbents: Extend captive resin production or long-term monomer offtake agreements to defend against pyromellitic dianhydride cost volatility. Add curing capacity in permissive regulatory jurisdictions before NHTSA thermal runaway standards fully phase in. For New Entrants and Emerging Players: Launch via direct mill relationships with Ohio-Michigan battery OEMs, bypassing traditional distributor tiers. Target silicone-polyimide hybrid aerospace grades where Saint-Gobain's US Southeast concentration leaves white-space for specialized converters. Pursue OSHA-compliant solvent recovery systems as qualification accelerant. For Investors and Strategic Acquirers: Specialty chemical conglomerates with fluoropolymer adjacencies are the most active acquirer in this space, seeking distressed curing assets in Texas and Louisiana. Long-term viability hinges on domestic content qualification under Inflation Reduction Act thresholds. Watch NHTSA thermal runaway standard implementation pace as inflection indicator for demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Production | Kaneka Corporation's captive dianhydride supply insulates margins from Asian feedstock volatility. |
| Regional Lamination Capacity Expansion | Proximity to Ford and GM battery plants in Michigan and Ohio enables JIT delivery contracts. |
| Silicone-Polyimide Hybrid Development | Saint-Gobain commands 40-60% premiums over standard Kapton in satellite bus applications. |
| Solvent Recovery Infrastructure Investment | OSHA-compliant recycling systems qualify facilities for expedited EPA Title V permitting. |
| Direct Mill Relationship Establishment | Bypassing distributor tiers captures margin compression from automotive procurement compression. |
Research Methodology
Multiple input streams — primary interviews with polyimide film plant managers, automotive tier-one procurement leads, and aerospace OEM material engineers; secondary validation through EPA Title V permitting databases, SEC 10-K filings, and customs/trade data; plus ACC industry reports — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, end-use industry, thickness grade, and regional production hub segmentation dimensions generated volume and value outputs over the projection horizon. CAGRs were derived from modeled adoption curves for EV battery thermal barriers and aerospace insulation demand, incorporating NHTSA regulatory phase-in assumptions and Inflation Reduction Act domestic content threshold impacts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under pyromellitic dianhydride supply disruption or accelerated EPA VOC emission tightening. Deviation in NHTSA thermal runaway standard enforcement timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
North America BOPP Films Market
Poly film
Global Biaxially Oriented Polypropylene (BOPP) in Films and Sheets Market
Poly film
Recyclable Lidding Films Market
Poly film
United States Polycarbonate Sheets and Films Market
Poly film
Global PVDC Coated Films Market
Poly film
Surface Printed Film Market
Poly film
PVC Film for Medical Market
Poly film
Germany Plastic Packaging Films Market
Poly film
Polytetrafluoroethylene (PTFE) Films Market
Poly film
PET Lidding Films Market
Poly film
Global Specialty Films Polymer Market
Poly film
Polyethylene Terephthalate (PET) Shrink Films Market
Poly film
UAE Plastic Packaging Films Market
Poly film
Silicone-Coated PET Films Market
Poly film
Twist Wrap Film Market
Poly film
Polyolefin Films Market