
 Thailand Plastic Packaging Films Market | 2026-2036
Thailand Plastic Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Plastic Packaging Films Market Insights
Thailand's Eastern Economic Corridor is tilting investment toward integrated film converting complexes that draw feedstock from nearby petrochemical plants. SCG Packaging Public Company Limited leverages its captive resin access and cartonboard integration to dominate domestic flexible packaging supply for consumer goods multinationals. Indorama Ventures anchors regional PET film supply through its Thailand-based polymerization and film extrusion assets that serve ASEAN beverage bottlers. Thai Future Incorporation Public Company Limited specializes in printed laminated films for food applications, competing on short-run customization speed rather than commodity scale.
Thailand plastic packaging films are multilayer or monolayer polymer substrates, typically ranging from 12 to 150 microns in thickness, manufactured through blown or cast extrusion processes and subsequently metallized, coated, or printed to achieve barrier against moisture, oxygen, and light. These films function primarily to preserve product integrity, enable portion control, and support brand communication across retail and institutional channels. Polypropylene films lead in rigid-to-flexible conversion for snack and confectionery applications where clarity and heat sealability command premium positioning. PE films sustain the fastest growth trajectory in e-commerce secondary packaging and agricultural mulch films where downgauging and recycled content incorporation are reshaping procurement specifications. PET films retain entrenched demand in pharmaceutical blister packs and high-barrier lidding where regulatory compliance and optical consistency create defensible margin pools.
Thailand's Ministry of Natural Resources and Environment enforces plastic waste management roadmaps that mandate recycled content thresholds and extended producer responsibility schemes, compelling converters to certify film recyclability or face market access restrictions. The Thailand Industrial Standards Institute administers TISI mark requirements for food-contact plastics that specify migration limits and additive disclosures, creating compliance costs that favor larger integrated producers over fragmented importers. BIS-equivalent conformity assessment pressures from neighboring ASEAN markets further filter which Thai film exporters can participate in cross-border supply chains. Stakeholders must monitor whether Thailand's anticipated carbon border adjustment discussions with the EU will extend beyond energy-intensive sectors to encompass embedded emissions in petrochemical-derived packaging materials.
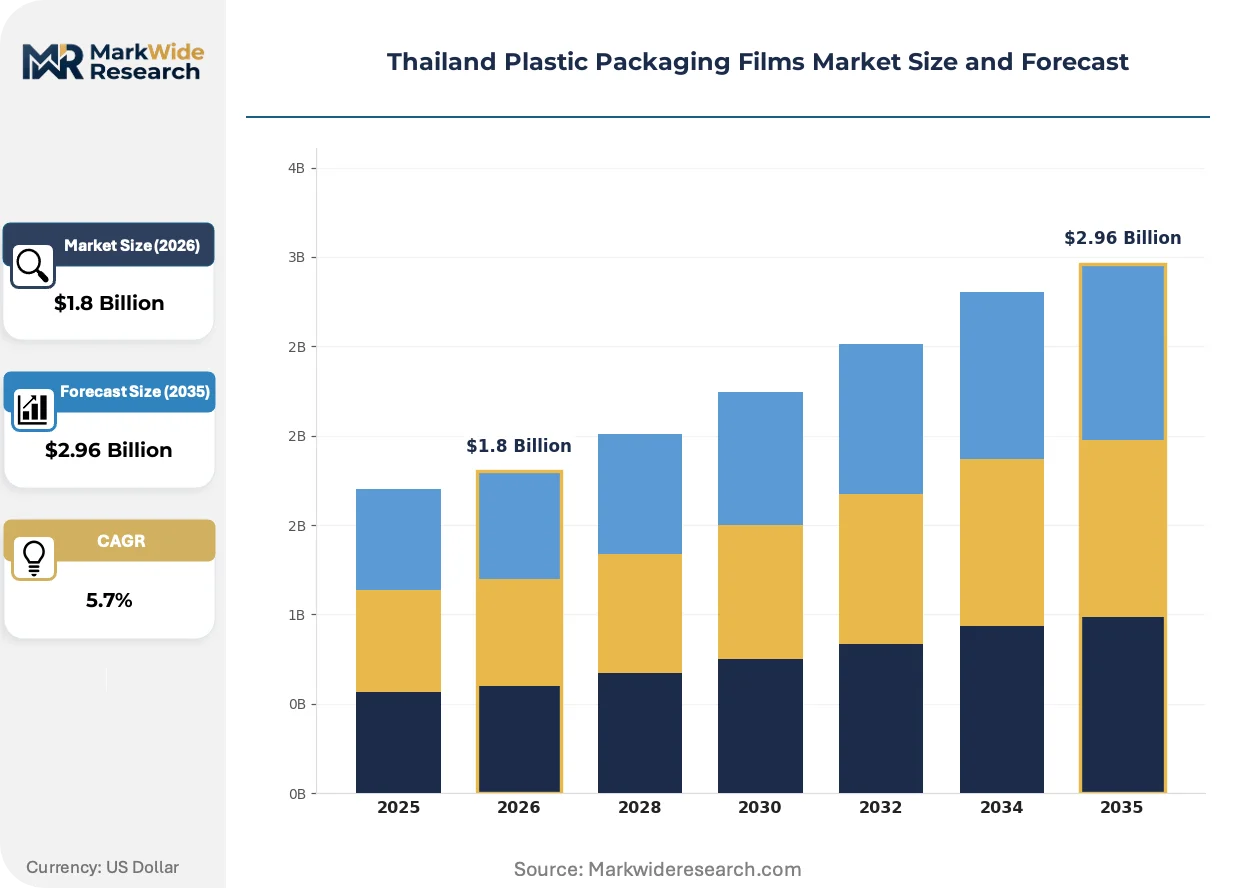
Market Dynamics
Thailand's plastic packaging films sector is restructuring around mono-material recyclability mandates from the Ministry of Natural Resources and Environment, forcing converters to abandon multi-layer barrier constructions in favor of single-polymer designs that maintain performance through advanced metallization and coating techniques.
Growth Catalysts
- Eastern Economic Corridor clustering:Petrochemical downstream facilities and film converters are co-locating in Rayong and Chonburi provinces to cut resin logistics costs and accelerate just-in-time supply to Bangkok food processors.
- Extended Producer Responsibility schemes:Thailand's national plastic waste management roadmap mandates recycled content thresholds, creating certified demand pull for post-consumer PE and PP feedstock among export-oriented seafood packers.
- Metallized barrier coatings:Vacuum deposition technologies are replacing ethylene vinyl alcohol laminates in snack and confectionery films, enabling circularity without sacrificing oxygen barrier performance.
Market Restraints
- Naphtha price volatility:Thai film producers remain exposed to imported feedstock costs, with domestic ethylene and propylene supply insufficient to cover flexible packaging resin demand.
- Technical limitation in downgauging:Agricultural mulch films below 15 microns lack the puncture resistance required for mechanized harvesting in Thailand's cassava and sugarcane belts.
- Cross-border BIS-equivalent barriers:Indonesian and Vietnamese conformity assessment requirements block Thai film exporters from ASEAN procurement tenders despite geographic proximity.
Strategic Opportunities
- Pharmaceutical blister pack migration:Thai converters with TISI food-contact certification can extend into regulated pharma packaging as multinational drugmakers regionalize ASEAN supply chains.
- E-commerce secondary packaging:Bangkok-based logistics platforms are specifying recycled-content PE mailer films, opening volume contracts for domestic extruders with post-consumer pellet supply agreements.
- Chemical recycling integration:Pyrolysis partnerships with petrochemical complexes in Map Ta Phut could unlock food-grade recycled polypropylene for mono-material flexible packaging.
Industry Challenges
- Migration testing capacity bottleneck:TISI-accredited laboratories face 12-week backlogs for food-contact compliance certification, delaying new product launches for mid-size converters.
- Legacy extrusion asset retrofit costs:Blown film lines designed for multi-layer structures require substantial capital expenditure to switch to mono-material production without throughput loss.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Plastic Packaging Films Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PE, PVC, PET, Polypropylene End Use Industry: Food, Beverage, Pharmaceuticals, Consumer Goods Thickness: Thin, Medium, Thick, Extra Thick Form: Roll, Sheet, Bag, Pouch |
| Companies Covered | Thai Future Incorporation Public Company Limited, SCG Packaging Public Company Limited, TPBI Public Company Limited, Polyplex (Thailand) Public Company Limited, Amcor plc, Sealed Air Corporation, Huhtamäki Oyj, Mondi Group, Indorama Ventures, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Plastic Packaging Films Market Trends and Innovations
Film converters across Thailand's Eastern Economic Corridor are racing to deploy equipment and material platforms that satisfy simultaneous demands for barrier performance, optical clarity, and end-of-life circularity.
Water-based barrier coatings applied through flexographic or gravure processes are rendering obsolete solvent-based adhesive laminations in snack and confectionery packaging. Bangkok-based food processors are specifying these constructions for export-ready products to preempt EU packaging waste directive compliance costs. The shift is compressing margins for conventional solvent lamination houses while rewarding converters with in-house coating deposition capability.
Thailand's Ministry of Natural Resources and Environment is accelerating enforcement of recycled content mandates under its national plastic waste management roadmap. Food-contact film producers must now certify post-consumer feedstock chain of custody to maintain access to domestic retail channels. Seafood exporters in Samut Sakhon and Samut Prakan are responding by consolidating procurement with converters holding TISI and EU-equivalent dual certification.
Brand owners in Thailand's retail sector are compressing packaging specification cycles from annual to quarterly reviews, driven by sustainability marketing competition and retailer private-label expansion. Central Group and CP All are unbundling film supply contracts by application type rather than awarding consolidated annual tenders. This behavioral shift is most visible in Bangkok's ready-to-eal meal segment, where short-run customization speed now outweighs unit cost in supplier selection criteria.
Thailand Plastic Packaging Films Market Segmentation
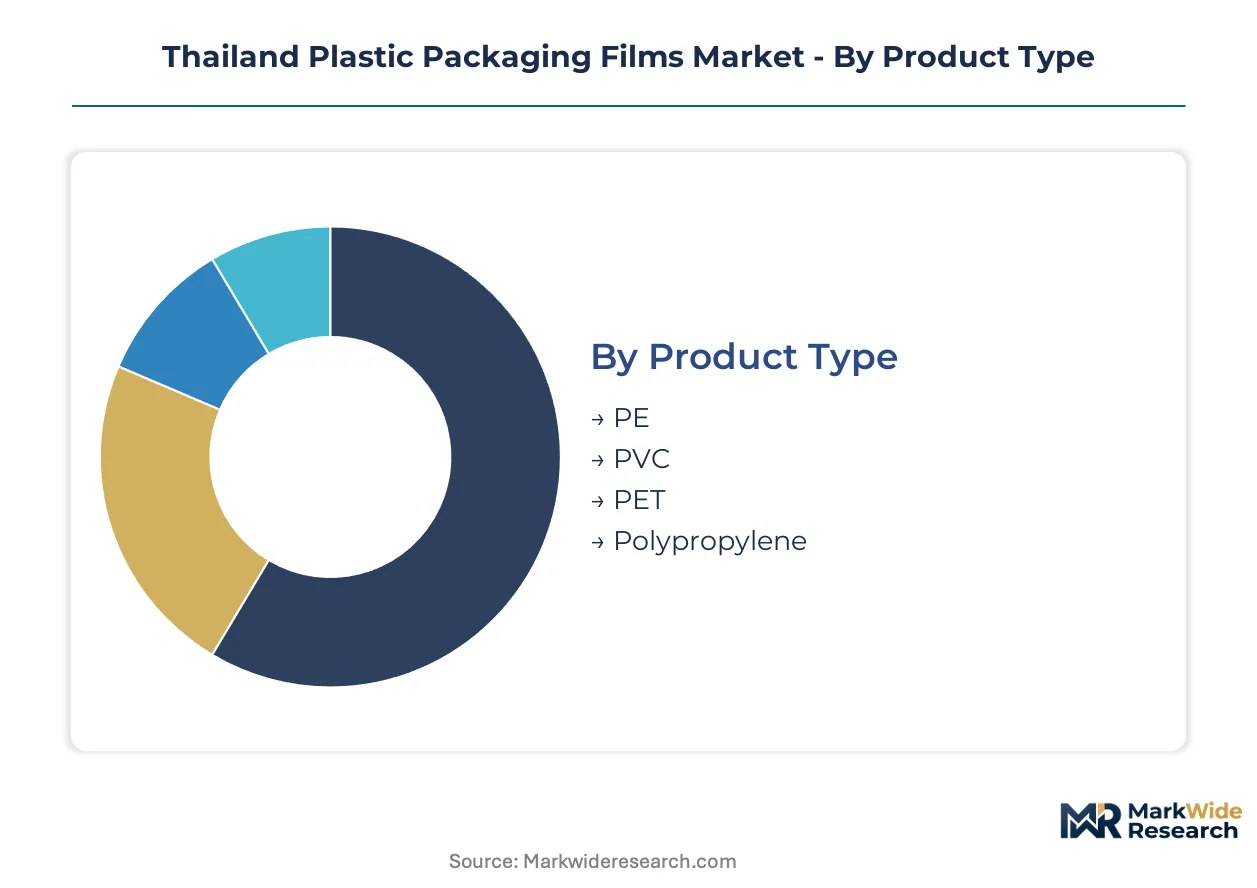
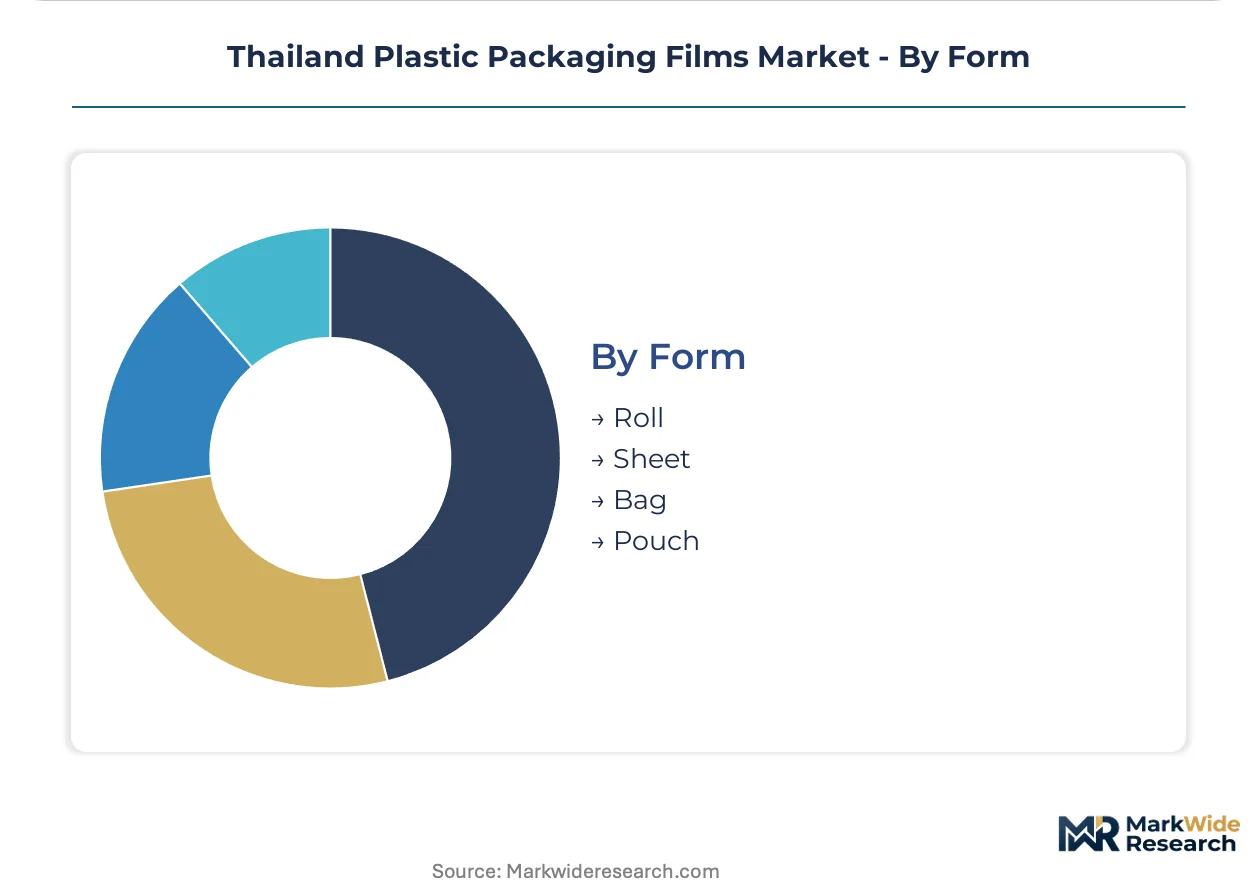
Thailand's plastic packaging films market segments along material chemistry, end-use application, physical specification, and delivery format. Each dimension carries distinct procurement rhythms and margin profiles that shape converter investment priorities across the Eastern Economic Corridor.
Product Type:
Cycle times vary sharply across polymer platforms, with commodity grades turning inventory weekly while specialty films sit on specification reviews for months.
- PE:Linear low-density and high-density polyethylene films dominate e-commerce mailers and agricultural mulch applications. Bangkok logistics platforms are consolidating procurement around post-consumer recycled-content specifications, forcing extruders to secure pyrolysis-derived feedstock partnerships.
- Polypropylene:Biaxially oriented PP films command premium positioning in snack and confectionery packaging where heat-seal strength and optical clarity enable brand differentiation. Rayong-based converters with metallization capability are capturing share from multi-layer laminate suppliers as mono-material mandates tighten.
- PET:Polyester films serve pharmaceutical blister packs and high-barrier lidding where TISI migration compliance creates defensible margin pools. Thai converters with dual EU-equivalent certification are extending into ASEAN regional supply chains for multinational drugmakers.
- PVC:Polyvinyl chloride films retain niche demand in shrink-wrap applications for beverage multipacks, though environmental scrutiny is compressing volume growth in retail channels.
Polypropylene dominates installed base across food packaging. PE is where expansion concentrates as circular economy mandates reshape procurement specifications.
End Use Industry:
Margin structures diverge sharply between regulated pharmaceutical applications and commodity consumer goods, with certification costs filtering competitive intensity.
- Food:Ready-to-eat meal processors in Bangkok and Samut Prakan are driving specification cycles toward quarterly reviews, prioritizing short-run customization speed over unit cost. Vacuum-deposited barrier coatings are displacing ethylene vinyl alcohol laminates in seafood export packaging.
- Beverage:ASEAN bottlers anchor PET film demand through Indorama Ventures' integrated polymerization assets. Shrink-label and lidding applications are consolidating around converters with in-house printing and metallization capability.
- Pharmaceuticals:Blister pack films require TISI food-contact certification plus pharmaceutical-grade cleanroom processing, creating entry barriers that favor established players with accredited laboratory relationships.
- Consumer Goods:Personal care and household product packaging exhibits highest price sensitivity, with procurement concentrating among converters offering three-tier pricing structures across premium, standard, and economy certification grades.
Food commands the broadest converter footprint. Pharmaceuticals is climbing the fastest as multinational drugmakers regionalize ASEAN manufacturing.
Thickness:
Downgauging pressure is reshaping equipment utilization across extrusion fleets, with technical limitations emerging below critical thresholds.
- Thin:Sub-20 micron films serve overwrap and lamination applications where material yield drives cost optimization. Agricultural mulch below 15 microns lacks puncture resistance for mechanized harvesting in Thailand's cassava belts.
- Medium:20-50 micron constructions balance barrier performance with processability across the widest application range, from snack pouches to industrial liners.
- Thick:50-100 micron films sustain demand in heavy-duty shipping sacks and construction vapor barriers where tensile strength overrides downgauging economics.
- Extra Thick:Above-100 micron specifications serve specialized industrial and agricultural applications with limited substitution risk from thinner alternatives.
Medium thickness holds the largest installed equipment base. Thin films are gaining share fastest as sustainability metrics drive gram-per-package reduction targets.
Form:
Supply chain configuration varies by delivery format, with roll stock favoring integrated producers and finished pouches rewarding customization specialists.
- Roll:Unconverted film rolls serve downstream converters and in-house packaging operations across the Eastern Economic Corridor, with just-in-time delivery contracts favoring petrochemical-adjacent suppliers.
- Sheet:Cut-to-size sheets address thermoforming and die-cutting applications in automotive and electronics packaging with precise dimensional tolerances.
- Bag:Pre-formed bags capture demand from mid-size food processors lacking in-house form-fill-seal capability, with Bangkok distributors holding consignment inventory for rapid replenishment.
- Pouch:Stand-up and flat pouches command premium positioning in ready-to-eat meals and premium snacks, with Thai Future Incorporation competing on short-run digital printing turnaround.
Roll form dominates resin throughput volume. Pouch conversion is where value-add expansion concentrates as brand owners unbundle supply contracts by application type.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's Ministry of Natural Resources and Environment anchors regulatory momentum across Southeast Asian flexible packaging markets, with national plastic waste management roadmaps in neighboring economies tracking Bangkok's circular economy enforcement timeline.
Indonesia
Seafood exporters in Jakarta and Surabaya are procuring mono-material PE films to preempt EU packaging waste directive compliance costs. BIS-equivalent conformity assessment requirements from the Indonesian National Standardization Agency block Thai film exporters from domestic procurement tenders. Industrial concentration clusters around Cilegon's petrochemical corridor where downstream converters are retrofitting extrusion lines for recyclable substrates.
Vietnam
Ho Chi Minh City-based food processors are accelerating flexible packaging specification cycles to quarterly reviews amid retailer private-label expansion. The Vietnam Directorate for Standards, Metrology and Quality enforces QCVN migration limits that favor larger integrated producers over fragmented importers. Binh Duong province hosts the fastest-growing converter base as brand owners unbundle supply contracts by application type.
Philippines
Manila's ready-to-eat meal segment is driving demand for short-run customization speed over unit cost in supplier selection criteria. The Food and Drug Administration administers food-contact plastic certifications that create compliance backlogs for mid-size converters. Cavite and Laguna industrial zones concentrate metallization-capable film producers serving ASEAN beverage bottlers.
Malaysia
Port Klang logistics platforms are specifying recycled-content PE mailer films, opening volume contracts for extruders with post-consumer pellet supply agreements. The Department of Standards Malaysia mandates SIRIM certification for food-contact plastics that filters cross-border participation. Penang's electronics packaging cluster sustains demand for precision-cut sheet formats with tight dimensional tolerances.
Singapore
Pharmaceutical multinationals regionalizing ASEAN manufacturing are consolidating procurement with converters holding dual TISI and EU-equivalent certification. The Health Sciences Authority enforces pharmaceutical-grade cleanroom processing standards that create entry barriers favoring established players. Tuas biomedical park anchors regional blister pack film demand as drugmakers shift production from European bases.
Thailand Plastic Packaging Films Market Competitive Landscape
Integrated petrochemical downstream operators and specialized converting houses split the market along capability specialization lines. Three structural archetypes dominate: resin-integrated conglomerates with captive feedstock access, mid-scale converters competing on short-run customization velocity, and multinational packaging groups leveraging regional certification networks. Dominant competitive moves center on metallization equipment deployment for mono-material barrier performance and pyrolysis partnerships to secure food-grade recycled polypropylene feedstock.
Within the integrated conglomerate tier, SCG Packaging Public Company Limited and Indorama Ventures exemplify resin-adjacent positioning that commands domestic flexible packaging supply relationships. Among specialized converting houses, Thai Future Incorporation Public Company Limited occupies a position defined by printed laminated film customization speed rather than commodity scale. These three named entities represent the strategic poles around which mid-market competitors must position to defend margin structures against certification cost pressures and specification cycle compression.
| Leading Market Players |
|---|
| Thai Future Incorporation Public Company Limited |
| SCG Packaging Public Company Limited |
| TPBI Public Company Limited |
| Polyplex (Thailand) Public Company Limited |
| Amcor plc |
| Sealed Air Corporation |
| Huhtamäki Oyj |
| Mondi Group |
| Indorama Ventures |
| Others |
Pricing and Supply Chain Analysis
Naphtha import dependency determines both the pricing tier spreads between petrochemical-integrated and merchant converters and the geographic clustering of extrusion capacity around Map Ta Phut. Thai film producers face margin compression when regional naphtha benchmarks spike, forcing non-integrated players to absorb cost volatility or cede share to SCG Packaging and Indorama Ventures with captive ethylene supply.
Pricing Analysis
Rayong-based converters command 15-20% premiums over Bangkok merchant extruders due to just-in-time resin access from adjacent petrochemical complexes. Pricing stratifies across premium, standard, and economy tiers based on TISI certification grade and volume commitment scale. Cost compression in standard-grade PE films is intensifying because Bangkok logistics platforms are consolidating procurement around post-consumer recycled-content specifications. Consumer goods packers exhibit highest price sensitivity, while pharmaceutical blister pack buyers prioritize optical consistency and migration compliance over unit cost.
Supply Chain Analysis
Upstream feedstock for Thai flexible packaging draws from Saudi Arabia, Qatar, and Singapore naphtha suppliers, with domestic ethylene and propylene supply covering roughly 60% of resin demand. Key inputs include linear low-density polyethylene, biaxially oriented polypropylene resin, and metallized aluminum deposition materials. Single-source vulnerability concentrates in pyrolysis-derived recycled polypropylene, where chemical recycling partnerships remain nascent. Distribution runs through Eastern Economic Corridor co-located converting complexes serving Bangkok food processors and Samut Sakhon seafood exporters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's plastic packaging films sector operates as a substitution defense against paper-based barrier materials and molded fiber alternatives gaining traction in EU export channels. Incumbents must navigate this threat while consolidating procurement relationships around mono-material recyclability mandates.
For Market Incumbents: Pre-empt paper substitution by accelerating metallized mono-material barrier deployment ahead of EU packaging waste directive enforcement. Secure pyrolysis partnerships with Map Ta Phut petrochemical complexes to lock in food-grade recycled polypropylene supply before chemical recycling capacity tightens. Certification investment in dual TISI and EU-equivalent standards anchors pharmaceutical film margins against commodity PE erosion.
For New Entrants and Emerging Players: Samut Prakan's ready-to-eal meal segment offers underpenetrated white-space for short-run digital printing specialists competing on quarterly specification cycle velocity. Target e-commerce secondary packaging in Bangkok logistics platforms with post-consumer recycled-content PE mailer films. Go-to-market angle should emphasize rapid TISI compliance certification through accredited laboratory relationships rather than commodity scale.
For Investors and Strategic Acquirers: Thailand's anticipated carbon border adjustment discussions with the EU reshape the acquisition landscape toward converters with embedded emissions transparency and renewable energy offtake agreements. Long-term viability favors metallization-capable mid-scale players with pharmaceutical certification pathways. Signal to watch is Ministry of Natural Resources and Environment enforcement timeline for recycled content thresholds in food-contact applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Metallization Equipment Deployment | Enables mono-material barrier performance without ethylene vinyl alcohol laminates in snack packaging. |
| Pyrolysis Partnership Formation | Unlocks food-grade recycled polypropylene supply for circular economy compliance in flexible films. |
| TISI Dual Certification Investment | Extends converter access to pharmaceutical blister packs and ASEAN regional supply chains. |
| E-commerce Packaging Line Expansion | Captures Bangkok logistics platform demand for post-consumer recycled-content PE mailer films. |
| Downgauging Technology Retrofit | Reduces gram-per-package metrics for agricultural mulch and snack film sustainability targets. |
Research Methodology
A standing panel of extrusion plant managers, procurement leads at Bangkok food processors, TISI-accredited laboratory directors, and Eastern Economic Corridor logistics coordinators provided ongoing calibration across the analysis window. Primary interviews with these stakeholders combined with secondary validation from Thailand Industrial Standards Institute filings, customs and trade data, SEC 10-K disclosures from listed packaging groups, and petrochemical downstream capacity databases. Bottom-up resin throughput estimates and top-down packaging value chain sizing were triangulated to anchor market dimensions.
Scenario-bracketing around naphtha price volatility, recycled content mandate enforcement timing, and EU carbon border adjustment scope generated bounded projections. Segmentation dimensions modeled include polymer chemistry, end-use application, thickness specification, and delivery format across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating downgauging trends and mono-material substitution rates. Industry-specific forecast inputs included Eastern Economic Corridor capacity expansion announcements and Ministry of Natural Resources and Environment regulatory roadmap milestones.
Practitioners should monitor naphtha benchmark movements, TISI laboratory certification backlogs, and EU-ASEAN trade negotiation progress for early signals requiring forecast revision. Cross-checking against petrochemical downstream utilization rates reported by Thai Olefins and Thai Polyethylene is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Volatile Corrosion Inhibitors (VCI) Packaging Market
Packaging Barrier Films
Oil Resistant Packaging Market
Packaging Barrier Films
Protective Films Market
Packaging Barrier Films
High Barrier Packaging Films for Pharmaceuticals Market
Packaging Barrier Films
Collation Shrink Films Market
Packaging Barrier Films
Pan Liners Market
Packaging Barrier Films
Micro-Perforated Food Packaging Market
Packaging Barrier Films
Barrier Packaging Market
Packaging Barrier Films
Self-Adhesive Films Market
Packaging Barrier Films
Barrier Coatings for Packaging Market
Packaging Barrier Films
Anti-Static Packaging Film Market
Packaging Barrier Films
Global High Barrier Packaging Films Market
Packaging Barrier Films
Specialty Films Market
Packaging Barrier Films
Barrier Coated Flexible Paper Packaging Market
Packaging Barrier Films
Global Adhesive Films Market
Packaging Barrier Films
High Barrier Lidding Film Market