
 Polyolefin Films Market | 2026-2036
Polyolefin Films Market Size, Share, and Industry Trends Forecast 2026-2036
Polyolefin Films Market Outlook
Price-performance divergence between premium coextruded barrier films and commodity monolayer grades is restructuring procurement behavior across consumer packaged goods. Berry Global Group leverages vertical integration from resin compounding to finished film to sustain margin capture in medical and food barrier segments. Sealed Air Corporation competes through equipment-film bundling that locks in converter loyalty and extends replacement cycle revenue. Amcor plc anchors its position via pharmaceutical blister and sterile packaging certifications that command specification-driven purchasing.
Polyolefin films are thermoplastic sheets or membranes composed primarily of polyethylene (LDPE, LLDPE, HDPE) or polypropylene (PP), manufactured through blown film, cast film, or biaxial orientation processes with thicknesses spanning ultra-thin (below 12 microns) to heavy-gauge constructions above 250 microns. These films serve as moisture barriers, sealant layers, and protective substrates across packaging, agricultural mulching, medical sterilization, and construction membrane applications. LLDPE dominates flexible packaging volume due to puncture resistance and downgauging compatibility, while PP film growth concentrates in high-clarity food wrap and biaxially oriented snack packaging where stiffness and optical properties command premium positioning. Thick and medium gauges retain stable demand in construction vapor barriers and agricultural greenhouse sheeting, though ultra-thin segments face margin compression from resin volatility and energy-intensive processing.
FDA food contact regulations, EPA emissions standards for extrusion operations, and REACH substance restrictions in Europe collectively shape formulation choices, driving substitution of conventional additives with bio-based nucleating agents and recycled content feedstocks. China's GB standards and NMPA medical device packaging rules further fragment compliance requirements for multinational film suppliers operating across multiple jurisdictions. Stakeholders must monitor evolving extended producer responsibility frameworks and chemical recycling infrastructure buildout, as these will determine which resin platforms and film architectures retain cost-competitive circularity credentials.
Market Dynamics
Mono-material film architectures are displacing multi-layer barrier constructions as Extended Producer Responsibility frameworks and chemical recycling infrastructure investments reshape converter R&D priorities across packaging value chains.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability targets are redirecting converter capex toward compatible mono-material LLDPE and PP structures that qualify for circular feedstock streams.
- E-commerce fulfillment expansion:Automated packaging lines in China and Southeast Asia are consuming puncture-resistant LLDPE films for appliance and consumer goods export protection.
- Downgauging technology diffusion:Advanced metallocene catalyst systems enable sub-12 micron films without performance loss, reducing resin input per packaged unit.
Market Restraints
- Ethylene feedstock volatility:Naphtha-cracker margins in the US Gulf Coast and Middle East swing with crude differentials, compressing film extruder margins on fixed-price contracts.
- Barrier performance ceiling:Mono-material polyethylene structures cannot match EVOH or aluminum oxide barrier layers for oxygen-sensitive pharmaceuticals and retort foods.
- Mechanical recycling contamination:Multi-layer legacy films in existing waste streams degrade rPET and rPE quality, limiting circular feedstock availability for food-contact applications.
Strategic Opportunities
- India flexible packaging underpenetration:Organized retail and quick-commerce expansion in Mumbai and Bangalore is generating first-time demand for pre-stretched cling films and wicketed bags.
- Chemical recycling scale-up:Pyrolysis and gasification investments in Rotterdam and Singapore promise food-grade recycled polyolefin feedstocks that mechanical routes cannot deliver.
- Agricultural film durability extension:UV-stabilized greenhouse sheeting with 5+ season lifespans commands premium positioning against single-season mulch films in water-stressed growing regions.
Industry Challenges
- Multi-jurisdiction compliance fragmentation:Simultaneous navigation of FDA 21 CFR food contact rules, REACH SVHC restrictions, and China's GB 4806 standards strains formulation teams at multinational converters.
- Extrusion equipment retooling costs:Transitioning from multi-layer coextrusion lines to mono-material-capable configurations requires die and cooling ring replacements that extend payback periods.
- Post-consumer feedstock quality inconsistency:Variable contamination levels in baled agricultural and commercial film waste disrupt blown film process stability and finished product clarity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyolefin Films Market |
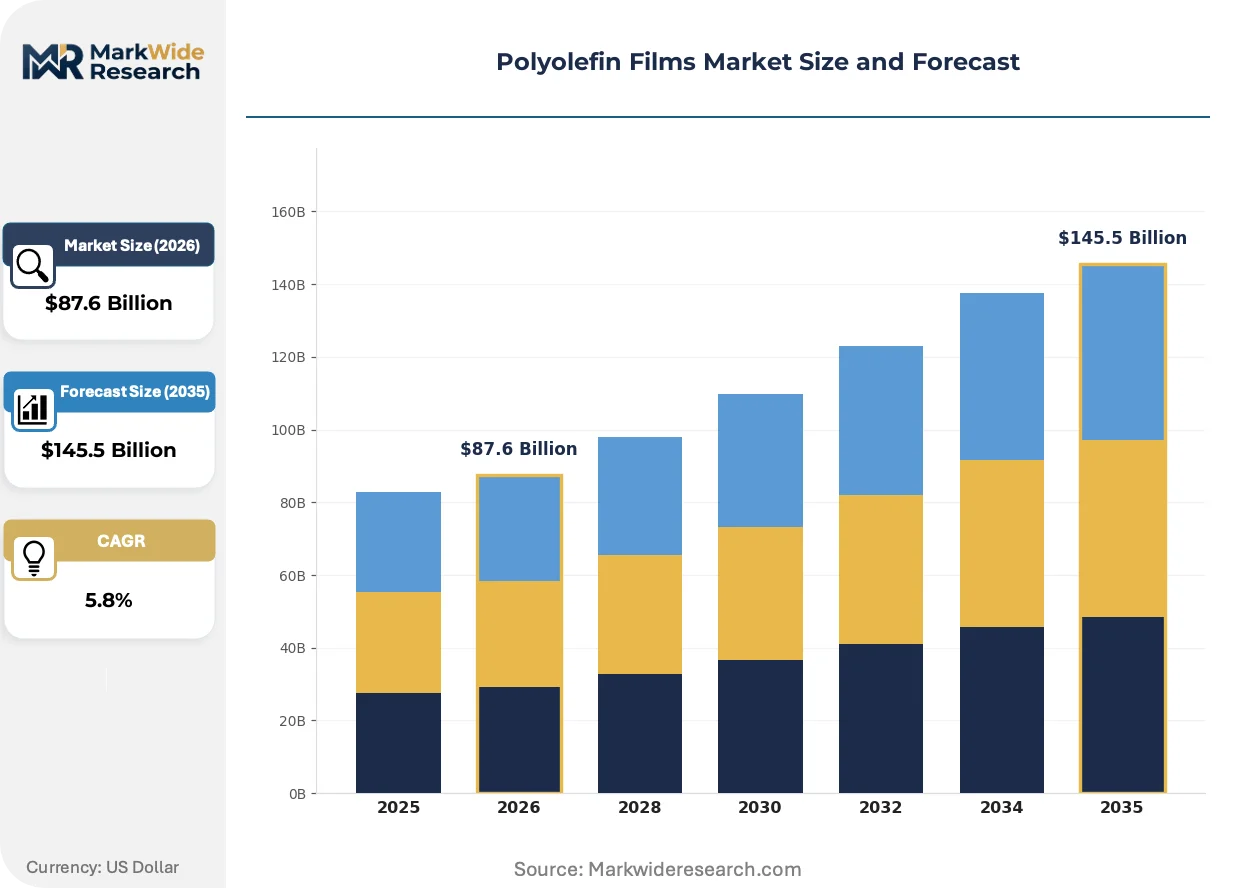
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $145.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LDPE, LLDPE, HDPE, PP Application: Packaging, Agriculture, Medical, Construction Thickness: Thick, Medium, Thin, Ultra-Thin Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | Berry Global Group, Sealed Air Corporation, Intertape Polymer Group, Amcor plc, Coveris Holdings S.A., Sigma Plastics Group, Winpak Ltd., SABIC, Toray Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyolefin Films Market Strategic Shifts
Advanced polymerization catalysts, regulatory-mandated design-for-recycling protocols, and converter-processor data integration are converging to redefine performance specifications and procurement criteria across flexible packaging applications.
Metallocene and single-site catalyst systems are electrifying molecular architecture control in LLDPE production. Food processors in Germany and Japan are specifying these resins for downgauged fresh produce bags that maintain dart impact resistance at 25% reduced thickness. The technology is electrifying margin compression for commodity Ziegler-Natta resin suppliers unable to match optical and mechanical property combinations.
REACH substance restrictions and the EU Green Deal's packaging circularity targets are eliminating perfluorinated substances and certain phthalate plasticizers from food-contact films. Converter formulation groups are substituting bio-based nucleating agents and mineral reinforcements to maintain clarity and stiffness. Pharmaceutical blister packaging manufacturers face the steepest compliance timelines, with EMA notified body reviews extending certification cycles by 8-14 months.
Brand-owner sustainability scorecards are reshaping supplier selection criteria beyond unit cost. Nestlé and Unilever procurement teams in Western Europe now weight post-consumer recycled content percentages and carbon footprint disclosures at 30-40% of vendor evaluation matrices. This behavioral pivot elevates film converters with mass-balance certifications and renewable electricity sourcing above price-competitive Asian exporters lacking verified chain-of-custody documentation.
Polyolefin Films Market Segmentation
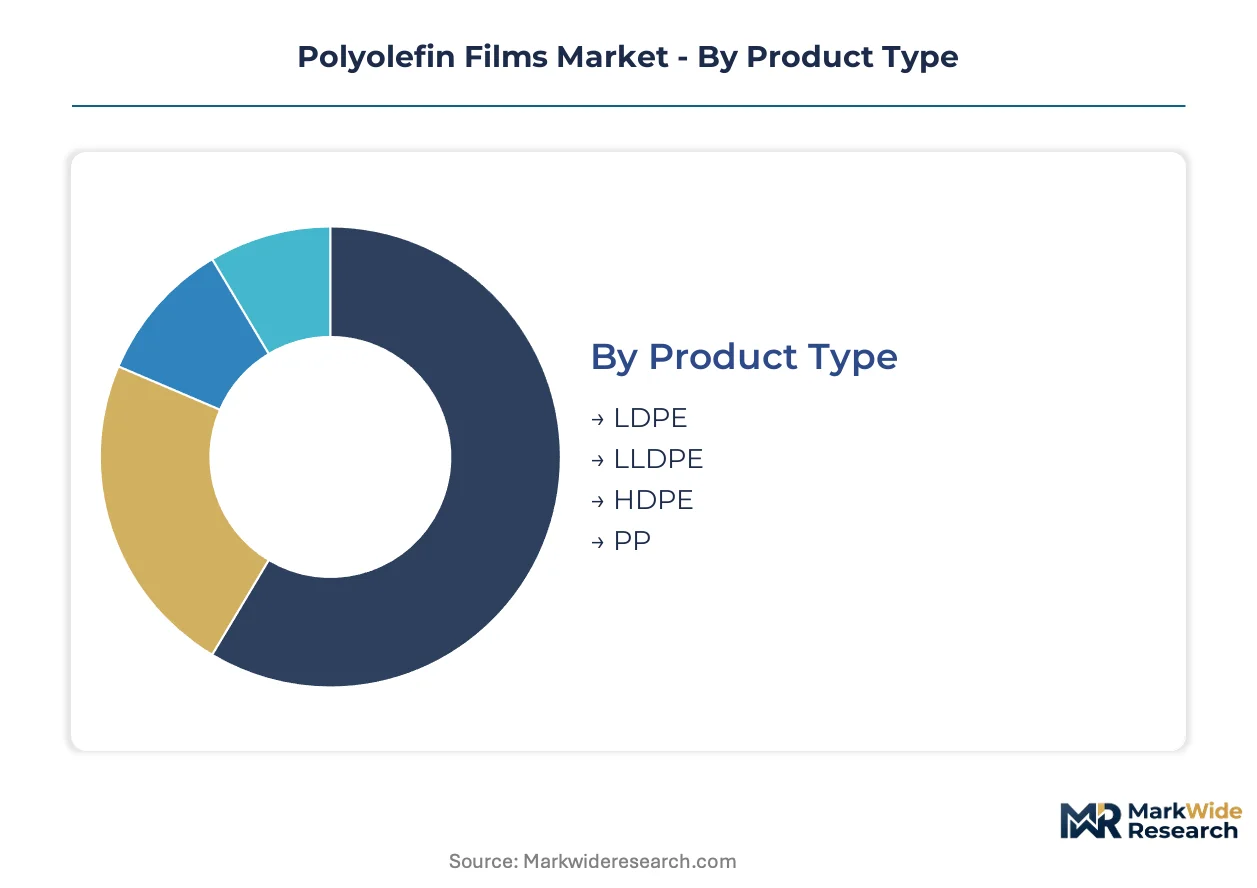
Polyolefin film specifications diverge sharply across resin chemistry, end-use performance thresholds, and supply chain access models. Converter procurement teams segment sourcing strategies by melt index requirements, barrier specifications, and regional regulatory compliance burdens.
Product Type:
Metallocene catalyst advances and comonomer selection differentiate performance tiers across polyethylene and polypropylene platforms.
- LDPE:Manufactured via high-pressure tubular or autoclave processes with high levels of long-chain branching. Demand clusters in Germany and France for shrink-wrap applications requiring high clarity and low haze in beverage multipacks.
- LLDPE:Linear low-density polyethylene produced with butene, hexene, or octene comonomers delivers superior puncture resistance and tear propagation strength. E-commerce fulfillment centers in China and the US specify downgauged LLDPE for automated packaging lines handling irregular appliance geometries.
- HDPE:High-density grades offer stiffness and moisture barrier properties for heavy-duty shipping sacks and industrial liners. Demand concentrates in construction vapor barrier specifications requiring tensile modulus above 800 MPa.
- PP:Polypropylene films excel in biaxial orientation processes yielding high clarity and dimensional stability. Food wrap applications in Japan and South Korea drive premium positioning for cast and oriented PP structures.
Mature deployment sits with LDPE in legacy shrink and stretch formats. Newer deployment is concentrated in metallocene LLDPE grades enabling sub-15 micron downgauging without dart impact degradation.
Application:
End-use performance requirements dictate resin selection, additive packages, and certification burdens across diverging value chains.
- Packaging:Flexible food packaging consumes the majority volume, with FDA and EU food contact compliance mandatory. Fresh produce bags and pre-made pouches in Western Europe drive mono-material LLDPE specifications aligned with EPR frameworks.
- Agriculture:Greenhouse sheeting and mulch films demand UV stabilization packages extending field lifespan. Water-stressed growing regions in Spain and Israel specify 5+ season durability premiums against single-season commodity alternatives.
- Medical:Sterilization pouches and pharmaceutical blister packs require ISO 11607 and USP Class VI certifications. The validation timelines extend procurement cycles substantially versus standard packaging grades.
- Construction:Vapor barrier membranes and under-slab protection films prioritize puncture resistance and permeance ratings. Building code compliance in Germany and the Netherlands mandates specific WVTR thresholds.
Volume concentration favors packaging applications. Steepest expansion trajectory is appearing in medical sterilization films as healthcare infrastructure investments accelerate across Southeast Asia.
Thickness:
Gauge selection balances material cost, mechanical performance, and processing efficiency across extrusion and conversion equipment.
- Thick:Gauges above 250 microns serve construction vapor barriers and heavy-duty agricultural greenhouse sheeting. German and Dutch building regulations specify minimum thickness for crawl space and under-slab applications.
- Medium:50-250 micron range dominates industrial liners and intermediate bulk container liners. Demand is stable across chemical and food ingredient handling applications.
- Thin:12-50 micron films constitute standard flexible packaging formats for snacks, baked goods, and frozen foods. Metallocene resin advances enable gauge reduction without seal strength compromise.
- Ultra-Thin:Sub-12 micron structures push equipment limits and require precise gauge control. Japanese fresh produce markets specify these grades for cost-efficient high-volume bag production.
Margin stability concentrates in thick and medium gauges where resin volatility passes through more directly. Ultra-thin segments face compression from energy-intensive processing and yield loss sensitivity.
Distribution Channel:
Channel selection reflects order scale, customization requirements, and technical service intensity across converter tiers.
- Wholesale:Distributors inventory commodity grades for small and mid-tier converters lacking direct resin contracts. Regional wholesalers in India and Brazil bridge supply gaps for non-integrated processors.
- Retail:Limited to specialty film formats for agricultural and construction end-users requiring immediate availability. Hardware and farm supply chains in the US and Australia stock greenhouse and mulch film SKUs.
- Online:Digital procurement platforms aggregate spot availability for standard grades. The channel is gaining traction among mid-tier converters in China seeking price transparency and reduced procurement cycle times.
- Direct Sales:Major resin producers and integrated film manufacturers serve high-volume converters through dedicated account management. Technical service intensity justifies the cost structure for pharmaceutical and medical device packaging certifications.
Direct relationships dominate premium certified segments. Online channels are expanding most quickly in commodity LLDPE and LDPE grades where specifications are standardized and technical support requirements are minimal.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor in Germany anchors European polyolefin film demand through its dense concentration of flexible packaging converters serving pharmaceutical and food sectors. Rotterdam's chemical recycling infrastructure investments are reshaping feedstock access for circular polyolefin production. Shenzhen's appliance manufacturing clusters in China consume substantial LLDPE volumes for export protection films.
China
E-commerce fulfillment automation in Shenzhen and Dongguan drives puncture-resistant LLDPE consumption for appliance export packaging. GB 4806 food contact standards mandate additive compliance for domestic and export-bound films. The Yangtze River Delta converter cluster is retooling toward mono-material structures to align with EU import requirements.
Germany
REACH SVHC restrictions are eliminating perfluorinated substances from food-contact film formulations. The Packaging Act's EPR frameworks redirect converter capex toward recyclable mono-material LLDPE architectures. Düsseldorf-based medical packaging specialists extend certification cycles for pharmaceutical blister films under EMA notified body reviews.
United States
FDA 21 CFR food contact regulations govern additive migration limits across flexible packaging applications. The Gulf Coast ethylene production corridor supplies resin to extrusion operations in Texas and Louisiana. Chicago-area converters serve Midwest food processors with downgauged metallocene LLDPE for fresh produce formats.
India
Organized retail expansion in Mumbai and Bangalore generates first-time demand for pre-stretched cling films and wicketed bags. FSSAI packaging safety standards tighten compliance burdens for imported film formulations. Gujarat's petrochemical corridor is expanding blown film capacity to serve domestic flexible packaging growth.
Japan
METI circular economy roadmaps accelerate design-for-recycling protocols across packaging value chains. Ultra-thin sub-12 micron specifications for fresh produce bags push metallocene resin adoption in Kanto region converter operations. Osaka-based food processors specify high-clarity cast PP for premium retail presentation formats.
Polyolefin Films Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification intensity and technical service depth. The vendor base stratifies between integrated resin-to-film producers, specialized medical packaging converters, and regional extrusion operations serving commodity packaging. Three archetypes dominate: backward-integrated multinationals with captive resin supply, certification-heavy specialists in pharmaceutical and sterile segments, and scale-driven regional players competing on throughput and logistics proximity. Capacity expansion and portfolio diversification toward mono-material architectures constitute the dominant competitive moves as EPR frameworks tighten.
Among North American packaging specialists, Berry Global Group exemplifies backward-integrated positioning from resin compounding through finished film. Sealed Air Corporation occupies the equipment-film bundling archetype that locks converter loyalty through integrated system sales. Amcor plc anchors the certification-intensive tier via pharmaceutical blister and sterile packaging credentials that command specification-driven purchasing. These three represent divergent margin-capture strategies as regulatory complexity increases.
| Leading Market Players |
|---|
| Berry Global Group |
| Sealed Air Corporation |
| Intertape Polymer Group |
| Amcor plc |
| Coveris Holdings S.A. |
| Sigma Plastics Group |
| Winpak Ltd. |
| SABIC |
| Toray Industries |
| Others |
Value Chain & Pricing Dynamics
The EU Packaging and Packaging Waste Regulation gates qualified supply for converters serving European brand owners, with mono-material certification requirements separating premium-tier pricing access from commodity spot markets. Resin volatility in the US Gulf Coast and Middle Eastern naphtha crackers feeds directly into film extruder margin compression, while downstream buyers in pharmaceutical and food sectors absorb certified-grade premiums through specification-locked contracts.
Pricing Analysis
Outcome-based pricing anchors value capture for equipment-film bundled systems that guarantee packaging line uptime and yield rates. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification intensity, with FDA food-contact and ISO 11607 sterile validations commanding 15-25% uplifts over commodity grades. Cost compression in ultra-thin gauge segments is intensifying because energy-intensive processing and yield loss sensitivity erode margins faster than resin pass-through mechanisms. Small and mid-tier converters lacking direct resin contracts exhibit highest price sensitivity, while pharmaceutical packaging specialists demonstrate lowest sensitivity due to specification-driven purchasing and extended validation timelines.
Supply Chain Analysis
Container freight rates from the Middle East and Asia to Rotterdam and Hamburg directly impact landed cost competitiveness for imported resin and finished film. Supply concentrates in China, Saudi Arabia, and the United States, with ethylene production anchored in naphtha crackers and shale gas feedstocks. Raw material dependencies center on ethylene and propylene monomers, metallocene catalyst systems, and UV stabilizer additive packages. Single-source vulnerability in metallocene catalyst supply creates bottlenecks for premium LLDPE grades specified in downgauged applications. Distribution runs through direct sales relationships for certified medical and pharmaceutical segments, while wholesale distributors serve commodity packaging converters in India and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation erects a cost-of-compliance moat that favors incumbent converters with existing mono-material R&D pipelines and EPR framework alignment. REACH SVHC restrictions and FDA 21 CFR migration limits compound formulation expertise barriers, raising capital requirements for new entrant qualification.
For Market Incumbents: Anchor certification intensity in pharmaceutical and sterile packaging segments where EMA notified body reviews and USP Class VI validations extend replacement cycle loyalty. Deepen backward integration into metallocene resin compounding to secure margin capture as commodity Ziegler-Natta suppliers face displacement. Defend against Asian exporters lacking verified chain-of-custody documentation by accelerating mass-balance certifications and renewable electricity sourcing that satisfy Nestlé and Unilever sustainability scorecards. For New Entrants and Emerging Players: Mid-tier converters in India's organized retail expansion represent the most penetrable buyer archetype, with Mumbai and Bangalore generating first-time demand for pre-stretched cling films and wicketed bags lacking domestic supply depth. White-space concentration appears in chemical recycling feedstock partnerships for pyrolysis-derived food-grade polyolefins that mechanical routes cannot deliver. Pursue equipment-film bundling partnerships with quick-commerce fulfillment centers seeking automated packaging line integration without legacy converter entrenchment. For Investors and Strategic Acquirers: Rotterdam chemical recycling infrastructure reaching operational scale is the leading indicator that circular feedstock access will determine which resin platforms retain cost-competitive positioning across the analysis window. Long-term viability favors converters with mono-material architecture portfolios and mass-balance certification depth over multi-layer legacy specialists facing retooling obsolescence. Target acquisition candidates with established EMA notified body relationships and pharmaceutical blister packaging validation histories. Monitor GB 4806 compliance investments by Yangtze River Delta converters as signal of China-EU trade corridor positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Architecture Transition | Aligns converter R&D with EU EPR recyclability mandates and brand-owner sustainability scorecards. |
| Metallocene Resin Backward Integration | Captures margin compression from commodity Ziegler-Natta suppliers in downgauged fresh produce applications. |
| Chemical Recycling Feedstock Partnership | Secures food-grade circular polyolefin access that mechanical recycling routes cannot deliver for pharmaceutical blister films. |
| Equipment-Film Bundling Expansion | Locks converter loyalty through integrated system sales extending replacement cycle revenue in automated packaging lines. |
| Mass-Balance Certification Investment | Elevates positioning above price-competitive Asian exporters in Unilever and Nestlé procurement evaluations. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this polyolefin films analysis, cross-referenced with primary interviews conducted with blown film plant managers, flexible packaging procurement leads at CPG brand owners, chemical recycling technology licensors, and EMA regulatory affairs specialists. Secondary validation drew from FDA 21 CFR food contact substance inventories, ECHA REACH SVHC candidate list updates, EU Packaging and Packaging Waste Regulation impact assessments, and China customs import-export statistics for LLDPE and PP film grades. Bottom-up volume modeling triangulated against top-down resin consumption estimates from petrochemical corridor production disclosures.
Data-stream reconciliation across resin production, film extrusion capacity, and end-use consumption patterns informed the analytical framework throughout the projection horizon. Segmentation dimensions modeled include resin chemistry tier, application performance threshold, thickness gauge category, and distribution channel access model. CAGRs were derived from elasticity-adjusted demand projections incorporating downgauging technology diffusion rates and regulatory compliance timeline impacts. Industry-specific forecast inputs encompassed metallocene catalyst adoption curves, chemical recycling infrastructure buildout schedules, and EPR framework implementation phasing across European member states.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ethylene feedstock volatility, pyrolysis yield rate improvements, and multi-jurisdiction regulatory harmonization progress. Forecasts reflect assumptions regarding converter retooling capex availability and brand-owner sustainability procurement weighting stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
In-Mould Label Film Market
Poly film
LDPE Films Market
Poly film
North America Shrink and Stretch Film Market
Poly film
India BOPP Films Market
Poly film
Peelable and Resealable Films Market
Poly film
Global EVOH Films for Packaging Market
Poly film
Global PVDC Coated Films Market
Poly film
Germany Plastic Packaging Films Market
Poly film
Anti Fog Polycarbonate Films and Sheets Market
Poly film
Morocco Plastic Packaging Films Market
Poly film
Global Specialty Films Polymer Market
Poly film
PP Film Blowing Machine Market
Poly film
France Plastic Packaging Films Market
Poly film
United Kingdom Plastic Packaging Films Market
Poly film
Metallized Film Market
Poly film
Canada Plastic Packaging Films Market