
 Bopet Films Market | 2026-2036
Bopet Films Market Size, Share, and Industry Trends Forecast 2026-2036
Bopet Films Market Analysis
Asset-light leasing models for metallizing and coating lines is tilting competitive dynamics toward mid-scale converters with lower capital barriers. Toray Industries, Inc. leverages captive resin supply and integrated film-to-converter relationships across Japan and Southeast Asia. UFlex Limited anchors its position through backward integration into resin compounding and extensive Indian distribution networks. SRF Limited specializes in high-barrier metallized grades for domestic snack and pharmaceutical packaging, competing on technical service rather than scale alone.
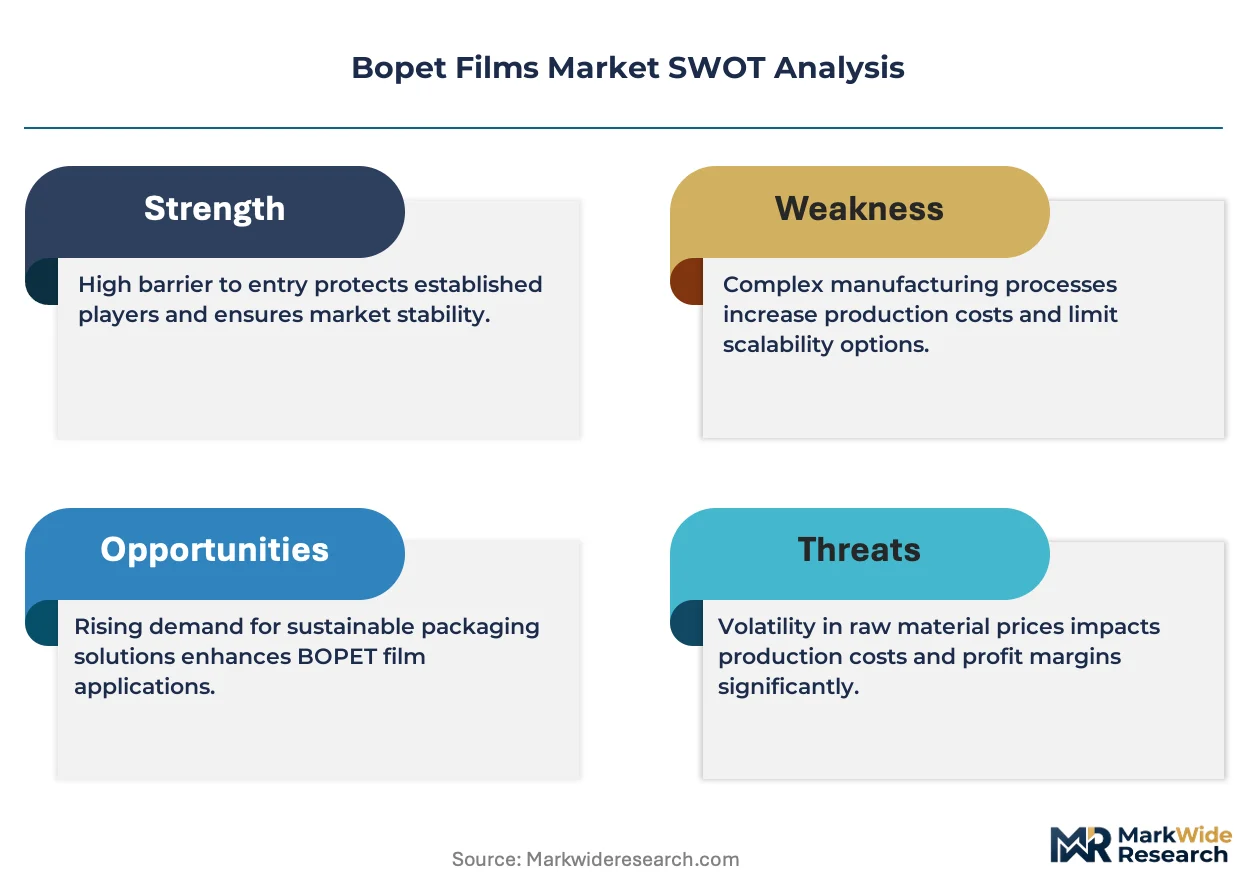
Biaxially oriented polyethylene terephthalate (BOPET) film is a thermoplastic polyester produced by sequential stretching in machine and transverse directions, yielding tensile strengths exceeding 200 MPa and dimensional stability across temperatures from minus sixty to one hundred fifty degrees Celsius. Its primary purpose spans flexible packaging lidding, electronics insulation substrates, and automotive solar control laminates where optical clarity and barrier performance converge. High barrier and optical product types command premium positioning as converters prioritize shelf-life extension and display-grade transparency in food and electronics applications. The below fifty micron thickness segment leads volume shipments for lightweight flexible packaging, while above one hundred fifty micron grades concentrate margin pools in industrial belting and electrical insulation where certification requirements limit supplier entry.
The FDA maintains food-contact substance notification requirements for BOPET resins and additives used in US packaging, while REACH and the EU Green Deal impose recycled content mandates and extended producer responsibility schemes affecting European film specifications. China's GB standards and SAMR labeling rules shape import eligibility and domestic product certification for foreign suppliers. Stakeholders must monitor evolving mono-material recyclability criteria across FDA, EFSA, and EU packaging directives, as regulatory alignment between food safety and circular economy frameworks will determine which film constructions retain market access.
Market Dynamics
Flexible food packaging converters are accelerating BOPET adoption to displace multi-layer laminates as the EU Green Deal and F-Gas Regulation mandate recyclable mono-material structures, while China scales domestic capacity to capture Asia-Pacific electronics substrate demand.
Growth Catalysts
- EU Green Deal packaging mandates:Recyclability requirements under the EU Green Deal and F-Gas Regulation are compelling converters to specify BOPET mono-material films over mixed-polymer laminates in food packaging applications.
- Electronics substrate demand:Asia-Pacific semiconductor and display manufacturing clusters in China, South Korea, and Taiwan are absorbing high optical-grade BOPET for flexible printed circuit and OLED encapsulation layers.
- Lightweighting protocols:Below fifty micron BOPET grades are penetrating snack and confectionery flexible packaging as brands pursue gram-per-pack reductions without sacrificing barrier performance.
Market Restraints
- PTA and MEG feedstock volatility:Purified terephthalic acid and monoethylene glycol prices track crude oil and naphtha indices, compressing film margin predictability for non-integrated converters.
- Metallizing equipment concentration:Vacuum metallizing line supply concentrates among German, Japanese, and Chinese equipment builders, creating eighteen-to-twenty-four month lead time bottlenecks for capacity expansion.
- AlOx coating performance ceiling:Aluminum oxide barrier coatings on BOPET remain permeable to oxygen at levels exceeding aluminum metallization, limiting shelf-life extension for oxygen-sensitive proteins.
Strategic Opportunities
- India pharmaceutical blister expansion:CDSCO quality mandates and domestic generic drug volume growth are creating demand for high-barrier clear and opaque BOPET lidding films in secondary packaging.
- Post-consumer recycled content integration:EFSA and FDA food-contact notifications for recycled PET feedstocks are opening pathways for chemically recycled BOPET in premium food packaging segments.
- Solar control automotive glazing:BOPET-based infrared-reflective laminates are penetrating electric vehicle cabin thermal management systems as OEMs seek weight reduction over glass.
Industry Challenges
- Thin-film metallizing technician scarcity:Vacuum coating process engineering expertise concentrates among aging workforces in Japan and Germany, constraining operational ramp rates for new production lines.
- Food-contact notification timelines:FDA substance notification reviews for novel BOPET additives and recycled content sources extend twelve-to-eighteen months, delaying product qualification for seasonal packaging programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bopet Films Market |
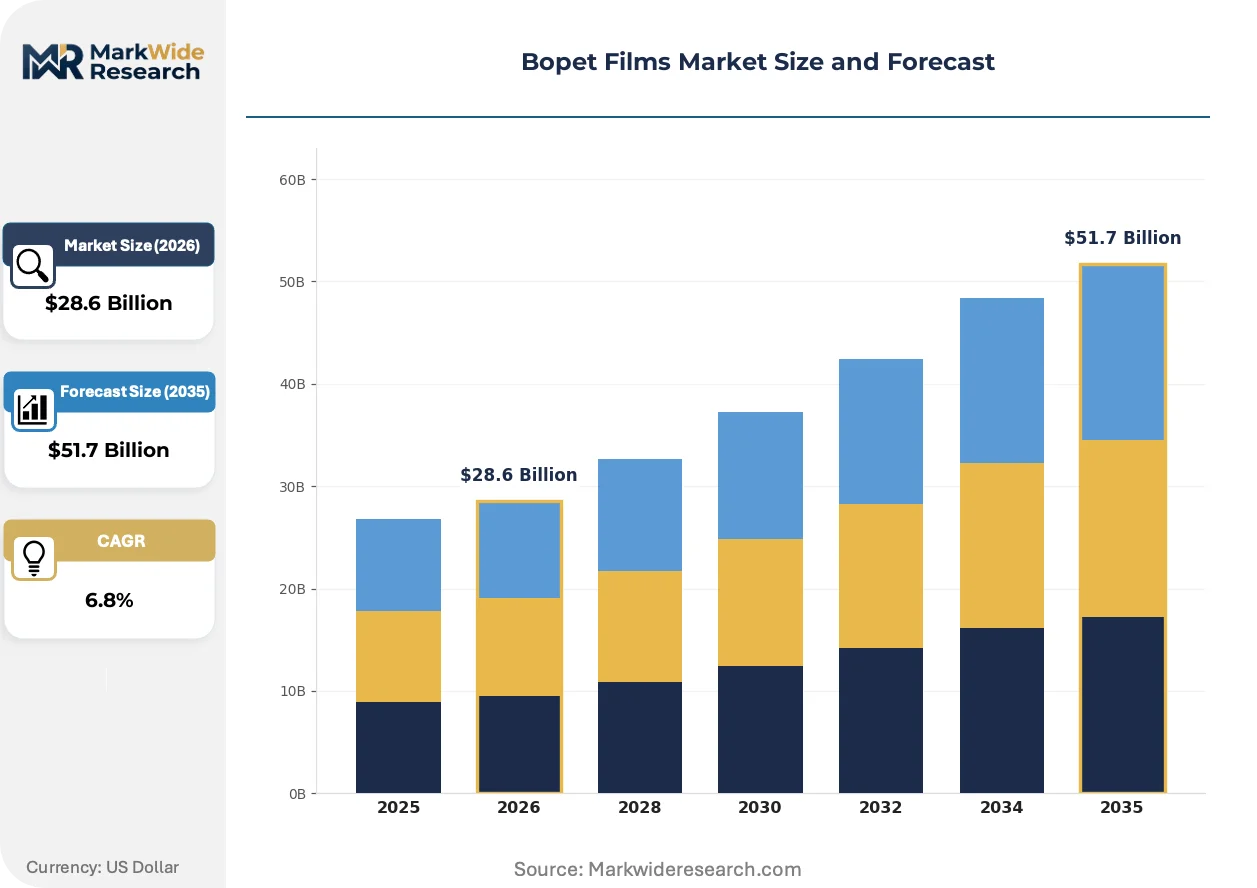
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal, High Barrier, Optical, Electrical Application: Packing, Electronics, Automotive, Labels End User: Food, Pharmaceuticals, Consumer Goods, Industrial Thickness: Below 50 Micron, 50-100 Micron, 100-150 Micron, Above 150 Micron |
| Companies Covered | Toray Industries, Inc., UFlex Limited, Polyplex Corporation Ltd., SRF Limited, Jindal Poly Films Ltd., DuPont Teijin Films, Mitsubishi Polyester Film, Inc., Kolon Industries, Inc., SKC Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bopet Films Market Emerging Trajectories
Digital printing compatibility and barrier coating advances are compressing converter specification cycles, while regulatory alignment on recyclability is fragmenting regional film construction standards.
Plasma-enhanced chemical vapor deposition of silicon oxide barrier layers is collapsing the performance gap between transparent high-barrier films and aluminum-metallized alternatives. Premium snack and ready-meal brands in Western Europe are qualifying SiOx-coated BOPET for microwaveable lidding at volumes that now threaten metallized film share in display-critical applications. This coating technology is collapsing the historical trade-off between optical clarity and oxygen barrier that has structured the premium packaging segment for two decades.
REACH authorization requirements for chromium VI in surface treatments are accelerating migration to alternative adhesion promotion chemistries in BOPET metallizing operations. The industrial consequence is qualification overhead for existing metallized film grades and capital retooling for European converters. Food packaging specifications in Germany and France are most affected, with major retailers now requiring documentation of chromium-free process chains for private-label sourcing.
Converter-direct resin compounding partnerships are displacing spot-market PET chip procurement among mid-scale flexible packaging producers. This channel shift compresses working capital requirements and locks in volume commitments, but fragments the merchant resin spot market. The pattern is most visible in China's Yangtze River Delta, where domestic film producers are securing captive resin streams from integrated PTA-PET operators to undercut import-dependent competitors.
Bopet Films Market Segmentation
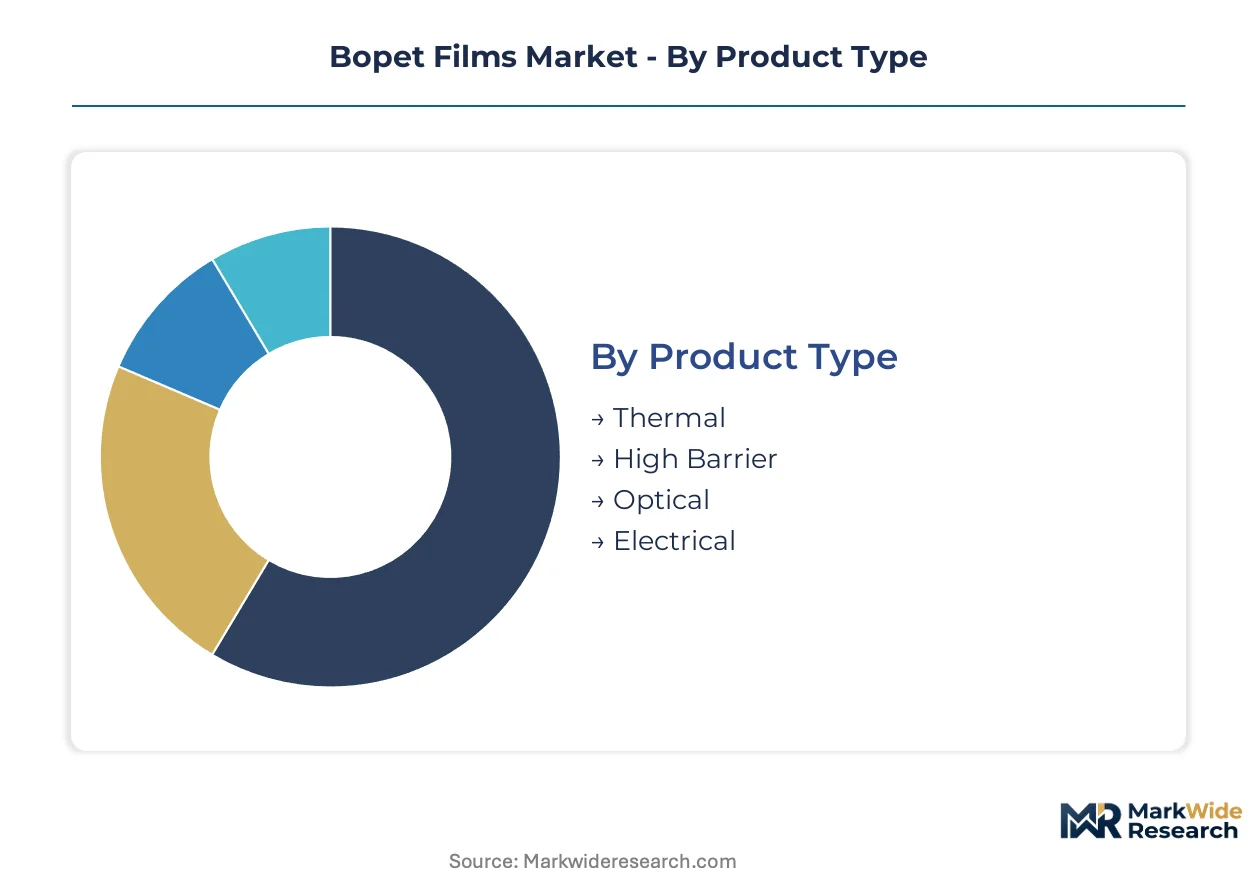
BOPET film specifications diverge sharply across end-use requirements, with thermal stability, optical clarity, and barrier performance dictating resin formulations and stretching protocols. Converter procurement patterns cluster around thickness bands and coating technologies that align with specific packaging, electronics, and industrial workflows.
Product Type:
Converters specify from a use-case spectrum spanning heat-resistant lidding, gas barrier protection, display-grade clarity, and dielectric insulation, each demanding distinct additive packages and surface treatments.
- High Barrier:Metallized or ceramic-coated grades achieve oxygen transmission rates below 0.5 cc/m²/day through aluminum oxide or silicon oxide deposition. European snack brands under EU Green Deal recyclability mandates are specifying clear high-barrier mono-materials to replace mixed-polymer laminates in premium packaging.
- Optical:Ultra-low haze grades below 1% light scattering serve as substrate films for liquid crystal display diffusers and OLED encapsulation. South Korean and Taiwanese display panel manufacturers are absorbing volume for flexible electronics substrates where surface roughness tolerances approach nanometer precision.
- Thermal:Heat-stabilized grades withstand 150°C processing temperatures for hot-fill and retort packaging applications.
- Electrical:Corona-treated or primed surfaces enable wire and cable insulation, motor slot liners, and capacitor dielectrics.
The dominant share belongs to High Barrier, while Optical is closing the gap fastest.
Application:
Cost tier stratification separates commodity flexible packaging from certified electronics and automotive specifications.
- Packing:Flexible lidding, pouch structures, and form-fill-seal webs constitute volume demand, with below-fifty-micron grades displacing thicker alternatives. Food brands in Germany and France are qualifying chromium-free metallized films for private-label sourcing under REACH authorization pressures.
- Electronics:Flexible printed circuit substrates, release films for semiconductor wafer dicing, and battery separator coatings command premium positioning. Chinese domestic film producers are scaling capacity to serve Yangtze River Delta electronics manufacturing clusters.
- Automotive:Infrared-reflective laminates for electric vehicle cabin glazing and interior trim applications.
- Labels:Pressure-sensitive face stocks and in-mold decoration films for durable goods branding.
Packing commands absolute volume leadership, though Electronics exhibits the steepest expansion trajectory.
End User:
Customer type determines certification burden and technical service intensity, with pharmaceutical and food contact applications imposing the strictest notification requirements.
- Food:Flexible packaging for snacks, confectionery, ready meals, and beverage lidding drives thickness demand toward lightweighting. FDA food-contact substance notifications and EFSA recycled content approvals are gating market access for novel resin formulations.
- Pharmaceuticals:Blister pack lidding and cold-form foil alternatives require particulate-free surfaces and consistent seal integrity. India's CDSCO quality mandates are expanding demand for high-barrier clear and opaque grades in domestic generic drug packaging.
- Consumer Goods:Personal care sachets, detergent pods, and cosmetic overwrap applications.
- Industrial:Membrane switch overlays, solar panel backsheet components, and adhesive tape carriers.
Food retains the largest installed base, while Pharmaceuticals is gaining share fastest on regulatory compliance premiums.
Thickness:
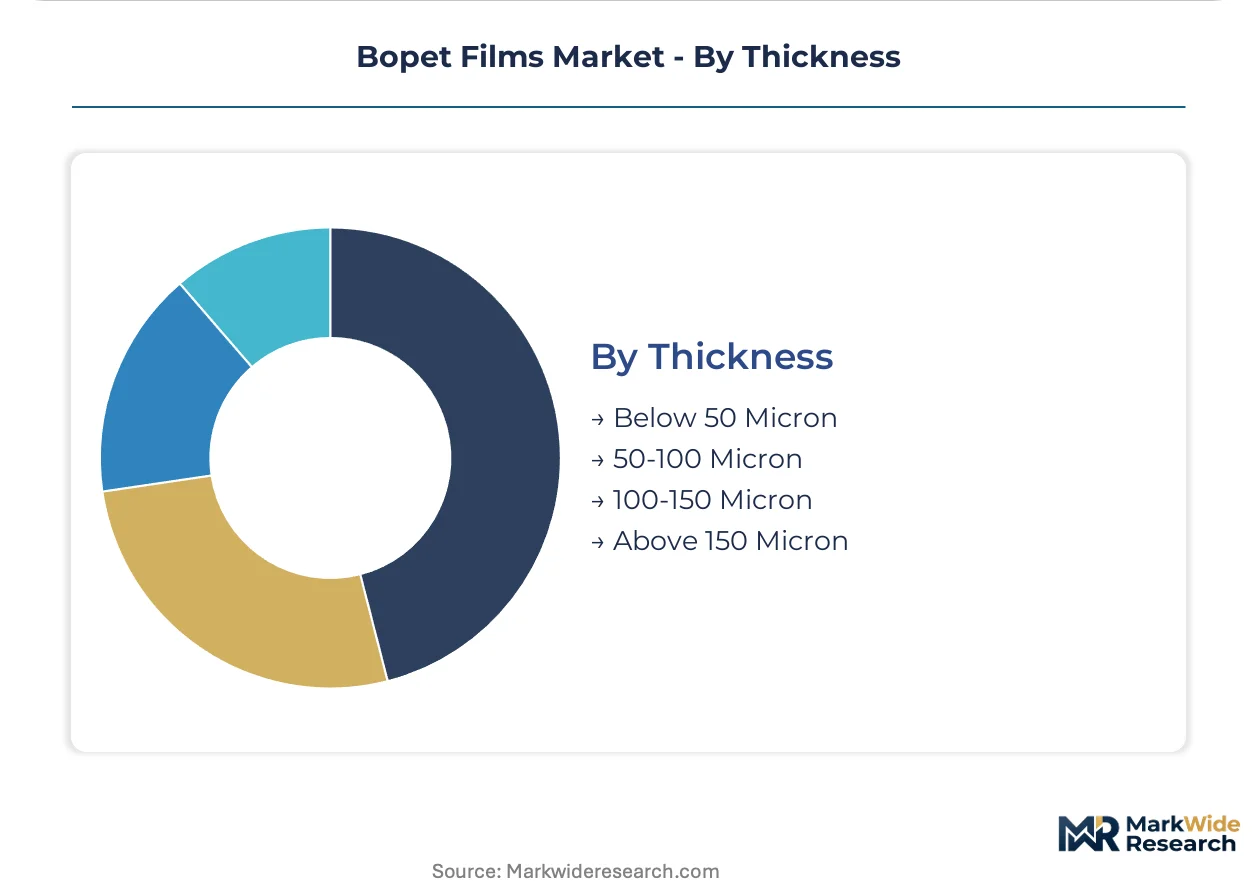
Margin concentration inversely tracks volume, with ultra-thin commodity grades competing on scale and heavy-gauge industrial films protected by certification barriers.
- Below 50 Micron:Lightweight flexible packaging for snack and confectionery applications where gram-per-pack reductions support brand sustainability claims. Converters in Western Europe are specifying these grades for mono-material recyclable structures under extended producer responsibility schemes.
- Above 150 Micron:Heavy-gauge industrial belting, electrical insulation laminates, and automotive glazing interlayers where UL and IEC certifications limit qualified supplier pools. Japanese and German equipment builders dominate vacuum metallizing line supply for these premium segments.
- 50-100 Micron:General-purpose packaging and label face stocks balancing stiffness and conformability.
- 100-150 Micron:Structural lidding and industrial tapes requiring enhanced puncture resistance.
Below 50 Micron holds volume leadership, while Above 150 Micron captures the highest margin per kilogram.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are reshaping regional BOPET supply chains as integrated resin producers in Asia undercut import-dependent converters in Western markets. China's domestic capacity expansion has flipped the country from net importer to regional exporter, while European converters face feedstock cost disadvantages against Middle Eastern PTA supply.
China
Electronics substrate demand from Yangtze River Delta semiconductor clusters absorbs premium optical-grade BOPET volumes. GB standards and SAMR labeling rules govern domestic certification requirements for foreign film suppliers. Jiangsu and Zhejiang provinces host integrated PTA-PET-film production complexes that now export metallized grades to Southeast Asian packaging converters.
Germany
REACH authorization pressures and EU Green Deal recyclability mandates are accelerating chromium-free metallizing process conversions among flexible packaging producers. The F-Gas Regulation tightens specifications for mono-material barrier films in snack and ready-meal applications. Bavaria and North Rhine-Westphalia concentrate vacuum metallizing technical expertise and equipment supply relationships.
United States
Food-contact substance notification requirements at FDA create twelve-to-eighteen month qualification timelines for novel BOPET additives and recycled content sources. Lightweighting protocols in snack packaging drive below-fifty-micron grade specification. The Southeast and Midwest host flexible packaging converter clusters serving private-label retail programs.
India
CDSCO quality mandates and domestic generic drug volume expansion are creating demand for high-barrier clear and opaque BOPET lidding films in pharmaceutical blister packaging. Maharashtra and Gujarat anchor backward-integrated resin compounding and film production capacity. Converter-direct resin partnerships are displacing spot-market PET chip procurement among mid-scale flexible packaging producers.
South Korea
Display panel manufacturers in Gyeonggi Province absorb ultra-low haze optical-grade BOPET for OLED encapsulation and liquid crystal display diffuser substrates. MFDS pharmaceutical packaging regulations shape barrier film specifications for domestic drug exports. Busan-Ulsan industrial corridors concentrate electronics-grade film conversion and metallizing operations.
Bopet Films Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream where captive resin supply and metallizing equipment access determine margin capture. The vendor base stratifies across three tiers: integrated petrochemical-film producers with captive PTA-PET streams, independent film converters leasing metallizing capacity, and regional packaging-grade specialists competing on technical service intensity. Consolidation pressure concentrates among mid-scale converters facing eighteen-to-twenty-four month vacuum metallizing equipment lead times. Dominant competitive moves include backward integration into resin compounding and converter-direct partnership structures that lock in volume commitments.
Among Japan and Korea-based integrated producers, Toray Industries, Inc. and SKC Co., Ltd. occupy positions defined by captive resin supply and regional electronics substrate relationships. Within the India-focused converter tier, UFlex Limited and SRF Limited exemplify archetypes differentiated by backward integration depth and barrier-grade technical specialization. These named entities anchor competitive dynamics without exhausting the strategic variety present in the vendor landscape.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| UFlex Limited |
| Polyplex Corporation Ltd. |
| SRF Limited |
| Jindal Poly Films Ltd. |
| DuPont Teijin Films |
| Mitsubishi Polyester Film, Inc. |
| Kolon Industries, Inc. |
| SKC Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Chinese PTA-PET integrated producers anchor upstream supply concentration, funneling margin capture toward metallizing-equipped converters in Germany and Japan while squeezing non-integrated film processors in India and Southeast Asia. Pricing power concentrates at the resin-film boundary where captive feedstock access separates margin-accretive players from spot-market converters facing working capital compression.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium-mid-economy pricing differentiation rests on optical-grade certification tier and metallizing equipment access, with below-fifty-micron commodity grades facing the steepest price sensitivity among snack packaging converters. Cost compression in standard grades is intensifying because Chinese domestic capacity expansion is flooding Asian export markets with undifferentiated volume. Pharmaceutical blister pack buyers exhibit least price sensitivity due to CDSCO and FDA notification requirements that lock in qualified supplier relationships.
Supply Chain Analysis
Extended payment terms from resin suppliers to mid-scale converters are becoming standard in India's Gujarat and Maharashtra clusters, mirroring supply-chain finance facilities pioneered by Japanese trading houses. Geographic supply concentration centers on China, India, and Germany for film extrusion, with South Korea and Taiwan anchoring optical-grade finishing. Raw material dependencies draw from purified terephthalic acid, monoethylene glycol, and vacuum metallizing equipment. Single-source vulnerability concentrates in German and Japanese metallizing line builders. Distribution runs through converter-direct resin partnerships displacing merchant spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for vacuum metallizing process optimization represent a service-attach opportunity expanding faster than base film tonnage, as aging technician scarcity in Japan and Germany forces converters to outsource operational expertise.
For Market Incumbents: Insulate metallizing capacity positions against Chinese optical-grade entrants by securing captive resin streams through backward integration into PTA-PET compounding. Lock in converter-direct partnerships with European snack brands facing EU Green Deal recyclability mandates. Prioritize chromium-free process qualification ahead of REACH authorization deadlines to defend private-label sourcing relationships with German and French retailers. For New Entrants and Emerging Players: Pursue pharmaceutical blister packaging white space in India's Maharashtra and Gujarat corridors where CDSCO quality mandates are expanding faster than domestic high-barrier film supply. Target below-fifty-micron mono-material specifications for European flexible packaging converters seeking gram-per-pack lightweighting. Lead with asset-light metallizing line leasing models to bypass eighteen-to-twenty-four month equipment lead time bottlenecks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed flexible packaging converters in Southeast Asia lacking integrated resin supply. Five-to-ten year viability hinges on regulatory alignment between FDA and EFSA food-contact notification pathways for recycled content integration. Watch for EFSA approval timelines for chemically recycled PET feedstocks as inflection indicator for premium segment revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive PTA-PET supply locks in margin capture against Chinese export pricing pressure. |
| Chromium-Free Metallizing Process Conversion | REACH authorization compliance secures German and French retailer private-label sourcing. |
| Asset-Light Metallizing Line Leasing | Lower capital barriers enable mid-scale converter entry into high-barrier film segments. |
| Converter-Direct Resin Partnerships | Volume commitments displace spot-market procurement in India's Yangtze River Delta clusters. |
| Post-Consumer Recycled Content Integration | EFSA and FDA notification pathways open premium food packaging segment access. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from listed petrochemical producers, and technical standards documentation from FDA and EFSA. Primary interviews spanned plant managers at integrated film producers, procurement leads at European flexible packaging converters, and technical directors at vacuum metallizing equipment builders. Secondary validation drew from REACH authorization databases, CDSCO quality mandate circulars, and SAMR labeling rule updates. Bottom-up volume modeling triangulated against top-down resin consumption estimates.
Forecast inputs include optical-grade certification tier, metallizing equipment access, and regional regulatory cluster alignment across the projection horizon. Segmentation dimensions modeled span product type, application end-use, thickness band, and coating technology. CAGRs derived from elasticity-adjusted demand curves incorporating feedstock price volatility and converter qualification timeline constraints. Industry-specific inputs encompass EU Green Deal recyclability mandate implementation pace and Asia-Pacific electronics substrate absorption rates.
Sensitivities concentrate around PTA-MEG feedstock price volatility, vacuum metallizing equipment delivery timelines, and FDA food-contact notification review durations. Forecasts reflect documented assumptions regarding regulatory alignment and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Starch-Based Plastic Films Market
Poly film
Blown Film Extruder Market
Poly film
Global BOPET Packaging Films Market
Poly film
Soft Touch Lamination Film Market
Poly film
Thermoplastic Polyurethane (TPU) Films Market
Poly film
Global Specialty Films Polymer Market
Poly film
Waste Wrap Film Market
Poly film
MOPP Packaging Films Market
Poly film
North America Polyimide Films Market
Poly film
North America BOPP Films Market
Poly film
Europe Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market
Poly film
Global Polyethylene Packaging Market
Poly film
Polymer Dispersed Liquid Crystal (PDLC) Film Market
Poly film
EVOH Encapsulation Film Market
Poly film
Italy Plastic Packaging Films Market
Poly film
PCR Bubble Films Market