

PCR Bubble Films Market Size, Share, and Industry Trends Forecast 2026-2036
PCR Bubble Films Market Insights
Buyer concentration in e-commerce logistics is consolidating as major fulfillment networks centralize packaging procurement under sustainability mandates. Sealed Air leverages its global manufacturing footprint to serve these consolidated accounts with certified recycled-content films. Pregis anchors its position through specialized cushioning solutions tailored to fragile electronics shipments. Smurfit Westrock competes by extending its paper-based packaging expertise into hybrid film-paper protective formats.
PCR bubble films are multilayer polyethylene structures manufactured with post-consumer recycled content, typically incorporating 30-90% recycled resin through coextrusion processes to maintain air retention and puncture resistance for protective packaging applications. Multi-layer films dominate value capture due to superior barrier performance and compatibility with high-percentage recycled feedstocks, while laminated formats occupy premium niches requiring moisture or static protection. Surface protection applications within the electronics end-user industry represent the fastest-expanding segment as semiconductor and display manufacturers adopt closed-loop packaging programs.
The EPA guides recycled-content standards in the United States, while REACH and the EU Green Deal establish material traceability and carbon-intensity thresholds across European supply chains. ECHA's SCIP database requirements for articles containing recycled substances are forcing film converters to document polymer chain-of-custody from collection through final product. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to invest in mechanical recycling partnerships or advanced chemical recycling infrastructure to secure PCR resin supply.
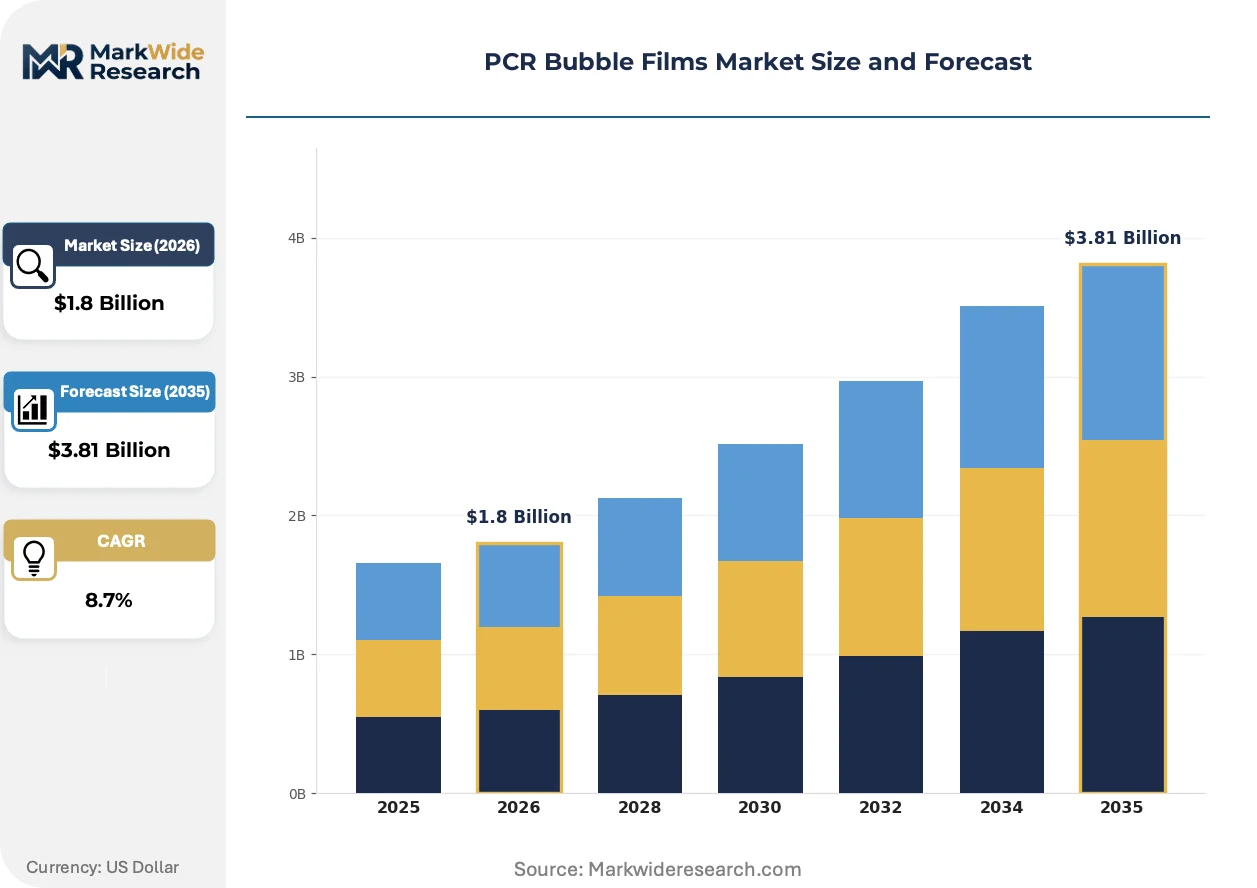
Market Dynamics
E-commerce fulfillment networks are centralizing packaging procurement under sustainability mandates, forcing film converters to certify recycled-content percentages and document polymer chain-of-custody through ECHA's SCIP database requirements.
Growth Catalysts
- EU Green Deal carbon-intensity thresholds:REACH compliance mandates are compelling European converters to source certified post-consumer resin, expanding addressable demand for traceable PCR films across Germany, France, and Italy.
- Electronics closed-loop packaging programs:Semiconductor and display manufacturers are specifying recycled-content protective films for surface protection applications, creating pull-through demand from component suppliers.
- Mechanical recycling infrastructure expansion:Collection and sorting investments in North American and European urban centers are stabilizing PCR polyethylene feedstock availability for coextrusion operations.
Market Restraints
- PCR resin price volatility:Post-consumer polyethylene bale costs fluctuate with oil-indexed virgin resin spreads, compressing converter margins when recycled feedstocks trade at par or premium to virgin material.
- Mechanical recycling yield losses:Contamination and polymer degradation during reprocessing limit high-percentage PCR incorporation in multi-layer structures without performance degradation in air retention and puncture resistance.
- REACH substance traceability burdens:ECHA documentation requirements for articles containing recycled substances impose administrative costs and compliance timelines that disadvantage smaller film converters without dedicated regulatory staff.
Strategic Opportunities
- Advanced chemical recycling partnerships:Pyrolysis and depolymerization investments by petrochemical majors in the US Gulf Coast and Rotterdam-Antwerp corridor promise food-grade compatible recycled polyethylene for protective packaging applications.
- Hybrid film-paper protective formats:Paper-based cushioning expertise from corrugated packaging specialists creates white space for recyclable all-fiber protective systems displacing pure polymer solutions in premium e-commerce channels.
- Extended producer responsibility frameworks:French and German packaging waste regulations are mandating minimum recycled-content percentages, creating regulatory tailwinds for certified PCR film suppliers with documented mass-balance chain-of-custody.
Industry Challenges
- Polymer chemist and process engineer scarcity:Coextrusion expertise for multi-layer recycled-content films is concentrated among aging technical workforces in Midwestern US and German packaging clusters, constraining capacity expansion timelines.
- SCIP database integration complexity:Film converters must reconfigure ERP systems to capture polymer origin data from municipal collection through reprocessing, entailing six-to-twelve-month certification timelines for EU market access.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PCR Bubble Films Market Trends and Innovations
Active developments across material science, regulatory compliance architecture, and buyer procurement models are restructuring competitive requirements for PCR bubble film suppliers serving protective packaging end-uses.
Multi-layer coextrusion with high-percentage recycled feedstocks is overtaking single-layer blown film construction in protective packaging specifications. E-commerce fulfillment centers in Germany and the Netherlands are requiring 50-70% PCR content in cushioning materials for consumer electronics shipments. This technology shift is compressing demand for conventional virgin-only bubble films while rewarding converters with backward integration into mechanical recycling operations.
REACH Article 33 obligations and ECHA's SCIP database implementation are mandating polymer chain-of-custody documentation from collection through final article. European film converters must now map recycled resin flows through reprocessors, compounders, and extrusion operations to satisfy downstream electronics and pharmaceutical packaging customers. The electronics end-use vertical is most affected, with semiconductor manufacturers auditing supplier compliance quarterly and disqualifying non-conforming material sources.
Centralized procurement by sustainability-mandated fulfillment networks is displacing fragmented distributor-based purchasing for protective packaging materials. Amazon, Zalando, and Otto Group are consolidating European bubble film contracts under master service agreements specifying certified recycled-content percentages and carbon footprint disclosures. This concentration is most visible in German and Polish logistics corridors, where three to five fulfillment networks now account for majority demand in regional protective packaging procurement.
PCR Bubble Films Market Segmentation
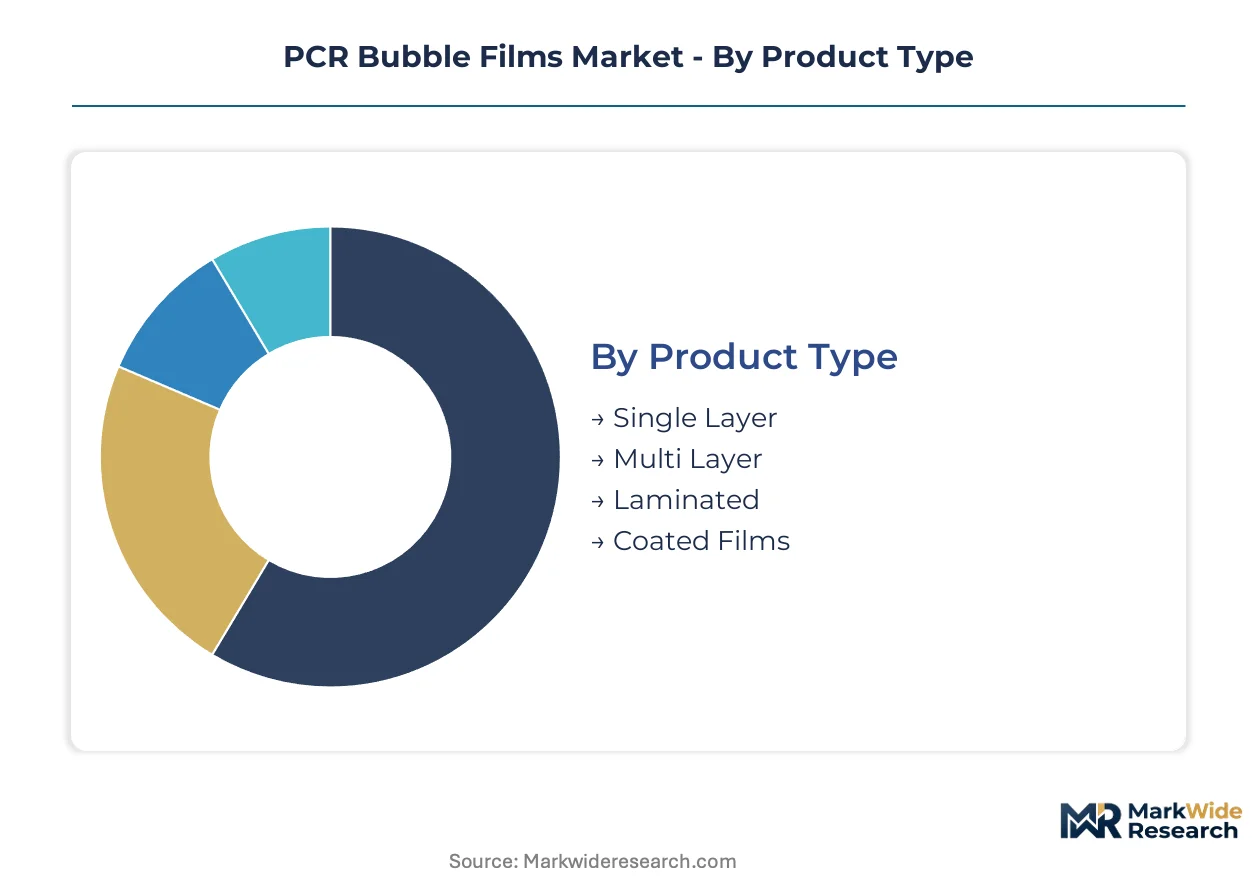
PCR bubble film specifications diverge sharply between high-volume commodity cushioning and precision surface protection for sensitive components. Procurement decisions increasingly hinge on recycled-content certification thresholds and multi-layer coextrusion compatibility rather than unit cost alone.
Product Type:
Volume-driven applications favor simpler constructions, while premium protective specifications demand complex multi-layer architectures with verified post-consumer resin chains.
- Multi Layer:Coextruded structures incorporate 30-90% post-consumer polyethylene across three to seven distinct polymer strata. E-commerce fulfillment networks in Germany and the Netherlands specify these formats for consumer electronics cushioning under 50-70% PCR procurement mandates.
- Laminated:Bonded constructions pair bubble substrates with moisture barriers or static-dissipative films for semiconductor wafer transport. REACH Article 33 obligations force converters to document adhesive chemistries through ECHA's SCIP database, elevating compliance costs for smaller suppliers.
- Single Layer:Monolithic blown film construction serves cost-sensitive void fill applications with limited recycled-content incorporation due to puncture resistance degradation.
- Coated Films:Surface-modified substrates receive anti-static or anti-fog treatments for pharmaceutical cold-chain applications requiring controlled atmosphere integrity.
Today's leader: Multi Layer. Tomorrow's challenger: Laminated.
Application:
End-use functional requirements determine whether air retention, puncture resistance, or surface conformity takes priority in film specification.
- Surface Protection:Low-tack adhesive layers and controlled surface energy prevent residue transfer onto display panels and precision optics. Semiconductor manufacturers in Taiwan and South Korea are expanding closed-loop packaging programs that specify certified recycled-content films for wafer shipping.
- Cushioning:Multi-chamber bubble configurations absorb impact energy for consumer electronics during last-mile distribution. Amazon and Zalando master service agreements are consolidating European demand under standardized 50-70% PCR content specifications.
- Protective Packaging:General-purpose wrapping applications span industrial equipment and automotive components with moderate performance requirements.
- Void Fill:Loose-fill bubble configurations occupy space within shipping containers to prevent load shifting during transport.
Surface Protection commands premium positioning. Cushioning captures volume scale.
End User Industry:
Regulatory exposure and sustainability disclosure requirements vary dramatically across customer verticals, reshaping supplier qualification criteria.
- Electronics:Display and semiconductor manufacturers audit packaging suppliers quarterly for ECHA SCIP database compliance and carbon footprint disclosures. Quarterly supplier audits disqualify non-conforming material sources from approved vendor lists.
- Pharmaceuticals:Cold-chain distribution demands moisture barrier performance and temperature stability across extended transit durations.
- Consumer Goods:Mass-market e-commerce channels prioritize unit economics over technical specifications for non-fragile merchandise.
- Industrial Equipment:Heavy machinery packaging emphasizes puncture resistance and load-bearing capacity over recycled-content percentages.
Electronics sets compliance standards. Pharmaceuticals follows with specialized barrier requirements.
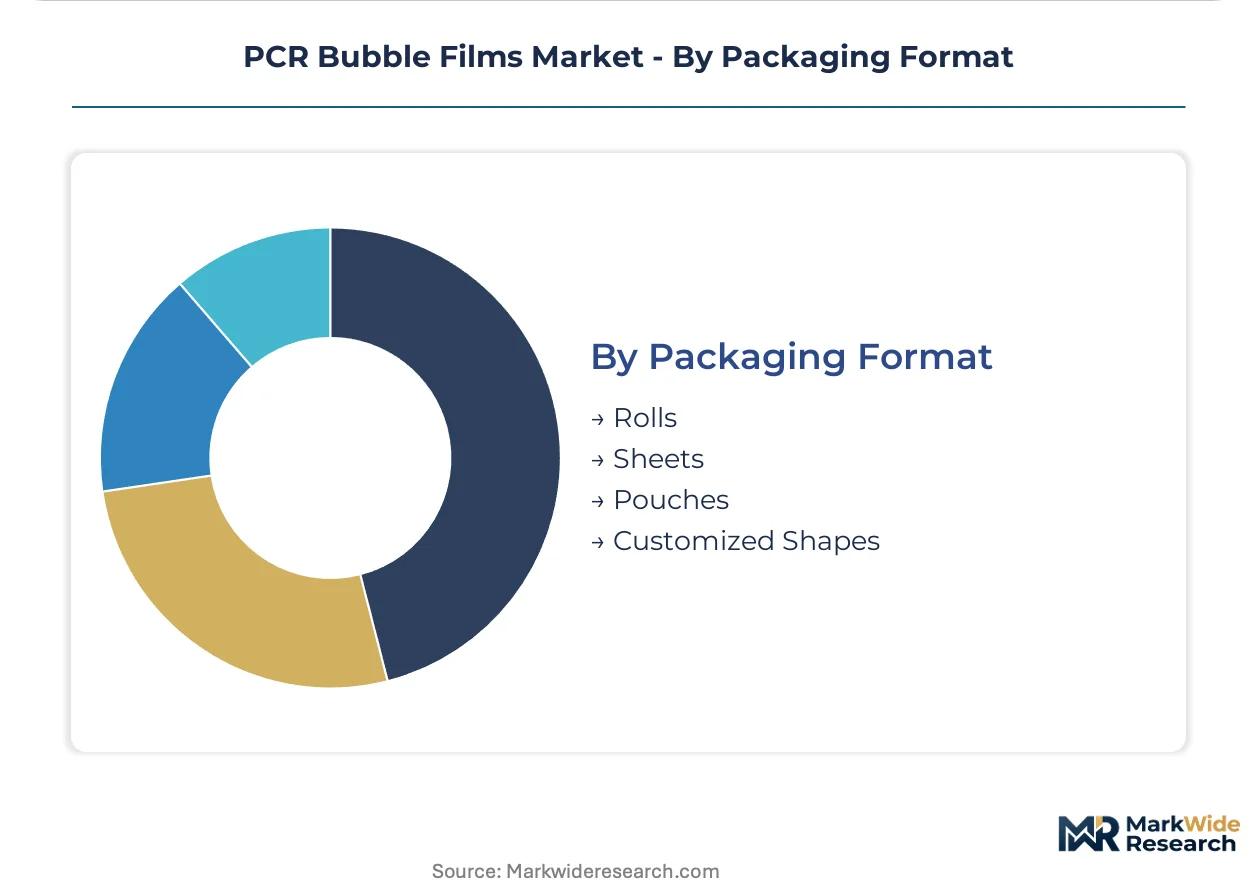
Packaging Format:
Converter capital equipment and downstream automation compatibility dictate format selection across fulfillment network specifications.
- Rolls:Continuous web formats feed high-speed void-fill dispensers and on-demand cushioning systems at automated fulfillment centers.
- Sheets:Pre-cut dimensions serve manual packing stations and irregular product geometries requiring custom wrapping.
- Pouches:Pre-formed bubble bags accelerate packing velocity for small electronics and pharmaceutical kits.
- Customized Shapes:Die-cut configurations conform to specific product footprints for high-value industrial components.
Rolls dominate automation investment cycles. Customized Shapes extract margin from specialized applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands higher PCR content mandates than the United States, while Chinese manufacturing clusters scale faster on volume despite lagging certification requirements. National regulatory frameworks and industrial concentration patterns create divergent competitive environments for film converters.
Germany
Amazon and Zalando fulfillment networks drive concentrated demand for 50-70% PCR cushioning specifications. The national packaging waste regulations under extended producer responsibility frameworks mandate minimum recycled-content percentages. The Rhine-Ruhr logistics corridor hosts coextrusion specialists serving these consolidated procurement accounts with certified mass-balance documentation.
United States
EPA recycled-content guidelines shape procurement standards for e-commerce fulfillment centers expanding protective packaging volumes. State-level extended producer responsibility legislation in California and New York creates patchwork compliance requirements. The Midwestern packaging belt around Chicago and Detroit concentrates technical coextrusion expertise for multi-layer recycled-content films.
China
Domestic e-commerce platforms generate massive void-fill demand with evolving sustainability specifications under dual carbon goals. The national standardization administration develops PCR content guidelines for protective packaging applications. The Yangtze River Delta manufacturing cluster around Shanghai scales bubble film production for both domestic consumption and export markets.
Netherlands
Rotterdam-Antwerp corridor logistics hubs centralize European distribution of certified PCR protective materials. REACH and ECHA SCIP database requirements enforce polymer chain-of-custody documentation across import flows. The Port of Rotterdam chemical recycling investments promise food-grade compatible recycled polyethylene feedstocks for regional converters.
South Korea
Semiconductor and display manufacturers specify closed-loop packaging programs with certified recycled-content surface protection films. The Ministry of Environment strengthens extended producer responsibility frameworks for electronics packaging waste. The Gyeonggi-do industrial complex around Seoul anchors demand for precision protective films with documented carbon footprint disclosures.
PCR Bubble Films Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: integrated packaging conglomerates with global manufacturing footprints, specialized protective film converters with technical coextrusion capabilities, and corrugated packaging specialists extending into hybrid film-paper formats. Dominant competitive moves include backward integration into mechanical recycling operations and strategic partnerships with chemical recycling infrastructure developers.
Among diversified packaging conglomerates, Sealed Air and Smurfit Westrock exemplify scale-driven archetypes with broad geographic manufacturing presence. Pregis occupies a focused specialist position emphasizing technical cushioning solutions. These three anchors represent divergent strategic postures: global footprint breadth versus application-specific technical depth versus paper-based packaging heritage extending into protective film adjacencies.
| Leading Market Players |
|---|
| Sealed Air |
| Pregis |
| Storopack Hans Reichenecker |
| Automated Packaging Systems |
| Intertape Polymer Group |
| Bunzl |
| ProAmpac |
| Smurfit Westrock |
| 3M |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up film converters in the US Midwest and German Ruhr region exercise pricing discipline through captive mechanical recycling operations, while sovereign-backed petrochemical majors in the Rotterdam-Antwerp corridor anchor premium-tier supply through pyrolysis investments. This ownership fragmentation creates divergent cost structures across virgin-indexed spot markets and long-term offtake contracts with certified mass-balance documentation.
Pricing Analysis
Capacity additions in Germany and the Netherlands are reshaping price floors for certified 50-70% PCR cushioning films as coextrusion specialists compete for Amazon and Zalando master service agreements. Three-tier pricing structure across premium, standard, and economy levels separates ECHA SCIP-compliant mass-balance certified supply from uncertified mechanical recycling grades and virgin-only commodity films. Price differentiation centers on documentation burden and carbon footprint disclosure granularity. Cost compression in standard-tier multi-layer films is intensifying because PCR resin bales trade at par with oil-indexed virgin polyethylene during crude volatility spikes. Consumer goods e-commerce channels exhibit highest price sensitivity, while semiconductor surface protection programs prioritize compliance certification over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with municipal collection infrastructure for post-consumer polyethylene bales across Germany, France, and Italy, where EPR frameworks concentrate feedstock access under national sorting monopolies. Raw material dependencies encompass post-consumer LDPE/LLDPE bales, compatibilizer additives for multi-layer coextrusion, and calcium carbonate fillers for puncture resistance modification. Supply chain risk manifests as regulatory restriction through ECHA SCIP database compliance timelines that disqualify non-conforming converters from EU electronics supply chains. Distribution runs through centralized fulfillment network procurement offices in Rhine-Ruhr and Polish logistics corridors, displacing fragmented distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
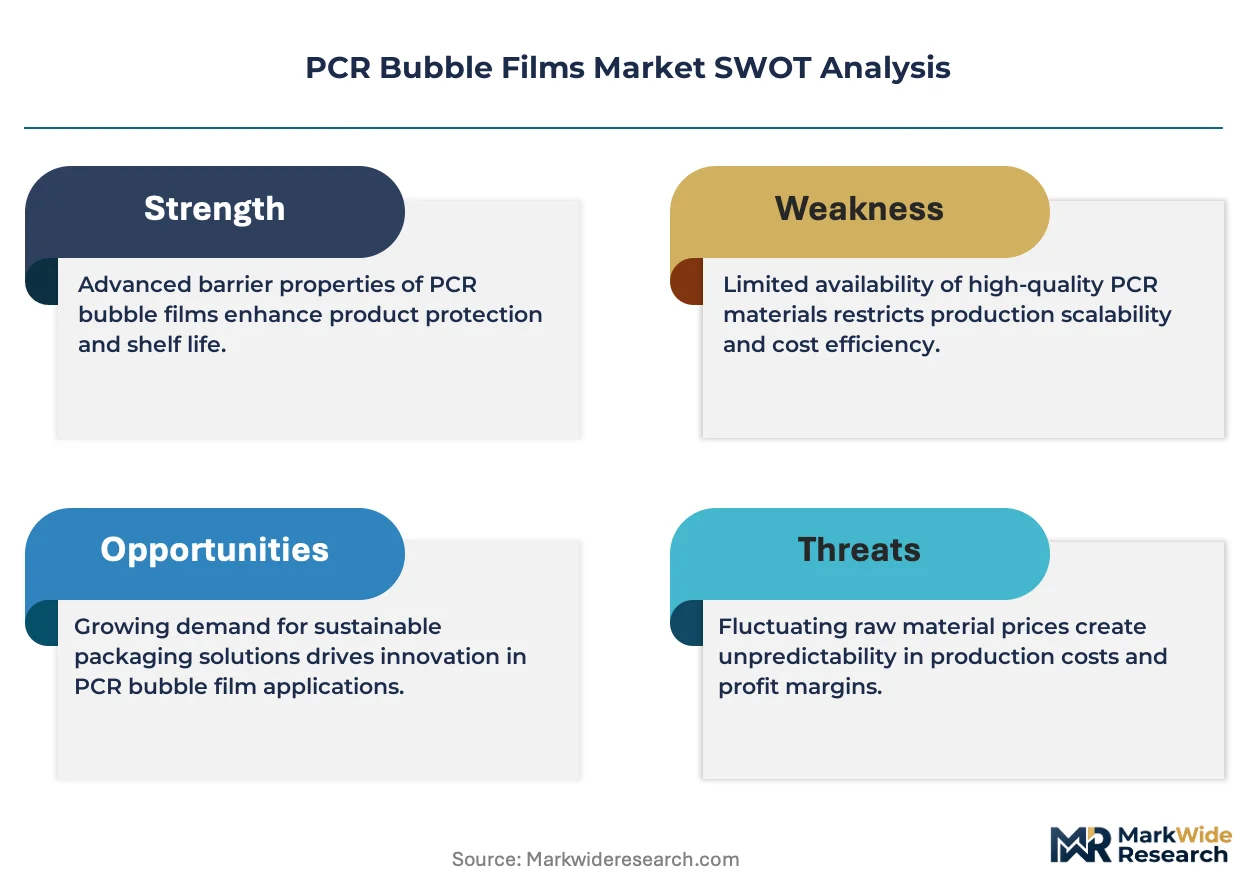
Margin expansion in PCR bubble films rests on chemical recycling cost-down curves displacing mechanical reprocessing yield losses, alongside premium-tier pull-through from semiconductor closed-loop packaging mandates requiring documented carbon intensity disclosures.
For Market Incumbents: Deepen backward integration into mechanical recycling partnerships with German and French EPR operators to secure captive PCR resin supply before chemical recycling scale-up commoditizes feedstock access. Incumbent converters must defend against corrugated packaging specialists extending hybrid film-paper formats by accelerating multi-layer coextrusion capacity additions in Poland and Czechia to serve Central European fulfillment networks. Certification investment in ECHA SCIP database ERP integration represents the critical lever for retaining electronics vertical supplier status. For New Entrants and Emerging Players: Mid-tier pharmaceutical cold-chain distributors represent an underserved buyer archetype requiring coated anti-fog PCR films with moderate barrier specifications below semiconductor-grade compliance burdens. New entrants should penetrate Italian and Spanish industrial equipment packaging segments where puncture resistance requirements exceed recycled-content mandates, enabling uncertified mechanical recycling feedstock utilization. Go-to-market execution should anchor on regional reprocessor partnerships offering toll-coextrusion services to bypass capital-intensive blown film equipment ownership. For Investors and Strategic Acquirers: Valuations sit cheapest among family-owned German mid-cap converters lacking dedicated regulatory affairs staff to navigate REACH Article 33 documentation requirements. Long-term viability across the analysis window favors targets with established electronics supplier relationships and backward-integrated bale sourcing contracts. The signal to watch is French and German EPR minimum recycled-content percentage escalations that would strand non-compliant virgin-only capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mechanical Recycling | Captive PCR resin supply secures margin stability against oil-indexed virgin polyethylene volatility. |
| Chemical Recycling Partnership | Pyrolysis offtake agreements with Rotterdam corridor operators promise food-grade compatible recycled polyethylene. |
| ECHA SCIP Database Certification | ERP system reconfiguration enables EU market access for electronics surface protection applications. |
| Hybrid Film-Paper Format Development | Corrugated packaging heritage extends into recyclable all-fiber protective systems for premium e-commerce channels. |
| Central European Capacity Expansion | Polish and Czech coextrusion additions serve consolidated Amazon and Zalando procurement offices. |
Research Methodology
Bottom-up electronics and pharmaceutical packaging modeling reconciled against top-down mechanical recycling capacity tracking forms the analytical core of this study. Primary interviews with film converter plant managers, e-commerce fulfillment procurement leads, EPR scheme operators, polymer compounding technical directors, and REACH compliance consultants combined with secondary validation from ECHA SCIP database filings, Cefic plastics recycling reports, EU packaging waste directive implementation documents, and SEC 10-K disclosures from listed packaging conglomerates. Top-down and bottom-up triangulation identified supply-demand imbalances in certified PCR resin availability.
Historical trendline analysis of coextrusion capacity utilization and PCR resin bale pricing spreads informed projection modeling across the analysis window. Segmentation dimensions encompassed product type tier, end-use industry vertical, packaging format automation compatibility, and regional regulatory cluster. CAGRs derived from fitted growth curves adjusted for EPR mandate implementation schedules and chemical recycling infrastructure commissioning timelines. Industry-specific forecast inputs included semiconductor capital expenditure cycles and e-commerce fulfillment square footage expansion patterns.
Underlying measurement precision varies by segment; multi-layer and laminated product categories carry tighter precision than single-layer commodity films due to concentrated supplier bases and documented contract volumes. Forecasts reflect assumptions regarding EPR percentage mandate trajectories, pyrolysis yield improvements, and coextrusion technical workforce availability that could materially revise outcomes if regulatory timelines accelerate or chemical recycling scale disappoints. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.