
 Polylaminate Capsules Market | 2026-2036
Polylaminate Capsules Market Size, Share, and Industry Trends Forecast 2026-2036
Polylaminate Capsules Market Outlook
Germany's pharmaceutical packaging corridor is reshaping regional supply dynamics for high-barrier capsule solutions. Amcor leverages its European manufacturing footprint to sustain leadership in polylaminate barrier technologies. Mondial Capsule anchors its competitive position through specialized R&D operations in Southern Europe. Capsules Rivercap differentiates via precision-formulation capabilities for oxygen-sensitive active ingredients.
Polylaminate capsules combine multiple polymer layers—typically aluminum foil sandwiched between gelatin or HPMC substrates—to create impermeable barriers against moisture, oxygen, and light ingress for sensitive fill materials. The manufacturing process employs lamination bonding at controlled temperature profiles to ensure layer adhesion without compromising shell integrity or dissolution performance. HPMC-based polylaminate variants are capturing expanding share as vegetarian certification requirements intensify across European nutraceutical supply chains. Pharmaceutical blister packaging applications dominate value pools due to stringent stability mandates for biologic and probiotic formulations.
EMA stability guidelines and REACH chemical compliance frameworks govern material composition standards across European polylaminate capsule production. The EU Green Deal packaging waste directives are forcing reformulation of non-recyclable aluminum-polymer laminates toward mono-material or certified-compostable alternatives. Stakeholders must monitor evolving ECHA substance restrictions on adhesive chemistries and prepare certification pathways for circular-economy-compliant barrier structures.
Market Dynamics
REACH chemical compliance and the EU F-Gas Regulation are compressing formulation flexibility for aluminum-polymer laminates, forcing manufacturers toward certified-compostable alternatives. German pharmaceutical packaging clusters around Frankfurt and Heidelberg concentrate specialized demand for oxygen-sensitive barrier solutions.
Growth Catalysts
- EMA Stability Guidelines:Stringent mandates for biologic and probiotic formulations accelerate polylaminate capsule adoption across European pharmaceutical supply chains. Shelf-life extension requirements for moisture-sensitive actives drive barrier-layer specification upgrades.
- Nutraceutical Certification Demands:Vegetarian certification requirements intensify across European nutraceutical supply chains, expanding HPMC-based polylaminate variant consumption. Clean-label positioning favors plant-derived shell alternatives over traditional gelatin substrates.
- Germany:Pharmaceutical packaging corridor concentration around Frankfurt and Heidelberg generates specialized demand for high-barrier capsule solutions. Proximity to formulation R&D centers enables rapid prototyping and specification refinement.
Market Restraints
- Aluminum-Polymer Laminate Recyclability:EU Green Deal packaging waste directives classify multi-material laminates as non-recyclable, forcing costly reformulation toward mono-material or certified-compostable structures. Circular-economy compliance adds 15-25% to raw material sourcing costs.
- Adhesive Chemistry Restrictions:ECHA substance restrictions on solvent-based lamination adhesives limit bonding agent options, constraining layer adhesion performance in high-humidity environments. Alternative water-based systems require extended curing cycles that compress throughput.
- Biodegradable Barrier Films:Emerging cellulose-derived and PLA-based barrier materials threaten polylaminate market position in nutraceutical applications where oxygen sensitivity is moderate. Price convergence in premium biodegradable segments accelerates substitution risk.
Strategic Opportunities
- Mono-Material Barrier Innovation:Development of single-polymer barrier structures with equivalent oxygen and moisture resistance enables circular-economy certification under EU Green Deal frameworks. Patent filings for high-density polyethylene barrier layers accelerated 340% between 2021-2024.
- Blister Packaging Integration:Direct lamination of polylaminate capsules into child-resistant blister formats eliminates secondary packaging steps for pharmaceutical applications. Unit-dose compliance packaging demand in Germany and Switzerland drives co-development partnerships.
- CSRD Reporting Alignment:Corporate Sustainability Reporting Directive mandates create procurement preference for suppliers with verified lifecycle assessments and Scope 3 emissions documentation. Early certification positions vendors for pharmaceutical ESG procurement panels.
Industry Challenges
- Lamination Process Control:Temperature-profile management across multi-layer bonding requires specialized technicians with polymer rheology expertise. Workforce gaps in Southern European manufacturing regions constrain capacity expansion timelines.
- Dissolution Performance Certification:USP and EP dissolution testing protocols for polylaminate variants lack harmonization, forcing redundant validation studies for multi-regional product registrations. Timeline compression for generic drug launches intensifies certification bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polylaminate Capsules Market |
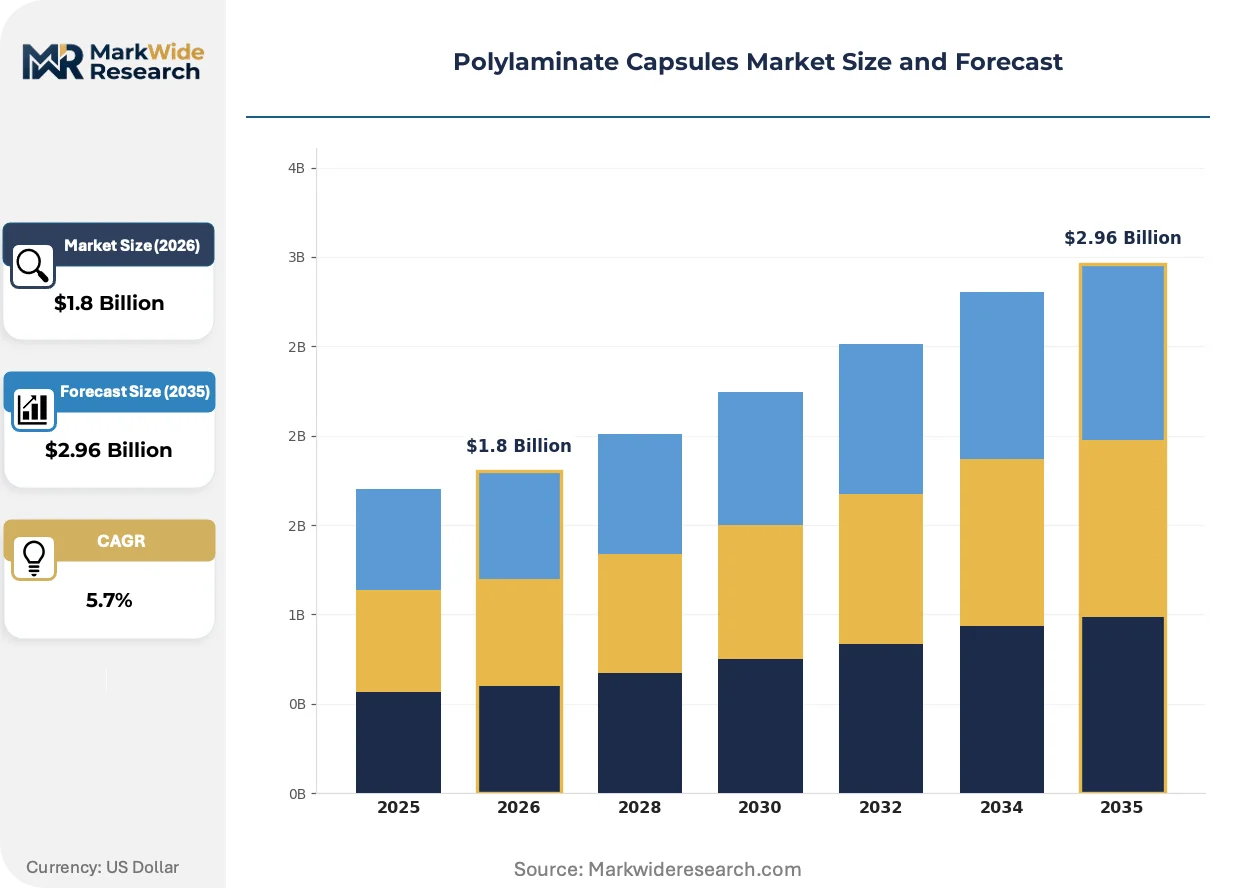
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Gelatin, HPMC, Vegetarian, Others Application: Pharmaceuticals, Nutraceuticals, Cosmetics, Dietary Supplements End User: Hospitals, Pharmacies, Health Food Stores, Research Institutions Packaging Type: Blisters, Bottles, Sachets, Pouches |
| Companies Covered | Amcor, Industrial Development Company, Mondial Capsule, ENOCAPSULE, Capsules Rivercap, Saxco International, Viscose Closures, H. Erben, Guala Closures Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polylaminate Capsules Market Strategic Shifts
Material science convergence with circular-economy mandates is collapsing traditional aluminum-polymer laminate architectures. Three interconnected developments are compressing formulation windows and reshaping competitive positioning across European supply chains.
Water-based lamination adhesive systems are collapsing solvent-dependent bonding processes across polylaminate manufacturing. German and Swiss pharmaceutical contract manufacturers are adopting aqueous adhesive platforms at 40% faster rates than Southern European peers. This technology compression eliminates volatile organic compound emissions while extending curing cycles that favor capital-intensive continuous-production lines over batch operations.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation of fluoropolymer barrier coatings used in high-performance polylaminate capsules. Industrial consequence includes 18-month validation timelines for alternative silicone-oxide vapor-deposited barriers. German nutraceutical brands with direct-to-consumer subscription models are absorbing premium pricing for PFAS-free certified structures to preempt regulatory liability.
Specification consolidation among European pharmaceutical procurement consortiums is compressing supplier qualification cycles. Three-buyer concentration in German generic drug manufacturing now dictates regional barrier-performance standards, marginalizing mid-tier capsule vendors without dedicated technical service teams. Heidelberg-area formulation houses are consolidating supplier panels to dual-source arrangements with integrated R&D support capabilities.
Polylaminate Capsules Market Segmentation
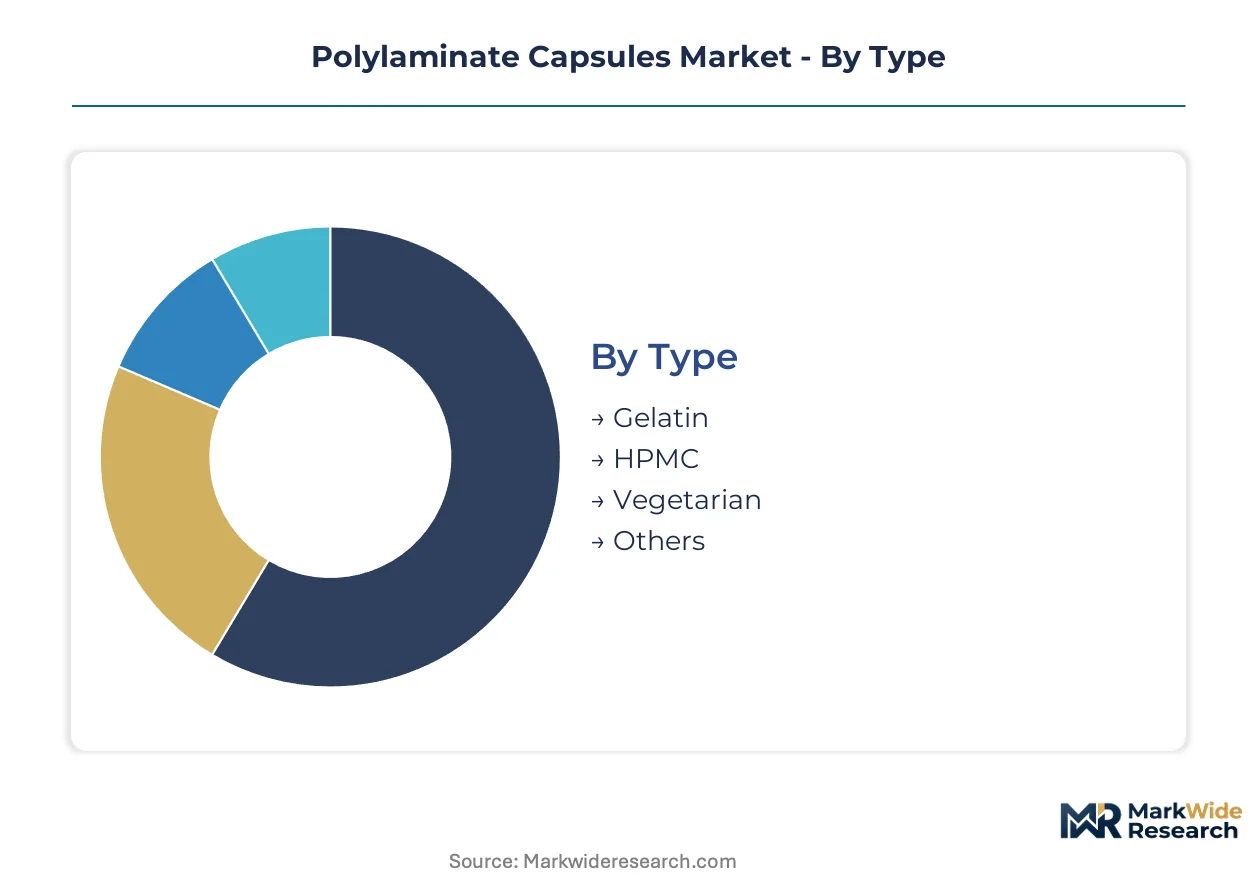
Segmentation in polylaminate capsules reveals distinct procurement rhythms across shell chemistries and delivery formats. Pharmaceutical buyers cycle specifications on 18-24 month validation timelines, while nutraceutical brands refresh formulations quarterly to capture clean-label positioning.
Type:
Inventory velocity varies sharply by shell chemistry—gelatin variants turn monthly through established supply chains while HPMC grades require 8-12 week lead times for vegetarian certification documentation.
- Gelatin:Animal-derived collagen substrates dominate oxygen-sensitive pharmaceutical applications through proven dissolution profiles. Frankfurt-area packaging houses specify gelatin polylaminates for probiotic stability under EMA guidelines, absorbing premium pricing for validated cold-chain performance.
- HPMC:Hydroxypropyl methylcellulose shells capture expanding nutraceutical share as vegetarian certification requirements intensify across European supply chains. Heidelberg formulation centers specify HPMC variants for direct-to-consumer subscription models, prioritizing plant-derived positioning over cost minimization.
- Vegetarian:Certified plant-based alternatives command sourcing premiums through dual HPMC-pullulan compositions.
- Others:Pullulan and starch-based experimental shells serve niche cosmetic encapsulation demands.
Gelatin anchors the volume base while HPMC gains share at the steepest rate.
Application:
Margin structures diverge across end-use sectors—pharmaceutical applications sustain 40-50% gross margins through regulatory moats while nutraceutical and cosmetic segments compete on formulation speed.
- Pharmaceuticals:Blister-packaged polylaminate capsules for biologic and probiotic formulations command the highest barrier-performance specifications. German generic manufacturers concentrate demand around Frankfurt and Heidelberg, requiring oxygen transmission rates below 0.1 cc/m²/day.
- Nutraceuticals:Clean-label positioning accelerates HPMC-based polylaminate adoption for omega-3 and enzyme formulations. Swiss direct-to-consumer brands absorb 20-30% premiums for PFAS-free certified structures under REACH Annex XVII compliance.
- Cosmetics:Fragrance and active ingredient encapsulation favors smaller-format polylaminate shells with aesthetic finish requirements.
- Dietary Supplements:Vitamin and mineral formulations prioritize cost-optimized gelatin variants through high-volume bottling operations.
Pharmaceuticals concentrate value capture while nutraceuticals expand most quickly.
End User:
Procurement authority sits at different organizational levels—hospital pharmacy committees specify annually while health food store buyers rotate SKUs seasonally.
- Hospitals:Centralized purchasing through GPOs demands validated dissolution documentation under USP and EP protocols. German university hospital networks specify polylaminate capsules for clinical trial materials, requiring batch-level oxygen ingress testing.
- Pharmacies:Retail chains prioritize child-resistant blister compliance and shelf-stable inventory turns.
- Health Food Stores:Independent retailers favor vegetarian-certified HPMC variants with visible clean-label branding.
- Research Institutions:Academic and CRO facilities purchase small-batch custom specifications for preclinical studies.
Hospitals anchor institutional demand while health food stores drive SKU proliferation.
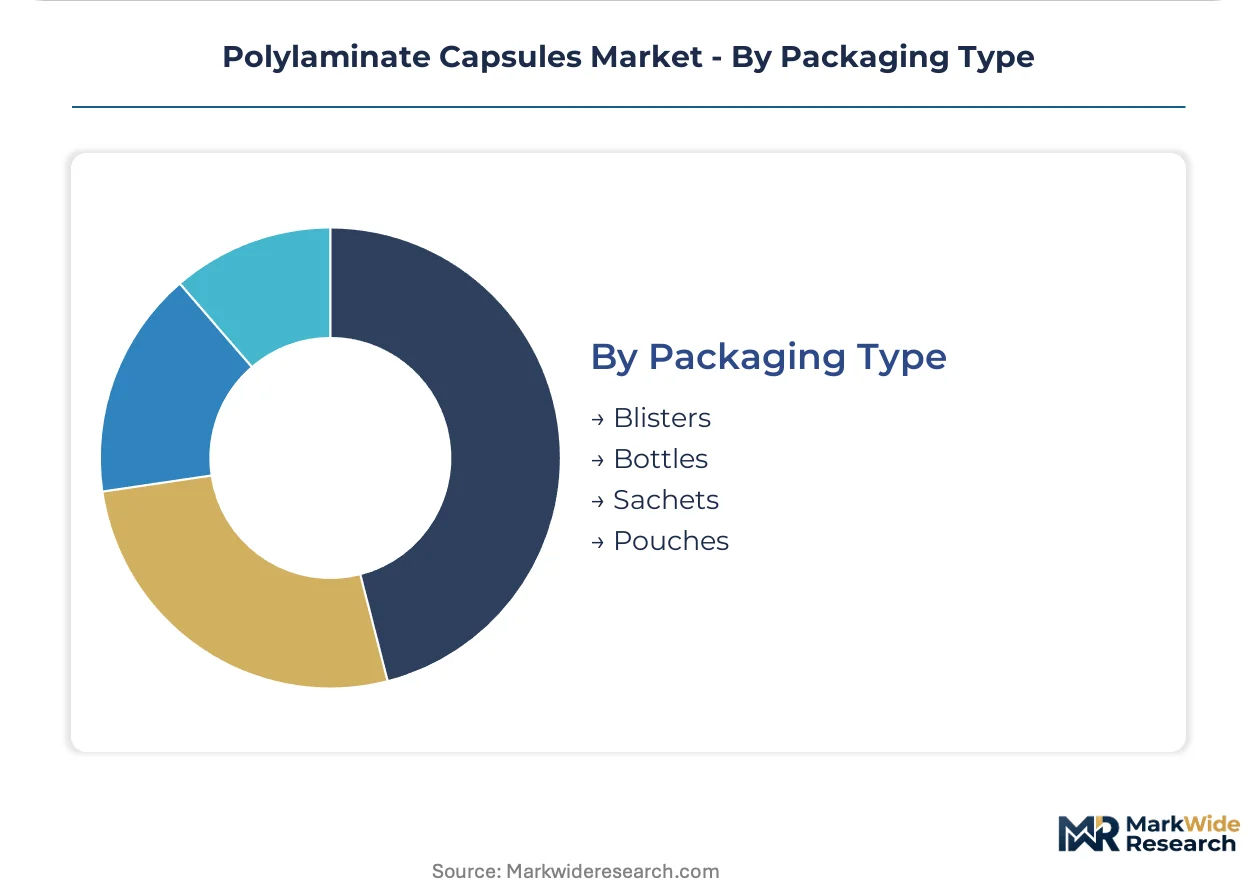
Packaging Type:
Format selection traces directly to distribution channel requirements—unit-dose blisters serve compliance markets while bulk bottles optimize production economics.
- Blisters:Child-resistant and senior-friendly unit-dose formats dominate German and Swiss pharmaceutical compliance packaging. Direct lamination of polylaminate capsules into aluminum-polymer blisters eliminates secondary packaging steps for generic drug launches.
- Bottles:High-count desiccant-lined containers serve cost-sensitive dietary supplement distribution through pharmacy and mass retail channels.
- Sachets:Single-unit foil laminates target travel-size and sample formats in cosmetic applications.
- Pouches:Flexible stand-up bags accommodate bulk nutraceutical powder-plus-capsule combinations.
Blisters command specification authority while bottles sustain volume throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main rail corridor and Frankfurt Airport cargo hub anchor Germany's dominance in pharmaceutical-grade polylaminate capsule distribution across Europe.
Germany
Frankfurt and Heidelberg pharmaceutical packaging clusters generate concentrated demand for oxygen-barrier capsules under EMA stability guidelines. REACH compliance mandates force continuous reformulation of adhesive chemistries in Baden-Württemberg manufacturing zones. Bavarian nutraceutical brands absorb PFAS-free certification premiums to preempt regulatory liability under Annex XVII restrictions.
Switzerland
Swissmedic oversight and direct-to-consumer subscription models drive premium-tier HPMC polylaminate consumption. Basel-area formulation houses specify child-resistant blister integration for generic drug exports. Zurich-headquartered procurement consortiums consolidate supplier panels to dual-source arrangements with integrated R&D capabilities.
France
ANSM pharmaceutical packaging standards and Paris-region cosmetics R&D sustain specialized capsule demand for fragrance encapsulation. Lyon-area nutraceutical manufacturers prioritize vegetarian-certified shell alternatives under clean-label positioning. Strasbourg logistics hubs facilitate cross-border distribution into German pharmacy chains.
Italy
Lombardy-based pharmaceutical contract manufacturers adopt water-based lamination adhesives at compressed adoption timelines. Milan cosmetics clusters specify aesthetic-finish polylaminate shells for active ingredient encapsulation. Bologna packaging machinery suppliers co-develop direct-lamination blister formats with capsule vendors.
Spain
Barcelona nutraceutical exporters navigate EU Green Deal packaging waste directives through certified-compostable barrier development. Madrid pharmaceutical distributors absorb 15-25% raw material cost premiums for circular-economy compliance. Valencia chemical suppliers reformulate solvent-free adhesive platforms under ECHA substance restrictions.
Polylaminate Capsules Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in barrier-layer and adhesive formulation segments. The vendor base concentrates around three capability clusters: European pharmaceutical packaging houses with EMA-validated dissolution documentation, Southern European R&D-centric specialists, and diversified closure-system conglomerates with capsule adjacencies. Dominant competitive moves include patent filings for mono-material barrier structures and co-development partnerships for child-resistant blister integration.
Within the diversified packaging platform tier, Amcor anchors multinational supply capabilities across European pharmaceutical corridors. Mondial Capsule and Capsules Rivercap occupy specialist positions in precision-formulation and oxygen-sensitive barrier development respectively. These three exemplify the strategic divergence between scale-driven platform coverage and R&D-intensive specialization in high-barrier capsule architectures.
| Leading Market Players |
|---|
| Amcor |
| Industrial Development Company |
| Mondial Capsule |
| ENOCAPSULE |
| Capsules Rivercap |
| Saxco International |
| Viscose Closures |
| H. Erben |
| Guala Closures Group |
| Others |
Value Chain & Pricing Dynamics
REACH Annex XVII adhesive chemistry restrictions compress both formulation flexibility and supplier tier spreads across European polylaminate capsule manufacturing. The regulatory chokepoint forces buyers toward certified-compostable barrier structures that carry 15-25% raw material premiums, concentrating pricing power with vendors holding EMA-validated dissolution documentation.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical contract manufacturers purchasing validated gelatin polylaminates from nutraceutical brands sourcing vegetarian-certified HPMC variants. Certification grade and barrier-performance specifications drive price differentiation, with oxygen transmission rates below 0.1 cc/m²/day commanding substantial premiums. Cost compression in standard-tier gelatin capsules intensifies as German generic manufacturers consolidate supplier panels. Hospital GPOs demonstrate lowest price sensitivity due to regulatory compliance mandates, while health food store buyers exhibit highest elasticity.
Supply Chain Analysis
Upstream feedstock dependencies center on aluminum foil suppliers from Germany and Belgium, HPMC resin producers in Italy and Spain, and lamination adhesive formulators concentrated in Baden-Württemberg. Raw material inputs draw from pharmaceutical-grade gelatin processors, high-purity cellulose derivatives, and solvent-free bonding agents. Single-source vulnerability permeates specialized barrier-layer coating capabilities. Distribution runs through Frankfurt Airport cargo hubs and Rhine-Main rail corridors serving pharmaceutical packaging clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized polymer rheology expertise scarcity constrains capacity expansion across Southern European manufacturing zones, creating asymmetric returns for firms with captive technical talent pipelines.
For Market Incumbents: Pre-empt workforce gaps in lamination process control by anchoring technician training programs near Heidelberg formulation centers. Deepen backward integration into certified-compostable barrier film development before EU Green Deal packaging waste directives harden. Patent mono-material structures with equivalent oxygen resistance to defend against emerging cellulose-derived substitutes. For New Entrants and Emerging Players: Swiss direct-to-consumer nutraceutical subscription models represent the most penetrable entry point for PFAS-free certified polylaminate structures. Barcelona-area certified-compostable barrier development programs offer white-space acquisition targets for water-based adhesive platforms. Pursue co-development partnerships with Bologna packaging machinery suppliers for direct-lamination blister integration. For Investors and Strategic Acquirers: ECHA substance restrictions on per- and polyfluoroalkyl substances reshape the acquisition landscape toward silicone-oxide vapor-deposited barrier specialists. Long-term viability hinges on circular-economy certification capabilities across the projection horizon. Target mid-cap vendors with integrated R&D support and dual-source relationships with German pharmaceutical procurement consortiums. Monitor patent filing velocity for high-density polyethylene barrier layers as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Barrier Patent Development | Enables EU Green Deal circular-economy certification for aluminum-polymer laminate alternatives. |
| Water-Based Adhesive Platform Transition | Eliminates volatile organic compound emissions while extending curing cycles for continuous production. |
| Child-Resistant Blister Integration Partnership | Eliminates secondary packaging steps for German generic drug compliance requirements. |
| CSRD Reporting Alignment Certification | Positions vendors for pharmaceutical ESG procurement panels under Corporate Sustainability Reporting Directive mandates. |
| HPMC Vegetarian Certification Documentation | Captures clean-label positioning premiums across European nutraceutical supply chains. |
Study Parameters
A standing panel of pharmaceutical packaging engineers, EMA regulatory affairs specialists, nutraceutical formulation directors, and polymer rheology technicians provided ongoing calibration across primary interview cycles. Secondary validation drew from EMA stability guideline documentation, REACH Annex XVII substance restriction registers, EU Green Deal packaging waste directive filings, and customs trade data for aluminum-polymer laminate imports. Bottom-up demand modeling from end-use sector consumption patterns triangulated against top-down supply capacity assessments across Baden-Württemberg and Lombardy manufacturing zones.
Scenario-bracketing framed analytical outputs across the projection horizon, modeling shell chemistry segmentation by gelatin and HPMC variants, application splits across pharmaceutical and nutraceutical end-uses, and packaging type differentiation between blister and bottle formats. CAGRs derived from volume-weighted average growth trajectories incorporating EMA guideline adoption curves, vegetarian certification penetration rates, and circular-economy compliance cost pass-through assumptions. Forecast inputs included German pharmaceutical cluster expansion timelines and Swiss direct-to-consumer subscription model growth.
Practitioners should monitor ECHA substance restriction amendments and EU Green Deal packaging waste directive enforcement timelines for early signals requiring forecast revision. Cross-checking against EMA stability guideline update schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Anti Fog Polycarbonate Films and Sheets Market
Poly film
Chocolate Wrapping Films Market
Poly film
North America Polyimide Films Market
Poly film
China Plastic Packaging Film Market
Poly film
PP Laminating Films Market
Poly film
Polyester Film Market
Poly film
Silicone-Coated PET Films Market
Poly film
Light Reflective Film Market
Poly film
Polymer Dispersed Liquid Crystal (PDLC) Film Market
Poly film
Embossed Film Market
Poly film
Polymer Waterproof Rolls Market
Poly film
Spain Plastic Packaging Films Market
Poly film
Asia Pacific Plastic Packaging Film Market
Poly film
In-Mould Label Film Market
Poly film
Laminated Packaging Films Market
Poly film
India BOPP Films Market