
 Thermal Barrier Coatings Market | 2026-2036
Thermal Barrier Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Barrier Coatings Market Intelligence
The gap between premium electron beam physical vapor deposition coatings and commodity plasma-sprayed alternatives is shifting from a performance distinction to a procurement priority for original equipment manufacturers. Praxair Surface Technologies leverages its atmospheric plasma spray infrastructure to sustain volume leadership in industrial turbine aftermarket services. Oerlikon Balzers Coating AG anchors its position through advanced physical vapor deposition systems that command specification lock-in from European aerospace primes.
Thermal barrier coatings are ceramic overlay systems, typically yttrium stabilized zirconia deposited to thicknesses of 250–500 micrometers, engineered to insulate superalloy substrates from gas path temperatures exceeding 1,200°C in turbine engines and industrial combustors. The yttrium stabilized zirconia product category dominates current volume owing to its proven phase stability and cost structure, while aluminates segments capture margin pools in next-generation propulsion architectures requiring higher surface temperatures. Aerospace application demand leads absolute spend, though power generation end users represent the fastest-growing procurement segment as combined cycle plant operators pursue efficiency gains through higher firing temperatures.
EPA stationary source standards and FAA engine certification requirements jointly dictate coating durability benchmarks and replacement intervals for US-sited equipment, while REACH compliance in Europe constrains binder chemistries and precursor sourcing for cross-border suppliers. The EU Green Deal's industrial decarbonization targets are embedding thermal barrier coating performance into carbon intensity calculations for gas turbine fleet operators. Stakeholders must monitor how evolving FAA Part 33 durability rules and emerging EPA greenhouse gas performance standards for power generation reshape coating specification timelines and supplier qualification pathways.
Market Dynamics
Electron beam physical vapor deposition systems are consolidating specification control among aerospace engine manufacturers, compressing qualification timelines for plasma-sprayed alternatives and redrawing procurement hierarchies across turbine supply chains.
Growth Catalysts
- FAA Part 33 durability mandates:Extended engine certification cycles are forcing original equipment manufacturers to specify higher-grade ceramic topcoats with proven thermal cycling resistance.
- Combined cycle power plants:Operators in the United States are pushing firing temperatures above 1,400°C to capture efficiency gains, accelerating ceramic overlay replacement frequencies.
- Yttrium stabilized zirconia refinement:Advanced powder morphology controls are extending coating service intervals by 15-20% in industrial gas turbines.
Market Restraints
- Plasma-sprayed commodity trap:Atmospheric plasma spray capacity concentrates in legacy industrial clusters, locking suppliers into price-competitive aftermarket segments with thin margin pools.
- Rare earth oxide volatility:Yttrium oxide supply chains exhibit concentration risk tied to Chinese export licensing regimes, injecting cost unpredictability into ceramic precursor procurement.
- Deposition rate ceilings:Electron beam physical vapor deposition throughput remains fundamentally slower than plasma spray, constraining volume scalability for large industrial components.
Strategic Opportunities
- India thermal power expansion:Ultra-supercritical coal plant installations under the National Thermal Power Corporation pipeline create first-mover openings for high-grade coating qualification.
- Aluminate ceramic systems:Gadolinium zirconate and rare earth aluminate chemistries enable 100-150°C temperature step-ups for next-generation propulsion architectures.
- Maintenance repair overhaul channel consolidation:Independent service facilities in the United States are aggregating volume sufficient to justify captive electron beam physical vapor deposition cell investments.
Industry Challenges
- Coating inspector certification gaps:Non-destructive evaluation technicians qualified to detect interfacial delamination in electron beam physical vapor deposition systems remain scarce relative to demand.
- Dual-chemistry supply chain complexity:Manufacturers serving both yttrium stabilized zirconia and aluminate product lines face working capital strain from divergent precursor inventories and shelf-life constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Barrier Coatings Market |
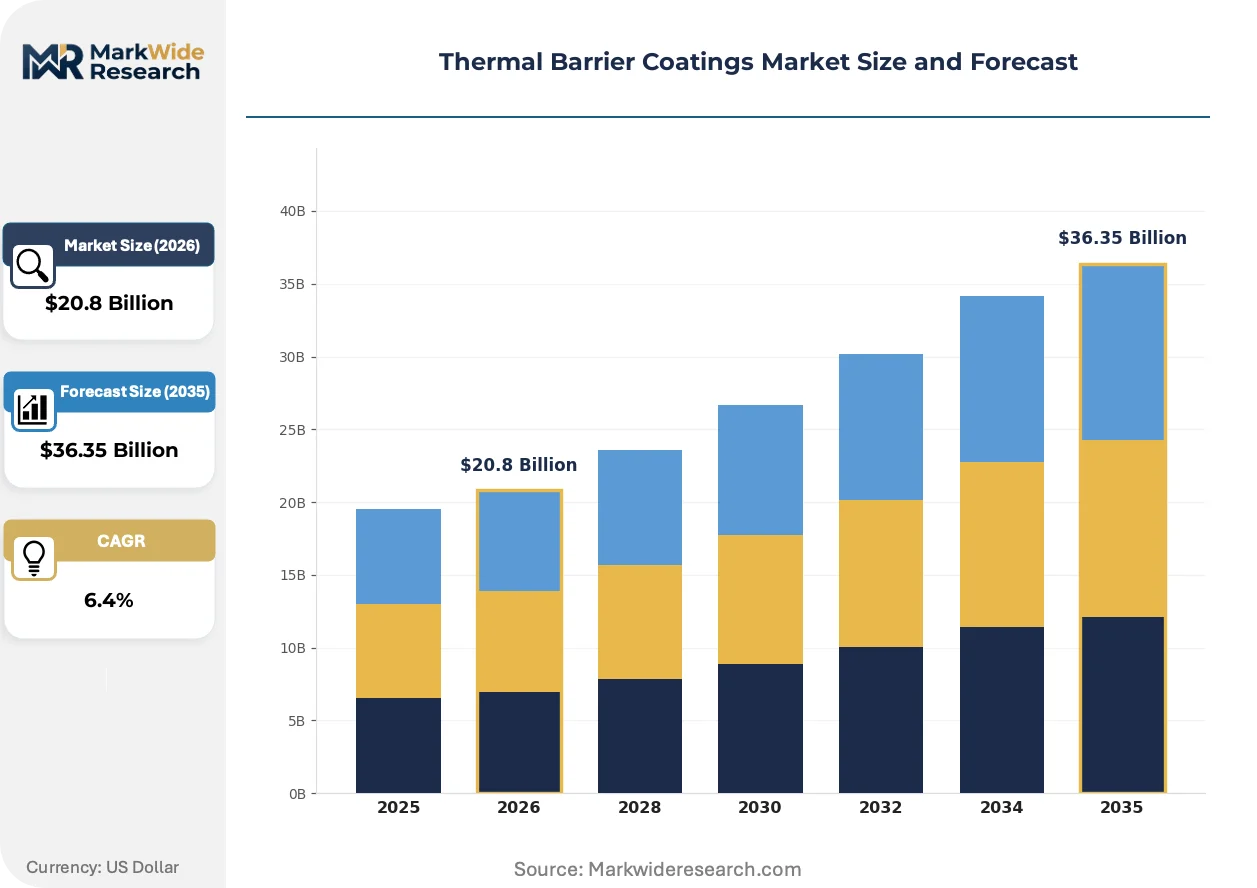
| Market Size in 2026 | $20.8 Billion |
| Market Size in 2035 | $36.35 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zirconium Dioxide, Yttrium Stabilized Zirconia, Aluminates, Others Application: Aerospace, Automotive, Power Generation, Industrial Technology: Plasma Spraying, Electron Beam Physical Vapor Deposition, Sol-Gel Coating, Coating by Chemical Vapor Deposition End User: Aerospace Manufacturers, Automotive Suppliers, Energy Providers, Marine Equipment Manufacturers |
| Companies Covered | AkzoNobel N.V., Bodycote plc, Praxair Surface Technologies, Oerlikon Balzers Coating AG, Sulzer Metco AG, H.C. Starck, Inc., Saint-Gobain S.A., PPG Industries, Inc., TWI Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Barrier Coatings Market Strategic Shifts & Innovations
Process automation and in-situ monitoring systems are compressing the feedback loop between deposition parameters and ceramic microstructure, collapsing development cycles that previously spanned multiple engine test campaigns.
Multilayered thermal barrier architectures with functionally graded interfaces are rewriting durability expectations for turbine airfoils subjected to thermal shock. GE Aviation and Rolls-Royce are specifying these systems for next-generation adaptive cycle engines. The technology is compressing the performance gap between developmental ceramics and production-ready coatings.
EPA greenhouse gas performance standards for stationary gas turbines are embedding coating thermal efficiency into carbon intensity compliance calculations. Power plant operators must now document heat rate improvements tied to ceramic topcoat condition. The United States market is responding with predictive replacement scheduling tied to efficiency degradation curves rather than calendar-based maintenance.
Long-term service agreements are displacing transactional coating replacement contracts in the aerospace aftermarket. Engine lessors and fleet operators in the United States are bundling thermal barrier coating refurbishment into power-by-the-hour arrangements. This concentrates procurement authority with original equipment manufacturer networks and marginalizes independent repair facilities lacking electron beam physical vapor deposition capability.
Thermal Barrier Coatings Market Segmentation
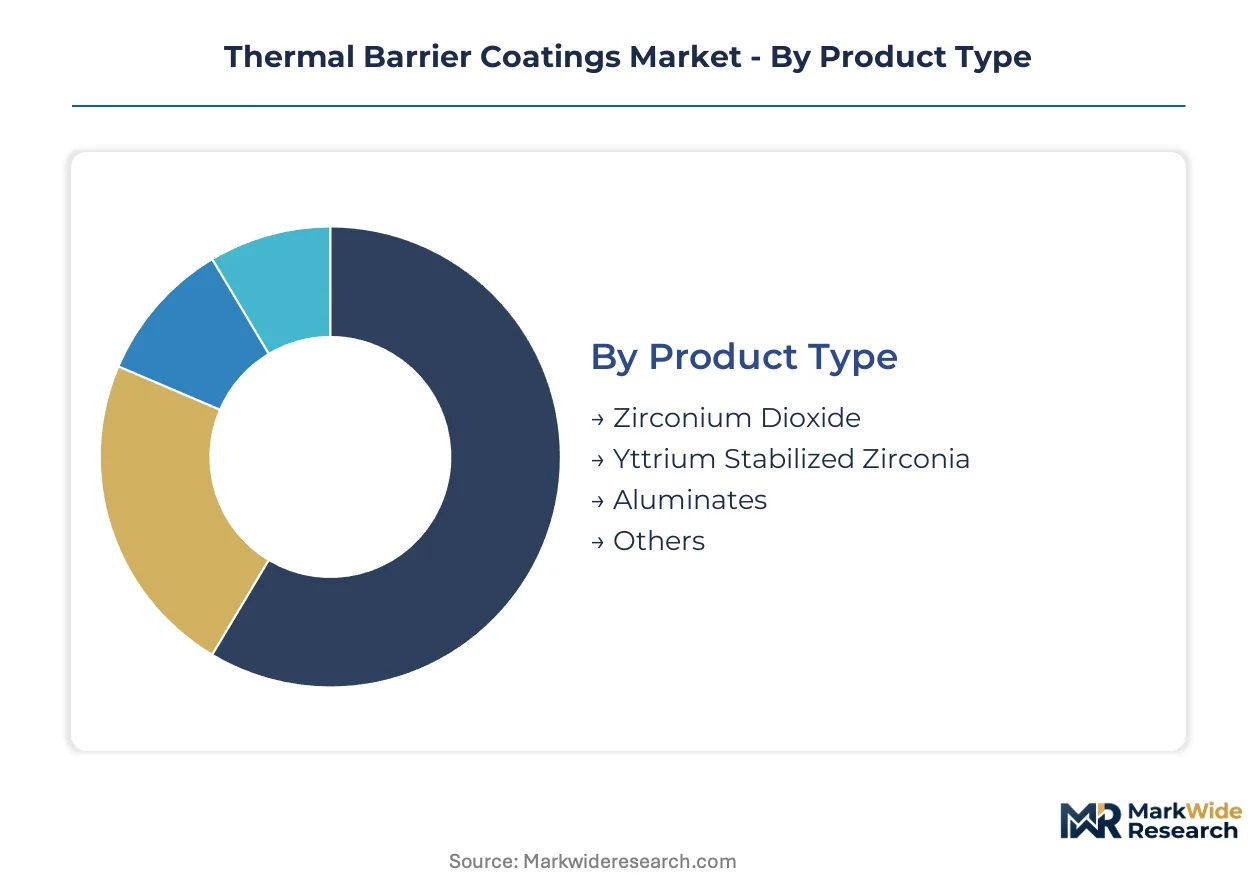
Thermal barrier coating procurement splits sharply between performance tiers and cost tiers, with upgrade cycles diverging across aerospace, power generation, and industrial end uses. Each segment category carries distinct specification pressures that reshape supplier positioning and margin capture.
Product Type:
Replacement cycles for ceramic topcoats vary dramatically by chemistry, with yttrium stabilized zirconia commanding standard overhaul intervals while aluminates extend service life for next-generation turbine architectures.
- Yttrium Stabilized Zirconia:This ceramic composition, typically deposited at 250–500 micrometer thicknesses, delivers proven phase stability against thermal cycling above 1,200°C. Demand clusters in United States maintenance repair overhaul facilities serving legacy aviation fleets and combined cycle power plants, where EPA emissions standards accelerate replacement frequencies for degraded topcoats.
- Aluminates:Gadolinium zirconate and rare earth aluminate chemistries enable operational temperatures 100–150°C higher than conventional systems. European aerospace primes specify these coatings for adaptive cycle engine programs, with REACH compliance constraints shaping precursor sourcing strategies for cross-border suppliers.
- Zirconium Dioxide:Pure zirconia variants serve cost-sensitive industrial turbine segments where thermal shock resistance requirements remain moderate.
- Others:Emerging ceramic composites including perovskite-structured oxides target specialized high-heat flux environments in experimental propulsion systems.
Volume placements concentrate in yttrium stabilized zirconia; the faster expansion belongs to aluminates.
Application:
Cost tier stratification separates aerospace specification-grade coatings from commodity industrial alternatives, with margin pools inversely distributed to volume.
- Aerospace:Turbine airfoils and combustor liners in commercial aviation engines require electron beam physical vapor deposition systems with FAA Part 33 durability certification. United States engine manufacturers specify these coatings for extended on-wing intervals, bundling refurbishment into power-by-the-hour service agreements.
- Power Generation:Combined cycle plant operators in the United States push firing temperatures above 1,400°C to capture efficiency gains, accelerating ceramic overlay replacement cycles tied to heat rate degradation curves rather than calendar maintenance.
- Automotive:Turbocharger turbine wheels and exhaust system components utilize plasma-sprayed coatings for thermal management in high-performance powertrains.
- Industrial:Atmospheric plasma spray capacity serves legacy gas turbine aftermarket segments with price-competitive procurement and compressed margin structures.
Revenue concentration sits with aerospace applications; power generation claims the steepest expansion trajectory.
Technology:
Customer type fragmentation—original equipment manufacturers versus independent service facilities—drives technology selection, with specification control consolidating among engine primes.
- Electron Beam Physical Vapor Deposition:This process deposits columnar ceramic microstructures with strain-tolerant porosity for turbine airfoils. Aerospace engine manufacturers in the United States and Europe mandate this technology for new-production hardware, compressing qualification pathways for alternative deposition methods.
- Plasma Spraying:Atmospheric and low-pressure plasma spray systems dominate industrial turbine aftermarket volume, with Praxair Surface Technologies leveraging installed base density for service leadership.
- Chemical Vapor Deposition:CVD coating systems produce dense, conformal ceramic layers for complex internal cooling passages in advanced turbine blades.
- Sol-Gel Coating:Solution-based deposition targets thin-film thermal protection for specialized components where thickness constraints preclude conventional ceramic overlays.
Procurement authority concentrates in electron beam physical vapor deposition for new hardware; plasma spraying retains volume leadership in aftermarket refurbishment.
End User:
Supply concentration among coating service providers mirrors the geographic clustering of end user manufacturing and overhaul infrastructure.
- Aerospace Manufacturers:GE Aviation and Rolls-Royce specify multilayered thermal barrier architectures with functionally graded interfaces for next-generation adaptive cycle engines, embedding coating performance into engine certification compliance.
- Energy Providers:United States combined cycle operators now document heat rate improvements tied to ceramic topcoat condition under emerging EPA greenhouse gas performance standards, shifting replacement scheduling to predictive models.
- Automotive Suppliers:Turbocharger manufacturers integrate thermal barrier coatings into high-performance powertrain thermal management strategies.
- Marine Equipment Manufacturers:Large-bore marine gas turbines utilize ceramic overlays for combustion chamber durability in commercial shipping propulsion systems.
Contract value concentrates with aerospace manufacturers; energy providers are gaining procurement sophistication fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Cincinnati anchors thermal barrier coating procurement authority through dense aerospace engine manufacturing and maintenance repair overhaul infrastructure clustered around GE Aviation operations.
United States
FAA Part 33 durability mandates and EPA greenhouse gas performance standards for stationary gas turbines drive specification-grade coating demand. Cincinnati, Ohio and Phoenix, Arizona concentrate electron beam physical vapor deposition capacity serving aerospace engine manufacturers. Power generation operators in Texas and California push firing temperatures above 1,400°C, accelerating ceramic overlay replacement cycles tied to heat rate compliance documentation.
Germany
REACH compliance constraints shape precursor sourcing strategies for cross-border coating suppliers serving European aerospace primes. Munich and Hamburg anchor industrial clusters where atmospheric plasma spray capacity serves combined cycle power plant aftermarket demand. The EU Green Deal's industrial decarbonization targets embed coating thermal efficiency into carbon intensity calculations for gas turbine fleet operators.
China
National Thermal Power Corporation ultra-supercritical coal plant installations create qualification openings for high-grade coating suppliers. Shanghai and Xi'an concentrate domestic electron beam physical vapor deposition research capacity. MIIT standards for gas turbine efficiency push domestic manufacturers toward advanced ceramic topcoat specifications previously imported from Western suppliers.
United Kingdom
Rolls-Royce specification lock-in for adaptive cycle engine programs drives demand for multilayered thermal barrier architectures with functionally graded interfaces. Derby and Bristol concentrate aerospace coating research tied to next-generation propulsion development. The country's national aviation regulator coordinates with EASA on durability certification pathways for novel ceramic chemistries.
India
NTPC ultra-supercritical pipeline expansion creates first-mover opportunities for coating qualification in high-temperature coal combustion environments. Gujarat and Maharashtra concentrate industrial gas turbine maintenance infrastructure serving petrochemical and power generation end users. BIS standards for thermal efficiency in stationary gas turbines are converging with international specifications.
Thermal Barrier Coatings Market Key Industry Players
Premium-margin players sit above commodity-margin players across technology certification tiers, with electron beam physical vapor deposition specialists commanding specification lock-in while atmospheric plasma spray operators compete on volume throughput. The vendor base stratifies into three archetypes: aerospace-grade deposition specialists, industrial aftermarket service consolidators, and integrated materials-precursor suppliers. Consolidation pressure concentrates among independent maintenance repair overhaul facilities seeking captive electron beam physical vapor deposition capability. Technology licensing agreements and strategic partnerships dominate competitive moves as qualification timelines compress.
Among European coating specialists, Oerlikon Balzers Coating AG and Sulzer Metco AG occupy positions within the premium-tier deposition technology segment. Bodycote plc exemplifies the industrial aftermarket service archetype through its geographic footprint density. AkzoNobel N.V. and PPG Industries, Inc. represent integrated materials suppliers with precursor and binder chemistry portfolios spanning multiple deposition technologies.
| Leading Market Players |
|---|
| AkzoNobel N.V. |
| Bodycote plc |
| Praxair Surface Technologies |
| Oerlikon Balzers Coating AG |
| Sulzer Metco AG |
| H.C. Starck, Inc. |
| Saint-Gobain S.A. |
| PPG Industries, Inc. |
| TWI Ltd. |
| Others |
Cost & Logistics Intelligence
FAA Part 33 durability mandates forcing specification upgrades among aerospace engine manufacturers are compressing procurement timelines and compelling suppliers to absorb qualification costs that feed into premium-tier pricing structures. This demand-side pressure concentrates margin capture among electron beam physical vapor deposition specialists while plasma-sprayed alternatives face commoditization.
Pricing Analysis
Value-based pricing anchored to engine on-wing performance and heat rate efficiency gains dominates procurement contracts for specification-grade coatings. Three-tier pricing structure across premium, standard, and economy levels separates electron beam physical vapor deposition systems with FAA certification from atmospheric plasma spray refurbishment and commodity industrial alternatives. Cost compression in plasma-sprayed aftermarket segments is intensifying because legacy capacity concentrates in price-competitive industrial clusters. Combined cycle power plant operators exhibit highest price sensitivity due to efficiency-driven procurement, while aerospace original equipment manufacturers prioritize performance over unit cost.
Supply Chain Analysis
Freight costs for yttrium oxide precursors and rare earth aluminate chemistries amplify total landed cost volatility given concentrated mining and processing infrastructure. Supply draws from China for yttrium oxide, Germany and the United States for advanced deposition equipment, and Japan for high-purity ceramic powders. Single-source vulnerability in Chinese rare earth export licensing regimes creates procurement risk for ceramic precursor sourcing. Distribution runs through original equipment manufacturer captive facilities, independent maintenance repair overhaul networks, and integrated coating service providers serving industrial turbine aftermarket demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electron beam physical vapor deposition cell scarcity props pricing power for qualified suppliers, creating a supply-constrained market structure where capacity additions lag specification demand from next-generation turbine programs.
For Market Incumbents: Cement specification lock-in through captive electron beam physical vapor deposition investments in Cincinnati and Phoenix aerospace clusters. Deepen upstream control over yttrium oxide precursor sourcing to buffer Chinese export licensing volatility. Defend against plasma-sprayed commodity encroachment by embedding coating performance into long-term service agreements with power-by-the-hour structures. For New Entrants and Emerging Players: Aluminate ceramic system qualification for adaptive cycle engine programs offers a technology-first wedge into premium-margin procurement previously dominated by established European suppliers. Target India's NTPC ultra-supercritical pipeline where first-mover coating qualification windows remain open. Pursue joint development agreements with domestic turbine manufacturers seeking to displace imported ceramic topcoat specifications. For Investors and Strategic Acquirers: Re-rating potential sits with independent maintenance repair overhaul facilities building captive electron beam physical vapor deposition capability given consolidation pressure and specification tier migration. Long-term viability centers on suppliers with dual-chemistry flexibility spanning yttrium stabilized zirconia and aluminate product lines. Monitor FAA Part 33 durability rule revisions as inflection signal for accelerated replacement cycle demand.| Strategic Initiative | Industry Significance |
|---|---|
| Electron Beam PVD Cell Investment | Captive deposition capacity secures specification lock-in from GE Aviation and Rolls-Royce procurement. |
| Backward Integration into Precursor Supply | Upstream control over yttrium oxide sourcing mitigates Chinese export licensing concentration risk. |
| Long-term Service Agreement Expansion | Power-by-the-hour bundling displaces transactional refurbishment contracts in aerospace aftermarket. |
| Aluminate Chemistry Qualification | Gadolinium zirconate certification opens 100-150°C temperature step-up opportunities in adaptive cycle engines. |
| India Market Entry Partnership | NTPC ultra-supercritical pipeline creates first-mover positioning ahead of domestic supplier maturation. |
Research Approach
Independent corroboration across primary interviews with coating service operations managers, aerospace procurement executives, and power plant maintenance directors, plus secondary validation through FAA certification filings, EPA emissions compliance databases, and customs trade data for ceramic precursor flows, underwrites the qualitative findings. Bottom-up triangulation against top-down market sizing from deposition equipment installed base and overhaul interval modeling ensures methodological rigor.
Comparable-period anchoring to historical replacement cycle data and specification migration patterns shapes the projection framework across the analysis window. Segmentation dimensions modeled include ceramic chemistry tier, deposition technology, end-use application, and geographic regulatory cluster. CAGRs derive from equipment fleet expansion, efficiency-driven firing temperature escalation, and mandated durability interval extensions. Forecast inputs incorporate EPA greenhouse gas performance standard compliance curves and FAA Part 33 certification timeline compression.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rare earth oxide supply disruption or accelerated aluminate chemistry substitution. Forecasts reflect documented assumptions regarding turbine fleet expansion, regulatory durability mandates, and deposition technology qualification pathways. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Anti-Microbial Nano Coatings Market
Coatings
Hydrophilic Interior Glass Defogging Coatings Market
Coatings
Global Industrial Floor Coatings Market
Coatings
Clear Coatings Market
Coatings
Non-Stick Coatings Market
Coatings
Wood Sealer Market
Coatings
Brazil Automotive OEM Coatings Market
Coatings
Germany Protective Coatings Market
Coatings
Global Low Friction Coatings Market
Coatings
Polyester Coatings Market
Coatings
Stain Resistant Coatings Market
Coatings
Perfluoroalkoxy (PFA) Coatings Market
Coatings
Coating Auxiliaries Market
Coatings
United Arab Emirates Protective Coatings Market
Coatings
Australia Industrial Coatings Market
Coatings
US Protective Coatings Market