
 Lithium Zirconate Market | 2026-2036
Lithium Zirconate Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Zirconate Market Insights
Energy sector procurement is collapsing the historical buyer mix that ceramics and electronics segments once dominated. Tosoh Corporation leverages its integrated zirconium material pipeline to sustain captive supply advantages across high-purity powder grades. Saint-Gobain anchors European demand through specialized crystal production for thermal barrier systems. American Elements competes on geographic reach, operating direct sales channels that bypass distributor markups for North American research buyers.
Lithium zirconate is a ceramic oxide compound with the formula Li₂ZrO₃, typically synthesized via solid-state reaction of lithium carbonate and zirconium dioxide at temperatures exceeding 1000°C, serving primarily as a solid electrolyte precursor and CO₂ absorbent at elevated temperatures. Powder formulations lead volume shipments due to their direct integration into battery cathode coating slurries and ceramic sintering processes, while crystal segments command premium positioning for aerospace thermal management applications where phase stability above 1500°C is mandatory. The battery application category is expanding fastest as solid-state electrolyte developers qualify lithium zirconate as an alternative to lithium lanthanum zirconate in intermediate-temperature operating windows.
China's SAMR enforces GB standards on ceramic material purity that filter import access for non-compliant suppliers, while Japan's METI classifies lithium zirconate under strategic material lists that trigger subsidy eligibility for domestic production scale-up. The EU REACH framework governs zirconium compound registration and downstream user notification obligations that lengthen European market entry timelines for new producers. Stakeholders must monitor solid-state battery pilot line yield data and regulatory material list revisions to time capacity commitments against qualified demand inflection points.
Market Dynamics
Solid-state battery developers are collapsing the historical buyer mix that ceramics and electronics segments once dominated, redirecting supplier qualification criteria toward high-purity powder grades and captive zirconium processing capabilities.
Growth Catalysts
- Japan's METI clean-energy material standards:These regulations redirect supplier qualification criteria toward lower-carbon production methods, accelerating domestic production scale-up through subsidy eligibility triggers.
- Solid-state electrolyte qualification:Battery developers are qualifying lithium zirconate as an alternative to lithium lanthanum zirconate in intermediate-temperature operating windows, expanding addressable demand.
- East Asian manufacturing clusters:Concentrated demand in Japan and China leverages overlapping zirconium processing infrastructure and battery supply chains to reduce logistics friction.
Market Restraints
- Zirconium dioxide feedstock volatility:Input cost swings compress margin buffers for non-integrated producers lacking captive mineral supply.
- China's SAMR GB standards:Ceramic material purity mandates filter import access for non-compliant suppliers, creating regulatory friction for European and North American entrants.
- Lithium lanthanum zirconate substitution:Competing solid electrolyte materials threaten to capture high-temperature operating window applications above lithium zirconate's thermal ceiling.
Strategic Opportunities
- Aerospace thermal management:Crystal segments command premium positioning where phase stability above 1500°C is mandatory, opening defensible niche markets beyond battery applications.
- China's dual carbon goals:National emissions targets redirect state procurement toward lower-carbon zirconate production methods, creating regulatory tailwinds for compliant domestic suppliers.
- Direct sales channel innovation:Research buyers in North America increasingly bypass distributor markups through manufacturer-direct relationships, compressing channel costs.
Industry Challenges
- High-temperature synthesis capex intensity:Solid-state reaction furnaces operating above 1000°C demand substantial capital deployment, constraining capacity expansion timelines for new entrants.
- EU REACH registration timelines:Zirconium compound registration and downstream user notification obligations lengthen European market entry timelines, delaying revenue recognition for qualified demand.
- Solid-state battery pilot yield uncertainty:Capacity commitments risk misalignment against qualified demand inflection points until commercial-scale yield data stabilizes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Zirconate Market |
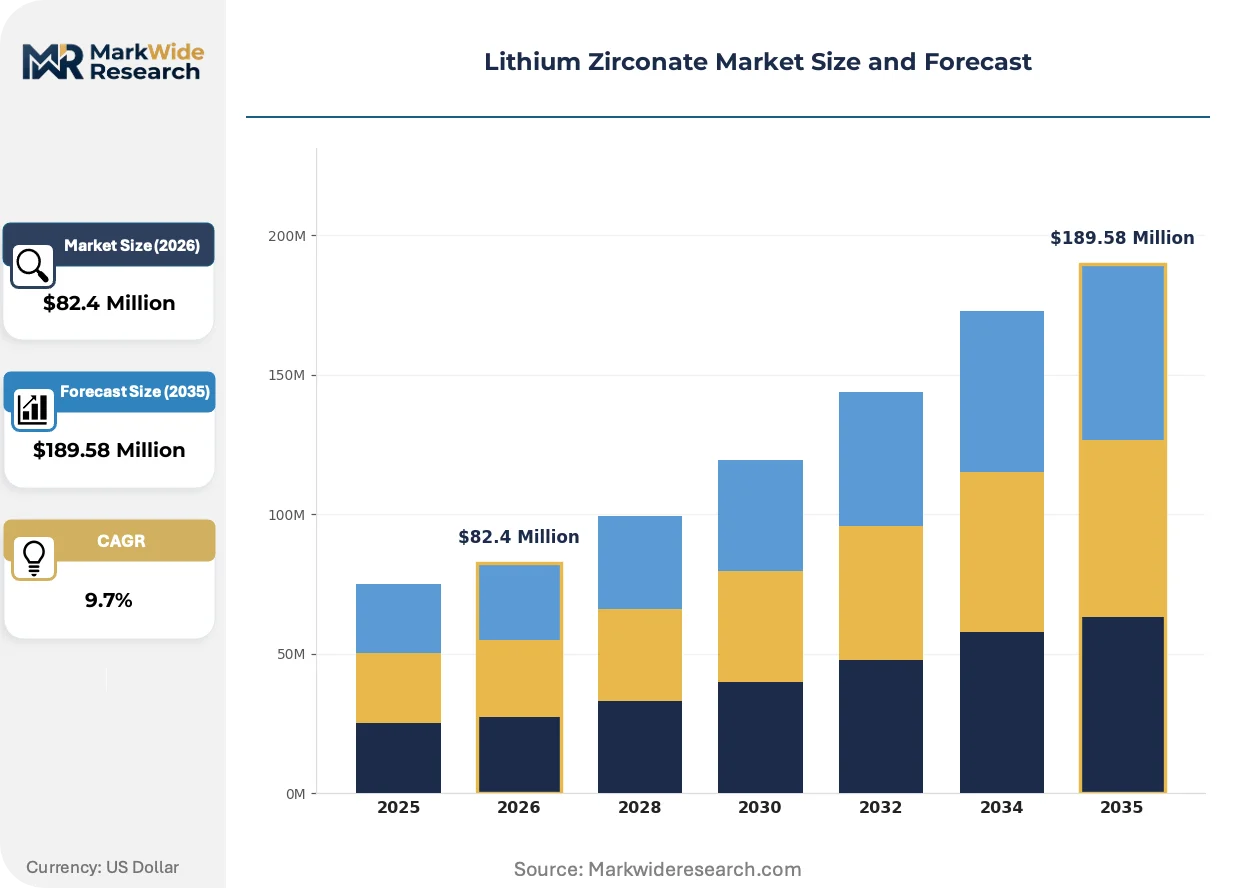
| Market Size in 2026 | $82.4 Million |
| Market Size in 2035 | $189.58 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Crystals, Pellets Application: Ceramics, Electronics, Batteries, Catalyst End User: Aerospace, Automotive, Energy, Consumer Goods Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Saint-Gobain, Daiichi Kigenso Kagaku Kogyo, American Elements, Tosoh Corporation, Lorad Chemical, Guangdong Orient Zirconic Industrial Science and Technology, Shandong Sinocera Functional Material, NextGen Ceramics, CeramiCore Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Zirconate Market Trends and Innovations
Process intensification and regulatory material reclassification are actively reshaping how lithium zirconate is synthesized, qualified, and procured across overlapping industrial verticals.
Low-temperature sol-gel synthesis routes are decomposing the traditional solid-state reaction monopoly that has governed lithium zirconate production for decades. Solid-state battery developers are piloting these alternative chemistries to reduce energy input costs and improve powder homogeneity. The structural consequence is compressing the capital barrier that historically protected incumbent furnace operators.
REACH framework amendments governing zirconium compound classification are tightening downstream user notification obligations across European manufacturing. Industrial consequence includes extended compliance timelines for new market entrants and elevated documentation burdens for existing suppliers. Battery material distributors are responding by consolidating supplier panels to reduce regulatory exposure.
Research buyers are compressing procurement cycles from annual blanket orders to quarterly spot purchases aligned with pilot line yield milestones. Direct manufacturer relationships are displacing traditional distributor networks for North American research institutions and solid-state battery startups. This behavioral shift is most visible in Massachusetts and California clusters where venture-funded battery developers prioritize supply chain transparency over volume discounts.
Lithium Zirconate Market Segmentation
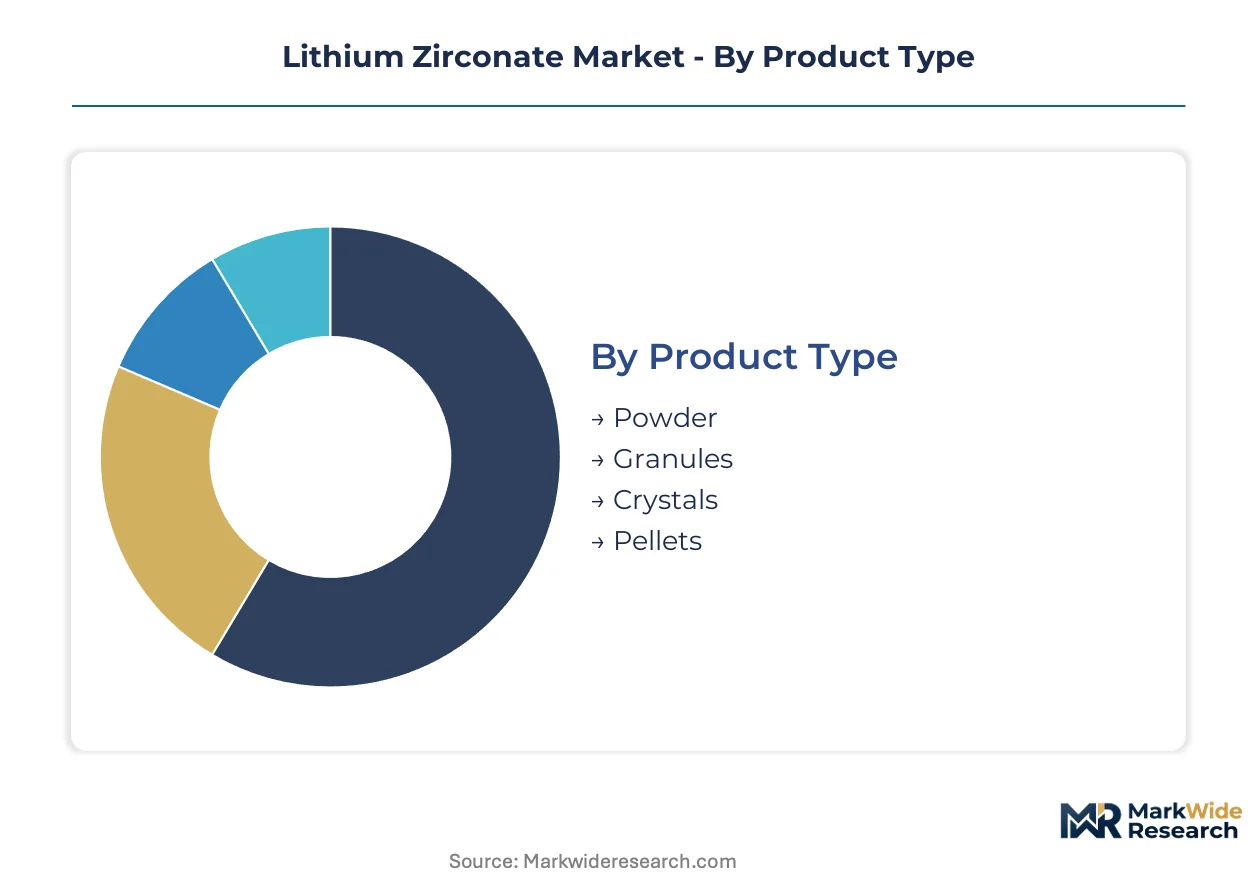
Lithium zirconate procurement channels diverge sharply by purity grade and volume scale. Powder formulations flow through distributor networks to ceramics manufacturers, while crystal grades move direct to aerospace primes. Understanding these channel-segment pairings exposes where margin pools concentrate and where new entrants face entrenched incumbents.
Product Type:
Powder and crystal grades dominate distinct channel configurations, with powder flowing through bulk chemical distributors and crystals commanding direct manufacturer relationships.
- Powder:Fine particulate formulations synthesized via solid-state reaction above 1000°C, typically 99.5-99.9% purity grades. Demand concentrates in East Asian battery cathode coating operations where slurry integration requires consistent particle size distribution. China's SAMR GB standards on ceramic purity filter non-compliant import access, advantaging domestic furnace operators.
- Crystals:Monocrystalline and polycrystalline structures exhibiting phase stability above 1500°C. Procurement runs direct from specialty ceramic manufacturers to Japanese and German aerospace thermal barrier system suppliers. Japan's METI strategic material classification triggers subsidy eligibility for domestic crystal production scale-up.
- Granules:Intermediate agglomerated forms serving ceramic sintering feedstock applications.
- Pellets:Compressed pre-forms for high-temperature CO₂ absorption systems in industrial gas processing.
By volume, powder leads. By growth pace, crystals are climbing the fastest.
Application:
Cost tier stratification separates commodity ceramics procurement from premium battery electrolyte qualification programs.
- Batteries:Solid-state electrolyte precursor applications qualify lithium zirconate against lithium lanthanum zirconate in intermediate-temperature windows. Japanese solid-state battery pilot lines in Osaka and Toyota City drive qualification demand. METI clean-energy material standards redirect supplier criteria toward lower-carbon production methods.
- Ceramics:Traditional refractory and structural ceramic additive applications, volume-heavy but margin-compressed. Procurement concentrates in China's Shandong and Jiangsu manufacturing clusters where zirconium processing infrastructure overlaps with tile and sanitaryware production.
- Electronics:Dielectric and insulating ceramic applications in semiconductor fabrication equipment.
- Catalyst:High-temperature CO₂ absorption and alkene epoxidation support media.
By revenue contribution, ceramics still dominates. By expansion trajectory, battery applications are gaining share fastest.
End User:
Customer type determines specification stringency, with automotive and energy buyers imposing qualification protocols that consumer goods purchasers ignore.
- Energy:Solid-state battery developers and grid-scale thermal storage system operators. Procurement cycles compress from annual blanket orders to quarterly spot purchases aligned with pilot yield milestones. Massachusetts and California venture-funded clusters prioritize supply chain transparency over volume discounts.
- Aerospace:Thermal barrier coating system integrators requiring crystal phase stability certification above 1500°C. European primes anchor demand through specialized crystal production contracts with Saint-Gobain.
- Automotive:Electric vehicle solid-state battery programs at Japanese and South Korean OEMs.
- Consumer Goods:Ceramic tile, tableware, and sanitaryware manufacturers purchasing standard powder grades.
By contract value, aerospace leads. By procurement volume growth, energy buyers are expanding most quickly.
Distribution Channel:
Supply concentration in East Asian manufacturing clusters shapes channel efficiency, with direct sales compressing markups where geographic proximity permits.
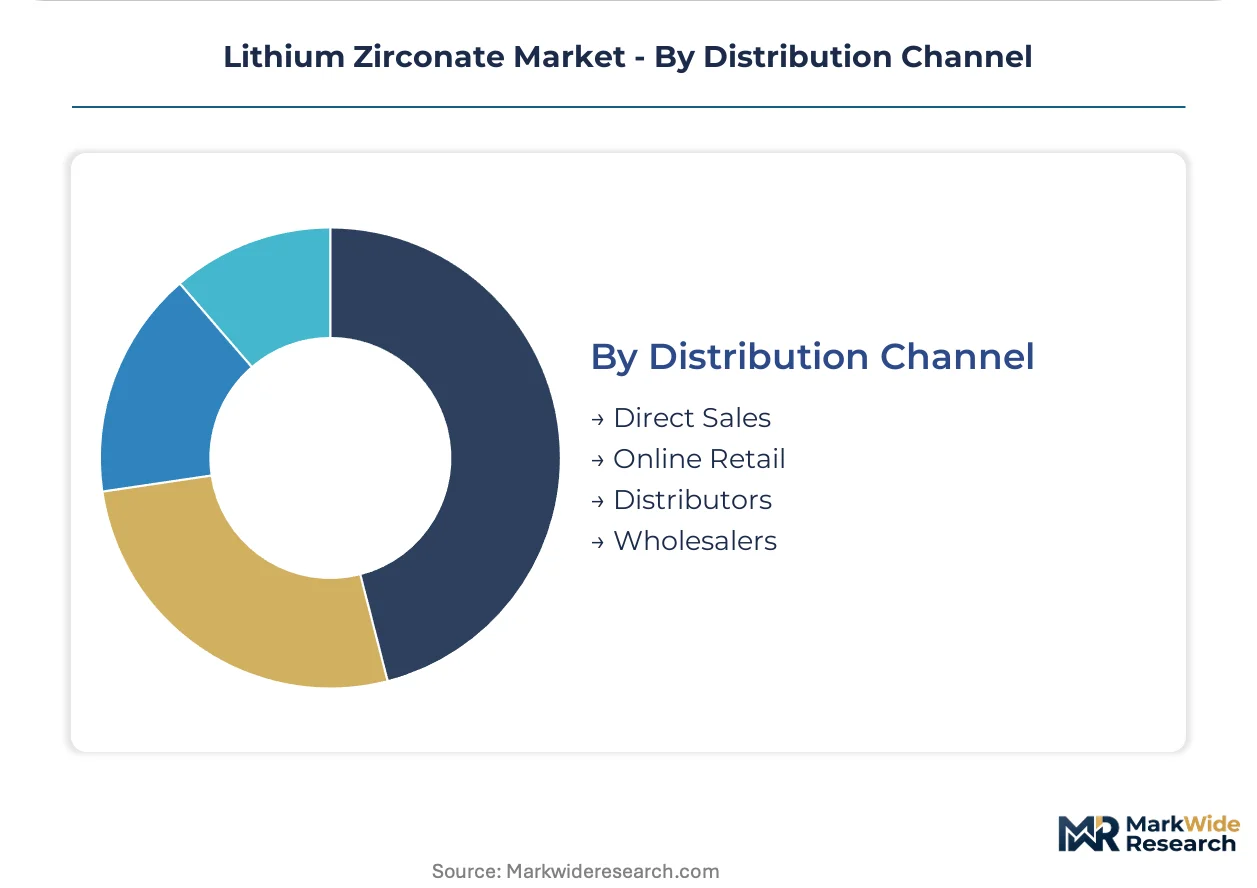
- Direct Sales:Manufacturer-direct relationships bypassing distributor networks. American Elements operates direct channels for North American research buyers. Japanese battery material distributors consolidate supplier panels to reduce REACH regulatory exposure.
- Distributors:Bulk chemical distributors serving ceramics and industrial catalyst buyers. Tosoh Corporation leverages integrated zirconium pipelines to sustain captive supply advantages.
- Online Retail:Small-volume research grade procurement through specialized chemical supply platforms.
- Wholesalers:Commodity powder aggregation for downstream ceramic processor resale.
By transaction count, distributors lead. By margin retention, direct sales channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Nagoya's specialized ceramic mineral handling terminals anchor Japan's zirconium processing corridor, while China's Yangtze River Delta pipeline networks feed integrated zirconate furnace clusters. These infrastructure assets concentrate production gravity where battery supply chains and refractory ceramics manufacturing overlap.
China
Solid-state battery cathode coating operations in Jiangsu and Shandong provinces drive powder-grade consumption. SAMR enforces GB standards on ceramic material purity that filter import access for non-compliant foreign suppliers. The Yangtze River Delta manufacturing belt hosts overlapping zirconium processing infrastructure and lithium-ion battery supply chains.
Japan
Pilot line qualification programs at Osaka and Toyota City facilities redirect procurement toward high-purity electrolyte precursor grades. METI classifies lithium zirconate under strategic material lists that trigger subsidy eligibility for domestic production scale-up. The Chubu region's Nagoya-Ogaki corridor concentrates specialty ceramic furnace operators serving aerospace thermal barrier contracts.
United States
Venture-funded battery developers in Massachusetts and California clusters compress procurement cycles to quarterly spot purchases aligned with yield milestones. EPA industrial chemical reporting obligations govern zirconium compound handling at processing facilities. The Pacific Northwest hosts research-grade material distributors bypassing traditional channel markups through direct manufacturer relationships.
Germany
Aerospace primes anchor crystal-grade demand through specialized thermal barrier system production contracts. ECHA REACH framework amendments tighten downstream user notification obligations for zirconium compound registration. The Bavarian industrial corridor around Nuremberg hosts precision ceramic manufacturers qualifying supply chains for EU defense procurement standards.
Lithium Zirconate Market Competitive Landscape
Concentration sits with integrated zirconium material pipeline operators and specialty ceramic manufacturers. The supplier base stratifies across captive mineral processors, research-grade direct sellers, and aerospace crystal specialists. Three archetypes dominate: backward-integrated chemical conglomerates with in-house zirconium dioxide supply; direct-channel material science vendors serving North American research buyers; and thermal barrier system contractors with aerospace certification lock-in. Competitive moves center on capacity expansion in East Asian manufacturing clusters and strategic partnerships between battery material distributors and pilot line developers.
Among Japanese chemical conglomerates, Tosoh Corporation and Daiichi Kigenso Kagaku Kogyo exemplify the backward-integrated archetype with captive zirconium processing capabilities. Saint-Gobain occupies a position representing European aerospace thermal barrier specialization. American Elements sits within the direct-sales tier, anchoring North American research buyer relationships that bypass distributor networks. These three patterns illustrate how geographic proximity to battery supply chains, aerospace certification requirements, and channel cost compression define competitive positioning.
| Leading Market Players |
|---|
| Saint-Gobain |
| Daiichi Kigenso Kagaku Kogyo |
| American Elements |
| Tosoh Corporation |
| Lorad Chemical |
| Guangdong Orient Zirconic Industrial Science and Technology |
| Shandong Sinocera Functional Material |
| NextGen Ceramics |
| CeramiCore Technologies |
| Others |
Pricing and Supply Chain Analysis
Lithium lanthanum zirconate displacement by lithium zirconate in intermediate-temperature solid-state electrolyte applications is simultaneously concentrating procurement gravity in Japan's Chubu corridor and compressing price premiums for non-integrated furnace operators lacking captive zirconium dioxide supply.
Pricing Analysis
Three-tier pricing structure across battery-grade powder, aerospace crystal, and industrial ceramic feedstock segments governs transaction economics. Price differentiation hinges on METI clean-energy certification status and volume scale, with automotive solid-state battery developers commanding steepest discounts above 500-kilogram quarterly commitments. Cost compression in standard ceramic powder is intensifying because China's SAMR GB compliance costs filter marginal foreign entrants. Consumer goods ceramic manufacturers exhibit highest price sensitivity, while aerospace thermal barrier system integrators prioritize phase stability certification over unit economics.
Supply Chain Analysis
Zirconium dioxide concentrate transit through Australia's heavy mineral sand corridors underwrites feedstock security for East Asian furnace clusters. Geographic supply concentration centers on China, Japan, and South Korea, where zirconium processing infrastructure overlaps with solid-state battery cathode coating operations. Raw material sourcing draws from Australian mineral sands, South African zircon feedstock, and Indonesian heavy mineral deposits. Single-source vulnerability persists in high-purity zirconium sponge refining. Distribution runs through bulk chemical distributors for ceramic buyers and direct manufacturer relationships for aerospace and battery developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from pilot-line yield uncertainty as solid-state battery commercialization timelines compress procurement cycles toward qualified demand inflection points.
For Market Incumbents: Shield margin position by deepening captive zirconium dioxide supply through backward integration into Australian heavy mineral sand offtake agreements. Accelerate METI clean-energy certification investment to capture subsidy-eligible procurement from Japanese solid-state battery developers before lithium lanthanum zirconate alternatives capture high-temperature applications.
For New Entrants and Emerging Players: Anchor in North American research buyer direct channels where American Elements' geographic reach leaves pricing gaps for venture-funded Massachusetts and California battery startups. Target sol-gel synthesis technology licensing as the most penetrable white-space angle, offering furnace operators energy input cost reduction without capital-intensive solid-state reaction retrofit.
For Investors and Strategic Acquirers: The market sits at a pre-commercial scale-up phase that favors backward-integrated specialty ceramic manufacturers with existing zirconium processing pipelines and aerospace certification lock-in. Long-term viability over the next decade rests on solid-state battery yield stabilization and regulatory material list permanence. Monitor Osaka and Toyota City pilot line qualification data as the primary inflection signal for capacity commitment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zirconium Feedstock | Captive mineral supply insulates margin buffers against Australian heavy mineral sand price volatility. |
| Low-Temperature Sol-Gel Capacity Buildout | Alternative synthesis routes reduce energy input costs and improve powder homogeneity for battery developers. |
| METI Clean-Energy Certification Program | Subsidy eligibility triggers redirect procurement toward compliant domestic Japanese production scale-up. |
| Direct Sales Channel Expansion | Manufacturer relationships bypass distributor markups for North American research buyers in Massachusetts and California. |
| Aerospace Crystal Production Joint Venture | Phase stability certification above 1500°C opens defensible niche markets beyond battery applications. |
Research Methodology
A standing panel of solid-state battery R&D directors, zirconium processing plant managers, aerospace thermal barrier system procurement leads, and ceramic material distributors provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from METI strategic material filings, SAMR GB standard publications, ECHA REACH registration databases, and customs trade data on zirconium compound flows. Bottom-up demand modeling from pilot line qualification programs triangulated against top-down capacity assessments from East Asian furnace operators.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product grade tier, end-use application, purity specification, and regional manufacturing cluster. CAGRs were derived from qualified demand inflection timing against capacity expansion timelines. Industry-specific forecast inputs incorporated solid-state battery yield milestone data and regulatory material list revision schedules.
Decision-makers should treat outputs as directional under assumptions of stable zirconium dioxide feedstock availability and sustained METI subsidy eligibility; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as lithium lanthanum zirconate substitution threats and REACH framework amendment timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Asia-Pacific Kaolin Market
Ceramics
Advanced Ceramic Additives Market
Ceramics
Tetramethyl Orthosilicate Market
Ceramics
South Korea Ceramic Tiles Market
Ceramics
Fly Ash and Ceramic Microsphere Market
Ceramics
Global Pseudo Boehmite Market
Ceramics
UAE Ceramic Tiles Market
Ceramics
Advanced Ceramics Market
Ceramics
Glass Ceramics Market
Ceramics
Germany Ceramic Tiles Market
Ceramics
Low Density Ceramic Proppant Market
Ceramics
Brazil Ceramic Tiles Market
Ceramics
Kaolin Market
Ceramics
Global Ceramic Balls Market
Ceramics
Dielectric Ceramics Market
Ceramics
Strontium Carbonate Market