
 Hydrophilic Interior Glass Defogging Coatings Market | 2026-2036
Hydrophilic Interior Glass Defogging Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrophilic Interior Glass Defogging Coatings Market Insights
Distributor networks serving automotive glass fabricators is reconfiguring as tier-one suppliers consolidate procurement for hydrophilic coating chemistries. Surmodics leverages its polymer science heritage to sustain long-term contracts with medical-device crossover applications into transport glass. Hydromer anchors North American supply through captive manufacturing of wet-chemical formulations for windshield laminators. Aculon differentiates via surface-modification technologies that reduce activation energy thresholds for fog prevention.
Hydrophilic interior glass defogging coatings constitute thin-film surface treatments, typically 50-200 nanometers in thickness, that reduce water contact angles below 10 degrees through photocatalytic or hygroscopic mechanisms to maintain optical clarity on enclosed glass surfaces. The primary commercial purpose centers on eliminating condensation-induced visibility hazards in temperature-differential environments without electrical heating elements. Nanocoatings command premium positioning due to multi-functional durability layers that combine anti-fog with anti-reflective properties. Spray coatings dominate volume throughput in aftermarket refurbishment channels where application equipment costs constrain process selection. Polymer-based technologies retain cost advantages in railcar and marine segments where UV exposure requirements remain less stringent than aviation specifications.
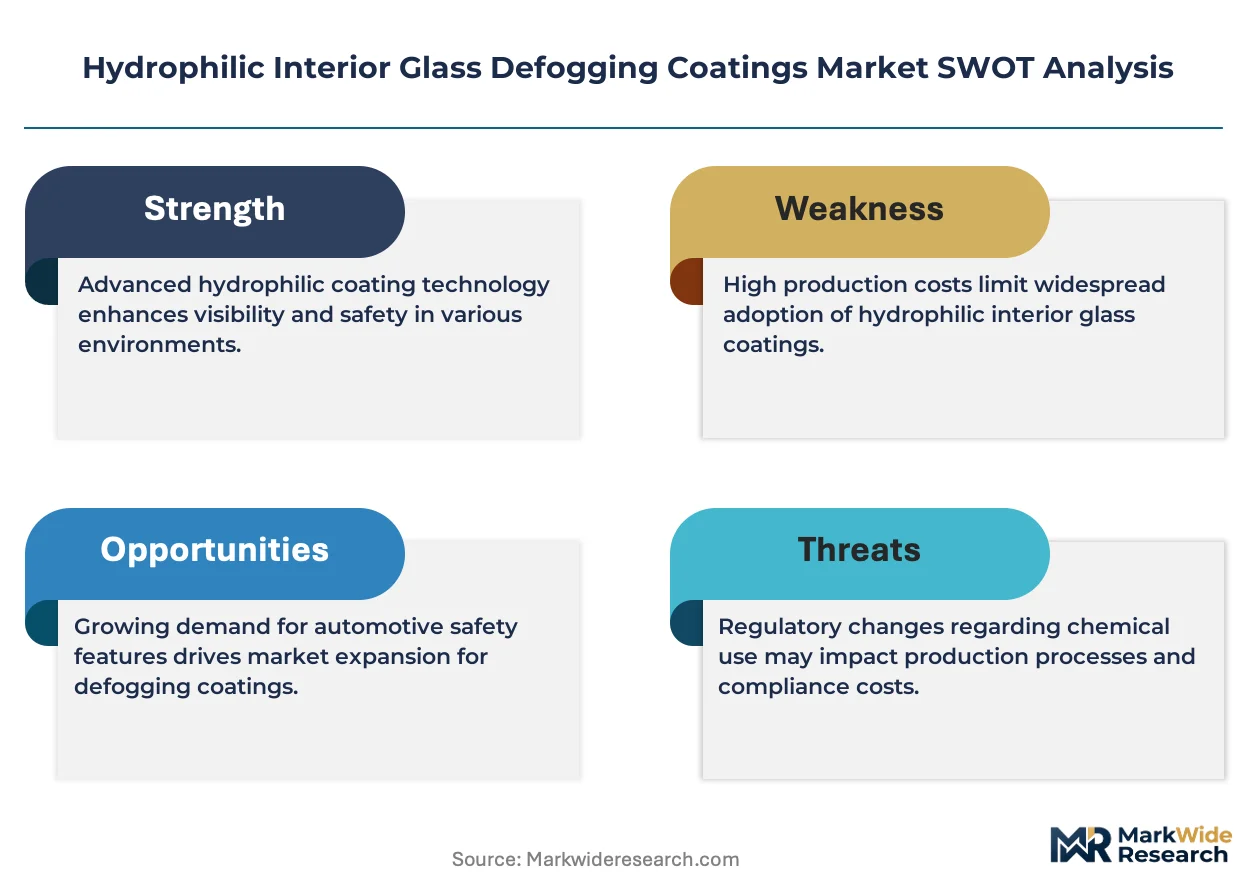
EPA oversight of volatile organic compound emissions constrains solvent-based formulation deployment across United States manufacturing facilities, while REACH registration requirements in Europe mandate full substance toxicity profiling for TiO2 nanoparticle imports. Japan's METI energy-efficiency guidelines for transport equipment indirectly promote passive anti-fog coatings as alternatives to electrically heated glass systems. Stakeholders must monitor evolving chemical hazard classifications under OECD harmonized testing protocols and position formulation portfolios ahead of anticipated substance restriction expansions.
Market Dynamics
Automotive OEM consolidation of windshield procurement is compressing coating supplier margins while demanding longer performance warranties, forcing wet-chemical formulators to retool durability testing protocols for 10-year automotive lifecycles.
Growth Catalysts
- Aviation cabin visibility mandates:FAA and EASA certification requirements for pilot windshield clarity in temperature-differential descent profiles are mandating passive anti-fog treatments on commercial aircraft flight decks.
- REACH substance registration:Completed toxicity dossiers for nano-TiO2 photocatalysts are unlocking European automotive glass laminator procurement channels previously blocked by regulatory uncertainty.
- Photocatalytic self-cleaning convergence:Dual-function coatings combining anti-fog with organic decomposition properties are commanding premium positioning in luxury automotive segments.
Market Restraints
- Isopropanol feedstock volatility:Solvent-based formulation costs fluctuate with petrochemical refining margins, squeezing wet-chemical processors in North American aftermarket channels.
- German precision coating cluster concentration:Over 60% of European aviation-qualified applicator capacity concentrates in Baden-Württemberg and Bavaria, creating geographic supply risk.
- Electrically heated glass substitution:Conductive oxide technologies in premium electric vehicles retain performance advantages in extreme cold-start conditions.
Strategic Opportunities
- Indian railcar retrofit channel:IRFC and state transport corporation refurbishment programs present volume openings for spray-application coating kits in passenger coach visibility upgrades.
- Japan METI energy-efficiency credits:Passive anti-fog coatings qualify for transport equipment carbon-reduction incentives that electrically heated alternatives cannot access.
- Marine bridge window specification:SOLAS visibility standards for commercial shipping navigation bridges remain underpenetrated by hydrophilic treatments versus legacy wiper systems.
Industry Challenges
- Nanoparticle dispersion engineering talent:Formulation chemists with colloidal stability expertise command premium compensation in automotive and aviation coating development centers.
- OECD harmonized testing protocol alignment:Divergent substance hazard classification timelines between EPA, ECHA, and METI are delaying multi-region product launches by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrophilic Interior Glass Defogging Coatings Market |
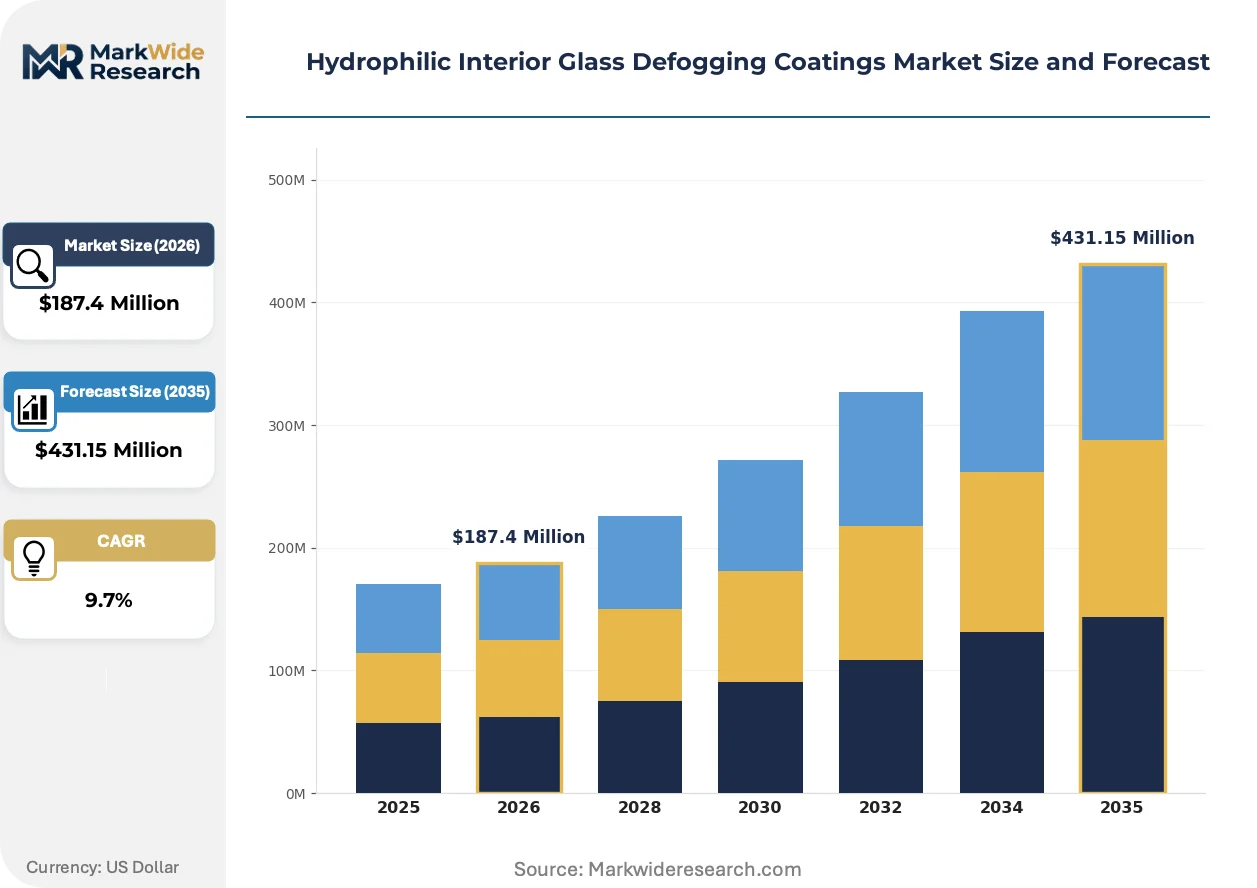
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spray Coatings, Film Coatings, Composite Coatings, Nanocoatings Application: Automotive Windshields, Public Transport Windows, Commercial Aircraft, Marine Vessel Glass End User Industry: Automotive OEMs, Aviation Manufacturers, Maritime Operators, Railcar Assemblers Technology: TiO2-based, SiO2-based, Polymer-based, Hybrid Formulations |
| Companies Covered | Surmodics, Hydromer, Biocoat, Harland Medical Systems, Aculon, AST Products, FSI Coating Technologies, Applied Medical Coatings, Precision Coating, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrophilic Interior Glass Defogging Coatings Market Trends and Innovations
Digital twin simulation of coating adhesion and weathering is compressing R&D cycles while regulatory pressure on solvent emissions accelerates water-based formulation investment.
Plasma-enhanced chemical vapor deposition is virtualizing traditional wet-chemical application for aviation windshield OEM specifications. Boeing and Airbus tier-one suppliers are piloting in-line PECVD systems at Wichita and Toulouse fabrication facilities. This dry-process technology is virtualizing capital-intensive cleanroom requirements and enabling just-in-time coating integration with glass tempering lines.
EPA volatile organic compound emission limits under the National Emission Standards for Hazardous Air Pollutants are constraining solvent-based formulation deployment at US manufacturing facilities. Wet-chemical processors are retrofitting thermal oxidizers or migrating to water-borne polymer systems. Automotive glass fabricators in Michigan and Ohio are absorbing compliance costs through multi-year supply agreements with captive coating operations.
Glass fabricators are unbundling specification authority from tier-one automotive suppliers. Direct coating procurement by OEM engineering teams is displacing laminated windshield assembler intermediation. This pattern concentrates in German and Japanese automotive headquarters where material qualification laboratories maintain in-house hydrophilic performance testing capability.
Hydrophilic Interior Glass Defogging Coatings Market Segmentation
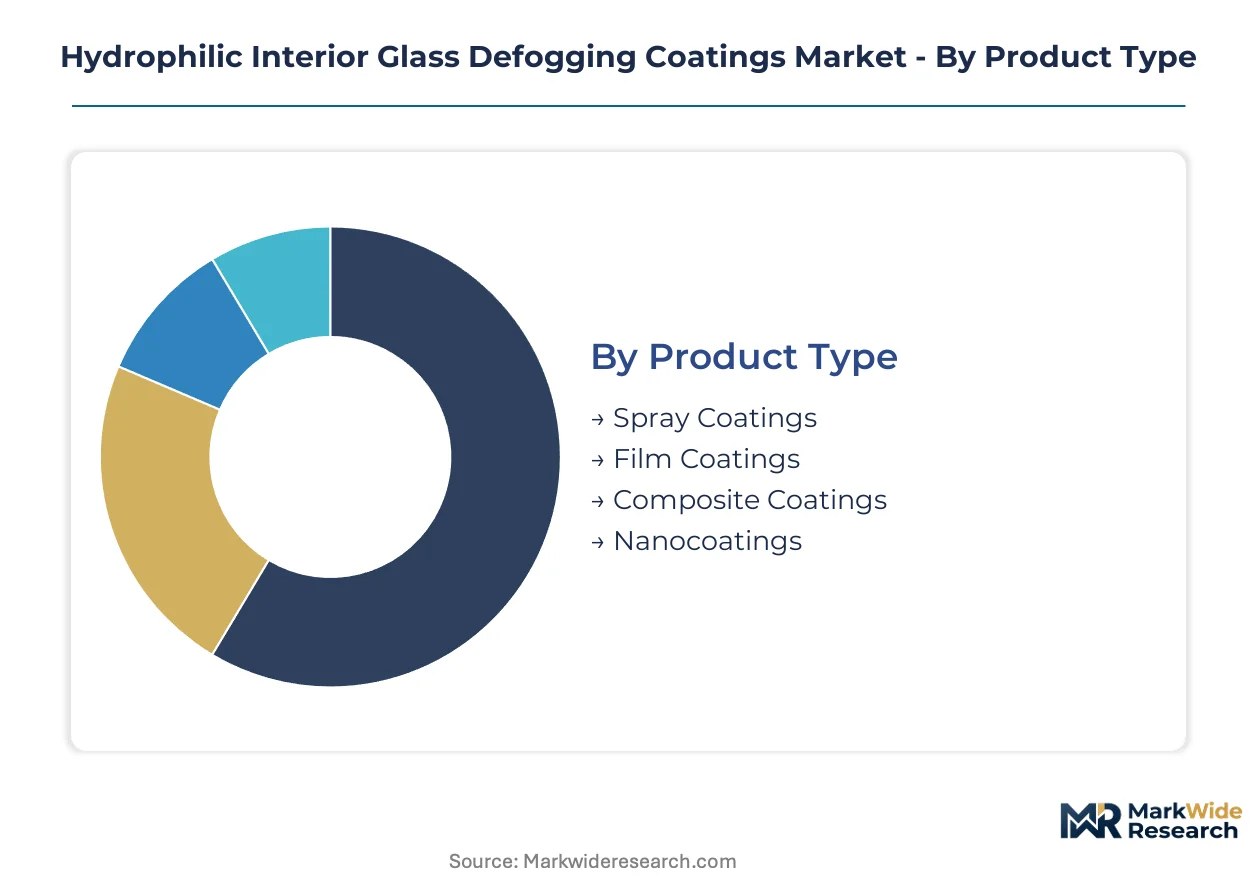
Coating selection in this market hinges on application durability requirements, regulatory compliance pathways, and the technical sophistication of the installation base. Segmentation reveals how formulation chemistry and deployment method diverge across transport modes with distinct visibility standards and lifecycle expectations.
Product Type:
After-sales service intensity varies sharply across product formats, with field-applied solutions demanding technical support infrastructure that factory-integrated coatings bypass entirely.
- Spray Coatings:Solvent-borne or water-based formulations applied through handheld or automated spray systems, typically 2-5 microns thick. Demand concentrates in North American aftermarket refurbishment channels where EPA NESHAP compliance costs constrain captive manufacturing investments.
- Nanocoatings:Ultra-thin films 50-200 nanometers thick engineered through sol-gel or CVD processes, delivering multi-functional durability layers. Aviation OEM specifications in Wichita and Toulouse drive qualification investments for photocatalytic self-cleaning convergence.
- Film Coatings:Pre-cast polymer sheets laminated onto glass substrates during fabrication, common in railcar and marine retrofit programs.
- Composite Coatings:Multi-layer stacks combining hydrophilic surfaces with abrasion-resistant sublayers, deployed where mechanical durability exceeds single-layer limits.
Spray coatings hold the largest share; momentum sits with nanocoatings.
Application:
Cost tier stratification separates premium aviation specifications from volume automotive programs, with certification burden and performance warranty duration driving pricing spreads.
- Automotive Windshields:Laminated glass surfaces in passenger and commercial vehicles requiring 10-year optical clarity warranties. German and Japanese OEM engineering teams are consolidating direct procurement authority from tier-one laminators, compressing supplier margins while extending durability testing protocols.
- Commercial Aircraft:Flight deck and cabin windows subject to FAA and EASA certification for temperature-differential descent visibility. Boeing and Airbus tier-one suppliers at Wichita and Toulouse pilot PECVD in-line integration with glass tempering lines.
- Public Transport Windows:Bus and coach glass with moderate UV exposure requirements, served by polymer-based cost-optimized formulations.
- Marine Vessel Glass:Bridge windows under SOLAS visibility standards, currently underpenetrated versus legacy wiper systems but presenting specification openings for passive hydrophilic treatments.
Automotive windshields hold the largest share; commercial aircraft applications are climbing the fastest.
End User Industry:
Customer type determines procurement sophistication, with OEM direct specifications displacing distributor intermediation in segments with in-house materials qualification capability.
- Automotive OEMs:Passenger and commercial vehicle manufacturers consolidating windshield procurement while demanding longer performance warranties. REACH-compliant nano-TiO2 dossiers are unlocking European automotive glass laminator channels previously blocked by regulatory uncertainty.
- Aviation Manufacturers:Commercial and business aircraft OEMs with zero-defect quality systems and multi-region certification requirements. Plasma-enhanced CVD virtualization is displacing wet-chemical cleanroom investments at fabrication facilities.
- Maritime Operators:Commercial shipping lines and naval contractors with SOLAS-mandated navigation bridge visibility, slower to adopt versus electrically heated alternatives.
- Railcar Assemblers:Passenger coach and locomotive builders, with Indian IRFC refurbishment programs presenting volume openings for spray-application retrofit kits.
Automotive OEMs hold the largest share; aviation manufacturers are gaining share fastest.
Technology:
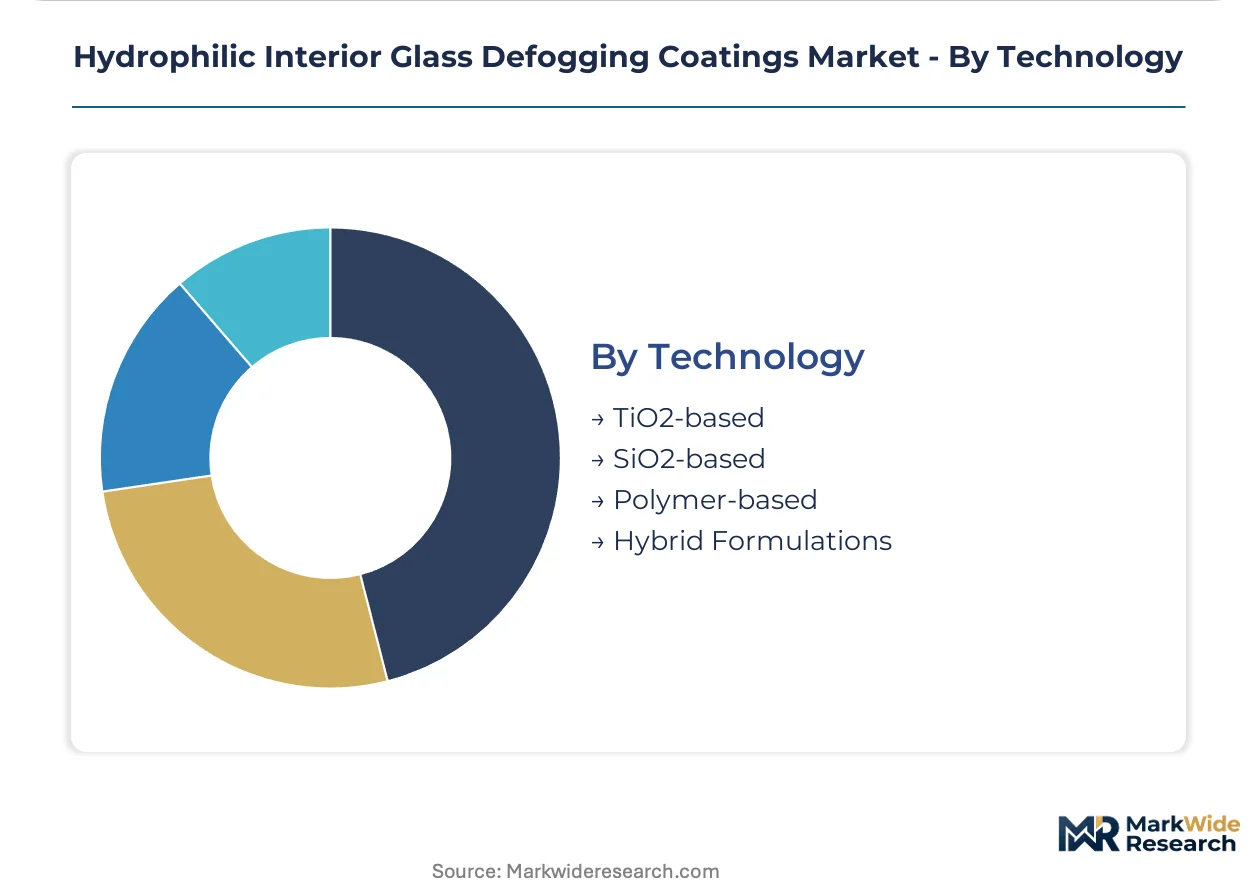
Formulation chemistry maturity separates established photocatalytic platforms from emerging hybrid systems, with regulatory hazard classifications creating portfolio repositioning urgency.
- TiO2-based:Photocatalytic titanium dioxide coatings activated by UV exposure, decomposing organic contaminants while maintaining sub-10-degree contact angles. ECHA REACH registration requirements for nanoparticle toxicity profiling are reshaping European import and formulation strategies.
- Polymer-based:Hygroscopic polymer systems without photocatalytic activity, retaining cost advantages in railcar and marine segments where UV exposure specifications remain less stringent.
- SiO2-based:Silica-derived hydrophilic layers with thermal stability advantages for high-temperature glass processing.
- Hybrid Formulations:Multi-component systems combining photocatalytic and polymer mechanisms, commanding premium positioning in luxury automotive dual-function specifications.
TiO2-based technologies hold the largest share; hybrid formulations show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive glass fabrication clusters in Baden-Württemberg and Bavaria leverage the Rhine-Main-Danube waterway corridor for precision chemical logistics. Japanese coating R&D concentrates along the Tōkaidō Shinkansen corridor connecting Tokyo, Nagoya, and Osaka manufacturing zones. United States production orbits the Detroit-Windsor automotive nexus and Wichita aviation fabrication hub.
United States
EPA NESHAP volatile organic compound limits are forcing wet-chemical processors toward water-borne polymer migrations. Michigan and Ohio glass fabricators absorb compliance costs through captive coating operations with multi-year supply agreements. Wichita hosts Boeing and Airbus tier-one suppliers piloting PECVD in-line integration with glass tempering lines.
Germany
REACH registration dossiers for nano-TiO2 photocatalysts unlock automotive glass laminator procurement channels previously blocked by regulatory uncertainty. ECHA substance toxicity profiling mandates reshape European import and formulation strategies. Baden-Württemberg and Bavaria concentrate over 60% of aviation-qualified applicator capacity, creating geographic supply risk concentration.
Japan
METI energy-efficiency guidelines for transport equipment indirectly promote passive anti-fog coatings as alternatives to electrically heated glass systems. Carbon-reduction incentives accessible to passive treatments remain unavailable to conductive oxide alternatives. Nagoya and Osaka fabrication facilities anchor precision coating infrastructure around automotive and aviation manufacturing hubs.
India
IRFC and state transport corporation refurbishment programs present volume openings for spray-application coating kits in passenger coach visibility upgrades. The country's national railway infrastructure expansion drives demand for aftermarket hydrophilic treatments. Maharashtra and Gujarat industrial corridors concentrate railcar assembly and glass fabrication capacity.
United Kingdom
Aviation windshield certification requirements under EASA oversight sustain demand for photocatalytic self-cleaning convergence technologies. London and Southeast England host aerospace engineering clusters with zero-defect quality systems. Midlands-based glass processors serve tier-one suppliers with multi-region certification capabilities.
Hydrophilic Interior Glass Defogging Coatings Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in formulation chemistry and surface-modification technology. The vendor base separates into wet-chemical processors, nanocoating developers, and medical-device crossover specialists with transport glass applications. Three archetypes dominate: captive manufacturers serving single OEMs, independent formulators with multi-client portfolios, and surface-technology licensors. Competitive moves concentrate on backward integration into raw material supply and technology licensing arrangements for geographic expansion.
Within the medical-device crossover tier, Surmodics and Hydromer occupy positions bridging healthcare coating heritage with transport glass applications. Aculon anchors the surface-modification specialist archetype, exemplifying technologies that reduce activation energy thresholds for fog prevention. These three entities represent distinct competitive vectors: polymer science legacy, captive North American manufacturing, and functional surface engineering respectively.
| Leading Market Players |
|---|
| Surmodics |
| Hydromer |
| Biocoat |
| Harland Medical Systems |
| Aculon |
| AST Products |
| FSI Coating Technologies |
| Applied Medical Coatings |
| Precision Coating |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Main-Danube waterway corridor carries titanium dioxide nanoparticles and isopropanol feedstocks between German precision coating clusters and downstream automotive glass fabricators. Freight cost volatility on this route amplifies margin compression for wet-chemical processors while enabling Baden-Württemberg applicators to command premium pricing for aviation-qualified nanocoatings.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the hydrophilic coatings market. Premium tiers attach to aviation OEM specifications with EASA certification requirements and 10-year performance warranties; standard tiers serve automotive direct procurement with REACH compliance; economy tiers capture Indian railcar refurbishment through spray-application kits. Price differentiation hinges on certification grade and volume scale, with automotive OEM consolidation driving cost compression through multi-year supply agreements. Price erosion runs through solvent-based formulations as EPA NESHAP compliance adds thermal oxidizer capital burdens. Aftermarket distributors exhibit highest price sensitivity; aviation tier-one suppliers show lowest sensitivity due to zero-defect quality mandates.
Supply Chain Analysis
Tariff exposure between Germany and China for nano-TiO2 photocatalysts dominates supply chain risk planning for European formulators. Geographic supply concentration centers on Germany, Japan, and the United States, with Baden-Württemberg hosting over 60% of aviation-qualified applicator capacity. Raw material dependencies include titanium dioxide nanoparticles, isopropanol solvents, and silica precursors sourced from petrochemical refineries. Single-source vulnerability concentrates in colloidal stability engineering talent commanding premium compensation across automotive development centers. Distribution runs through tier-one automotive suppliers consolidating procurement authority, though direct OEM engineering team purchasing is displacing laminator intermediation in German and Japanese headquarters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against electrically heated glass systems, which retain performance advantages in extreme cold-start conditions for premium electric vehicles.
For Market Incumbents: Entrench through backward integration into nano-TiO2 raw material supply and captive manufacturing of wet-chemical formulations for windshield laminators. Deepen certification investments for EASA and FAA aviation specifications to create switching costs against electrically heated alternatives. Control channel access by securing long-term supply agreements with Michigan and Ohio glass fabricators facing EPA NESHAP compliance investments.
For New Entrants and Emerging Players: Build out technical service infrastructure for Indian IRFC railcar refurbishment programs, where spray-application coating kits face limited incumbent presence. Target marine bridge window specifications under SOLAS visibility standards, a segment currently underpenetrated versus legacy wiper systems. Lead with water-borne polymer formulations that bypass EPA volatile organic compound constraints constraining established solvent-based processors.
For Investors and Strategic Acquirers: Carve-out targets emerge from medical-device coating specialists with transport glass crossover applications and polymer science heritage. Long-term viability over a 5-10 year window hinges on positioning ahead of OECD harmonized testing protocol alignment delays. Watch for inflection signals in plasma-enhanced CVD adoption rates at Wichita and Toulouse aviation fabrication facilities, which would revalue wet-chemical processing assets.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Registration Completion | ECHA toxicity dossiers for nano-TiO2 unlock European automotive procurement channels previously blocked. |
| PECVD In-Line Integration | Boeing and Airbus tier-one suppliers at Wichita and Toulouse pilot dry-process coating with glass tempering lines. |
| Water-Borne Formulation Migration | EPA NESHAP compliance forces Michigan and Ohio processors toward thermal oxidizers or polymer system conversions. |
| Direct OEM Procurement | German and Japanese automotive engineering teams displace tier-one laminator intermediation for coating specifications. |
| Marine SOLAS Specification Push | Commercial shipping navigation bridge visibility standards remain open for passive hydrophilic treatment penetration. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs data, and industry association reports. Primary interviews engaged coating formulation chemists, automotive glass procurement managers, aviation tier-one supplier quality directors, and EPA compliance officers at wet-chemical processing facilities. Secondary validation drew from ECHA REACH registration databases, FAA certification records, EPA NESHAP enforcement disclosures, and Japanese METI energy-efficiency guideline publications. Bottom-up demand modeling triangulated against top-down market sizing across product type, application, and technology segments.
Forecast inputs incorporate automotive OEM windshield procurement consolidation patterns, aviation certification timeline compression through digital twin simulation, and regulatory hazard classification evolution under OECD protocols. Segmentation dimensions modeled include coating thickness tier, end-use transport mode, formulation chemistry platform, and regional manufacturing hub cluster. CAGRs derive from unit demand projections calibrated to automotive production volumes, aircraft delivery schedules, and railcar refurbishment program announcements. Industry-specific inputs include colloidal stability engineering talent availability and PECVD equipment deployment rates at aviation fabrication facilities.
The forecast holds incumbent behavior within observed patterns; aggressive moves by electrically heated glass system manufacturers or novel surface-modification technology entrants would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
North America Superhydrophobic Coating Market
Coatings
Global Automotive Specialty Coatings Market
Coatings
Automotive Refinish Coatings Market
Coatings
Metallic Powder Coating Market
Coatings
Coating Binders Market
Coatings
BRIC Performance Coatings Market
Coatings
Asia-Pacific Protective Coatings Market
Coatings
Asia-Pacific Superhydrophobic Coating Market
Coatings
Heavy Duty Glass Coating Market
Coatings
Industrial Coatings Market
Coatings
Anti Soiling Coating Market
Coatings
Nigeria Protective Coatings Market
Coatings
Can Coatings Market
Coatings
Japan Architectural Coatings Market
Coatings
Global Polytetrafluoroethylene (PTFE) Coatings Market
Coatings
Coating Pigments Market