
 Global Low Friction Coatings Market | 2026-2036
Global Low Friction Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Low Friction Coatings Market Intelligence
Custom formulation services for specific industrial applications is fragmenting the value chain away from standardized, high-volume products. The Chemours Company leverages its deep expertise in fluoropolymer chemistry to serve high-specification aerospace clients. In contrast, PPG Industries, Inc. specializes in large-scale coatings for marine and industrial equipment. Daikin Industries, Ltd. competes on the basis of its advanced fluorochemical research and development capabilities for niche electronics uses.
Low friction coatings are surface-engineered materials designed to reduce the coefficient of friction between two contacting surfaces. These coatings, often just a few microns thick, contain solid lubricants like PTFE or molybdenum disulfide suspended in a binder matrix to ensure adhesion and durability. PTFE and other fluoropolymer-based products command a significant share due to their widespread use in automotive components and food processing equipment. Emerging materials like graphene, however, represent the fastest-growing product type, driven by demand in high-performance aerospace assemblies.
Product formulation and market access are shaped by a complex web of chemical regulations. Compliance with the EU's REACH framework, EPA standards in the United States, and China's GB standards for industrial materials dictates material selection and limits the use of certain volatile organic compounds. Suppliers must therefore balance performance requirements for applications like industrial machinery against an evolving landscape of environmental and health-based chemical restrictions.
Market Dynamics
The fundamental dynamic in the low friction coatings market is the direct conflict between escalating performance demands from end-users and a tightening global regulatory framework. Automotive and aerospace sectors require coatings that deliver higher durability and lower friction coefficients for efficiency, while bodies like the EU's ECHA and the US EPA simultaneously restrict the use of key high-performance fluorochemicals.
Growth Catalysts
- Automotive Fuel Efficiency Mandates:Regulations in the United States and Europe targeting lower vehicle emissions and improved fuel economy create persistent demand for friction-reducing coatings on engine pistons, bearings, and transmission parts.
- Advanced Material Development:The emergence of graphene and other 2D materials as solid lubricants provides a performance leap for specialized applications, particularly in high-performance aerospace assemblies and satellite mechanisms.
- Industrial Automation in China:Rapid expansion in China's manufacturing sector, focused on robotics and high-speed machinery, drives significant volume demand for durable, low friction coatings to improve equipment lifespan and reduce energy consumption.
Market Restraints
- Fluorochemical Regulation:The EU's REACH framework and proposals to restrict per- and polyfluoroalkyl substances (PFAS) create significant formulation uncertainty and risk for products based on PTFE and other fluoropolymers.
- Input Cost Volatility:Prices for key raw materials, including molybdenum disulfide and fluoropolymer precursors, are subject to supply chain disruptions and geopolitical factors, impacting formulator margins and final product pricing.
- Substrate Adhesion Complexity:Achieving durable adhesion of micron-thick coatings to a wide variety of substrates, from advanced composites to specialized metal alloys, remains a significant technical barrier limiting application scope.
Strategic Opportunities
- Medical Device Coatings:There is an underpenetrated opportunity in the medical sector for biocompatible, low friction coatings on devices such as catheters, guidewires, and surgical instruments to improve patient comfort and device performance.
- PFAS-Free Formulations:Developing and marketing high-performance, non-fluorinated coating systems presents a major opportunity to capture share from customers looking to de-risk their supply chains ahead of future regulations.
- Renewable Energy Applications:Wind turbine gearboxes, blade pitch mechanisms, and solar tracking systems represent a growing application area where low friction coatings can enhance energy output and reduce maintenance cycles.
Industry Challenges
- Regulatory Navigation:Formulators face the operational challenge of managing a patchwork of chemical inventories and standards, including the EPA's TSCA in the US, China's GB standards, and Europe's REACH, which complicates global product launches.
- Application Process Control:Ensuring consistent coating thickness and quality during application, especially for complex geometries, requires significant capital investment in automated spray equipment and stringent quality control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Low Friction Coatings Market |
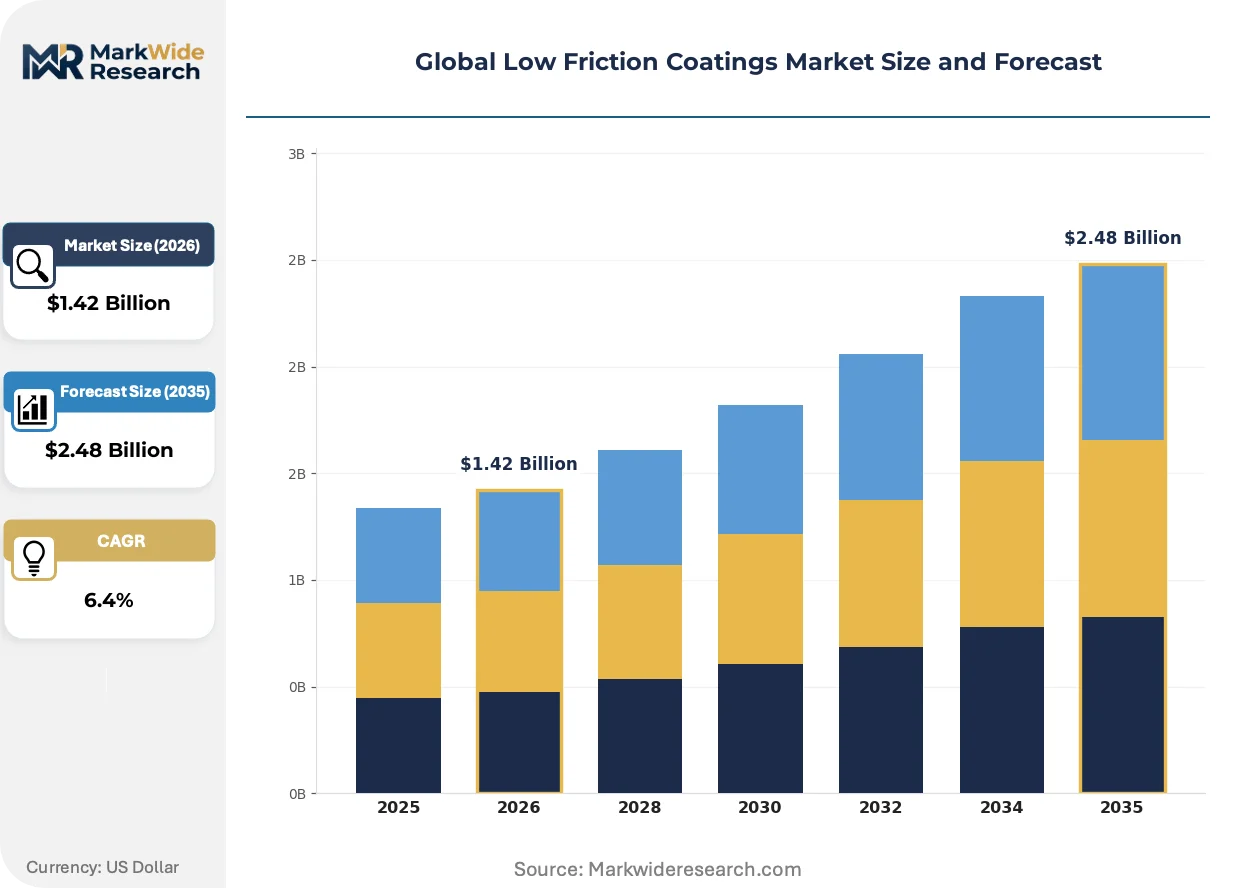
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PTFE, Graphene, Molybdenum Disulfide, Silicone, Fluoropolymer, Boron Nitride Application: Automotive Components, Aerospace Assemblies, Industrial Machinery, Marine Equipment, Textile Machines, Food Processing Technology: Chemical Vapor Deposition, Plasma Spraying, Electrostatic Spraying, Thermal Spraying, Physical Vapor Deposition, Sol-Gel Coating End User: Manufacturing Facilities, Engine Assemblers, Aircraft Manufacturers, Shipbuilders, Garment Producers, Food Packaging Plants |
| Companies Covered | The Chemours Company, DuPont, PPG Industries, Inc., Daikin Industries, Ltd., Whitford Corporation, Endura Coatings, Poeton Industries, Klüber Lubrication, Akzo Nobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Low Friction Coatings Market Strategic Shifts & Innovations
Material science advancements are converging with sustainability mandates to redefine product value. The market is shifting from coatings that solely reduce friction to multifunctional surfaces that offer enhanced durability, environmental compliance, and integrated performance monitoring, creating new competitive battlegrounds for formulators.
Smart coatings incorporating self-healing properties or embedded nano-sensors represent a frontier in material science. High-value sectors like aerospace and wind energy are the primary adopters, seeking to improve asset reliability. This innovation is digitizing surface analysis, enabling a shift from scheduled component replacement to predictive maintenance based on real-time wear data.
The European Union's ongoing evaluation of PFAS under the REACH framework is forcing a strategic pivot in chemical selection. This regulatory pressure directly impacts the formulation of coatings that have long relied on fluoropolymers for their performance characteristics. The food processing and medical device segments are most affected, accelerating R&D into compliant, high-performance silicone and ceramic-based alternatives.
A demand-side shift toward application-specific solutions is altering competitive dynamics. Original equipment manufacturers are increasingly bypassing standardized products in favor of co-development partnerships with formulators to create bespoke coatings. This trend is most pronounced in the high-specification electronics and automotive racing sectors, where off-the-shelf solutions fail to meet unique thermal and tribological requirements.
Global Low Friction Coatings Market Segmentation
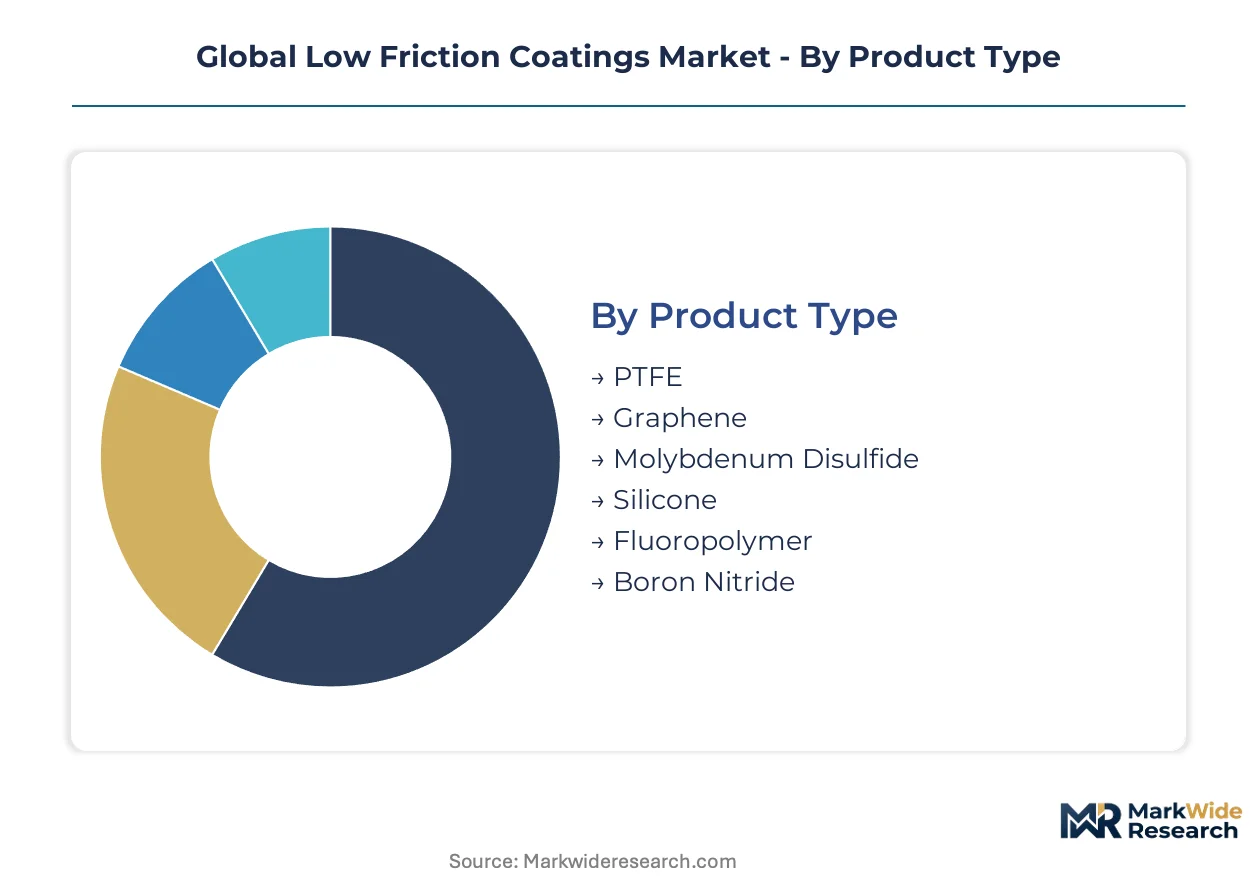
The global low friction coatings market is highly diversified, driven by the unique performance demands across various end-use sectors. Segmenting the market by product type, application, technology, and end user provides a granular understanding of the specific material science requirements and strategic opportunities within this specialized industry.
Product Type:
The market for low friction coatings is characterized by a spectrum of product types, ranging from established materials to rapidly developing innovations.
- PTFE:Polytetrafluoroethylene is a synthetic fluoropolymer known for its extremely low coefficient of friction, chemical inertness, and thermal stability. Widespread demand from the automotive components sector drives its application in engine parts, reducing wear and improving fuel efficiency.
- Graphene:This emerging 2D material offers exceptional strength, thermal conductivity, and ultra-low friction characteristics for high-performance applications. Demand from advanced aerospace assemblies is pushing its adoption for critical components in satellite mechanisms and aircraft engines.
- Molybdenum Disulfide:This solid lubricant is valued for its high-temperature stability and load-carrying capacity, particularly in heavy industrial machinery.
- Silicone:Silicone-based coatings provide good release properties and flexibility, finding use in medical devices and certain food processing equipment.
- Fluoropolymer:This broad category includes various fluorinated polymers beyond PTFE, offering diverse performance profiles for specific industrial and chemical resistance needs.
- Boron Nitride:Hexagonal boron nitride is a ceramic material offering high thermal conductivity and lubricity, suitable for high-temperature and electrical insulation applications.
PTFE retains volume leadership; Graphene holds the steepest expansion curve.
Application:
Demand for low friction coatings spans a diverse range of industrial and consumer applications, each presenting unique performance requirements and environmental challenges.
- Automotive Components:These coatings are crucial for reducing friction in engine parts, transmission systems, and braking components, enhancing fuel efficiency and extending vehicle lifespan. Stricter emissions regulations in the United States and Europe are accelerating demand for these solutions.
- Aerospace Assemblies:In aerospace, low friction coatings provide critical wear resistance and operational reliability for landing gear, control surfaces, and satellite mechanisms. High-specification requirements for durability and performance drive their use in both commercial and defense aircraft.
- Industrial Machinery:Coatings on gears, bearings, and hydraulic systems reduce energy consumption and maintenance costs in manufacturing facilities.
- Marine Equipment:Applications include propeller shafts and underwater mechanisms, where coatings protect against corrosion and reduce drag in harsh environments.
- Textile Machines:These coatings prevent fiber buildup and reduce friction on moving parts, improving efficiency and product quality in garment production.
- Food Processing:Non-stick and low friction surfaces on conveyors and processing equipment ensure hygiene and efficient material handling in food packaging plants.
Automotive Components drive significant volume, while Aerospace Assemblies set benchmarks for extreme performance.
Technology:
The selection of coating technology is heavily influenced by substrate compatibility, desired film thickness, and the scale of production required for various applications.
- Chemical Vapor Deposition:This process creates thin, highly uniform films with excellent adhesion and purity, ideal for semiconductor and precision engineering components. It is often employed for high-performance optical and electronic applications.
- Plasma Spraying:A versatile thermal spray technique, plasma spraying applies durable, dense coatings for wear and corrosion resistance on large industrial parts. This method is widely adopted for heavy machinery and structural components due to its robust nature.
- Electrostatic Spraying:This cost-effective method is used for applying uniform coatings to complex geometries, common in general industrial finishing.
- Thermal Spraying:A broad category encompassing processes like flame spray and arc spray, used for applying metallic and ceramic coatings to large surfaces.
- Physical Vapor Deposition:PVD techniques like sputtering and evaporation are used for very thin, hard, and wear-resistant coatings in tools and medical devices.
- Sol-Gel Coating:This low-temperature process allows for the creation of ceramic or glass-like coatings on temperature-sensitive substrates, including optical components.
Chemical Vapor Deposition offers unparalleled precision for critical components, while Plasma Spraying provides robust solutions for large-scale industrial needs.
End User:
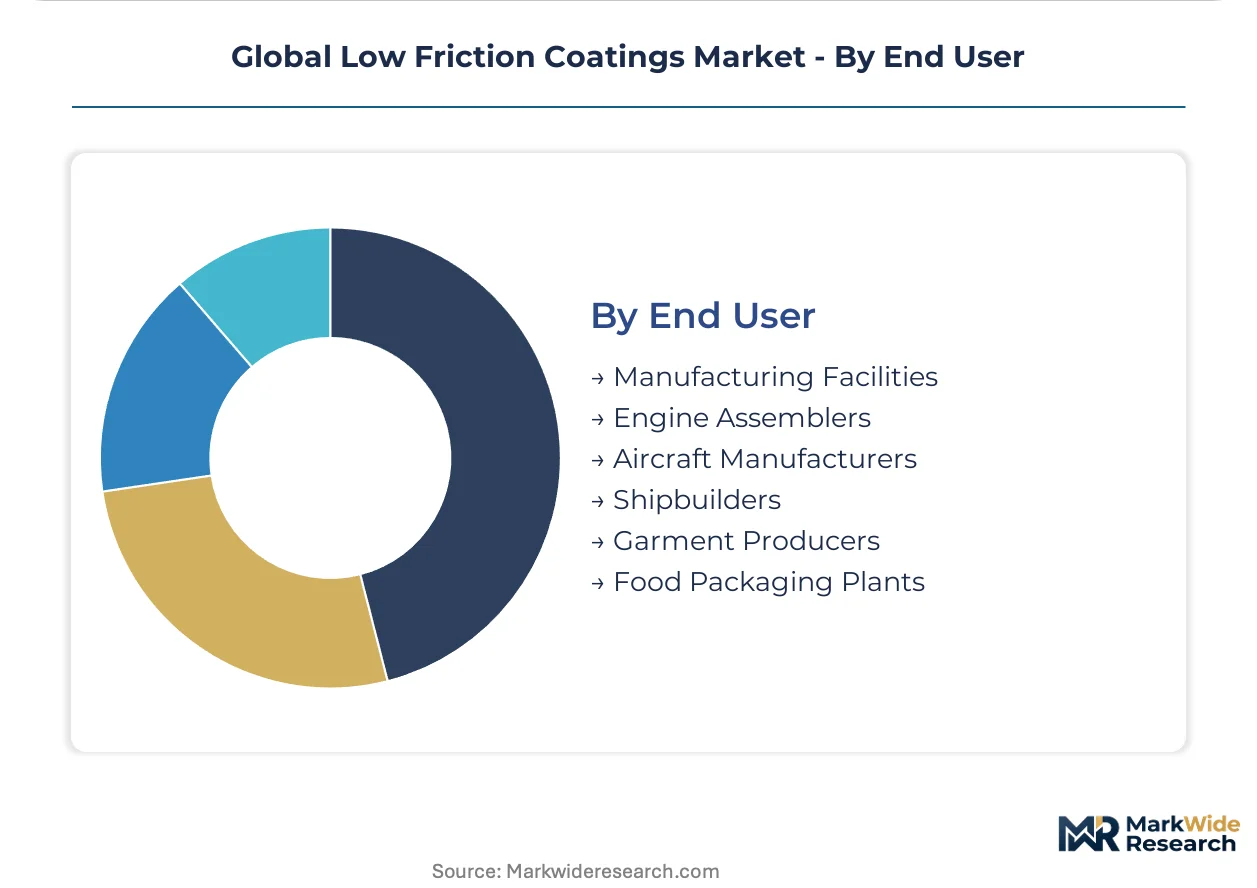
End-user segments exhibit distinct procurement patterns and specifications, reflecting their operational environments and regulatory obligations.
- Manufacturing Facilities:This segment includes a broad range of industrial operations that utilize low friction coatings on their production machinery and equipment. Demand centers on improving operational efficiency and extending the lifespan of critical components in high-volume production.
- Engine Assemblers:Focused on internal combustion and electric engines, these users require coatings that withstand extreme temperatures and pressures to enhance performance and fuel economy. Regulations on emissions drive innovation in this specialized area.
- Aircraft Manufacturers:This sector demands high-reliability coatings for components exposed to harsh environmental conditions and extreme mechanical stresses.
- Shipbuilders:Coatings are applied to marine engines, propellers, and hull components for corrosion protection and drag reduction in saltwater environments.
- Garment Producers:These facilities use coatings on textile machinery to reduce friction, prevent material buildup, and ensure smooth operation during fabric processing.
- Food Packaging Plants:Coatings on conveyors, cutting tools, and sealing equipment ensure non-stick properties, hygiene, and compliance with food safety standards.
Manufacturing Facilities represent a broad base for general industrial coatings, whereas Engine Assemblers demand highly specialized solutions for performance optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for low friction coatings vary significantly across global regions, driven by distinct industrial priorities and regulatory landscapes. Advanced economies prioritize high-performance solutions for aerospace, while emerging markets focus on volume applications for industrial machinery. This differentiation influences material selection and technological adoption.
United States
Automotive and aerospace sectors in the United States generate demand for low friction coatings, particularly for engine parts and critical aircraft components. EPA standards, including those for PFAS, influence material selection. Manufacturing hubs like Detroit and Wichita actively seek advanced coating solutions.
Germany
German industrial machinery and automotive manufacturing drive significant demand for durable low friction coatings, enhancing operational efficiency. The EU's REACH framework heavily dictates permissible chemical formulations. Industrial clusters in Bavaria and Baden-Württemberg integrate advanced coating technologies into precision engineering.
China
Industrial automation and China's expanding automotive sector create immense volume demand for low friction coatings for robotics and engine parts. Compliance with China's GB standards is essential for market access. Manufacturing hubs in the Yangtze River Delta adopt these coatings to improve equipment lifespan.
Japan
Precision manufacturing in Japan, particularly for niche electronics and advanced automotive components, requires highly specialized low friction coatings. METI guidelines for chemical substance management shape new coating formulations. Industrial centers in Kanto and Chubu invest in fluorochemical research.
India
India's expanding automotive production and general industrial manufacturing sectors fuel demand for cost-effective, durable low friction coatings. BIS standards for industrial products guide material selection. Major industrial corridors in Maharashtra and Tamil Nadu integrate these coatings to enhance machine efficiency.
Global Low Friction Coatings Market Key Industry Players
Capability concentration sits with one tier of specialized chemical formulators; scale advantage sits with another group of diversified industrial coatings providers. The market exhibits a tiered structure, from highly specialized fluoropolymer experts to broad-portfolio industrial suppliers. Strategic archetypes include high-performance niche players and volume-driven generalists. Companies pursue strategic partnerships for advanced material development and engage in portfolio diversification to meet evolving regulatory demands.
Within the high-specification, chemistry-intensive tier, The Chemours Company exemplifies deep expertise in fluoropolymer chemistry, serving high-specification aerospace clients. This player leverages its material science capabilities to address complex performance requirements. PPG Industries, Inc. occupies a position as a large-scale coatings provider, specializing in solutions for marine and general industrial equipment, leveraging its extensive manufacturing footprint and broad market access. Daikin Industries, Ltd. represents advanced fluorochemical research and development capabilities, anchoring niche electronics applications through its material science innovations and focus on compliant formulations.
| Leading Market Players |
|---|
| The Chemours Company |
| DuPont |
| PPG Industries, Inc. |
| Daikin Industries, Ltd. |
| Whitford Corporation |
| Endura Coatings |
| Poeton Industries |
| Klüber Lubrication |
| Akzo Nobel N.V. |
| Others |
Cost & Logistics Intelligence
The EU's ECHA, with its PFAS restrictions, is creating undercapacity for compliant fluoropolymer alternatives, driving up R&D costs for formulators and impacting their pricing strategies. This regulatory-induced scarcity directly influences the market's cost structure and product availability for key applications.
Pricing Analysis
Contract-based long-term offtake agreements dominate pricing for high-specification aerospace and medical coatings, while custom industrial applications often use project-based models. Price differentiation stems from achieving stringent performance characteristics like ultra-low friction coefficients and ensuring compliance with regulations such as REACH and EPA standards. Pricing pressure intensifies due to the significant R&D investment required for PFAS-free alternatives and persistent raw material volatility. Industrial machinery buyers demonstrate higher price sensitivity compared to the less elastic demand from aerospace and medical device sectors.
Supply Chain Analysis
Contract manufacturing for low friction coatings concentrates in specialized facilities within China for industrial volume, Germany for precision engineering, and Japan for advanced fluorochemical development. The supply chain relies heavily on key raw materials such as PTFE, molybdenum disulfide, fluoropolymer precursors, and emerging graphene. Regulatory restriction, particularly PFAS bans, represents a significant structural risk, alongside input cost volatility for specialized chemicals. Distribution flows primarily through direct sales channels to large Original Equipment Manufacturers and through specialized industrial distributors for smaller clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market reflects a shift towards buyer power, driven by Original Equipment Manufacturers increasingly demanding co-development partnerships for bespoke coatings, fragmenting traditional standardized product procurement.
For Market Incumbents:
Build intellectual property moats through advanced material science and regulatory compliance expertise. Incumbents must invest heavily in PFAS-free R&D to counter tightening fluorochemical regulations and emerging graphene solutions. Securing long-term raw material contracts for compliant alternatives mitigates supply chain risks. Certification investment, particularly for medical devices and aerospace applications, reinforces market position against new threats.
For New Entrants and Emerging Players:
Pursue underpenetrated opportunities in medical device coatings and renewable energy applications, such as wind turbine components. Niche electronics and specialized aerospace assemblies utilizing advanced materials like graphene represent penetrable segments. A strategic go-to-market angle involves forming co-development partnerships with Original Equipment Manufacturers to create application-specific, compliant coating solutions.
For Investors and Strategic Acquirers:
Capital-intensity ratios are inflecting upward across high-performance materials like graphene, signaling a shift in investment requirements. The market remains viable for formulators demonstrating robust R&D in compliant, high-performance materials over the long term. Acquisition targets should include specialized formulators with proprietary PFAS-free technologies or advanced material expertise in areas such as graphene or boron nitride. Adoption rates of non-fluorinated coatings in automotive and food processing sectors serve as a critical signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for PFAS-Free Production | Secures compliant supply for automotive and food processing sectors facing regulatory pressure. |
| Joint Venture for Graphene Synthesis | Accelerates development of next-generation, ultra-performance aerospace and electronics coatings. |
| Regulatory Compliance Certification Program | Unlocks market access in highly regulated medical device and specialized electronics applications. |
| Strategic Partnership with OEM | Drives co-development of application-specific, high-performance solutions meeting unique requirements. |
| R&D Investment in Silicone-Ceramic Hybrid Coatings | Addresses demand for compliant, durable alternatives in industrial machinery and food processing. |
Research Approach
Operator-level perspectives from R&D directors at coating manufacturers, procurement leads at automotive OEMs, aerospace engineers, and regulatory compliance specialists anchored the qualitative base. Secondary validation involved extensive review of EU REACH documentation, EPA regulatory reports, China's GB standards, and material science journals. This primary and secondary research informed both bottom-up analysis from product formulations and top-down validation from end-user demand trends.
Scenario-based modeling, combined with historical data extrapolation, formed the analytical framework across the analysis window. Segmentation dimensions modeled included product type (PTFE, Graphene), application (Automotive, Aerospace), technology (CVD, Plasma Spraying), end user (Manufacturing, Engine Assemblers), and regional regulatory impact. Compound annual growth rates were derived from an assessment of market growth drivers, restraints, and competitive intensity throughout the forecast period. Key forecast inputs included raw material price indices, global automotive production volumes, and aerospace R&D spending.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth or industrial production output would shift the trajectory. Forecasts reflect assumptions regarding regulatory stability and technological advancement. Sudden shifts in chemical regulations or unforeseen supply chain disruptions for critical raw materials pose significant risk factors. Quarterly review of regulatory updates and raw material pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Mexico Floor Coatings Market
Coatings
United States Automotive OEM Coatings Market
Coatings
Solvent Borne Coatings Market
Coatings
Radiation Curable Coatings Market
Coatings
Italy Protective Coatings Market
Coatings
Sol-Gel Coatings Market
Coatings
Global Optical Coating Market
Coatings
Global Intumescent Coatings Market
Coatings
Saudi Arabia Floor Coatings Market
Coatings
Europe Protective Coatings Market
Coatings
Global Radiation Cured Coatings Market
Coatings
Acrylic Protective Coating Market
Coatings
Automotive Conformal Coatings Market
Coatings
Food Grade Ceramic Coatings Market
Coatings
Global Fireproofing Coatings for Wood Market
Coatings
Water-Based Alkyd Coatings Market