
 Anti-Microbial Nano Coatings Market | 2026-2036
Anti-Microbial Nano Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Microbial Nano Coatings Market Analysis
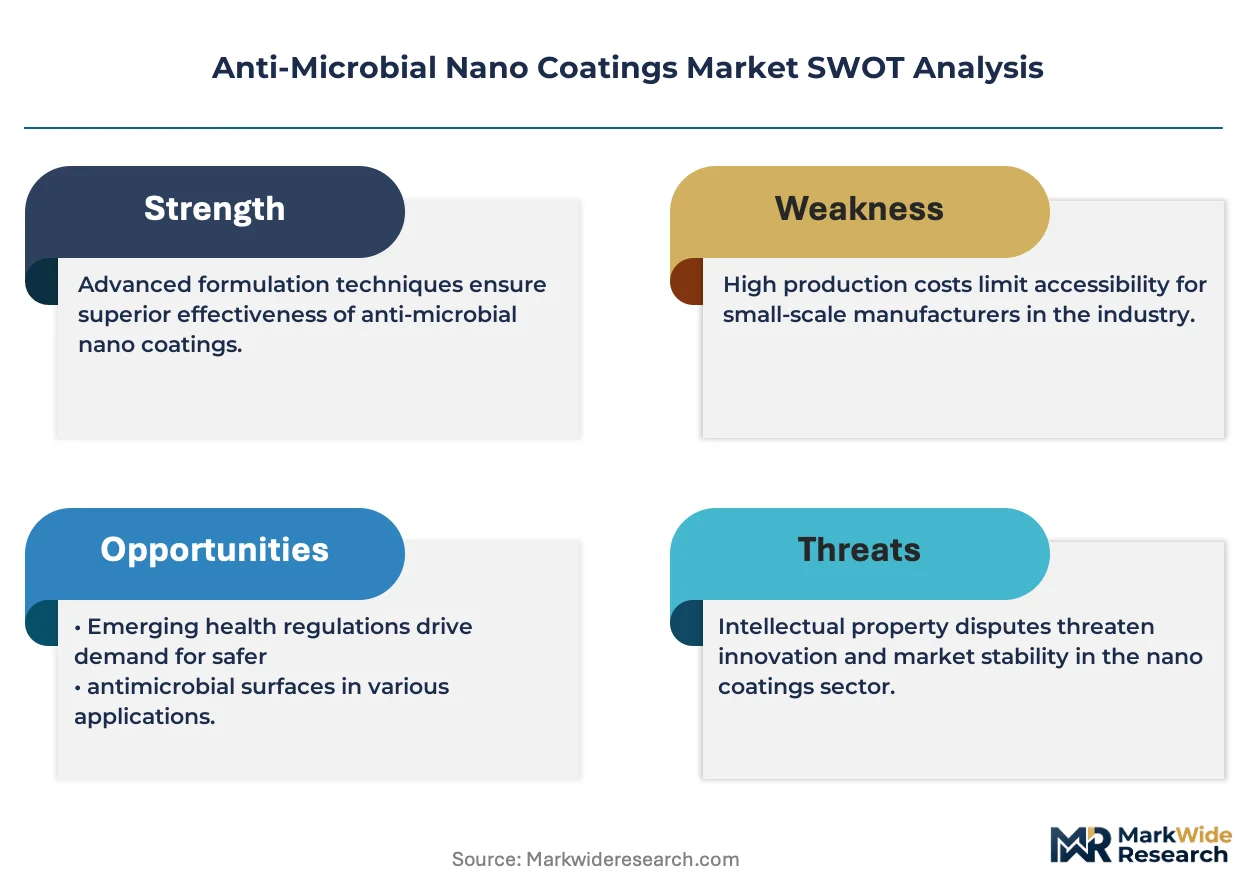
A shortage of trained nanomaterials chemists and surface engineering specialists is unwinding production timelines at multiple coating houses. 3M leverages its polymer science infrastructure to sustain captive supply of proprietary nano-dispersions across North American healthcare channels. Bio-Gate AG anchors European medical device certification pathways through its silver-ion platform, while Nano-Care Deutschland AG specializes in solvent-free aqueous formulations for textile integrators.
Anti-microbial nano coatings constitute ultra-thin films, typically 1–100 nanometers in thickness, engineered with biocidal metal ions or photocatalytic oxides that disrupt microbial cell membranes upon surface contact. Silver-dominant product types currently occupy the largest margin pools due to established FDA and EPA registration pathways, though titanium dioxide formulations are gaining traction in UV-activated electronics applications. Medical devices and food packaging represent the fastest-expanding application clusters, driven by post-pandemic hygiene protocols and extended shelf-life mandates from retail chains.
The EPA regulates antimicrobial claims under FIFRA in the United States, while the EU REACH framework and MDR govern substance authorization and medical device biocompatibility across Europe. These overlapping compliance layers force manufacturers to maintain parallel toxicology dossiers and migration testing protocols, raising barriers for formulation newcomers. Stakeholders must now decide whether to pursue multi-jurisdictional registration strategies or cede geographic segments to regionally entrenched competitors with existing regulatory dossiers.
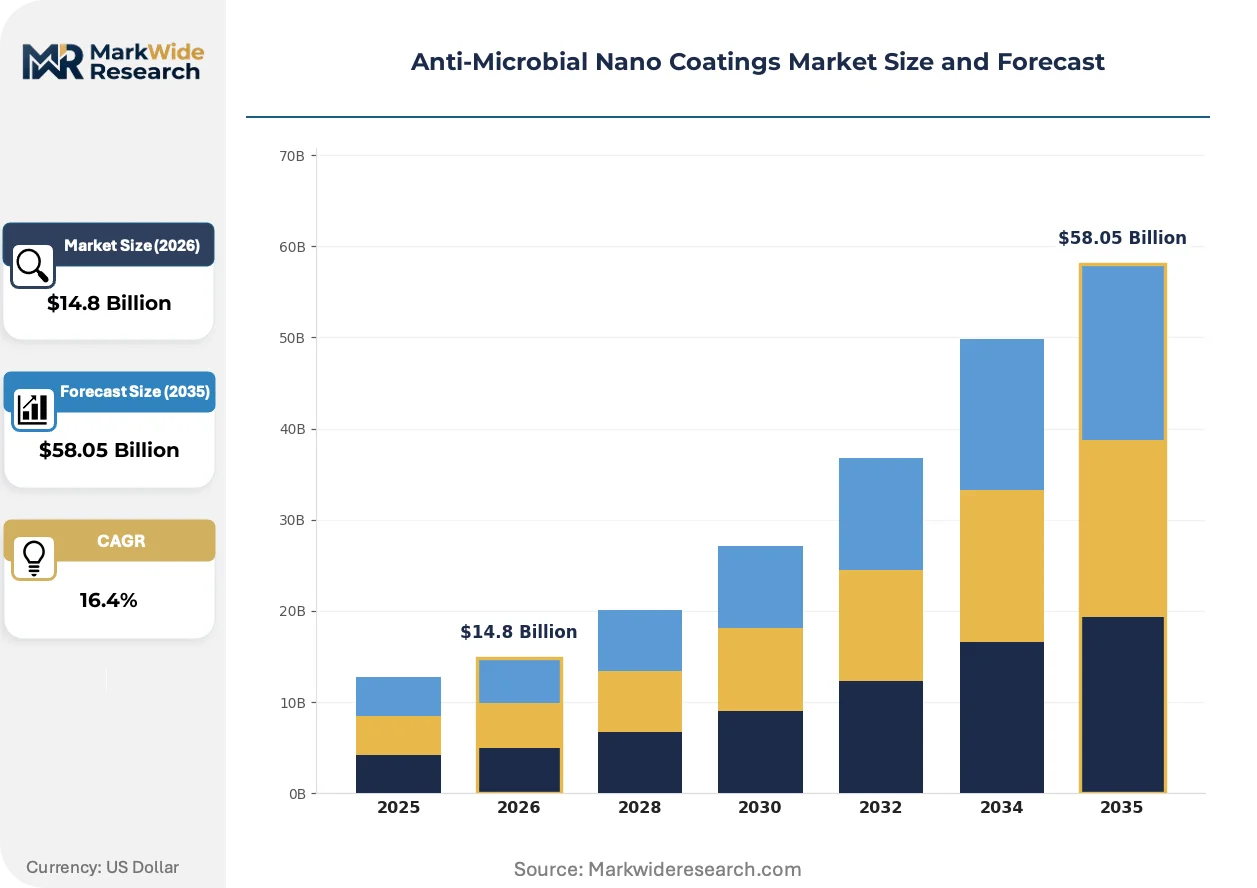
Market Dynamics
The EPA's tightening efficacy claim requirements under FIFRA are forcing coating houses to rebuild toxicology dossiers, compressing margins for multi-jurisdictional players while advantaging regionally entrenched competitors with existing registration pathways.
Growth Catalysts
- Post-pandemic hospital procurement:Healthcare facilities are expanding nano-coated medical device purchases to reduce hospital-acquired infections, pulling silver-ion formulations into surgical instrument contracts.
- REACH substance authorization:The EU's evolving biocidal products regulation is creating compliant supply scarcity that rewards early dossier filers with preferential medical device certification timelines.
- Photocatalytic oxide integration:Titanium dioxide coatings are penetrating UV-activated electronics manufacturing, enabling self-sanitizing touchscreens for retail and transit infrastructure.
Market Restraints
- Silver price volatility:Fluctuations in precious metal commodity markets compress formulation margins and destabilize long-term supply agreements for coating houses.
- German supply concentration:Precision manufacturing clusters in Bavaria and Baden-Württemberg create geographic single-point vulnerability for copper-based antimicrobial feedstock.
- Migration testing complexity:The EU MDR's biocompatibility protocols require parallel toxicology studies that extend product launch timelines by 18-24 months for cross-border sellers.
Strategic Opportunities
- India food packaging penetration:FSSAI shelf-life extension mandates for retail chains are opening solvent-free aqueous formulation demand previously served by conventional preservatives.
- Copper-zinc oxide convergence:Hybrid metal-ion platforms are unlocking textile integrator contracts that silver-dominant formulations cannot cost-effectively serve.
- US EPA fast-track pathways:The agency's emerging antimicrobial pesticide registration framework offers first-mover dossier advantages for novel photocatalytic chemistries.
Industry Challenges
- Surface engineering talent scarcity:Coating houses report 8-12 month hiring delays for nanomaterials chemists with thin-film deposition expertise, unwinding production timelines.
- Legacy equipment retrofit costs:Textile and packaging manufacturers face capex-intensive vacuum deposition line upgrades to accommodate nano-coating integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Microbial Nano Coatings Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $58.05 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silver, Copper, Zinc, Titanium Dioxide Application: Medical Devices, Textiles, Food Packaging, Electronics End User: Healthcare, Consumer Goods, Automotive, Construction Form: Aqueous, Solvent-Based, Powder, Spray |
| Companies Covered | Bio-Gate AG, 3M, Nano-Care Deutschland AG, Nanofilm Ltd, NANOSONO LTD, GBneuhaus GmbH, NANOPOOL GmbH, Toto USA, Blue Nano Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Microbial Nano Coatings Market Emerging Trajectories
Formulation chemistry is pivoting toward solvent-free aqueous systems as environmental compliance tightens, while regulatory fragmentation forces parallel certification strategies and buyer procurement consolidates around pre-qualified supplier pools.
Photocatalytic titanium dioxide coatings are miniaturizing active layer thickness below 50 nanometers while maintaining UV-activated biocidal efficacy. Electronics manufacturers in Japan and South Korea are adopting these ultra-thin films for smartphone and kiosk touchscreens. This thickness compression is miniaturizing material input costs and enabling price penetration into mass-market consumer devices previously reserved for premium medical applications.
The EU MDR's biocompatibility classification system is reclassifying antimicrobial-coated implants as higher-risk devices, triggering mandatory clinical evidence requirements. Coating suppliers must now sponsor migration studies and cytotoxicity testing that previously fell on device OEMs. German and Swiss medical device clusters are responding by vertically integrating formulation capabilities to control certification timelines and intellectual property.
Retail chain procurement departments are consolidating supplier qualification around pre-certified coating houses with existing EPA and REACH dossiers. Food packaging integrators in North America and Europe are bypassing regional distributors to contract directly with formulation specialists. This channel compression is most visible in Germany, where precision equipment manufacturers now require coating partners to hold Bio-Gate AG-equivalent silver-ion platform certifications as table stakes for contract consideration.
Anti-Microbial Nano Coatings Market Segmentation
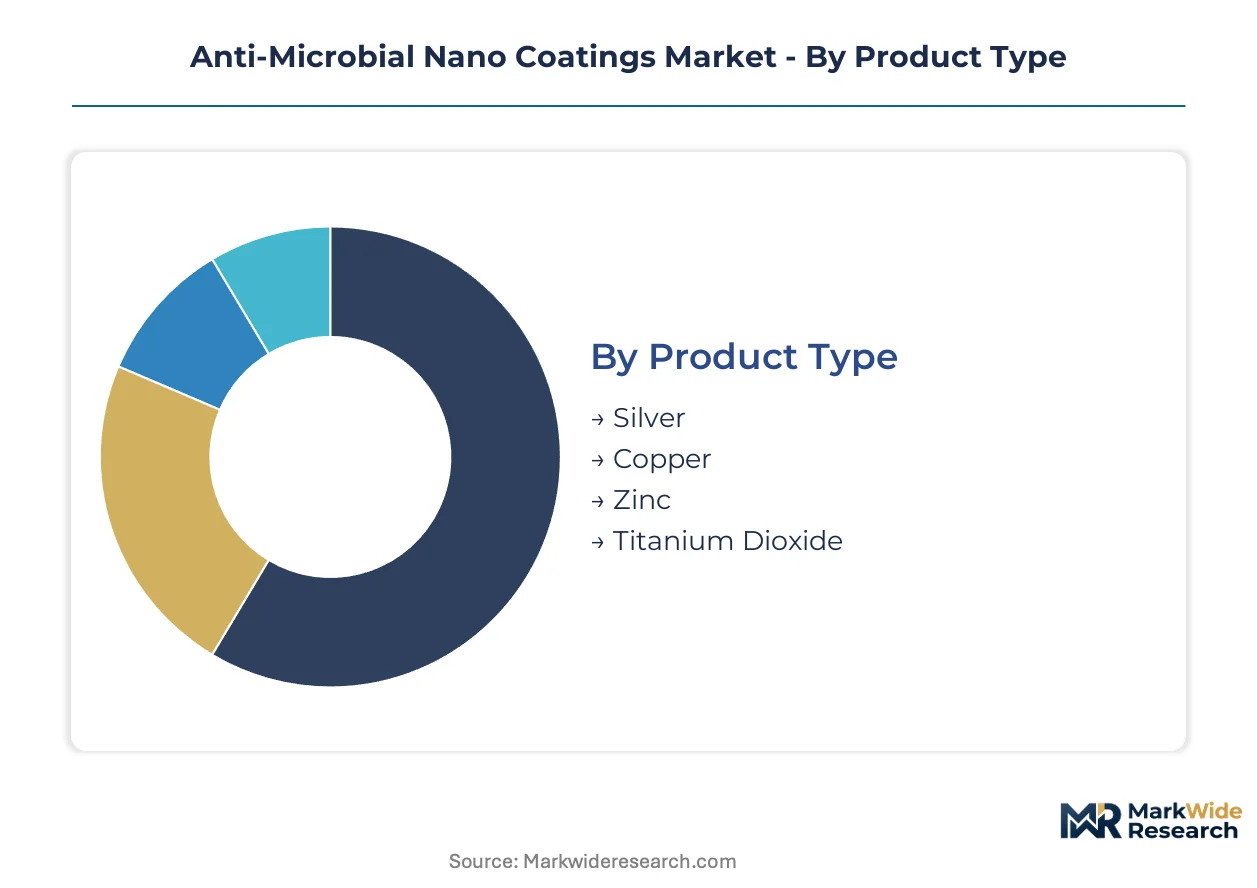
Anti-microbial nano coatings require precise segment targeting due to divergent regulatory pathways and application-specific performance thresholds. Formulation choices directly determine addressable end-use markets and compliance burden intensity.
Product Type:
EPA and EU REACH impose distinct registration requirements on metal-ion versus photocatalytic platforms, fragmenting competitive positioning across jurisdictions.
- Silver:Dominant ion-release chemistry leverages established FDA medical device and EPA FIFRA registration frameworks. Hospital procurement in Germany and the United States concentrates here due to proven cytotoxicity dossiers and surgical instrument OEM specifications.
- Titanium Dioxide:UV-activated photocatalytic oxides penetrate electronics manufacturing in Japan and South Korea, where METI efficiency standards and self-sanitizing touchscreen mandates from retail chains drive specification. Thickness compression below 50 nanometers enables cost penetration into mass-market consumer devices.
- Copper:Bavarian precision equipment manufacturers specify copper-ion formulations for food processing hygiene compliance.
- Zinc:Lower-cost alternative attracts textile integrators seeking cost-effective antimicrobial performance.
Established volume favors silver; emerging adoption favors titanium dioxide.
Application:
End-use concentration in healthcare and food processing creates margin tier differentiation based on biocompatibility certification depth.
- Medical Devices:EU MDR reclassification of antimicrobial-coated implants as higher-risk devices mandates clinical evidence and migration testing. Coating suppliers now sponsor cytotoxicity studies previously borne by device OEMs, compressing timelines for dossier-ready formulation houses.
- Food Packaging:FSSAI shelf-life extension mandates in India and retail chain consolidation in North America pull solvent-free aqueous formulations. Direct contracting between packaging integrators and certified coating specialists is compressing distribution channels.
- Textiles:Copper-zinc hybrid platforms unlock contracts that silver-dominant formulations cannot cost-effectively serve.
- Electronics:Japanese and South Korean smartphone manufacturers adopt ultra-thin photocatalytic films for kiosk and touchscreen applications.
Medical devices command premium certification pricing; food packaging offers steepest volume expansion trajectory.
End User:
Procurement sophistication varies sharply across customer types, with healthcare and automotive demanding traceable supply chain documentation.
- Healthcare:Hospital-acquired infection reduction protocols drive nano-coated surgical instrument procurement. Post-pandemic procurement departments require pre-qualified suppliers with existing EPA and REACH dossiers.
- Consumer Goods:Mass-market electronics and apparel manufacturers prioritize cost-competitive aqueous formulations with rapid line integration.
- Automotive:Interior surface hygiene specifications from German OEMs create qualified supplier list concentration.
- Construction:HVAC and high-touch surface applications remain nascent due to legacy equipment retrofit costs and extended payback periods.
Healthcare concentrates margin; consumer goods concentrates volume scale.
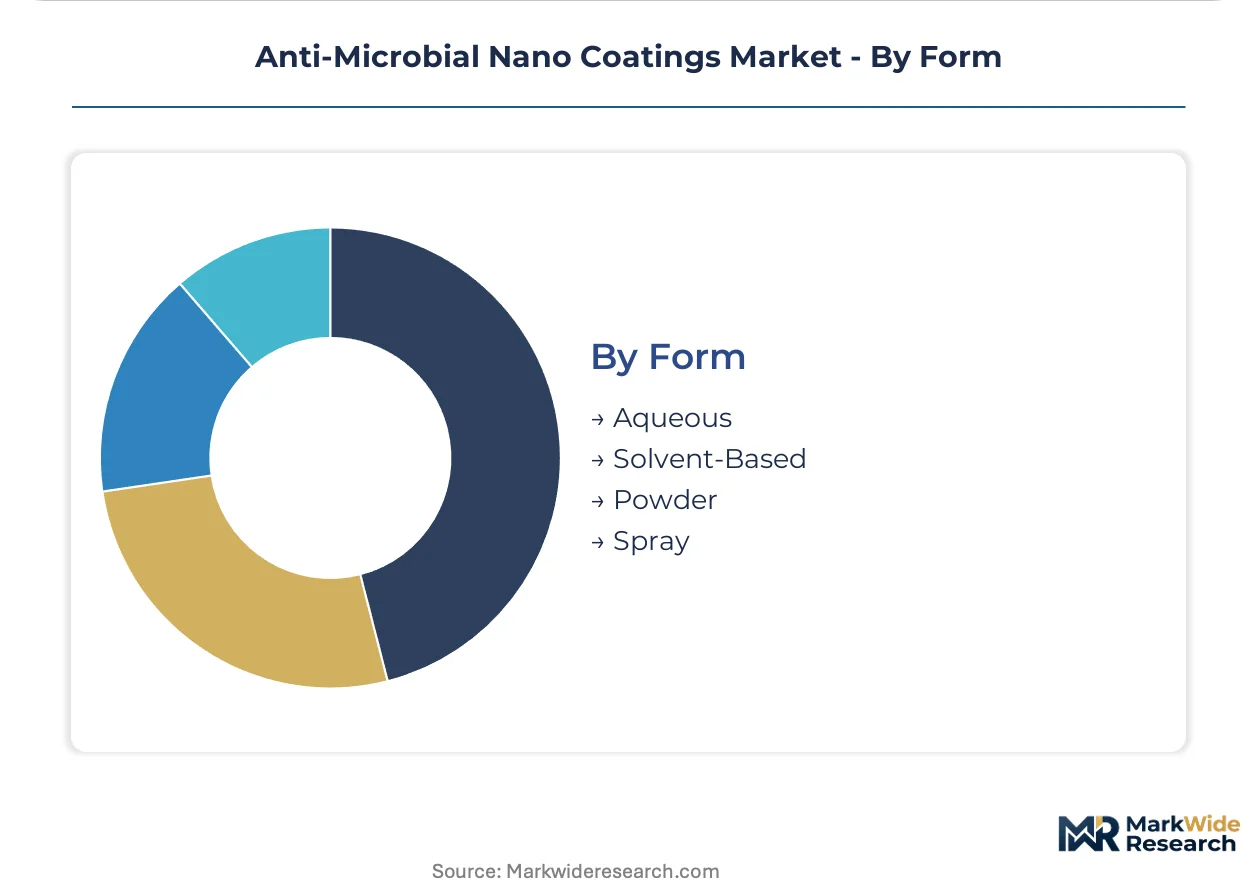
Form:
Environmental compliance tightening favors aqueous systems, while solvent-based legacy capacity persists in specialized electronics deposition.
- Aqueous:Solvent-free formulations dominate textile and food packaging integration due to EU REACH substance authorization advantages and FSSAI alignment in India. Nano-Care Deutschland AG specialization in this chemistry reflects regulatory tailwinds.
- Solvent-Based:Electronics manufacturing in Japan retains solvent-carrier systems for precision thickness control in vacuum deposition lines.
- Powder:Industrial equipment coatings utilize dry-form application for high-temperature curing environments.
- Spray:Field application and retrofit markets favor aerosol delivery for construction and maintenance use cases.
Aqueous systems gain regulatory preference; solvent-based retains performance-critical niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA's FIFRA registration framework anchors the United States as the dominant geography, while EU REACH substance authorization and MDR biocompatibility protocols reshape competitive positioning across Germany, Switzerland, and the broader European cluster.
United States
Hospital-acquired infection reduction protocols drive nano-coated surgical instrument procurement across the Cleveland Clinic and Mayo Clinic networks. EPA's tightening efficacy claim requirements under FIFRA force coating houses to rebuild toxicology dossiers, compressing margins for multi-jurisdictional players. Boston's medical device corridor concentrates demand for silver-ion formulations with existing FDA registration pathways.
Germany
Precision manufacturing clusters in Bavaria and Baden-Württemberg create concentrated pull for copper and silver-based formulations in food processing equipment. EU MDR reclassification of antimicrobial-coated implants as higher-risk devices mandates clinical evidence and migration testing previously borne by device OEMs. Stuttgart's automotive interior suppliers now require coating partners to hold Bio-Gate AG-equivalent silver-ion platform certifications.
Japan
Smartphone and kiosk touchscreen manufacturers in Tokyo and Osaka adopt ultra-thin photocatalytic titanium dioxide films for self-sanitizing consumer electronics. METI efficiency standards and retail chain mandates drive specification below 50 nanometer thickness compression. Kyushu's electronics manufacturing base integrates these UV-activated coatings into mass-market device production lines.
India
FSSAI shelf-life extension mandates for retail chains open solvent-free aqueous formulation demand previously served by conventional preservatives. Mumbai and Delhi-NCR packaging integrators bypass regional distributors to contract directly with certified coating specialists. Gujarat's textile belt attracts copper-zinc hybrid platforms for cost-effective antimicrobial performance in apparel exports.
South Korea
Electronics manufacturers in Seoul and Busan deploy photocatalytic oxide coatings for UV-activated touchscreen applications in transit infrastructure and retail kiosks. MFDS biocompatibility protocols align with EU MDR standards, enabling cross-certified medical device coating exports. Daegu-Gyeongbuk's display panel cluster tests sub-50 nanometer titanium dioxide integration for next-generation consumer devices.
Anti-Microbial Nano Coatings Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where formulation specialists with regulatory dossiers command premium positioning against aqueous-system volume producers. The vendor base spans German precision coating houses, North American polymer science conglomerates, and Asian electronics-focused deposition specialists. Three archetypes dominate: multi-jurisdictional registrants with parallel EPA-REACH dossiers, captive-supply polymer conglomerates, and solvent-free aqueous formulation specialists. Competitive moves concentrate on geographic expansion through distributor acquisition and technology licensing for photocatalytic oxide platforms.
Within the multi-jurisdictional registrant tier, Bio-Gate AG and 3M occupy positions anchored by existing regulatory pathways, while Nano-Care Deutschland AG exemplifies the aqueous formulation specialist archetype with solvent-free chemistry alignment. These three entities represent distinct competitive vectors: silver-ion platform certification depth, captive polymer science infrastructure, and environmental compliance-focused textile integration respectively. German GmbH and AG structures dominate the European cluster, reflecting precision manufacturing heritage and medical device certification concentration.
| Leading Market Players |
|---|
| Bio-Gate AG |
| 3M |
| Nano-Care Deutschland AG |
| Nanofilm Ltd |
| NANOSONO LTD |
| GBneuhaus GmbH |
| NANOPOOL GmbH |
| Toto USA |
| Blue Nano Inc. |
| Others |
Supply Flow & Price Mechanics
Silver-ion substitution by copper-zinc hybrid platforms redraws raw material sourcing maps from Bavarian precision clusters toward Indian textile belts, simultaneously compressing formulation premiums in cost-sensitive apparel segments while elevating margin pools in EU MDR-certified medical device tiers. This feedstock migration channels procurement power toward coating houses with multi-metal ion expertise.
Pricing Analysis
German medical device corridors command 40-60% premiums over Indian textile integrators for equivalent antimicrobial efficacy, reflecting EU MDR certification depth and migration testing documentation. Pricing stratifies across certified-premium, REACH-compliant-standard, and economy-aqueous tiers, with silver-dominant formulations anchored by FDA registration pathways. Cost compression in textile-grade copper-zinc platforms intensifies as Gujarat apparel exporters consolidate supplier lists. Hospital procurement committees in Cleveland Clinic and Mayo Clinic networks exhibit lowest price sensitivity, prioritizing cytotoxicity dossier completeness over per-unit cost.
Supply Chain Analysis
Bavarian and Baden-Württemberg precision manufacturing clusters constitute a chokepoint for copper-based antimicrobial feedstock, concentrating European medical device and food processing equipment supply. Formulation chemistry draws from South Korean electronics-grade titanium dioxide, Indian textile-grade zinc oxide, and German pharmaceutical-grade silver nitrate. Single-source vulnerability in EU REACH-authorized biocidal substance suppliers exposes coating houses to 18-24 month requalification timelines. Distribution runs through direct contracting between certified formulation specialists and packaging integrators, bypassing regional distributors in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anti-microbial nano coatings occupy an early-cycle expansion phase where post-pandemic hospital procurement protocols and FSSAI shelf-life mandates in India accelerate penetration beyond legacy preservative chemistries.
For Market Incumbents: Shield silver-ion platform margins by deepening captive supply of proprietary nano-dispersions through polymer science infrastructure investments in North American healthcare channels. Accelerate EU MDR dossier refresh cycles ahead of biocompatibility reclassification deadlines to forestall emerging aqueous-formulation specialists from capturing textile integrator contracts. For New Entrants and Emerging Players: Lead with solvent-free aqueous formulations targeting Indian food packaging integrators under FSSAI shelf-life extension mandates, where incumbent silver-ion platforms carry prohibitive cost structures. Establish direct contracting relationships with Mumbai and Delhi-NCR packaging houses, bypassing distributor layers that entrenched competitors control. For Investors and Strategic Acquirers: The market sits at a pre-consolidation phase that favors multi-jurisdictional registrants with parallel EPA-REACH dossiers over single-region aqueous volume producers. Acquisition targets should demonstrate existing Bio-Gate AG-equivalent certification depth or Nano-Care Deutschland AG-style environmental compliance alignment. Monitor EPA fast-track pathway announcements for novel photocatalytic chemistries as inflection signals for technology-licensing valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Dossier Expansion | Early filing secures preferential medical device certification timelines under EU MDR reclassification. |
| Backward Integration into Nano-Dispersion Production | Captive supply of proprietary silver-ion platforms insulates 3M from precious metal commodity volatility. |
| Solvent-Free Aqueous Formulation Scale-Up | Nano-Care Deutschland AG specialization aligns with FSSAI mandates and EU substance authorization tailwinds. |
| Photocatalytic Oxide Technology Licensing | Sub-50 nanometer titanium dioxide patents unlock Japanese electronics manufacturing adoption curves. |
| Direct Hospital System Partnership | Cleveland Clinic and Mayo Clinic procurement consolidation rewards pre-qualified EPA-REACH dossier holders. |
Methodological Framework
Desk research of EPA FIFRA registration databases, EU ECHA biocidal product filings, and FDA medical device premarket notifications preceded structured interviews with coating house R&D directors, hospital procurement managers, textile integrator technical leads, and regulatory affairs specialists at German medical device clusters. Secondary validation drew from customs trade data on silver nitrate and titanium dioxide imports, SEC 10-K disclosures from polymer science conglomerates, and METI efficiency standard publications. Bottom-up volume estimates from application-specific coating consumption triangulated against top-down market sizing from formulation specialist revenue aggregates.
Variance decomposition across product type, application, end user, and form dimensions anchored the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate distributions weighted by regulatory pathway maturity and adoption curve positioning. Industry-specific forecast inputs incorporated silver price volatility indices, EU MDR implementation timelines, and FSSAI enforcement intensity in Indian retail chain procurement.
Underlying assumptions cover sustained EPA efficacy claim tightening, REACH substance authorization continuity, and hospital-acquired infection protocol permanence, with deviation risk concentrated in precious metal commodity shocks and photocatalytic oxide regulatory reclassification. Practitioners should keep alternative scenarios live as MFDS-EU MDR alignment evolution and India PLI scheme extensions for specialty chemicals reshape geographic manufacturing footprints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Waterborne Automobile Coating Market
Coatings
Acrylic Protective Coating Market
Coatings
US Industrial Coatings Market
Coatings
Europe Protective Coatings Market
Coatings
Wood Sealer Market
Coatings
US Protective Coatings Market
Coatings
Thermal Insulation Coating Market
Coatings
Russia Architectural Coatings Market
Coatings
Technical Coil Coatings Market
Coatings
Transparent Conductive Coatings Market
Coatings
Global PET Film Coated Steel Coil Market
Coatings
North America Powder Coatings Market
Coatings
Physical Vapor Deposition (PVD) Coatings Market
Coatings
Global Industrial Floor Coatings Market
Coatings
Extrusion Coating Market
Coatings
Epoxy Coating Market