
 Process Pipe Coating Market | 2026-2036
Process Pipe Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Process Pipe Coating Market Analysis
Gulf Coast petrochemical producers is shifting toward higher-specification fusion-bonded epoxy capacity to serve sour-gas transmission lines. PPG Industries sustains technology leadership through integrated resin-to-coating R&D pipelines. Shawcor Ltd. dominates subsea and offshore project specifications with specialized application equipment networks. Akzo Nobel N.V. differentiates via marine-grade corrosion chemistry adapted for process pipe environments.
Process pipe coating comprises thermoset polymer layers—typically epoxy, polyurethane, or polyethylene—applied at 250–500 micron dry-film thickness to carbon steel substrates via spray, brush, or dip methods, creating dielectric barriers against electrochemical corrosion in pressurized fluid transport systems. Epoxy formulations anchor the current revenue base due to proven adhesion on prepared steel and broad chemical resistance, while polyurethane coatings represent the fastest-expanding category as operators seek flexible, abrasion-resistant layers for dynamic piping configurations. Application segmentation shows oil and gas commanding the deepest specification requirements, though water supply infrastructure is emerging as a volume growth vector as municipal replacement cycles accelerate.
EPA NESHAP standards constrain solvent-borne coating chemistries in US facilities, while REACH registration requirements in Europe force reformulation of legacy epoxy hardener systems. ISO 21809 governs fusion-bonded epoxy application for oil and gas pipelines, creating certification barriers for uncertified applicators. Stakeholders must monitor evolving PFAS restrictions and carbon-border adjustment mechanisms as these frameworks threaten to disqualify incumbent coating technologies from public infrastructure procurement.
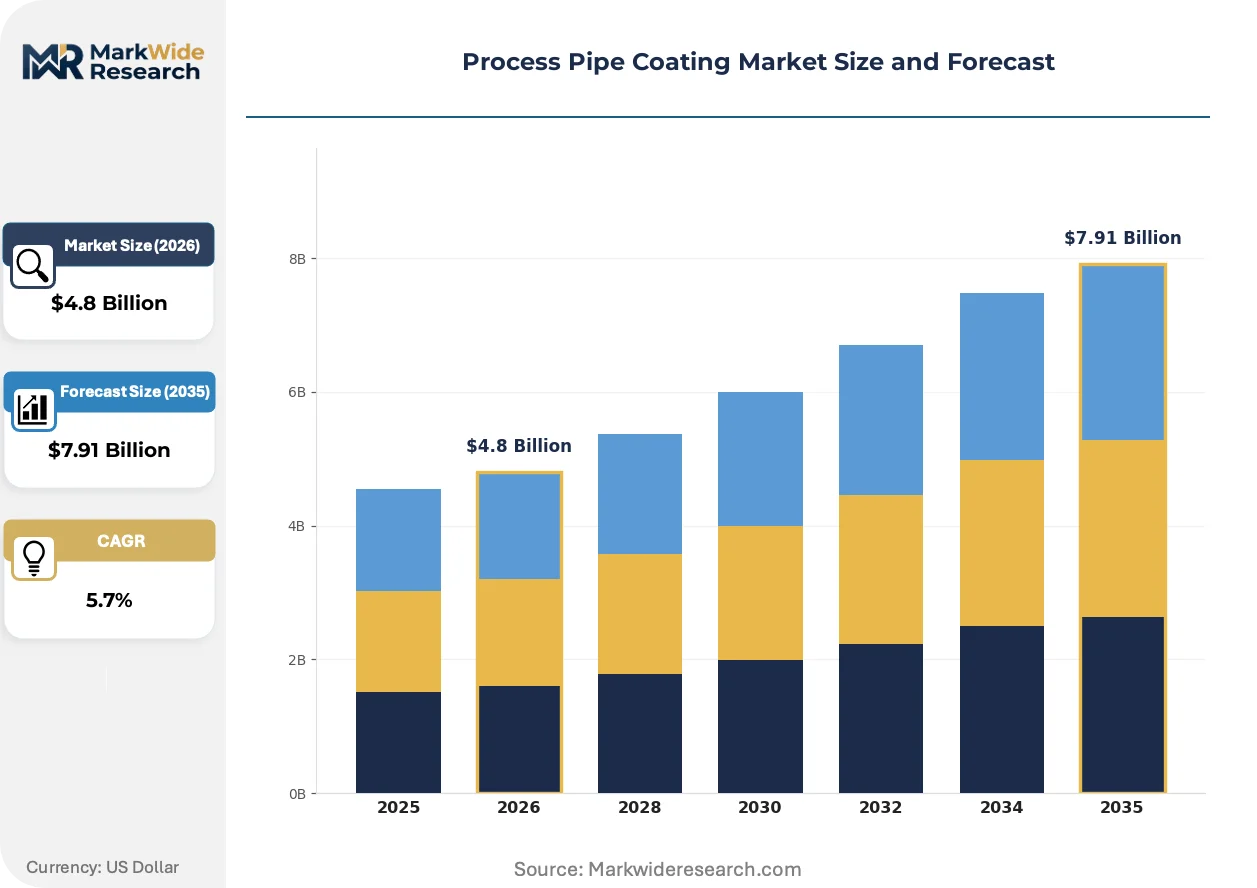
Market Dynamics
Offshore sour-gas development is compressing specification cycles as operators demand fusion-bonded epoxy systems rated for higher temperature and hydrogen sulfide exposure, forcing coating houses to accelerate qualification timelines.
Growth Catalysts
- EPA NESHAP compliance deadlines:US refineries face accelerated coating replacement schedules to meet volatile organic compound emission limits, creating pull-through demand for low-solvent epoxy formulations.
- Subsea tieback proliferation:Deepwater projects in the Gulf of Mexico and West Africa require specialized three-layer polyethylene systems with cathodic disbondment resistance.
- Hydrogen infrastructure pilot programs:European energy utilities are testing modified epoxy chemistries for high-pressure hydrogen transport, opening adjacent specification categories.
Market Restraints
- Epoxy resin supply concentration:Bisphenol-A and amine hardener production clusters in China and Germany expose coating formulators to feedstock volatility and logistics disruption.
- REACH authorization timelines:ECHA's substance evaluation procedures for legacy hardener components extend reformulation cycles to 18-24 months, freezing product development pipelines.
- Thermoplastic tape substitution:Polypropylene and PVC wrap systems are capturing low-pressure water transmission segments where excavation access permits mechanical application.
Strategic Opportunities
- India pipeline expansion:The Petroleum and Natural Gas Regulatory Board's city gas distribution mandates are creating demand for corrosion-resistant coatings on previously unprotected distribution networks.
- CCUS injection lines:Carbon capture projects require chemically resistant internal linings for supercritical CO2 transport, a specification category with limited qualified suppliers.
- Digital application monitoring:Real-time dry-film thickness verification via integrated sensor systems is enabling outcome-based contracting models with asset owners.
Industry Challenges
- Qualified applicator scarcity:ISO 21809 certification requirements for fusion-bonded epoxy installation exceed current training pipeline capacity, constraining project execution speed.
- Legacy coating compatibility:Patch repairs on 1980s-era coal-tar enamel systems require surface preparation protocols that damage adjacent intact sections, complicating maintenance scope.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Process Pipe Coating Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Epoxy, Polyurethane, FBE, Polyethylene Application: Oil & Gas, Water Supply, Chemical Processing, Power Generation End User: Utilities, Manufacturers, Contractors, Industrial Facilities Installation Method: Spray Application, Brush Application, Manual Coating, Dip Coating |
| Companies Covered | LyondellBasell Industries Holdings B.V., PPG Industries, Inc., Shawcor Ltd., The Sherwin-Williams Company, Akzo Nobel N.V., The Bayou Companies, L.B. Foster Company, WASCO Energy Group of Companies, Arkema S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Process Pipe Coating Market Emerging Trajectories
Coating specification is pivoting from commodity procurement to performance-engineered systems, with asset owners embedding lifecycle cost models into tender evaluation and demanding predictive corrosion monitoring integration.
Dual-cure epoxy-urethane hybrid formulations are rewriting field application economics by combining ambient-cure convenience with fusion-bonded epoxy durability. Offshore contractors in the North Sea and Gulf of Mexico are adopting these systems for tie-in spool fabrication where shop heating capacity is constrained. The technology is compressing the competitive gap between established applicators with fixed-plant assets and mobile service providers.
EU Green Deal carbon-border adjustment mechanisms are tightening embodied-carbon disclosure requirements for imported steel and coating materials. European pipeline operators now require Environmental Product Declarations for coating systems, favoring suppliers with renewable energy-integrated manufacturing. This policy shift is disadvantaging imports from coal-dependent production regions and accelerating regional supply chain reconfiguration.
Asset owners are consolidating procurement around integrated coating-inspection-maintenance contracts, displacing transactional material purchasing. Major oil and gas operators in Norway and the United Kingdom are bundling decade-long corrosion management responsibility with coating application, transferring performance risk to service providers. This contracting evolution is most advanced in offshore pipeline segments where inspection access costs dominate lifecycle economics.
Process Pipe Coating Market Segmentation
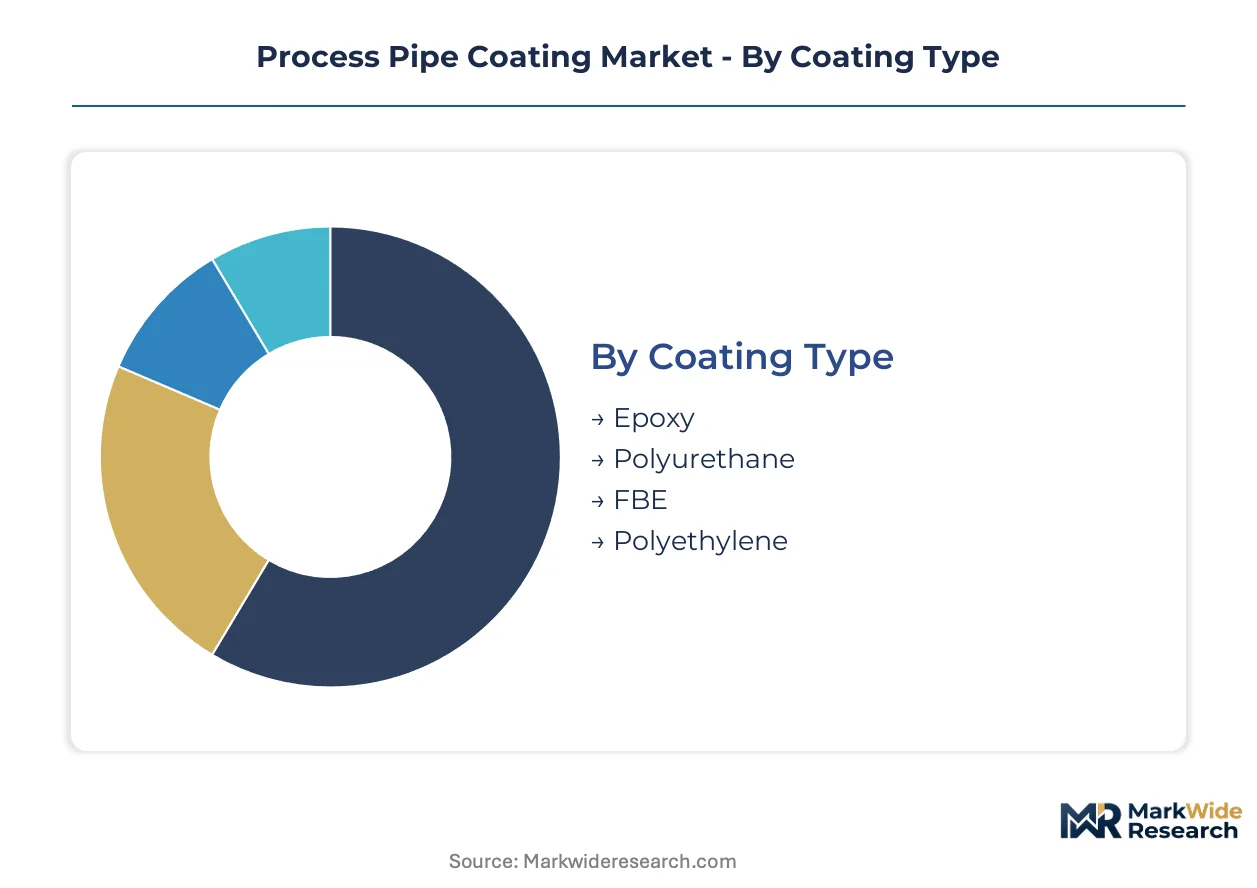
Coating selection in process pipe applications hinges on substrate compatibility, service environment chemistry, and installation constraints. Specification engineers weigh lifecycle corrosion resistance against application throughput and field repair accessibility when segmenting procurement.
Coating Type:
Buyers in this category differentiate by chemical resistance requirements and cure protocol flexibility.
- Epoxy:Thermoset polymer systems based on bisphenol-A resins and amine hardeners deliver dielectric barrier protection at 250–500 micron dry-film thickness. Demand concentrates in United States Gulf Coast refineries where EPA NESHAP compliance deadlines are accelerating low-solvent formulation procurement.
- Polyurethane:Aliphatic and aromatic isocyanate-cured elastomers provide abrasion resistance and flexibility for dynamic piping configurations. Norwegian North Sea offshore contractors specify these systems for tie-in spools where thermal cycling and mechanical impact resistance govern selection.
- FBE:Fusion-bonded epoxy powders require heated substrate application but deliver superior cathodic disbondment resistance for buried transmission lines.
- Polyethylene:Three-layer systems with adhesive tie-coats dominate subsea installations demanding long-term seawater immersion protection.
Volume sits with epoxy; growth tilts toward polyurethane.
Application:
End-use severity determines specification tier and certification burden.
- Oil & Gas:Sour-gas transmission and subsea gathering systems impose the deepest qualification requirements. Gulf of Mexico deepwater projects are compressing specification cycles for hydrogen sulfide-rated fusion-bonded epoxy systems.
- Water Supply:Municipal distribution networks and potable water transmission drive volume procurement with lower certification barriers. India's Petroleum and Natural Gas Regulatory Board city gas distribution mandates are expanding corrosion protection into previously uncoated networks.
- Chemical Processing:Acid, caustic, and solvent exposure necessitates specialty linings with broad chemical resistance spectra.
- Power Generation:Cooling water circuits and flue gas desulfurization lines require coatings rated for thermal shock and pH cycling.
Revenue concentrates in oil and gas; volume expansion is steepest in water supply.
End User:
Procurement sophistication varies sharply by asset ownership structure and in-house technical capacity.
- Utilities:Regulated water and energy transmission operators with standardized material specifications and multi-year maintenance contracts.
- Manufacturers:Original equipment fabricators coating pipe spools prior to shipment, requiring shop-controlled application environments and ISO 21809 certification.
- Contractors:Field service providers executing turnarounds and tie-ins where mobile equipment and ambient cure protocols dominate.
- Industrial Facilities:Owner-operators with captive maintenance crews and legacy coating compatibility challenges.
Specification authority rests with utilities; execution speed depends on contractor capacity.
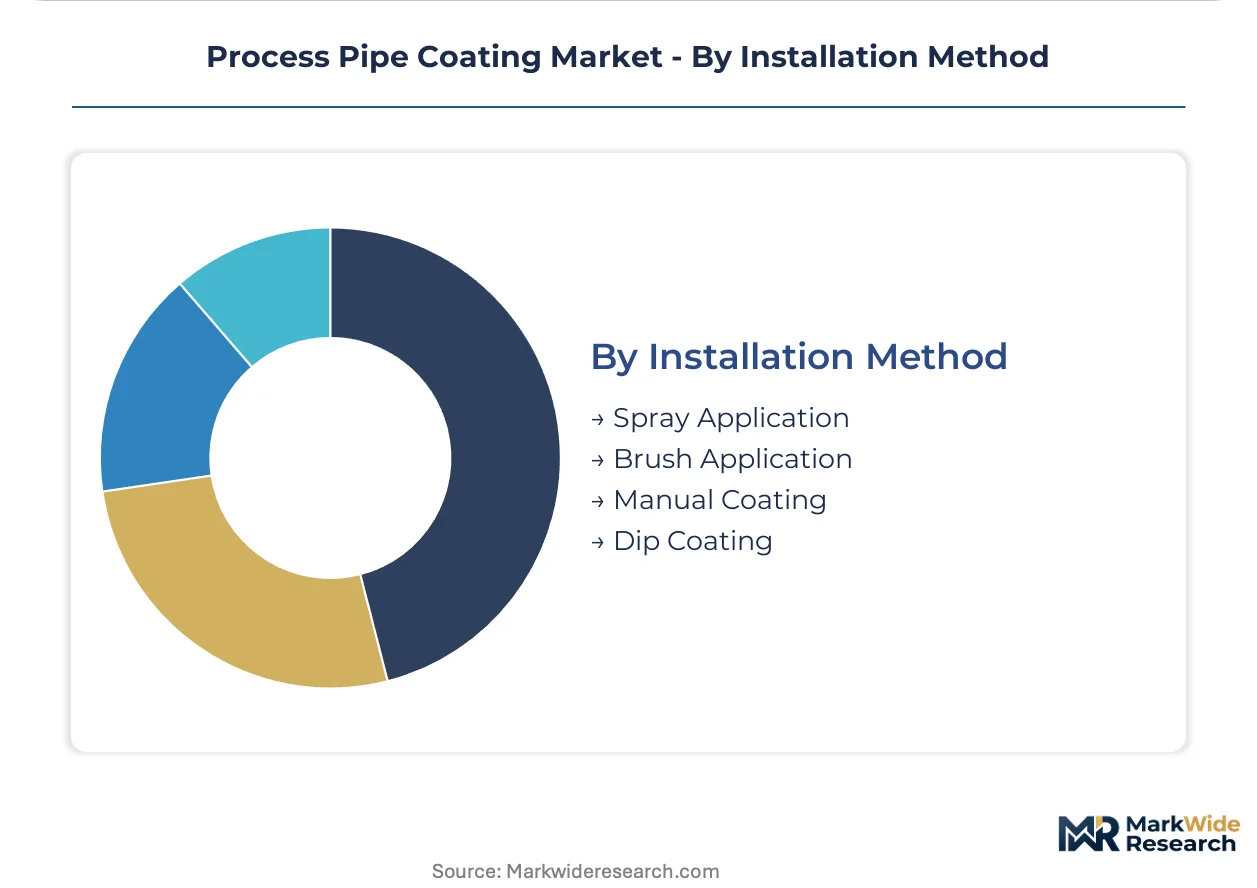
Installation Method:
Equipment capital intensity and labor skill requirements segment applicator capabilities.
- Spray Application:Airless and plural-component spray systems deliver high throughput for large-diameter pipe in shop environments. United States Gulf Coast petrochemical infrastructure renewal projects are driving specification upgrades for automated spray quality assurance.
- Brush Application:Manual stripe coating and touch-up work where access constraints preclude mechanized methods. European REACH authorization timelines for legacy hardener components are extending reformulation cycles and freezing brush-grade product pipelines.
- Manual Coating:Hand-applied trowel and roller methods for complex geometries and repair patches.
- Dip Coating:Immersion systems for small-diameter fittings and standardized components requiring uniform film thickness.
Throughput favors spray; flexibility belongs to brush.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bisphenol-A and amine hardener production clusters in China and Germany supply coating formulators worldwide. Feedstock proximity shapes regional manufacturing footprints. Demand concentrates where sour-gas transmission and subsea infrastructure multiply.
United States
EPA NESHAP compliance deadlines are accelerating coating replacement schedules across Gulf Coast refineries. Low-solvent epoxy formulations dominate procurement as operators face volatile organic compound emission limits. Houston anchors the deepest specification requirements for fusion-bonded epoxy systems serving sour-gas transmission lines.
Germany
REACH authorization timelines for legacy hardener components extend reformulation cycles to 18-24 months. ECHA substance evaluation procedures freeze product development pipelines for brush-grade epoxies. The Ruhr industrial corridor concentrates coating application capacity serving chemical processing infrastructure.
China
Domestic epoxy resin production capacity expansion is reducing import dependence for bisphenol-A feedstocks. The country's national chemical safety regulator is tightening volatile organic compound thresholds for coating manufacturing facilities. Yangtze River Delta petrochemical clusters are integrating captive coating production for pipeline exports.
Norway
North Sea offshore contractors specify polyurethane systems for tie-in spools where thermal cycling resistance governs selection. EU Green Deal carbon-border adjustment mechanisms are tightening embodied-carbon disclosure requirements for imported coating materials. Stavanger anchors integrated coating-inspection-maintenance contract consolidation among major oil and gas operators.
India
Petroleum and Natural Gas Regulatory Board city gas distribution mandates are expanding corrosion protection into previously uncoated networks. BIS standards alignment with ISO 21809 is creating certification barriers for uncertified applicators. Gujarat pipeline fabrication yards are scaling fusion-bonded epoxy capacity to serve Middle East export contracts.
Process Pipe Coating Market Vendor Landscape
Global majors compete with regional champions across specification tiers and application method capabilities. The vendor base stratifies between integrated resin-to-coating R&D pipelines, specialized subsea application equipment networks, and marine-grade corrosion chemistry adapters. Three archetypes dominate: petrochemical-integrated formulators, offshore project specialists, and diversified industrial coatings houses. Capacity expansion and strategic partnerships constitute the dominant competitive moves as qualification timelines compress.
Among diversified industrial coatings houses, PPG Industries and The Sherwin-Williams Company exemplify scale-driven positions spanning multiple specification tiers. Shawcor Ltd. occupies a specialist position within offshore and subsea project archetypes. Akzo Nobel N.V. anchors the marine-grade adaptation segment. These three named companies represent distinct capability configurations rather than direct segment overlap.
| Leading Market Players |
|---|
| LyondellBasell Industries Holdings B.V. |
| PPG Industries, Inc. |
| Shawcor Ltd. |
| The Sherwin-Williams Company |
| Akzo Nobel N.V. |
| The Bayou Companies |
| L.B. Foster Company |
| WASCO Energy Group of Companies |
| Arkema S.A. |
| Others |
Supply Flow & Price Mechanics
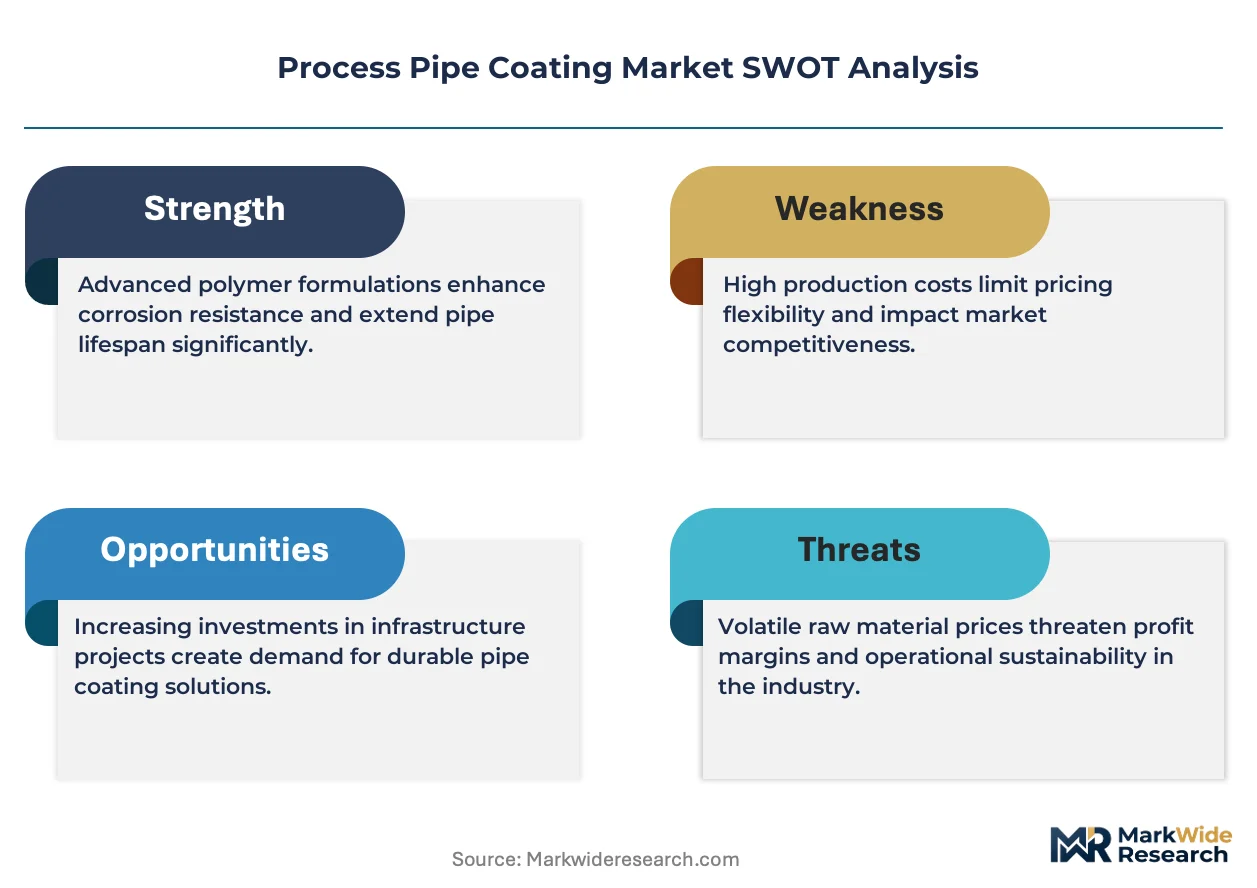
Captive resin-to-coating integration anchors competitive positioning for established formulators, compressing procurement cycles for bisphenol-A and amine hardeners while insulating qualified suppliers from spot-market volatility that erodes margin at transactional competitors.
Pricing Analysis
Performance-warranty bundling separates premium fusion-bonded epoxy suppliers from unbundled commodity coating vendors. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 21809 certification tier and cathodic disbondment warranty duration. Cost compression in standard-grade epoxy formulations is intensifying because REACH-driven reformulation cycles extend R&D amortization periods. Municipal water utilities exhibit highest price sensitivity; offshore oil and gas operators prioritize lifecycle cost over unit price.
Supply Chain Analysis
Domestic-content mandates in India's Petroleum and Natural Gas Regulatory Board city gas distribution program are reshaping sourcing toward Gujarat-based fabrication yards. Bisphenol-A production clusters in China and Germany, plus amine hardener capacity concentrated in Germany, expose coating formulators to feedstock volatility. Single-source vulnerability runs through Chinese epoxy resin supply for Asian applicators. Distribution runs through petrochemical-integrated formulators with captive logistics networks serving Gulf Coast and North Sea corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around qualified applicator capacity scarcity, with ISO 21809 certification bottlenecks forcing subscale service providers toward acquisition or exit.
For Market Incumbents: Anchor defensive positioning through backward integration into specialty amine hardener production, eliminating ECHA authorization timeline exposure. Expand fixed-plant fusion-bonded epoxy capacity in the United States Gulf Coast corridor to capture EPA NESHAP compliance-driven replacement demand. Certification investment in hydrogen-rated epoxy systems creates differentiation against thermoplastic tape substitution threats. For New Entrants and Emerging Players: Launch via mobile application service models targeting India's city gas distribution buildout, where BIS certification alignment lags demand growth. White-space concentrates in CCUS injection line internal linings for supercritical CO2 transport, a specification category with limited qualified suppliers. Digital application monitoring partnerships with asset owners enable outcome-based contracting entry without fixed-plant capital. For Investors and Strategic Acquirers: Exit pathways concentrate in specialized subsea application equipment networks and marine-grade corrosion chemistry adapters. Long-term viability favors vertically integrated resin-to-coating pipelines with renewable energy-integrated manufacturing for EU Green Deal compliance. Watch hydrogen infrastructure pilot program scale as inflection indicator for modified epoxy chemistry demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Hardeners | ECHA authorization timeline compression secures formulation continuity for REACH-compliant epoxies. |
| Fixed-Plant FBE Capacity Expansion | Gulf Coast sour-gas transmission demand outstrips current ISO 21809 certified applicator throughput. |
| Hydrogen-Rated Epoxy Qualification | European energy utility pilot programs open adjacent specification categories with limited competition. |
| Digital Application Monitoring Partnership | Real-time dry-film thickness verification enables outcome-based contracting with Norwegian asset owners. |
| Renewable Energy Manufacturing Integration | Environmental Product Declaration compliance secures European procurement preference under carbon-border adjustments. |
Methodological Framework
Trade databases, regulatory filings, and industry association reports formed the secondary backbone, cross-referenced with primary interviews involving coating formulator R&D directors, ISO 21809 certification auditors, petrochemical procurement managers, and offshore project engineering leads. Bottom-up and top-down triangulation validated volume estimates across coating type, application severity tier, and installation method segments.
Bottom-up modeling anchored individual country demand trajectories to named project pipelines and regulatory compliance deadlines, while top-down cross-checks applied macro industrial investment cycles. Segmentation dimensions included coating chemistry family, substrate service environment, cure protocol flexibility, and regional specification authority concentration. CAGRs derived from regression against historical replacement cycle timing and emerging hydrogen infrastructure pilot scale.
The model assumes a particular technology adoption path; alternative pathways for thermoplastic tape systems in low-pressure water transmission would alter the outlook. Forecasts reflect assumptions regarding REACH authorization timeline resolution and EPA NESHAP enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Middle East and Africa Super Hydrophobic Coatings Market
Coatings
Global Photocatalytic Coatings Market
Coatings
Epoxy Surface Coatings Market
Coatings
Leisure Boat Marine Coatings Market
Coatings
Global Pipe Coatings Market
Coatings
Global Metal Coatings Market
Coatings
Paper Coating Binders Market
Coatings
Global Coated Steel Market
Coatings
South Korea Marine Coatings Market
Coatings
Coating Pigments Market
Coatings
Global Polytetrafluoroethylene (PTFE) Coatings Market
Coatings
Egyptian Protective Coatings Market
Coatings
Antifouling Coatings Market
Coatings
France Protective Coatings Market
Coatings
Global Coil Coatings Market
Coatings
United States Floor Coatings Market