
 Germany Protective Coatings Market | 2026-2036
Germany Protective Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Protective Coatings Market Foresight
Preventive maintenance contracts and software-defined coating monitoring is rebalancing how German industrial buyers procure protection systems, shifting capital expenditure toward lifecycle service models. PPG Industries Inc. leverages its broad technology portfolio to anchor large automotive contracts in Stuttgart and Munich manufacturing zones. BASF SE sustains deep R&D integration with local chemical clusters in Ludwigshafen. Hempel A/S specializes in marine-grade systems for Hamburg and Bremen shipyards.
Germany protective coatings are multi-layer formulations—typically incorporating epoxy primers, polyurethane topcoats, or zinc-rich sacrificial layers—engineered to resist corrosion, chemical attack, and thermal cycling in heavy industrial environments. Application through spray coating and powder coating technologies dominates volume, with powder systems gaining share as solvent-free alternatives align with tightening emissions rules. Epoxy and polyurethane product types command the largest current volumes, while silicone coatings capture premium positions in high-temperature aerospace and power generation segments.
KBA vehicle type-approval requirements, REACH chemical registration mandates, and the EU Green Deal's industrial decarbonization benchmarks collectively shape formulation choices and market access conditions across German coating suppliers. The Federal Environment Agency enforces strict VOC thresholds that push manufacturers toward waterborne and high-solids technologies. Stakeholders must monitor evolving EU taxonomy criteria for sustainable industrial processes and position coating portfolios to meet dual demands from German manufacturing plants and export-facing automotive OEMs.
Market Dynamics
Waterborne formulation transitions are compressing solvent-borne capacity across German coating plants as REACH VOC thresholds tighten and automotive OEMs mandate low-emission supply chains.
Growth Catalysts
- Automotive OEM specification upgrades:Stuttgart and Munich assembly plants are expanding multi-layer coating protocols for electric vehicle battery enclosures and lightweight body structures.
- EU Green Deal industrial decarbonization:Benchmarks for carbon-intensive processes are redirecting capital toward energy-cured and UV-hardening coating lines.
- North Rhine-Westphalia infrastructure renewal:Chemical processing and steel fabrication clusters are driving demand for high-performance corrosion protection systems.
Market Restraints
- Titanium dioxide and epoxy resin cost volatility:Feedstock price swings compress margin stability for mid-tier formulators serving construction and marine segments.
- Specialized additive supply concentration:Functional pigments and cross-linking agents rely on concentrated Central European chemical production networks.
- Waterborne performance gaps in extreme environments:Humidity tolerance and salt-spray resistance limitations restrict adoption in offshore wind and heavy marine applications.
Strategic Opportunities
- Bavaria aerospace tier expansion:Munich-anchored satellite and drone manufacturing is creating demand for thermal-control and radar-absorbent coating systems.
- Preventive maintenance software integration:IoT-enabled coating degradation monitoring is opening recurring revenue streams among industrial asset operators.
- High-solids powder coating regulatory preference:Federal Environment Agency enforcement patterns favor solvent-free technologies in metal finishing and appliance manufacturing.
Industry Challenges
- Formulation chemist talent scarcity:Specialized expertise in hybrid polymer systems and regulatory compliance is concentrating among incumbent R&D centers.
- Multi-certification timeline compression:KBA automotive approval, REACH registration, and EU taxonomy alignment create parallel validation burdens for new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Protective Coatings Market |
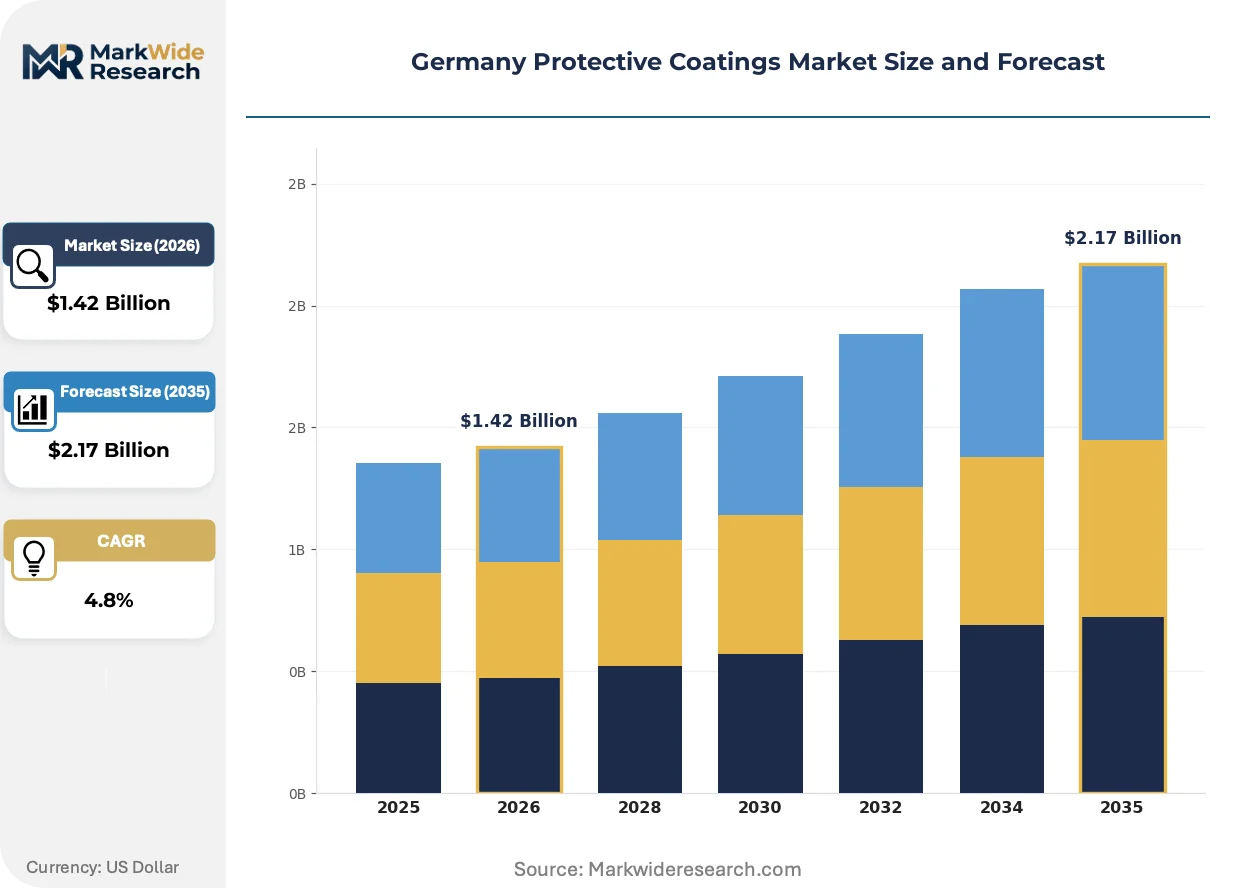
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
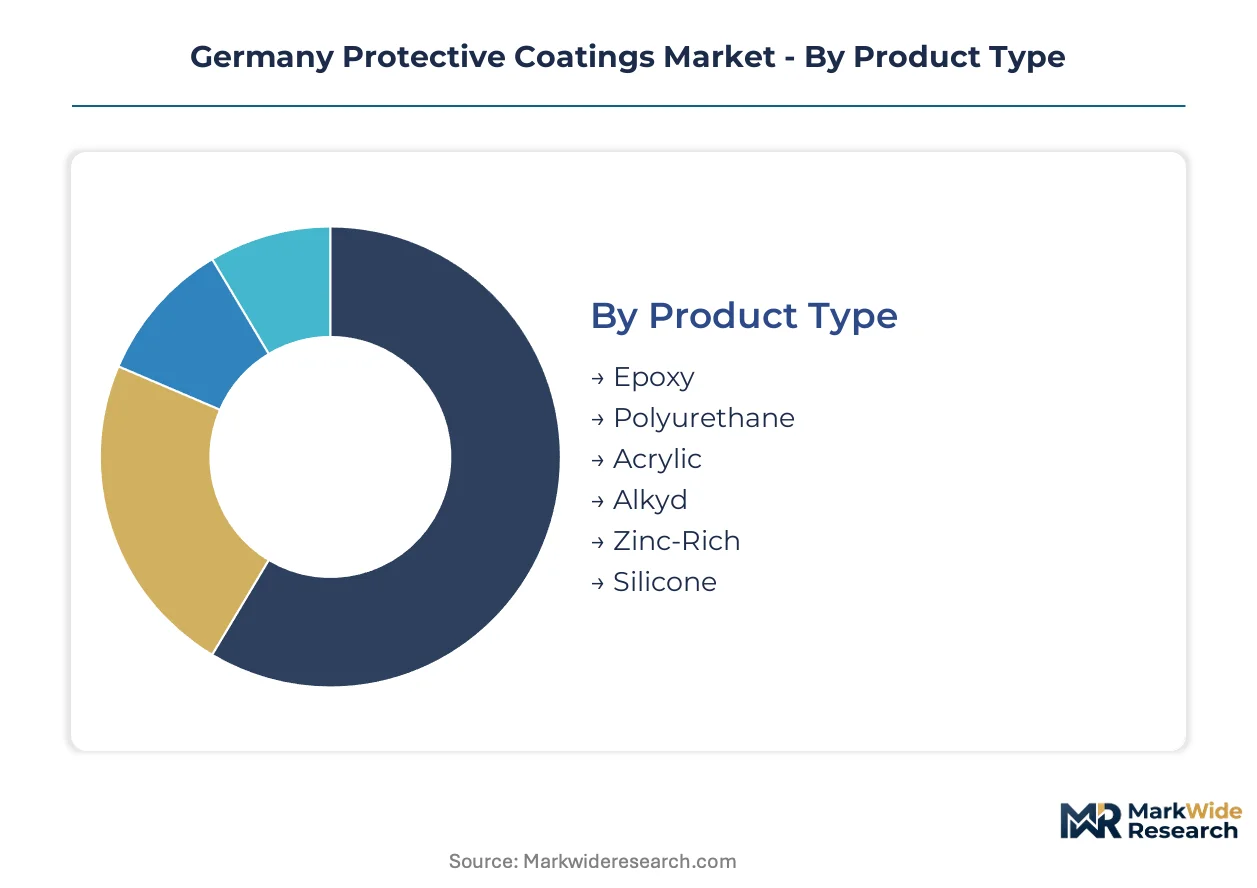
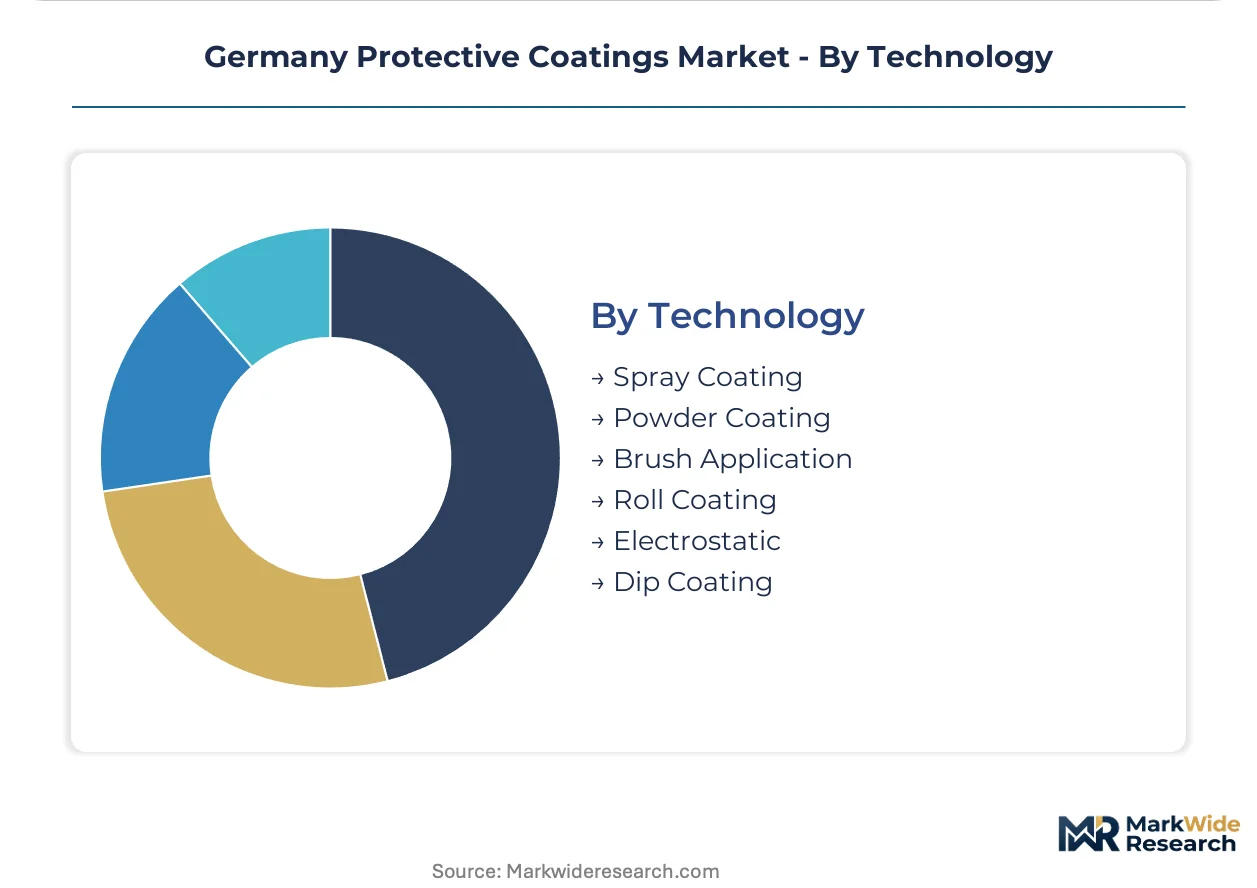
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Alkyd, Zinc-Rich, Silicone Application: Marine Structures, Industrial Equipment, Infrastructure, Aerospace Components, Oil & Gas Facilities, Automotive OEMs End User: Manufacturing Plants, Construction Firms, Refining Companies, Aeronautics Services, Vehicle Assemblers, Shipyards Technology: Spray Coating, Powder Coating, Brush Application, Roll Coating, Electrostatic, Dip Coating |
| Companies Covered | The Sherwin-Williams Company, Axalta Coating Systems, RPM International Inc., Hempel A/S, Beckers Group, AkzoNobel N.V., Jotun, BASF SE, PPG Industries Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Protective Coatings Market Shifts & Advancements
Digital coating specification platforms and predictive degradation analytics are rewiring how German industrial buyers evaluate lifecycle performance against first-cost procurement.
Self-healing polymer coating technology is modularizing repair functionality directly into polyurethane and epoxy matrices. Automotive tier suppliers in Baden-Württemberg are piloting microcapsule-embedded systems that autonomously seal minor scratches and corrosion initiation points. This capability is modularizing maintenance intervals and compressing total cost-of-ownership calculations for fleet operators.
REACH authorization procedures are tightening access to chromium VI compounds and specific isocyanate hardeners. The Federal Environment Agency's updated SVHC candidate list is forcing reformulation of anti-corrosive primers across marine and industrial segments. Coating laboratories in Ludwigshafen and Hamburg are accelerating bio-based hardener development to preempt supply discontinuities.
Lifecycle service contracting is displacing transactional product sales among large German manufacturing accounts. Chemical plant operators in North Rhine-Westphalia now specify coating performance guarantees rather than material volumes. Equipment OEMs in Bavaria are bundling application services with substrate warranties, compressing the role of independent distributors in high-value segments.
Germany Protective Coatings Market Segmentation
Coating procurement in Germany is fragmenting across performance tiers and application technologies. Buyers now specify lifecycle guarantees rather than material volumes, forcing suppliers to align portfolio structures with asset-operator risk models.
Product Type:
Upgrade cycles for corrosion protection systems are accelerating as REACH authorization deadlines force reformulation of legacy chemistries.
- Epoxy:Two-component systems built on bisphenol-A and novolac resins deliver chemical resistance and substrate adhesion for immersion service. Demand concentrates in North Rhine-Westphalia's chemical processing corridor where tank linings and pipeline coatings require frequent recoating intervals.
- Polyurethane:Aliphatic and aromatic formulations provide UV stability and abrasion resistance in topcoat applications. Bavarian automotive assembly plants specify these for exterior body panels and battery enclosure sealing where color retention and flexibility matter.
- Acrylic:Water-reducible systems serve decorative and light industrial finishing with moderate durability requirements.
- Alkyd:Traditional oil-modified polyesters persist in maintenance painting of structural steel where cost sensitivity dominates.
- Zinc-Rich:Inorganic and organic sacrificial primers protect steel substrates in marine and infrastructure exposures.
- Silicone:Heat-cured elastomeric coatings withstand continuous service temperatures exceeding 200°C in power generation and aerospace applications.
Volume placements concentrate in epoxy and polyurethane systems; the faster expansion belongs to silicone formulations as thermal management requirements intensify.
Application:
Cost-tier differentiation separates specification-grade systems from commodity alternatives across German industrial procurement.
- Marine Structures:Immersion-grade epoxy and antifouling systems protect hulls, ballast tanks, and offshore platforms in Hamburg and Bremen shipyards. KBA type-approval requirements and EU MRV emissions monitoring are extending coating inspection intervals and driving premium system adoption.
- Industrial Equipment:Chemical-resistant linings and abrasion-resistant topcoats serve processing machinery in Ludwigshafen and Leverkusen chemical clusters.
- Infrastructure:Bridge deck waterproofing and steel superstructure coatings address Federal Transport Infrastructure Plan renewal schedules.
- Aerospace Components:Thermal control and radar-absorbent coatings support Munich-anchored satellite manufacturing.
- Oil & Gas Facilities:High-temperature resistant systems protect downstream processing equipment.
- Automotive OEMs:Multi-layer protocols for electric vehicle architectures integrate corrosion protection with electromagnetic shielding.
Procurement value clusters in marine and industrial equipment; aerospace components are gaining share fastest as Bavaria's satellite tier expands.
End User:
Customer-type segmentation reveals divergent buying behaviors between capital-project owners and recurring-maintenance operators.
- Manufacturing Plants:Chemical processors and metal fabricators in North Rhine-Westphalia specify performance-based coating contracts with guaranteed service intervals.
- Construction Firms:General contractors and steel erectors source commodity-grade systems for structural fireproofing and architectural finishing.
- Refining Companies:Downstream operators in Rhineland refineries demand heat-resistant and chemical-resistant linings for process vessels.
- Aeronautics Services:Maintenance, repair, and overhaul providers in Munich and Hamburg apply specialized coatings for airframe refurbishment.
- Vehicle Assemblers:Stuttgart and Munich OEM plants integrate coating specifications into supplier quality agreements.
- Shipyards:Hamburg and Bremen builders specify coating systems during newbuild construction and dry-dock maintenance cycles.
Contract value concentrates with manufacturing plants and vehicle assemblers; shipyards are expanding procurement most quickly as offshore wind installation vessel orders accumulate.
Technology:
Application-method selection directly determines capital equipment requirements and regulatory compliance pathways for German coating operations.
- Spray Coating:Airless and conventional spray systems dominate high-volume industrial finishing where complex geometries require uniform film builds.
- Powder Coating:Electrostatic fluidized bed and spray processes eliminate solvent emissions, aligning with Federal Environment Agency VOC thresholds in metal finishing and appliance manufacturing.
- Brush Application:Manual touch-up and maintenance recoating persists in field construction and ship repair where equipment access limits mechanized methods.
- Roll Coating:Continuous coil coating lines serve flat metal sheet producers in Ruhr industrial zones.
- Electrostatic:Charged particle deposition improves transfer efficiency in automotive and furniture finishing operations.
- Dip Coating:Immersion processes coat complex hollow sections and fasteners in batch operations.
Equipment investment concentrates in spray and powder coating lines; electrostatic methods are climbing the fastest as transfer efficiency regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Rhine-Westphalia's industrial corridor generates the heaviest coating demand from chemical processing plants and steel fabrication clusters. Bavaria's automotive belt around Munich and Stuttgart drives specification-grade consumption for electric vehicle production. Hamburg and Bremen anchor marine coating procurement for shipbuilding and offshore wind installation.
North Rhine-Westphalia
Chemical processing infrastructure and steel fabrication dominate coating consumption across the Ruhr industrial zone. The Federal Environment Agency enforces strict VOC thresholds that accelerate waterborne technology transitions in Leverkusen and Duisburg manufacturing plants. Ludwigshafen's chemical cluster sustains deep R&D integration between coating suppliers and local polymer research centers.
Bavaria
Automotive OEM assembly plants in Munich and Ingolstadt specify multi-layer coating protocols for battery enclosures and lightweight body structures. KBA vehicle type-approval requirements mandate rigorous coating performance validation for exterior durability and corrosion resistance. Munich-anchored satellite manufacturing creates emerging demand for thermal-control and radar-absorbent coating systems in aerospace applications.
Baden-Württemberg
Stuttgart's automotive headquarters and tier supplier networks drive premium coating specifications across passenger vehicle and commercial truck segments. EU Green Deal industrial decarbonization benchmarks redirect capital toward energy-cured and UV-hardening coating lines in regional assembly plants. Automotive tier suppliers in the region pilot microcapsule-embedded self-healing polymer systems for autonomous scratch repair functionality.
Hamburg
Shipyards and offshore wind installation vessel builders consume immersion-grade epoxy and antifouling systems at scale. EU MRV emissions monitoring extends coating inspection intervals and drives premium system adoption for hull protection and ballast tank linings. The port city's marine engineering cluster coordinates specification standards between classification societies and coating manufacturers.
Lower Saxony
Volkswagen's Wolfsburg headquarters and supplier parks concentrate automotive coating demand for mass-market vehicle production. Federal Transport Infrastructure Plan renewal schedules drive bridge deck waterproofing and steel superstructure coating procurement across state highway networks. Wind energy manufacturing in the region consumes protective systems for turbine tower fabrication and offshore foundation structures.
Germany Protective Coatings Market Competitive Landscape
Capital-heavy integrated producers compete with asset-light specialty formulators across distinct technology tiers. The supplier base consolidates around three structural positions: multinational chemical conglomerates with captive resin supply, regional coating specialists with deep application expertise, and automotive-focused integrators with OEM qualification lock-in. M&A activity concentrates on additive technology acquisitions and regional distribution networks. Strategic partnerships between formulators and equipment manufacturers bundle application services with substrate warranties.
Among diversified chemical conglomerates, BASF SE and PPG Industries Inc. exemplify integrated R&D-to-application architectures that span polymer synthesis through specification-grade formulation. Hempel A/S occupies a specialist position within marine-grade system development, anchoring technical service capabilities in port-proximate locations. These three entities represent distinct competitive archetypes: captive supply chain control, automotive OEM integration depth, and vertical application expertise respectively.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| Axalta Coating Systems |
| RPM International Inc. |
| Hempel A/S |
| Beckers Group |
| AkzoNobel N.V. |
| Jotun |
| BASF SE |
| PPG Industries Inc. |
| Others |
Supply & Pricing Matrix
Automotive OEM specification upgrades for electric vehicle battery enclosures are forcing German coating suppliers to absorb certification costs while maintaining tier-one supply status, compressing margin structures for non-integrated formulators. REACH authorization timelines and KBA type-approval requirements create pricing power asymmetries that favor incumbent producers with captive regulatory expertise.
Pricing Analysis
Margin tightening in mid-tier marine and industrial segments traces to titanium dioxide and epoxy resin cost volatility that formulators cannot fully pass to price-sensitive construction buyers. Three-tier pricing structure across specification-grade, performance-standard, and commodity-economy levels separates automotive OEM contracts with lifecycle guarantees from spot-market construction procurement. Cost-down pressure on waterborne formulations accelerates because Federal Environment Agency VOC enforcement favors solvent-free technologies despite their higher production overhead. Construction firms exhibit the greatest price sensitivity, while automotive assemblers accept premium positioning for validated supply security.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Antwerp, and Hamburg coordinate hub-and-spoke patterns that feed German industrial clusters with just-in-time resin and additive deliveries. Raw material sourcing draws from Belgian petrochemical complexes for epoxy precursors, Chinese titanium dioxide feedstock, and Central European functional pigment production. Single-source vulnerability concentrates in specialized cross-linking agents and bio-based hardener development capacity. Distribution runs through authorized distributor networks for specification-grade systems, while commodity coatings move through construction supply wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany Protective Coatings Market functions as a cost-of-compliance story where REACH authorization procedures and KBA type-approval requirements erect barrier-to-entry moats that protect validated incumbents from unqualified competitors.
For Market Incumbents: Anchor defensive positioning through backward integration into specialty resin production and accelerated bio-based hardener R&D to preempt REACH supply discontinuities. Consolidate channel control by acquiring regional distributors in North Rhine-Westphalia's chemical corridor. Threat from emerging waterborne specialists with automotive qualification mandates margin protection through specification lock-in. For New Entrants and Emerging Players: EU Green Deal industrial decarbonization benchmarks in Germany open a window for energy-cured and UV-hardening coating technologies that bypass incumbent solvent-borne infrastructure. Target preventive maintenance software integration as the most penetrable white-space, where IoT-enabled degradation monitoring displaces transactional product sales. Pursue partnership-based go-to-market models with equipment OEMs bundling application services. For Investors and Strategic Acquirers: The window for entry favors additive technology specialists with REACH-compliant portfolios and established automotive qualification pathways. Long-term viability hinges on regulatory compliance durability rather than volume scale. Watch Federal Environment Agency SVHC candidate list expansions as the inflection signal for reformulation-driven acquisition demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resins | Captive supply of epoxy precursors insulates margin structures from Ludwigshafen cluster price volatility. |
| REACH-Compliant Bio-Based Hardener Development | Preemptive reformulation capability secures market access as ECHA tightens chromium VI authorization. |
| Preventive Maintenance Software Platform | IoT-enabled coating degradation monitoring shifts procurement from product volumes to performance guarantees. |
| Energy-Cured Coating Line Investment | UV-hardening technology aligns with EU Green Deal decarbonization benchmarks for Bavarian automotive plants. |
| Regional Distribution Network Acquisition | Channel control in North Rhine-Westphalia compresses independent distributor roles in specification-grade segments. |
Research Methodology
Trade association filings, customs import records, and ECHA REACH registration databases formed the secondary backbone for volume and value estimation. Primary interviews with coating plant managers, automotive OEM procurement leads, chemical distributor channel partners, and Federal Environment Agency compliance officers combined with secondary validation through bottom-up and top-down triangulation.
Bottom-up modeling aggregated segment-level demand across product type, application technology, and end-user industry, while top-down cross-checks validated aggregate market scale against chemical production and consumption indicators. Segmentation dimensions included resin chemistry tier, substrate application method, and regional industrial cluster concentration. CAGRs were derived from trend extrapolation of automotive production cycles, infrastructure renewal schedules, and regulatory compliance timelines.
The model assumes a particular technology adoption path; alternative pathways for waterborne formulation penetration in heavy marine environments would alter the outlook if humidity tolerance limitations resolve faster than projected. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Africa Automotive Refinish Coatings Market
Coatings
Waterproof Coating Market
Coatings
Saudi Arabia Industrial Coatings Market
Coatings
Anti-Microbial Coatings Market
Coatings
FBE Coatings Market
Coatings
Conductive Polymer Coatings Market
Coatings
Electronic Protection Device (EPD) Coatings Market
Coatings
Germany Automotive OEM Coatings Market
Coatings
Marine Anti Fouling Coatings Market
Coatings
Global Photocatalytic Coatings Market
Coatings
Camouflage Coatings Market
Coatings
France Automotive OEM Coatings Market
Coatings
Flexible Waterproof Coating Market
Coatings
PU Coatings Market
Coatings
Asia-Pacific Flat Glass Coating Market
Coatings
Fillers and Coating Market