
 Perfluoroalkoxy (PFA) Coatings Market | 2026-2036
Perfluoroalkoxy (PFA) Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Perfluoroalkoxy (PFA) Coatings Market Analytics
Buyer concentration in semiconductor capital equipment is pivoting toward a handful of original equipment manufacturers that specify PFA-coated components for wet processing tools. Chemours Company leverages its vertical integration in fluoropolymer resin supply to secure preferred supplier status with toolmakers. Daikin Industries anchors its position through proprietary melt-processable copolymer grades optimized for electrostatic chuck and chamber component applications. Solvay S.A. differentiates via specialty PFA formulations that sustain performance under repeated thermal cycling in high-purity chemical delivery systems.
Perfluoroalkoxy coatings are melt-processable fluoropolymer finishes composed of tetrafluoroethylene and perfluoroalkyl vinyl ether copolymers, typically applied at film thicknesses of 25-100 micrometers to achieve continuous service temperatures up to 260°C with near-universal chemical inertness. Their primary industrial purpose is to protect metal substrates from corrosive attack while preventing metallic ion contamination in ultra-clean process environments. Fluoropolymer coatings occupy the premium tier of the product type landscape, commanding margin pools in semiconductor and pharmaceutical applications where substitution risks are unacceptable. Powder coatings represent the fastest-growing application format, displacing liquid systems in electrostatic spray operations that reduce volatile organic compound emissions and solvent handling costs. The industrial equipment application segment leads absolute volume, though medical devices generate superior unit economics due to validation requirements and regulatory file continuity obligations.
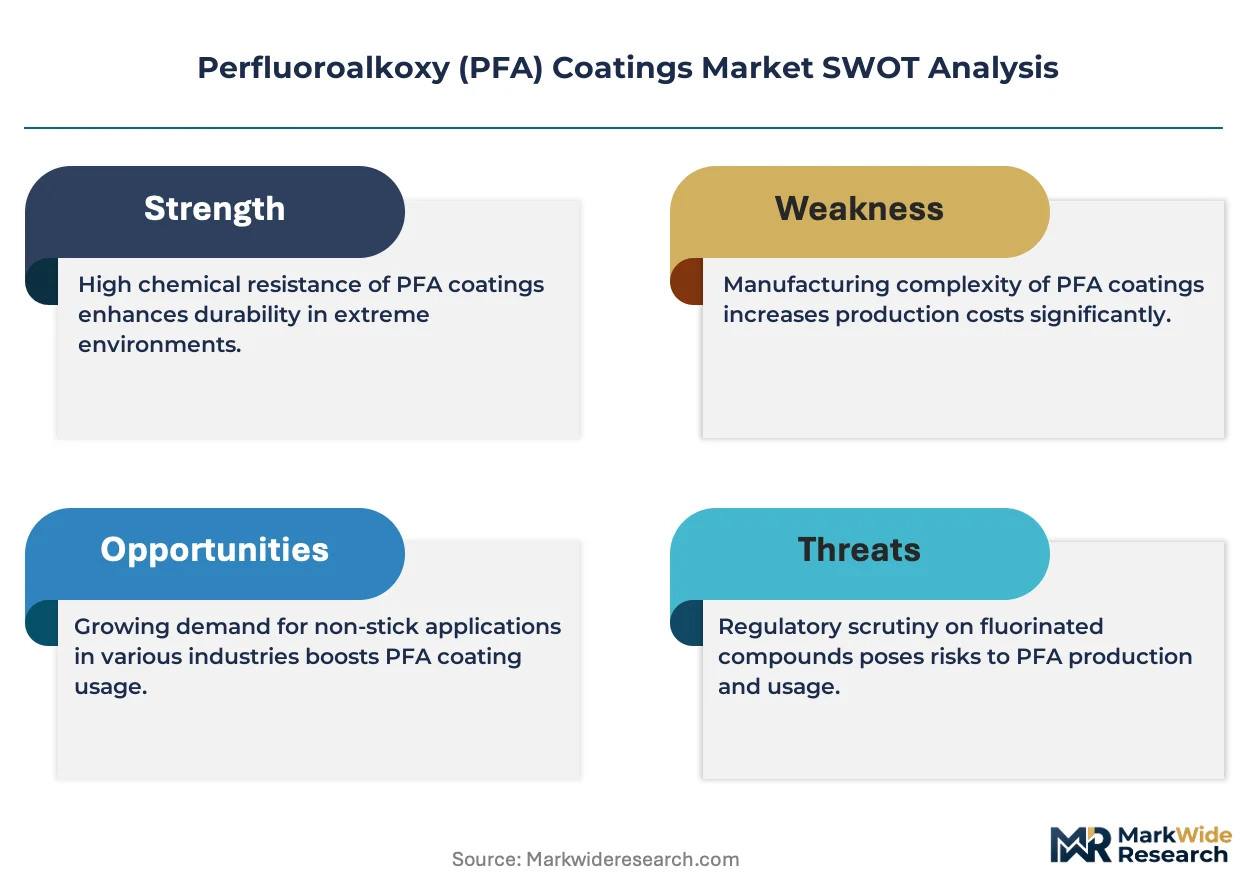
The EPA oversees fluoropolymer manufacturing under TSCA Section 5 premanufacture notification requirements, while the EU REACH restriction proposal on PFAS substances threatens market access for non-essential uses unless critical-use exemptions are secured. FDA 21 CFR 175.300 compliance enables PFA coating adoption in food-contact processing equipment, expanding the addressable market beyond traditional chemical containment applications. Stakeholders must monitor the evolving regulatory bifurcation between jurisdictions that grandfather existing fluoropolymer chemistries and those accelerating phase-out timelines, as this divergence will reshape supplier qualification requirements and capital allocation priorities across the value chain.
Market Dynamics
Semiconductor capital equipment manufacturers are consolidating their supplier bases around fluoropolymer coating specialists capable of certifying batch-to-batch ionic purity below 10 parts per billion. This buyer concentration is compressing qualification timelines while elevating technical barriers for second-tier applicators.
Growth Catalysts
- Advanced node migration:Taiwan and South Korea-based foundries are specifying thicker PFA films for 3nm and 2nm process tools to withstand hydrofluoric acid exposure during wafer cleaning cycles.
- REACH critical-use exemptions:The EU regulatory pathway for essential industrial fluoropolymer applications is preserving market access for semiconductor and pharmaceutical coating deployments.
- Electrostatic spray powder systems:Dry application technology is eliminating solvent recovery infrastructure and reducing volatile organic compound emissions in coating operations.
Market Restraints
- Fluoromonomer supply concentration:Tetrafluoroethylene feedstock production clusters in China and the United States create geographic vulnerability for coating manufacturers dependent on imported resin.
- Thermal expansion mismatch:Differential coefficients between PFA films and aluminum substrates limit maximum coating thickness in high-cyclic thermal applications.
- PFAS substitution pressure:European environmental agencies are accelerating scrutiny of all perfluorinated chemistries, threatening demand in non-critical industrial segments.
Strategic Opportunities
- Biopharmaceutical single-use systems:Stainless steel vessel manufacturers in Germany and Switzerland are qualifying PFA-lined components for cell culture media preparation to eliminate metallic ion leaching.
- India semiconductor fabrication:The country's PLI scheme for electronic manufacturing is attracting coating applicators to establish local service capabilities for imported process tools.
- Laser ablation surface preparation:Converging robotics and pulsed laser cleaning is enabling automated substrate pretreatment that improves PFA adhesion on complex geometries.
Industry Challenges
- Fluoropolymer welding certification:Qualified technicians capable of fusion-bonding PFA sheet linings without introducing contamination are scarce across North American and European service networks.
- Cleanroom application infrastructure:ISO Class 5 coating facilities require capital outlays exceeding standard industrial paint operations by an order of magnitude.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Perfluoroalkoxy (PFA) Coatings Market |
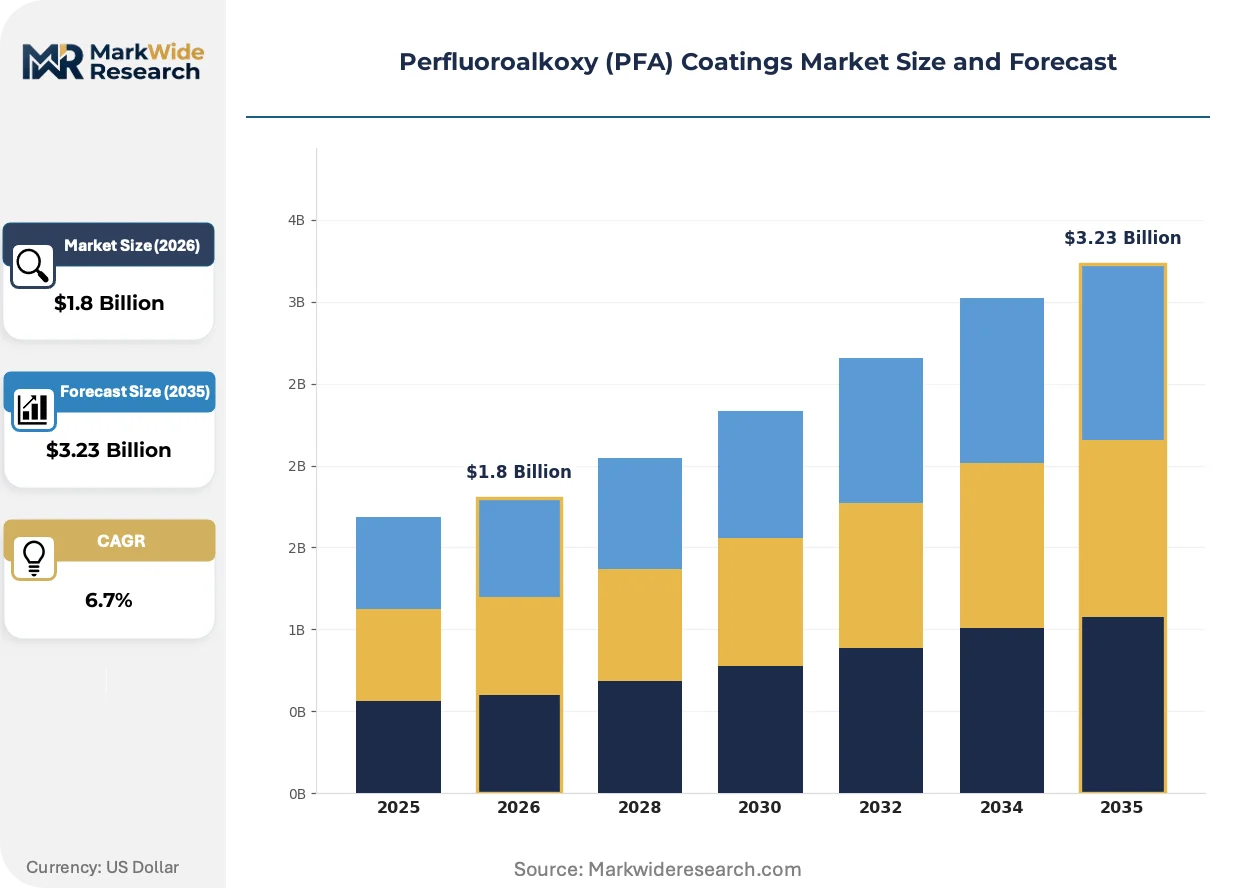
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluoropolymer Coatings, Liquid Coatings, Powder Coatings, Aerosol Coatings Application: Industrial Equipment, Chemical Processing, Electronics, Medical Devices End User: Manufacturing, Healthcare, Aerospace, Automotive Components Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Chemours Company, Daikin Industries, Ltd., Solvay S.A., AGC Inc., 3M Company, Whitford Corporation, Gujarat Fluorochemicals Ltd., Lincotek Surface Solutions, Intech Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Perfluoroalkoxy (PFA) Coatings Market Evolving Landscape
Coating applicators are integrating in-process monitoring systems that track film thickness and pinhole density in real time. This instrumentation shift is compressing quality assurance cycles while raising the technical floor for market participation.
Plasma-enhanced chemical vapor deposition of fluoropolymer films is automating the transition from batch dip-coating to continuous reel-to-reel processing. Medical device manufacturers in Minnesota and Massachusetts are adopting these systems for catheter guidewire insulation. The technology is automating labor-intensive masking operations while enabling sub-10-micrometer coating uniformity on elongated components.
ECHA's PFAS restriction proposal under REACH is forcing coating suppliers to document essential-use justifications for semiconductor and pharmaceutical applications. The regulatory friction is diverting technical resources toward dossier preparation and away from product development. European toolmakers are dual-qualifying Asian coating sources to mitigate supply disruption risks from potential authorization delays.
Original equipment manufacturers are unbundling coating services from component procurement, creating direct contractual relationships with specialized applicators. Semiconductor tool builders in Hsinchu and Suwon are establishing approved vendor lists that bypass traditional distributor channels. This disintermediation is most visible in East Asia, where capital equipment makers seek traceability to individual coating batches for warranty compliance.
Perfluoroalkoxy (PFA) Coatings Market Segmentation
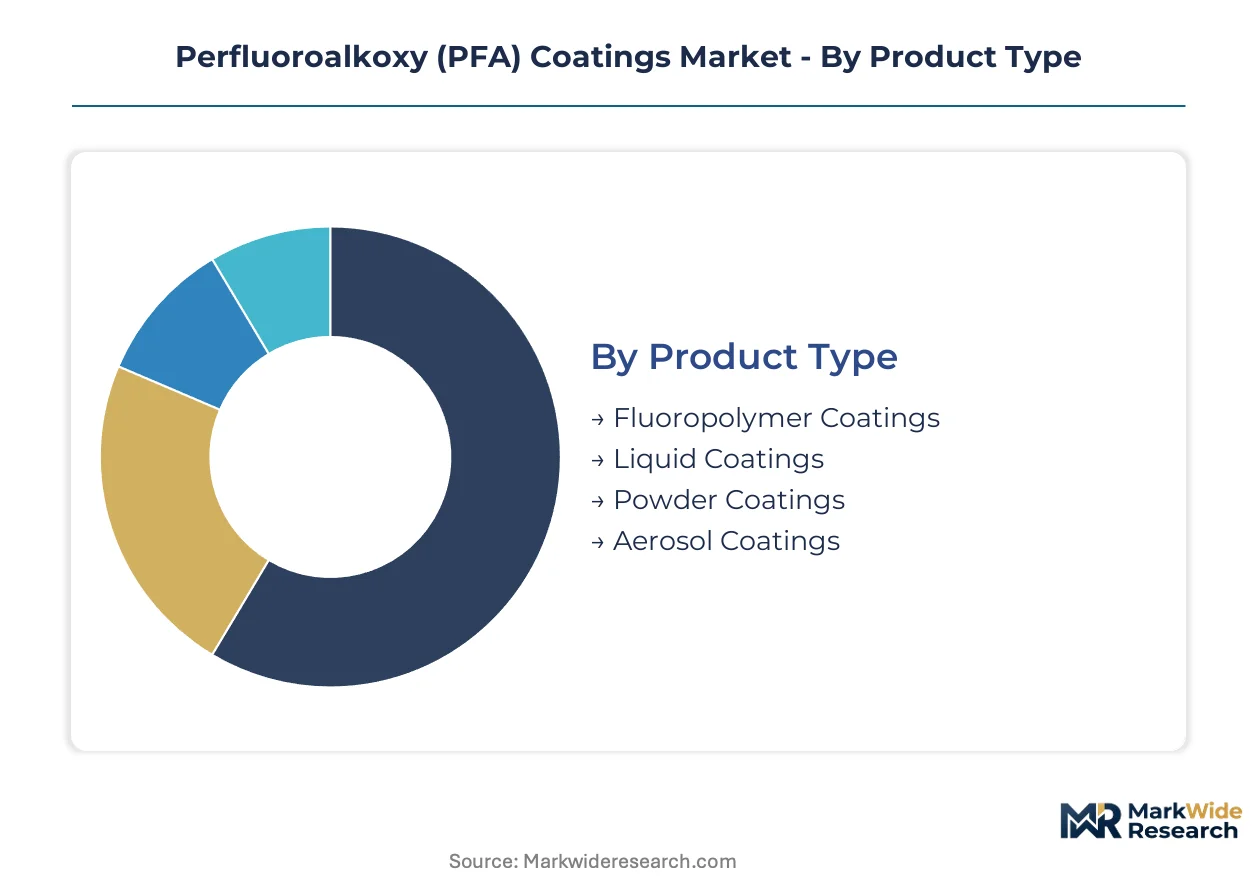
PFA coating procurement patterns diverge sharply across product formats and end-use specifications. Semiconductor toolmakers impose distinct purity and thickness requirements that reshape supplier economics within each segment.
Product Type:
Supply concentration in fluoropolymer resin production tilts competitive advantage toward coating manufacturers with captive or preferred feedstock access.
- Fluoropolymer Coatings:Premium copolymer formulations deliver continuous service temperatures to 260°C with near-universal chemical inertness. Taiwan and South Korea foundries specify these for 3nm node wet processing tools where metallic ion contamination risks are unacceptable.
- Powder Coatings:Dry electrostatic application eliminates solvent recovery infrastructure and volatile organic compound emissions. East Asian applicators are displacing liquid systems in high-volume semiconductor component finishing.
- Liquid Coatings:Solvent-based systems retain position in complex geometry dipping operations where film uniformity demands exceed powder capabilities.
- Aerosol Coatings:Pressurized delivery suits field repair and maintenance applications in chemical processing infrastructure.
Today's leader: Fluoropolymer Coatings. Tomorrow's challenger: Powder Coatings.
Application:
Cost tier differentiation separates validated pharmaceutical and semiconductor applications from standard industrial protective finishes.
- Industrial Equipment:Chemical containment vessels and piping systems constitute the volume base. German and Swiss stainless steel fabricators specify PFA linings for cell culture media preparation to eliminate metallic ion leaching.
- Electronics:Semiconductor capital equipment manufacturers consolidate supplier bases around specialists certifying batch-to-batch ionic purity below 10 parts per billion. Hsinchu and Suwon toolmakers establish approved vendor lists bypassing traditional distribution.
- Chemical Processing:Aggressive acid handling infrastructure in fluorinated chemistry plants drives specification of thicker film builds.
- Medical Devices:Validation requirements and regulatory file continuity obligations generate superior unit economics despite smaller absolute volumes.
The steepest expansion trajectory belongs to Electronics. Chemical Processing maintains defensive positioning through replacement demand.
End User:
Customer type fragmentation creates distinct qualification barriers between regulated healthcare applications and price-sensitive manufacturing sectors.
- Manufacturing:Semiconductor fabrication equipment and chemical process industries dominate procurement with technical specifications that exclude commodity applicators.
- Healthcare:FDA 21 CFR 175.300 compliance enables food-contact and medical device adoption, expanding addressable market beyond traditional containment.
- Aerospace:Fuel system and hydraulic component protection applications specify PFA for extreme temperature cycling resistance.
- Automotive Components:Fuel handling and battery system applications are gaining specification as electric vehicle thermal management requirements intensify.
Manufacturing commands current procurement volume. Healthcare presents the premium margin pool.
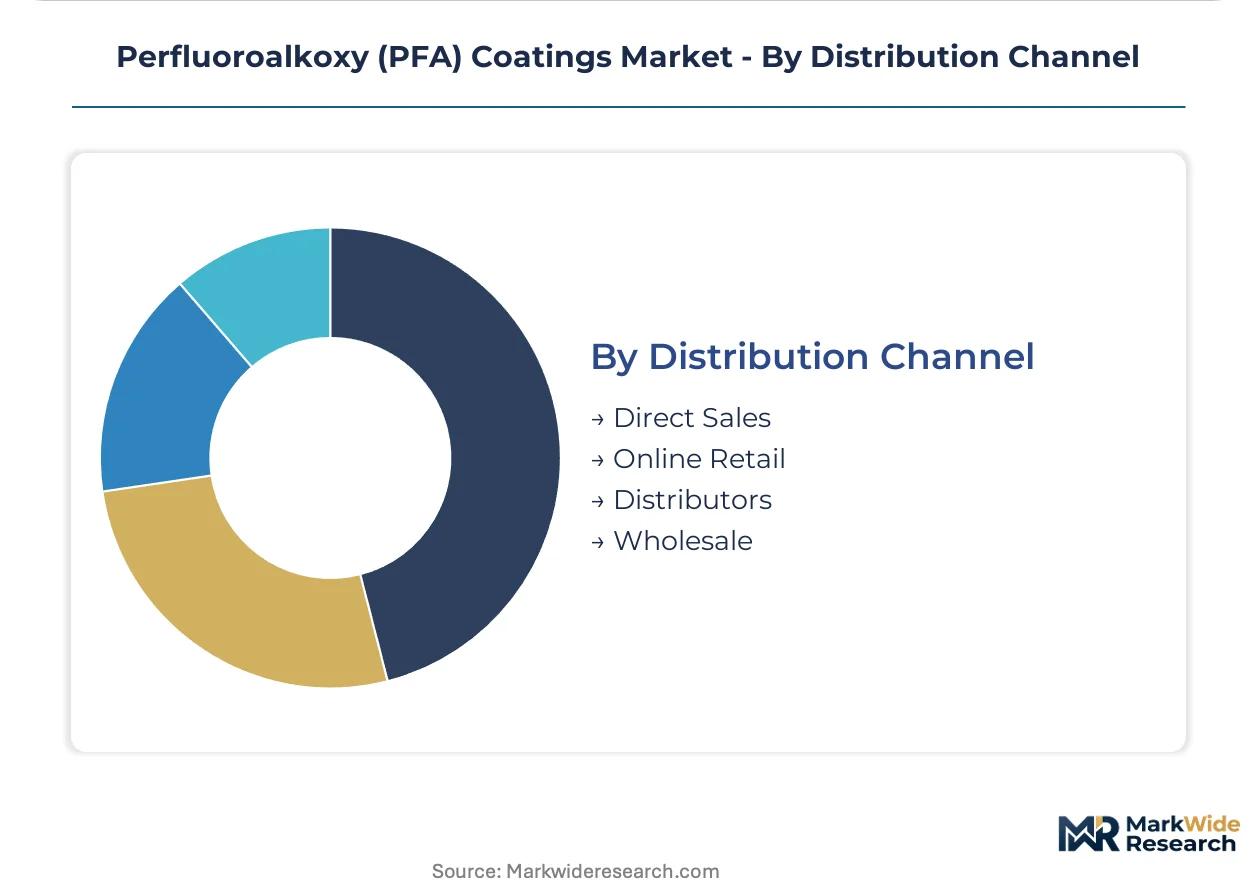
Distribution Channel:
Channel maturity varies with customer technical sophistication and batch traceability requirements.
- Direct Sales:Original equipment manufacturers unbundle coating services from component procurement, creating direct contractual relationships with specialized applicators for warranty compliance.
- Distributors:Traditional channels retain position in maintenance, repair, and operations procurement for chemical processing facilities.
- Online Retail:Aerosol and small-volume liquid formulations migrate to digital channels for convenience purchasing.
- Wholesale:Bulk resin and coating material supply to certified applicator networks.
Direct Sales is consolidating share fastest. Distributors defend residual maintenance demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States semiconductor equipment manufacturers specify PFA coatings at stricter purity thresholds than German chemical processors, reflecting divergent end-use priorities across major demand centers.
United States
EPA TSCA Section 5 oversight shapes fluoropolymer manufacturing compliance costs for domestic coating applicators. Minnesota and Massachusetts medical device clusters drive specification of sub-10-micrometer PFA films for catheter guidewire insulation. FDA 21 CFR 175.300 certification expands addressable demand into food-contact processing equipment beyond traditional containment uses.
Taiwan
Hsinchu-based foundries anchor procurement of ultra-pure PFA-coated components for 3nm and 2nm wet processing tools. The island's semiconductor supply chain concentrates specification authority with original equipment manufacturers that bypass traditional distribution channels. Local toolmakers establish approved vendor lists mandating batch-to-batch ionic purity below 10 parts per billion.
South Korea
Suwon-area capital equipment manufacturers unbundle coating services from component procurement, creating direct contractual relationships with specialized applicators. MFDS regulatory alignment with FDA standards facilitates medical device coating qualification for export markets. Domestic foundries specify thicker PFA films to withstand hydrofluoric acid exposure during advanced node wafer cleaning cycles.
Germany
ECHA's REACH PFAS restriction proposal compels coating suppliers to document essential-use justifications for pharmaceutical and semiconductor applications. Swiss and German stainless steel fabricators qualify PFA-lined vessels for cell culture media preparation to eliminate metallic ion leaching. Bavarian and Baden-Württemberg industrial clusters concentrate biopharmaceutical single-use system manufacturing.
Japan
METI industrial policy supports domestic fluoropolymer resin production for captive coating supply. Japanese applicators optimize proprietary melt-processable copolymer grades for electrostatic chuck and chamber component specifications. Osaka and Nagoya industrial corridors maintain qualified technician networks for fusion-bonding PFA sheet linings without contamination.
Perfluoroalkoxy (PFA) Coatings Market Competitive Landscape
United States and Japanese producers anchor one tier; European and Indian specialists hold differentiated positions in regional qualification networks. The vendor base concentrates around fluoropolymer resin manufacturers with captive coating application capabilities and independent applicators serving maintenance demand. Three archetypes dominate: integrated resin-to-coating manufacturers, certified high-purity applicators, and regional service specialists. Capacity expansion in East Asian semiconductor clusters and strategic partnerships for REACH compliance documentation represent the dominant competitive vectors.
Among integrated manufacturers, Chemours Company exemplifies the resin-anchored archetype through upstream control over tetrafluoroethylene feedstock production. Daikin Industries occupies a parallel position as a Japanese copolymer specialist with proprietary formulation capabilities. Solvay S.A. represents the European tier, anchoring specialty PFA formulation expertise for thermal cycling applications. These three entities collectively illustrate how backward integration into fluoromonomer supply constrains competitive entry for second-tier applicators lacking preferred resin access.
| Leading Market Players |
|---|
| Chemours Company |
| Daikin Industries, Ltd. |
| Solvay S.A. |
| AGC Inc. |
| 3M Company |
| Whitford Corporation |
| Gujarat Fluorochemicals Ltd. |
| Lincotek Surface Solutions |
| Intech Services, Inc. |
| Others |
Value Network & Pricing Analysis
Tetrafluoroethylene feedstock price volatility cascades through three distinct pricing tiers—semiconductor-grade ultra-pure coatings, industrial protective finishes, and maintenance repair aerosols—with each tier absorbing cost shocks differentially based on certification requirements and buyer concentration.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for semiconductor-grade PFA coatings as local applicators achieve batch-to-batch ionic purity below 10 parts per billion. Three-tier pricing separates FDA-validated medical device coatings from industrial protective finishes and commodity maintenance formulations. Price differentiation hinges on ISO Class 5 cleanroom certification and volume scale, with pharmaceutical buyers showing least sensitivity due to regulatory file continuity obligations. Cost compression in industrial tiers is intensifying because East Asian foundries are consolidating approved vendor lists and bypassing distribution markups.
Supply Chain Analysis
Refurbishment flows for PFA-lined chemical containment vessels create secondary material recovery channels that extend resin utilization and moderate virgin feedstock demand. Tetrafluoroethylene production concentrates in China and the United States, with coating manufacturers drawing from these clusters through long-term offtake arrangements or captive integration. Fluoropolymer resin, perfluoroalkyl vinyl ether comonomer, and specialized spray application equipment constitute critical input dependencies. Single-source vulnerability persists in high-purity resin grades qualified for semiconductor applications. Distribution runs through direct contractual relationships between East Asian toolmakers and certified applicators, displacing traditional distributor channels in premium tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PFA coatings market functions as a geographic-arbitrage play where REACH regulatory friction in Europe elevates compliance costs against East Asian manufacturing clusters with streamlined qualification pathways.
For Market Incumbents: Anchor resin supply security through backward integration into tetrafluoroethylene feedstock or preferred long-term contracts with Chinese and US producers. Accelerate REACH essential-use dossier preparation to defend semiconductor and pharmaceutical market access against substitution threats. Expand ISO Class 5 cleanroom capacity in Taiwan and South Korea to capture advanced node tool qualification demand. For New Entrants and Emerging Players: India's PLI scheme for electronic manufacturing opens a window for coating applicators to establish local service capabilities for imported semiconductor process tools. Target biopharmaceutical single-use systems in Germany and Switzerland where stainless steel fabricators seek PFA-lined alternatives to eliminate metallic ion leaching. Pursue laser ablation surface preparation partnerships to differentiate on automated substrate pretreatment for complex geometries. For Investors and Strategic Acquirers: Asymmetric upside sits with certified high-purity applicators possessing established relationships with Hsinchu and Suwon toolmakers. Long-term viability centers on regulatory navigation capabilities across REACH, EPA TSCA, and FDA frameworks. Monitor ECHA PFAS restriction implementation timelines as the critical inflection signal for demand bifurcation between exempted critical uses and phased industrial applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoromonomer Supply | Chemours and Daikin leverage captive tetrafluoroethylene production to constrain second-tier competitor resin access. |
| REACH Essential-Use Dossier Investment | Solvay and European applicators allocate technical resources to secure pharmaceutical and semiconductor exemption pathways. |
| ISO Class 5 Cleanroom Capacity Expansion | East Asian specialists in Taiwan and South Korea capture advanced node tool qualification demand from consolidating foundries. |
| Laser Ablation Surface Preparation Adoption | Medical device manufacturers in Minnesota and Massachusetts automate catheter guidewire coating for sub-10-micrometer uniformity. |
| India Local Service Capability Establishment | Coating applicators position for PLI scheme-driven semiconductor fabrication equipment demand without import dependency. |
Research Methodology
Coverage spans Taiwan, South Korea, the United States, Germany, and Japan, with primary inputs from each region combined with secondary validation. Interviews with semiconductor tool procurement managers, fluoropolymer plant engineers, pharmaceutical vessel fabricators, and coating application technicians informed demand-side dynamics. Secondary sources include EPA TSCA Section 5 filings, ECHA REACH restriction proposals, FDA 21 CFR 175.300 compliance databases, and SEC disclosures from fluoropolymer resin manufacturers. Bottom-up coating volume estimates triangulated against top-down semiconductor capital equipment spending patterns.
Rate-of-change decomposition separates volume growth from price realization across the projection horizon. Segmentation dimensions encompass product format, application industry, end-user sector, and regional regulatory cluster. CAGRs derive from installed base expansion in semiconductor fabrication, replacement cycle analysis for chemical processing infrastructure, and qualification timeline compression in pharmaceutical applications. Forecast inputs incorporate foundry node migration roadmaps from Taiwan and South Korea, REACH authorization probability assessments, and powder coating displacement rates for liquid systems.
Revisions become necessary when ECHA accelerates PFAS restriction timelines, when tetrafluoroethylene supply disruptions emerge from China or US production clusters, or when semiconductor capital expenditure cycles inflect. Forecasts reflect assumptions about regulatory grandfathering continuity, feedstock price stability, and cleanroom capacity expansion schedules. Practitioners should monitor ECHA restriction implementation progress, foundry tool procurement announcements from Hsinchu and Suwon, and fluoromonomer spot market indicators for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
E-Coat Market
Coatings
BRIC Performance Coatings Market
Coatings
France Automotive OEM Coatings Market
Coatings
Global Radiation Cured Coatings Market
Coatings
Japan Protective Coatings Market
Coatings
Global Polyurea Coating Market
Coatings
Carbon Fiber Coatings Market
Coatings
Compound Coating Market
Coatings
Ethylene Tetrafluoroethylene (ETFE) Coatings Market
Coatings
China Marine Coatings Market
Coatings
Global Anti-Corrosion Coating Market
Coatings
Acrylic Surface Coating Market
Coatings
Cladding Coatings Market
Coatings
Clear Coatings Market
Coatings
Global Fusion Bonded Epoxy Coatings Market
Coatings
Bio-Based Coatings Market