
 Textile Coatings Market | 2026-2036
Textile Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Coatings Market Analysis
Automotive OEMs is rotating demand toward high-durability coated fabrics for electric vehicle interiors, displacing traditional upholstery buyers in volume terms. Covestro AG leverages its polymer science heritage to supply specification-grade polyurethane coating resins to tier-one seat suppliers. Clariant AG anchors pigment and additive formulations that meet automotive fogging and flame-retardancy standards. Huntsman International LLC competes through differentiated elastomeric coating technologies for abrasion-resistant automotive textiles.
Textile coatings constitute polymer-based surface treatments applied to woven, knitted, or nonwoven substrates through knife-over-roll, dip, or spray processes, typically yielding add-on weights of 20–200 g/m² to impart water resistance, flame retardancy, or antimicrobial protection for industrial, transportation, and consumer applications. Polyurethane coatings dominate technical applications where elasticity and hydrolysis resistance command premium positioning, while silicone formulations occupy niche medical and extreme-temperature segments with higher margin structures. The coating technology segment sustains the largest installed equipment base, though laminating is displacing conventional coating in automotive interior programs requiring multi-layer barrier performance.
REACH restrictions on solvent-based systems and the EU Green Deal carbon-border adjustments are forcing European formulators to validate bio-based feedstock chains and waterborne process chemistry. EPA toxics release reporting and OSHA permissible exposure limits for isocyanates shape comparable compliance burdens for US coating operations. Stakeholders must monitor evolving substance restrictions under ECHA SVHC candidate listing and calibrate R&D portfolios between performance equivalence and regulatory pre-emption.
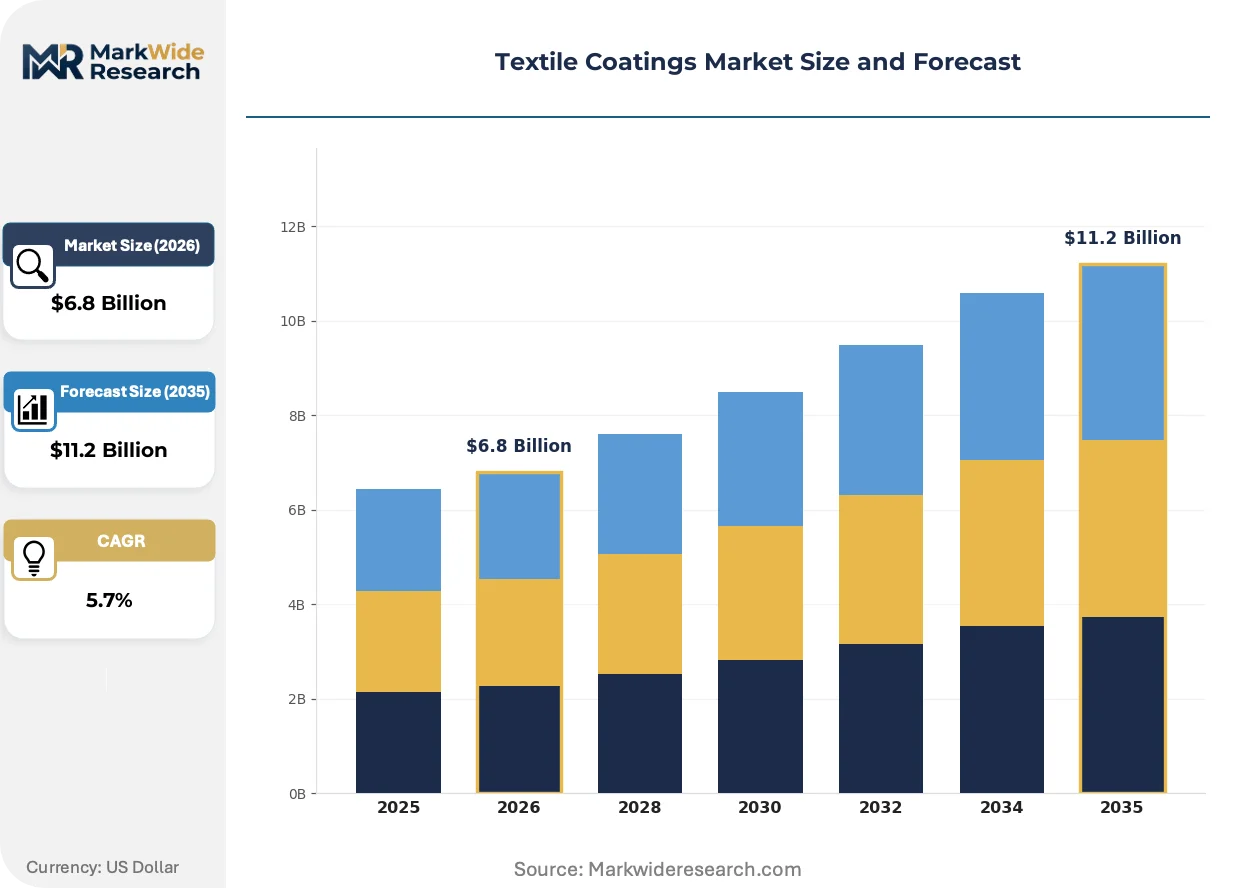
Market Dynamics
REACH solvent restrictions and EU Green Deal carbon-border adjustments are forcing formulators to abandon conventional coating chemistry, redirecting R&D investment toward waterborne and bio-based validation pipelines.
Growth Catalysts
- Automotive lightweighting mandates:OEMs specify coated textiles for EV interior components to reduce vehicle mass, displacing heavier traditional upholstery systems in procurement volumes.
- REACH Annex XVII restrictions:European solvent-phase coating bans accelerate waterborne polyurethane adoption, creating first-mover advantage for compliant formulation houses.
- Technical textile clustering:Stuttgart and Frankfurt industrial corridors concentrate specification-grade coating demand, enabling supplier scale economies and co-development partnerships with tier-one seat manufacturers.
Market Restraints
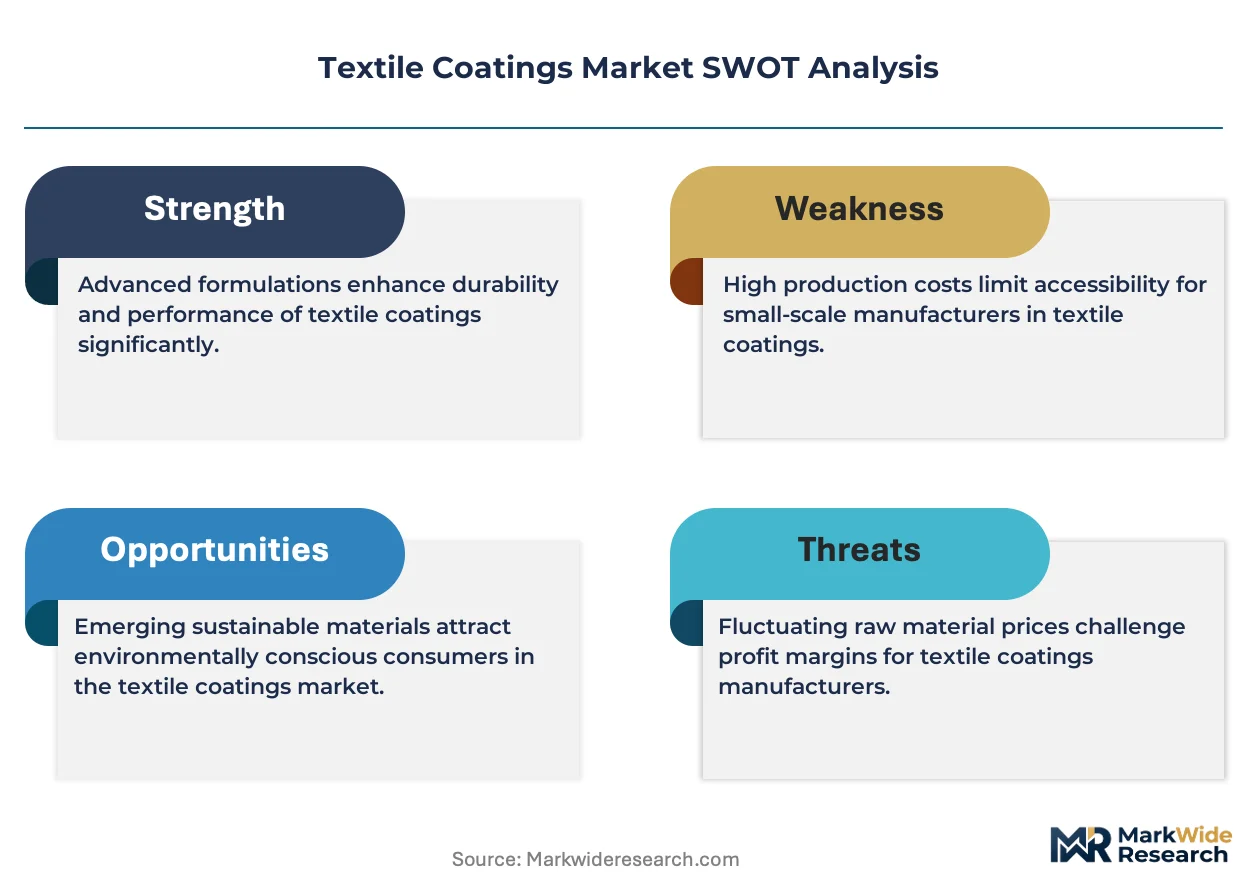
- Petrochemical feedstock volatility:Polyurethane precursor costs fluctuate with propylene and MDI spot markets, compressing margin predictability for coating operations.
- Isocyanate exposure limits:OSHA permissible exposure ceilings for TDI and MDI force capital-intensive ventilation and PPE compliance across US production facilities.
- Performance equivalence gaps:Bio-based polyurethane alternatives currently exhibit inferior hydrolysis resistance versus fossil-derived benchmarks, limiting technical textile qualification rates.
Strategic Opportunities
- Medical textile expansion:Silicone-coated antimicrobial fabrics for surgical drapes and gowns offer premium margin structures in underpenetrated healthcare verticals.
- EU Green Deal carbon border adjustments:CBAM implementation rewards European producers with verified bio-based supply chains, disadvantaging import competition from non-compliant origins.
- Digital coating control:Inline spectroscopic monitoring converges with AI-driven viscosity adjustment, enabling real-time quality assurance and reduced material waste.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in waterborne polyurethane rheology and bio-based monomer compatibility remains concentrated among retiring technical cohorts.
- ECHA SVHC notification timelines:Candidate substance listing creates unpredictable reformulation cycles, requiring contingency R&D expenditure before final regulatory determinations.
- Legacy equipment retrofit costs:Converting solvent-based coating lines to waterborne operation demands drying system overhaul and infrared curing installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Coatings Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Acrylic, Silicone, PVC Application: Apparel, Upholstery, Automotive, Industrial End User: Textile Manufacturers, Fashion Brands, Automotive OEMs, Home Decor Technology: Coating, Laminating, Printing, Finishing |
| Companies Covered | Huntsman International LLC, Clariant AG, Covestro AG, Akzo Nobel N.V., Arkema SA, BASF SE, The Lubrizol Corporation, PPG Industries Inc., Solvay SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Coatings Market Emerging Trajectories
Active chemistry substitution, regulatory chemistry migration, and procurement specification tightening are converging to reshape competitive capability requirements across formulation and application technology.
Waterborne polyurethane coating systems are supplanting solvent-based analogs in automotive interior programs, with tier-one seat suppliers accelerating qualification timelines to meet OEM sustainability scorecard requirements. This chemistry migration compresses the viable supplier base to those with validated low-VOC process capability.
ECHA REACH restrictions on N-methyl-2-pyrrolidone and other process solvents force European formulators to revalidate entire raw material qualification chains. Technical textile producers in Germany and Italy are responding by consolidating procurement relationships with resin suppliers possessing certified green chemistry portfolios.
Specification-driven buying patterns now dominate automotive and medical textile segments, with OEM technical teams embedding coating performance criteria directly into component sourcing contracts. Tier-one suppliers in Germany report extended qualification cycles but reduced price sensitivity once approved formulations achieve production scale.
Textile Coatings Market Segmentation
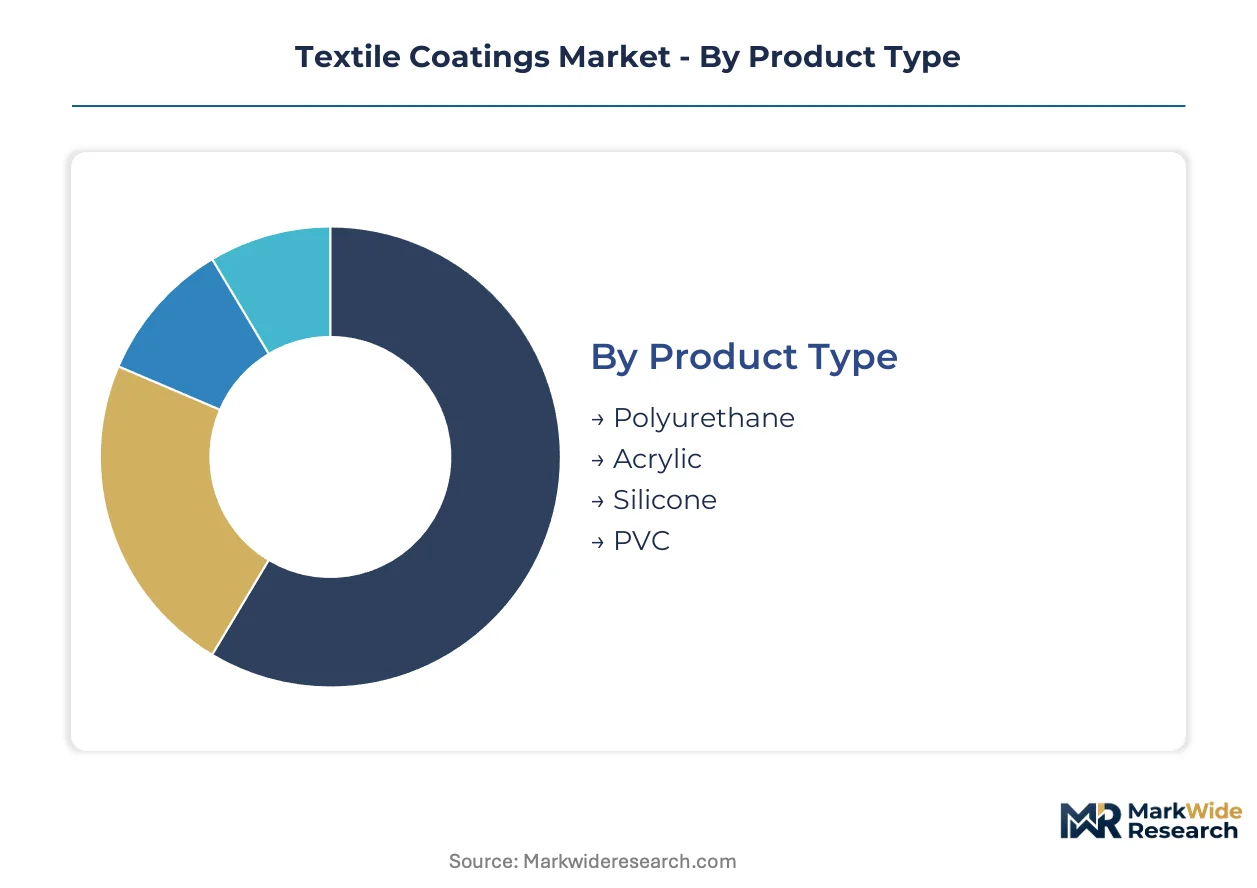
Segmentation in textile coatings reveals how formulation chemistry, application method, and end-use specifications create distinct margin architectures. Procurement patterns diverge sharply between specification-driven automotive programs and price-sensitive apparel finishing, reshaping supplier capability requirements across each slice.
Product Type:
Polyurethane commands premium positioning through elasticity and hydrolysis resistance specifications, while silicone and acrylic formulations occupy differentiated margin tiers based on temperature tolerance and cost-performance tradeoffs.
- Polyurethane:Thermoset polymer systems deliver superior abrasion resistance and flex durability for technical textile applications. Demand concentrates in automotive seating programs across Germany and Italy, where OEM sustainability scorecards now mandate waterborne formulation validation before supplier qualification.
- Silicone:Cross-linked polysiloxane coatings provide extreme temperature stability and biocompatibility for medical textile segments. Surgical drape and gown manufacturers in the United States specify silicone antimicrobial finishes, though higher raw material costs limit penetration in mainstream industrial applications.
- Acrylic:Water-dispersible polymer emulsions offer cost-competitive UV resistance for outdoor fabric applications.
- PVC:Plasticized polyvinyl chloride systems retain volume in tarpaulin and protective covering segments despite REACH pressure on plasticizer chemistries.
Polyurethane holds installed capacity. Silicone is rotating up the share rankings.
Application:
Automotive procurement specifications now embed coating performance criteria directly into component sourcing contracts, creating qualification barriers that apparel and home decor segments rarely replicate.
- Automotive:Tier-one seat suppliers specify coated textiles for EV interior lightweighting initiatives, with Stuttgart and Frankfurt industrial corridors driving specification-grade volumes. REACH Annex XVII solvent restrictions accelerate waterborne polyurethane adoption, compressing the viable supplier base to compliant formulation houses.
- Industrial:Protective fabrics for construction, agriculture, and logistics require flame-retardant and chemical-resistant coatings. German technical textile clusters source industrial coated fabrics through consolidated procurement relationships with resin suppliers possessing certified green chemistry portfolios.
- Apparel:Weatherproof outerwear and performance sportswear drive water-repellent finishing demand.
- Upholstery:Residential and commercial furniture applications favor cost-optimized acrylic and PVC coating systems.
Automotive captures the steepest expansion trajectory. Industrial maintains the broadest geographic footprint.
End User:
Automotive OEMs now displace traditional upholstery buyers in volume terms, rotating procurement toward high-durability coated fabrics with embedded sustainability compliance requirements.
- Automotive OEMs:Electric vehicle programs specify coated textile interior components to reduce vehicle mass, with technical teams embedding coating performance criteria into sourcing contracts. Extended qualification cycles in Germany reduce price sensitivity once approved formulations achieve production scale.
- Textile Manufacturers:Weaving and knitting operations apply coating as a value-add finishing step, with technical capabilities concentrated among European producers navigating ECHA SVHC notification timelines.
- Fashion Brands:Outerwear and performance apparel labels specify water-repellent and breathable coating finishes.
- Home Decor:Residential furnishing brands source coated fabrics for upholstery and drapery applications.
Automotive OEMs drive specification-grade volume. Textile manufacturers control the largest installed coating capacity base.
Technology:
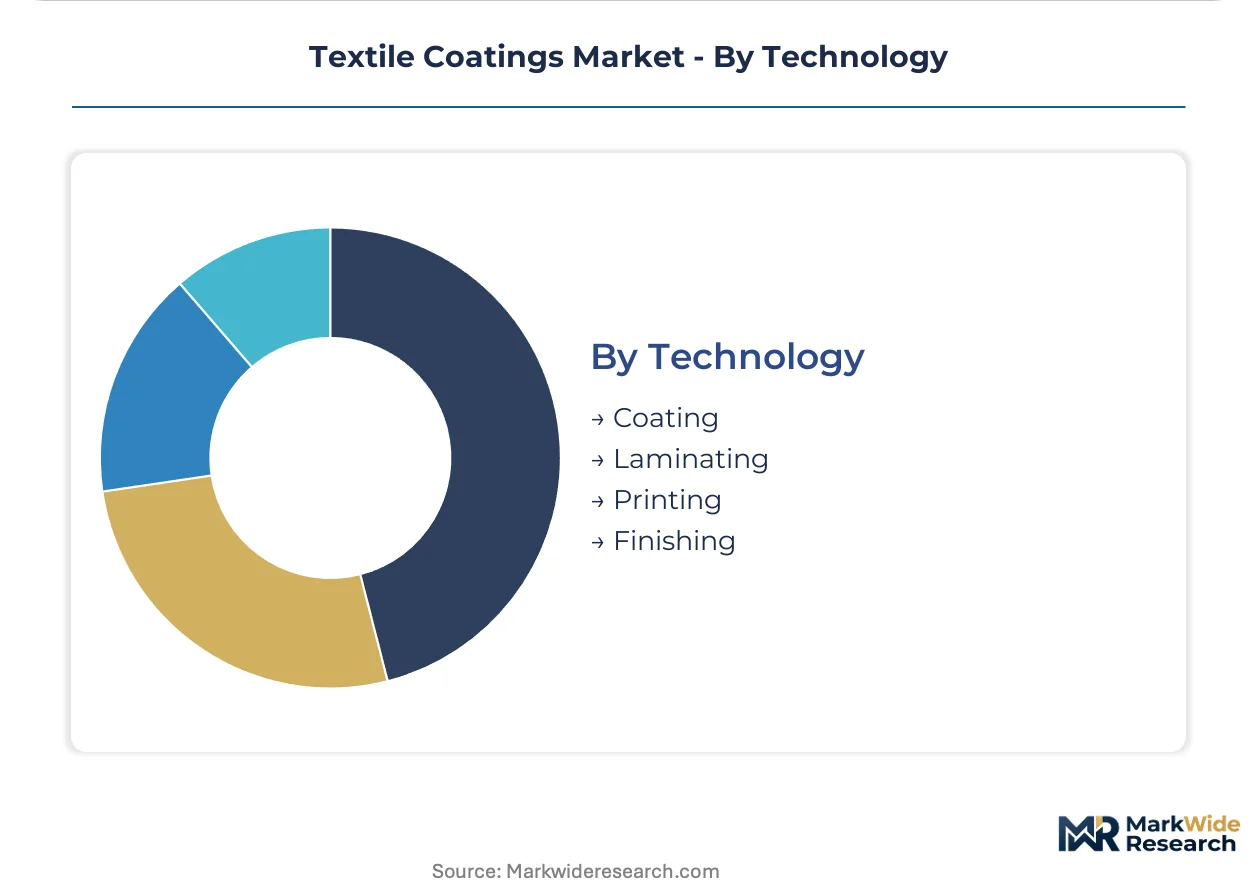
Coating sustains the largest installed equipment base, though laminating displaces conventional coating in automotive interior programs requiring multi-layer barrier performance.
- Coating:Knife-over-roll, dip, and spray processes apply polymer-based surface treatments yielding add-on weights of 20–200 g/m². The installed base concentrates in Germany and Italy, where legacy solvent-based lines face costly retrofit demands for waterborne conversion.
- Laminating:Multi-layer bonding creates barrier performance for automotive seating and medical textile applications. Tier-one suppliers accelerate qualification timelines to meet OEM requirements, with Stuttgart-based manufacturers leading adoption of hot-melt and flame lamination systems.
- Printing:Rotary and flatbed systems apply decorative and functional surface patterns.
- Finishing:Chemical and mechanical post-treatments modify hand feel and performance characteristics.
Coating retains the deepest installed base. Laminating is climbing the fastest in share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German coating formulators export specification-grade polyurethane systems to automotive tier-one suppliers across Italy, France, and Poland. This trade corridor channels REACH-compliant chemistry toward Southern and Eastern European assembly plants.
Germany
Stuttgart and Frankfurt industrial corridors concentrate technical textile coating demand for EV interior programs. REACH Annex XVII solvent restrictions accelerate waterborne polyurethane validation pipelines among formulators. Baden-Württemberg coating operations supply tier-one seat manufacturers with specification-grade resins.
Italy
Automotive upholstery producers in Piedmont and Lombardy source coated fabrics for premium vehicle interiors. ECHA SVHC notification timelines force reformulation cycles among resin importers. Milan-based technical textile clusters consolidate procurement with certified green chemistry suppliers.
United States
OSHA permissible exposure limits for isocyanates drive ventilation upgrades across coating facilities in Michigan and Ohio. EPA toxics release reporting shapes compliance burdens for polyurethane operations. Detroit-area automotive suppliers specify coated textiles for lightweighting initiatives.
China
MIIT industrial standards for volatile organic compound emissions redirect coating chemistry toward waterborne systems in Jiangsu and Zhejiang provinces. Yangtze River Delta textile manufacturers supply domestic automotive OEMs with specification-grade coated fabrics. Shanghai-based formulators validate bio-based feedstock alternatives.
India
BIS certification requirements for automotive interior materials concentrate coating demand around Chennai and Pune manufacturing corridors. PLI scheme incentives attract technical textile investments with integrated coating capability. Tamil Nadu producers supply domestic OEMs and export markets.
Textile Coatings Market Vendor Landscape
Listed leaders compete with private specialists across formulation chemistry and application technology dimensions. The supplier base organizes into three tiers: multinational resin producers with polymer science heritage, regional coating specialists with validated OEM qualification, and captive operations within integrated textile manufacturers. Consolidation pressures favor scale players with waterborne process capability and certified bio-based supply chains. Competitive moves center on portfolio diversification into medical textile segments and strategic partnerships with tier-one automotive suppliers.
Within the multinational resin tier, Covestro AG and Clariant AG exemplify archetypes of polymer science heritage and pigment-additive specialization respectively. Huntsman International LLC occupies a position among differentiated elastomeric technology providers. These three entities represent the dominant competitive anchors against which regional specialists calibrate qualification timelines and sustainability scorecard compliance.
| Leading Market Players |
|---|
| Huntsman International LLC |
| Clariant AG |
| Covestro AG |
| Akzo Nobel N.V. |
| Arkema SA |
| BASF SE |
| The Lubrizol Corporation |
| PPG Industries Inc. |
| Solvay SA |
| Others |
Supply Flow & Price Mechanics
REACH Annex XVII solvent restrictions gate both supplier qualification and price differentiation simultaneously, compressing margins for non-compliant formulators while rewarding validated waterborne chemistry with premium positioning in automotive procurement programs.
Pricing Analysis
Solvent-based polyurethane coatings, waterborne polyurethane systems, and emerging bio-based alternatives stratify across distinct pricing tiers based on formulation complexity and compliance certification. Price differentiation rests on REACH validation status and automotive OEM qualification tier, with specification-grade resins commanding substantial premiums over commodity industrial grades. Cost compression in conventional solvent-based tiers is intensifying because of feedstock volatility in MDI and propylene markets. Apparel and home decor segments exhibit the highest price sensitivity, while automotive tier-one suppliers demonstrate reduced price sensitivity once formulations achieve production-scale approval.
Supply Chain Analysis
Propylene oxide and MDI feedstock transit through Rotterdam and Antwerp port complexes anchors European coating resin supply security. Manufacturing gravity centers on Germany, Italy, and China, with Baden-Württemberg and Lombardy clusters feeding automotive upholstery demand while Jiangsu province supplies domestic Chinese OEMs. Raw material dependencies include petrochemical precursors, bio-based polyols, and specialty isocyanates. Single-source vulnerability concentrates in MDI supply chains dominated by limited global producers. Distribution runs through tier-one seat manufacturer direct contracts and technical textile converter networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against laminating technology substitution, which threatens to displace conventional coating in multi-layer automotive barrier applications.
For Market Incumbents: Secure waterborne process capability through drying system retrofit and infrared curing installation to maintain automotive qualification status. Anchor backward integration into bio-based polyol supply chains to preempt REACH carbon-border adjustment exposure. Defensive consolidation around Stuttgart and Frankfurt technical textile clusters will concentrate scale economies against regional specialists. For New Entrants and Emerging Players: EU Ecolabel fast-track certification opens procurement channels among Milan-based technical textile producers seeking green chemistry portfolio validation. Target medical textile segments in the United States, where silicone-coated antimicrobial fabrics remain underpenetrated and specification barriers are lower than automotive. A direct technical sales model to surgical drape manufacturers bypasses entrenched automotive supply relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across waterborne conversion capex cycles, favoring acquirers with balance-sheet capacity to fund legacy line retrofits. Acquisition targets should display validated OEM qualification timelines and certified bio-based feedstock chains. Monitor ECHA SVHC candidate listing velocity as the inflection signal for contingent reformulation expenditure cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne Process Conversion | REACH Annex XVII compliance secures automotive procurement qualification and sustains margin premiums. |
| Bio-based Feedstock Validation | EU Green Deal carbon-border adjustments reward verified supply chains with competitive positioning. |
| Medical Textile Portfolio Entry | Silicone-coated antimicrobial fabrics access premium margin structures in underpenetrated healthcare verticals. |
| Tier-One Supplier Partnership | Co-development relationships with Stuttgart seat manufacturers embed specifications into long-term contracts. |
| Digital Coating Control Deployment | Inline spectroscopic monitoring with AI-driven viscosity adjustment reduces material waste and quality variance. |
Methodological Framework
Desk research of customs trade databases, ECHA regulatory filings, and SEC chemical company disclosures preceded structured interviews with coating formulator R&D directors, tier-one automotive seat procurement managers, and technical textile plant engineers. Primary fieldwork across Stuttgart, Milan, and Shanghai industrial corridors validated secondary estimates of waterborne adoption rates and qualification timeline durations. Bottom-up capacity assessments triangulated against top-down demand modeling from automotive production forecasts.
Variance decomposition across product type, application method, and end-use specification dimensions shaped the analytical framework over the projection horizon. Segmentation modeling incorporated formulation chemistry grade, OEM qualification tier, and regional regulatory cluster as core dimensions. CAGRs derived from trend extrapolation of historical adoption curves, adjusted for regulatory inflection points and technology substitution thresholds. Industry-specific inputs included MDI price volatility indices and automotive lightweighting content-per-vehicle trajectories.
Underlying assumptions cover sustained REACH enforcement stringency and waterborne performance equivalence achievement, with deviation risk concentrated in bio-based hydrolysis resistance qualification failures and isocyanate regulatory tightening. Forecasts reflect these boundary conditions; outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Chemical Resistant Coatings Market
Coatings
Global Anti-Smudge Coatings Market
Coatings
Global Polyaspartic Coatings Market
Coatings
Electron Beam Curable Coating Market
Coatings
Global Hydrophobic Coating Market
Coatings
Global Fusion Bonded Epoxy Coatings Market
Coatings
Camouflage Coatings Market
Coatings
France Automotive OEM Coatings Market
Coatings
Corrosion Protective Coatings and Acid Proof Lining Market
Coatings
Global PET Film Coated Steel Coil Market
Coatings
Waterborne Automobile Coating Market
Coatings
Powder Coating Booth Market
Coatings
Asia-Pacific Protective Coatings Market
Coatings
Vinyl Surface Coatings Market
Coatings
Global Sputter Coatings Market
Coatings
Acrylic Coating Market