
 United Arab Emirates Protective Coatings Market | 2026-2036
United Arab Emirates Protective Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Protective Coatings Market Analytics
Domestic blending capacity in the Gulf Cooperation Council is rebalancing as localized resin sourcing expands. Jotun leverages its marine certification portfolio to anchor premium supply contracts across UAE shipyards and offshore yards. Hempel A/S sustains its position through specialized anti-corrosion formulations for the region's sour gas processing infrastructure. National Paints Factories Co. Ltd. competes on proximity, operating manufacturing assets within the Emirates that reduce import lead times for construction sector buyers.
Protective coatings are engineered film-forming systems comprising binders, pigments, extenders, and functional additives that cure to provide barrier protection against corrosion, chemical attack, and thermal degradation on metal and concrete substrates. Epoxy systems dominate the product type landscape due to their adhesion strength and chemical resistance in petrochemical environments, while water-based technology gains regulatory momentum as MOHAP and municipal environmental guidelines tighten solvent emissions across industrial facilities. The oil and gas end user segment commands the deepest specification requirements, whereas construction applications drive volume throughput across standard architectural protection grades.
MOHAP environmental regulations, Abu Dhabi Quality and Conformity Council standards, and Emirates Authority for Standardization and Metrology specifications collectively mandate VOC thresholds, fire resistance ratings, and coating durability benchmarks that determine product market access. Compliance with these frameworks now requires reformulation investments that favor suppliers with in-house technical service laboratories stationed in the Emirates. Stakeholders must monitor the pace of green building code adoption in Dubai and Abu Dhabi, as these codes will determine whether premium-certified systems capture incremental margin or standard grades retain volume dominance across project portfolios.
Market Dynamics
MOHAP's solvent emission thresholds are compressing formulation cycles across UAE manufacturing facilities, forcing rapid water-based system qualification timelines that favor suppliers with in-country technical service laboratories.
Growth Catalysts
- Offshore Infrastructure Expansion:Abu Dhabi's sour gas field development is generating specification-grade coating procurement for subsea pipelines and platform superstructures. Petrochemical operators are mandating 25-year corrosion protection warranties.
- MOHAP VOC Compliance Deadlines:The Ministry of Health and Prevention's 2025 emission reduction targets are accelerating solvent-to-water-based transitions across industrial coating facilities in Dubai and Sharjah.
- Maritime Cluster Concentration:Dry dock maintenance cycles at Jebel Ali and Khalifa Port are consolidating demand for IMO-certified anti-fouling and tank coating systems.
Market Restraints
- Epoxy Resin Import Dependency:Bisphenol-A and amine hardener supply chains remain concentrated in Asian manufacturing hubs, exposing UAE blenders to freight rate volatility and extended lead times.
- Specialized Applicator Scarcity:NACE-certified coating inspectors and spray application technicians command premium wages, constraining project execution velocity for complex industrial assets.
- Water-Based Performance Gaps:Current-generation low-VOC formulations exhibit inferior chemical resistance in high-temperature hydrocarbon exposure environments compared to solvent-borne epoxies.
Strategic Opportunities
- Ras Al Khaimah Manufacturing Zone:Underutilized industrial land and port access present greenfield blending facility opportunities with proximity to northern emirates construction demand.
- Green Building Code Alignment:Dubai Municipality's Al Sa'fat sustainability rating system creates specification pathways for low-emission coating systems in premium commercial developments.
- Nano-Additive Integration:Graphene-reinforced and self-healing polymer technologies are opening differentiation margins in high-value offshore maintenance contracts.
Industry Challenges
- Qualification Timeline Compression:ADNOC's accelerated project schedules are compressing coating system approval cycles from 18 months to 8 months, straining supplier laboratory capacity.
- Substrate Preparation Standards:Inconsistent surface cleanliness compliance across contractor tiers is generating premature coating failure disputes and warranty claim complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Protective Coatings Market |
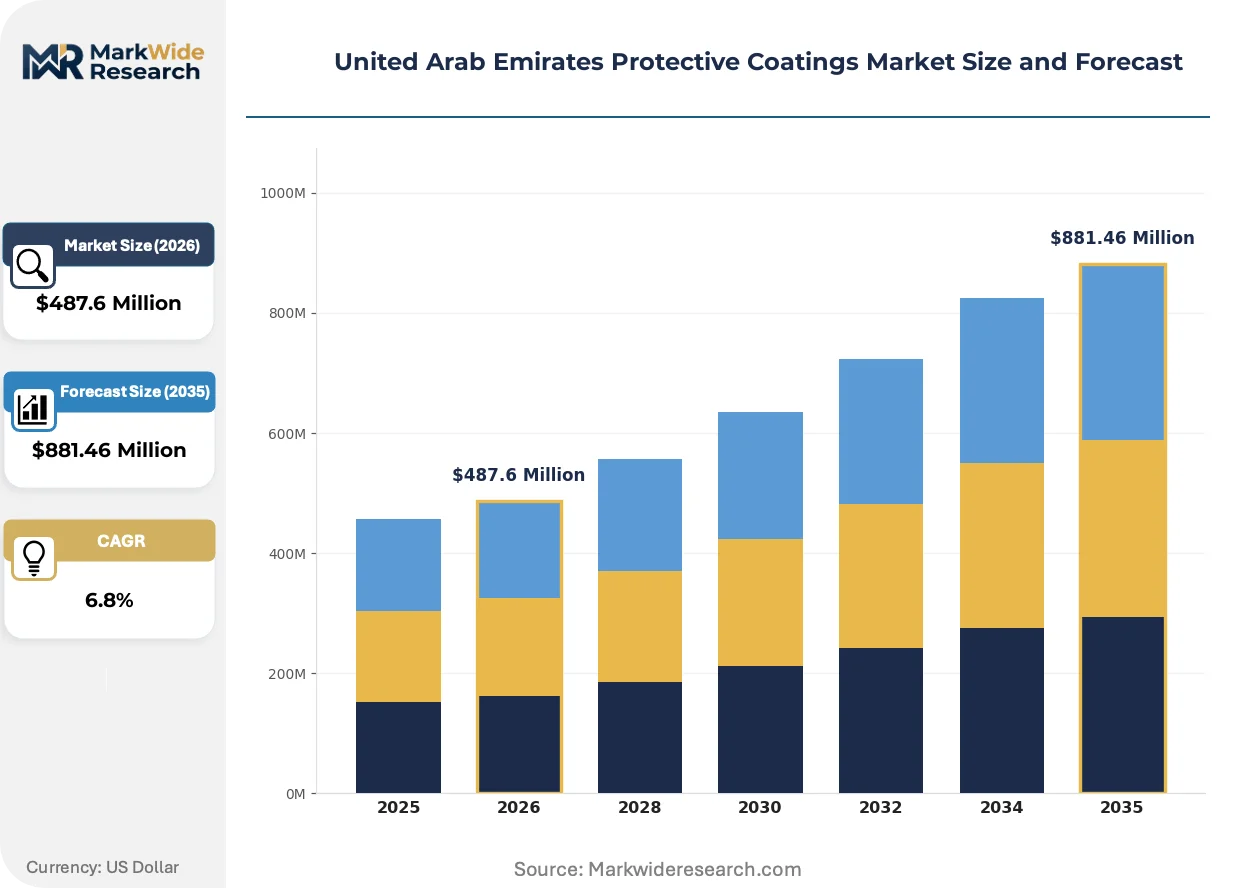
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Acrylic, Zinc End User: Construction, Automotive, Marine, Oil & Gas Technology: Water-Based, Solvent-Based, Powder Coating, UV-Cured Application: Corrosion Protection, Aesthetic Coating, Fire Protection, Anti-Fouling |
| Companies Covered | Akzo Nobel N.V., Jotun, Nippon Paint Holdings Co., Ltd., Sigma Paints, The Sherwin-Williams Company, National Paints Factories Co. Ltd., Hempel A/S, PPG Industries, Berger Paints India Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Protective Coatings Market Evolving Landscape
Formulation science and application methodology are converging around performance verification systems that compress qualification timelines while extending asset protection intervals in harsh Gulf operating environments.
Polyaspartic and polysiloxane topcoat systems are modularizing project execution for UAE offshore operators. These fast-cure chemistries enable return-to-service windows under 24 hours for platform maintenance campaigns. ADNOC and international asset managers are specifying these systems for living quarters and process equipment where operational downtime carries severe production penalties.
MOHAP's 2025 VOC emission thresholds are mandating reformulation investments across solvent-borne epoxy portfolios. Industrial coating facilities in Jebel Ali Free Zone are retrofitting spray booths and installing carbon capture systems to maintain operating licenses. Water-based epoxy and acrylic technologies are capturing specification share in secondary containment and atmospheric service applications where chemical exposure severity permits.
Asset owners are consolidating coating procurement under integrated maintenance contracts that bundle surface preparation, application, and performance warranties. EPC contractors in Abu Dhabi's industrial zones are absorbing coating scope to reduce interface risk on lump-sum projects. This bundling is compressing standalone coating distributor margins while favoring applicators with in-house blending capabilities and direct manufacturer relationships.
United Arab Emirates Protective Coatings Market Segmentation
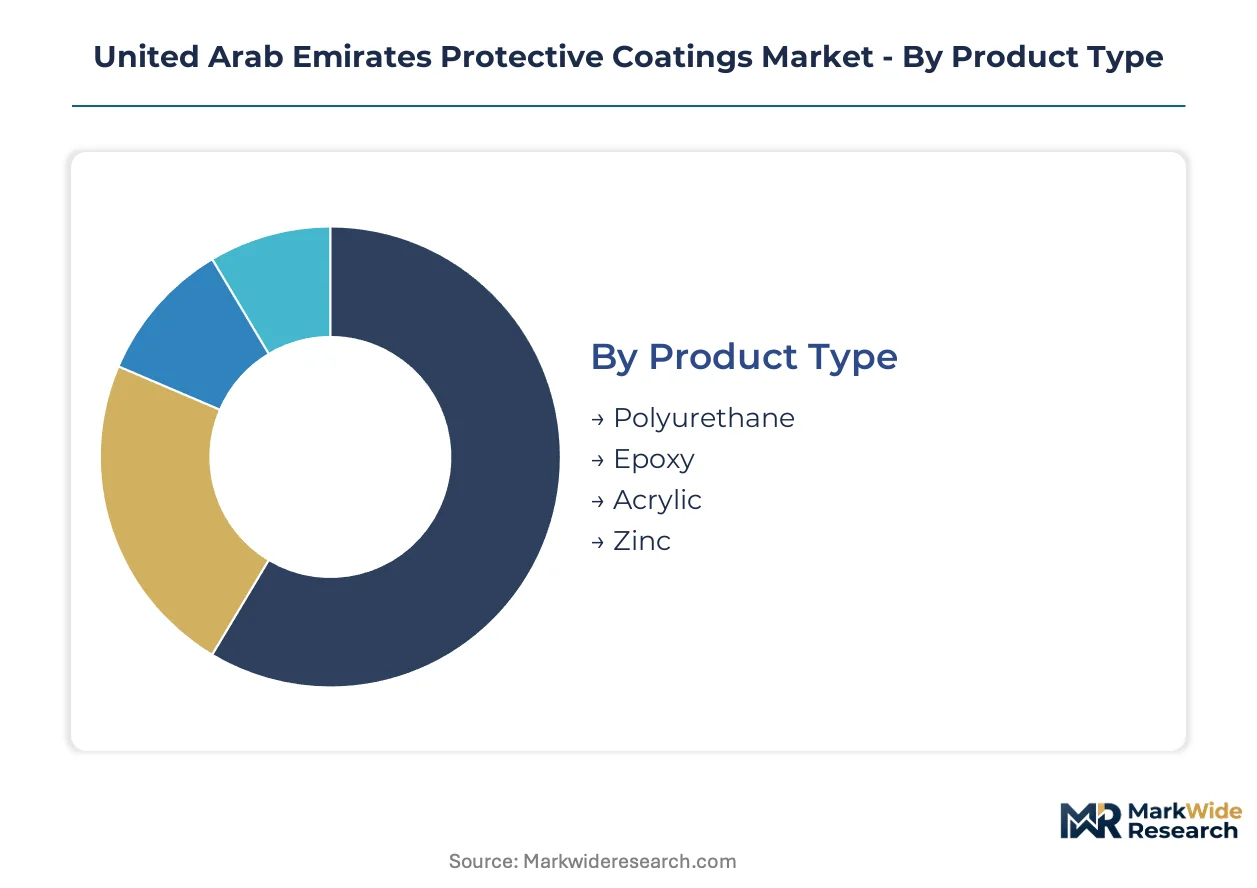
Segmentation in the UAE protective coatings market reveals how specification requirements diverge across petrochemical infrastructure, maritime assets, and commercial construction. Understanding these divisions exposes where procurement budgets concentrate and where regulatory pressure is reshaping technology choices.
Product Type:
Epoxy systems anchor the specification landscape through adhesion chemistry and barrier performance in hydrocarbon exposure environments.
- Epoxy:These thermosetting systems combine bisphenol-A resins with polyamine hardeners to form dense cross-linked films. Demand concentrates in Abu Dhabi's sour gas processing facilities where operators mandate 25-year corrosion protection warranties for subsea pipelines. MOHAP emission thresholds are forcing water-borne epoxy qualification for secondary containment applications.
- Polyurethane:Aliphatic and aromatic isocyanate-cured systems deliver UV stability and abrasion resistance for exterior exposure. Procurement is climbing fastest in Dubai's commercial high-rises where aesthetic durability requirements intersect with Al Sa'fat sustainability scoring for low-VOC facade systems.
- Acrylic:Thermoplastic emulsion systems offer breathable protection for atmospheric service on concrete substrates. Specifications are expanding in Sharjah's residential construction sector where cost-sensitive developers prioritize application speed over chemical resistance.
- Zinc:Inorganic and organic zinc-rich primers provide galvanic protection for steel structures in marine atmospheres. Dry dock operators at Jebel Ali specify these systems for ballast tank refurbishment cycles.
Mature deployment sits with Epoxy. Newer deployment is concentrated in Polyurethane.
End User:
Capital intensity and asset lifespan determine coating specification tiers across UAE industrial sectors.
- Oil & Gas:Exploration and production operators specify high-build epoxy and polysiloxane systems for platform superstructures and processing equipment. ADNOC's accelerated project schedules are compressing coating approval cycles from 18 months to 8 months, straining supplier laboratory capacity in the Emirates.
- Marine:Shipyards and offshore yards demand IMO-certified anti-fouling and tank coating systems. Maintenance cycles at Khalifa Port are consolidating procurement under integrated service contracts that bundle surface preparation and application scope.
- Construction:Standard architectural protection grades drive volume throughput across Dubai and Sharjah building envelopes. National Paints Factories leverages domestic manufacturing assets to reduce import lead times for this price-sensitive segment.
- Automotive:Refinish and OEM coating specifications remain limited in the UAE market, concentrated in luxury vehicle service centers and assembly operations in Dubai Industrial City.
Specification-grade procurement dominates Oil & Gas. Volume throughput concentrates in Construction.
Technology:
Regulatory compliance timelines are forcing formulation transitions that favor suppliers with in-country technical service infrastructure.
- Solvent-Based:Traditional epoxy and alkyd systems retain performance advantages in high-temperature hydrocarbon exposure where water-borne alternatives exhibit chemical resistance gaps. Facilities in Jebel Ali Free Zone are retrofitting spray booths with carbon capture to maintain operating licenses under tightening MOHAP thresholds.
- Water-Based:Acrylic and epoxy emulsion technologies are capturing specification share in atmospheric service and secondary containment applications. Municipal environmental guidelines in Dubai and Sharjah are accelerating qualification timelines for industrial facilities.
- Powder Coating:Thermoset polyester and epoxy-polyester hybrid systems deliver zero-VOC protection for metal fabrications and rebar. Application is expanding in Ras Al Khaimah's construction materials manufacturing zone.
- UV-Cured:Rapid-cure acrylate oligomer systems enable high-throughput coating of flat stock and assembled components. Adoption remains niche in UAE industrial applications due to substrate geometry constraints and capital equipment requirements.
Established infrastructure supports Solvent-Based. Regulatory momentum is accelerating Water-Based.
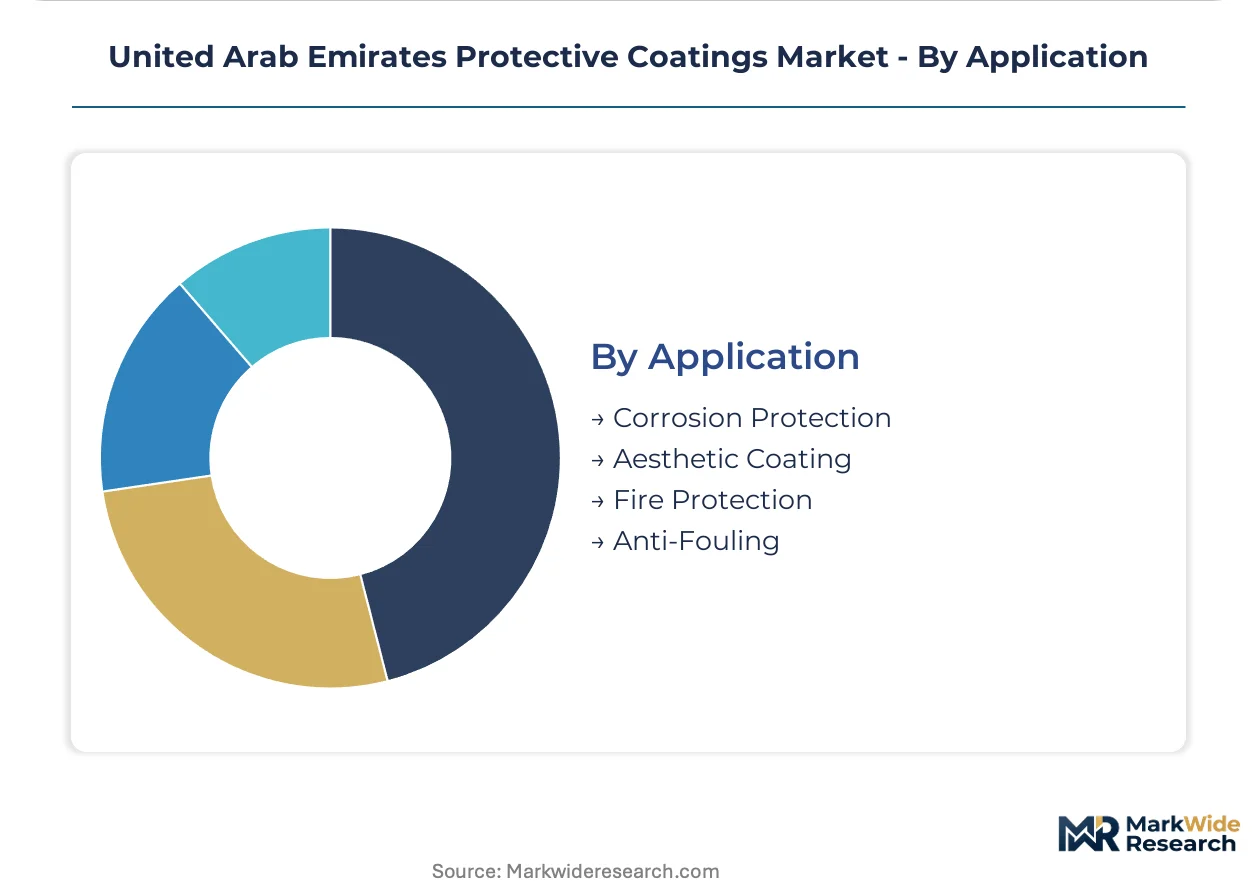
Application:
Functional performance requirements determine binder selection and film thickness specifications across asset categories.
- Corrosion Protection:High-performance barrier and sacrificial coating systems for steel infrastructure in petrochemical and marine environments. ADNOC and international asset managers specify these systems for 25-year protection intervals on subsea pipelines and platform structures.
- Fire Protection:Intumescent and cementitious coating systems that expand under thermal exposure to insulate structural steel. Dubai Municipality building codes mandate these specifications for high-rise commercial developments.
- Anti-Fouling:Biocide-releasing and foul-release coatings for vessel hulls and offshore platform substructures. Dry dock maintenance at Jebel Ali and Khalifa Port drives cyclical demand for IMO-compliant systems.
- Aesthetic Coating:Decorative and color-stable finishes for commercial building envelopes and infrastructure visibility. Al Sa'fat sustainability ratings are creating specification pathways for low-emission systems in premium Dubai developments.
Engineering-critical deployment centers on Corrosion Protection. Sustainability-linked deployment is expanding in Aesthetic Coating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Epoxy resin feedstocks concentrate in Asian manufacturing hubs, exposing UAE blenders to freight volatility while domestic formulation capacity expands across the Emirates.
Abu Dhabi
Sour gas field development and ADNOC infrastructure expansion drive specification-grade coating procurement for subsea pipelines and platform superstructures. MOHAP environmental guidelines mandate VOC emission reductions across industrial facilities in the emirate. The Ruwais industrial complex anchors petrochemical clustering where 25-year corrosion protection warranties dominate procurement criteria.
Dubai
Commercial high-rise construction and maritime maintenance cycles at Jebel Ali generate dual demand streams for aesthetic facade systems and IMO-certified anti-fouling coatings. Dubai Municipality's Al Sa'fat sustainability rating system creates specification pathways for low-emission coating systems in premium developments. Jebel Ali Free Zone facilities are retrofitting spray booths with carbon capture systems to maintain operating licenses.
Sharjah
Residential construction sector growth drives volume throughput for cost-sensitive architectural protection grades. Municipal environmental guidelines accelerate water-based epoxy qualification timelines for industrial coating facilities. National Paints Factories leverages domestic manufacturing assets to reduce import lead times for construction sector buyers concentrated in the emirate's building materials distribution corridors.
Northern Emirates
Ras Al Khaimah's underutilized industrial land and port access present greenfield blending facility opportunities with proximity to construction demand across Ajman, Fujairah, and Umm Al Quwain. Powder coating application is expanding in the emirate's construction materials manufacturing zone. The zone's thermoset polyester systems deliver zero-VOC protection for metal fabrications serving regional infrastructure projects.
United Arab Emirates Protective Coatings Market Competitive Landscape
Global majors compete with regional champions across certification depth and proximity-to-market dimensions. The vendor base stratifies between premium specification-grade suppliers and volume-focused domestic blenders. Three archetypes dominate: marine-certified specialists with offshore yard relationships, petrochemical-focused formulators with sour gas expertise, and construction-optimized manufacturers with shortened import lead times. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualification timelines compress.
Within the marine-certified tier, Jotun and Hempel A/S exemplify specification-grade positioning through offshore yard anchoring and anti-corrosion formulation depth. National Paints Factories Co. Ltd. occupies the domestic manufacturing archetype, leveraging Emirates-based production assets to serve construction sector volume demand. Akzo Nobel N.V. represents the diversified multinational structure competing across multiple end-use segments with broad technology portfolios.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| Jotun |
| Nippon Paint Holdings Co., Ltd. |
| Sigma Paints |
| The Sherwin-Williams Company |
| National Paints Factories Co. Ltd. |
| Hempel A/S |
| PPG Industries |
| Berger Paints India Limited |
| Others |
Value Network & Pricing Analysis
NACE-certified coating inspectors and spray application technicians in the Emirates command premium wages that widen spreads between specification-grade and standard-tier pricing. Labor-cost differentials between certified applicator pools in Abu Dhabi's industrial zones and generalist contractors in Sharjah's construction corridors translate into three-tier pricing structure across premium, standard, and economy levels for protective coating systems.
Pricing Analysis
Warranty bundling separates project-based coating procurement from standalone material supply, with ADNOC's 25-year corrosion protection warranties commanding substantial premiums over unbundled specifications. Price differentiation hinges on certification depth (IMO marine compliance, NACE inspection protocols) and volume scale, with construction sector buyers in Dubai and Sharjah exhibiting highest price sensitivity. Cost compression in standard architectural grades is intensifying because National Paints Factories' domestic manufacturing assets reduce import lead times and enable aggressive positioning against imported alternatives.
Supply Chain Analysis
Epoxy resin feedstocks rest on Asian specialty chemical producers in China, South Korea, and Japan, exposing UAE blenders to freight rate volatility. Bisphenol-A, amine hardeners, and zinc dust pigments anchor formulation costs, with single-source vulnerability concentrated in high-purity resin grades for sour gas applications. Distribution runs through Jebel Ali Free Zone blending facilities and direct manufacturer relationships with EPC contractors, bypassing traditional distributor tiers as procurement consolidates under integrated maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE protective coatings market has become a vertical-integration race, with players pursuing backward integration into resin sourcing to secure supply continuity and margin control amid Asian import dependency.
For Market Incumbents: To counter compressed qualification timelines from ADNOC's accelerated project schedules, expand in-country technical service laboratory capacity in Abu Dhabi and Dubai. Deepen backward integration into captive epoxy resin blending to reduce exposure to Asian freight volatility and extend formulation control over water-based system transitions mandated by MOHAP thresholds. For New Entrants and Emerging Players: Launch via Ras Al Khaimah greenfield manufacturing assets with proximity to northern emirates construction demand and underutilized industrial land. Target powder coating application for zero-VOC metal fabrications in the emirate's construction materials zone, leveraging municipal environmental guidelines to displace solvent-based alternatives in cost-sensitive segments. For Investors and Strategic Acquirers: The window for entry favors domestic manufacturing archetypes with Emirates-based production assets and shortened import lead times. Monitor ADNOC's coating system approval cycle compression as the inflection indicator for laboratory capacity scarcity and technical service infrastructure value accretion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Sourcing | Captive bisphenol-A supply secures formulation continuity against Asian freight volatility. |
| In-Country Technical Service Laboratory Expansion | Abu Dhabi and Dubai facilities compress ADNOC qualification timelines from 18 months to 8 months. |
| Water-Based System Reformulation Investment | MOHAP emission thresholds mandate solvent-to-water transitions across Jebel Ali Free Zone facilities. |
| Integrated Maintenance Contract Bundling | EPC contractors in Ruwais absorb coating scope to reduce interface risk on lump-sum projects. |
| Nano-Additive Technology Partnership | Graphene-reinforced formulations open differentiation margins in high-value offshore maintenance. |
Research Methodology
Multi-period observation of coating system qualification timelines, MOHAP regulatory enforcement patterns, and ADNOC procurement contract structures anchored the trend analysis, supplemented by interviews with plant managers at UAE blending facilities, procurement leads at EPC contractors, technical R&D directors at global coating suppliers, and NACE-certified inspection firms. Secondary validation drew from customs and trade data, SEC 10-K filings of listed coating manufacturers, Emirates Authority for Standardization and Metrology specifications, and Abu Dhabi Quality and Conformity Council standards. Bottom-up volume modeling across emirate-level construction permits and oilfield development announcements was triangulated against top-down market sizing from identified supplier revenue disclosures.
Input-output matrices mapped epoxy resin feedstock flows from Asian manufacturing hubs through Jebel Ali Free Zone blending capacity to end-use demand across oil and gas, marine, and construction segments. Modeled dimensions spanned product type (epoxy, polyurethane, acrylic, zinc), end-user industry, technology platform, and emirate-level geographic clustering. CAGRs were derived from regression analysis of historical procurement patterns against projected infrastructure investment schedules, with water-based technology transition rates and IMO marine certification adoption curves serving as key forecast sensitivity inputs.
The model assumes a particular technology adoption path; alternative pathways for solvent-based epoxy retention in high-temperature hydrocarbon environments would alter the outlook if water-based performance gaps persist beyond MOHAP compliance deadlines. Forecasts reflect assumptions regarding ADNOC project acceleration, freight rate stability in Asian resin supply chains, and municipal green building code enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Noise and Vibration Coatings Market
Coatings
Global Graphite Coatings Market
Coatings
Global Hydrophobic Coating Market
Coatings
France Automotive OEM Coatings Market
Coatings
ASEAN Automotive OEM Coatings Market
Coatings
Europe Anti-Friction Coatings Market
Coatings
Waterborne Wood Coatings Market
Coatings
Flexible Waterproof Coating Market
Coatings
North America Superhydrophobic Coating Market
Coatings
France Protective Coatings Market
Coatings
South Africa Protective Coatings Market
Coatings
Canada Automotive OEM Coatings Market
Coatings
Anti-Graffiti Coatings Market
Coatings
Transparent Conductive Coatings Market
Coatings
2K Coatings Market
Coatings
Vacuum Coating Machine Market