
 Aerospace Filter Market | 2026-2036
Aerospace Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Filter Market Analysis
Defense procurement offices are collapsing historical lead times for filter replacements as military aviation fleets expand sustainment budgets. Parker Hannifin Corporation leverages its vertical integration across hydraulic and fuel filtration systems to anchor Pentagon supply chains. Donaldson Company, Inc. competes through specialized engine air intake solutions for tactical aircraft. Safran sustains European military and commercial dual-use positioning with differentiated cabin air technologies.
An aerospace filter is a precision-engineered porous medium, typically constructed from glass microfiber, PTFE membrane, or sintered metal mesh with pore ratings from 0.1 to 100 microns, designed to remove contaminants from air, fuel, or hydraulic fluid in flight-critical systems. HEPA filters dominate cabin air quality applications where ASHRAE and aircraft OEM standards mandate 99.97% efficiency at 0.3 microns. Activated carbon filters capture volatile organic compounds and ozone in recirculated cabin air, a segment where nanofiltration technology is displacing conventional adsorption in next-generation platforms. Fuel filtration systems utilizing microfiltration occupy the most concentrated margin pool due to engine OEM qualification barriers and recurring overhaul cycles.
The FAA mandates compliance with 14 CFR Part 25.831 for cabin ozone and ventilation standards, while the EASA CS-25 certification framework enforces equivalent particulate limits for European-registered aircraft. EPA regulations on aircraft emissions indirectly shape filter efficiency requirements as engine manufacturers tighten intake cleanliness specifications to meet combustion standards. Stakeholders must monitor evolving military airworthiness directives and dual-use export control classifications that determine supplier eligibility for defense contracts.
Market Dynamics
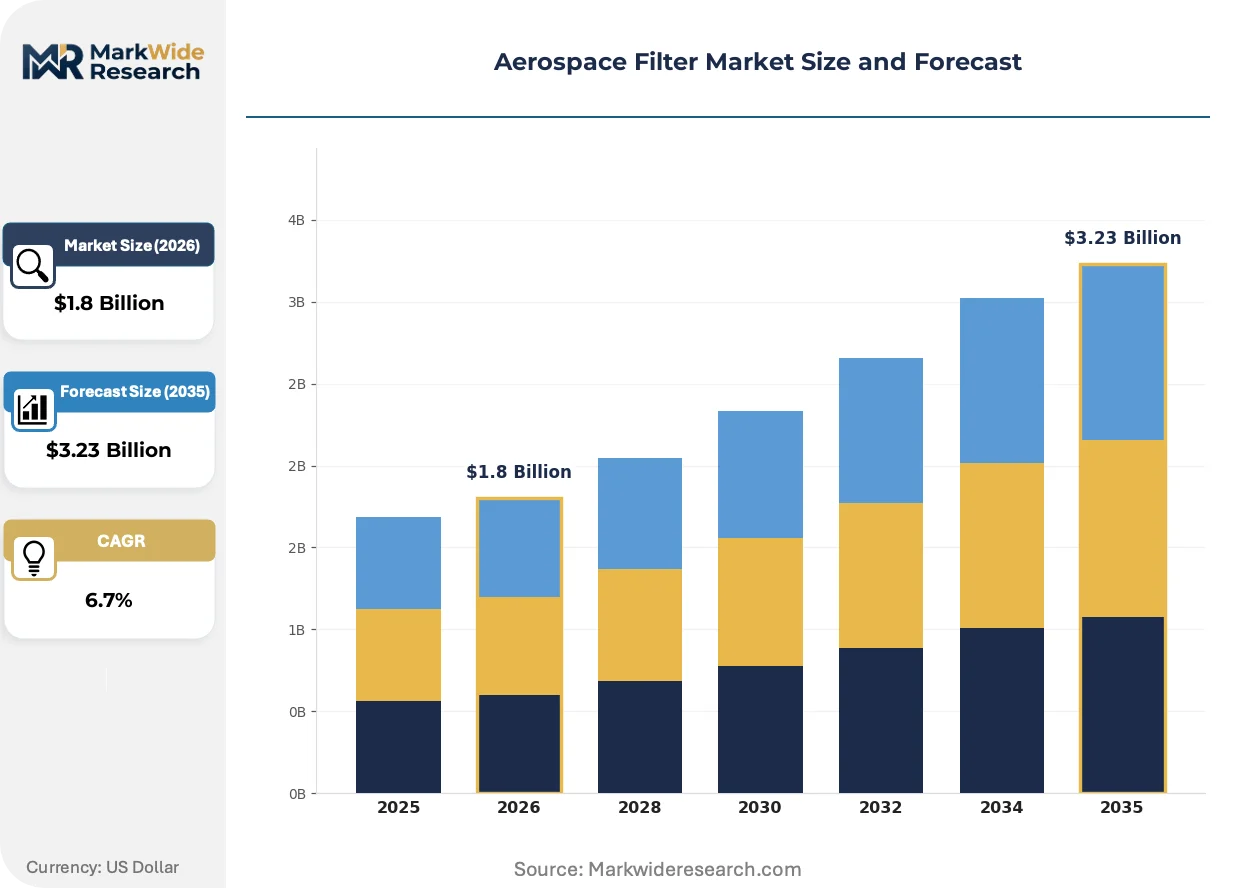
Military aviation sustainment budgets are compressing replacement cycles for flight-critical filtration systems, while FAA and EASA particulate mandates force cabin air technology upgrades across commercial fleets. This dual pressure from defense procurement acceleration and regulatory stringency defines current market motion.
Growth Catalysts
- 14 CFR Part 25.831:FAA ozone and ventilation mandates compel HEPA and activated carbon retrofit programs across narrow-body and wide-body aircraft operating in US airspace.
- Hydraulic fluid cleanliness specifications:Engine OEMs tighten ISO 4406 particle count requirements, driving recurring demand for microfiltration elements in landing gear and flight control systems.
- Glass microfiber media:Advances in pleating density and binder chemistry extend filter service intervals while maintaining 99.97% efficiency at 0.3 microns, reducing total cost of ownership for operators.
Market Restraints
- PTFE membrane supply concentration:Fluoropolymer production clusters in limited chemical processing corridors, exposing filter manufacturers to input cost volatility and allocation constraints.
- EASA CS-25 certification timelines:Extended validation protocols for new cabin air technologies delay product commercialization by 18-36 months, freezing development capital.
- Sintered metal mesh substitution:Advanced polymer composites displace metal filtration in non-critical hydraulic applications, compressing addressable volume in legacy platform retrofits.
Strategic Opportunities
- Urban air mobility platforms:Electric vertical take-off and landing aircraft require lightweight, compact filtration architectures that incumbent aerospace suppliers can adapt from unmanned systems expertise.
- Nanofiltration-adsorption convergence:Hybrid media combining graphene oxide layers with activated carbon capture ultrafine particulates and VOCs simultaneously, opening premium positioning in next-generation cabin systems.
- Direct-to-operator distribution:Airlines and defense maintenance units bypass traditional distribution tiers through OEM-authorized e-procurement portals, capturing margin previously held by intermediaries.
Industry Challenges
- Multiphysics simulation expertise:Filter design now requires coupled fluid-structure-thermal modeling capabilities that legacy aerodynamics teams lack, creating recruitment bottlenecks in specialized labor markets.
- Dual-use export control navigation:ITAR and EAR classifications for military-qualified filtration systems impose compliance overhead that disqualifies smaller suppliers from defense contract pools.
- Platform-specific qualification lock-in:Engine OEM proprietary test protocols prevent standardization, forcing suppliers to maintain parallel certification tracks for Boeing, Airbus, and military airframe programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Filter Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA Filters, Activated Carbon Filters, Electrostatic Filters, Foam Filters End User: Commercial Aviation, Military Aviation, Space Exploration, General Aviation Application: Cabin Air Quality, Fuel Filtration, Engine Air Intake, Hydraulic Systems Technology: Microfiltration, Nanofiltration, Ultrafine Filtration, Adsorption |
| Companies Covered | Parker Hannifin Corporation, Donaldson Company, Inc., Safran, Pall Corporation, Freudenberg & Co. KG, Eaton Corporation, Porvair PLC, Hollingsworth & Vose, PTI Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Filter Market Emerging Trajectories
Filtration technology is fragmenting along performance-tier lines as regulatory thresholds harden and platform electrification creates new thermal and particulate management requirements. Material science advances and procurement model disruption are the dominant vectors of change.
Electrospun nanofiber media is decomposing the traditional HEPA-activated carbon stack architecture in cabin air systems. Regional airlines and low-cost carriers in Southeast Asia adopt these lighter, thinner configurations to reduce HVAC power draw and extend range. The technology is decomposing established supply relationships as Asian membrane specialists bypass incumbent Western filter assemblers.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of PTFE membranes and fluorinated coatings used in fuel and hydraulic filtration. European filter manufacturers accelerate bio-based polymer development programs to maintain EASA certification eligibility. Military aviation procurement offices in Germany and France now require PFAS-free alternatives in new platform solicitations, compressing qualification timelines.
Power-by-the-hour maintenance contracts are reshaping filter procurement from transactional part sales to integrated availability guarantees. Lessors and asset managers in Ireland and Singapore bundle filtration replacement into airframe lease rates, transferring inventory risk to OEM service networks. This model concentrates purchasing authority with MRO integrators and erodes distributor influence in aftermarket channels.
Aerospace Filter Market Segmentation
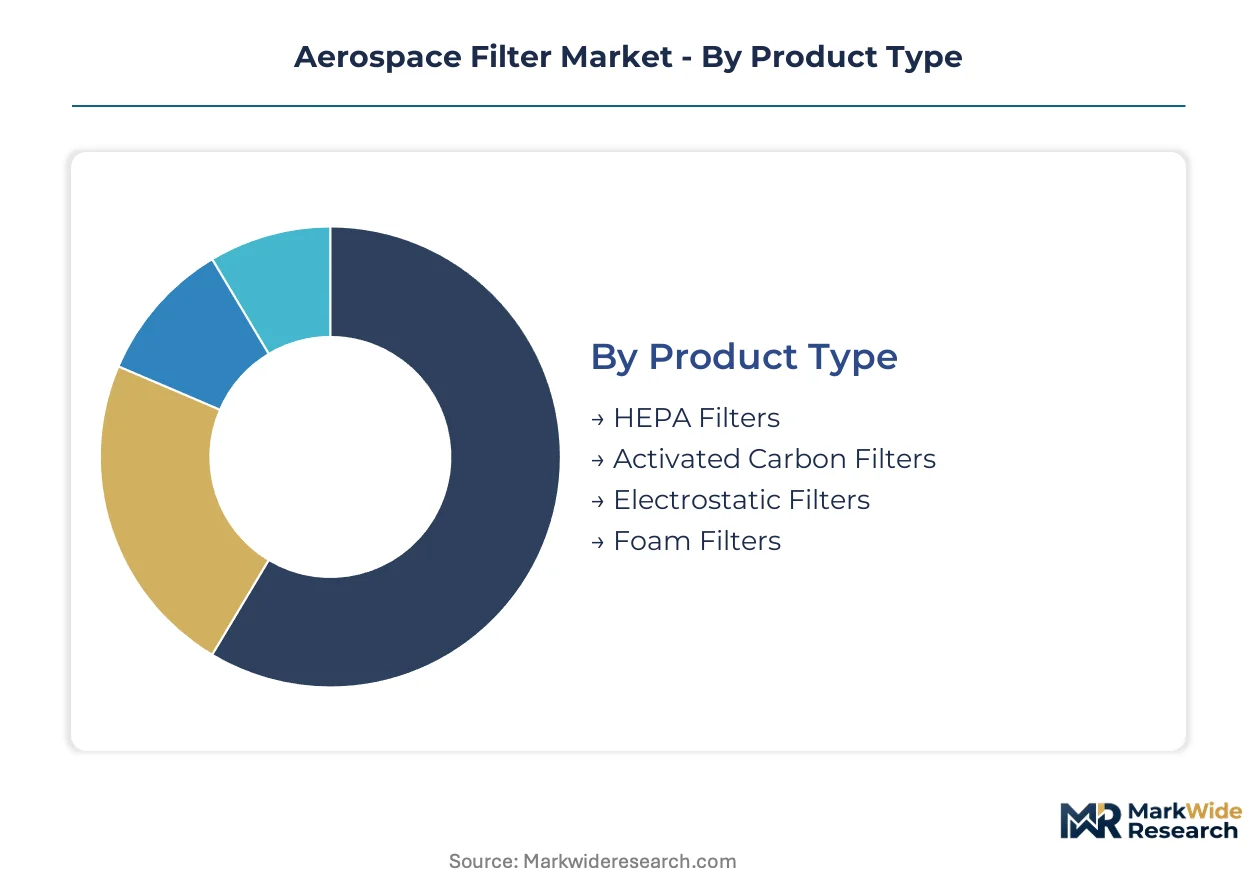
Aerospace filter procurement channels diverge sharply between defense sustainment contracts, commercial OEM line-fit programs, and aftermarket MRO distribution. Understanding which segments flow through which channels determines supplier strategy and margin capture.
Product Type:
Channel mix varies by filtration performance tier: HEPA and activated carbon filters move through OEM-authorized distribution for cabin retrofits, while foam and electrostatic variants reach general aviation through direct-to-operator portals.
- HEPA Filters:Glass microfiber media with 99.97% efficiency at 0.3 microns, pleated to maximize surface area within constrained HVAC envelopes. Demand concentrates in narrow-body fleet retrofits across United States commercial aviation as FAA Part 25.831 compliance deadlines tighten.
- Activated Carbon Filters:Impregnated carbon beds adsorb ozone and volatile organic compounds in recirculated cabin air. European carriers under EASA CS-25 mandates drive replacement cycles, with REACH PFAS restrictions forcing media reformulation.
- Electrostatic Filters:Charged fiber matrices capture sub-micron particles without the pressure drop of dense mechanical media. Regional turboprop operators favor these for reduced HVAC power draw.
- Foam Filters:Open-cell polyurethane or reticulated structures provide coarse pre-filtration in general aviation piston engine intakes. Recreational pilots purchase through direct e-commerce channels.
By volume, HEPA filters lead. By growth pace, activated carbon variants are climbing the fastest as ozone regulations tighten globally.
End User:
Cost tier segmentation separates flight-critical military systems from commercial availability contracts and general aviation discretionary purchases.
- Commercial Aviation:Power-by-the-hour contracts bundle filtration into airframe lease rates, transferring inventory risk to OEM service networks. Irish and Singaporean lessors concentrate purchasing authority with MRO integrators.
- Military Aviation:Sustainment budgets from Pentagon procurement offices compress replacement cycles for hydraulic and fuel filtration. ITAR qualification barriers limit supplier pools.
- Space Exploration:Launch vehicle environmental control systems require ultra-low outgassing media certified to NASA-STD-6001. Low unit volumes command premium pricing.
- General Aviation:Owner-operated piston and turboprop fleets purchase through distributor networks or direct channels, with price sensitivity highest in this tier.
Commercial aviation generates the largest revenue pool. Military aviation shows the steepest expansion trajectory as fleet sustainment accelerates.
Application:
Volume concentration tracks platform production rates, while margin pools align with certification barriers and recurring overhaul intervals.
- Cabin Air Quality:Combined HEPA and activated carbon stacks protect passenger health and crew alertness. Regulatory mandates in United States and European Union airspace force retrofit investments.
- Fuel Filtration:Microfiltration elements meeting ISO 4406 cleanliness specifications prevent injector wear and combustion degradation. Engine OEM qualification protocols create sticky supplier relationships.
- Engine Air Intake:Barrier filters and inertial separators protect turbine blades from foreign object damage. Tactical aircraft in desert operating environments drive replacement frequency.
- Hydraulic Systems:Pressure and return line filters maintain fluid cleanliness for flight control actuation. Landing gear and flap systems require high-collapse-pressure designs.
Fuel filtration leads by installed base value. Cabin air quality systems are gaining share fastest as post-pandemic health standards harden.
Technology:
Supply concentration clusters around membrane manufacturing capabilities, with performance tier determining geographic sourcing patterns.
- Microfiltration:Pleated synthetic or glass fiber media with 0.1 to 10 micron ratings dominate fuel and hydraulic applications. German and United States chemical processors control binder chemistry supply.
- Nanofiltration:Electrospun fiber layers below 100 nanometers capture ultrafine particulates without the depth of traditional HEPA media. Asian membrane specialists are disrupting Western incumbent positions.
- Ultrafine Filtration:Sintered metal mesh and ceramic structures withstand extreme temperatures in engine bleed air systems. Limited foundry capacity constrains supply expansion.
- Adsorption:Activated carbon, zeolite, and emerging metal-organic frameworks capture molecular contaminants. REACH restrictions on fluorinated coatings force bio-based alternative development.
Microfiltration holds the largest installed base. Nanofiltration represents the most rapid technology transition as weight reduction pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Defense Logistics Agency's distribution network across CONUS air bases underwrites United States dominance in military aerospace filtration procurement. European aerospace corridors rely on the Airbus A320/A350 supply chain radiating from Toulouse and Hamburg for commercial filter demand. Asian manufacturing growth connects through Singapore's Changi cargo hub for MRO filter distribution.
United States
Pentagon procurement offices compress hydraulic and fuel filter replacement cycles as tactical aircraft fleets expand sustainment budgets. FAA 14 CFR Part 25.831 mandates HEPA and activated carbon retrofits across narrow-body commercial fleets operating US airspace. The defense aerospace corridor spanning Ohio, Texas, and California concentrates Parker Hannifin and Donaldson manufacturing capacity for Pentagon supply chains.
Germany
REACH restrictions on per- and polyfluoroalkyl substances force PTFE membrane reformulation in fuel and hydraulic filtration systems. EASA CS-25 certification protocols delay new cabin air technology commercialization by 18-36 months, freezing development capital. The Baden-Württemberg industrial cluster around Stuttgart hosts specialized glass microfiber pleating operations serving Airbus and military platform suppliers.
France
Safran sustains dual-use positioning across European military and commercial aerospace with differentiated cabin air technologies. ANSM and DGAC enforcement of EASA particulate standards drives activated carbon replacement cycles in Air France-KLM and Transavia fleets. The Toulouse-Blagnac aerospace cluster anchors filter qualification testing for A320 family line-fit programs.
United Kingdom
RAF Typhoon and F-35 sustainment contracts accelerate microfiltration demand for engine air intake and hydraulic systems. The UK Civil Aviation Authority enforces EASA-equivalent cabin air quality standards post-Brexit through retained EU law frameworks. The South West England aerospace corridor around Bristol and Yeovil concentrates defense filter engineering for BAE Systems platforms.
Japan
METI procurement guidelines prioritize domestic filter sourcing for Japan Air Self-Defense Force F-15 and F-35 fleets. JIS standards alignment with ISO 4406 cleanliness specifications tightens hydraulic fluid filtration requirements across commercial and defense applications. The Aichi Prefecture aerospace manufacturing zone around Nagoya integrates filter supply into Mitsubishi Heavy Industries and Subaru defense production lines.
Aerospace Filter Market Vendor Landscape
Concentration sits with diversified industrial conglomerates holding engine OEM qualification certificates and ITAR-compliant defense supply positions. Three to five integrated filtration specialists control premium-tier fuel and hydraulic system markets through captive aerospace divisions. Strategic moves center on backward integration into membrane manufacturing and geographic expansion through MRO service network acquisitions.
Among North American diversified industrials, Parker Hannifin Corporation and Donaldson Company, Inc. exemplify the vertically integrated archetype spanning hydraulic, fuel, and engine air intake filtration. Safran occupies a position within the European dual-use specialist tier, leveraging cabin air technology differentiation across commercial and military platforms. Pall Corporation represents the precision filtration pure-play model focused on microfiltration qualification barriers.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Donaldson Company, Inc. |
| Safran |
| Pall Corporation |
| Freudenberg & Co. KG |
| Eaton Corporation |
| Porvair PLC |
| Hollingsworth & Vose |
| PTI Technologies |
| Others |
Supply Flow & Price Mechanics
Membrane manufacturing scale economies in glass microfiber and PTFE production concentrate supply among German and United States chemical processors, establishing price floors that filter assemblers cannot undercut without sacrificing EASA or FAA certification eligibility. This scale asymmetry grants raw material suppliers outsized pricing power while compressing margins for downstream integrators competing on engine OEM qualification.
Pricing Analysis
Volume-discount tiering structures separate Pentagon sustainment contracts from commercial aftermarket transactions, with defense procurement offices capturing 15-20 point spreads on multi-year hydraulic filter programs. Three-tier pricing stratification across ITAR-qualified, EASA-certified, and uncertified general aviation tiers reflects the cost of dual-use export compliance and platform-specific qualification testing. Cost compression in uncertified foam filter segments intensifies as Asian membrane specialists bypass Western assemblers with direct e-commerce distribution. Owner-operated piston fleets exhibit highest price sensitivity, while power-by-the-hour MRO integrators prioritize availability guarantees over unit cost.
Supply Chain Analysis
Port congestion on trans-Pacific lanes from Shanghai to Long Beach elevates inbound logistics costs for glass microfiber media sourced from Asian membrane specialists, forcing safety stock builds at Donaldson and Parker Hannifin distribution centers. Supply concentrates in Germany, the United States, and Japan for fluoropolymer resin and specialized pleating equipment. Raw material dependencies include PTFE resin, borosilicate glass fiber, and activated carbon coconut shell feedstock. Single-source vulnerability sits with fluoropolymer production clusters facing REACH PFAS restrictions. Distribution runs through OEM-authorized service networks and defense logistics agency depots, bypassing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power-by-the-hour maintenance contracts and integrated availability guarantees expand faster than hardware unit sales, converting filter procurement from transactional part replacement to recurring service revenue streams with superior cash flow predictability.
For Market Incumbents: Consolidate membrane manufacturing capabilities through backward integration into glass microfiber pleating operations, capturing margin currently held by German chemical processors. Lock in Pentagon supply chain position by expanding ITAR-compliant production capacity in the Ohio-Texas defense corridor before qualification timelines lengthen. Nanofiltration technology from Asian specialists threatens premium HEPA positioning; defend through accelerated graphene oxide hybrid media R&D programs. For New Entrants and Emerging Players: EASA CS-25 certification fast-tracks for cabin air retrofit applications offer the most penetrable entry vector, as regulatory compliance deadlines force fleet-wide upgrades regardless of incumbent relationships. Target regional turboprop operators in Southeast Asia with electrostatic filter configurations that reduce HVAC power draw and extend range. Go-to-market leverage comes from direct-to-operator e-procurement portals that bypass established distribution tiers and capture margin compression benefits. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among MRO integrators holding power-by-the-hour contracts with Irish and Singaporean lessors, where filtration replacement is bundled into airframe lease rates. Long-term viability over a decade horizon favors suppliers with dual-use military-commercial positioning and captive membrane manufacturing. Acquisition target archetype: precision filtration pure-plays with engine OEM qualification certificates but limited geographic footprint. Watch for REACH PFAS restriction enforcement as inflection indicator for bio-based polymer substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Manufacturing | Captures margin from German glass microfiber suppliers and secures EASA certification feedstock. |
| ITAR-Compliant Capacity Expansion | Qualifies suppliers for Pentagon hydraulic and fuel filter sustainment contracts with compressed replacement cycles. |
| Graphene Oxide Hybrid Media Development | Opens premium positioning in next-generation cabin air systems as nanofiltration displaces conventional HEPA stacks. |
| Direct-to-Operator E-Procurement Portal Launch | Bypasses distributor tiers and captures margin compression from Asian membrane specialist competition. |
| PFAS-Free Alternative Qualification | Maintains EASA certification eligibility under REACH restrictions and meets German military procurement mandates. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with MRO procurement directors, defense logistics agency contract officers, airline fleet managers, and filter manufacturing plant managers. Secondary validation drew from FAA airworthiness directive filings, EASA CS-25 certification databases, SEC 10-K disclosures from diversified industrials, and customs trade data on fluoropolymer resin imports. Bottom-up segment sizing triangulated against top-down macro aerospace production forecasts.
Across the analysis window, volume and value projections employed a multi-dimensional segmentation framework spanning filtration technology tier, platform application, end-use military-commercial split, and regional regulatory cluster. CAGRs were derived from regression analysis against airframe production rates, fleet age distributions, and mandated retrofit compliance schedules. Industry-specific inputs included hydraulic fluid cleanliness specification tightening by engine OEMs and REACH PFAS restriction implementation timelines.
Underlying assumptions cover sustained defense aviation sustainment budget expansion, stable fluoropolymer resin supply from German and United States chemical processors, and EASA-FAA regulatory harmonization on cabin air particulate standards, with deviation risk concentrated in REACH enforcement acceleration or PTFE membrane supply disruption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Polishing Filter Market
Filters
ePTFE Filter Film Market
Filters
Filtration and Separation Market
Filters
Compact Filters Market
Filters
Melt-Blown Polypropylene Filters Market
Filters
Global Pleated Filters Market
Filters
Drum Filters Market
Filters
Coolant Filtration Systems Market
Filters
Fabric Filter System Market
Filters
United States Activated Carbon Market
Filters
Global High Temperature Filters Market
Filters
Global Filter Press Market
Filters
High Purity Chemical Filters Market
Filters
Adsorbent Market
Filters
Industrial Filter Paper Market
Filters
Color Filter Glass Market