
 US Protective Coatings Market | 2026-2036
US Protective Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
US Protective Coatings Market Insights
Asset-light leasing models for spray equipment and application infrastructure is narrowing the capital barrier for mid-size contractors entering industrial coating services. PPG Industries, Inc. leverages its integrated supply chain across resin manufacturing and distribution to sustain cost advantages in high-volume marine contracts. The Sherwin-Williams Company anchors its position through extensive branch networks that control last-mile delivery to commercial construction sites. Axalta Coating Systems differentiates via specialized formulations for automotive OEM refinishing that demand precise color-matching technology.
US protective coatings are formulated systems comprising binders, pigments, solvents or water carriers, and functional additives that cure into adherent films providing barrier protection against corrosion, chemical attack, fire, or ultraviolet degradation; these systems typically achieve dry film thicknesses of 3–10 mils for standard industrial service and up to 250 mils for specialized fireproofing applications. Their primary purpose is extending asset life cycles in harsh operating environments where unprotected steel or concrete would deteriorate structurally. Water-based formulations are capturing share as EPA VOC limits tighten, though solvent-based systems retain dominance in marine and chemical resistance applications where performance specifications remain stringent. Corrosion protection represents the largest application segment by installed base, while fire protection coatings command premium positioning due to stringent building code enforcement and specialized certification requirements.
Federal EPA regulations on volatile organic compound emissions directly constrain formulation chemistry and drive reformulation investments across the supplier base. OSHA workplace exposure standards and state-level California Air Resources Board mandates further shape application methods and contractor compliance costs. Stakeholders must monitor evolving Department of Transportation infrastructure funding allocations and state-level procurement specifications that increasingly require extended warranty periods and verified performance testing.
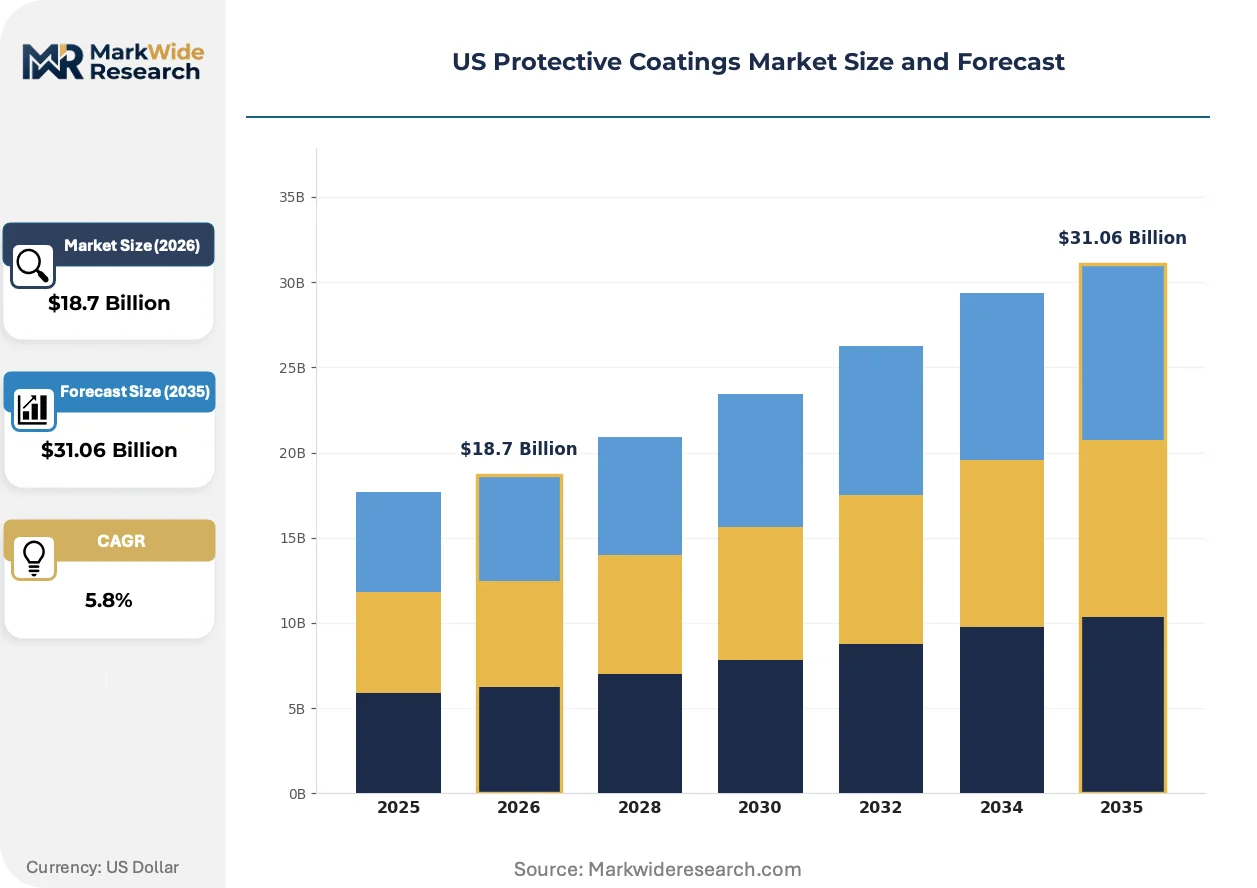
Market Dynamics
EPA VOC regulations are compressing formulation chemistry timelines while infrastructure rehabilitation accelerates demand for corrosion protection systems across aging bridges and petrochemical facilities.
Growth Catalysts
- Infrastructure Rehabilitation:Federal Department of Transportation funding allocations target bridge and highway corrosion protection, expanding the installed base for high-performance coating systems.
- EPA VOC Compliance Mandates:State-level California Air Resources Board standards and federal emission limits are forcing solvent-to-water formulation conversions that open retrofit demand.
- Petrochemical Facility Expansion:Gulf Coast concentration in Texas and Louisiana drives specialized coating requirements for offshore platforms and chemical processing infrastructure.
Market Restraints
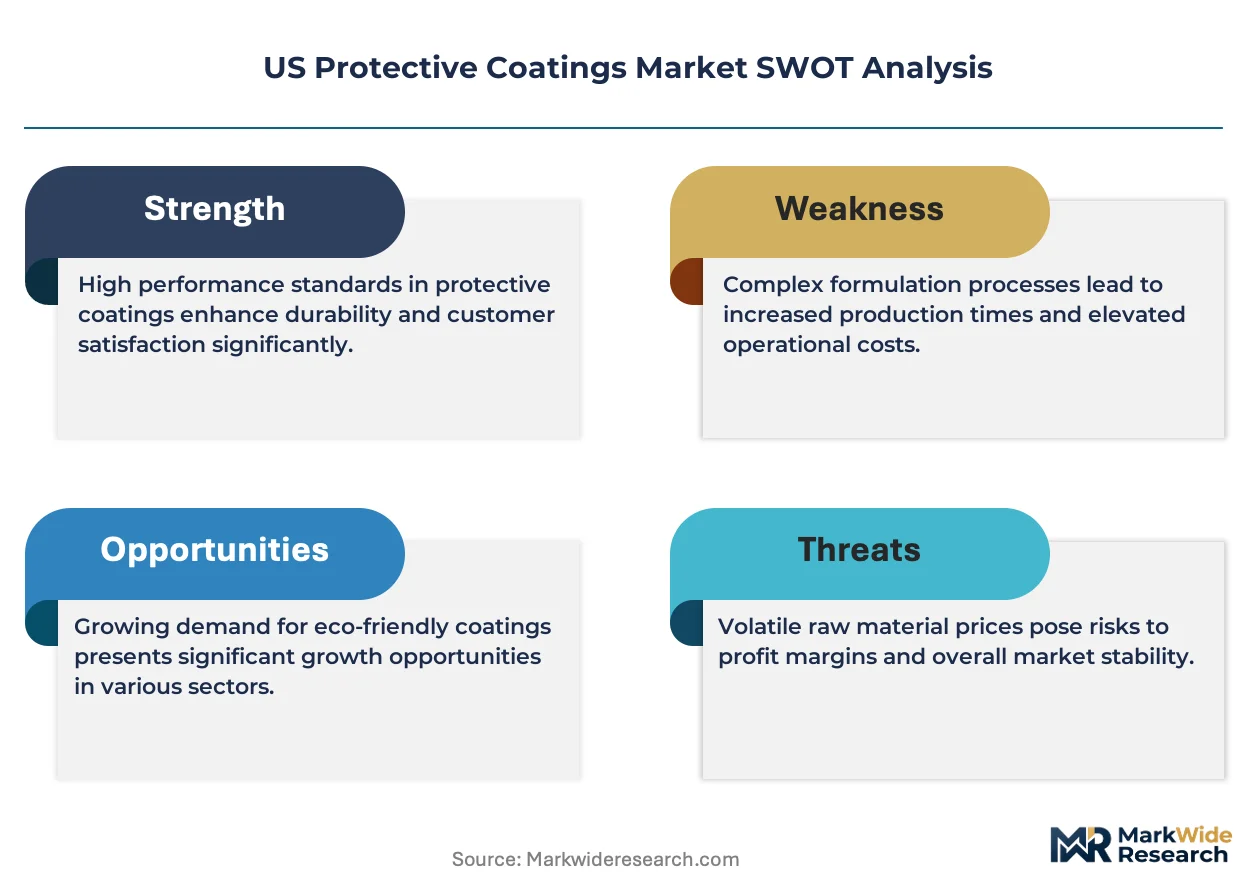
- Raw Material Volatility:Epoxy resin and titanium dioxide feedstock costs fluctuate with crude oil and mining output, compressing margin stability for formulation suppliers.
- Application Labor Scarcity:Certified industrial coating applicators concentrate in Gulf Coast and California metros, creating geographic supply bottlenecks for national project execution.
- Performance Trade-offs:Water-based systems face technical limitations in marine immersion and chemical splash zones where solvent-based formulations retain specification dominance.
Strategic Opportunities
- Fire Protection Certification Gap:Underpenetrated Midwest and Mountain West commercial construction markets lack sufficient intumescent coating applicators certified to UL 263 and ASTM E119 standards.
- Equipment Leasing Models:Asset-light spray infrastructure rental programs enable mid-size contractors to enter industrial service without capital-intensive plural-component equipment purchases.
- Extended Warranty Procurement:State transportation departments increasingly specify 10-15 year performance warranties, favoring suppliers with in-house testing and field service capabilities.
Industry Challenges
- Applicator Certification Bottlenecks:SSPC QP-1 and QP-2 certification timelines stretch 6-12 months, constraining contractor capacity expansion for federally funded infrastructure projects.
- Reformulation Cost Recovery:EPA-compliant water-based system R&D and production line conversions require capital deployment without immediate price premium realization in competitive bidding environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Protective Coatings Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent-Based, Water-Based, Powder Coatings, High-Performance End User: Marine, Aerospace, Automotive, Construction Application: Corrosion Protection, Fire Protection, Aesthetic Coatings, Chemical Resistance Technology: Electrostatic Spray, Brush Application, Roller Coating, HVLP |
| Companies Covered | RPM International Inc, Hempel A/S, The Sherwin-Williams Company, Tnemec, Axalta Coating Systems, PPG Industries, Inc., Jotun, INDURON, AkzoNobel N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Protective Coatings Market Trends and Innovations
Formulation chemistry and application methodology are undergoing simultaneous transformation as regulatory pressure intersects with infrastructure renewal timelines and contractor capacity constraints.
High-solids and 100% solids epoxy systems are collapsing the dry film thickness application steps required for heavy industrial corrosion protection. Petrochemical facility maintenance teams in Texas and Louisiana are specifying these technologies for turnaround windows compressed from weeks to days. The structural consequence is reduced labor hour requirements per square foot and compressed project timelines that favor contractors with plural-component spray equipment.
EPA Method 24 VOC testing protocols and state-level California Air Resources Board SCM-2007 architectural coating standards are mandating reformulation across the supplier base. Industrial coating manufacturers are accelerating waterborne and exempt solvent development programs to maintain specification eligibility in regulated jurisdictions. Marine and chemical processing segments face the steepest compliance burden where performance specifications resist water-based substitution.
Asset owners are consolidating procurement through national account structures that bundle coating supply with application services and warranty performance. Commercial construction and industrial facility managers are displacing fragmented local contractor bidding with single-source responsibility contracts. This concentration is most visible in California and Gulf Coast markets where large-scale infrastructure and petrochemical projects dominate capital expenditure flows.
US Protective Coatings Market Segmentation
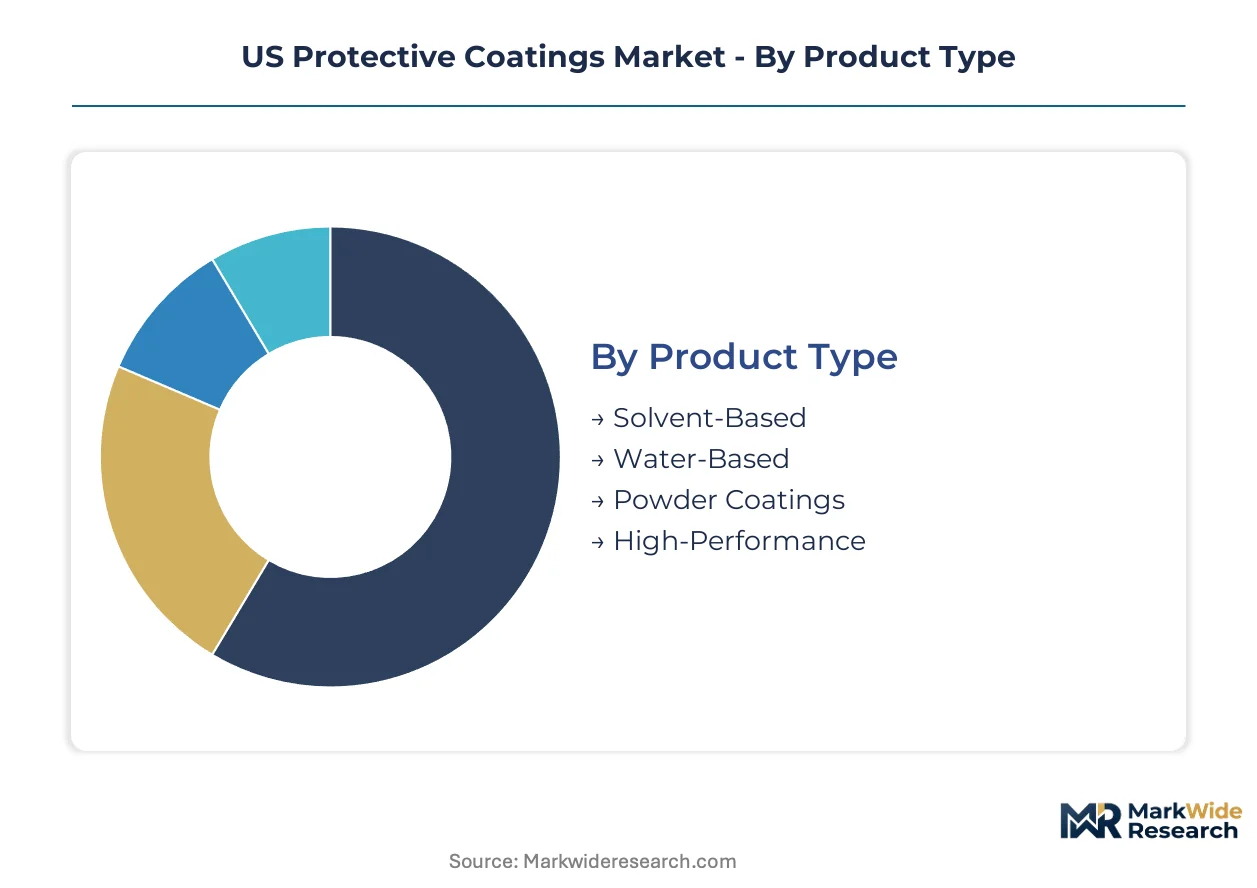
Protective coatings segmentation reveals divergent replacement cycles across product chemistries and end-use exposures. Cycle time variance—from annual marine maintenance to decade-long infrastructure warranties—shapes inventory velocity and formulation pricing power differently across each segment cluster.
Product Type:
Solvent-based systems turn over fastest in marine immersion service where re-coating intervals compress to 3-5 years, while powder coatings deliver 15-20 year lifecycles in architectural metal finishing.
- Solvent-Based:Epoxy and polyurethane formulations achieve superior chemical resistance and substrate adhesion in immersion environments. Demand concentrates in Gulf Coast petrochemical facilities and offshore platforms where EPA VOC waivers still permit specification for critical service. Reformulation timelines are compressing as California Air Resources Board mandates phase out compliant usage windows.
- Water-Based:Acrylic and urethane dispersions serve commercial construction and light industrial maintenance with reduced ventilation requirements. Texas and California transportation departments specify these systems for bridge rehabilitation where worker exposure regulations constrain solvent use. Performance gaps persist in continuous chemical splash zones.
- Powder Coatings:Thermoset polyester and epoxy-polyester hybrids deliver zero-VOC application with exceptional durability on architectural aluminum and steel.
- High-Performance:Fluoropolymer and ceramic-filled systems command specification in aerospace engine components and extreme-temperature processing equipment.
Solvent-based formulations anchor the volume base in marine and chemical processing while water-based alternatives gain share at the steepest rate under regulatory pressure.
End User:
Cost tier stratification separates specification-grade aerospace systems from commodity construction maintenance, with margin structures varying 3-4x across the hierarchy.
- Marine:Ship hull antifouling and ballast tank coatings face 2-3 year dry-dock cycles driving recurring demand. Louisiana and Texas port infrastructure expansion sustains applicator capacity concentration along the Gulf Coast. IMO 2023 antifouling biocide restrictions are forcing copper-free formulation development.
- Construction:Steel structure corrosion protection and concrete sealing represent the broadest addressable base. Federal Department of Transportation infrastructure allocations target bridge deck and highway barrier coatings. Warranty specifications extending to 10-15 years favor suppliers with in-house testing laboratories.
- Aerospace:OEM and MRO coatings demand precise thickness control and FAA-certified application protocols.
- Automotive:Refinish and OEM electrocoat systems require color-matching technology and robotic application integration.
Construction absorbs the largest absolute volume while marine replacement frequency sustains the most predictable recurring revenue streams.
Application:
Geographic concentration patterns align application specialization with regional industrial bases—Gulf Coast chemical resistance, California seismic fireproofing, Midwest infrastructure corrosion.
- Corrosion Protection:Zinc-rich primers and epoxy barrier systems protect steel in atmospheric and immersion service. Aging bridge inventories across the Interstate Highway System sustain federal and state procurement volumes. SSPC QP-1 certified contractor scarcity constrains project execution timelines.
- Fire Protection:Intumescent and cementitious coatings achieve UL 263 and ASTM E119 ratings for structural steel in commercial high-rise construction. California and Pacific Northwest seismic code enforcement drives specification density. Applicator certification gaps in Mountain West states create supply bottlenecks.
- Aesthetic Coatings:Architectural metal finishing and color-matched industrial equipment coatings serve brand visibility and facility maintenance requirements.
- Chemical Resistance:Vinyl ester and novolac epoxy systems protect concrete and steel in secondary containment and processing areas.
Corrosion protection commands the installed base volume while fire protection coatings expand most quickly under stringent building code adoption.
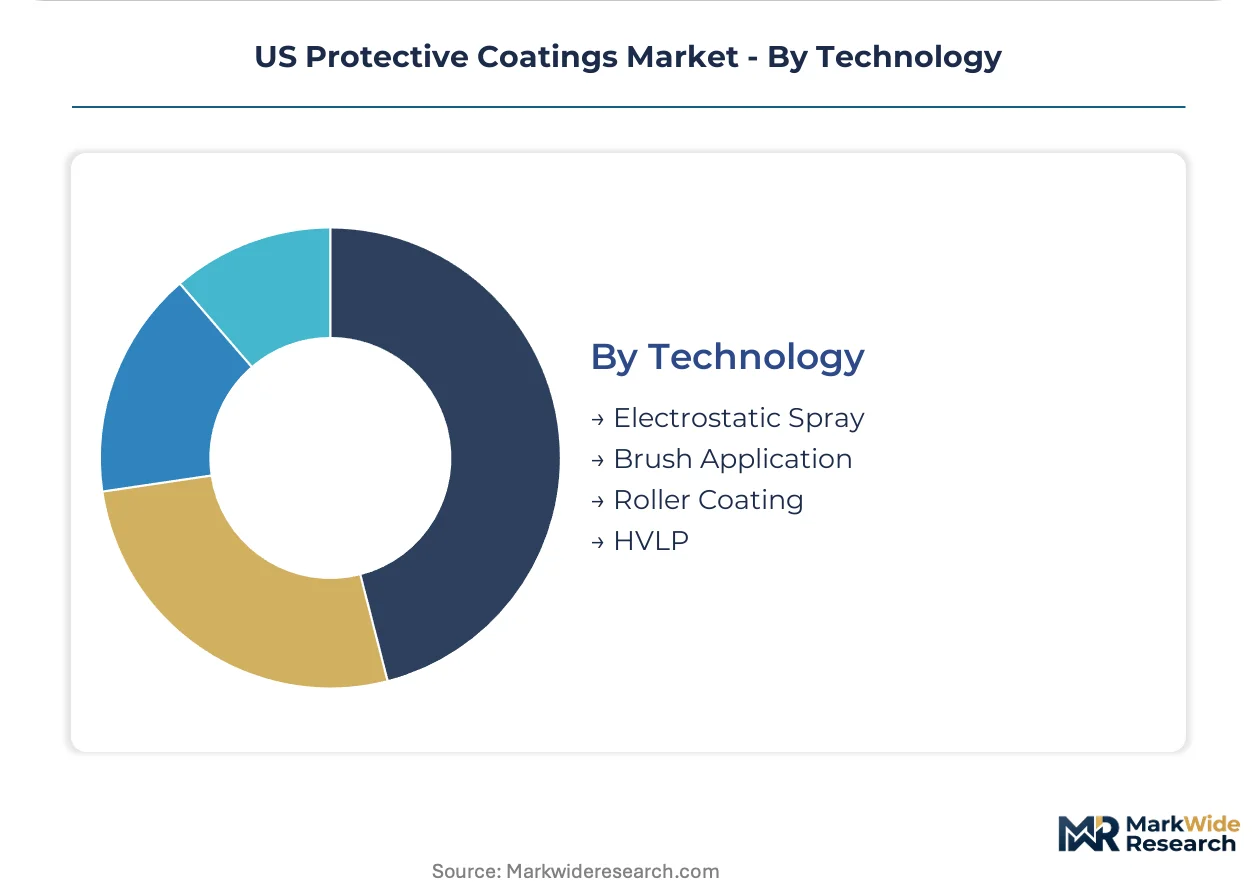
Technology:
Application methodology selection tracks project scale and specification precision—electrostatic spray dominates OEM volume, HVLP serves touch-up and maintenance, plural-component equipment enables high-solids field application.
- Electrostatic Spray:Charged particle deposition achieves 95%+ transfer efficiency on conductive metal substrates in factory-controlled environments. Automotive OEM and appliance manufacturing lines specify this technology for uniform film build. Capital equipment requirements favor high-volume coating operations.
- HVLP:High-volume low-pressure spray systems reduce overspray and solvent emissions for field maintenance and touch-up work. California South Coast Air Quality Management District rules mandate HVLP for architectural coating contractors. Equipment portability supports distributed project execution.
- Brush Application:Manual coating methods persist in confined space maintenance and small-area repair where spray equipment access is impractical.
- Roller Coating:Continuous web coating of metal coil and flat stock serves building products and container manufacturing.
Electrostatic spray retains the highest throughput volume while HVLP gains specification share fastest under district-level air quality enforcement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial facility managers and infrastructure contractors concentrate procurement decisions in coastal petrochemical corridors and seismic zones where corrosion and fire protection specifications are most stringent.
Texas
Offshore platform maintenance and Gulf Coast refinery turnarounds drive demand for immersion-grade epoxy systems. EPA Region 6 enforcement of VOC limits accelerates solvent-to-water formulation conversions among Houston-area applicators. The Port of Houston-Baytown corridor hosts the densest concentration of SSPC-certified contractors serving petrochemical infrastructure.
California
Bridge rehabilitation and commercial high-rise construction sustain specification volumes for intumescent fireproofing. California Air Resources Board SCM-2007 standards mandate zero-VOC architectural coatings across South Coast and Bay Area air districts. Los Angeles-Long Beach port complex maintenance programs favor water-based systems compliant with regional air quality management rules.
Louisiana
Chemical processing facility expansion and Mississippi River barge fleet maintenance create recurring demand for chemical-resistant barrier coatings. State environmental quality regulations align with federal EPA Method 24 testing protocols for industrial coating procurement. The Lake Charles-Baton Rouge industrial corridor concentrates applicator capacity for turnaround maintenance windows.
Illinois
Aging Interstate Highway System bridge inventories sustain federal Department of Transportation funding flows for corrosion protection systems. Illinois EPA adoption of federal VOC standards shapes specification requirements for Chicago-area infrastructure contractors. The Chicago-Gary industrial zone maintains legacy steel structure maintenance programs with extended warranty procurement terms.
Washington
Pacific Northwest marine vessel construction and aerospace manufacturing demand high-performance fluoropolymer and specialty corrosion systems. Washington State Department of Ecology oversight of industrial coating emissions parallels California regulatory stringency. Seattle-Tacoma port infrastructure and Boeing manufacturing facilities anchor specification-grade coating procurement volumes.
US Protective Coatings Market Competitive Landscape
Channel-controlling players compete with product-specialist players across formulation chemistry and application service bundling. The vendor base separates into national account managers with integrated supply chains, regional specialists with certified applicator networks, and technology-focused developers of high-solids systems. Three archetypes dominate: integrated resin-to-distribution manufacturers, application-service bundlers, and high-performance formulation specialists. Competitive moves concentrate on strategic partnerships for warranty-backed installation and geographic expansion of certified contractor networks.
Among integrated supply chain operators, PPG Industries, Inc. and The Sherwin-Williams Company occupy positions that exemplify scale-driven distribution control. Axalta Coating Systems represents the specialization archetype with focused formulation development. These three anchors demonstrate how competitive positioning separates volume-driven national coverage from technology-differentiated segment focus.
| Leading Market Players |
|---|
| RPM International Inc |
| Hempel A/S |
| The Sherwin-Williams Company |
| Tnemec |
| Axalta Coating Systems |
| PPG Industries, Inc. |
| Jotun |
| INDURON |
| AkzoNobel N.V. |
| Others |
Pricing and Supply Chain Analysis
The Houston-Baytown corridor concentrates epoxy resin manufacturing capacity and SSPC-certified applicator networks, translating upstream supply tightness into pricing leverage for immersion-grade formulations during refinery turnaround seasons.
Pricing Analysis
Cost-plus contracts with titanium dioxide and epoxy resin indexation dominate procurement between Gulf Coast formulators and petrochemical facility operators. Pricing stratifies across UL 263 certified fireproofing, SSPC QP-1 specified industrial systems, and commodity maintenance coatings based on certification burden and warranty duration. Cost compression in water-based architectural tiers intensifies because EPA VOC compliance investments lack immediate price premium recovery. Transportation departments and national account construction managers exhibit lowest price sensitivity due to performance warranty requirements, while small commercial maintenance contractors face acute margin pressure.
Supply Chain Analysis
Export-control restrictions on advanced fluoropolymer precursor chemicals limit formulation access for aerospace-grade protective systems. Manufacturing concentrates in the United States, Germany, and Japan for high-performance resin synthesis, with China dominating titanium dioxide pigment supply. Raw material dependencies center on crude oil derivatives for epoxy intermediates, mined titanium feedstock, and specialized ceramic fillers for extreme-temperature applications. Single-source vulnerability runs through Gulf Coast petrochemical intermediates exposed to hurricane season disruption. Distribution runs through manufacturer-direct national accounts for large infrastructure projects and regional distributor networks serving fragmented commercial maintenance demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as EPA reformulation mandates and applicator certification bottlenecks displace solvent-based specialists unable to fund waterborne R&D transitions.
For Market Incumbents: Build certification moats through accelerated SSPC QP-1 and QP-2 training program investments that constrain contractor capacity expansion for federally funded bridge rehabilitation. Consolidate position by acquiring regional waterborne formulation specialists in California and Texas to capture CARB-compliant specification share. Threat of stranded solvent-based inventory and margin compression from titanium dioxide volatility demands backward integration into resin manufacturing or captive supply agreements with Gulf Coast petrochemical producers. For New Entrants and Emerging Players: Mountain West fire protection markets offer underpenetrated white-space as UL 263 certified applicator scarcity creates supply bottlenecks for commercial high-rise construction. Target equipment leasing models for plural-component spray infrastructure that lower capital barriers for mid-size contractors entering industrial coating services. Go-to-market angle should bundle coating supply with application warranty performance to displace fragmented local contractor bidding in Midwest transportation department procurement. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory compliance play because EPA VOC trajectory and infrastructure rehabilitation timelines create sustained retrofit demand for reformulated systems. Acquisition focus should center on waterborne technology developers with in-house testing laboratories capable of extended warranty underwriting. Signal to watch is California Air Resources Board expansion of SCM-2007 standards to industrial coatings, which would force accelerated solvent-to-water conversion investments across the supplier base.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Manufacturing | Captive epoxy supply insulates margin stability from crude oil derivative volatility. |
| SSPC Certification Network Expansion | Controlled contractor pipeline secures allocation for federally funded infrastructure awards. |
| Waterborne Formulation R&D Investment | EPA Method 24 compliance maintains specification eligibility in CARB-regulated jurisdictions. |
| Equipment Leasing Program Launch | Asset-light model captures mid-size contractor demand without capital-intensive purchases. |
| Extended Warranty Service Bundling | Performance guarantees displace fragmented bidding in state transportation procurement. |
Research Methodology
A standing panel of coating formulators, SSPC-certified contractor operations managers, state transportation department procurement officers, and petrochemical facility maintenance directors provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with these stakeholders and secondary validation through EPA Method 24 filing databases, California Air Resources Board SCM-2007 compliance registries, Department of Transportation infrastructure funding disclosures, and SEC 10-K filings from publicly traded coating manufacturers. Bottom-up volume estimates from applicator capacity and project backlogs were triangulated against top-down spending flows from federal and state procurement databases.
Scenario bracketing around EPA enforcement intensity and infrastructure appropriation cycles shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation chemistry, end-use industry exposure, application technology, and regional regulatory cluster. CAGRs were derived from replacement cycle analysis and specification conversion rates. Industry-specific forecast inputs incorporated SSPC certification pipeline timelines and CARB waiver expiration schedules for solvent-based marine coatings.
Practitioners should monitor EPA Region 6 enforcement actions and California Air Resources Board rulemaking expansions for early signals of reformulation acceleration. Forecasts reflect assumptions regarding sustained Department of Transportation funding levels and gradual waterborne performance gap closure in chemical immersion service. Material shifts in federal infrastructure appropriations or breakthrough ceramic-filled waterborne formulations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Epoxy Powder Coatings Market
Coatings
Sol Gel Nanocoating Market
Coatings
Coating Binders Market
Coatings
Graphene Coatings Market
Coatings
Pure Epoxy Powder Coatings Market
Coatings
Global Low Friction Coatings Market
Coatings
Protective Antimicrobial Coatings for High-Touch Surfaces Market
Coatings
Global Smart Coating Market
Coatings
Sustained Release Coatings Market
Coatings
Fire Retardant Coatings Market
Coatings
Polymer Modified Cementitious Coatings Market
Coatings
Ethylene Tetrafluoroethylene (ETFE) Coatings Market
Coatings
Soft Touch Polyurethane Coatings Market
Coatings
Clear Coatings Market
Coatings
Global Polyaspartic Coatings Market
Coatings
China Marine Coatings Market