
 Australia Industrial Coatings Market | 2026-2036
Australia Industrial Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Industrial Coatings Market Outlook
The capability gap between integrated resin producers and toll-coating contractors is collapsing as raw material volatility reshapes procurement economics. DuluxGroup leverages captive distribution through trade-store networks to sustain margin capture across metropolitan job sites. PPG Industries anchors its position with automotive refinish technology leadership at OEM-certified collision centers. Hempel competes through marine-specialized formulations serving dry-dock operators at Fremantle and Newcastle ports.
Australia industrial coatings encompass liquid and powder systems formulated with epoxy, polyurethane, acrylic, or aliphatic resin bases, typically applied at 75-250 microns dry-film thickness to protect steel and concrete substrates from corrosion, chemical attack, and UV degradation in harsh operational environments. These formulations serve primarily to extend asset life cycles in infrastructure and equipment exposed to coastal salt, mining dust, and industrial effluent. Waterborne technology leads volume growth as VOC compliance tightens across states, while solventborne systems retain dominance in heavy-duty anticorrosive applications where film integrity under immersion conditions remains non-negotiable. Powder coating occupies a structural niche in metal fabrication and appliance manufacturing, capitalizing on zero-VOC profiles and high-transfer-efficiency application at Queensland and Victorian production lines.
TGA chemical oversight and APAS product certification frameworks govern coating composition disclosures and environmental release profiles, compelling reformulation investments among domestic blenders. WorkSafe Australia and state EPA bodies enforce airborne solvent exposure limits that accelerate waterborne system migration in factory-applied settings. Stakeholders must monitor evolving state-based PFAS restrictions and biosecurity import protocols that threaten to disrupt specialty additive supply chains from Asian manufacturing sources.
Market Dynamics
Raw material volatility and TGA reformulation mandates are compressing margins for Australian blenders while accelerating consolidation between resin producers and application contractors.
Growth Catalysts
- Marine dry-dock cycles:Fremantle and Newcastle port maintenance programs are expanding vessel coating refurbishment schedules, pulling high-performance epoxy systems into scheduled turnaround windows.
- APAS certification pathways:Accelerated product approval timelines for waterborne anticorrosive formulations are reducing time-to-market for compliant domestic manufacturers.
- Western Australia mining infrastructure:Pilbara iron ore and lithium processing facilities are driving demand for extreme-duty coatings in dust-laden, high-salinity environments.
Market Restraints
- Epoxy resin import concentration:Australian blenders source over 70% of bisphenol-A feedstock from Northeast Asian petrochemical complexes, exposing formulations to shipping cost spikes and currency hedging costs.
- Solventborne phase-out friction:WorkSafe Australia airborne exposure limits are tightening faster than waterborne technology can match immersion-grade film integrity, creating compliance-performance tradeoffs in tank lining applications.
- Specialty additive supply vulnerability:Biosecurity import protocols and emerging state-based PFAS restrictions threaten disruption of fluoropolymer and silicone surfactant supply chains from Chinese and Korean manufacturers.
Strategic Opportunities
- Queensland manufacturing belt expansion:Brisbane-Gold Coast metal fabrication clusters are adopting powder coating lines for appliance and construction equipment production, creating captive demand for zero-VOC systems.
- Renewable energy infrastructure:Offshore wind turbine foundation projects in Bass Strait and solar farm mounting structures in New South Wales are opening specifications for 25-year durability coatings.
- Digital color-matching services:Trade-store networks are deploying spectrophotometer-linked tinting systems that compress custom color turnaround from days to hours for metropolitan job sites.
Industry Challenges
- Applicator certification bottlenecks:NACE/SSPC-equivalent inspector qualifications are scarce in regional Western Australia and Queensland, constraining quality assurance for critical infrastructure projects.
- Legacy solventborne inventory stranding:Blenders face working capital pressure from reformulated product lines as TGA disclosure requirements accelerate obsolescence of pre-2020 formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Industrial Coatings Market |
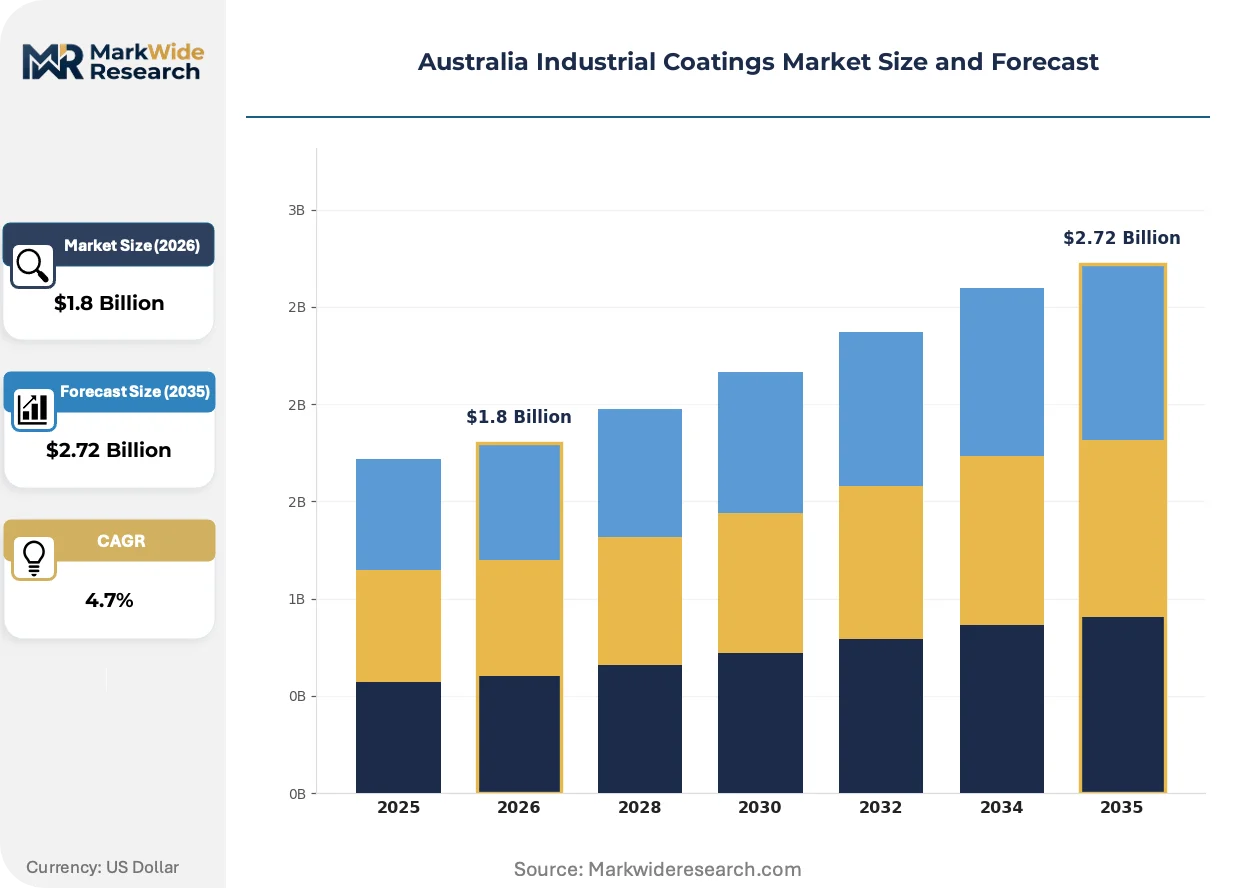
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Aliphatic End User: Manufacturing, Construction, Marine, Automotive Application: Protective Coatings, Decorative Coatings, Anticorrosive, Primers Technology: Waterborne, Solventborne, Powder Coating, UV Coating |
| Companies Covered | Nippon Paint Holdings, DuluxGroup, Sherwin-Williams, Axalta Coating Systems, Hempel, Akzo Nobel, Jotun, BASF, PPG Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Industrial Coatings Market Strategic Shifts
Waterborne technology advances and digital application systems are restructuring procurement economics across Australian industrial coatings, compressing the traditional supplier-contractor boundary.
High-solids waterborne epoxy systems are displacing conventional solventborne tank linings in marine and chemical storage applications. Fremantle dry-dock operators and Gladstone LNG facility maintenance teams are specifying these formulations for immersion service where VOC compliance is mandatory. The shift is displacing incumbent two-pack solventborne products from specification lists at major port authorities.
TGA chemical oversight frameworks now mandate granular composition disclosures for imported coating constituents, with APAS certification requiring third-party verification of environmental release profiles. This regulatory architecture is forcing reformulation investments among domestic blenders and creating compliance barriers for non-certified Asian imports. Western Australian mining contractors are responding by consolidating supplier lists around APAS-registered manufacturers.
Asset owners in Queensland and Victoria are unbundling coating specification from application contracting, directly procuring certified material systems while tendering labor separately. This procurement fragmentation is compressing margins for traditional supply-and-apply contractors and elevating the importance of technical documentation and warranty terms in competitive positioning. The pattern is most visible in Brisbane infrastructure projects and Melbourne manufacturing facility refurbishments.
Australia Industrial Coatings Market Segmentation
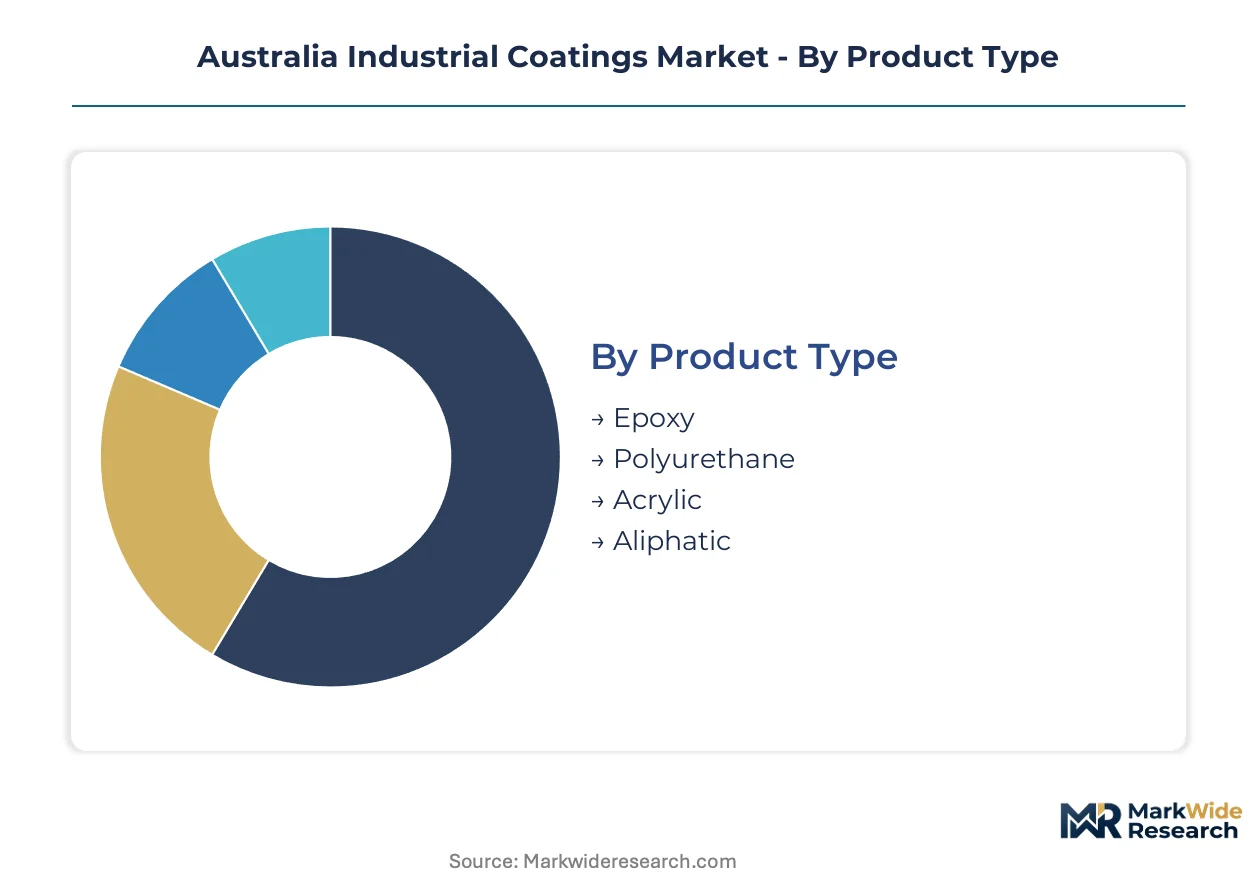
Segmentation in Australian industrial coatings reveals how TGA compliance costs and raw material sourcing geography reshape competitive economics across formulation types and end-use verticals. Understanding these splits exposes where margin compression concentrates and where technology premiums survive.
Product Type:
Epoxy formulations dominate domestic blending capacity, while polyurethane and acrylic systems rely more heavily on imported resin feedstocks subject to biosecurity protocols.
- Epoxy:Two-pack systems formulated with bisphenol-A and amine hardeners deliver the immersion-grade film integrity required for marine ballast tanks and Pilbara processing equipment. Demand concentrates at Fremantle dry-dock operators and Western Australian iron ore infrastructure where salt-laden corrosion cycles mandate 250-micron dry-film specifications.
- Polyurethane:Aliphatic and aromatic variants provide UV-stable topcoats for exposed structural steel. Queensland manufacturing facilities and Brisbane-Gold Coast metal fabrication clusters specify these for outdoor construction equipment where gloss retention and color stability justify premium pricing over acrylic alternatives.
- Acrylic:Waterborne acrylic dispersions serve decorative and light-duty protective applications in Victorian appliance manufacturing and New South Wales commercial construction.
- Aliphatic:Specialty aliphatic urethane systems command specification in high-visibility infrastructure where long-term chalking resistance outweighs formulation cost.
Epoxy commands the established base. The steepest expansion runs through polyurethane as UV-stable specifications proliferate across Queensland infrastructure tenders.
End User:
Customer concentration varies sharply by state regulatory environment, with marine and mining end-users facing the most stringent APAS certification requirements.
- Manufacturing:Brisbane-Gold Coast metal fabrication and Victorian appliance production lines specify powder coating and waterborne systems for zero-VOC compliance. Queensland manufacturers are unbundling material procurement from application contracting, compressing margins for traditional supply-and-apply vendors.
- Construction:Commercial and civil infrastructure projects in Sydney and Melbourne specify protective coatings for steel frameworks and concrete substrates exposed to coastal salt.
- Marine:Fremantle and Newcastle port authorities mandate high-performance epoxy systems for scheduled dry-dock maintenance cycles.
- Automotive:OEM-certified collision centers specify premium refinish coatings with rapid cure profiles and color-matching precision.
Manufacturing absorbs the highest volume. Marine generates the steepest technology premium per liter applied.
Application:
Application function determines whether solventborne technology retains specification or waterborne systems can displace incumbent formulations.
- Protective Coatings:Heavy-duty systems for industrial infrastructure and mining equipment exposed to mechanical abrasion and chemical attack.
- Decorative Coatings:Aesthetic finishes for commercial buildings and consumer goods where color range and gloss level drive selection.
- Anticorrosive:Immersion-grade and atmospheric-zone formulations for marine vessels, chemical storage tanks, and coastal steel structures. Fremantle dry-dock operators and Gladstone LNG facilities are specifying high-solids waterborne epoxies where VOC compliance is mandatory, displacing legacy solventborne tank linings from port authority specifications.
- Primers:Surface preparation and adhesion-promoting layers that determine coating system durability in harsh Australian operational environments.
Anticorrosive applications command specification authority. Decorative coatings are gaining share fastest as waterborne technology advances close the performance gap.
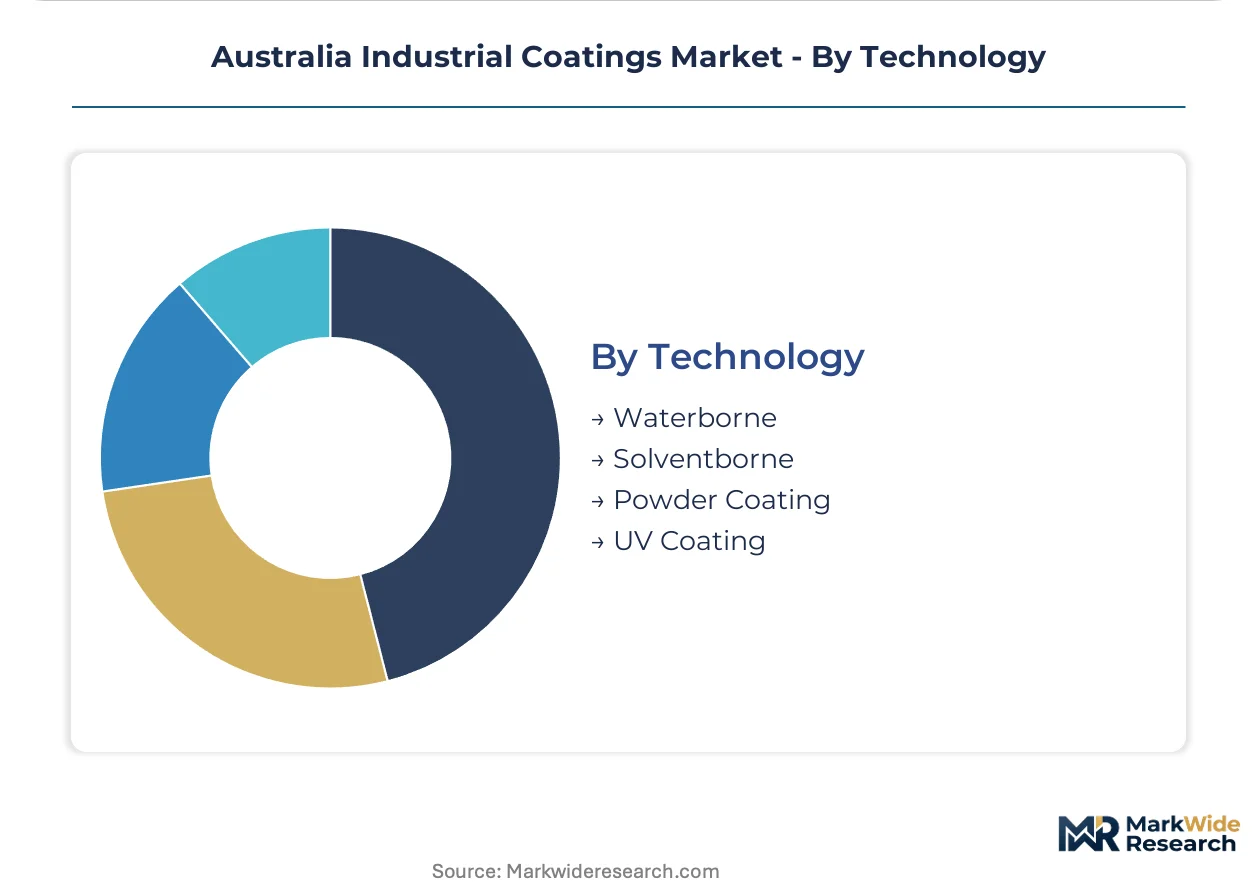
Technology:
Technology choice tracks state-level VOC enforcement intensity, with WorkSafe Australia exposure limits accelerating factory-floor migration away from solventborne systems.
- Waterborne:Acrylic and epoxy dispersions with sub-100 g/L VOC content. High-solids waterborne epoxies are displacing conventional solventborne tank linings in marine and chemical storage applications where TGA disclosure requirements and port authority mandates enforce compliance.
- Solventborne:Traditional two-pack epoxies and urethanes retain dominance in immersion service where film integrity under continuous saltwater exposure remains non-negotiable. Reformulation investments are accelerating as pre-2020 formulations face TGA obsolescence.
- Powder Coating:Zero-VOC thermoset systems applied electrostatically to metal substrates. Queensland and Victorian production lines for appliances and construction equipment are adopting captive powder lines for environmental compliance and transfer efficiency.
- UV Coating:Rapid-cure systems for specialized manufacturing applications requiring minimal process downtime and immediate handling strength.
Solventborne technology retains the revenue base. Waterborne systems are climbing the fastest as state EPA enforcement tightens factory-applied specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western Australia consumes industrial coatings at intensity levels unmatched elsewhere in Australia, driven by Pilbara mining infrastructure exposure to salt-laden corrosion cycles that demand 250-micron dry-film specifications rather than the standard 75-150 micron applications common in eastern states.
New South Wales
Sydney commercial construction and Newcastle port maintenance programs anchor coating demand. WorkSafe New South Wales enforces airborne solvent exposure limits that accelerate waterborne system adoption in factory-applied settings. The Newcastle-Fremantle marine corridor specifies high-performance epoxy systems for scheduled dry-dock refurbishment cycles.
Victoria
Melbourne manufacturing facilities and appliance production lines specify powder coating and waterborne systems for zero-VOC compliance. The state's EPA enforces stricter VOC thresholds than Queensland or South Australia. Victorian metal fabrication clusters in Melbourne's southeastern suburbs are unbundling material procurement from application contracting.
Queensland
Brisbane-Gold Coast metal fabrication and Gladstone LNG facility maintenance drive demand for UV-stable polyurethane topcoats. Queensland's manufacturing belt adopts powder coating lines for appliance and construction equipment production. The state's EPA enforcement lags Victoria, preserving solventborne specification in immersion-grade applications longer than southern neighbors.
Western Australia
Pilbara iron ore and lithium processing facilities consume extreme-duty coatings in dust-laden, high-salinity environments. The state's Department of Mines, Industry Regulation and Safety mandates corrosion protection standards for offshore and coastal infrastructure. Fremantle port dry-dock operators specify high-solids waterborne epoxies where VOC compliance intersects with immersion-grade film integrity requirements.
South Australia
Adelaide manufacturing and defense infrastructure sustain moderate coating demand at specification levels below Western Australia's mining intensity. The state's EPA aligns VOC enforcement with national WorkSafe Australia frameworks rather than pioneering stricter thresholds. Limited local blending capacity forces reliance on interstate supply chains for specialized anticorrosive formulations.
Australia Industrial Coatings Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in Australian industrial coatings. DuluxGroup and PPG Industries occupy the upper tier through captive distribution networks and OEM-certified service relationships. Mid-tier specialists compete on formulation agility for APAS certification pathways. The dominant competitive moves are backward integration into resin sourcing and geographic consolidation of application contractor networks.
Within the integrated multinational tier, Akzo Nobel and Hempel occupy positions defined by marine-specialized formulation heritage. DuluxGroup exemplifies the domestic-anchored archetype through trade-store network control. PPG Industries represents the technology-licensing model with automotive refinish leadership. These three entities anchor competitive dynamics without exhausting the participant base.
| Leading Market Players |
|---|
| Nippon Paint Holdings |
| DuluxGroup |
| Sherwin-Williams |
| Axalta Coating Systems |
| Hempel |
| Akzo Nobel |
| Jotun |
| BASF |
| PPG Industries |
| Others |
Value Chain & Pricing Dynamics
Captive blending capacity at DuluxGroup and PPG Industries anchors price floors across Australian industrial coatings, concentrating procurement leverage among integrated multinationals while forcing toll-coating contractors into volume-discount races. Scale advantages in resin sourcing and APAS certification investments create defensive moats that smaller blenders struggle to bridge, compressing margins at the mid-tier.
Pricing Analysis
After-sales service contracts and extended warranty coverage drive lifetime value for Australian coating suppliers, with technical support and specification consulting bundled into premium tier offerings. Three-tier pricing structure across premium, standard, and economy levels separates APAS-certified immersion-grade epoxies from uncertified imports and generic trade-store products. Cost compression in standard-grade waterborne acrylics is intensifying because Queensland manufacturers are unbundling material procurement from application labor. Mining contractors in Western Australia exhibit lowest price sensitivity, prioritizing film integrity guarantees over per-liter costs, while Brisbane metal fabrication clusters drive hardest volume bargaining.
Supply Chain Analysis
Inventory cycles for bisphenol-A and amine hardeners stretch 8-12 weeks from Northeast Asian petrochemical complexes, exposing Australian blenders to shipping cost volatility and currency hedging expenses. Domestic formulation draws from China, South Korea, and Japan for epoxy resin feedstocks, with specialty fluoropolymer additives sourced from Chinese and Korean manufacturers. Single-source vulnerability concentrates in PFAS-based surfactants facing state-based restriction threats. Distribution runs through DuluxGroup's trade-store networks, PPG's OEM-certified collision centers, and direct procurement channels to Pilbara mining operators and Fremantle dry-dock facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australian industrial coatings fragment across procurement unbundling, with asset owners separating material specification from application contracting. This demand-side shift creates specialist niches for APAS-certified blenders and regional applicator networks.
For Market Incumbents: Fortify captive distribution control through spectrophotometer-linked tinting deployments at metropolitan trade stores, compressing custom color turnaround to defend against digital-native entrants. Deepen backward integration into waterborne epoxy resin production to offset Northeast Asian import volatility. Expand APAS certification coverage for high-solids formulations before TGA disclosure mandates accelerate pre-2020 product obsolescence.
For New Entrants and Emerging Players: Lead with powder coating line integration for Queensland appliance manufacturers seeking zero-VOC compliance with captive application capacity. Target South Australian defense and Adelaide manufacturing infrastructure where limited local blending capacity forces reliance on interstate supply chains. Pursue direct procurement relationships with solar farm developers in New South Wales specifying 25-year durability coatings for mounting structures.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors waterborne formulation specialists with APAS certification momentum and regional applicator network control. Long-term viability hinges on regulatory compliance infrastructure rather than commodity volume scale. Acquisition candidates should demonstrate proven reformulation capabilities under TGA chemical oversight frameworks. Watch for inflection when state-based PFAS restrictions trigger specialty additive supply disruptions, advantaging domestic blenders with alternative surfactant partnerships.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Sourcing | Captive bisphenol-A supply insulates margin compression from Northeast Asian shipping volatility. |
| APAS Certification Acceleration | Third-party verification creates compliance barriers against uncertified Asian imports under TGA mandates. |
| Powder Coating Line Expansion | Zero-VOC systems capture Queensland manufacturing belt demand from appliance and construction equipment producers. |
| Digital Color-Matching Deployment | Spectrophotometer-linked tinting compresses custom turnaround from days to hours at metropolitan job sites. |
| Regional Applicator Network Consolidation | NACE-equivalent qualification scarcity in Western Australia creates acquisition opportunities for certified contractors. |
Study Parameters
The analysis maps epoxy, polyurethane, acrylic, and aliphatic formulation sub-sectors, each validated through plant managers at Pilbara mining facilities, procurement leads at Brisbane-Gold Coast metal fabricators, and technical R&D directors at domestic blending operations. Primary interviews with Fremantle dry-dock operators, Gladstone LNG maintenance teams, and Victorian appliance manufacturers combined with secondary validation from Australian Bureau of Statistics trade data, WorkSafe Australia exposure limit filings, and TGA chemical disclosure registers. Bottom-up volume estimates from end-use consumption patterns triangulated against top-down capacity assessments from resin import customs records.
Consistency checks validated volume and value outputs against ACCC industry reports and SEC 10-K segment disclosures from multinational coating suppliers. The analytical framework modeled technology migration, end-use vertical, and state-level regulatory enforcement intensity across the projection horizon. CAGRs derived from segment-level demand elasticity and substitution rates between solventborne and waterborne systems. Forecast inputs incorporated TGA reformulation timelines, APAS certification pathway speeds, and biosecurity protocol changes affecting specialty additive imports.
The analysis sits within stated boundaries; outcomes outside sustained mining infrastructure investment cycles or accelerated PFAS restriction enforcement would require recalibration. Forecasts reflect documented assumptions regarding resin import cost trajectories and state EPA VOC enforcement harmonization. Raw material volatility, currency fluctuation, and regulatory timeline shifts constitute primary revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Can Coatings Market
Coatings
South Korea Marine Coatings Market
Coatings
Polyurethane Powder Coatings Market
Coatings
Functional Coil Coating Market
Coatings
Global Waterborne Coatings Market
Coatings
Spain Automotive OEM Coatings Market
Coatings
Coating Thickness Gauge Market
Coatings
Canada Protective Coatings Market
Coatings
Anti-Microbial Powder Coatings Market
Coatings
Corrosion Protection Coating Market
Coatings
Plasma Impulse Chemical Vapor Deposition (PICVD) Coating Market
Coatings
United States Floor Coatings Market
Coatings
Global Anti-Corrosion Coating Market
Coatings
Anti-Microbial Nano Coatings Market
Coatings
Global Radiation Cured Coatings Market
Coatings
Concrete Floor Coatings Market