
 Stain Resistant Coatings Market | 2026-2036
Stain Resistant Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Stain Resistant Coatings Market Intelligence
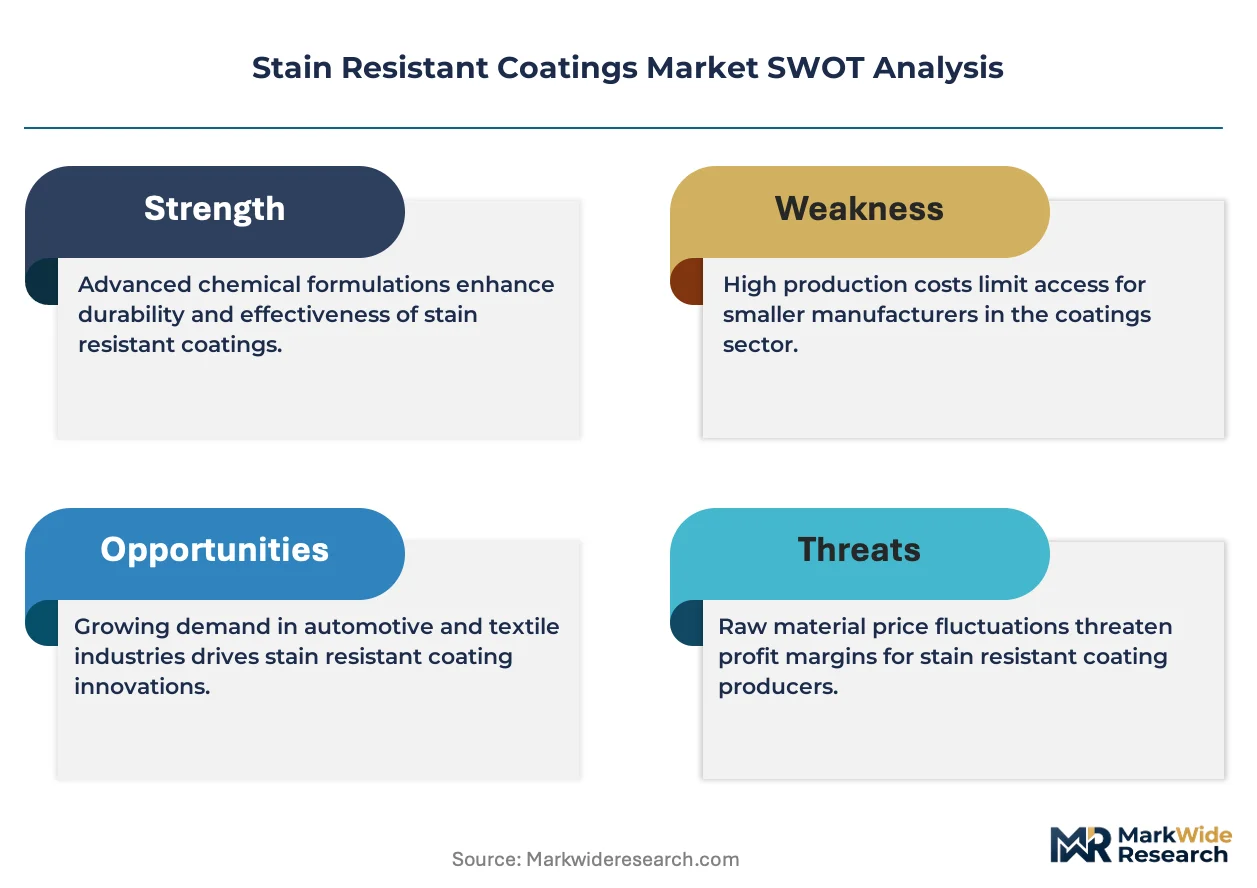
Performance-based warranty programs tied to specific stain-resistance metrics are restructuring the value proposition beyond simple material sales. This shift benefits large, diversified firms like BASF SE, which leverages its extensive research and development to validate performance claims. The Chemours Company specializes in high-performance fluoropolymer technologies, anchoring the premium end of the market. Meanwhile, PPG Industries, Inc. utilizes its vast distribution network to push warrantied systems into the automotive and architectural sectors.
Stain resistant coatings are surface treatments engineered to prevent liquids and solids from adhering to or penetrating a substrate. They function by creating a low surface energy barrier, exhibiting hydrophobic and oleophobic properties to repel common staining agents. Fluoropolymer technologies continue to lead the high-performance segment, though silicone-based and advanced acrylic formulations are gaining traction. Key applications in textiles and automotive interiors drive significant volume, with consumer electronics demanding specialized, thin-film solutions.
Regulatory actions from the US EPA and the European Chemicals Agency under REACH are restricting the use of legacy PFAS chemistries. Concurrently, China's GB standards impose strict limits on volatile organic compound content in coatings. Successfully navigating the transition to alternative, compliant chemistries without compromising performance or durability remains the central challenge for formulators.
Market Dynamics
The regulatory-driven transition away from legacy per- and polyfluoroalkyl substances (PFAS) is the central force shaping the market. This shift compels formulators to innovate with alternative chemistries while managing performance trade-offs and complex compliance landscapes across geographies.
Growth Catalysts
- Automotive Interior Specifications:OEM requirements for stain-free vehicle interiors, supported by warranties, drive adoption of durable coatings for upholstery and carpets.
- Textile Production Geography:Demand concentrates in textile manufacturing hubs like Vietnam and Bangladesh, where coatings are applied at scale for apparel exports.
- Regulatory Substitution Pressure:The EU's REACH directive restricts legacy PFAS, forcing the adoption of compliant, next-generation alternatives in Europe.
Market Restraints
- Cost of Alternatives:Compliant non-PFAS formulations, such as advanced silicones, often have a higher price point than the legacy technologies being replaced.
- Performance Gaps:Many alternatives struggle to match the combined oil and water repellency of traditional long-chain fluoropolymer technologies.
- VOC Content Rules:China's GB standards impose strict limits on volatile organic compounds, increasing formulation costs for market access.
Strategic Opportunities
- Thin-Film Electronics:The consumer electronics sector requires specialized, ultra-thin coatings that provide stain and fingerprint resistance on device surfaces.
- Bio-Based Chemistries:Developing coatings from renewable feedstocks meets sustainability demands and offers a key differentiator in environmentally conscious markets.
- New Geographic Markets:Architectural applications in fast-growing urban centers in Southeast Asia and South America represent a significant expansion opportunity.
Industry Challenges
- Reformulation and Re-certification:Transitioning product lines to new chemistries requires extensive R&D investment and lengthy re-certification processes to meet industry and regulatory standards.
- Durability Validation:Proving the long-term durability and performance of new formulations to support warranty programs is a time-consuming and costly validation challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stain Resistant Coatings Market |
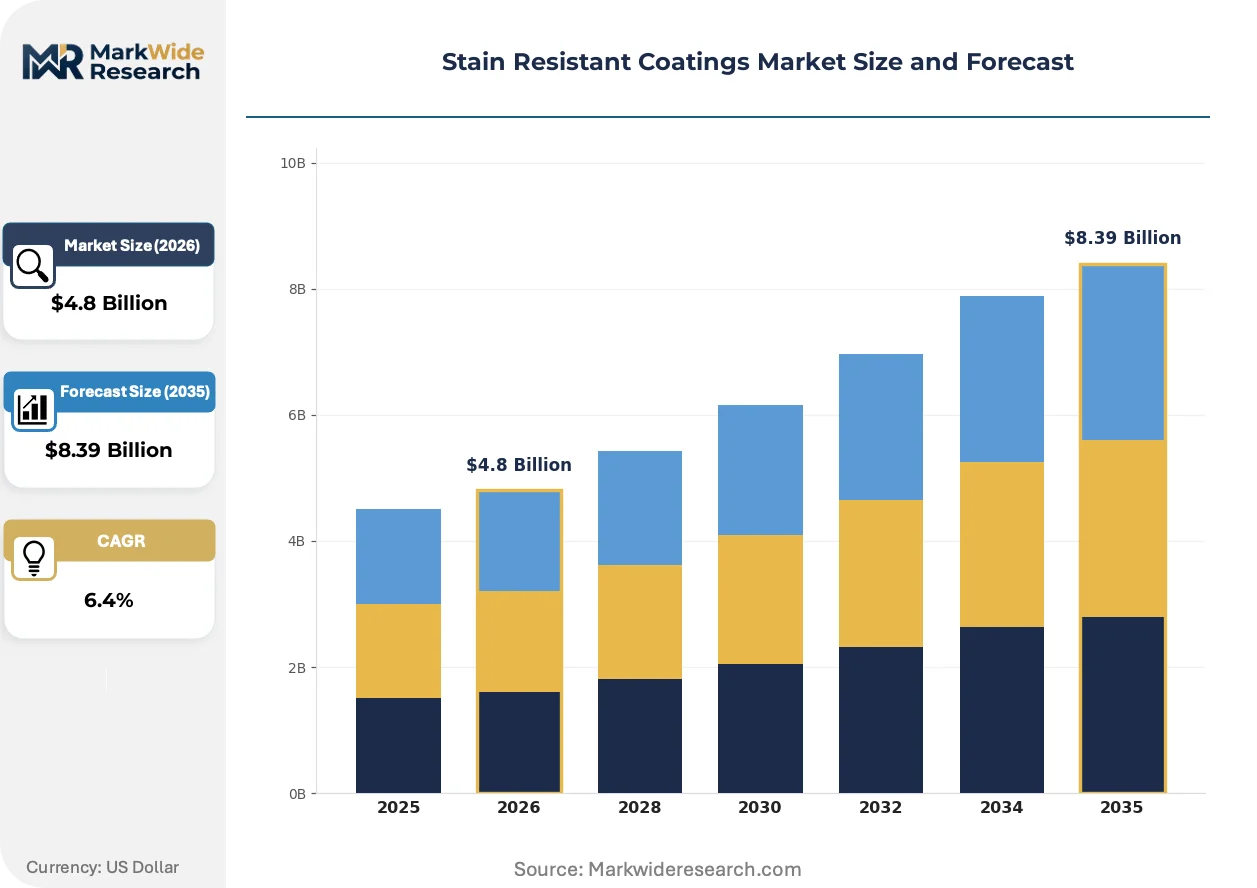
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluoropolymer, Silicone-Based, Acrylic, Polyurethane, Epoxy Application: Textiles, Automotive Interiors, Consumer Electronics, Packaging, Footwear End User: Fabric Manufacturers, OEM Suppliers, Electronics Assemblers, Luxury Goods Producers, Sportswear Brands Form: Liquid, Powder, Aerosol, Paste, Dispersion |
| Companies Covered | BASF SE, Jotun, PPG Industries, Inc, 3M Company, Nippon Paint Holdings Co., Ltd., Sherwin-Williams Company, Axalta Coating Systems, The Chemours Company, AkzoNobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stain Resistant Coatings Market Strategic Shifts & Innovations
A fundamental re-engineering of the market's chemical foundation is underway, driven by regulatory pressures and evolving performance expectations. This transition is creating new value chains and business models centered on validated, compliant performance rather than simple material supply.
Advanced silicone-based formulations are engineered to create a low surface energy barrier for repelling water and oil. The automotive and textile sectors are rapidly adopting these technologies as viable alternatives to restricted fluorochemistries. This material science shift is electrifying the innovation pipeline, forcing investment into non-fluorinated solutions to maintain performance benchmarks.
The US EPA's PFAS Strategic Roadmap establishes a framework for restricting certain fluorochemicals and evaluating their risks. This action directly impacts supply chains for consumer goods, requiring manufacturers to seek and validate compliant coating inputs. The textile and food packaging sectors are most affected, accelerating their transition to non-PFAS chemistries to ensure continued market access.
Performance-based warranty programs are altering the core value proposition from material sales to guaranteed outcomes against specific stain-resistance metrics. This model disrupts traditional distribution channels, favoring suppliers who can provide integrated, validated systems. The shift is most prominent within the North American and European architectural and automotive interior segments where long-term durability is critical.
Stain Resistant Coatings Market Segmentation
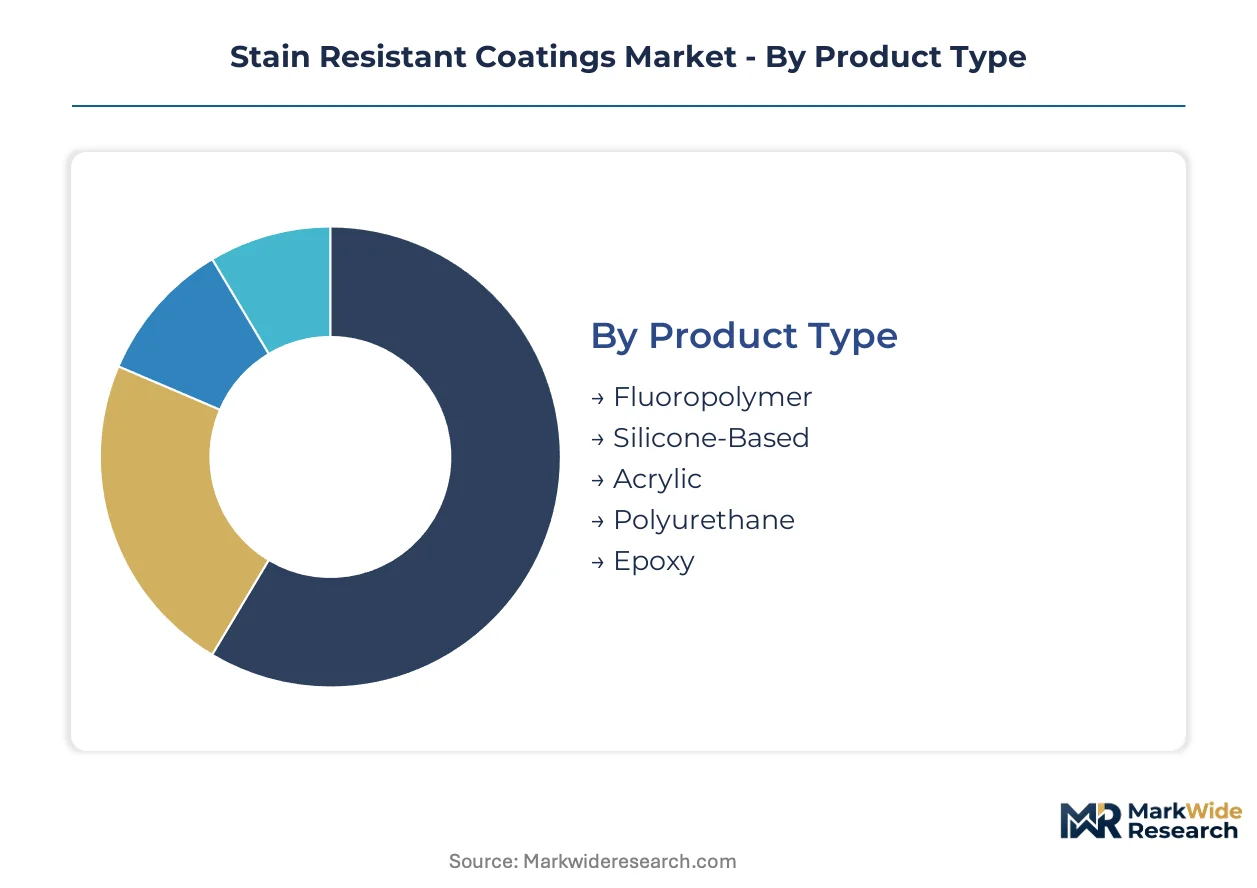
Segmentation provides a granular understanding of how diverse chemistries and application methods address specific performance needs within the stain resistant coatings market. This detailed view reveals where regulatory compliance and material science innovation intersect to create distinct value propositions across various end-use sectors.
Product Type:
Product type segmentation highlights the volume-driven adoption of established chemistries versus the premium positioning of advanced alternatives.
- Fluoropolymer:These high-performance polymers offer superior oleophobic and hydrophobic properties, forming a robust barrier against oil and water-based stains. Demand concentrates in premium automotive interiors and specialized textile applications where combined repellency is critical, despite ongoing regulatory pressures.
- Silicone-Based:Engineered to create a low surface energy, silicone-based coatings effectively repel water and many common staining agents, serving as a key non-PFAS alternative. Their adoption is accelerating in automotive upholstery and technical textiles, driven by regulatory shifts and performance validation.
- Acrylic:Acrylic formulations provide good water repellency and durability at a competitive cost, often used in architectural coatings and general-purpose textile treatments.
- Polyurethane:These coatings are valued for their abrasion resistance and flexibility, finding application in automotive interiors and footwear where mechanical stress is common.
- Epoxy:Epoxy-based stain resistant coatings offer exceptional hardness and chemical resistance, primarily deployed in industrial flooring and protective finishes.
Mature deployment sits with Acrylic formulations. Newer deployment is concentrated in Silicone-Based chemistries.
Application:
Application drives material specification and performance requirements, influencing coating chemistry and durability standards.
- Automotive Interiors:This segment demands highly durable and long-lasting stain resistant coatings for upholstery, carpets, and trim, often backed by OEM warranties. North American and European automotive manufacturers are particularly stringent on performance and compliance with VOC limits.
- Textiles:Coatings for textiles require flexibility, wash durability, and often breathability, applied to apparel, home furnishings, and technical fabrics. Demand concentrates in manufacturing hubs like Vietnam and Bangladesh for export-oriented production.
- Consumer Electronics:Specialized, ultra-thin film solutions are required for device screens and casings to resist fingerprints and minor liquid spills. This application prioritizes optical clarity and minimal impact on device aesthetics.
- Packaging:Stain resistant coatings in packaging provide grease and moisture barriers, particularly for food contact materials. Compliance with food safety regulations from bodies like the US FDA and European EFSA is paramount.
- Footwear:Coatings for footwear enhance water and dirt repellency, extending product life and maintaining appearance for both casual and performance-oriented shoes.
The segment expanding most quickly is Automotive Interiors, driven by stringent OEM warranty programs.
End User:
End-user requirements dictate the specific performance metrics and regulatory compliance needs for stain resistant coatings.
- Fabric Manufacturers:These users require coatings that integrate seamlessly into large-scale textile finishing processes, ensuring consistent application and compliance with global apparel export standards. Their operations in Vietnam and Bangladesh are particularly sensitive to cost and regulatory changes.
- OEM Suppliers:Original Equipment Manufacturers demand coatings that meet rigorous performance specifications and long-term durability for components used in automotive, appliance, and consumer electronics sectors. Their procurement is highly sensitive to re-certification costs.
- Electronics Assemblers:These companies utilize precision coating techniques for delicate electronic components and device surfaces, focusing on thin-film solutions that do not interfere with functionality. Fingerprint resistance is a primary concern.
- Luxury Goods Producers:This segment prioritizes coatings that preserve the aesthetic and material integrity of high-value items, such as leather goods and premium textiles, without altering texture or appearance.
- Sportswear Brands:Sportswear manufacturers require coatings that enhance the performance attributes of technical fabrics, providing water and stain repellency while maintaining breathability and flexibility.
Regulatory shifts disproportionately affect Fabric Manufacturers, while Luxury Goods Producers focus on aesthetic preservation.
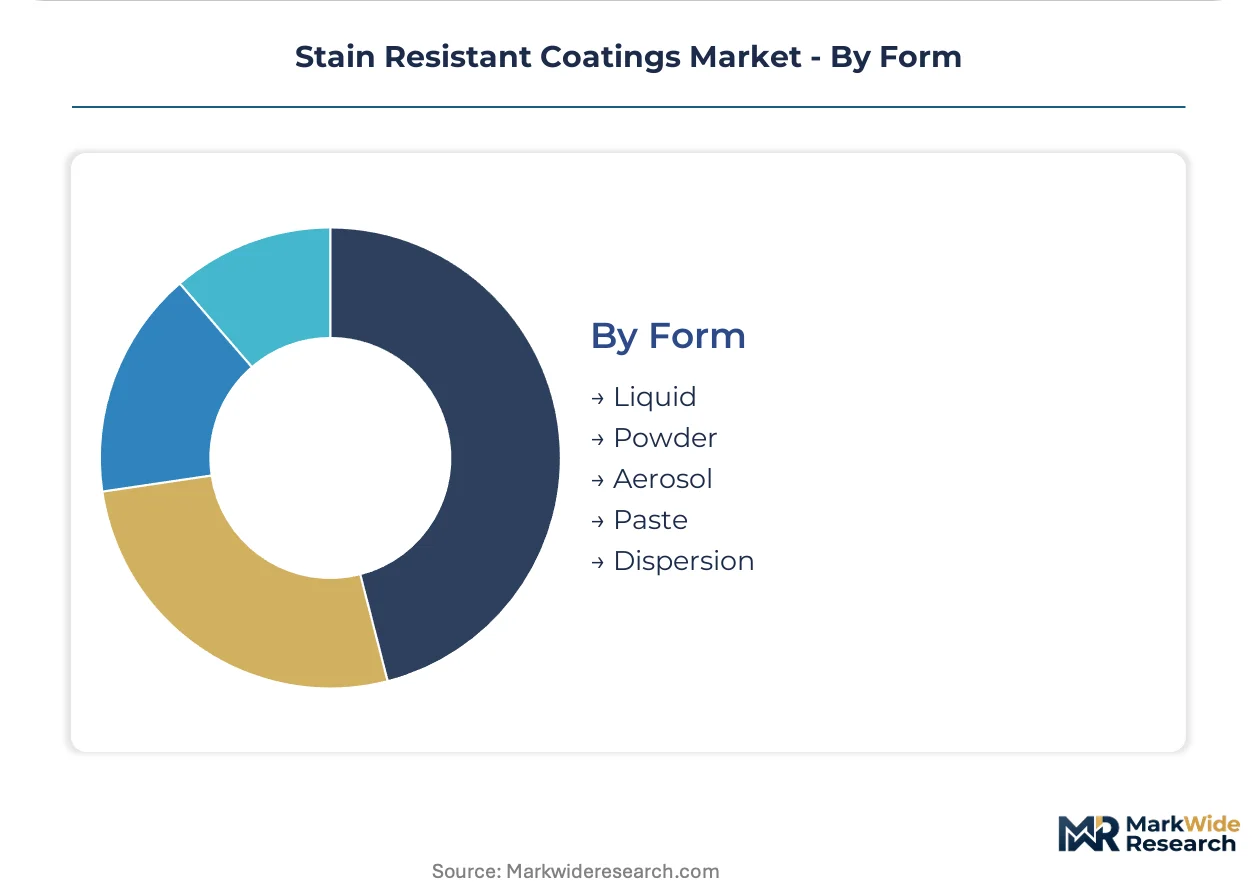
Form:
The physical form of the coating influences application methods and substrate compatibility, impacting industrial process efficiency.
- Liquid:Liquid coatings, either solvent or water-based, are versatile and applied through spraying, dipping, or rolling, making them suitable for a wide range of industrial and architectural applications. Their adaptability supports diverse manufacturing processes.
- Dispersion:These forms consist of fine solid particles suspended in a liquid medium, offering stable formulations crucial for uniform application in textile finishing and advanced material treatments. They provide consistent performance on complex substrates.
- Powder:Powder coatings are solvent-free and provide a durable, hard-wearing finish, primarily used on metal substrates in automotive and industrial sectors.
- Aerosol:Aerosol forms offer convenient, ready-to-use solutions, popular in consumer-facing products and DIY applications for localized treatment.
- Paste:Paste forms are characterized by their thicker consistency, suitable for specialized applications requiring high build-up or localized repair of surfaces.
Ease of application drives demand for Aerosol forms, whereas Liquid coatings are critical for large-scale industrial processes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The stain resistant coatings market exhibits a distinct geographical divide between high-volume manufacturing hubs and advanced consumption markets. While production for textiles concentrates in specific Asian nations, stringent performance demands and regulatory frameworks drive innovation and adoption across North American and European automotive and architectural sectors. This global interplay shapes regional investment and technology transfer.
United States
Automotive interior specifications and architectural applications generate significant demand for durable stain resistant coatings. The US EPA's PFAS Strategic Roadmap directly influences supply chains, compelling manufacturers to validate compliant coating inputs. Automotive clusters in Michigan and the Southeast drive adoption of advanced, warrantied coating systems.
Germany
European automotive OEMs demand high-performance, compliant coatings for vehicle interiors, supporting long-term warranties. The EU's REACH directive restricts legacy PFAS chemistries, accelerating the shift to non-fluorinated alternatives. Chemical industry centers in North Rhine-Westphalia and Bavaria develop and test next-generation silicone-based formulations.
China
Manufacturing activity for textiles and electronics creates substantial demand for functional coatings within China. The nation's GB standards impose strict limits on volatile organic compound content, influencing formulation costs. Industrial zones in the Yangtze River Delta and Pearl River Delta are key production and consumption centers for compliant coatings.
Vietnam
Textile manufacturing hubs in Vietnam require cost-effective and compliant stain resistant coatings for apparel exports. Global apparel brands increasingly mandate non-PFAS chemistries for products sourced from the region. Factories around Ho Chi Minh City and Hanoi integrate advanced silicone-based treatments into finishing processes.
Bangladesh
The ready-made garment industry in Bangladesh drives significant volume for textile coatings, particularly for water and stain repellency. International buyers enforce strict chemical management policies, pushing for the adoption of compliant, non-fluorinated alternatives. Textile processing zones around Dhaka and Chittagong adapt to evolving chemical input requirements.
Stain Resistant Coatings Market Key Industry Players
Capital-heavy producers compete with asset-light designers within the stain resistant coatings market, creating a tiered competitive structure. Diversified chemical giants anchor the foundational material supply, while specialized formulators drive innovation in high-performance segments. Key strategic archetypes include large-scale chemical manufacturers, niche fluoropolymer specialists, and application-focused solution providers. Competitive moves involve extensive research and development into compliant chemistries and expanding distribution networks to push validated systems.
Among the prominent players, BASF SE represents a diversified chemical conglomerate, leveraging broad R&D capabilities across numerous industrial applications. The Chemours Company exemplifies specialization, anchoring the premium segment with high-performance fluoropolymer technologies. PPG Industries, Inc. occupies a position as an integrated solutions provider, utilizing its extensive distribution network to deliver warrantied systems to automotive and architectural clients. These companies collectively illustrate the varied strategic approaches to market participation.
| Leading Market Players |
|---|
| BASF SE |
| Jotun |
| PPG Industries, Inc |
| 3M Company |
| Nippon Paint Holdings Co., Ltd. |
| Sherwin-Williams Company |
| Axalta Coating Systems |
| The Chemours Company |
| AkzoNobel N.V. |
| Others |
Cost & Logistics Intelligence
Automotive OEMs' stringent warranty demands dictate a value-based pricing model for stain resistant coatings. This concentrates pricing power among suppliers capable of delivering validated, long-term performance systems.
Pricing Analysis
Cost-down pressure on compliant non-PFAS formulations accelerates because advanced silicones often carry higher input costs. Pricing stratifies across performance tiers, with premium value-based pricing for long-term warranted systems. Performance validation and compliance certifications, such as REACH, drive price differentiation. Fabric manufacturers exhibit the highest price sensitivity, while Luxury Goods Producers prioritize aesthetic preservation over cost.
Supply Chain Analysis
Skilled workforce availability in chemical industry centers like Germany and China is critical for advanced coating production. Supply concentrates in these nations, alongside manufacturing hubs such as Vietnam for textile applications. The supply chain relies on fluoropolymer precursors, silicone intermediates, and specialized acrylic monomers. Regulatory restriction on PFAS chemistries represents a significant structural risk, impacting global availability; distribution runs through direct sales to large OEMs and specialized distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stain resistant coatings market is supply-constrained, with reformulation and re-certification processes creating a bottleneck. This capacity limitation props up pricing for validated, compliant alternative chemistries.
For Market Incumbents: Hedge against regulatory phase-outs of legacy PFAS by accelerating R&D investment in advanced silicone and acrylic formulations. Acquire specialized formulators with proven non-fluorinated solutions to mitigate performance gaps. Invest in certification processes for new chemistries to maintain market access and reinforce channel control against emerging substitute technologies. This secures long-term market position.
For New Entrants and Emerging Players: Direct-to-consumer online channels offer a route to penetrate specialized niche applications, particularly in consumer electronics for thin-film solutions. Target bio-based chemistries for environmentally conscious markets, differentiating through sustainability claims. Leverage performance-based warranty programs for specific applications to build trust and market share. Focus on segments currently underserved by large incumbents' broad offerings.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking proprietary non-PFAS technologies and validated performance. Long-term viability remains high, driven by regulatory shifts and sustained demand for durable stain resistant solutions. Acquire mid-sized formulators with strong R&D pipelines in advanced silicones or bio-based chemistries. The signal to watch is the successful commercial scale-up of bio-based alternatives, indicating a broader market shift.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increases supply of compliant non-PFAS chemistries in key manufacturing hubs. |
| R&D Investment | Develops next-generation bio-based and advanced silicone formulations for future demand. |
| Certification & Validation | Ensures new chemistries meet stringent OEM and global regulatory standards like REACH. |
| Distribution Network Expansion | Pushes warrantied systems into new architectural and automotive markets in Southeast Asia. |
| Strategic Partnerships | Secures localized application for textile manufacturers in Vietnam and Bangladesh. |
Research Approach
Independent corroboration across R&D directors, OEM procurement leads, and textile finishing plant managers underwrites the qualitative findings. Primary interviews with regulatory affairs specialists provided critical insights into compliance landscapes. Secondary validation utilized EPA filings, ECHA REACH documents, and China's GB standards. This approach ensured robust bottom-up and top-down triangulation for market sizing.
The forecast window was anchored to historical reference periods, establishing baseline market dynamics. An analytical framework modeled segmentation dimensions including product type, application, end-user, and form across the analysis window. Compound annual growth rates were derived from historical trends and projected impacts of regulatory changes. Key forecast inputs included PFAS phase-out timelines and OEM warranty program expansion.
The model holds under current regulatory trajectory and material science innovation pace; deviation in unexpected breakthroughs or rapid shifts in consumer preferences would shift market dynamics. Forecasts reflect documented assumptions regarding these factors. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Cellulosic Fire Protection Intumescent Coatings Market
Coatings
Global Heat Resistant Coatings Market
Coatings
Fluoropolymer Coating Market
Coatings
Coating Binders Market
Coatings
Color-Shifting Coating Market
Coatings
FEVE Fluoropolymer Coatings Market
Coatings
Asia-Pacific Superhydrophobic Coating Market
Coatings
Marine Nanocoating Market
Coatings
Global Floor Coatings Market
Coatings
Conductive Polymer Coatings Market
Coatings
Camouflage Coatings Market
Coatings
High Temperature Coatings Market
Coatings
Coated Casing Market
Coatings
Process Pipe Coating Market
Coatings
Global Industrial Floor Coatings Market
Coatings
Polymer Modified Cementitious Coatings Market