
 Coating Auxiliaries Market | 2026-2036
Coating Auxiliaries Market Size, Share, and Industry Trends Forecast 2026-2036
Coating Auxiliaries Market Outlook
ISO 14001 environmental management certification is unwinding competitive barriers for coating auxiliary suppliers seeking automotive OEM qualification. BASF SE leverages captive petrochemical feedstock to sustain margin on dispersant grades. Evonik Industries AG anchors its position through silicone-based wetting agent specialization. Dow Inc. competes on scale in North American emulsion polymer supply.
Coating auxiliaries encompass functional additives—dispersants, surfactants, wetting agents, and rheology modifiers—typically dosed at 0.1–5.0 wt% in liquid or powder form to stabilize pigment distribution, reduce surface tension, and control application viscosity in formulated coatings. These chemistries enable high-solids and waterborne systems to meet performance parity with legacy solvent-borne films. Dispersants command the deepest margin pools due to patent-protected polymeric architectures and qualification lock-in with automotive OEMs. Wetting agents are expanding fastest in waterborne industrial coatings as metal substrate adhesion requirements tighten. Powder-form additives remain mature in architectural segments where shelf stability and shipping economics dominate procurement criteria.
REACH registration dossiers and the EU Green Deal carbon border adjustments are forcing reformulation of solvent-borne industrial coatings toward bio-based auxiliary chemistries. EPA TSCA Section 5 premanufacture notices and OSHA permissible exposure limits shape product registration timelines and plant capital allocation in the United States. China's GB standards on volatile organic compound emissions in protective coatings are redirecting local auxiliary demand toward low-HAP emulsion systems. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded formulation investments and misaligned R&D pipelines.
Market Dynamics
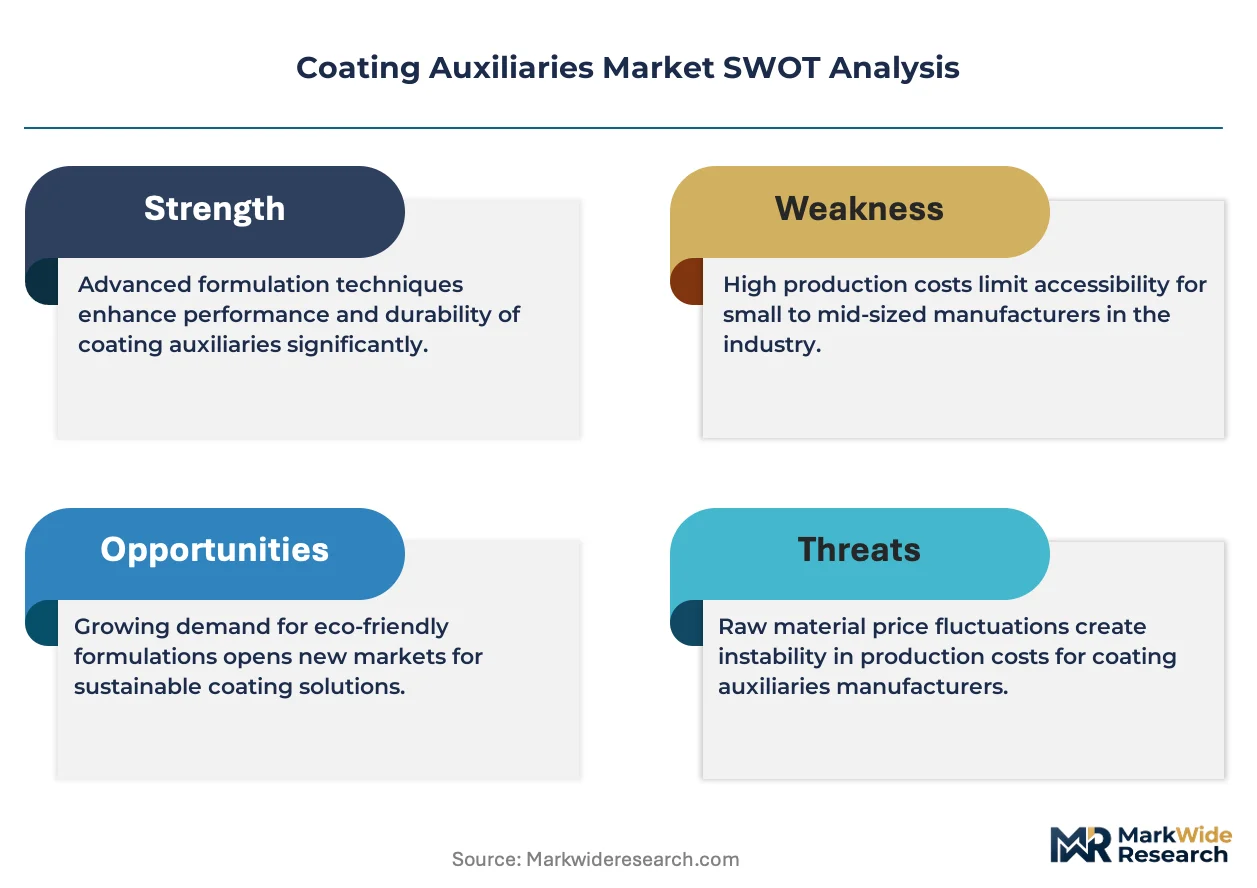
REACH registration dossiers and EU Green Deal carbon border adjustments are forcing wholesale reformulation of solvent-borne industrial coatings toward bio-based auxiliary chemistries, compressing legacy product margins while opening premium positioning for compliant suppliers.
Growth Catalysts
- Automotive OEM low-VOC mandates:German car manufacturers are expanding procurement specifications for wetting agents with volatile organic compound content below 50 g/L in basecoat applications.
- China GB standards on VOC emissions:Protective coatings regulations issued by MEE are redirecting auxiliary demand toward low-HAP emulsion systems in industrial maintenance sectors.
- Waterborne technology parity:Advances in polyurethane dispersion chemistry enable waterborne systems to match solvent-borne adhesion on metal substrates, unlocking automotive and machinery end-uses.
Market Restraints
- Petrochemical feedstock volatility:Propylene oxide and ethylene oxide price swings directly compress margins on polyether dispersant production.
- German supply concentration:Ludwigshafen and Leverkusen chemical clusters host disproportionate share of European dispersant capacity, creating single-point vulnerability.
- Bio-based performance gaps:Plant-derived surfactants fail to match silicone-based wetting agents on substrate wetting speed in high-speed coil coating lines.
Strategic Opportunities
- India protective coatings expansion:BIS certification requirements for industrial paints are creating qualified supplier shortages that foreign auxiliary producers can fill through local blending partnerships.
- UV-curable auxiliary development:Photoinitiator-compatible dispersants for energy-cured wood coatings represent unserved demand in furniture manufacturing hubs.
- EU Green Deal carbon border mechanism:Import tariffs on high-carbon coatings will advantage European auxiliary producers with certified low-carbon production processes.
Industry Challenges
- ISO 14001 automotive qualification timelines:Environmental management certification cycles stretch 18-24 months, delaying supplier onboarding for urgent OEM reformulation programs.
- Multi-jurisdiction registration divergence:Separate dossier requirements under REACH, EPA TSCA Section 5, and China MEE force redundant toxicology testing and fragment R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coating Auxiliaries Market |
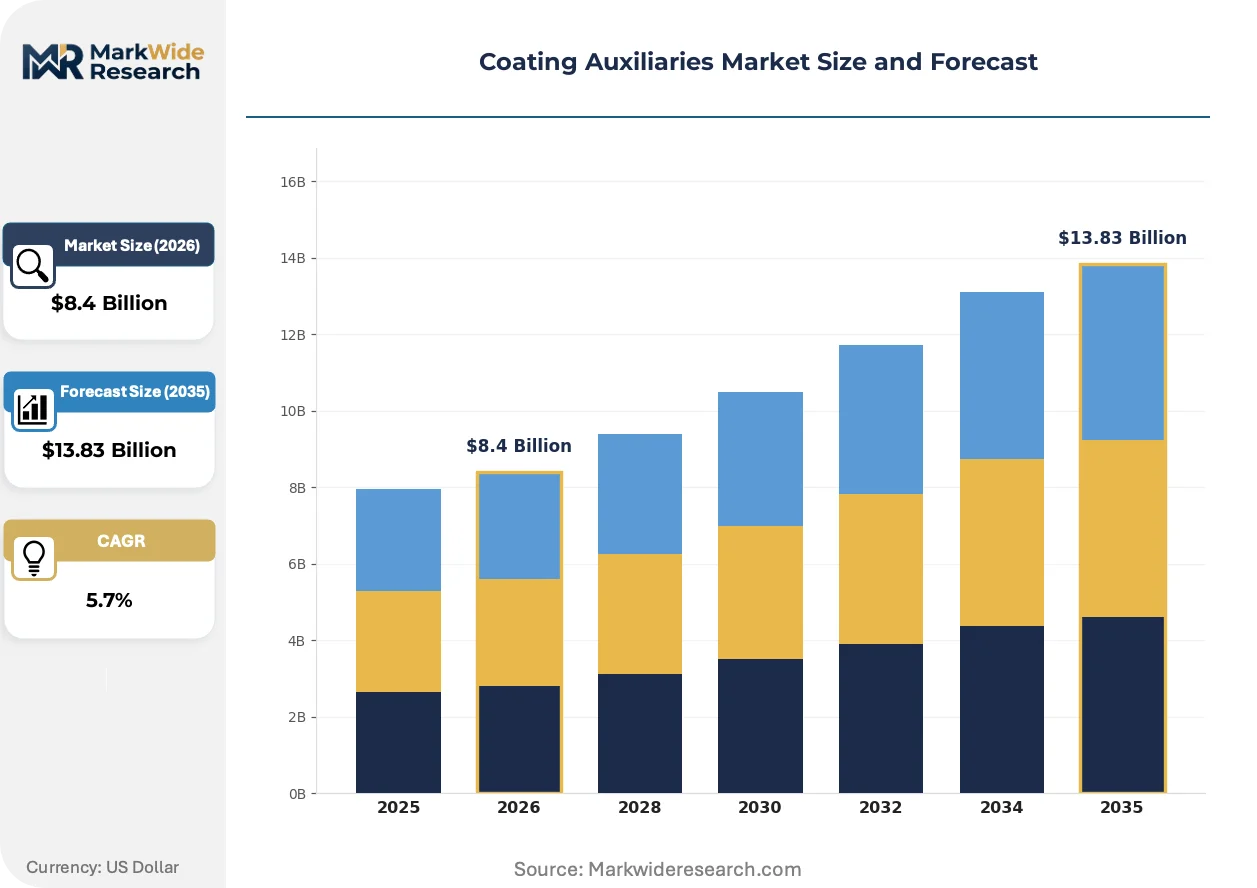
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dispersants, Surfactants, Wetting Agents, Additives Application: Automotive Coatings, Industrial Coatings, Wood Finishes, Protective Coatings End User: Manufacturers, Contractors, Distributors, Retailers Form: Liquid, Powder, Pastes, Emulsions |
| Companies Covered | BASF SE, Dow Inc., Evonik Industries AG, Clariant International Ltd., Huntsman Corporation, Solvay S.A., Lanxess AG, Arkema Group, Zschimmer & Schwarz GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coating Auxiliaries Market Strategic Shifts
Digital formulation platforms and closed-loop manufacturing controls are compressing development cycles for coating auxiliaries while tightening performance tolerances. Suppliers must now integrate real-time viscosity modeling with raw material traceability systems.
Polymeric dispersant architecture is miniaturizing through dendrimer and hyperbranched polymer designs that achieve equivalent pigment stabilization at 30-40% lower dosage rates. Automotive OEMs in Germany and Japan are qualifying these grades for metallic basecoats where film thickness budgets are shrinking. The technology is miniaturizing auxiliary volume per vehicle, pressuring suppliers to capture value through performance premiums rather than volume growth.
EPA TSCA Section 5 premanufacture notice requirements are lengthening introduction timelines for novel surfactant chemistries by 12-18 months. Industrial coatings formulators in the United States are responding by accelerating qualification of existing substances for new applications rather than developing new molecular entities. Waterborne industrial maintenance coatings bear the greatest compliance burden as legacy solvent-borne alternatives face simultaneous OSHA permissible exposure limit reductions.
Specification bundling by multinational paint manufacturers is consolidating auxiliary procurement decisions at regional headquarters rather than individual plant levels. Tier-2 coating producers in Southeast Asia are losing direct supplier relationships as BASF, Evonik, and Dow negotiate framework agreements with AkzoNobel and PPG at European or North American headquarters. Procurement centralization is compressing price negotiation cycles and favoring suppliers with multi-continent manufacturing footprints capable of uniform product specifications across Ludwigshafen, Freeport, and Ningbo facilities.
Coating Auxiliaries Market Segmentation
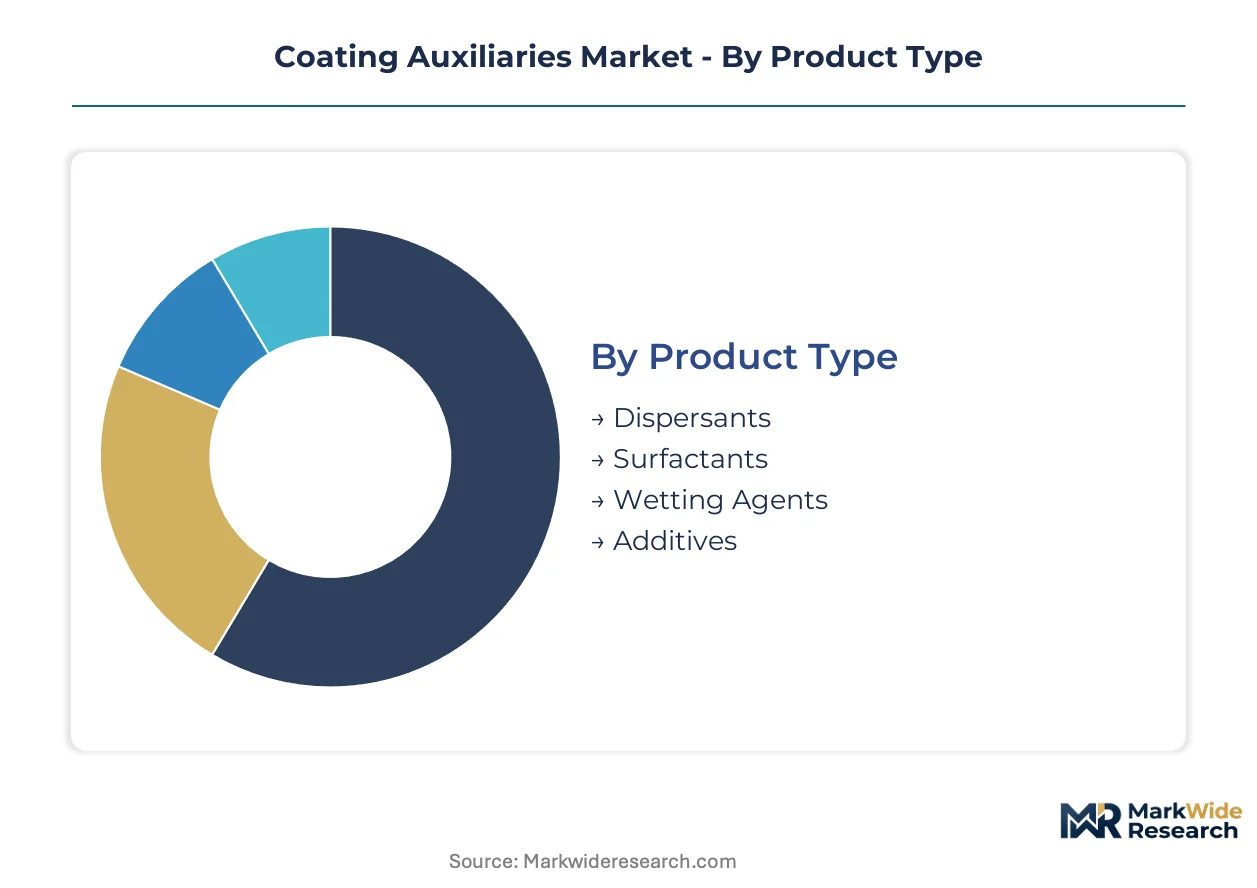
Segmentation in coating auxiliaries reveals how procurement power, formulation complexity, and regulatory compliance intersect across distinct commercial channels. Each dimension shapes margin capture differently—product type determines patent protection intensity, while application end-use dictates qualification timelines with OEMs.
Product Type:
Dispersants flow through direct technical sales channels to automotive OEMs, while surfactants and wetting agents distribute through regional distributors serving industrial maintenance contractors. Additives reach architectural formulators via bulk blending terminals.
- Dispersants:Polymeric architectures with anchoring groups stabilize pigment distribution in high-solids automotive basecoats. Demand concentrates with German automotive OEMs qualifying low-VOC metallic finishes under REACH dossier requirements.
- Surfactants:Surface-active chemistries reduce interfacial tension in waterborne industrial primers. Demand is accelerating in China's protective coatings sector as MEE GB standards tighten VOC ceilings on maintenance applications.
- Wetting Agents:Silicone and fluorosurfactant chemistries enable substrate wetting on metal coil lines.
- Additives:Defoamers, rheology modifiers, and flow agents complete formulation stability.
Dispersants dominate installed base. Wetting agents are where expansion concentrates.
Application:
Automotive coatings command the longest qualification cycles and deepest margin pools. Industrial coatings, wood finishes, and protective coatings serve fragmented contractor bases with faster procurement but price-sensitive specifications.
- Automotive Coatings:OEM basecoat and clearcoat systems require ISO 14001-certified auxiliary suppliers with 18-24 month qualification timelines. Demand concentrates in Germany's Ludwigshafen and Leverkusen chemical clusters serving Volkswagen, BMW, and Mercedes-Benz reformulation programs.
- Industrial Coatings:Machinery and equipment finishes prioritize corrosion resistance over aesthetic depth. Demand is climbing fastest in India's industrial corridor as BIS certification requirements create qualified supplier shortages for protective paint formulators.
- Wood Finishes:Furniture and cabinetry coatings favor UV-curable systems with photoinitiator-compatible dispersants.
- Protective Coatings:Infrastructure and marine applications specify high-build epoxy systems with sag-control additives.
Automotive coatings anchor premium pricing. Industrial coatings are gaining share fastest.
End User:
Manufacturers procure through framework agreements with multi-continent suppliers, while contractors purchase spot quantities through regional distributors. Retailers serve DIY architectural segments with pre-formulated consumer products.
- Manufacturers:Multinational paint producers centralize auxiliary procurement at European or North American headquarters, compressing negotiation cycles with BASF, Evonik, and Dow. Specification bundling favors suppliers with uniform product specifications across Ludwigshafen, Freeport, and Ningbo facilities.
- Contractors:Industrial maintenance applicators in Southeast Asia are losing direct supplier relationships as procurement centralizes.
- Distributors:Regional chemical distributors stock fast-moving wetting agent and dispersant grades for mid-tier formulators.
- Retailers:Home improvement channels move consumer-grade paint additives in small-package formats.
Manufacturers control volume concentration. Contractors represent the most contested channel.
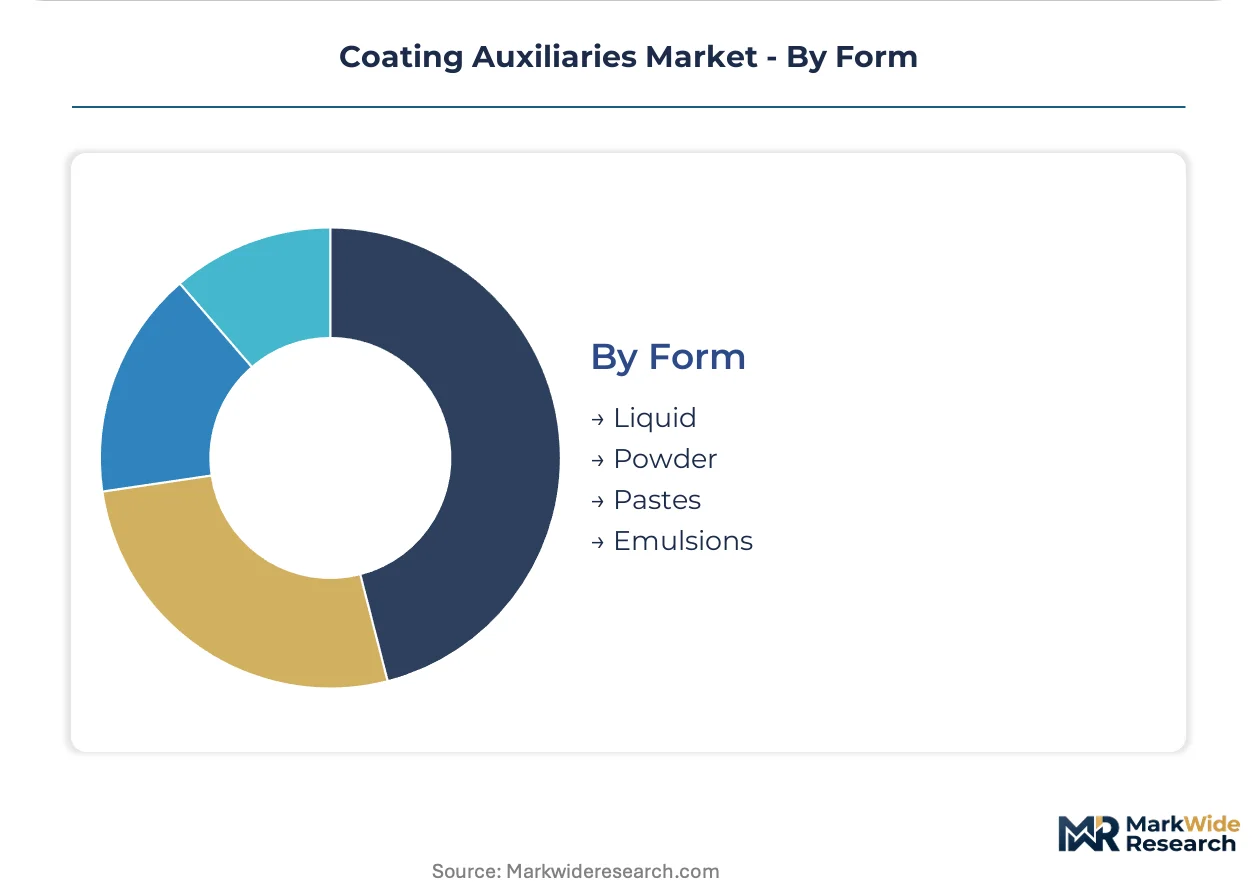
Form:
Liquid and emulsion forms dominate waterborne system adoption, while powder forms retain share in architectural segments where shipping economics and shelf stability matter. Pastes serve niche high-concentration applications.
- Liquid:Pumpable concentrates enable automated dosing in continuous coating lines. Demand concentrates with automotive OEMs in Germany and Japan qualifying dendrimer dispersant architectures for metallic basecoats where film thickness budgets are shrinking.
- Emulsions:Aqueous dispersed phases stabilize waterborne polyurethane systems. Demand is expanding in China's industrial maintenance sector as MEE regulations redirect formulation away from solvent-borne alternatives.
- Powder:Dry-flow additives serve architectural coating producers prioritizing inventory stability.
- Pastes:High-solids concentrates target specialty wood finish applications.
Liquid forms dominate current formulation share. Emulsions are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and industrial coatings formulators concentrate procurement decisions in four distinct chemical manufacturing clusters, each shaped by divergent regulatory timelines and feedstock access.
Germany
Volkswagen, BMW, and Mercedes-Benz mandate low-VOC wetting agents below 50 g/L for metallic basecoat applications. REACH dossier requirements and the EU Green Deal carbon border mechanism compress legacy solvent-borne margins while opening premium positioning for compliant suppliers. Ludwigshafen and Leverkusen chemical clusters host disproportionate European dispersant capacity, creating single-point vulnerability.
United States
Industrial maintenance contractors accelerate waterborne system adoption as OSHA permissible exposure limits tighten on legacy solvent-borne alternatives. EPA TSCA Section 5 premanufacture notices lengthen novel surfactant introduction timelines by 12-18 months. Freeport, Texas petrochemical infrastructure anchors polyether dispersant production despite propylene oxide price volatility.
China
MEE GB standards on VOC emissions redirect protective coatings demand toward low-HAP emulsion systems in industrial maintenance sectors. Waterborne polyurethane dispersion chemistry advances enable parity with solvent-borne adhesion on metal substrates. Ningbo chemical parks concentrate auxiliary blending capacity serving domestic automotive and machinery OEMs.
India
BIS certification requirements for industrial paints create qualified supplier shortages that foreign auxiliary producers fill through local blending partnerships. Infrastructure and automotive manufacturing expansion drives protective coatings consumption. Gujarat and Maharashtra industrial corridors attract dispersant toll-manufacturing agreements with multinational suppliers.
Japan
Automotive OEMs qualify dendrimer dispersant architectures for metallic basecoats where film thickness budgets are shrinking. METI regulations on carbon intensity in chemical production favor low-carbon auxiliary imports under bilateral trade frameworks. Kansai and Chubu chemical clusters specialize in silicone-based wetting agent refinement for high-speed coil coating lines.
Coating Auxiliaries Market Competitive Environment
Player mix skews toward diversified chemical conglomerates with captive petrochemical feedstock positions. Market structure concentrates around three strategic archetypes: integrated petrochemical majors leveraging backward integration into ethylene oxide and propylene oxide supply, silicone chemistry specialists commanding premium positioning in wetting agents, and regional toll-blenders serving price-sensitive architectural segments. Competitive dynamics center on multi-continent manufacturing footprints capable of uniform product specifications and framework agreement negotiation with centralized procurement functions at multinational paint manufacturers.
Within the integrated petrochemical tier, BASF SE and Dow Inc. anchor positions through scale advantages in polyether dispersant production and emulsion polymer supply respectively. Evonik Industries AG exemplifies the silicone chemistry specialist archetype, occupying premium positioning through substrate wetting technology. These three entities represent the dominant competitive anchors against which mid-tier suppliers and regional blenders benchmark qualification timelines and pricing structures.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Evonik Industries AG |
| Clariant International Ltd. |
| Huntsman Corporation |
| Solvay S.A. |
| Lanxess AG |
| Arkema Group |
| Zschimmer & Schwarz GmbH & Co. KG |
| Others |
Value Chain & Pricing Dynamics
Captive ethylene oxide capacity at Ludwigshafen and Freeport anchors margin structures for polyether dispersant producers, compressing price floors for non-integrated competitors while concentrating procurement leverage with automotive OEMs seeking multi-year supply assurance. Scale advantages in captive petrochemical feedstock translate directly into pricing power across wetting agent and dispersant grades, forcing toll-blenders toward service-based differentiation.
Pricing Analysis
Cost-plus contracts with ethylene oxide indexation dominate long-term supply agreements between integrated producers and automotive OEMs, insulating BASF and Dow from feedstock volatility while exposing regional blenders to spot market swings. Price differentiation separates ISO 14001-certified grades for German automotive qualification from uncertified architectural additives, with certification premiums widening as REACH dossier requirements tighten. Cost compression in standard wetting agents is intensifying because Chinese emulsion system suppliers are absorbing margin to capture industrial maintenance share. Contractors purchasing through regional distributors exhibit highest price sensitivity, while multinational paint manufacturers negotiating framework agreements at headquarters level prioritize specification uniformity over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites naphtha feedstock delivery to Ningbo chemical parks, creating logistics vulnerability for European and North American auxiliary producers dependent on Asian ethylene oxide derivatives. Supply concentrates in Germany, China, and the United States, with Ludwigshafen, Ningbo, and Freeport hosting disproportionate share of polyether dispersant capacity. Raw material dependencies center on propylene oxide, ethylene oxide, and silicone intermediates sourced from petrochemical complexes. Single-source vulnerability persists in high-purity silicone wetting agents refined in Kansai and Chubu clusters. Distribution runs through multinational paint manufacturer headquarters procurement functions, with BASF, Evonik, and Dow negotiating framework agreements that bypass regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and formulation support subscriptions are expanding faster than commodity additive volumes, transforming coating auxiliaries from transactional chemical supply into embedded process partnerships. Recurring-revenue attachment rates climb highest among automotive OEM qualification programs where 18-24 month certification cycles lock in multi-year service relationships.
For Market Incumbents: Secure dendrimer dispersant architecture patents through accelerated R&D investment, as Japanese automotive OEMs qualify 30-40% dosage reduction grades that threaten volume-based revenue models. Defend against Chinese emulsion system suppliers absorbing margin in industrial maintenance by embedding real-time viscosity modeling and raw material traceability systems as subscription services. Capacity addition in Gujarat and Maharashtra industrial corridors addresses India's BIS certification-driven supplier shortages. For New Entrants and Emerging Players: Lead with UV-curable auxiliary development for furniture manufacturing hubs, where photoinitiator-compatible dispersants represent unserved demand absent from incumbent portfolios. India's protective coatings sector offers the most penetrable geography, with qualified supplier shortages under BIS certification creating immediate volume opportunity. Go-to-market execution should emphasize local blending partnerships rather than greenfield manufacturing, accelerating regulatory compliance without capital-intensive asset deployment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among silicone chemistry specialists with automotive OEM qualification lock-in, where substrate wetting technology generates multi-year service contracts resistant to price erosion. Long-term viability favors integrated producers with captive ethylene oxide supply and multi-continent manufacturing footprints capable of uniform specifications across Ludwigshafen, Freeport, and Ningbo. Acquisition targets should demonstrate ISO 14001 certification completion and active REACH dossier maintenance. The signal to watch is EPA TSCA Section 5 premanufacture notice backlog length, as extended timelines advantage existing substance qualification over novel chemistry development.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Captive petrochemical feedstock insulates margin from propylene oxide price volatility at Ludwigshafen. |
| Green Manufacturing Transition | EU Green Deal carbon border mechanism advantages certified low-carbon production processes for European auxiliary exports. |
| Long-term Supply Agreement | Framework contracts with AkzoNobel and PPG at headquarters level compress negotiation cycles and lock volume. |
| Joint Venture | Local blending partnerships in Gujarat industrial corridors address India's BIS certification requirements without greenfield capital. |
| Capacity Expansion | Ningbo chemical park auxiliary blending capacity serves domestic Chinese automotive and machinery OEM reformulation programs. |
Study Parameters
A spread of perspectives from coating formulators, automotive OEM procurement teams, chemical plant managers, and regional distribution partners converged on the working assumptions driving this analysis. Primary interviews with technical R&D directors at multinational paint manufacturers and regulatory affairs leads navigating REACH, EPA TSCA Section 5, and China MEE requirements were cross-validated against secondary sources including customs and trade data, SEC 10-K filings, and ACC/Cefic industry reports. Bottom-up volume estimates by product type and application were triangulated against top-down market sizing derived from petrochemical feedstock consumption patterns.
Segmentation dimensions modeled include dispersant, surfactant, wetting agent, and additive product categories; automotive, industrial, wood finish, and protective coating applications; liquid, emulsion, powder, and paste forms; and manufacturer, contractor, distributor, and retailer end-user channels. CAGRs were derived from regression analysis of historical formulation adoption rates and regulatory compliance timelines across the projection horizon. Industry-specific forecast inputs incorporated automotive OEM metallic basecoat qualification cycles and waterborne polyurethane dispersion chemistry advancement trajectories.
Forecasts assume regulatory continuity in REACH, EPA TSCA, and China MEE regimes; material policy shifts would require re-modeling of solvent-borne to waterborne transition timelines. Assumptions reflect stable petrochemical feedstock availability and unimpeded logistics through Strait of Malacca transit routes. Revision becomes warranted when carbon border adjustment implementation crosses thresholds that restructure European import competitiveness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Russia Architectural Coatings Market
Coatings
BRIC Performance Coatings Market
Coatings
2K Protective Coatings Market
Coatings
Protective Antimicrobial Coatings for High-Touch Surfaces Market
Coatings
Polyvinylidene Chloride (PVDC) Coated Films Market
Coatings
Global Coated Steel Market
Coatings
Global Hydrophobic Coating Market
Coatings
Europe Metal Finishing Market
Coatings
Global Fire-Resistant Coating Market
Coatings
Italy Protective Coatings Market
Coatings
South Korea Marine Coatings Market
Coatings
Marine Anti Fouling Coatings Market
Coatings
United Kingdom Protective Coatings Market
Coatings
Africa Automotive Refinish Coatings Market
Coatings
Asia-Pacific Coil Coatings Market
Coatings
Saudi Arabia Floor Coatings Market