
 Global Industrial Floor Coatings Market | 2026-2036
Global Industrial Floor Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Floor Coatings Market Foresight
Food processing plant construction is recalibrating demand toward antimicrobial and thermal-shock-resistant systems. RPM International Inc. leverages its broad distribution network across North American food safety infrastructure. Akzo Nobel N.V. anchors European demand through specialized polyurethane formulations for cold-storage environments. PPG Industries, Inc. competes on manufacturing scale in high-solids epoxy production for heavy-traffic logistics floors.
Industrial floor coatings are protective polymer systems applied at thicknesses from 2 mils to 250 mils to concrete substrates, engineered to resist chemical attack, abrasion, and thermal cycling in manufacturing environments. Epoxy formulations dominate installed volume due to cost-performance ratios in warehouse and general manufacturing applications, while polyurethane coatings command premium positioning for flexible, UV-stable requirements in electronics clean rooms. Water-based technologies are gaining formulation share as VOC regulations tighten across multiple jurisdictions, though solvent-based systems retain stronghold status in heavy machinery plants requiring rapid return-to-service.
EPA VOC regulations and REACH restrictions in Europe are forcing reformulation investments toward low-emission and bio-based chemistries, while China's MEE standards are tightening discharge controls for coating production facilities. ISO 14001 and OSHA slip-resistance mandates further shape product certification requirements for facility operators. Stakeholders must monitor regulatory divergence between jurisdictions to optimize regional product portfolios and avoid compliance-driven margin erosion.
Market Dynamics
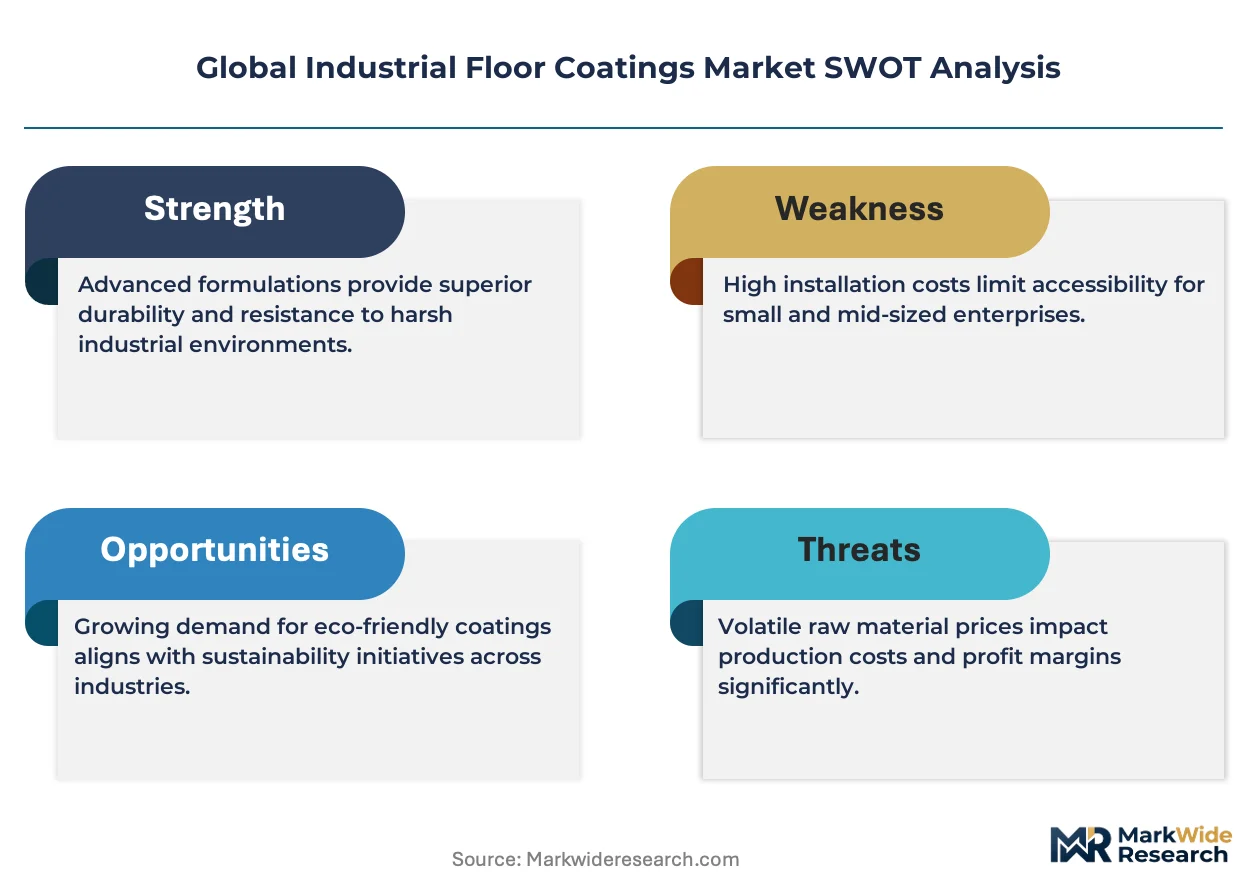
Formulation chemistry is pivoting under regulatory compression as REACH, EPA VOC limits, and China's MEE standards force simultaneous reformulation across three major production zones, squeezing solvent-based epoxy margins while elevating water-based and bio-alternatives.
Growth Catalysts
- Pharmaceutical Cleanroom Expansion:Sterile manufacturing protocols in injectable drug facilities are mandating seamless, coved floor-to-wall coating systems with ISO 14644-1 compliance, driving specification upgrades.
- REACH Article 57 SVHC Restrictions:European manufacturers must eliminate bisphenol-A and isocyanate-heavy formulations from supply chains, accelerating investment in hybrid polyaspartic alternatives.
- Guangdong-Jiangsu Industrial Cluster Buildout:State-directed development zones in China's Pearl and Yangtze River deltas are specifying heavy-duty epoxy and polyurethane systems for new logistics and electronics manufacturing floors.
Market Restraints
- Petrochemical Feedstock Volatility:Epoxy resin prices fluctuate with benzene and propylene supply disruptions from Gulf Coast refining capacity constraints.
- Specialized Applicator Concentration:Certified installation contractors cluster in Germany, the US, and Japan, creating 6-12 month project backlogs in emerging manufacturing regions.
- Cementitious Polymer Overlay Substitution:Self-leveling concrete systems with integral hardeners capture 15-20% of light-duty warehouse specifications previously held by thin-film coatings.
Strategic Opportunities
- Vietnam Electronics Manufacturing Corridor:Samsung and Foxconn supplier park expansions near Bac Ninh and Hai Phong lack established coating specification standards, creating first-mover specification capture potential.
- US Inflation Reduction Act Clean Energy Manufacturing:Battery gigafactory construction in Michigan, Georgia, and Nevada mandates chemical-resistant, spark-resistant flooring for electrolyte handling zones.
- IoT-Enabled Predictive Maintenance Convergence:Embedded floor sensors monitoring coating wear and substrate moisture are creating recurring revenue attachment models for applicators.
Industry Challenges
- Certified Polysulfide Applicator Shortage:Cold-storage polyurethane and polysulfide systems require specialized moisture-controlled application training that outpaces vocational program output in North America and Europe.
- Multi-Jurisdiction Formulation Registration:Manufacturers maintaining separate SKUs for EPA, REACH, and GB standard compliance face inventory fragmentation and working capital strain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Floor Coatings Market |
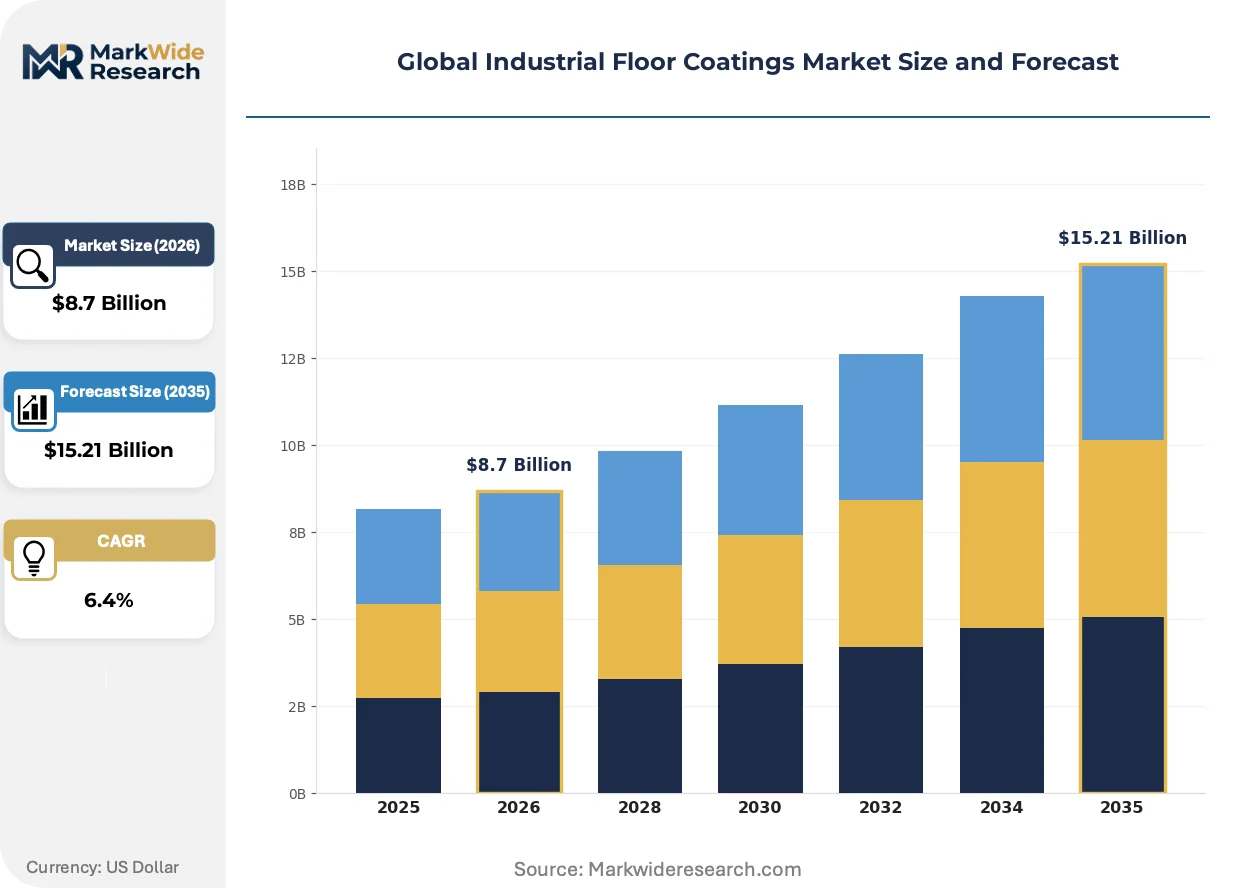
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
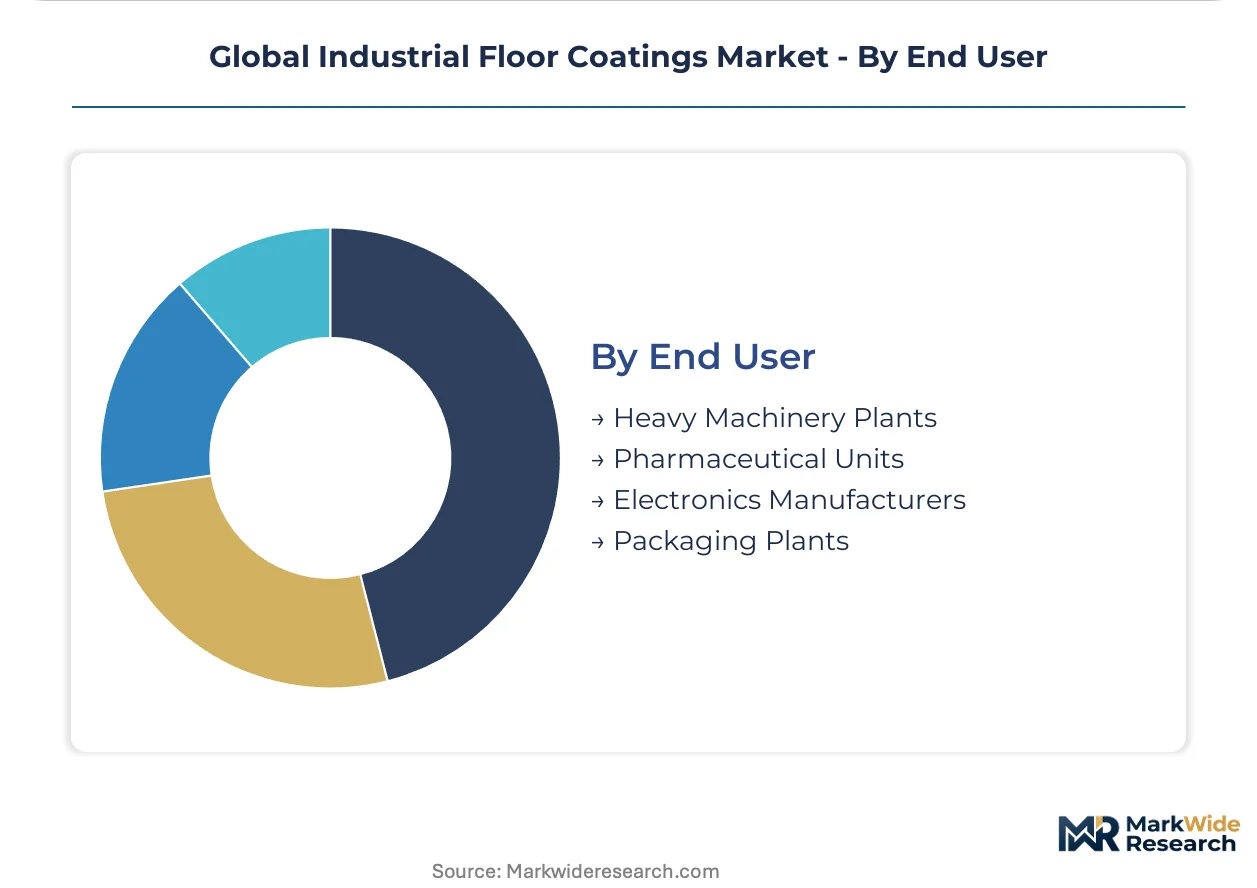
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Polysiloxane, Cementitious Technology: Solvent-Based, Water-Based, Powder Coatings, UV Cured, High-Solid Application: Warehouses, Manufacturing Facilities, Food Processing Plants, Clean Rooms, Laboratories End User: Heavy Machinery Plants, Pharmaceutical Units, Electronics Manufacturers, Packaging Plants |
| Companies Covered | RPM International Inc., Akzo Nobel N.V., PPG Industries, Inc., Jotun A/S, MAPEI S.p.A., The Sherwin-Williams Company, BASF SE, Hempel A/S, Sika AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Floor Coatings Market Shifts & Advancements
Active chemistry innovation is compressing cure cycles and expanding performance envelopes as regulatory pressure and operational uptime requirements converge on formulation laboratories.
Bio-based epoxy resins derived from lignin and plant-based polyols are electrifying R&D pipelines across European and North American suppliers. Food processing and pharmaceutical facilities in Denmark and the Netherlands are piloting these systems for VOC-neutral compliance. The technology is electrifying competitive positioning by enabling premium pricing against conventional petrochemical formulations while satisfying ESG procurement mandates.
EPA VOC Rule 40 CFR Part 59 Subpart D is tightening allowable emissions from architectural and industrial maintenance coatings, forcing reformulation of high-solids solventborne systems. Manufacturers serving the US market are accelerating waterborne epoxy and 100% solids polyurethane development. Heavy machinery plants in Ohio and Texas are accepting extended cure schedules to maintain regulatory access.
Facility operators are consolidating coating specification authority at corporate engineering levels, displacing decentralized plant maintenance purchasing. Regional applicators in France and Japan report direct engagement with headquarters engineering teams rather than site-level procurement. This concentration is most visible in multi-site food processing conglomerates seeking standardized HACCP-compliant flooring across their networks.
Global Industrial Floor Coatings Market Segmentation
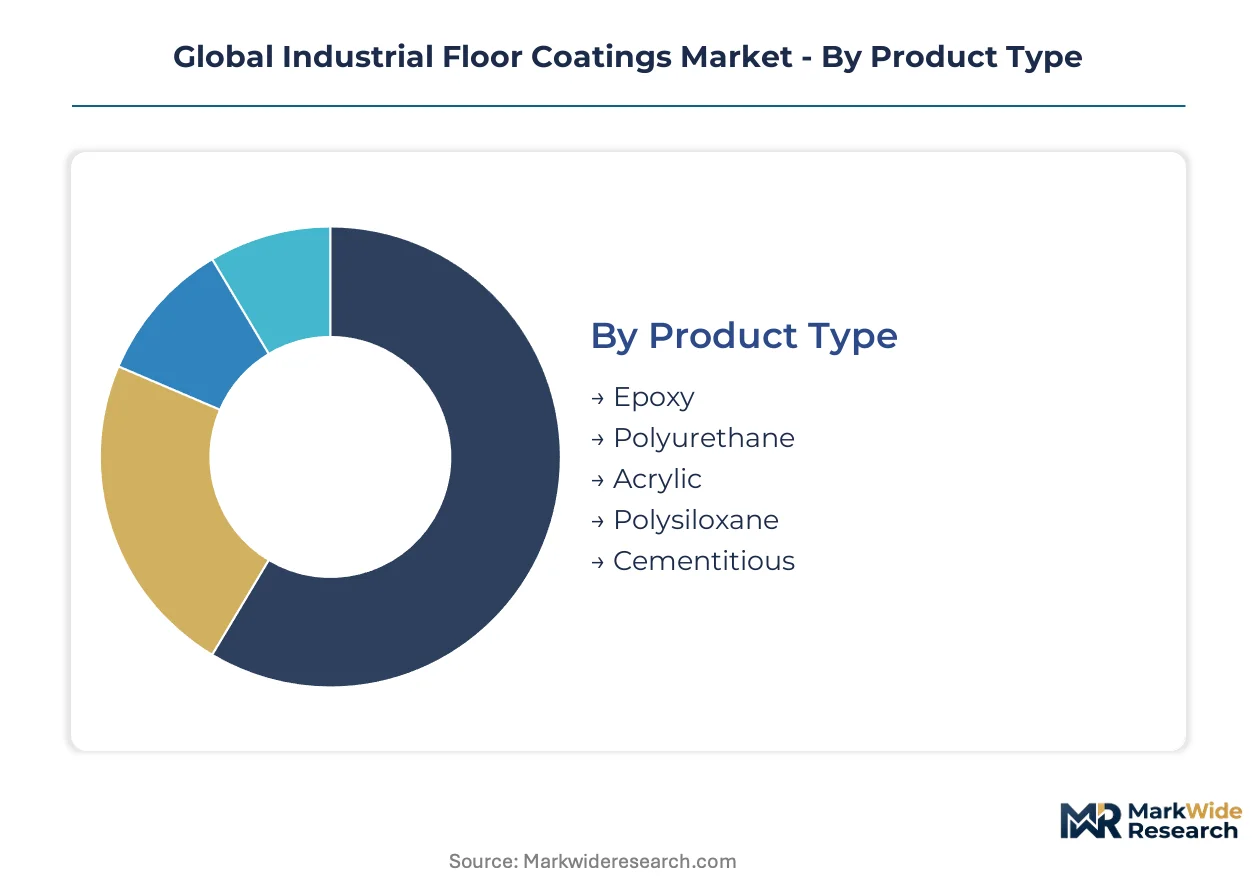
Industrial floor coatings demand fragments across chemistry, application method, and facility type, with each axis imposing distinct certification burdens and margin profiles. Procurement teams navigate specification complexity by mapping performance requirements against regulatory compliance tiers.
Product Type:
ISO 9001 quality management and facility-specific HACCP or FDA food contact approvals dominate certification requirements across product categories, with cold-storage and pharmaceutical applications layering GMP and EU 10/2011 migration testing obligations.
- Epoxy:Two-part thermosetting systems built from bisphenol-A or bisphenol-F resins with amine hardeners deliver chemical resistance and compressive strength for heavy-traffic zones. Demand concentrates in Guangdong logistics parks and Ohio automotive plants where rapid return-to-service and cost-performance ratios override premium alternatives. REACH Article 57 SVHC restrictions are forcing reformulation away from traditional aromatic amine curing agents.
- Polyurethane:Aliphatic and aromatic isocyanate-based formulations provide elastomeric recovery, UV stability, and thermal shock resistance for temperature-cycling environments. Electronics clean rooms in Bavaria and pharmaceutical suites in New Jersey specify these systems for seamless, coved installations meeting ISO 14644-1 particulate standards. Applicator certification scarcity limits deployment speed in emerging manufacturing corridors.
- Acrylic:Thermoplastic emulsions and solvent-borne systems offering moderate durability with faster cure schedules and lower material cost.
- Polysiloxane:Hybrid inorganic-organic coatings combining siloxane backbone flexibility with organic functional groups for extreme chemical exposure and thermal cycling.
- Cementitious:Polymer-modified Portland cement overlays with integral hardeners and sealers for heavy-duty slurry and trowel-applied specifications.
Leading the category by volume: Epoxy. Growing fastest: Polyurethane.
Technology:
Application method determines VOC exposure, cure speed, and capital equipment requirements, with water-based systems gaining share in regulated jurisdictions while solvent platforms retain dominance where rapid throughput and ambient temperature curing remain non-negotiable.
- Solvent-Based:Traditional alkyd, epoxy, and polyurethane formulations dissolved in aromatic or aliphatic hydrocarbons enabling low-temperature application and rapid film formation. Heavy machinery plants in Texas and Saudi Arabia specify these systems for 24-hour return-to-service despite EPA VOC Rule 40 CFR Part 59 Subpart D compliance costs.
- Water-Based:Emulsion and dispersion technologies using water as primary carrier with coalescing aids for film formation at ambient conditions. Food processing networks in Denmark and the Netherlands are mandating these platforms for ESG procurement alignment and worker exposure reduction.
- Powder Coatings:Thermosetting epoxy and hybrid powders applied electrostatically and oven-cured for zero-VOC, thick-film industrial specifications.
- UV Cured:Photoinitiator-activated acrylate and epoxy systems enabling instant cure under ultraviolet exposure for high-throughput manufacturing lines.
- High-Solid:Reduced-solvent formulations above 70% volume solids bridging regulatory compliance and traditional application performance.
Volume concentration: Solvent-Based. Steepest expansion trajectory: Water-Based.
Application:
Facility operational intensity and contamination sensitivity drive coating thickness, seam detailing, and coving requirements, with clean rooms and food plants imposing the most stringent substrate preparation and certification protocols.
- Warehouses:Thin-film epoxy and polyurethane sealers over concrete substrates for abrasion resistance in forklift and pallet-jack traffic zones. E-commerce fulfillment centers in Jiangsu province are specifying rapid-cure systems to minimize downtime during 24/7 operations.
- Manufacturing Facilities:Multi-layer epoxy and polyurethane builds with quartz or aluminum oxide broadcast for impact and chemical resistance across assembly and machining floors.
- Food Processing Plants:USDA-accepted, thermal-shock-resistant polyurethane and epoxy systems with antimicrobial additives and integral coving for drainage compliance. HACCP mandates in US and EU facilities are standardizing specification authority at corporate engineering levels.
- Clean Rooms:Seamless, low-outgassing polyurethane and epoxy systems with conductive or static-dissipative properties for ISO 14644-1 classified environments.
- Laboratories:Chemical-resistant epoxy and vinyl ester systems with containment curbs and secondary containment integration for spill protection.
Category anchor by specification volume: Warehouses. Fastest specification upgrade cycle: Clean Rooms.
End User:
Capital intensity and regulatory exposure vary dramatically across end-user categories, with pharmaceutical and electronics manufacturers driving premium chemistry adoption while packaging plants optimize for cost and speed.
- Heavy Machinery Plants:Thick-film, high-build epoxy and cementitious systems for impact resistance under stamping presses and forging equipment. Michigan and Georgia battery gigafactories are mandating spark-resistant, chemical-resistant platforms for electrolyte handling zones under IRA clean energy manufacturing incentives.
- Pharmaceutical Units:Validated, FDA 21 CFR Part 211 compliant flooring with documented installation and maintenance protocols for sterile and aseptic processing.
- Electronics Manufacturers:Static-control polyurethane and epoxy systems with precise resistivity ranges for semiconductor and component assembly.
- Packaging Plants:Cost-optimized epoxy and acrylic sealers for moderate chemical exposure and abrasion in printing, converting, and bottling operations.
Highest value per square meter: Pharmaceutical Units. Fastest facility construction pipeline: Heavy Machinery Plants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong's special economic zones and Jiangsu's industrial parks concentrate state-directed coating demand for electronics and logistics infrastructure. Germany's REACH enforcement and US battery manufacturing incentives reshape formulation requirements across major demand centers.
United States
Battery gigafactory construction in Michigan, Georgia, and Nevada drives specification of spark-resistant, chemical-resistant systems for electrolyte handling zones. EPA VOC Rule 40 CFR Part 59 Subpart D tightens allowable emissions from industrial maintenance coatings. Ohio and Texas heavy machinery plants accept extended cure schedules to maintain regulatory access.
Germany
Pharmaceutical suites in Bavaria and cold-storage facilities across the country specify seamless, coved polyurethane installations. REACH Article 57 SVHC restrictions eliminate bisphenol-A and isocyanate-heavy formulations from supply chains. Applicator certification programs concentrate in Baden-Württemberg and North Rhine-Westphalia, creating specialized labor bottlenecks.
China
State-directed development zones in the Pearl and Yangtze River deltas specify heavy-duty epoxy and polyurethane systems for new logistics and electronics manufacturing floors. MEE standards tighten discharge controls for coating production facilities. Guangdong and Jiangsu provinces anchor industrial park construction with accelerated procurement timelines.
Netherlands
Food processing networks mandate water-based platforms for ESG procurement alignment and worker exposure reduction. EU 10/2011 migration testing obligations layer onto facility-specific HACCP approvals. Rotterdam and Eindhoven industrial corridors pilot bio-based epoxy resins derived from lignin and plant-based polyols.
Vietnam
Samsung and Foxconn supplier park expansions near Bac Ninh and Hai Phong lack established coating specification standards. The country's national environmental regulator tightens industrial discharge monitoring for manufacturing zones. Northern manufacturing corridors present first-mover specification capture potential for antimicrobial and thermal-shock-resistant systems.
Global Industrial Floor Coatings Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation expertise commanding premium positioning in pharmaceutical and electronics applications while scale producers dominate warehouse and logistics specifications. The vendor base organizes around three strategic archetypes: integrated chemical conglomerates with resin backward integration, specialized coating formulators with certified applicator networks, and regional compounders serving price-sensitive construction markets. Dominant competitive moves include geographic expansion into Vietnam and Indonesia manufacturing corridors, plus portfolio diversification toward water-based and bio-based chemistries.
Among US-based diversified coating manufacturers, RPM International Inc. and PPG Industries, Inc. occupy positions anchored by distribution scale and high-solids production capacity. Akzo Nobel N.V. represents the European specialist archetype with polyurethane formulation depth for cold-storage and clean-room environments. These three exemplify how regulatory compliance investments and certified applicator network density separate premium-tier positioning from commodity competition.
| Leading Market Players |
|---|
| RPM International Inc. |
| Akzo Nobel N.V. |
| PPG Industries, Inc. |
| Jotun A/S |
| MAPEI S.p.A. |
| The Sherwin-Williams Company |
| BASF SE |
| Hempel A/S |
| Sika AG |
| Others |
Supply & Pricing Matrix
REACH Article 57 SVHC restrictions and EPA VOC Rule 40 CFR Part 59 Subpart D are forcing pharmaceutical and food processing buyers toward low-emission formulations, compelling suppliers to absorb reformulation costs while maintaining price accessibility for mid-tier warehouse operators.
Pricing Analysis
Short lead-time premiums of 15-25% apply to certified applicator networks in Germany and Japan where project backlogs stretch 6-12 months. Three-tier pricing structure across premium, standard, and economy levels separates GMP-validated pharmaceutical systems from general manufacturing epoxies and thin-film warehouse sealers. Price differentiation hinges on certification grade and geographic delivery cost. Cost compression in standard-tier epoxies is intensifying because cementitious polymer overlays capture 15-20% of light-duty specifications. Packaging plants exhibit highest price sensitivity; pharmaceutical units show least.
Supply Chain Analysis
Certified applicator shortages in North America and Europe constrain installation capacity despite resin availability from China, Germany, and the US. Epoxy formulation draws from benzene and propylene feedstocks anchored in Gulf Coast refining clusters. Single-source vulnerability concentrates in aromatic amine curing agents subject to REACH restrictions. Distribution runs through specialized contractor networks rather than commodity retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial floor coatings function as a cost-of-compliance market where REACH, EPA VOC, and China's MEE standards erect formulation barriers that favor incumbents with multi-jurisdiction registration capabilities and certified applicator networks.
For Market Incumbents: Lock in specification authority at corporate engineering levels of multi-site food processing conglomerates before decentralized procurement revives. Deepen backward integration into bio-based resin feedstocks to deflect petrochemical price volatility. Defend against cementitious overlay substitution by demonstrating lifecycle cost superiority in thermal-cycling environments. For New Entrants and Emerging Players: Bio-based epoxy systems derived from lignin present a technology-first wedge into Denmark and Netherlands food processing networks where ESG procurement mandates outpace incumbent reformulation speed. Target Vietnam's Bac Ninh and Hai Phong electronics corridors where Samsung and Foxconn supplier parks lack established coating standards. Lead with water-based platform demonstrations to capture first-mover specification authority. For Investors and Strategic Acquirers: The window for entry favors regional compounders with captive applicator training capacity in Southeast Asian manufacturing corridors. Long-term viability rests on formulation portfolios spanning solvent-based, water-based, and bio-based chemistries with unified SKU efficiency. Watch for MEE enforcement acceleration in Guangdong and Jiangsu as inflection signal for compliance-heavy market consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Resins | Secures lignin and plant-based polyol supply chains for REACH-compliant formulation leadership. |
| Certified Applicator Network Expansion | Addresses 6-12 month project backlogs in emerging manufacturing regions like Vietnam and Indonesia. |
| Multi-Jurisdiction SKU Consolidation | Reduces inventory fragmentation from separate EPA, REACH, and GB standard compliance requirements. |
| Corporate Engineering Direct Engagement | Captures specification authority as facility operators consolidate purchasing at headquarters level. |
| IoT-Enabled Predictive Maintenance Platform | Creates recurring revenue attachment through embedded floor sensors monitoring coating wear. |
Research Methodology
Document review covered customs and trade flow databases, SEC 10-K filings, ECHA REACH registration dossiers, and MEE discharge monitoring reports, complemented by interviews with plant engineers at heavy machinery facilities, procurement leads at pharmaceutical manufacturers, certified coating applicators, and technical R&D directors at formulation houses. Bottom-up demand modeling triangulated against top-down macroeconomic indicators across the analysis window.
Segment-level projections incorporated chemistry type, application method, facility operational intensity, and regional regulatory cluster as core dimensions. CAGRs derived from regression analysis of historical installation volumes against industrial construction permits and capital expenditure disclosures. Battery gigafactory construction pipelines and pharmaceutical cleanroom expansion timelines served as industry-specific demand anchors.
Several conditions sit outside the modeled scope, including abrupt petrochemical feedstock disruptions, trade policy shifts affecting resin import tariffs, and unforeseen regulatory harmonization between EPA and MEE standards. Forecasts reflect assumptions about continued enforcement trajectories for existing VOC and SVHC restrictions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
High Performance Coatings Market
Coatings
Batters and Coatings Market
Coatings
US Concrete Floor Coatings Market
Coatings
Global Flat Glass Coatings Market
Coatings
Glass Coatings Market
Coatings
Global PET Film Coated Steel Coil Market
Coatings
Mexico Floor Coatings Market
Coatings
Corrosion Protective Coatings and Acid Proof Lining Market
Coatings
Physical Vapor Deposition (PVD) Coatings Market
Coatings
Cladding Coatings Market
Coatings
High Build Rust Stabilizer with Reinforced Glass Flake Coating Market
Coatings
Plasma Impulse Chemical Vapor Deposition (PICVD) Coating Market
Coatings
Asia-Pacific Coil Coatings Market
Coatings
France Automotive OEM Coatings Market
Coatings
Coating Market
Coatings
Thermal Insulation Coating Market