
 Next-Generation Titrators Market | 2026-2036
Next-Generation Titrators Market Size, Share, and Industry Trends Forecast 2026-2036
Next-Generation Titrators Market Foresight
Software-defined calibration and remote diagnostics is realigning what instrument vendors actually sell, shifting revenue from hardware transactions to recurring service contracts. Metrohm leverages its service infrastructure across European pharmaceutical hubs to lock in multi-year agreements. Hanna Instruments anchors its position in water treatment through localized support networks and rapid replacement part availability. Thermo Fisher Scientific differentiates via cloud-connected titration platforms that feed directly into enterprise LIMS architectures.
Next-generation titrators are precision analytical instruments that automate the quantitative determination of analyte concentration through controlled reagent delivery, with modern units achieving resolution down to microliter increments and real-time electrochemical endpoint detection. These systems serve industrial and commercial laboratories by eliminating human titration error, accelerating throughput, and generating auditable compliance data for regulated substances. Automated titrators command the largest installed base and margin pool, while multichannel configurations represent the fastest-growing product category as high-volume labs consolidate multiple analytical workflows onto single platforms. Among end users, pharmaceutical labs generate the strongest replacement demand, though water treatment facilities are expanding fastest as utilities face tightening discharge monitoring obligations.
FDA cGMP guidelines and EPA Clean Water Act methods shape instrument specifications, mandating electronic records, audit trails, and validated analytical procedures that only automated, software-integrated titrators can satisfy. ISO 17025 accreditation requirements further filter vendor selection toward suppliers offering documented uncertainty budgets and traceable calibration certificates. Stakeholders must weigh total cost of ownership against connectivity readiness, as regulatory bodies on both sides of the Atlantic advance digital submission requirements that favor instruments with native data-export architectures.
Market Dynamics
Software-defined calibration and remote diagnostics are compressing instrument vendor business models from hardware transactions toward recurring service revenue, locking laboratories into multi-year agreements through predictive maintenance and cloud-connected compliance architectures.
Growth Catalysts
- FDA cGMP electronic records mandates:Drug manufacturers in the United States face audit trail requirements that only automated, software-integrated titrators satisfy, forcing replacement of manual and semi-automated systems.
- Water utilities in Germany:Chemical manufacturers and municipal treatment operators upgrade legacy potentiometric installations to multichannel platforms capable of simultaneous parameter monitoring.
- ISO 17025 accreditation expansion:Third-party testing laboratories across industrial hubs demand documented uncertainty budgets and traceable calibration certificates, filtering procurement toward validated suppliers.
Market Restraints
- High-purity reagent cost volatility:Karl Fischer and potentiometric titrations depend on certified anhydrous solvents and standardized titrants whose prices fluctuate with petrochemical feedstock markets.
- Electrode supply concentration:Specialized glass and ion-selective electrode manufacturing clusters in Switzerland and Germany create single-source dependencies for precision sensing components.
- Legacy LIMS integration friction:Existing enterprise laboratory information management systems often lack native API architectures, complicating data export and digital submission workflows.
Strategic Opportunities
- Contract research organizations in India:CDSCO-regulated bioequivalence and stability testing labs represent underpenetrated demand for automated Karl Fischer moisture determination systems.
- EPA Clean Water Act method updates:Revised discharge monitoring protocols create procurement windows for utilities requiring alkalinity, hardness, and chloride automation.
- Edge-to-cloud convergence:Titration platforms combining local analytical execution with centralized data lakes enable pharmaceutical quality control networks to consolidate distributed laboratory footprints.
Industry Challenges
- Electrochemical sensor calibration expertise:Maintenance of ion-selective electrode response curves and junction potential stability requires specialized analytical chemists in short supply at mid-sized industrial laboratories.
- Multi-instrument validation timelines:FDA 21 CFR Part 11 compliance for software revisions demands documented IQ/OQ/PQ protocols that extend deployment cycles by months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next-Generation Titrators Market |
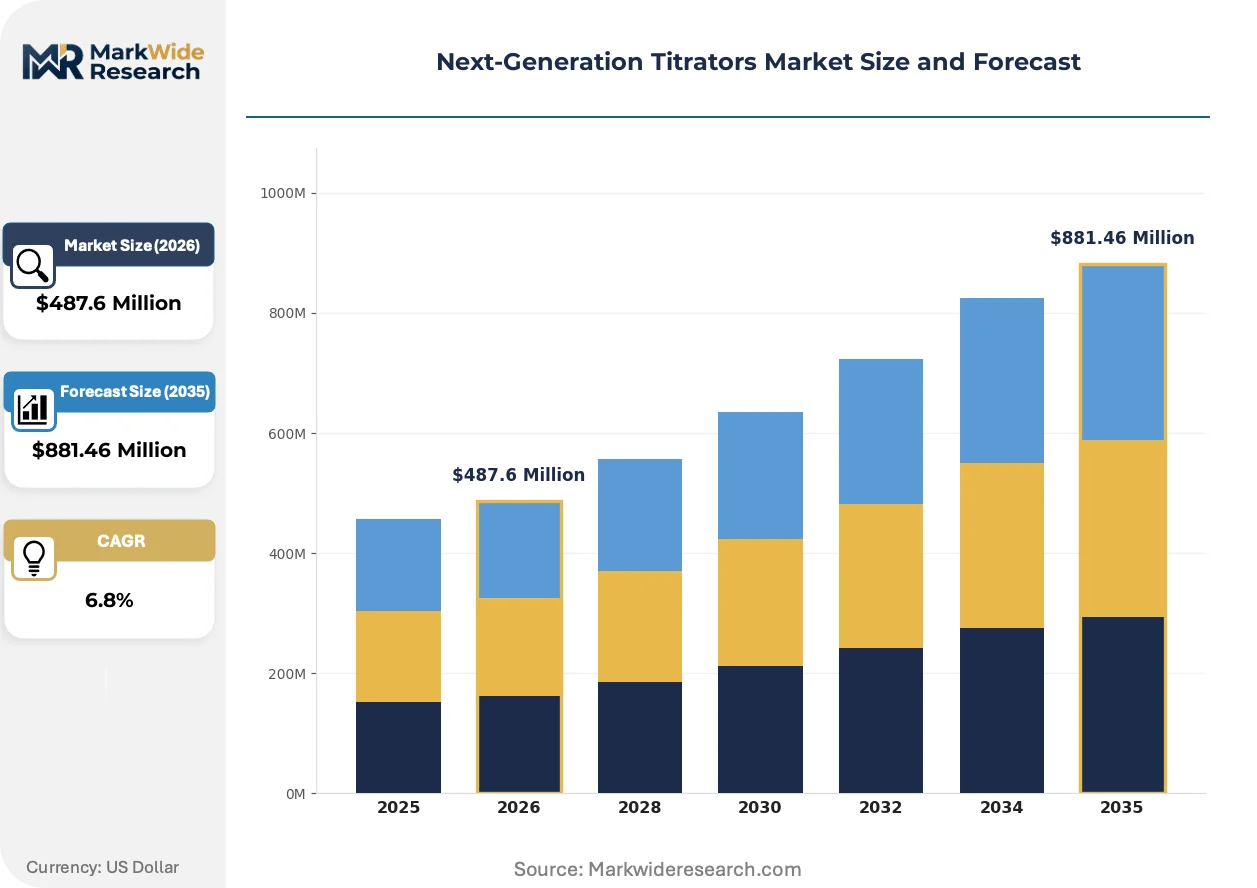
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Titrators, Automated Titrators, Compact Titrators, Multichannel Titrators End User: Pharmaceutical Labs, Academic Institutions, Chemical Manufacturers, Water Treatment Facilities Technology: Electrochemical, Visual Indicator, Potentiometric, Conductometric Application: Quality Control, Research & Development, Environmental Testing, Food & Beverage Analysis |
| Companies Covered | Hanna Instruments, DKK-TOA, Metrohm, Anton Paar, Thermo Fisher Scientific, Mettler Toledo, Xylem, Shimadzu, Hach, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next-Generation Titrators Market Shifts & Advancements
Digital connectivity architectures are displacing standalone instrument operation, embedding titration systems within broader laboratory automation ecosystems and redefining how analytical data flows into regulatory submissions.
Predictive maintenance algorithms are integrating electrochemical sensor drift monitoring with automated reagent consumption tracking, enabling pharmaceutical quality control labs to schedule interventions before out-of-specification events occur. Large molecule manufacturers in the United States and Germany are deploying these systems at scale. The technology is integrating instrument uptime guarantees into service contract pricing, compressing total cost of ownership calculations toward operational expenditure models.
EMA's Annex 11 revision and FDA's computer system validation guidance are tightening electronic signature and audit trail requirements for analytical equipment. Instrument vendors must now embed cryptographic data integrity controls at the firmware level. European pharmaceutical manufacturers are responding by specifying titrators with native LIMS connectivity and automated backup architectures during procurement.
Service unbundling is separating hardware acquisition from calibration, maintenance, and reagent supply agreements, allowing water treatment utilities to optimize cash flow through operational leasing structures. Municipal laboratories in Germany and industrial facilities in the United States are piloting per-sample pricing models. This shift is most visible among high-throughput environmental testing networks where instrument utilization rates justify outcome-based contracting over capital purchase.
Next-Generation Titrators Market Segmentation
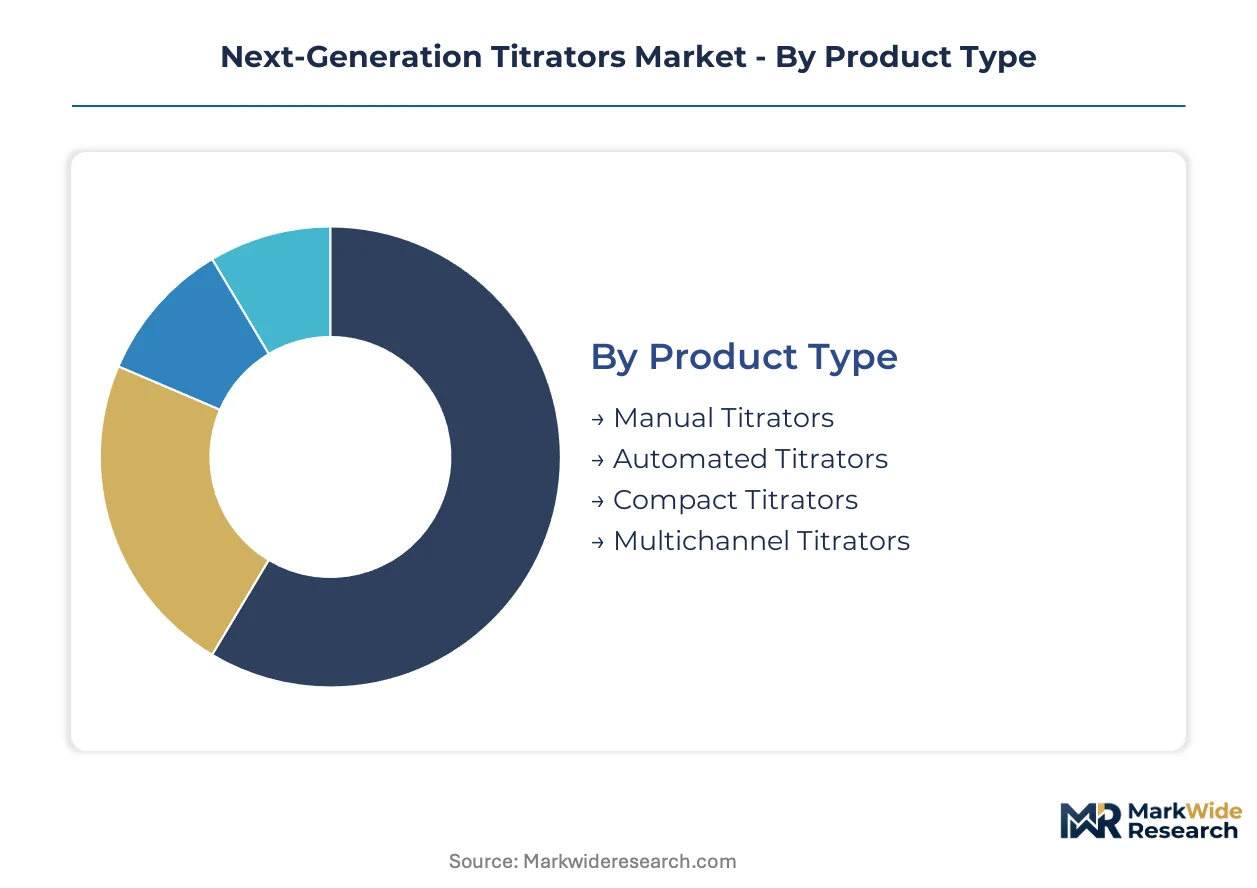
Next-generation titrators fragment across four distinct dimensions that reshape procurement priorities and vendor positioning. Product type determines capital intensity and service attach rates. End-user concentration in regulated industries forces compliance-native architectures. Technology choice locks laboratories into specific reagent and electrode supply chains. Application context dictates throughput requirements and validation burden.
Product Type:
Supply concentration among precision fluidics manufacturers in Switzerland and Germany shapes tier availability and lead times for automated platforms.
- Automated Titrators:These systems integrate precision syringe drives, automated sample changers, and software-controlled endpoint detection to eliminate operator variability. Pharmaceutical labs in the United States and Germany concentrate replacement demand here as FDA cGMP and EMA Annex 11 mandates force retirement of manual methods. The installed base commands the largest margin pool through multi-year service contracts.
- Multichannel Titrators:Parallel analytical channels enable simultaneous determination of multiple parameters from single sample aliquots. Chemical manufacturers and water utilities upgrade legacy installations to these platforms, consolidating bench space and reducing per-sample labor costs. This configuration climbs the fastest as high-throughput labs seek workflow consolidation.
- Manual Titrators:Basic burette-and-flask assemblies persist in educational settings and developing-market industrial labs with limited capital budgets. Demand concentrates in academic institutions and small-scale food producers where regulatory pressure remains minimal.
- Compact Titrators:Reduced-footprint units with stripped automation features serve mobile testing applications and satellite quality control stations. Water treatment field teams and regional pharmaceutical manufacturing sites deploy these for rapid deployment scenarios.
Today's leader: Automated Titrators. Tomorrow's challenger: Multichannel Titrators.
End User:
Cost tier stratification separates capital-rich regulated industries from budget-constrained educational and municipal buyers.
- Pharmaceutical Labs:These facilities operate under FDA 21 CFR Part 11 and EMA Annex 11 compliance frameworks that mandate electronic records, audit trails, and validated analytical procedures. Replacement cycles accelerate as legacy systems fail software revision requirements. The segment generates strongest pricing power for vendors offering documented IQ/OQ/PQ protocols.
- Water Treatment Facilities:Municipal utilities and industrial discharge operators face tightening EPA Clean Water Act and EU Water Framework Directive monitoring obligations. Alkalinity, hardness, and chloride automation drive procurement windows across Germany and the United States. This end-use category expands most quickly as regulatory enforcement intensifies.
- Chemical Manufacturers:Process control laboratories require robust Karl Fischer moisture determination and acid-base titration for raw material verification. Demand clusters in German chemical clusters and US Gulf Coast petrochemical complexes.
- Academic Institutions:Teaching laboratories and basic research facilities prioritize capital cost minimization over compliance features. Procurement concentrates in undergraduate chemistry programs and developing-market research institutes.
Pharmaceutical Labs anchor current revenue. Water Treatment Facilities are gaining share fastest.
Technology:
Volume concentration in potentiometric methods reflects decades of standardization in pharmacopeial and environmental test protocols.
- Potentiometric:Ion-selective electrode potential measurement against reference electrodes dominates pH, ion selective, and redox titrations. Pharmaceutical quality control and water analysis standard methods embed this technology. Electrode supply dependencies on Swiss and German manufacturers create procurement risk.
- Electrochemical:Broad category encompassing amperometric, coulometric, and voltammetric detection methods. Karl Fischer moisture determination relies on coulometric variants in pharmaceutical stability testing labs. This technology shows steepest expansion trajectory as sensor miniaturization advances.
- Conductometric:Solution conductivity change detection serves specialized applications including surfactant titrations and water purity verification. Demand concentrates in industrial process control and detergent manufacturing quality labs.
- Visual Indicator:Colorimetric endpoint detection persists in educational settings and legacy standard methods requiring minimal equipment investment. Academic laboratories and developing-market food producers maintain this lowest-cost tier.
Potentiometric methods dominate installed base. Electrochemical platforms are climbing fastest.
Application:
Customer type maturity separates validated, regulated workflows from exploratory research environments with flexible method requirements.
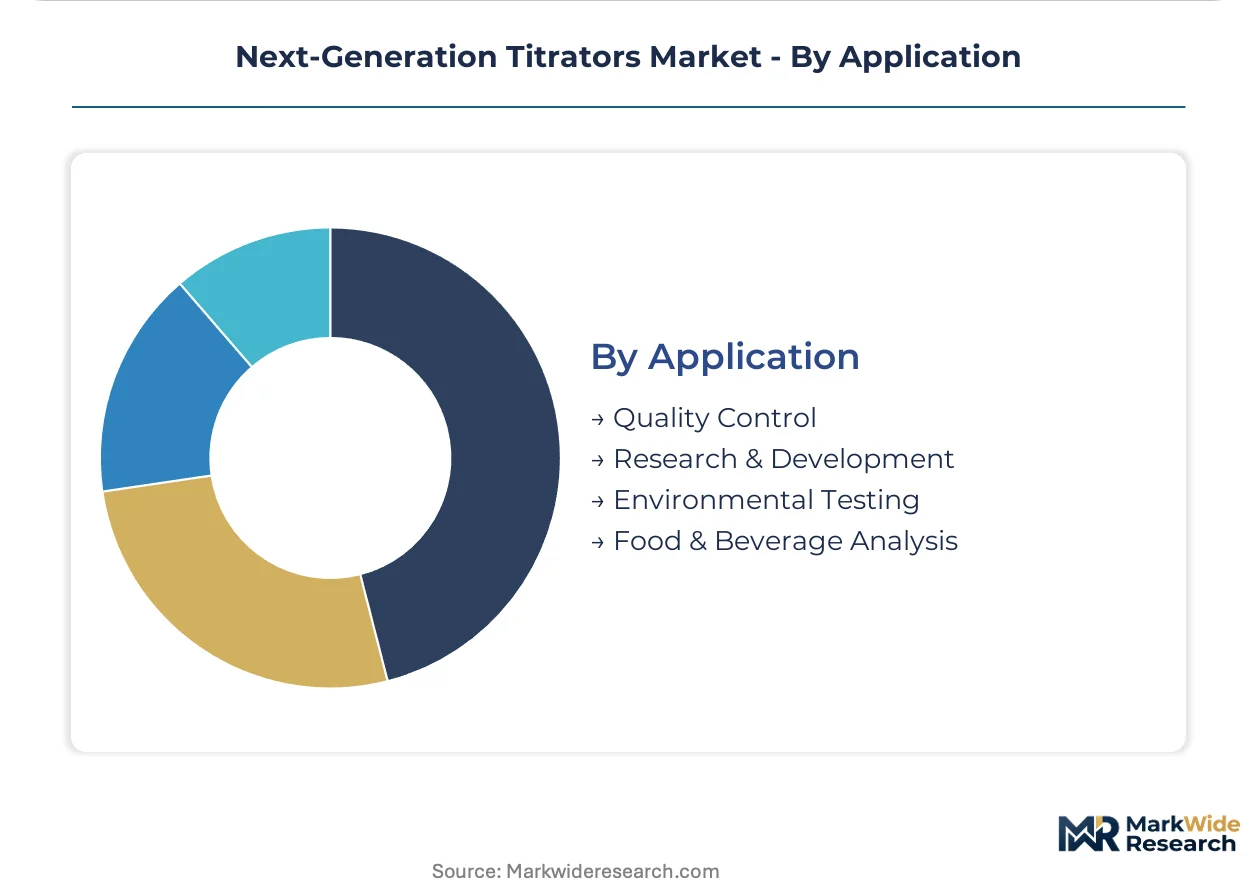
- Quality Control:Repetitive batch release testing in pharmaceutical, food, and chemical manufacturing demands maximum automation, electronic records, and regulatory compliance documentation. FDA cGMP and ISO 17025 accreditation requirements filter procurement toward validated suppliers with service infrastructure.
- Environmental Testing:EPA and EU-mandated discharge monitoring, soil analysis, and drinking water compliance drive demand for multichannel alkalinity and hardness automation. Commercial laboratories and municipal utilities concentrate procurement in Germany and the United States.
- Research & Development:Method development and exploratory analysis prioritize flexibility over validation, with academic and corporate research labs accepting manual and semi-automated platforms. Funding cycles and grant constraints shape purchasing patterns.
- Food & Beverage Analysis:Moisture, acidity, and preservative determination for product safety and labeling compliance. FSSAI in India and FDA food safety requirements tighten precision demands, though cost sensitivity remains higher than pharmaceutical equivalents.
Quality Control commands premium positioning. Environmental Testing shows strongest momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates replacement demand for multichannel potentiometric systems, while the United States drives cloud-connected compliance architectures through FDA mandates. Japan and India expand at divergent velocities shaped by domestic regulatory maturation and import substitution policies.
United States
Pharmaceutical quality control labs in New Jersey and Massachusetts accelerate replacement cycles as FDA 21 CFR Part 11 enforcement tightens electronic record requirements. EPA Clean Water Act method updates create procurement windows for municipal utilities across the Great Lakes region. Thermo Fisher Scientific anchors cloud-connected platform deployment through enterprise LIMS integration capabilities.
Germany
Chemical manufacturers in Ludwigshafen and Leverkusen upgrade legacy installations to multichannel platforms capable of simultaneous parameter monitoring. EMA Annex 11 revisions tighten audit trail specifications for pharmaceutical exporters. Metrohm leverages its Swiss-German service infrastructure to lock in multi-year calibration and maintenance agreements across the Rhine-Ruhr industrial cluster.
Japan
PMDA pharmaceutical manufacturing guidelines drive adoption of automated Karl Fischer systems in Osaka and Tokyo pharmaceutical corridors. Domestic instrument vendors face pressure from European competitors offering native Japanese language compliance software. Shimadzu anchors electrochemical sensor supply relationships with university research institutes and generic drug manufacturers.
India
CDSCO-regulated contract research organizations in Hyderabad and Bangalore represent underpenetrated demand for automated moisture determination systems. FSSAI food safety enforcement tightens precision requirements for domestic and export-oriented processors. Import substitution policies favor localized service networks over direct European equipment procurement.
Switzerland
Precision electrode manufacturing clusters in Herisau and Schaffhausen create supply dependencies for ion-selective sensing components globally. Swissmedic pharmaceutical device regulations filter procurement toward vendors offering documented uncertainty budgets. Metrohm and Metrohm Autolab anchor high-value service contracts through predictive maintenance algorithms and cryptographic data integrity controls.
Next-Generation Titrators Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with precision fluidics integration favoring integrated instrument vendors over component suppliers. The vendor base stratifies across three tiers: multinationals with native LIMS architectures, regional specialists with localized service density, and emerging Asian fabricators competing on capital cost minimization. Dominant competitive moves include predictive maintenance algorithm development and per-sample pricing model piloting among water treatment networks.
Among Swiss and German precision instrument specialists, Metrohm and Anton Paar exemplify the service-integrated archetype, anchoring multi-year agreements through calibration infrastructure and reagent supply continuity. Thermo Fisher Scientific occupies a position at the cloud-connected platform tier, representing the enterprise software convergence strategy. Hanna Instruments sits within the rapid-response service network archetype, with localized part availability supporting water treatment utility procurement cycles.
| Leading Market Players |
|---|
| Hanna Instruments |
| DKK-TOA |
| Metrohm |
| Anton Paar |
| Thermo Fisher Scientific |
| Mettler Toledo |
| Xylem |
| Shimadzu |
| Hach |
| Others |
Supply & Pricing Matrix
Precision fluidics engineers concentrated in Switzerland and Germany command wage premiums that widen spreads between premium automated titrators and economy manual units. Labor-cost differentials between Swiss manufacturing clusters and Asian assembly operations translate into three-tier pricing structures across premium, standard, and economy levels.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for entry-level potentiometric systems. Pricing stratifies across premium, standard, and economy tiers based on software integration depth and ISO 17025 certification documentation. Cost compression in the manual segment is intensifying because Indian contract manufacturers are scaling electrochemical sensor assembly. Water treatment utilities exhibit highest price sensitivity, while pharmaceutical labs under FDA cGMP mandates absorb premium tiers without volume negotiation.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme and China's import substitution policies are reshaping sourcing patterns for ion-selective electrode components. Precision glass membrane manufacturing rests on Swiss and German production clusters, while electronic subassemblies feed from South Korean and Taiwanese semiconductor fabricators. Single-source vulnerability concentrates in specialized reference electrode junction materials. Distribution runs through authorized service networks rather than open-channel commerce, locking buyers into vendor-direct relationships for calibration reagents and replacement sensors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Next-generation titrators offer margin-expansion pathways as predictive maintenance algorithms convert capital sales into recurring service revenue streams. Software-defined calibration architectures reduce field service costs while locking laboratories into multi-year agreements.
For Market Incumbents: Extend predictive maintenance algorithm development to compress competitor entry windows. Deepen backward integration into precision syringe drive manufacturing to offset Swiss fluidics cost premiums. Defend against emerging Asian fabricators by embedding cryptographic data integrity controls at firmware level, responding to FDA 21 CFR Part 11 and EMA Annex 11 revision timelines.
For New Entrants and Emerging Players: Enter via CDSCO-regulated contract research organizations in Hyderabad and Bangalore, where automated Karl Fischer moisture determination systems remain underpenetrated. Target municipal water utilities in the United States Great Lakes region facing EPA Clean Water Act method update procurement windows. Lead with per-sample pricing models rather than capital purchase positioning to bypass incumbent service infrastructure advantages.
For Investors and Strategic Acquirers: Enterprise laboratory software vendors are the most active acquirer in this space, seeking native titration data architectures for LIMS integration. Five-to-ten year viability favors vendors with cloud-connected platforms and validated IQ/OQ/PQ protocol libraries. Watch for EPA method revision announcements as inflection indicators triggering utility replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Algorithm Development | Pharmaceutical labs in New Jersey and Massachusetts convert hardware sales into recurring service contracts. |
| Cloud-Connected Platform Integration | Thermo Fisher Scientific feeds titration data directly into enterprise LIMS architectures for FDA compliance. |
| Per-Sample Pricing Model Piloting | German municipal utilities optimize cash flow through operational leasing structures for multichannel systems. |
| Backward Integration into Precision Fluidics | Metrohm anchors syringe drive manufacturing to secure supply continuity for automated titrator production. |
| Localized Service Network Expansion | Hanna Instruments builds rapid replacement part availability to capture water treatment utility procurement cycles. |
Research Methodology
Coverage spans the United States, Germany, India, Japan, and Switzerland, with primary inputs from each. The study combines structured interviews with laboratory directors, regulatory affairs specialists at pharmaceutical manufacturers, procurement managers at water utilities, and aftermarket service heads at instrument vendors. Secondary validation draws from FDA 21 CFR Part 11 guidance documents, EMA Annex 11 revisions, EPA Clean Water Act method updates, and ISO 17025 accreditation standards. Bottom-up demand modeling triangulates against top-down market sizing across product type, end user, technology, and application dimensions.
Granularity extends to individual country-regulatory cluster intersections, with separate modeling for FDA-regulated United States pharmaceutical labs, EMA-governed German chemical manufacturers, CDSCO-scrutinized Indian contract research organizations, PMDA-aligned Japanese generic drug producers, and Swissmedic-certified precision instrument hubs. CAGRs derive from segment-level volume trajectories weighted by pricing tier mix. Forecast inputs include laboratory automation capex cycles, regulatory enforcement intensity indices, and electrode replacement rate assumptions.
The model holds under stable regulatory enforcement timelines; deviation in EPA method revision schedules or EMA Annex 11 implementation deadlines would shift replacement demand curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Leather Testing Machine Market
Testing Equipment
Combustion Testing Equipment Market
Testing Equipment
PFAS Ultra-Trace Water Analysis Test Instruments Market
Testing Equipment
Solar Testing Equipment Market
Testing Equipment
Dynamic Vapor Sorption Analyzer Market
Testing Equipment
Water Test Kits Market
Testing Equipment
Gas Calorimeter Market
Testing Equipment
Global Chromatography Columns Market
Testing Equipment
Global Liquid Chromatography Systems Market
Testing Equipment
Flash Point Apparatus Market
Testing Equipment
Abrasion Tester Market
Testing Equipment
Global Chromatography Instrumentation Market
Testing Equipment
United States Material Testing Market
Testing Equipment
Total Hydrocarbon Analyzers Market
Testing Equipment
Hydrogen Gas Analyzers Market
Testing Equipment
Gold Tester Market