
 Non-Stick Coatings Market | 2026-2036
Non-Stick Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Stick Coatings Market Outlook
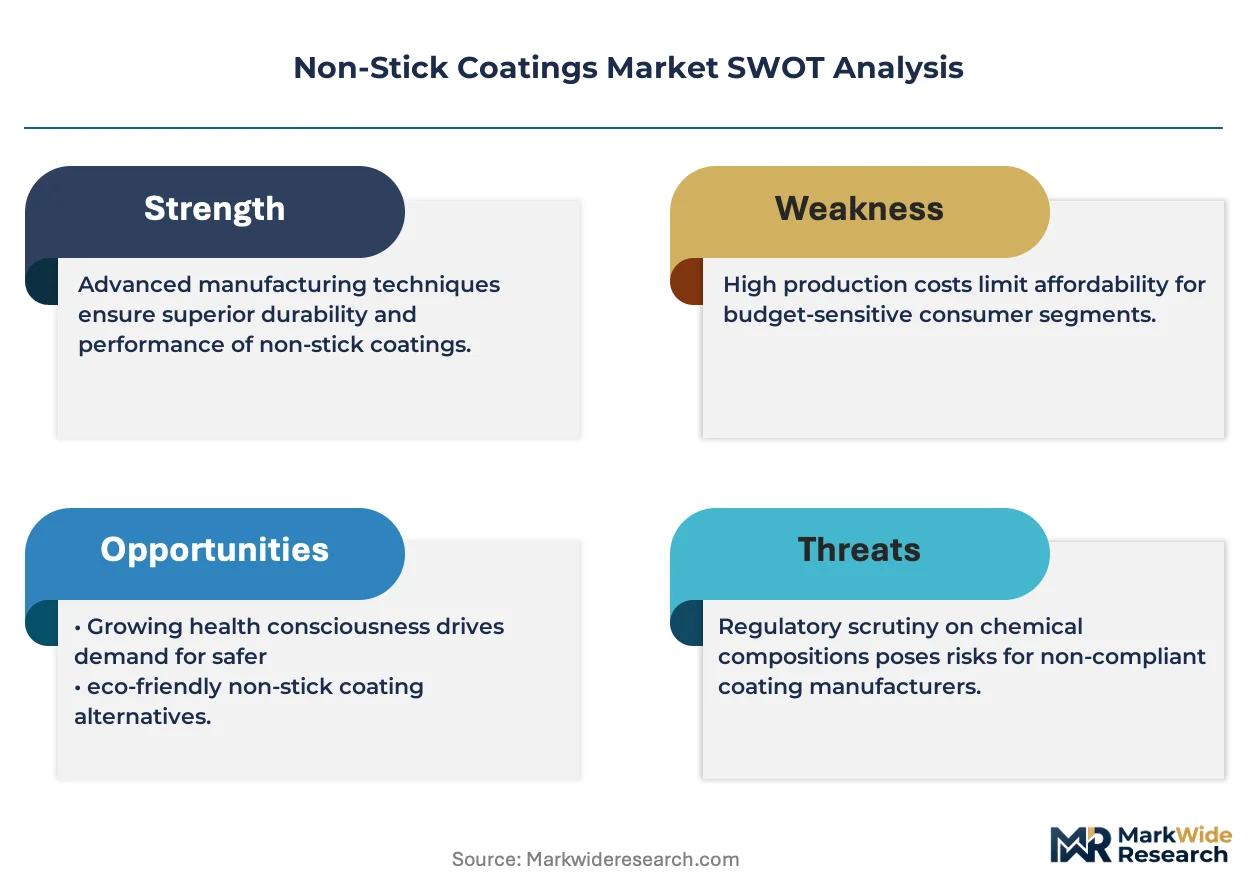
Modular coating kits that separate base-layer primers from topcoat finishes is shifting buyer choice toward configurable performance tiers. The Chemours Company leverages its fluoropolymer heritage to sustain supply relationships with premium cookware brands. PPG Industries anchors its position through industrial-scale spray coating systems for food processing lines. Whitford Corporation specializes in PFOA-free formulations that compete on regulatory compliance credentials.
Non-stick coatings are thin-film surface treatments, typically 25–75 microns thick, engineered from fluoropolymer resins or ceramic matrices to minimize surface energy and prevent adhesion. Their primary commercial purpose spans consumer cookware durability, industrial bakeware release efficiency, and food processing equipment hygiene. PTFE formulations still dominate installed base value, while ceramic segments capture fastest growth as temperature tolerance requirements climb above 450°C in commercial kitchens. Spray coating technology leads application-method revenue due to precision control over film thickness, whereas dip coating occupies cost-sensitive mass production of standardized bakeware shapes.
FDA food-contact substance notifications and EPA toxicity evaluations under the Toxic Substances Control Act constrain traditional fluoropolymer pathways in the United States, while REACH Annex XVII restrictions on PFOA-related substances enforce reformulation across European supply chains. ECHA substance evaluations further tighten per- and polyfluoroalkyl substance thresholds, redirecting R&D investment toward silicone and sol-gel ceramic platforms. Stakeholders must monitor evolving state-level prohibitions in California and New York that outpace federal timelines, as these jurisdictions effectively set de facto national product standards for coatings sold through national retail channels.
Market Dynamics
Reformulation pressure from PFOA phase-outs is compressing product development cycles and forcing coating suppliers to rebuild formulation libraries around ceramic and silicone chemistries. This structural shift is redrawing competitive positions based on regulatory compliance speed rather than traditional fluoropolymer scale.
Growth Catalysts
- REACH Annex XVII restrictions:European PFOA-related substance limits are accelerating R&D investment into sol-gel ceramic platforms and expanding addressable markets for compliant suppliers.
- Commercial kitchen temperature requirements:Professional bakeware and food processing equipment operating above 450°C is pulling demand toward ceramic matrix formulations with superior thermal tolerance.
- China cookware export manufacturing:Concentrated production in Zhejiang and Guangdong provinces is driving volume procurement of spray coating systems for standardized appliance components.
Market Restraints
- Fluoropolymer raw material concentration:Supply of PTFE resins concentrates among a limited set of chemical producers, creating input cost volatility and qualification delays for alternative formulations.
- Reformulation capex intensity:Transitioning from traditional fluoropolymer to ceramic or silicone platforms requires dedicated spray coating line reconfiguration and curing oven upgrades.
- Performance trade-offs in ceramic coatings:Current sol-gel formulations exhibit reduced abrasion resistance compared to mature PTFE systems, limiting penetration in high-wear industrial bakeware applications.
Strategic Opportunities
- Modular coating kit architecture:Separating base-layer primers from topcoat finishes enables configurable performance tiers and opens premium positioning for suppliers with primer chemistry expertise.
- California and New York state prohibitions:Jurisdictions outpacing federal EPA timelines are creating early-mover advantages for PFOA-free formulations in national retail distribution.
- Food processing equipment hygiene mandates:USDA and FDA inspection protocols are expanding specification of non-stick surfaces in meat, dairy, and ready-to-eat production lines.
Industry Challenges
- Formulation chemist talent scarcity:Deep expertise in sol-gel ceramic synthesis and silicone crosslinking chemistry remains concentrated among a limited pool of specialists with fluoropolymer backgrounds.
- Dual certification timelines:Simultaneous FDA food-contact substance notification and EPA toxicity evaluation under TSCA extends product launch windows by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Stick Coatings Market |
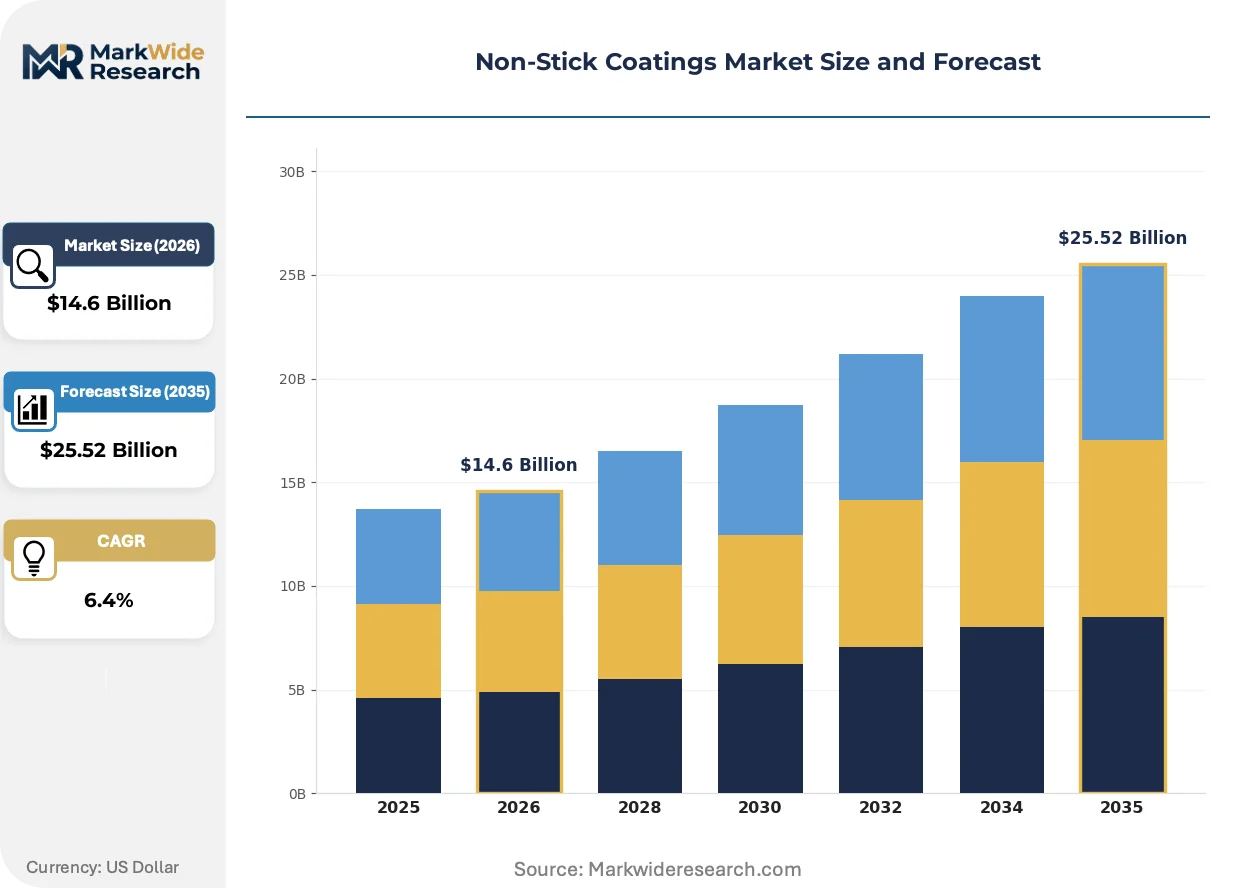
| Market Size in 2026 | $14.6 Billion |
| Market Size in 2035 | $25.52 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PTFE, Ceramic, Silicone, PFOA-Free Application: Cookware, Bakeware, Industrial Equipment, Food Processing End User: Households, Restaurants, Food Manufacturers, Industrial Entities Technology: Spray Coating, Dip Coating, Roll Coating, Liquid Coating |
| Companies Covered | The Chemours Company, PPG Industries, Inc., DAIKIN INDUSTRIES, Ltd., 3M, Solvay, Akzo Nobel N.V., Whitford Corporation, Showa Denko K.K., BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Stick Coatings Market Strategic Shifts
Coating application technology is converging with quality control systems to enable real-time thickness monitoring and predictive maintenance. This integration is compressing defect rates and reshaping supplier-customer relationships around performance guarantees rather than material supply.
Plasma-enhanced chemical vapor deposition is automating the application of ultra-thin ceramic films onto complex geometries. Commercial kitchen equipment manufacturers in Germany and Japan are adopting this technology for fryer baskets and baking molds. The process is automating what previously required manual spray booth labor and enabling consistent 15-25 micron coatings on edges and corners.
ECHA substance evaluations under REACH are tightening per- and polyfluoroalkyl substance thresholds across European supply chains. Industrial coating applicators in Italy and France are requalifying their entire formulation portfolios ahead of enforcement deadlines. Food processing equipment OEMs are responding by dual-sourcing ceramic and silicone alternatives to de-risk specification dependencies.
Buyer specification practices are consolidating around certified compliance documentation rather than brand reputation. Large cookware retailers in the United States are requiring third-party testing certificates for PFOA-free claims before contract renewal. This behavioral shift is most visible in private-label procurement, where compliance credentials now determine supplier selection ahead of historical price-performance metrics.
Non-Stick Coatings Market Segmentation
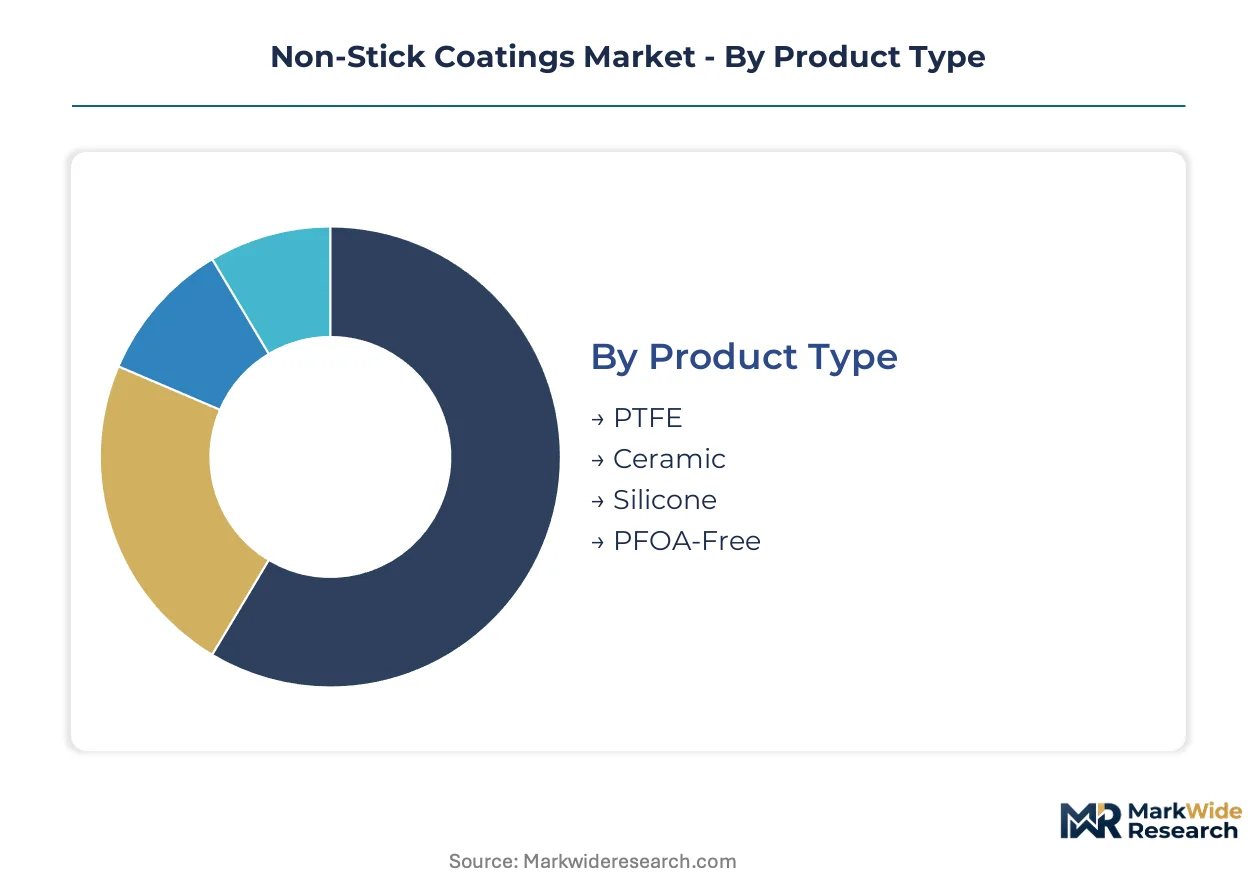
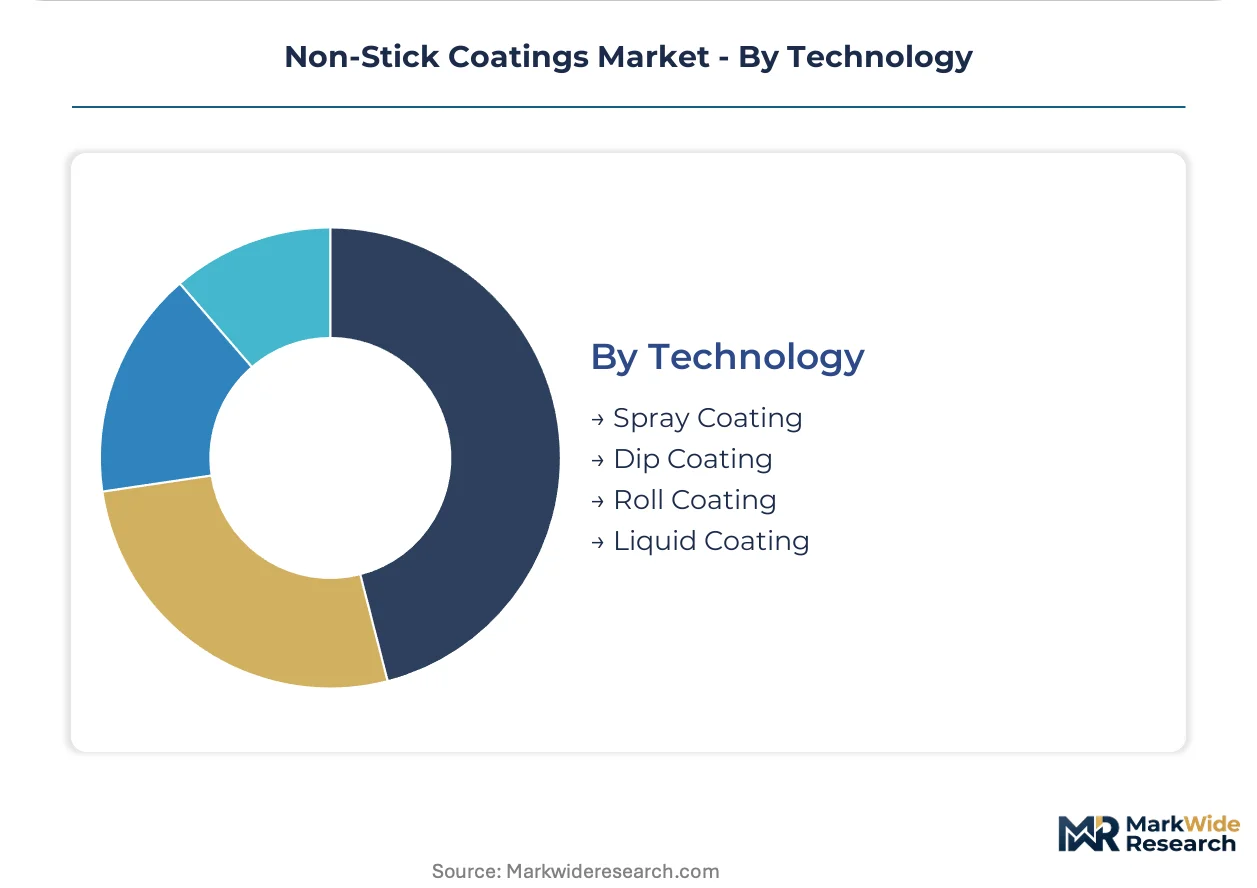
Segmentation in non-stick coatings reveals how formulation chemistry, application method, and end-use thermal requirements create distinct procurement patterns. Buyers select coating architectures based on regulatory compliance deadlines, operating temperatures, and equipment geometries rather than surface performance alone.
Product Type:
Formulation chemistry determines thermal ceiling, abrasion resistance, and regulatory pathway complexity across coating specifications.
- PTFE:Fluoropolymer resin systems deliver the lowest surface energy and longest track record in consumer cookware. Food manufacturers in China and the United States specify PTFE for standardized appliance components where FDA food-contact substance notifications already exist.
- Ceramic:Sol-gel matrices withstand temperatures exceeding 450°C in commercial kitchen environments. Professional bakeware manufacturers in Germany and Japan specify ceramic for fryer baskets and baking molds where thermal tolerance outweighs abrasion concerns.
- Silicone:Crosslinked polysiloxane formulations bridge temperature performance between PTFE and ceramic platforms. Industrial food processing lines specify silicone where moderate heat resistance combines with flexibility requirements.
- PFOA-Free:Reformulated fluoropolymer and hybrid chemistries eliminate perfluorooctanoic acid content to meet REACH Annex XVII and state-level prohibitions. Retail procurement in California and New York now requires PFOA-free certification as a contract condition.
PTFE leads on scale; ceramic leads on momentum.
Application:
Equipment geometry and production batch size dictate coating selection across consumer and industrial use cases.
- Cookware:Skillets, saucepans, and specialty vessels require uniform 25-50 micron films for household durability. Zhejiang and Guangdong province manufacturers drive volume procurement of spray coating systems for standardized pot and pan geometries.
- Bakeware:Muffin tins, cake pans, and sheet trays demand release efficiency above 200°C baking temperatures. Commercial bakeries specify ceramic formulations where repeated thermal cycling degrades traditional fluoropolymer films.
- Industrial Equipment:Mixing vessels, conveyor components, and processing surfaces require chemical resistance beyond consumer applications. Meat and dairy processors specify non-stick surfaces under USDA inspection protocols.
- Food Processing:High-volume production lines for ready-to-eat meals integrate coating specifications into hygiene mandates. FDA inspection protocols now expand non-stick surface requirements across slaughter, processing, and packaging stages.
Cookware dominates procurement volume; food processing commands specification premiums.
End User:
Procurement authority and performance validation requirements diverge sharply between household purchasers and industrial specifiers.
- Households:Individual consumers select coatings through retail channels based on brand claims and price positioning. Third-party PFOA-free certification is displacing brand reputation as the primary selection criterion in United States private-label procurement.
- Restaurants:Commercial kitchen operators prioritize thermal tolerance and rapid cleaning turnaround over initial cost. Professional bakeware in high-heat applications specifies ceramic to minimize replacement frequency.
- Food Manufacturers:Industrial scale production requires documented compliance with FDA food-contact substance notifications and EPA toxicity evaluations. Dual certification timelines extend supplier qualification to 18-24 months.
- Industrial Entities:Heavy manufacturing and chemical processing specify coatings for corrosion resistance beyond food-contact applications. These buyers source through industrial distributors rather than retail channels.
Food manufacturers concentrate procurement value; restaurants drive fastest adoption of ceramic alternatives.
Technology:
Application method controls film thickness precision, capital equipment requirements, and labor content per unit.
- Spray Coating:Automated spray booths deliver precision thickness control for complex geometries. This method leads revenue in application technology due to adaptability across cookware shapes and industrial component sizes.
- Dip Coating:Immersion processes coat entire surfaces uniformly for standardized bakeware shapes. Mass production of muffin tins and cake pans in China relies on dip coating for cost-sensitive volume output.
- Roll Coating:Continuous roller systems apply thin films to flat or cylindrical substrates. Industrial food processing equipment manufacturers specify roll coating for conveyor belts and drum surfaces.
- Liquid Coating:Brush or flow applications enable field repair and custom equipment retrofit. Maintenance departments in aging food processing plants specify liquid coating to extend equipment service life.
Spray coating commands technology investment; dip coating retains volume leadership in standardized shapes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
DuPont pioneered fluoropolymer coatings at its New Jersey facilities in the 1930s, establishing the technical foundation that spread to industrial clusters across three continents. Today, formulation expertise and regulatory compliance speed determine competitive position in distinct national markets.
United States
FDA food-contact substance notifications and EPA toxicity evaluations under TSCA constrain traditional fluoropolymer pathways while accelerating ceramic and silicone alternatives. California and New York state prohibitions on PFOA-related substances outpace federal timelines, effectively setting de facto national standards for coatings distributed through national retail channels. Cookware manufacturers in the Southeast and industrial bakeware producers in the Midwest drive procurement volume.
China
Zhejiang and Guangdong provinces concentrate cookware export manufacturing and domestic appliance production, driving volume procurement of spray coating systems. The country's national chemical regulator enforces GB standards for food-contact materials while provincial environmental authorities tighten emissions controls on coating application facilities. Appliance OEMs in the Yangtze River Delta specify ceramic formulations for premium product lines targeting European export markets.
Germany
Commercial kitchen equipment manufacturers specify ceramic matrix coatings for fryer baskets and baking molds operating above 450°C. ECHA substance evaluations under REACH tighten per- and polyfluoroalkyl substance thresholds, forcing industrial coating applicators to requalify entire formulation portfolios. Precision engineering clusters in Bavaria and Baden-Württemberg integrate plasma-enhanced chemical vapor deposition for ultra-thin ceramic films on complex geometries.
Japan
METI industrial standards and PMDA food-contact regulations shape coating specifications for domestic appliance and food processing equipment markets. Commercial kitchen equipment manufacturers adopt plasma-enhanced deposition technology for consistent 15-25 micron coatings on edges and corners. Industrial coating specialists in the Chubu region around Nagoya serve automotive and food equipment OEMs with hybrid ceramic-fluoropolymer formulations.
Italy
Industrial coating applicators in Northern Italy requalify formulation portfolios ahead of REACH Annex XVII enforcement deadlines on PFOA-related substances. Food processing equipment OEMs in Emilia-Romagna dual-source ceramic and silicone alternatives to de-risk specification dependencies. Artisan cookware manufacturers in Lombardy and Piedmont specify PFOA-free formulations for export markets in France and Germany.
Non-Stick Coatings Market Competitive Environment
Premium-margin players sit above commodity-margin players across regulatory compliance speed and formulation heritage. The market structure divides between fluoropolymer heritage suppliers rebuilding libraries around ceramic platforms and specialists native to sol-gel and silicone chemistries. Three archetypes dominate: diversified chemical conglomerates with coating divisions, pure-play coating formulators, and industrial equipment-integrated applicators. Competitive moves concentrate on strategic partnerships for dual-certification acceleration and geographic expansion into Chinese manufacturing clusters.
Among diversified chemical conglomerates, The Chemours Company and DAIKIN INDUSTRIES, Ltd. occupy positions reflecting fluoropolymer heritage and reformulation investment. PPG Industries anchors the industrial-scale application systems tier. Whitford Corporation exemplifies the pure-play specialist archetype competing on PFOA-free compliance credentials.
| Leading Market Players |
|---|
| The Chemours Company |
| PPG Industries, Inc. |
| DAIKIN INDUSTRIES, Ltd. |
| 3M |
| Solvay |
| Akzo Nobel N.V. |
| Whitford Corporation |
| Showa Denko K.K. |
| BASF |
| Others |
Value Chain & Pricing Dynamics
Plasma-enhanced chemical vapor deposition adoption in Germany and Japan is compressing coating thickness tolerances while concentrating equipment supply among specialized system integrators. This manufacturing-method transition simultaneously elevates capital requirements for new entrants and shifts procurement power toward buyers with volume scale to amortize installation costs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates PFOA-free certified formulations from legacy PTFE and commodity ceramic grades. Price differentiation rests on REACH Annex XVII compliance credentials and thermal tolerance certification above 450°C. Cost compression in economy-tier dip coating is intensifying because Chinese mass producers are consolidating procurement volumes. Food manufacturers exhibit lowest price sensitivity due to dual certification timelines, while household retail channels face acute margin pressure from private-label competition.
Supply Chain Analysis
Refurbishment flows for industrial bakeware and food processing equipment are creating secondary coating service markets that extend asset lifecycles and fragment original supplier relationships. Raw material supply concentrates in China for ceramic sol-gel precursors, the United States for fluoropolymer resins, and Germany for silicone crosslinking agents. Formulation chemists with dual expertise in fluoropolymer heritage and ceramic synthesis remain scarce, creating single-source vulnerability for specialized R&D talent. Distribution runs through industrial applicator networks in Italy and France for European food equipment OEMs, direct procurement relationships in Zhejiang and Guangdong for Chinese cookware exports, and national retail channel consolidation in the United States for consumer markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Annex XVII PFOA-related substance restrictions function as a regulatory compounder, accelerating reformulation investment and redrawing competitive positions based on compliance speed rather than historical scale.
For Market Incumbents: Anchor market position through captive supply of sol-gel ceramic precursors and accelerated FDA food-contact substance notification pipelines. Defensive consolidation around spray coating line reconfiguration capabilities protects against emerging pure-play ceramic specialists. Certification investment in California and New York state prohibitions ahead of federal timelines secures national retail channel access. For New Entrants and Emerging Players: REACH Annex XVII in Europe opens a window for PFOA-free formulation specialists to capture share from fluoropolymer heritage suppliers during portfolio requalification. White-space targets include modular coating kit architectures separating base-layer primers from topcoat finishes, and plasma-enhanced deposition services for German commercial kitchen equipment manufacturers. Go-to-market positioning around third-party compliance documentation displaces brand reputation in United States private-label procurement. For Investors and Strategic Acquirers: Roll-up economics work for regional industrial coating applicators because ECHA substance evaluation timelines are forcing fragmented Italian and French operators to seek scale for dual-sourcing qualification costs. Long-term viability centers on ceramic platform expertise and regulatory compliance infrastructure rather than fluoropolymer legacy assets. Monitor FDA food-contact substance notification backlogs as inflection indicator for reformulation investment intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sol-Gel Precursors | Secures supply of ceramic matrix raw materials amid REACH-driven formulation shifts. |
| Dual-Certification Acceleration Partnership | Compresses FDA and EPA TSCA evaluation timelines through shared toxicology data. |
| Plasma-Enhanced Deposition Capacity Buildout | Captures German and Japanese commercial kitchen equipment specification premiums. |
| Modular Coating Kit Architecture Launch | Enables configurable performance tiers for premium cookware brand positioning. |
| California-New York Compliance Pre-Certification | Establishes early-mover advantage in United States national retail distribution. |
Study Parameters
Bottom-up food processing equipment modeling reconciled against top-down fluoropolymer resin supply tracking forms the analytical core. Primary interviews with coating formulator R&D directors, industrial bakeware procurement managers, food manufacturer quality assurance leads, and spray coating system integrators combined with secondary validation from ECHA substance evaluation databases, FDA food-contact substance notification filings, customs trade data for ceramic precursor imports, and SEC 10-K disclosures from diversified chemical conglomerates. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map formulation chemistry transitions, application technology adoption curves, and end-use thermal requirement thresholds across the projection horizon. Segmentation dimensions modeled include product type, application method, end-user procurement authority, and regional regulatory cluster. CAGRs derive from fitted growth curves calibrated to historical penetration rates of ceramic alternatives in commercial kitchen environments. Industry-specific forecast inputs incorporate ECHA enforcement timeline assumptions and plasma-enhanced deposition equipment installation rates.
Revisions become necessary when ECHA substance evaluation thresholds tighten beyond modeled assumptions or when California and New York state prohibitions accelerate federal regulatory convergence. Forecasts reflect documented assumptions about reformulation capex intensity and certification timeline durations. Practitioners should monitor FDA food-contact substance notification approval rates and REACH Annex XVII enforcement consistency for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global PET Film Coated Steel Coil Market
Coatings
High Performance Epoxy Coating Market
Coatings
France Protective Coatings Market
Coatings
Global Low Temperature Powder Coatings Market
Coatings
Corrosion Protection Coating Market
Coatings
Asia-Pacific Marine Coatings Market
Coatings
Solvent Borne Coatings Market
Coatings
Australia Industrial Coatings Market
Coatings
Global Fire-Resistant Coating Market
Coatings
Spain Automotive OEM Coatings Market
Coatings
Global Automotive Specialty Coatings Market
Coatings
Sustained Release Coatings Market
Coatings
Anti-Friction Coatings Market
Coatings
Morocco Automotive OEM Coatings Market
Coatings
Solar Reflective Film Market
Coatings
Glazes Market