
 Clear Coatings Market | 2026-2036
Clear Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Clear Coatings Market Outlook
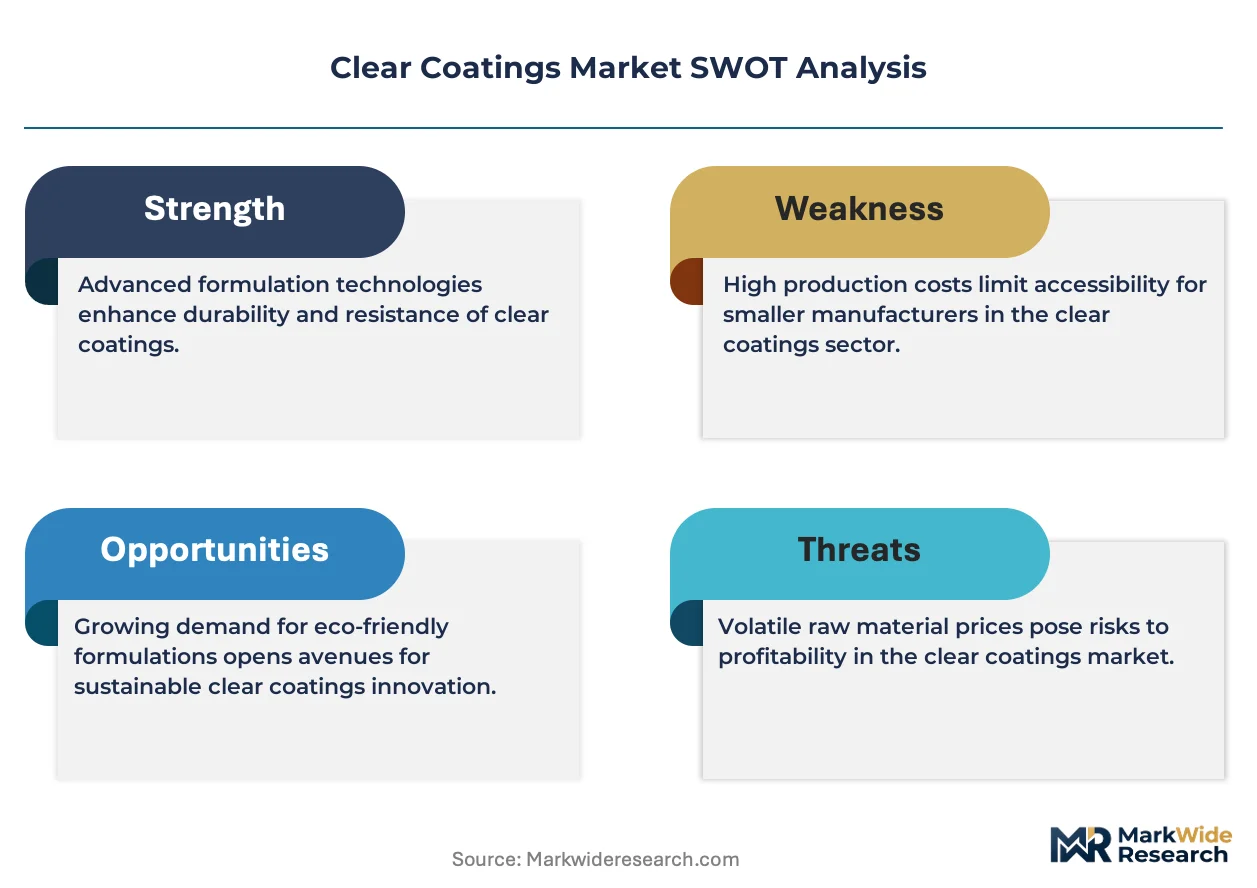
Capital-intensity divergence between integrated resin producers and formulation-only competitors is reorganizing competitive tiers in clear coatings. PPG Industries sustains upstream control over alkyd and acrylic resin supply, insulating margin pools from raw material volatility. Akzo Nobel N.V. differentiates through marine and protective specialization, while BASF SE leverages its Ludwigshafen chemical complex to dominate polyurethane clear coat precursors.
Clear coatings constitute transparent, non-pigmented film-forming systems typically comprising acrylic, polyurethane, epoxy, or nitrocellulose resins dissolved or dispersed in solvent or water carriers, designed to protect substrates while preserving visual aesthetics. These formulations cure through oxidation, evaporation, or cross-linking mechanisms to yield hardness ratings between 2H and 6H pencil scale, primarily serving protective and decorative functions across industrial and consumer applications. Acrylic systems lead architectural and DIY segments due to rapid dry times and UV stability, while polyurethane coatings command premium positioning in automotive and flooring applications where abrasion resistance determines lifecycle value. Epoxy clear coats occupy a mature niche in electronics conformal coating, with nitrocellulose formulations retreating to specialty furniture repair channels amid solvent-emission pressures.
EPA VOC regulations and REACH substance restrictions are forcing reformulation investments toward water-borne and UV-curable platforms, while China's MEE enforces GB standards on industrial coating emissions that reshape local manufacturing compliance costs. ISO 12944 corrosion protection standards and automotive OEM specifications further segment market access by performance tier. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded formulation assets and misaligned capacity investments.
Market Dynamics
Water-borne formulation mandates under EPA and REACH protocols are compressing solvent-borne capacity while forcing simultaneous investment in UV-curable pilot lines, creating a bifurcated capital allocation environment for coating manufacturers.
Growth Catalysts
- Automotive OEM specifications:Tier-1 suppliers in Germany and Japan now require 6H pencil hardness ratings for exterior trim applications, pulling polyurethane clear coat volumes into premium vehicle programs.
- China's dual carbon goals:MEE enforcement of GB standards on industrial coating emissions is accelerating water-borne line conversions in Guangdong and Jiangsu furniture export clusters.
- UV-curable technology maturation:Instant cure cycles at 25°C are decomposing thermal drying bottlenecks in flatline wood coating operations across North American cabinetry producers.
Market Restraints
- Isocyanate feedstock volatility:Aliphatic diisocyanate supply concentrates among three Ludwigshafen-based producers, exposing polyurethane clear coat margins to input cost spikes.
- REACH substance restrictions:ECHA candidate list expansion for reprotoxic monomers is forcing reformulation of high-performance automotive refinish lines before alternatives achieve equivalent gloss retention.
- Epoxy substitution ceiling:Electronics conformal coating demand is plateauing as parylene vapor deposition captures miniaturized PCB protection applications below 50-micron thickness requirements.
Strategic Opportunities
- India PLI scheme for furniture:Duty concessions on coating line imports are opening captive clear coat demand among Moradabad and Jodhpur metal-furniture exporters targeting EU retail chains.
- Marine superyacht refit:IMO antifouling restrictions are redirecting maintenance spend toward high-gloss clear coat systems for hull aesthetic renewal in Mediterranean and Caribbean service yards.
- AI-driven color matching:Spectrophotometer-integrated dispensing is compressing custom-mix lead times from 48 hours to 90 minutes in automotive collision repair channels.
Industry Challenges
- Formulation chemist scarcity:Water-borne resin synthesis expertise pools concentrate among retirees from 1990s alkyd-to-acrylic transition programs, constraining R&D velocity for mid-tier producers.
- ISO 12944 certification timelines:Corrosion protection laboratory testing cycles extend 18-24 months for C5-M marine ratings, delaying market entry for new polyurethane entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clear Coatings Market |
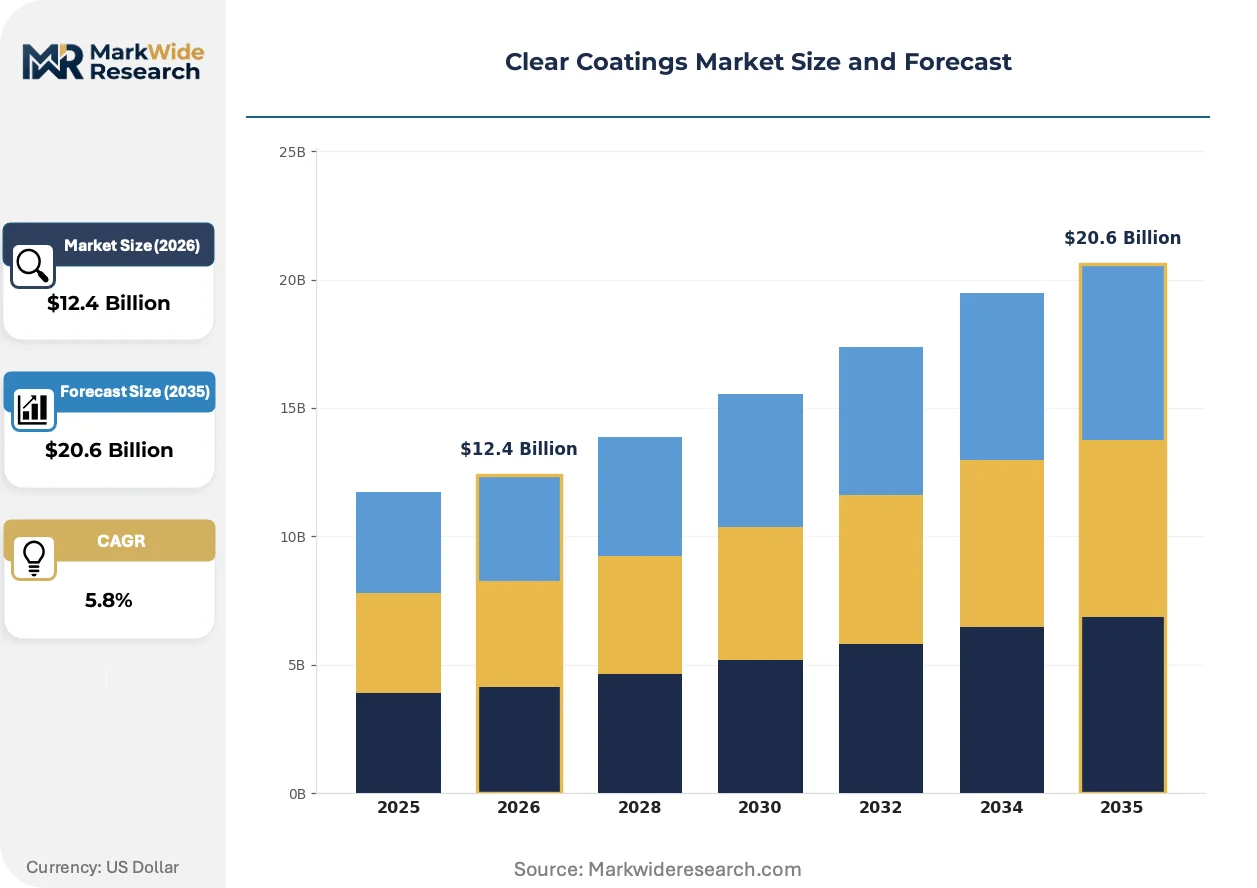
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polyurethane, Epoxy, Nitrocellulose Application: Automotive Finishing, Furniture, Flooring, Electronics End User: Manufacturers, Contractors, Retailers, DIY Enthusiasts Distribution Channel: Online, Hardware Stores, Specialty Stores, Wholesalers |
| Companies Covered | Axalta Coating Systems, Akzo Nobel N.V., PPG Industries, Inc., The Sherwin-Williams Company, Hempel A/S, BASF SE, 3M Company, Kansai Paint Co., Ltd., RPM International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clear Coatings Market Strategic Shifts
Formulation science is pivoting toward hybrid cure mechanisms that reconcile regulatory pressure with performance thresholds previously exclusive to solvent-borne systems.
Self-healing clear coat technology employing microencapsulated polymer precursors is decomposing the traditional trade-off between scratch resistance and refinishability in automotive OEM programs. German and Japanese luxury manufacturers are piloting these systems on hood and door panels where stone-chip exposure concentrates lifecycle warranty costs. The technology is decomposing aftermarket touch-up paint volumes while shifting value capture toward integrated coating-substrate system suppliers.
REACH authorization requirements for chromium trioxide in corrosion-inhibiting primers are cascading into downstream clear coat specifications, forcing compatibility testing with chromate-free pretreatment layers. European automotive OEMs now mandate full system approval rather than component-level qualification, extending validation timelines but reducing field failure liability. Suppliers with captive pretreatment chemistry capabilities are capturing specification-setting roles previously held by independent clear coat formulators.
Consolidated procurement by multi-site furniture retailers is compressing supplier rosters from twelve to three approved clear coat vendors per coating category. IKEA and Ashley Furniture now require quarterly sustainability scorecards covering water-borne content percentage and renewable feedstock ratios, displacing spot-buy relationships with regional distributors. This concentration is most visible in Vietnam and Poland, where export-oriented manufacturing parks house clustered finishing operations serving EU and US retail channels.
Clear Coatings Market Segmentation
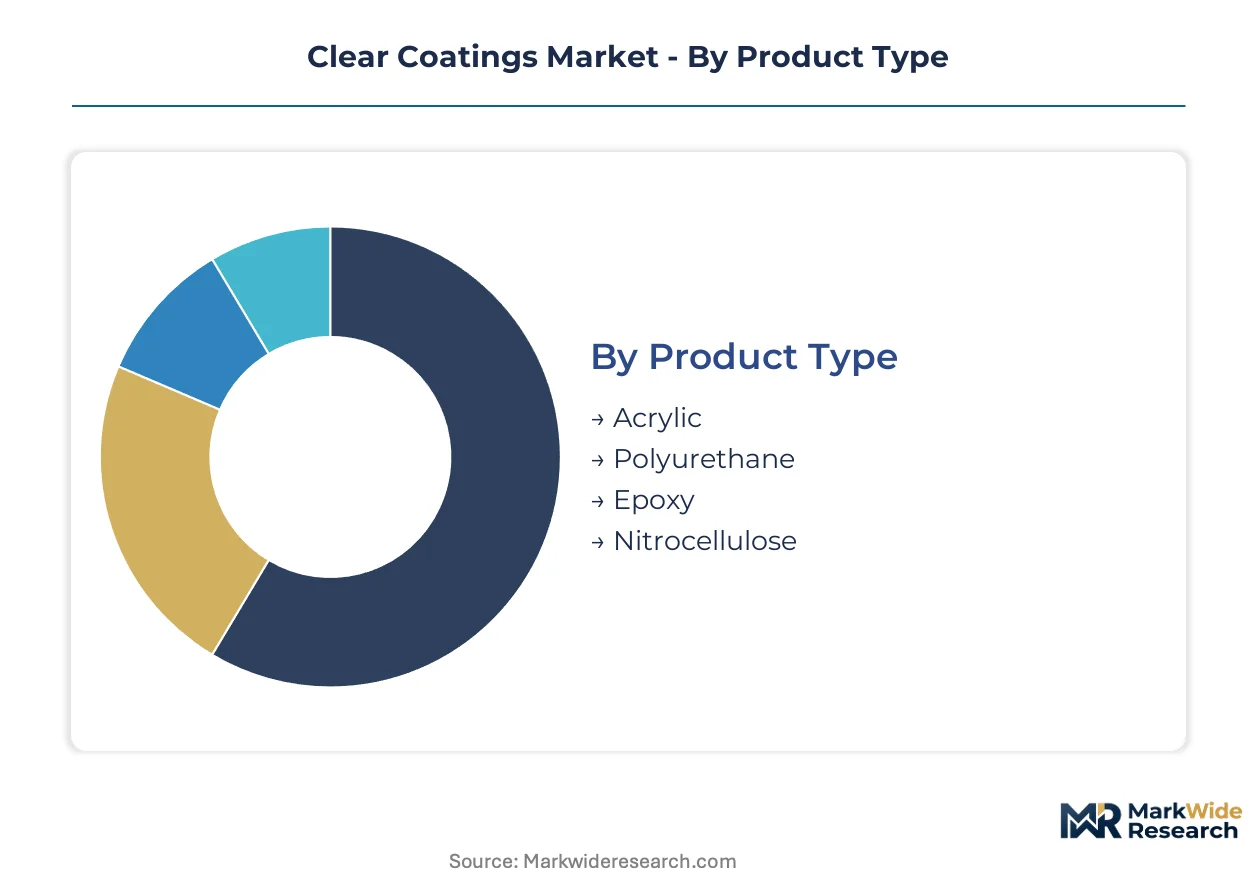
Clear coatings segmentation reveals how resin chemistry, application environment, and procurement channel each impose distinct performance specifications and margin structures. Formulators must align R&D investment with the hardness, cure speed, and regulatory compliance demands of specific end-use clusters.
Product Type:
Margin pools concentrate in polyurethane systems where aliphatic diisocyanate supply scarcity sustains premium pricing power.
- Acrylic:Rapid oxidative cure at ambient temperature yields 2H-4H hardness ratings suitable for architectural trim and DIY refinishing. Demand clusters in North American big-box retail channels where low-VOC water-borne formulations face EPA compliance deadlines.
- Polyurethane:Two-component aliphatic systems achieve 6H pencil hardness with exceptional UV stability and gloss retention. Automotive OEM exterior trim specifications in Germany and Japan pull volumes into premium vehicle programs where lifecycle warranty costs justify material expenditure.
- Epoxy:Amine-cured systems provide chemical resistance for electronics conformal coating applications below 100-micron thickness requirements.
- Nitrocellulose:Solvent-borne lacquers retain niche demand in antique furniture restoration where historical authenticity overrides emission concerns.
Polyurethane holds installed capacity. Acrylic is rotating up the share rankings as water-borne line conversions accelerate in furniture export clusters.
Application:
Volume concentration follows manufacturing geography, with export-oriented production centers absorbing disproportionate clear coat throughput.
- Automotive Finishing:Exterior clear coat specifications demand 6H hardness, 90+ gloss units at 60°, and 10-year warranty compliance. Tier-1 suppliers in Japan and Germany mandate full system approval encompassing pretreatment, primer, and clear coat layers.
- Furniture:Flatline spray operations on wood substrates prioritize 30-minute dust-free times and stackability within 4 hours. China's Guangdong and Jiangsu export clusters drive water-borne formulation demand under MEE enforcement of GB emission standards.
- Flooring:Two-component polyurethane systems dominate commercial high-traffic installations where abrasion resistance determines recoating intervals.
- Electronics:Conformal coating applications plateau as parylene vapor deposition captures miniaturized PCB protection below 50-micron thickness.
Automotive finishing commands specification authority. Furniture is expanding most quickly as sustainability scorecards consolidate supplier rosters for EU and US retail channels.
End User:
Procurement sophistication diverges sharply between specification-driven manufacturers and price-sensitive retail consumers.
- Manufacturers:Integrated coating-substrate system suppliers with captive pretreatment chemistry capabilities capture OEM specification-setting roles. Full system approval requirements extend validation timelines but reduce field failure liability exposure.
- Contractors:Automotive collision repair channels absorb AI-driven spectrophotometer-integrated dispensing systems that compress custom-mix lead times from 48 hours to 90 minutes.
- Retailers:IKEA and Ashley Furniture consolidated procurement now demands quarterly sustainability scorecards covering water-borne content percentage and renewable feedstock ratios.
- DIY Enthusiasts:Big-box retail channels in the United States favor pre-mixed water-borne acrylics with 2-hour recoat windows and soap-and-water cleanup.
Manufacturers hold formulation development resources. Retailers are climbing the fastest as sustainability compliance reshapes vendor qualification criteria.
Distribution Channel:
Channel economics reflect inventory velocity, technical service requirements, and regulatory documentation burdens.
- Online:E-commerce platforms capture standard-grade acrylic and polyurethane volumes where technical specification is self-service and SDS documentation is digitally accessible.
- Hardware Stores:Mass retail channels in the United States and Canada stock water-borne DIY formulations with prominent low-VOC labeling for regulatory compliance visibility.
- Specialty Stores:Independent distributors serve automotive refinish and marine applications requiring color-matching expertise and spray equipment technical support.
- Wholesalers:Bulk procurement relationships with furniture manufacturers in Vietnam and Poland concentrate volumes for export-oriented finishing operations.
Specialty stores maintain technical service relationships. Online is gaining share fastest as SDS digitization and self-service specification tools mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and Japan where automotive OEM specifications command premium formulations, while cost-competitive production clusters in China and Vietnam absorb volume growth under tightening environmental compliance.
United States
Automotive refinish channels and furniture manufacturing absorb substantial polyurethane and acrylic volumes. EPA VOC regulations under the Clean Air Act compress solvent-borne capacity while accelerating water-borne line conversions. Michigan and Ohio automotive corridors sustain demand for high-hardness clear coat systems serving Tier-1 supplier networks.
Germany
Luxury automotive OEMs in Bavaria and Baden-Württemberg mandate 6H pencil hardness ratings for exterior trim applications. REACH substance restrictions through ECHA force reformulation of high-performance refinish lines before alternatives achieve equivalent gloss retention. Ludwigshafen chemical complexes dominate aliphatic diisocyanate supply for polyurethane precursors.
China
Domestic automotive production and furniture exports drive substantial volume absorption across Guangdong and Jiangsu provinces. MEE enforcement of GB standards on industrial coating emissions accelerates water-borne line conversions in export-oriented manufacturing parks. Pearl River Delta furniture clusters reshape local compliance costs under dual carbon goals.
Japan
Premium vehicle programs in Aichi and Kanagawa prefectures pull polyurethane clear coat volumes through stringent lifecycle warranty requirements. METI industrial standards govern chemical emissions from coating operations. Automotive OEM specifications extend validation timelines but reduce field failure liability exposure for approved system suppliers.
India
Moradabad and Jodhpur metal-furniture exporters target EU retail chains through PLI scheme duty concessions on coating line imports. BIS certification requirements for industrial coatings create entry barriers for unqualified imports. Domestic formulation capacity expands to serve captive demand from export-oriented manufacturing parks.
Clear Coatings Market Competitive Environment
Concentration sits with integrated resin producers who control upstream alkyd, acrylic, and polyurethane precursor supply. Three distinct archetypes populate the competitive terrain: diversified chemical conglomerates with captive resin production, specialized coating formulators with marine and protective expertise, and regional players serving price-sensitive furniture export clusters. Capacity expansion and backward integration into resin synthesis represent the dominant competitive moves as raw material volatility reshapes margin pools.
Within the integrated chemical conglomerate tier, BASF SE and PPG Industries exemplify upstream control strategies that insulate formulation margins from feedstock volatility. Akzo Nobel N.V. occupies a specialization position anchored in marine and protective coating expertise. Kansai Paint Co., Ltd. represents the Asia-Pacific formulation-focused archetype serving automotive OEM channels.
| Leading Market Players |
|---|
| Axalta Coating Systems |
| Akzo Nobel N.V. |
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| Hempel A/S |
| BASF SE |
| 3M Company |
| Kansai Paint Co., Ltd. |
| RPM International Inc. |
| Others |
Value Chain & Pricing Dynamics
Water-borne resin substitution for solvent-borne alkyds simultaneously relocates supply geography toward Ludwigshafen and Guangdong chemical complexes while compressing pricing power among formulation-only competitors lacking captive acrylic dispersion capacity. This input transition rewards integrated producers with upstream resin control while exposing spot buyers to aliphatic diisocyanate supply squeezes.
Pricing Analysis
The customization-premium spread between automotive OEM configured-to-order polyurethane systems and standard-grade DIY acrylics spans three performance tiers tied to hardness certification and warranty backing. Price differentiation hinges on ISO 12944 corrosion ratings and 6H pencil hardness validation for Tier-1 supplier approval, with automotive exterior trim specifications commanding substantial premiums over architectural refinish volumes. Pricing pressure intensifies in furniture export clusters as IKEA and Ashley Furniture sustainability scorecards consolidate supplier rosters from twelve to three approved vendors per coating category. Retail DIY consumers exhibit highest price sensitivity, while German and Japanese luxury automotive OEMs prioritize lifecycle warranty compliance over material expenditure.
Supply Chain Analysis
Inventory cycles for aliphatic diisocyanate precursors extend substantially beyond standard resin lead times due to Ludwigshafen production concentration among three integrated chemical complexes. Raw material flows draw from Germany, China, and Japan for polyurethane precursors, acrylic monomers, and epoxy curing agents respectively. Supply chain risk centers on single-source vulnerability for aliphatic diisocyanate feedstocks where BASF SE and Covestro AG control capacity expansion decisions. Distribution runs through specialty coatings distributors for automotive refinish and marine applications, while bulk procurement relationships with Vietnamese and Polish furniture manufacturers concentrate standard-grade volumes for export-oriented finishing operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clear coatings constitute a defensive-moat market where REACH and EPA regulatory entrenchment creates substantial formulation approval barriers that protect incumbent positions from rapid competitive displacement.
For Market Incumbents: Compound specification authority through captive pretreatment chemistry capabilities that capture OEM full-system approval roles previously held by independent formulators. Extend ISO 12944 C5-M marine certification investments to delay competitive entry, while accelerating water-borne line conversions in Guangdong and Jiangsu furniture clusters ahead of MEE enforcement tightening. Aliphatic diisocyanate supply scarcity among Ludwigshafen producers threatens margin pools for polyurethane-dependent portfolios. For New Entrants and Emerging Players: Certification fast-track through BIS industrial coating approval in India opens captive demand from Moradabad and Jodhpur metal-furniture exporters targeting EU retail chains. Target AI-driven spectrophotometer-integrated dispensing in automotive collision repair channels where custom-mix lead time compression from 48 hours to 90 minutes displaces established supplier relationships. Marine superyacht refit yards in Mediterranean and Caribbean service channels offer specification-setting opportunities outside OEM-dominated automotive tiers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated resin producers with backward control over alkyd, acrylic, and polyurethane precursor supply. Long-term viability over the projection horizon rests on capacity expansion and captive synthesis capabilities that insulate formulation margins from feedstock volatility. Watch ECHA candidate list expansion for reprotoxic monomers as the inflection signal forcing premature reformulation investments before alternatives achieve equivalent gloss retention.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Resin Synthesis | Captive supply of water-borne dispersions insulates PPG Industries from raw material volatility in EPA-regulated markets. |
| ISO 12944 C5-M Marine Certification Investment | Eighteen-month laboratory testing cycles delay competitive entry for new polyurethane entrants in hull aesthetic renewal channels. |
| AI-Driven Spectrophotometer Dispensing Deployment | Ninety-minute custom-mix lead times compress automotive collision repair procurement decisions toward technology-advantaged suppliers. |
| Water-Borne Line Conversion in Guangdong Clusters | MEE GB standard enforcement accelerates compliance investments among furniture exporters serving EU sustainability scorecards. |
| Long-Term Supply Agreement with Aliphatic Diisocyanate Producers | Fixed-volume contracts with Ludwigshafen complexes hedge polyurethane clear coat margins against input cost spikes. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with coating formulators, automotive Tier-1 procurement officers, furniture manufacturing plant managers, and marine refinish distributors; and secondary validation through customs trade databases, SEC 10-K filings, EPA enforcement records, and ECHA substance restriction notifications. Bottom-up volume estimates from application-level consumption patterns triangulated against top-down resin production capacity data from ACC and Cefic industry reports.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning resin chemistry tier, end-use application environment, procurement channel structure, and regional regulatory compliance cluster. CAGRs derived from historical trajectory analysis adjusted for water-borne mandate acceleration and UV-curable technology maturation. Forecast inputs incorporated automotive OEM specification timelines, MEE enforcement intensity in Pearl River Delta manufacturing parks, and REACH authorization requirements for chromium trioxide in corrosion-inhibiting pretreatment layers.
Decision-makers should treat outputs as directional under assumptions of sustained EPA and REACH regulatory trajectory, continued aliphatic diisocyanate supply concentration, and water-borne formulation performance parity achievement; material deviation in ECHA candidate list expansion pace or automotive OEM specification relaxation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Coating Resins Market
Coatings
Japan Architectural Coatings Market
Coatings
Japan Protective Coatings Market
Coatings
E-Coat Market
Coatings
Global High-Performance Anti-Corrosion Coatings Market
Coatings
South Africa Automotive OEM Coatings Market
Coatings
United States Automotive OEM Coatings Market
Coatings
Cold Gas Spray Coating Market
Coatings
France Protective Coatings Market
Coatings
Tablet and Pellet Coating Systems Market
Coatings
US Concrete Floor Coatings Market
Coatings
Global Mirror Coatings Market
Coatings
PU Coatings Market
Coatings
Polyurethane Powder Coatings Market
Coatings
High Temperature Coatings Market
Coatings
Polyvinylidene Chloride (PVDC) Coated Films Market