
 Wood Sealer Market | 2026-2036
Wood Sealer Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Sealer Market Analytics
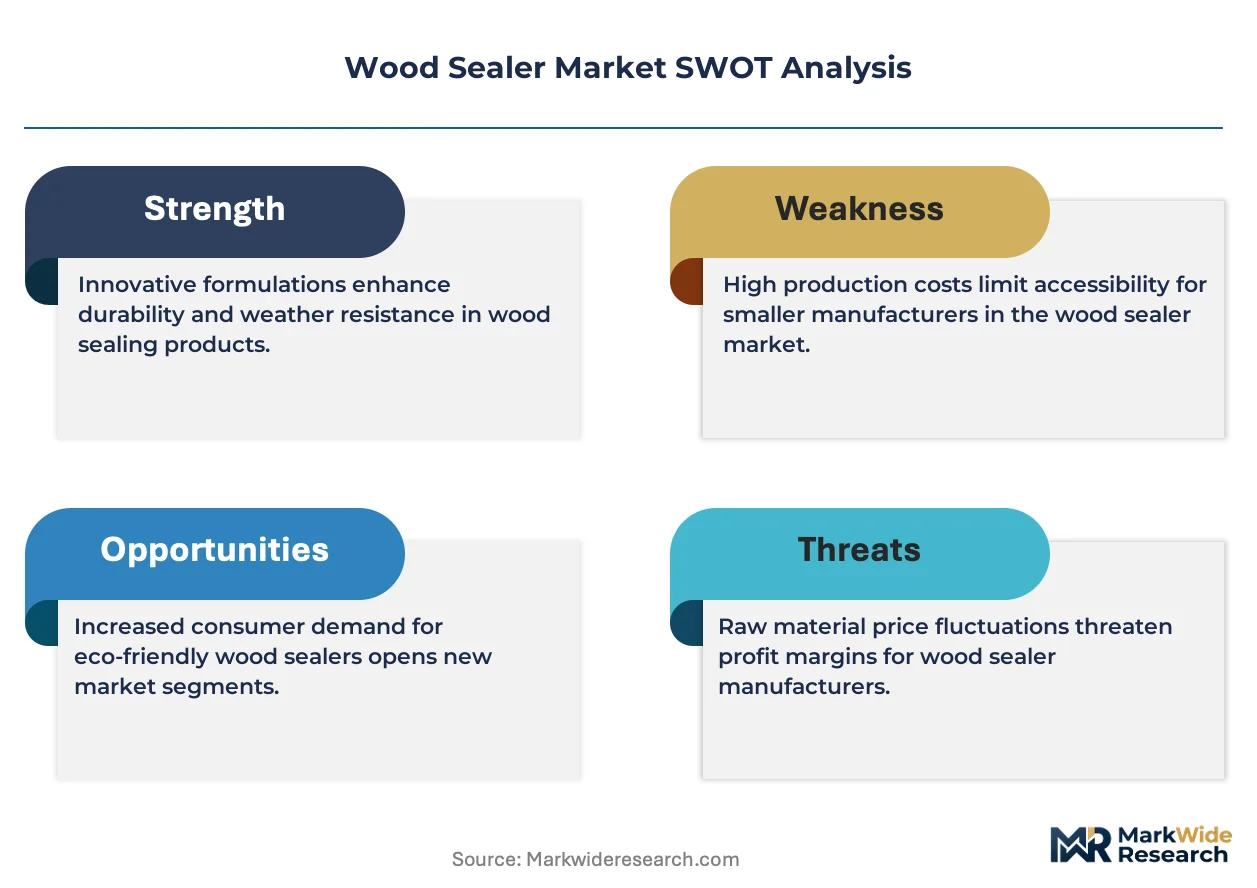
Specialty retail and pro-contractor distribution is reshaping how wood sealers reach end users. Thompson's WaterSeal leverages its brand heritage to dominate big-box shelf space. Seal-Once differentiates through nano-polymer technology leadership in eco-formulations. Reliable Paints competes on geographic density across South Asian export channels.
Wood sealer denotes a protective coating formulated with resins, solvents, and additives that penetrates or films over cellulose substrates to block moisture ingress, UV degradation, and fungal attack; typical formulations specify solids content between 20% and 45% and dry-film thickness requirements measured in mils for performance grading. Water-based sealers lead volume due to regulatory tailwinds, while oil-based variants retain margin pools in heritage restoration and marine applications where deep penetration matters. Decking and fencing command the fastest application growth as exterior structures multiply in suburban construction.
EPA VOC regulations and REACH substance restrictions in Europe are forcing solvent-phase reductions and biocide re-registration across formulations. OSHA workplace exposure limits further constrain spray-application methods in commercial settings. Stakeholders must monitor pending chemical hazard classifications that could delist incumbent preservatives before committing to multi-year supply agreements.
Market Dynamics
EPA VOC emission standards for architectural coatings are forcing systematic reformulation across the wood sealer industry, compressing solvent-phase volumes while elevating water-based chemistry R&D spending. This regulatory pressure intersects with raw material cost volatility in petroleum-derived alkyd resins.
Growth Catalysts
- Residential Decking Construction:Suburban outdoor living expansion in the United States drives protective coating demand for pressure-treated lumber and composite substrates.
- REACH Biocide Re-registration:European Union substance restrictions accelerate development of next-generation fungicides with improved environmental profiles.
- Nano-polymer Penetration Technology:Advanced particle engineering enables deeper wood fiber saturation with reduced solids loading requirements.
Market Restraints
- Petroleum Resin Cost Volatility:Crude oil price fluctuations destabilize alkyd and polyurethane feedstock pricing for oil-based formulations.
- Supply Concentration in Titanium Dioxide:Chinese pigment production controls create input bottlenecks for UV-blocking additive packages.
- Deep-penetration Technical Limits:Water-based chemistries fail to match oil-phase capillary action in dense hardwood species.
Strategic Opportunities
- Heritage Restoration Segment:Historic building preservation mandates in Italy and France sustain premium oil-based sealer demand.
- Marine Application Expansion:Yacht and dock maintenance cycles create recurring revenue pools in coastal Mediterranean markets.
- OSHA Workplace Exposure Alignment:Spray-application restrictions favor brush and roll-on product formats with lower liability profiles.
Industry Challenges
- Formulation Chemistry Talent Scarcity:Retiring polymer scientists constrain R&D velocity for compliant biocide alternatives.
- Multi-jurisdiction Certification Timelines:Parallel EPA, REACH, and BIS registration processes delay product launches by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Sealer Market |
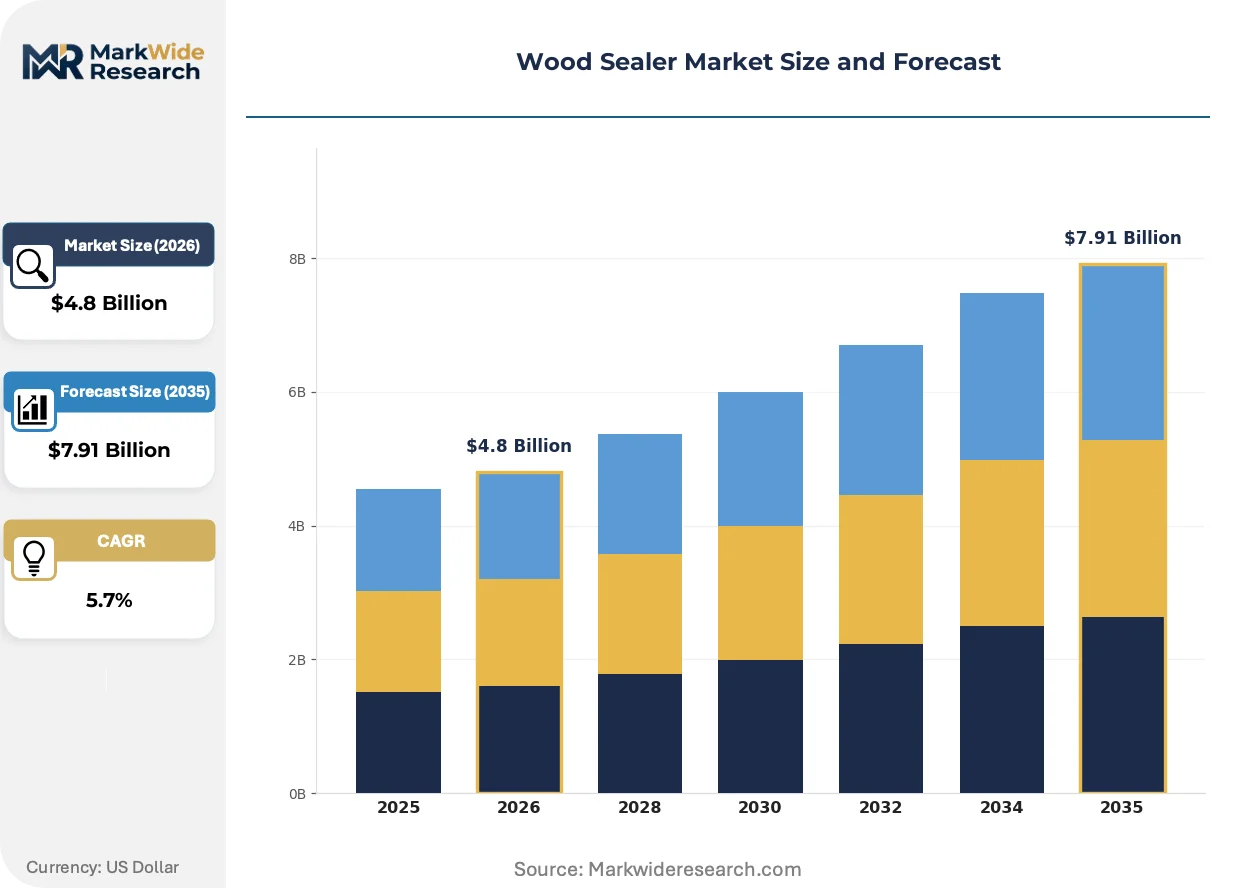
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil-Based Sealers, Water-Based Sealers, Varnish Sealers, Polyurethane Sealers Application: Furniture, Flooring, Decking, Fencing Form: Liquid, Gel, Spray, Paste End User: Contractors, DIY Enthusiasts, Manufacturers, Retail Stores |
| Companies Covered | Thompson's WaterSeal, Seal-Once, Pettit Marine Paint, Sasco Products, Nano Polycoat, Reliable Paints, Sachar Paints Industries, Desai Coat, Jyoti Enterprises, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Sealer Market Evolving Landscape
Reformulation chemistry is converging with application-method constraints, creating parallel innovation tracks in low-VOC penetration technologies and compliant installation protocols.
Silane-siloxane hybrid chemistry is rendering obsolete traditional acrylic film-forming sealers in above-grade concrete and wood protection. Commercial contractors in the United States are specifying these penetrating systems for parking structure and boardwalk projects. The technology is rendering obsolete warranty claims tied to peeling and flaking failures.
EPA architectural coating VOC limits are tightening maximum allowable emissions for deck and siding products. Formulators are responding with exempt-solvent blends and water-reducible alkyd hybrids. Marine and specialty restoration segments face compliance cost pressure while residential decking adapts faster.
Professional contractor specification authority is consolidating purchasing decisions away from retail walk-in traffic. Big-box distributors are losing specification influence to pro-focused supply houses with field technical support. This pattern concentrates most visibly in United States suburban construction corridors.
Wood Sealer Market Segmentation
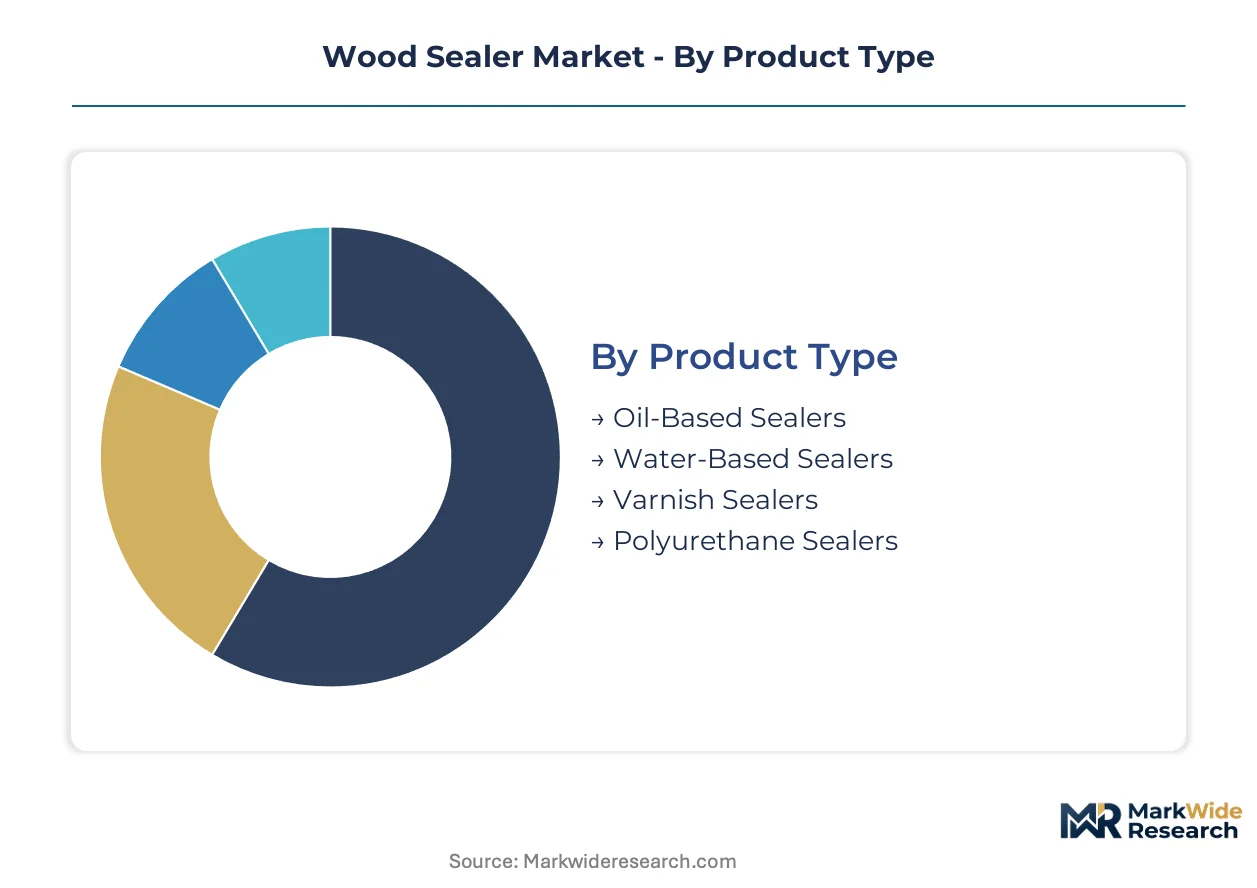
Wood sealer purchasing decisions fragment across technical specifications, project scale, and regulatory exposure. Formulation chemistry and application method together determine performance outcomes in residential, commercial, and industrial settings.
Product Type:
Formulation chemistry defines penetration depth, VOC compliance burden, and substrate compatibility across use cases.
- Water-Based Sealers:Acrylic and polyurethane dispersions with 20-45% solids content meet EPA architectural coating VOC limits for residential decking. Demand clusters in United States suburban construction corridors where spray-application restrictions favor low-odor, fast-dry formulations.
- Oil-Based Sealers:Alkyd and natural oil formulations deliver capillary penetration into dense hardwood species for heritage restoration and marine applications. REACH biocide re-registration pressures are elevating formulation costs in European preservation markets.
- Varnish Sealers:Film-forming urethane-alkyd hybrids provide gloss retention for interior furniture and cabinetry. United States specialty retail channels dominate specification authority for premium interior finishes.
- Polyurethane Sealers:Two-component and moisture-cure systems offer abrasion resistance for high-traffic flooring in commercial and industrial settings.
Water-based formulations command the established base. The steepest expansion runs through oil-based heritage restoration segments where deep penetration specifications resist substitution.
Application:
Surface exposure conditions determine durability requirements and re-coating frequency across residential and commercial assets.
- Decking:Horizontal surfaces face UV degradation, moisture cycling, and fungal attack in exterior exposure. United States outdoor living trends drive protective coating specification for pressure-treated lumber and composite substrates in suburban markets.
- Fencing:Vertical wood structures require water-repellent penetration with reduced film-build to prevent peeling. Coastal Mediterranean markets generate recurring maintenance demand for yacht dock and marina fencing systems.
- Flooring:Interior wood surfaces prioritize abrasion resistance and gloss retention in residential and commercial settings.
- Furniture:Interior cabinetry and millwork demand aesthetic finish quality with minimal substrate distortion.
Decking commands the established base. The steepest expansion runs through fencing applications where coastal maintenance cycles create recurring revenue pools.
Form:
Physical state determines application equipment requirements, coverage rates, and OSHA workplace exposure compliance.
- Liquid:Low-viscosity penetrating sealers enable brush, roll, and spray application with standardized coverage rates of 150-400 square feet per gallon. United States pro-contractor channels specify liquid formulations for field efficiency in large-scale decking projects.
- Spray:Aerosol and pump-spray packaging target touch-up applications and intricate detail work. OSHA workplace exposure limits are constraining commercial spray-application methods in favor of lower-liability brush and roll formats.
- Gel:Thixotropic formulations cling to vertical surfaces without sagging in fencing and siding applications.
- Paste:High-solids putty-grade sealers fill cracks and defects in heritage restoration and marine repair contexts.
Liquid formulations command the established base. The steepest expansion runs through gel systems where vertical application efficiency gains specification share in fencing and siding.
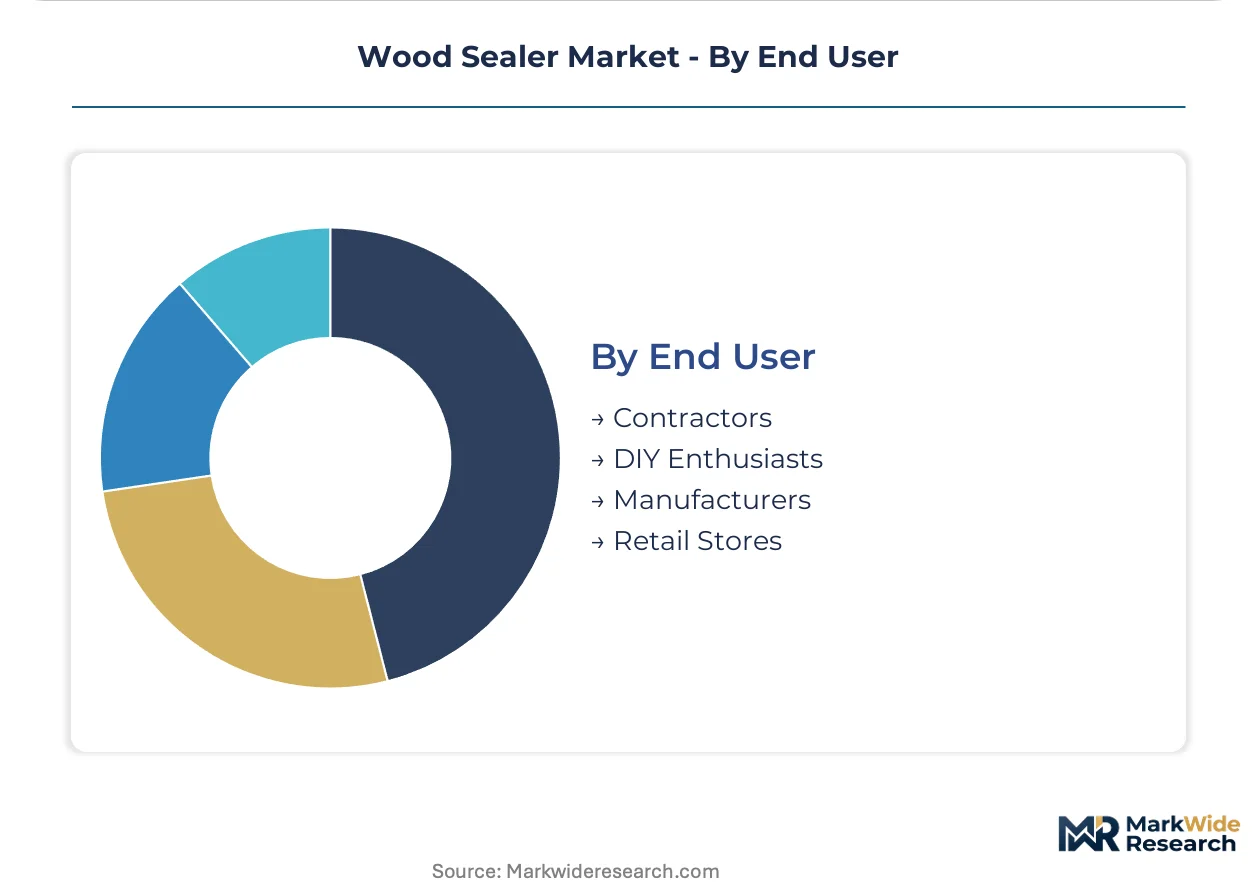
End User:
Purchasing authority concentrates differently across specification-driven commercial projects and price-sensitive residential maintenance.
- Contractors:Professional installers exercise specification authority through pro-focused supply houses with field technical support. United States suburban construction corridors show concentrated purchasing consolidation away from retail walk-in traffic.
- DIY Enthusiasts:Homeowners prioritize convenience, brand recognition, and low-VOC labeling for residential decking and fencing projects. Big-box retail shelf space competition intensifies around Thompson's WaterSeal heritage positioning and Seal-Once nano-polymer differentiation.
- Manufacturers:Industrial wood product producers specify pre-treatment and finish coatings for dimensional lumber, engineered wood, and millwork.
- Retail Stores:Distribution intermediaries curate assortment based on inventory velocity, margin structure, and regional climate conditions.
Contractor channels command the established base. The steepest expansion runs through DIY enthusiasts where outdoor living trends and water-based regulatory compliance intersect.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA architectural coating VOC limits anchor the United States as the dominant geography, while REACH biocide re-registration and dual carbon goals reshape formulation requirements across Europe and Asia-Pacific manufacturing clusters.
United States
Suburban outdoor living expansion drives protective coating specification for pressure-treated lumber decking in Sun Belt construction corridors. EPA VOC emission standards for architectural coatings compress solvent-phase volumes while elevating water-based chemistry R&D spending. Dallas-Fort Worth and Phoenix metropolitan clusters concentrate contractor specification authority through pro-focused supply houses with field technical support.
Germany
Heritage building preservation mandates sustain premium oil-based sealer demand for historic timber structures in Bavaria and Baden-Württemberg. ECHA REACH substance restrictions accelerate development of next-generation fungicides with improved environmental profiles. The Stuttgart industrial corridor hosts formulation specialists serving Central European restoration contractors.
China
Engineered wood product manufacturing expansion creates industrial pre-treatment coating demand for dimensional lumber and millwork exports. MEE environmental compliance standards and dual carbon goals pressure solvent-phase reduction in Guangdong and Zhejiang coating clusters. The Yangtze River Delta concentration serves furniture OEM specification for water-based interior finishes.
Italy
Coastal marina maintenance cycles generate recurring revenue pools for yacht dock and fencing protection systems along Ligurian and Adriatic shorelines. EU Green Deal implementation timelines accelerate biocide re-registration for marine-grade formulations. The Venice-Trieste corridor concentrates specialty restoration contractors serving UNESCO heritage timber structures.
India
South Asian export channel density drives geographic competition across Maharashtra and Gujarat industrial zones. BIS certification requirements for architectural coatings create multi-jurisdiction registration complexity alongside EPA and REACH parallel processes. The Mumbai-Pune corridor anchors distribution infrastructure serving residential decking and fencing applications.
Wood Sealer Market Competitive Landscape
Heritage-brand specialists and nano-technology formulators split the market between mass retail shelf presence and contractor specification channels. The vendor base organizes around three strategic archetypes: big-box retail dominators leveraging brand recognition, technology-led eco-formulation pioneers, and geographic-density exporters serving regional industrial clusters. Consolidation pressure concentrates through M&A activity targeting water-based chemistry capabilities, while strategic partnerships accelerate exempt-solvent blend development for regulatory compliance.
Within the heritage-brand tier, Thompson's WaterSeal exemplifies retail channel dominance through decades of consumer recognition in North American home improvement distribution. Seal-Once occupies a position representing nano-polymer technology leadership among eco-formulation specialists targeting contractor specification authority. Reliable Paints anchors the geographic-density archetype with South Asian export channel concentration. These three company structures illustrate how formulation chemistry specialization, distribution control, and regional manufacturing proximity compete as distinct strategic vectors.
| Leading Market Players |
|---|
| Thompson's WaterSeal |
| Seal-Once |
| Pettit Marine Paint |
| Sasco Products |
| Nano Polycoat |
| Reliable Paints |
| Sachar Paints Industries |
| Desai Coat |
| Jyoti Enterprises |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese titanium dioxide pigment production is compressing margins for UV-blocking additive packages while simultaneously granting formulation buyers leverage in annual contract negotiations across North American and European coating clusters.
Pricing Analysis
Geographic price spreads between United States and South Asian export channels exceed transportation cost differentials, reflecting BIS certification burdens and EPA VOC compliance overhead that premium formulations command. Three-tier pricing structure across premium, standard, and economy levels stratifies by solids content and biocide registration tier, with heritage restoration oil-based sealers capturing brand premiums. Pricing pressure stems from petroleum resin cost volatility destabilizing alkyd feedstock budgeting. DIY enthusiasts exhibit highest price sensitivity, while heritage restoration contractors demonstrate lowest elasticity due to specification lock-in.
Supply Chain Analysis
Upstream petroleum-derived alkyd resins and Chinese titanium dioxide pigments anchor raw material dependencies for UV-blocking and film-forming formulations. Formulation chemistry concentrates in United States, Germany, and China, with South Asian exporters serving price-sensitive regional markets. Single-source vulnerability concentrates in Chinese pigment production controls creating input bottlenecks. Distribution runs through pro-focused supply houses consolidating specification authority away from big-box retail in United States suburban construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wood sealer demand sits in early-cycle expansion as suburban outdoor living trends in Sun Belt metropolitan clusters accelerate protective coating specification for residential decking assets.
For Market Incumbents: Build formulation chemistry moats through captive R&D investment in exempt-solvent blends and water-reducible alkyd hybrids that preempt EPA VOC tightening. Consolidate pro-contractor channel control through field technical support investments in Dallas-Fort Worth and Phoenix construction corridors. Counter nano-polymer displacement threats by acquiring silane-siloxane hybrid technology capabilities. For New Entrants and Emerging Players: Build out white-space positions in coastal Mediterranean marine maintenance cycles where recurring dock and yacht protection demand outpaces incumbent service coverage. Target fencing applications in suburban United States markets where gel formulation vertical application efficiency gains specification share. Pursue direct contractor specification authority through pro-focused supply house partnerships rather than retail shelf competition. For Investors and Strategic Acquirers: Capital is best deployed toward water-based chemistry specialists with pending EPA registration pipelines and proven nano-polymer penetration platforms. Long-term viability favors assets with multi-jurisdiction certification capabilities spanning EPA, REACH, and BIS parallel processes. Monitor REACH biocide re-registration timelines as inflection signals for incumbent preservative delisting risk and replacement chemistry acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Exempt-Solvent Blend Development | EPA VOC compliance positioning preempts regulatory compression on solvent-phase volumes. |
| Pro-Contractor Channel Expansion | Field technical support investments consolidate specification authority in Sun Belt corridors. |
| Nano-Polymer Technology Acquisition | Silane-siloxane hybrid capabilities displace traditional acrylic film-forming warranty exposures. |
| Multi-Jurisdiction Certification Investment | Parallel EPA, REACH, and BIS registration capabilities compress product launch timelines. |
| Heritage Restoration Segment Focus | Deep penetration specifications in Italian and French preservation markets resist water-based substitution. |
Research Methodology
A spread of perspectives from coating formulators, pro-contractor procurement leads, big-box category buyers, and regulatory affairs specialists converged on the working assumptions driving volume and value estimates. Primary fieldwork across United States, German, and Chinese manufacturing clusters was cross-referenced with EPA architectural coating rulemakings, REACH substance restriction updates, customs trade data, and SEC filings from publicly traded chemical companies. Bottom-up segment sizing and top-down macro validation were triangulated to constrain estimate variance.
Demand-supply balance modeling across formulation chemistry types, application methods, and end-user channels structured the analytical framework over the projection horizon. Segmentation dimensions included product chemistry, substrate application, physical form, and purchasing authority archetype. CAGRs were derived from elasticity-adjusted adoption curves and replacement cycle frequencies. Key inputs encompassed suburban construction permit velocities, biocide re-registration timelines, and raw material cost pass-through coefficients.
Stress conditions across petroleum resin price volatility, Chinese pigment export restrictions, and EPA VOC enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory compliance cost trajectories and contractor channel consolidation rates. Material shifts in REACH biocide hazard classifications or EPA architectural coating emission thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Battery Coating Market
Coatings
Sol Gel Nanocoating Market
Coatings
Coating Pigments Market
Coatings
Antimicrobial Coil Coating Market
Coatings
Flexible Waterproof Coating Market
Coatings
Japan Marine Coatings Market
Coatings
Global Powder Coating Market
Coatings
Hydrophilic Interior Glass Defogging Coatings Market
Coatings
Global Surface Protection Films Market
Coatings
Egyptian Protective Coatings Market
Coatings
Glazes Market
Coatings
Graphene Coatings Market
Coatings
Silicone Coating Market
Coatings
Coating Agents for Synthetic Leather Market
Coatings
Stain Resistance Coatings Market
Coatings
Saudi Arabia Floor Coatings Market