
 Functional Additives and Barrier Coatings Market | 2026-2036
Functional Additives and Barrier Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Additives and Barrier Coatings Market Foresight
Performance-based coating subscriptions and software-defined barrier tuning is decoupling material sales from long-term value capture in the packaging sector. BASF SE leverages its Ludwigshafen integrated site to sustain captive supply of UV stabilizers and slip agents for European converters. Dow Inc. anchors North American supply of plasma-deposited barrier films through its Midland materials science campus. Arkema S.A. differentiates via fluoropolymer-free hydrophobic chemistries that navigate tightening F-Gas Regulation constraints.
Functional additives and barrier coatings comprise surface-active chemistries and thin-film depositions engineered to control permeation, degradation, and interfacial properties across polymer, metal, and cellulosic substrates. Sol-gel silica coatings achieve oxygen transmission rates below 0.01 cc/m²/day at 23°C, enabling modified-atmosphere food packaging without multi-layer coextrusion complexity. Hydrophobic agents and antimicrobial additives occupy mature, high-volume positions where margin pools have compressed; UV stabilizers and flame retardants represent faster-growing categories driven by construction durability codes and electronics enclosure standards. Chemical vapor deposition and layer-by-layer assembly command premium positioning for precision barrier applications in flexible electronics and pharmaceutical blister packs.
REACH registration requirements and EU F-Gas Regulation phase-down schedules shape permissible chemistries for food-contact and industrial barrier applications in Europe. FDA food additive regulations and EPA chemical substance inventory listings govern market access for U.S.-supplied antimicrobial and slip agents. OSHA permissible exposure limits for volatile deposition precursors influence technology selection in domestic manufacturing. Stakeholders must monitor evolving substance restriction lists and deposition energy intensity benchmarks to align R&D portfolios with compliance trajectories.
Market Dynamics
REACH chemical migration limits and EU F-Gas Regulation phase-downs are compressing permissible chemistries while simultaneously elevating demand for fluoropolymer-free alternatives. This regulatory squeeze is redrawing competitive advantage toward integrated producers with captive reformulation capabilities.
Growth Catalysts
- Modified-atmosphere food packaging:Retailers demand shelf-life extension without multi-layer coextrusion complexity. Sol-gel silica coatings achieve sub-0.01 cc/m²/day oxygen transmission rates.
- EU Green Deal implementation:Circular economy mandates for packaging recyclability favor mono-material structures compatible with thin-film barrier depositions over laminated films.
- Electronics enclosure standards:Flame retardant and UV stabilizer demand accelerates as construction durability codes tighten across building-integrated photovoltaics and outdoor infrastructure.
Market Restraints
- Silicon alkoxide precursor volatility:Sol-gel coating input costs fluctuate with semiconductor-grade chemical supply constraints and energy-intensive purification requirements.
- German production cluster concentration:Ludwigshafen and Marl chemical parks anchor European UV stabilizer and slip agent supply, creating geographic single-point vulnerability.
- Plasma deposition capex barriers:Chemical vapor deposition equipment requires cleanroom infrastructure and specialized precursor handling that excludes mid-scale converters.
Strategic Opportunities
- Pharmaceutical blister pack migration:Layer-by-layer assembly enables precision moisture barriers for humidity-sensitive biologics where aluminum cold-form foil faces recyclability pressure.
- India packaging modernization:FSSAI food-contact material notifications are tightening, creating first-mover advantage for REACH-compliant additive suppliers establishing local technical service.
- Flexible electronics convergence:Atomic layer deposition for organic photovoltaics and foldable displays merges barrier requirements with semiconductor processing expertise.
Industry Challenges
- Deposition precursor toxicology assessment:ECHA substance evaluation timelines extend 18-36 months for novel organometallic precursors, delaying product launches.
- Legacy coextrusion asset stranding:Multi-layer film lines represent sunk capital incompatible with thin-film coating retrofits, forcing parallel technology maintenance.
- Cross-functional formulation expertise:Barrier coating development requires simultaneous mastery of polymer rheology, surface chemistry, and regulatory toxicology that few technical teams possess.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Additives and Barrier Coatings Market |
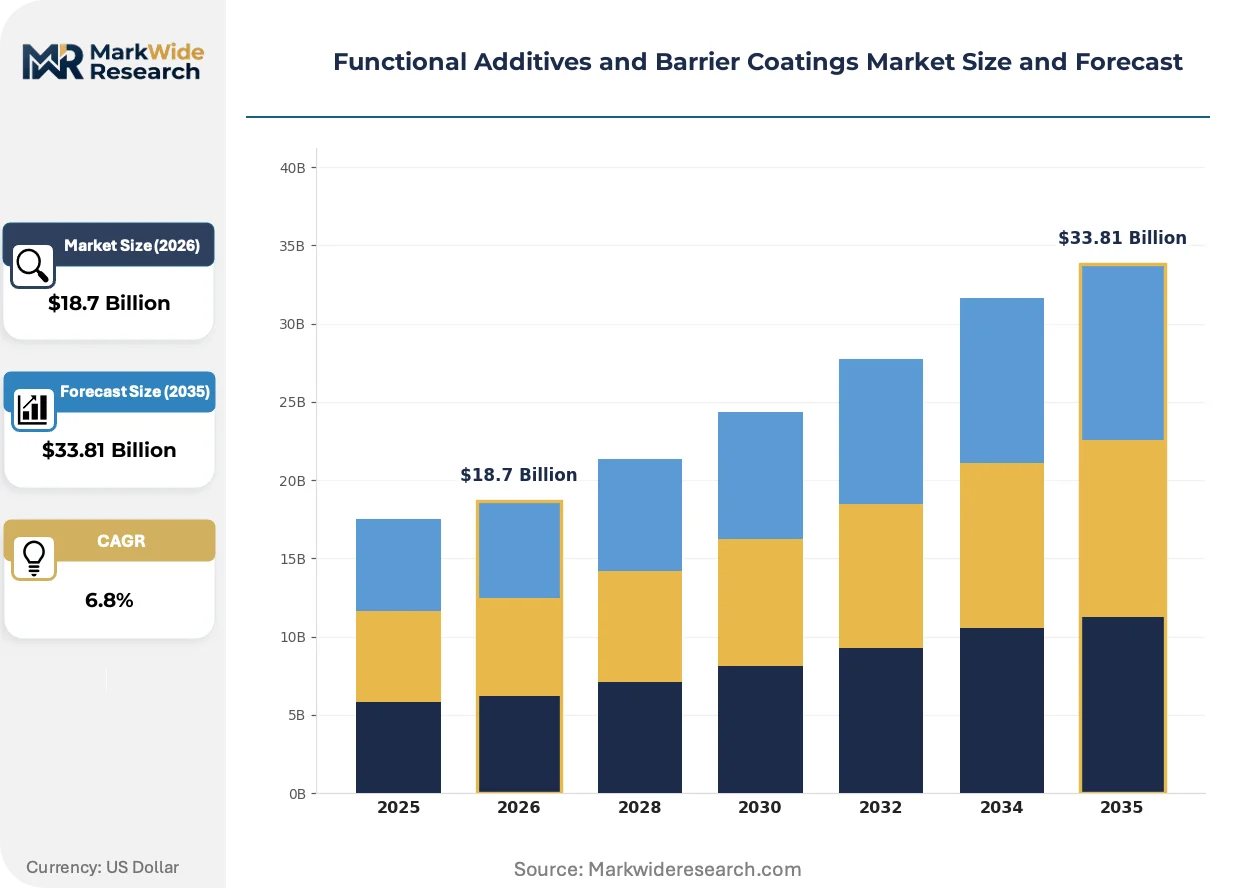
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrophobic Agents, Antimicrobial Additives, UV Stabilizers, Flame Retardants, Slip Agents Technology: Sol-Gel, Plasma Deposition, Chemical Vapor Deposition, Electrospinning, Layer-by-Layer Assembly Application: Food Packaging, Electronics Enclosures, Protective Apparel, Automotive Components, Construction Materials End User: Packaging Manufacturers, Electronic Assemblers, Safety Equipment Producers, Vehicle Parts Suppliers, Building Materials Fabricators |
| Companies Covered | BASF SE, Dow Inc., Arkema S.A., Evonik Industries AG, Solvay S.A., Henkel AG & Co. KGaA, Clariant AG, Songwon Industrial Co. Ltd., AkzoNobel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Additives and Barrier Coatings Market Shifts & Advancements
Active barrier technologies are displacing passive material stacking as the dominant architecture for shelf-life extension. Software-defined deposition control and performance-based coating subscriptions are decoupling capital intensity from barrier function delivery.
Atomic layer deposition is unifying angstrom-precision thickness control with roll-to-roll processing compatibility. Pharmaceutical blister manufacturers adopt this for moisture barriers on thermoformed trays. The technology is unifying barrier performance with format flexibility that aluminum cold-form foil cannot match, compressing incumbent material volumes.
EU F-Gas Regulation phase-down schedules are eliminating perfluorinated chemistry options for hydrophobic barrier coatings. Arkema and Solvay accelerate fluoropolymer-free alternatives through hydrophobic nanocomposite development. Food-contact material producers in Italy and Spain face compressed reformulation timelines as 2026 reduction targets approach.
Converters consolidate procurement around technical service partnerships rather than commodity additive transactions. Mid-sized European packaging groups now specify formulation support, migration testing, and regulatory documentation as standard contract terms. This behavior shift concentrates supplier relationships in Germany and Benelux where technical service infrastructure is densest.
Functional Additives and Barrier Coatings Market Segmentation
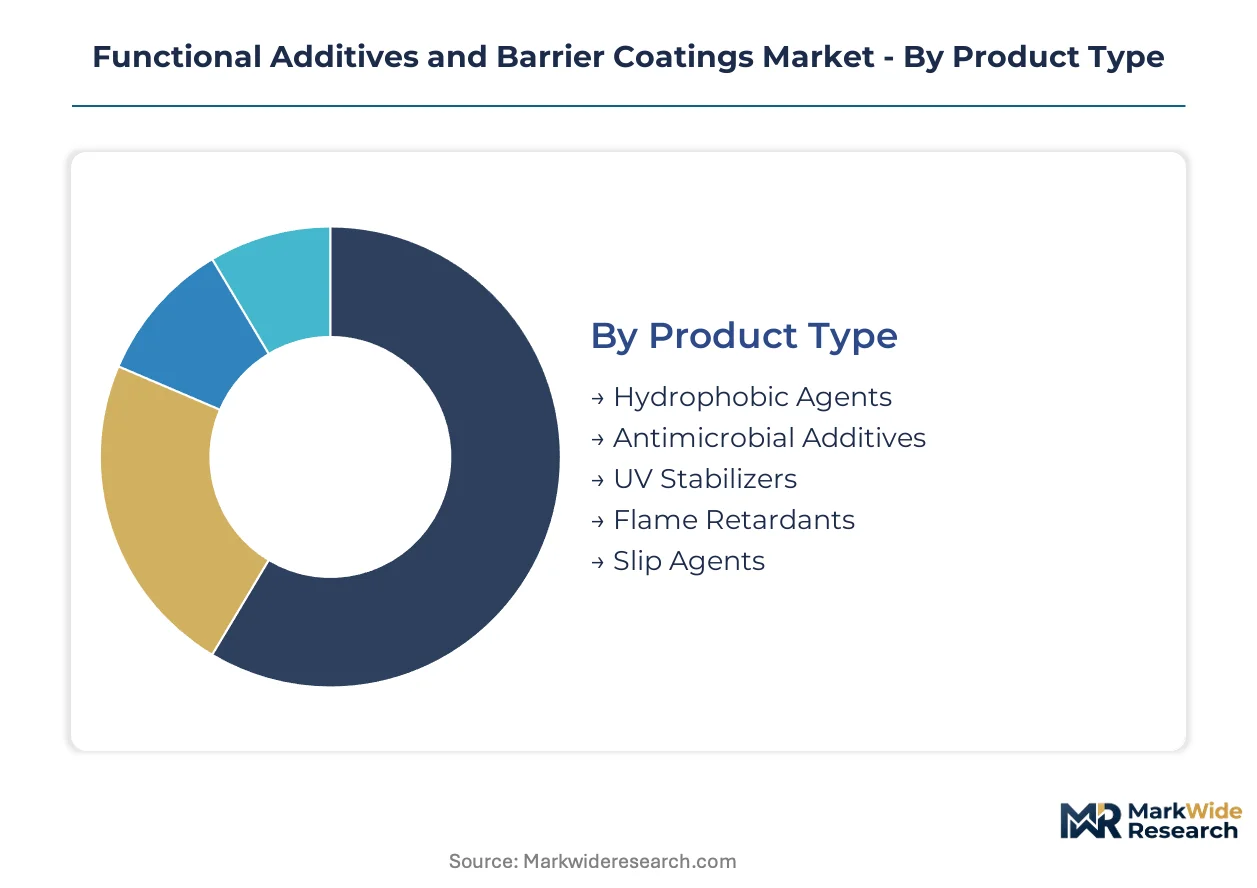
Segmentation in functional additives and barrier coatings reveals where value capture concentrates versus where volume commoditizes. Product chemistry, deposition technology, and end-use performance requirements create distinct margin pools that suppliers navigate through specialized formulation capabilities.
Product Type:
Integration depth varies sharply across additive categories, with some functioning as standalone surface treatments and others requiring embedding within polymer matrices during processing.
- UV Stabilizers:Hindered amine light stabilizers and benzotriazole derivatives absorb ultraviolet radiation to prevent polymer chain scission. Demand concentrates in Germany's construction sector as building-integrated photovoltaics expand and outdoor durability codes tighten under EU Green Deal implementation.
- Flame Retardants:Halogen-free phosphorus and nitrogen-based chemistries interrupt combustion through char formation or radical scavenging. Electronics enclosure manufacturers in automotive and building sectors drive specification intensity as IEC 60695 and EN 13501 standards elevate testing thresholds.
- Hydrophobic Agents:Silane and fluoropolymer-free nanocomposite surface modifiers repel moisture without compromising recyclability.
- Antimicrobial Additives:Silver-ion and organic biocide formulations inhibit microbial growth on food-contact surfaces.
- Slip Agents:Erucamide and oleamide fatty acid derivatives reduce film-to-film friction in high-speed packaging lines.
UV stabilizers lead volumes today; flame retardants are gaining share fastest.
Technology:
Cost tier stratification separates capital-intensive vacuum deposition methods from solution-based coating approaches accessible to mid-scale converters.
- Sol-Gel:Alkoxide hydrolysis-condensation produces silica networks with sub-0.01 cc/m²/day oxygen transmission rates. Food packaging converters in Italy and Spain adopt this for mono-material recyclable structures as EU circular economy mandates phase out multi-layer laminates.
- Layer-by-Layer Assembly:Electrostatic deposition of oppositely charged polyelectrolytes builds angstrom-precise moisture barriers. Pharmaceutical blister pack manufacturers specify this for biologics humidity protection where aluminum cold-form foil faces recyclability pressure.
- Plasma Deposition:Glow discharge activation enables conformal coating on temperature-sensitive substrates.
- Chemical Vapor Deposition:Precursor gas-phase reactions deposit ceramic barriers requiring cleanroom infrastructure.
- Electrospinning:High-voltage fiber drawing creates nanofibrous membranes for breathable protective apparel.
Sol-gel dominates current installed capacity; layer-by-layer assembly shows steepest expansion trajectory.
Application:
Customer type determines whether barrier specifications prioritize regulatory compliance, optical clarity, or mechanical durability.
- Food Packaging:Modified-atmosphere structures demand oxygen and moisture control without compromising mechanical seal integrity or recyclability streams.
- Electronics Enclosures:Flame retardancy and UV resistance protect outdoor infrastructure and building-integrated photovoltaics where construction durability codes tighten.
- Protective Apparel:Breathable waterproof membranes serve safety equipment producers facing EN 343 and ISO 16603 certification requirements.
- Automotive Components:Underhood thermal management and interior UV protection specifications vary by OEM platform.
- Construction Materials:Weathering resistance and moisture barriers extend facade and roofing system service life.
Food packaging anchors current demand; electronics enclosures are expanding most quickly.
End User:
Supply concentration patterns reveal which customer categories command technical service investment versus transactional supply relationships.
- Packaging Manufacturers:Consolidated European converter groups now specify formulation support, migration testing, and REACH documentation as standard procurement terms.
- Electronic Assemblers:Outsourced manufacturing services in automotive and consumer electronics drive flame retardant and conformal coating specifications.
- Safety Equipment Producers:Certification-dependent procurement for protective apparel creates sticky supplier relationships around test data packages.
- Vehicle Parts Suppliers:Tier-1 and Tier-2 automotive specifications cascade material requirements through subcontracting chains.
- Building Materials Fabricators:Construction sector procurement cycles and project-based demand create volume volatility.
Packaging manufacturers represent the largest addressable base; electronic assemblers show the fastest procurement sophistication gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates additive production capacity while the United States anchors North American barrier film supply, with both markets diverging on regulatory compliance timelines.
United States
Modified-atmosphere packaging converters in the Midwest demand oxygen-barrier coatings for protein shelf-life extension. FDA food additive regulations and EPA chemical substance inventory listings govern antimicrobial and slip agent market access. Dow Inc. anchors plasma-deposited barrier film supply from its Midland, Michigan materials science campus.
Germany
Building-integrated photovoltaics and outdoor infrastructure drive UV stabilizer demand as construction durability codes tighten. EU F-Gas Regulation phase-downs and REACH chemical migration limits compress permissible chemistries for food-contact materials. BASF SE and Evonik Industries AG maintain specialized additive production clusters in Ludwigshafen and Marl chemical parks.
China
Flexible electronics manufacturers in the Yangtze River Delta adopt atomic layer deposition for foldable displays and organic photovoltaics. GB standards and MIIT industrial policy shape domestic barrier coating certification requirements. Zhejiang and Jiangsu provinces host growing sol-gel silica coating capacity serving regional food packaging modernization.
India
FSSAI food-contact material notifications are tightening compliance requirements for imported additives and coatings. Maharashtra and Gujarat packaging converters seek REACH-compliant technical service partnerships as regulatory enforcement intensifies. Mumbai-based distributors now specify migration testing documentation as standard procurement terms.
Japan
Pharmaceutical blister pack manufacturers specify layer-by-layer assembly moisture barriers for humidity-sensitive biologics. METI industrial standards and PMDA pharmaceutical packaging regulations guide barrier technology selection. Osaka and Nagoya industrial corridors concentrate precision deposition equipment supply serving domestic electronics and medical device sectors.
Functional Additives and Barrier Coatings Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated chemical producers commanding premium positions in regulated food-contact applications while regional coating service providers capture mid-scale converter volume. The vendor base organizes into three strategic archetypes: captive integrated producers with backward control over precursor supply, independent formulation specialists with deep regulatory documentation capabilities, and equipment-technology licensors monetizing deposition process IP. Competitive moves concentrate on M&A for regulatory compliance assets and capacity expansion in fluoropolymer-free hydrophobic chemistry.
Among European integrated producers, BASF SE, Evonik Industries AG, and Arkema S.A. exemplify the archetype of captive supply chain control combined with REACH-compliant formulation infrastructure. These Germany and France-based entities occupy positions where regulatory documentation depth and technical service density create defensive moats against commodity import competition.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Arkema S.A. |
| Evonik Industries AG |
| Solvay S.A. |
| Henkel AG & Co. KGaA |
| Clariant AG |
| Songwon Industrial Co. Ltd. |
| AkzoNobel |
| Others |
Supply & Pricing Matrix
Captive integration into semiconductor-grade precursor supply anchors pricing power for European sol-gel silica producers serving modified-atmosphere food packaging. BASF SE's Ludwigshafen complex and Dow Inc.'s Midland campus sustain backward control over UV stabilizer and plasma-deposition input streams, insulating margin structures from silicon alkoxide volatility while compressing third-party converter procurement leverage.
Pricing Analysis
Capacity additions in Zhejiang and Jiangsu provinces are reshaping price floors for sol-gel silica coatings as Chinese domestic supply reduces import dependency. Contract-based long-term offtake dominates premium tiers, with price differentiation hinging on REACH documentation depth and migration testing bundling. Cost compression in standard-grade hydrophobic agents intensifies as Indian converters enter procurement markets. Safety equipment producers show least price sensitivity due to certification-dependent sticky relationships, while mid-scale Italian packaging groups drive hardest bargain pressure.
Supply Chain Analysis
EU F-Gas Regulation phase-downs and India's FSSAI notification tightening are reshaping sourcing patterns for fluoropolymer-free alternatives and REACH-compliant additives. Supply concentrates in Germany, China, and the United States, with silicon alkoxide precursors, hindered amine light stabilizers, and plasma deposition equipment feeding from specialized chemical parks. Single-source vulnerability runs through Ludwigshafen and Marl clusters for European UV stabilizer supply. Distribution runs through technical service partnerships rather than commodity spot markets, with formulation support and regulatory documentation bundled into standard procurement terms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in fluoropolymer-free hydrophobic chemistry and pharmaceutical blister pack barrier migration, as premium-tier shift toward layer-by-layer assembly outpaces commodity additive commoditization.
For Market Incumbents: Hedge silicon alkoxide cost exposure through captive precursor production or long-term offtake agreements with semiconductor-grade chemical suppliers. Deepen technical service infrastructure in India and Southeast Asia before FSSAI enforcement intensifies local compliance requirements. Defensive consolidation around regulatory documentation capabilities creates moats against commodity import competition from Chinese sol-gel capacity additions. For New Entrants and Emerging Players: The premium-to-economy price gap in pharmaceutical blister pack moisture barriers offers white-space entry for atomic layer deposition specialists with roll-to-roll processing compatibility. Target India's Maharashtra and Gujarat packaging corridors with REACH-compliant additive technical service partnerships. FSSAI notification tightening creates first-mover advantage for suppliers establishing local migration testing capabilities before enforcement hardens. For Investors and Strategic Acquirers: Roll-up economics work for independent formulation specialists with deep regulatory documentation capabilities because REACH compliance assets and ECHA substance evaluation expertise concentrate in fragmented European technical service providers. Five-to-ten year viability favors acquisition targets with fluoropolymer-free hydrophobic chemistry portfolios and pharmaceutical barrier coating customer relationships. Watch ECHA substance evaluation timeline extensions for novel organometallic precursors as inflection indicator for competitive launch velocity compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | BASF SE's Ludwigshafen captive alkoxide production insulates margin structures from semiconductor-grade chemical volatility. |
| Fluoropolymer-Free Chemistry Expansion | Arkema S.A. and Solvay S.A. navigate EU F-Gas Regulation phase-downs through hydrophobic nanocomposite development. |
| Technical Service Partnership Consolidation | Mid-sized European converters now specify formulation support and REACH documentation as standard contract terms. |
| Atomic Layer Deposition Scale-Up | Pharmaceutical blister manufacturers adopt angstrom-precision moisture barriers as aluminum cold-form foil faces recyclability pressure. |
| India Market Technical Service Buildout | Mumbai-based distributors specify migration testing documentation as FSSAI food-contact material notifications tighten enforcement. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at German chemical parks, procurement leads at Italian and Spanish food packaging converters, technical R&D directors at barrier coating developers, and distribution channel partners across Benelux. Secondary validation drew from customs and trade data, Cefic industry reports, SEC 10-K filings, and ECHA substance evaluation databases. Bottom-up capacity and demand modeling triangulated against top-down market sizing across product chemistry, deposition technology, and end-use application dimensions.
Segment-weighting approaches distributed value and volume across UV stabilizers, flame retardants, hydrophobic agents, antimicrobial additives, and slip agents by chemistry type, while sol-gel, layer-by-layer assembly, plasma deposition, chemical vapor deposition, and electrospinning technologies were modeled separately. End-use splits across food packaging, electronics enclosures, protective apparel, automotive components, and construction materials informed regional allocation. CAGRs derived from installed capacity expansion trajectories, regulatory compliance timeline impacts, and substitution elasticity between barrier coating technologies and legacy multi-layer coextrusion. Price realization trends incorporated raw material pass-through mechanics and technical service bundling intensity.
Caveats apply where ECHA substance evaluation timeline extensions, EU F-Gas Regulation acceleration, or FSSAI enforcement intensity shifts could materially shift the outlook. Forecasts reflect assumptions around regulatory trajectory continuity, precursor supply stability, and converter capital expenditure cycles for deposition equipment adoption. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Materials
Flexible Thin Film Market
Functional Materials
Thin Film Materials Market
Functional Materials
Functional Composites Market
Functional Materials
Functionalized Nanocomposites Market
Functional Materials
UHMWPE for Li-Battery Market
Functional Materials
Thin-Film Encapsulation Market
Functional Materials
Smart Card Materials Market
Functional Materials
Functional Acids Market
Functional Materials
Global Thin Film Coatings Market
Functional Materials
Adaptive Camouflage Materials Market
Functional Materials
Korea Personal Care Encapsulation Materials Market
Functional Materials
Global Smart Material Market
Functional Materials
Global Piezoelectric Smart Materials Market
Functional Materials
Ferroelectric Materials Market
Functional Materials
Asia-Pacific Lithium Foil Market
Functional Materials
Rapid Self-Healing Gel Market