
 Polyester Coatings Market | 2026-2036
Polyester Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Polyester Coatings Market Intelligence
The shift towards asset-light production models, where brand owners outsource manufacturing to specialized toll coaters, is reconfiguring competitive access to advanced formulation capabilities. This allows smaller firms to compete on innovation without heavy capital expenditure. In this environment, Akzo Nobel N.V. leverages its vast production scale and distribution network. Meanwhile, PPG Industries, Inc. specializes in high-performance automotive and industrial applications, and BASF SE differentiates through its deep expertise in polymer chemistry and sustainable solutions.
Polyester coatings are thermosetting polymers derived from the reaction between a polyol and a dicarboxylic acid. Their chemical structure provides excellent hardness, flexibility, and resistance to impact, chemicals, and UV degradation. The primary purpose is to deliver a durable, protective, and aesthetically pleasing finish on a variety of substrates. Powder coatings technology continues to gain market share over liquid coatings due to its lower environmental impact with minimal VOC emissions. While architectural surfaces remain the largest volume application, the consumer electronics segment requires advanced formulations for thin-film and high-adhesion properties.
Regulatory frameworks are a significant force shaping product development. The EU's REACH and RoHS directives restrict the use of hazardous substances, compelling manufacturers to reformulate products for market access in Europe. Similarly, regulations from the US Environmental Protection Agency (EPA) on volatile organic compound (VOC) emissions drive the adoption of waterborne and powder coating technologies. Balancing performance requirements, cost pressures, and evolving global environmental standards remains the central challenge for all market participants.
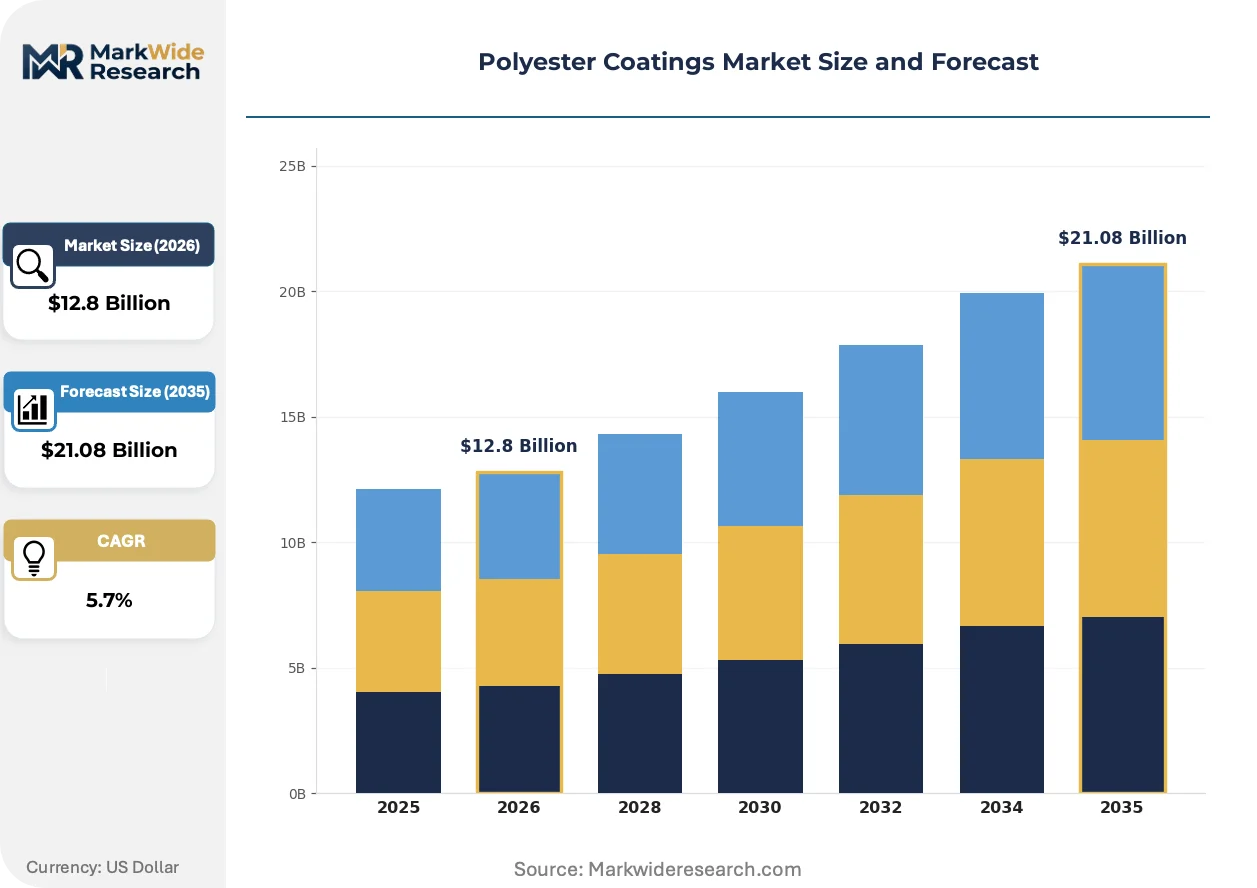
Market Dynamics
The central dynamic in the polyester coatings market is the pressure to meet stringent environmental regulations, such as the EU Green Deal, while simultaneously delivering the high-performance characteristics demanded by advanced manufacturing sectors like consumer electronics and automotive.
Growth Catalysts
- Low-VOC Formulations:Mandates from bodies like the US EPA are compelling a switch to environmentally compliant technologies, directly benefiting waterborne and powder polyester coatings which have minimal to zero volatile organic compound emissions.
- Consumer Electronics Miniaturization:Demand from manufacturing clusters in China for durable, thin-film coatings is rising with the trend of smaller, more complex electronic devices that require superior protection and aesthetics.
- Powder Coating Adoption:The architectural sector continues to substitute traditional liquid paints with polyester powder coatings, driven by the technology's superior durability, one-coat application efficiency, and reduced environmental footprint.
Market Restraints
- Raw Material Volatility:The prices of essential precursors like dicarboxylic acids and polyols are tied to volatile petrochemical feedstock markets, creating margin pressure and cost uncertainty for coating manufacturers.
- Technical Performance Gaps:Achieving ultra-thin films below 20 microns with consistent finishes remains a challenge for powder coating technology, limiting its use in specific high-precision electronic and optical applications.
- Threat of Substitution:In high-specification applications, such as coastal architectural facades or premium automotive clearcoats, polyester coatings face competition from fluoropolymers and advanced acrylics that offer superior long-term weatherability.
Strategic Opportunities
- Bio-Based Polyester Resins:The development of polyesters from renewable feedstocks presents a significant opportunity to meet corporate sustainability mandates and appeal to environmentally conscious customers in the furniture and packaging sectors.
- Coatings for Flexible Substrates:Expanding applications in flexible electronics, solar panels, and medical wearables create a new market for polyester coatings engineered for high elasticity, adhesion, and durability on non-rigid surfaces.
- Infrastructure Expansion in ASEAN:Major public and private construction projects across Southeast Asian nations offer an underpenetrated market for protective polyester coatings used on building materials, bridges, and transportation equipment.
Industry Challenges
- Regulatory Divergence:Formulators face complexity in developing products that simultaneously comply with differing chemical restrictions, such as the EU's REACH and China's GB standards, often requiring region-specific product lines.
- Application Skill Gaps:A shortage of technicians trained in advanced powder coating application, color matching, and quality control can lead to inconsistent finish quality and limit the adoption of more complex coating systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyester Coatings Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aliphatic Polyester, Aromatic Polyester, Unsaturated Polyester, Hybrid Polyester Application: Architectural Surfaces, Automotive Parts, Consumer Electronics, Appliances Technology: Powder Coatings, Liquid Coatings, UV Curable, Waterborne End User: OEM Manufacturers, Fabricators, Industrial Equipment Makers, Furniture Producers |
| Companies Covered | BASF SE, PPG Industries, Inc., Akzo Nobel N.V., The Sherwin-Williams Company, Axalta Coating Systems, Jotun A/S, Nippon Paint Holdings Co., Ltd., RPM International Inc., Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyester Coatings Market Strategic Shifts & Innovations
Product development is increasingly defined by the pursuit of circularity and the digitalization of formulation. These forces are compelling manufacturers to rethink material inputs and shorten innovation cycles to meet new sustainability and performance benchmarks set by end-users.
Digital twin and simulation software provides a platform for predictive formulation and performance testing. R&D teams in the automotive and aerospace industries are early adopters, using these tools to test virtual prototypes of coatings under simulated environmental stressors. This technology is virtualizing the traditional trial-and-error laboratory process, significantly reducing material waste, development costs, and time-to-market for new high-performance polyester coatings.
Regulatory frameworks are a primary catalyst for technological change. The US Environmental Protection Agency's (EPA) stringent limits on volatile organic compounds (VOCs) under the Clean Air Act directly discourage the use of traditional solvent-borne systems. This federal pressure is most acute in the industrial finishing and architectural coatings segments, forcing a market-wide pivot toward powder and waterborne polyester technologies to ensure compliance.
Asset-light production models are altering supply chain relationships and access to technology. Brand owners in the appliance and electronics industries increasingly outsource manufacturing and coating application to specialized toll coaters, disrupting direct-sales channels. This shift is most pronounced in Asia's manufacturing hubs, allowing smaller brands to leverage advanced coating capabilities without significant capital investment in plant and equipment.
Polyester Coatings Market Segmentation
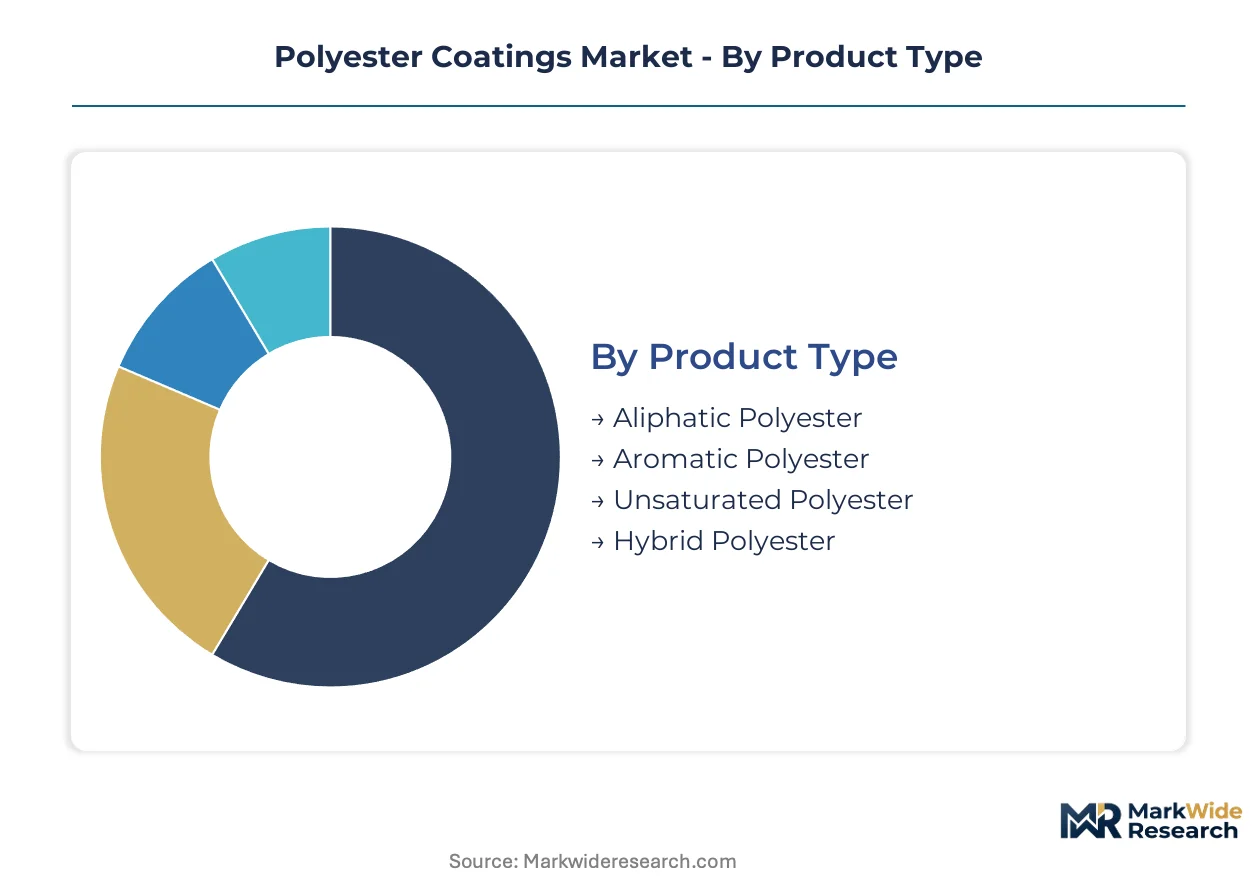
Segmentation provides critical insight into the diverse demands and technological imperatives shaping the polyester coatings market. Understanding these distinct segments helps manufacturers tailor formulations, address specific regulatory challenges, and optimize distribution strategies for targeted end-use sectors.
Product Type:
The product type segmentation reveals a spectrum from established formulations to advanced, specialized chemistries.
- Aliphatic Polyester:These resins offer excellent UV and weather resistance, making them ideal for outdoor architectural coatings and durable exterior applications. Demand concentrates in European facades due to stringent weatherability standards from bodies like the EU Green Deal.
- Unsaturated Polyester:These thermosetting resins cure rapidly, forming hard, rigid films often reinforced with glass fibers for structural applications and composites. Demand for these materials is high in infrastructure projects across Southeast Asia, particularly for pipe and tank linings.
- Aromatic Polyester:These offer high hardness and chemical resistance, frequently used in industrial protective coatings and coil applications.
- Hybrid Polyester:Combining properties of different resin types, these offer balanced performance across diverse applications requiring specific property blends.
Aliphatic Polyester retains volume leadership; Hybrid Polyester holds the steepest expansion curve.
Application:
Applications drive specific performance requirements, dictating formulation complexity and volume demand.
- Architectural Surfaces:This segment represents the largest volume, demanding coatings with superior durability, aesthetic retention, and weather resistance for buildings. Adoption of polyester powder coatings in China's urban development projects drives significant volumes.
- Consumer Electronics:Requires advanced thin-film coatings with high adhesion, scratch resistance, and dielectric properties for miniaturized devices. Manufacturing clusters in South Korea and China concentrate demand for these specialized formulations.
- Automotive Parts:Polyester coatings provide excellent chip resistance, gloss retention, and aesthetic appeal for various vehicle components.
- Appliances:These coatings offer durable, chemical-resistant finishes for household and commercial appliances, ensuring long-term aesthetic integrity.
Consumer electronics applications are expanding most quickly, while architectural surfaces maintain substantial market presence.
Technology:
Technology choices are increasingly shaped by environmental regulations and performance trade-offs.
- Powder Coatings:These solvent-free systems offer superior durability, excellent finish, and minimal VOC emissions, making them a preferred choice for industrial and architectural applications. US EPA regulations on VOCs strongly favor their adoption in industrial finishing operations.
- Waterborne:Utilizing water as the primary solvent, these coatings significantly reduce volatile organic compounds and hazardous air pollutants, aligning with sustainability goals. European manufacturers increasingly adopt waterborne systems to comply with EU Green Deal objectives and REACH directives.
- Liquid Coatings:Traditional solvent-borne systems still provide high-performance finishes for specific industrial uses where rapid drying or specialized aesthetics are required.
- UV Curable:These coatings offer rapid curing times and high chemical resistance, suitable for high-speed production lines in industries like furniture and packaging.
Powder coatings are gaining share fastest, driven by environmental compliance across multiple geographies.
End User:
End-user segments exhibit distinct procurement patterns and demand for specialized coating properties.
- OEM Manufacturers:These companies integrate coatings into their primary product assembly, demanding consistent quality, reliable supply, and adherence to specific performance standards. Automotive OEMs in Germany require specific polyester formulations for exterior and interior components.
- Industrial Equipment Makers:Coatings protect heavy machinery and specialized tools from harsh operating environments, chemical exposure, and abrasion. Manufacturers in Japan seek durable coatings for agricultural and construction equipment to extend product lifespan.
- Fabricators:These users apply coatings to components or structures, requiring versatile and easy-to-apply formulations that meet various client specifications.
- Furniture Producers:Polyester coatings provide aesthetic appeal, scratch resistance, and chemical protection for various furniture types, enhancing durability and finish.
OEM manufacturers and industrial equipment makers command significant volumes, influencing product development cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal and similar environmental policies drive regional shifts in polyester coatings demand. These frameworks compel manufacturers to prioritize low-VOC formulations and sustainable solutions across diverse applications. This global regulatory push shapes both product innovation and market access.
China
China's robust manufacturing sector drives demand for polyester coatings in consumer electronics and architectural projects. China's GB standards enforce strict environmental compliance, pushing for powder coating adoption. Manufacturing hubs like the Yangtze River Delta concentrate specialized thin-film coating production for global brands. Urban development in major cities also consumes vast volumes of durable powder coatings.
United States
Stringent US EPA regulations on VOC emissions accelerate the shift towards waterborne and powder polyester coatings in industrial finishing. The Clean Air Act mandates continuous product reformulation for environmental compliance. Automotive manufacturing centers in the Midwest demand high-performance coatings for vehicle components. Construction projects across major US metropolitan areas also require durable finishes.
Germany
European manufacturers, particularly in Germany, increasingly adopt waterborne systems for automotive and architectural applications. The EU Green Deal and REACH directives compel continuous innovation in sustainable polyester formulations. Automotive OEMs in Bavaria demand specific high-performance coatings for exterior and interior components. Industrial equipment makers across the Ruhr area also seek durable protective finishes.
India
Infrastructure expansion and rapid urbanization fuel demand for polyester coatings in India's construction sector. BIS standards ensure quality and safety for building materials, influencing coating specifications. Major industrial zones in Maharashtra utilize protective coatings for machinery and structural components. Emerging consumer electronics manufacturing in Bangalore also requires specialized thin-film applications.
Polyester Coatings Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, combining large, diversified chemical conglomerates with specialized coating manufacturers. Global players leverage extensive R&D and distribution networks to serve multiple end-use sectors, including automotive and consumer electronics. Smaller, agile firms often focus on niche applications or provide toll coating services to brand owners, enabling innovation without heavy capital expenditure. Competitive moves include strategic partnerships for technology co-development and targeted capacity expansion in emerging markets.
Global chemical giants like BASF SE exemplify deep expertise in polymer chemistry, anchoring sustainable solutions within the polyester coatings market. PPG Industries, Inc. represents a significant force in high-performance automotive and industrial applications, delivering specialized formulations. Akzo Nobel N.V. occupies a position of vast production scale and extensive distribution, serving a broad range of architectural and industrial clients. These entities leverage their R&D capabilities and market reach to influence product development and compliance standards.
| Leading Market Players |
|---|
| BASF SE |
| PPG Industries, Inc. |
| Akzo Nobel N.V. |
| The Sherwin-Williams Company |
| Axalta Coating Systems |
| Jotun A/S |
| Nippon Paint Holdings Co., Ltd. |
| RPM International Inc. |
| Arkema |
| Others |
Cost & Logistics Intelligence
Capacity utilization in China's manufacturing clusters directly influences pricing power for specialized thin-film coatings. This dynamic affects both supplier investment and buyer negotiations within the polyester coatings market.
Pricing Analysis
Certification for specific performance standards, such as those required by automotive OEMs in Germany, creates the primary spread in polyester coatings pricing. Project-based pricing dominates for large architectural surface contracts, while per-unit transactional models prevail in consumer electronics. Price differentiation stems from customization level and brand premium. Cost compression in the architectural segment is intensifying due to competition from regional suppliers, making it highly price-sensitive compared to high-performance automotive applications.
Supply Chain Analysis
Volatile petrochemical feedstock markets, particularly for dicarboxylic acids and polyols, anchor the upstream supply chain for polyester coatings. Supply concentration for these precursors exists primarily in China and the Middle East, leading to commodity price volatility as a structural risk. Key manufacturing hubs for finished coatings are in China, Germany, and the United States. Distribution runs through a hybrid model, combining direct sales to large OEMs with specialized distributors serving fabricators and smaller end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polyester coatings market is undergoing a platform-economics inflection, driven by the emergence of digital twin and simulation software that reshapes product development cycles and material testing.
For Market Incumbents:Build a regulatory compliance moat through continuous investment in low-VOC and sustainable formulations. Akzo Nobel N.V. can leverage its vast distribution network to push waterborne and powder coating technologies, countering the threat of substitution from advanced acrylics. Strategic partnerships for bio-based resin development offer a lever to meet corporate sustainability mandates, especially for European OEMs.
For New Entrants and Emerging Players:Pursue niche applications requiring specialized thin-film properties for flexible substrates in emerging electronics. The underpenetrated infrastructure expansion in ASEAN nations offers a white-space target for protective polyester coatings. A go-to-market angle focusing on rapid prototyping and customized small-batch formulations can attract consumer electronics manufacturers in new Asian hubs.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among specialized toll coaters serving asset-light brand owners in the appliance and electronics industries. Long-term viability hinges on companies demonstrating expertise in advanced polymer chemistry and sustainable solutions. Acquisition targets should prioritize firms with strong R&D capabilities in bio-based resins or advanced thin-film technology. The signal to watch is the increasing adoption rate of circular economy principles within end-user industries.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | This initiative enhances market access in Europe due to stringent EU Green Deal objectives. |
| Digital Twin Integration | This technology reduces development costs and accelerates time-to-market for complex formulations. |
| Capacity Expansion in ASEAN | This move capitalizes on infrastructure growth and rising demand for protective coatings in Southeast Asia. |
| Strategic Partnerships for Bio-Resins | These collaborations secure access to renewable feedstocks, aligning with corporate sustainability goals. |
| Product Launch for Flexible Substrates | This targets new market opportunities in flexible electronics and medical wearables applications. |
Research Approach
Desk research of regulatory filings, trade publications, and corporate financial reports preceded structured interviews with R&D directors, procurement leads at OEMs, and specialized toll coaters. This approach combined primary insights from industry stakeholders with secondary validation from market data. Bottom-up analysis of production capacities and top-down validation through end-user demand forecasts ensured robust data triangulation.
Assumptions regarding stable petrochemical feedstock prices were held fixed, while varying regulatory compliance timelines across regions. The analytical framework modeled segmentation dimensions including product type, application, technology, and end-user, alongside regional adoption patterns. Compound annual growth rates were derived from historical data extrapolation and projected demand shifts over the projection horizon. Increased adoption of powder coating technology served as a key forecast input.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth or energy prices would shift the trajectory. Forecasts reflect assumptions about technology adoption and regulatory enforcement. Cross-checking against national environmental agency reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Polymer Modified Cementitious Coatings Market
Coatings
Italy Protective Coatings Market
Coatings
Stealth Coating Material Market
Coatings
France Protective Coatings Market
Coatings
Global High-Performance Anti-Corrosion Coatings Market
Coatings
Global Fire-Resistant Coating Market
Coatings
Yacht Coatings Market
Coatings
2K Protective Coatings Market
Coatings
Coating Binders Market
Coatings
Coatings Raw Materials Market
Coatings
Marking Coatings Market
Coatings
Fluid Bed and Coating System Market
Coatings
Industrial Coatings Market
Coatings
Thailand Architectural Coatings Market
Coatings
Global Powder Coating Market
Coatings
Color-Shifting Coating Market