
 Brazil Automotive OEM Coatings Market | 2026-2036
Brazil Automotive OEM Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Automotive OEM Coatings Market Insights
Single-source supply agreements for clearcoat resins is decoupling from long-standing petrochemical partnerships across southeastern Brazil. PPG Industries leverages captive solventborne technology to sustain volume leadership at ABC Paulista assembly plants. Akzo Nobel N.V. anchors its position through waterborne R&D partnerships with domestic auto manufacturers. Renner Herrmann SA dominates regional distribution networks for primer and sealer grades.
Brazil automotive OEM coatings encompass solventborne, waterborne, powder, and UV-curable formulations applied to passenger and commercial vehicles during original manufacturing, typically requiring 80-140 micrometre dry-film thickness for corrosion protection and aesthetic finish. These systems must withstand tropical UV exposure, salt spray, and stone-chip damage across Brazil's varied climate zones. Waterborne technology is capturing share fastest as OEMs retool spray booths to meet environmental compliance, while solventborne basecoat retains margin pools in luxury and commercial vehicle lines. Clearcoat demand concentrates at high-volume São Paulo and Minas Gerais assembly corridors where throughput justifies capital-intensive automated application lines.
ANVISA oversees chemical substance registration affecting coating raw material sourcing, while CONAMA resolutions under IBAMA jurisdiction mandate volatile organic compound limits that reshape formulation requirements. Brazil's INMETRO certification for automotive components creates additional compliance thresholds for coating durability and adhesion performance. Stakeholders must monitor pending updates to CONAMA's automotive sector emission protocols and assess waterborne conversion capex against solventborne operating cost advantages.
Market Dynamics
Waterborne basecoat conversion is compressing solventborne margins across southeastern Brazil as OEMs retool spray booths to meet CONAMA emission limits, while resin supply consolidation forces formulators to rebuild procurement relationships.
Growth Catalysts
- CONAMA Protocol 18/2015:Volatile organic compound limits at assembly plants are mandating waterborne system adoption, creating captive demand for compliant coating suppliers.
- São Paulo State Production Clusters:Light commercial vehicle assembly concentration in the ABC Paulista corridor generates coating volume density that justifies automated clearcoat line investment.
- UV-Curable Sealer Technology:Energy-cured primer systems are reducing bake cycle times at high-throughput plants, lowering energy intensity per vehicle unit.
Market Restraints
- Petrochemical Feedstock Volatility:Acrylic and polyurethane resin precursors track naphtha pricing, compressing formulation margins during crude oil swings.
- Import Dependency for Specialty Additives:Photoinitiators and rheology modifiers concentrate with German and Japanese suppliers, exposing formulators to currency and logistics risk.
- Solventborne Basecoat Technical Floor:Metallic effect durability requirements in luxury vehicle segments prevent full waterborne conversion, fragmenting R&D resource allocation.
Strategic Opportunities
- Minas Gerais Assembly Corridor:Emerging OEM capacity in Betim and Contagem regions lacks established coating supply infrastructure, opening distribution network expansion.
- INMETRO Durability Certification:Extended warranty programs tied to certified coating performance create premium pricing tiers for validated systems.
- Powder Clearcoat Convergence:Powder topcoat technology adapted from appliance and architectural markets is penetrating commercial vehicle segments seeking zero-VOC solutions.
Industry Challenges
- Spray Booth Reconfiguration Complexity:Waterborne conversion requires humidity control infrastructure and flash-off zone expansion, extending plant downtime during retrofit.
- Cross-Coat Compatibility Validation:Layer adhesion between legacy solventborne primers and new waterborne basecoats demands extensive testing protocols, slowing formulation rollout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Automotive OEM Coatings Market |
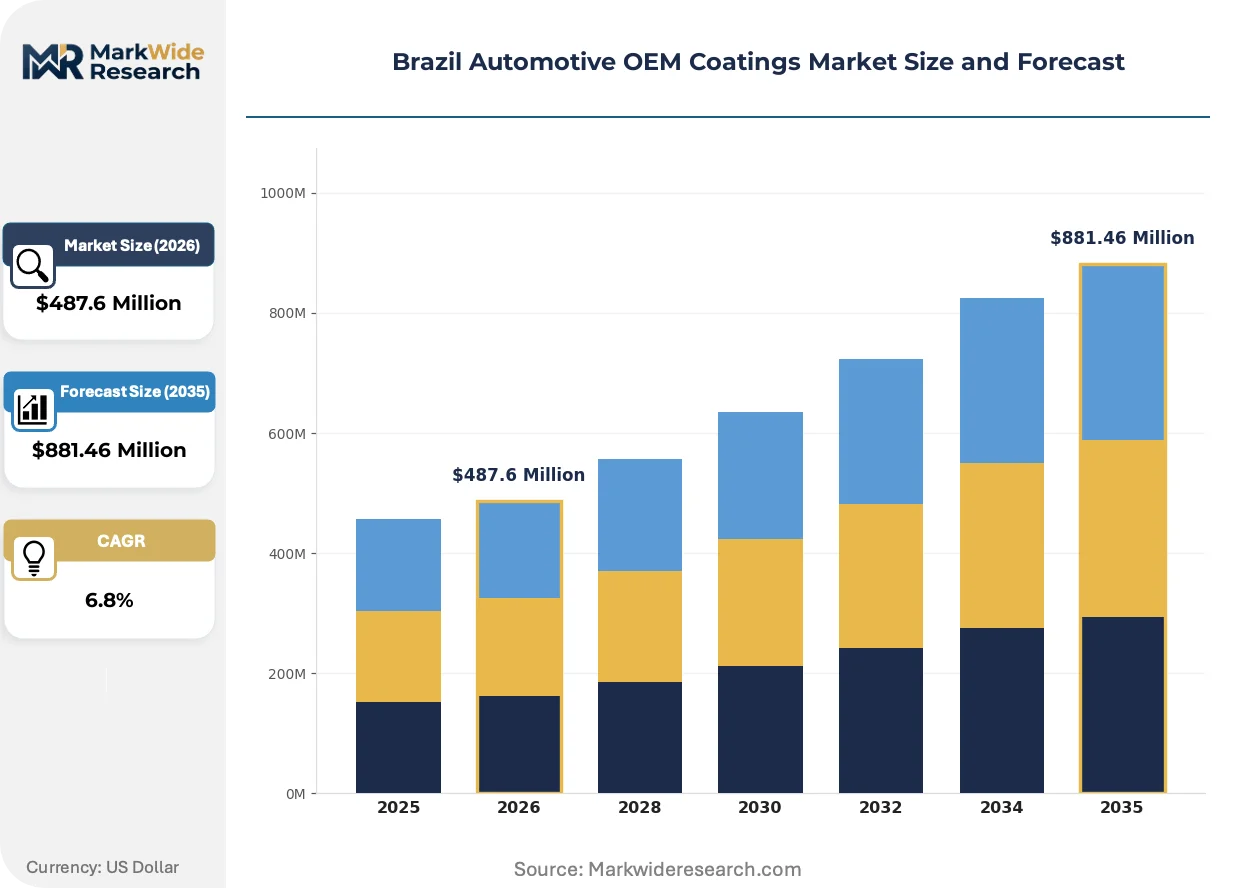
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basecoat, Clearcoat, Primer, Sealer Technology: Waterborne, Solventborne, UV-Curable, Powder Coating Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Luxury Vehicles End User: OEMs, Aftermarket Providers, Distributors, Auto Manufacturers |
| Companies Covered | PPG Industries, Inc., Nippon Paint Holdings Co. Ltd, Akzo Nobel N.V., Renner Herrmann SA, The Sherwin-Williams Company, Axalta Coating Systems, RPM International Inc., Mankiewicz Gebr. & Co., BASF SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Automotive OEM Coatings Market Trends and Innovations
Formulation chemistry and application hardware are diverging from legacy solventborne architectures as environmental compliance hardens and OEMs pursue throughput gains through cure-cycle compression.
Self-healing clearcoat chemistry incorporating microencapsulated polymer repair agents is expanding into premium passenger vehicle segments. Mercedes-Benz and BMW assembly operations in São Paulo state are piloting these systems for stone-chip recovery. The technology is expanding into warranty-reduction value propositions that offset raw material cost premiums.
CONAMA Resolution 491/2018 tightening volatile organic compound thresholds for automotive finishing operations is forcing solventborne phase-out timelines. Formulators must resubmit product registrations with ANVISA under revised substance classifications. Waterborne basecoat and powder primer categories absorb the regulatory displacement, with commercial vehicle OEMs facing compressed compliance deadlines versus passenger car producers.
Fleet procurement centralization at rental and logistics operators is consolidating coating specification authority away from individual assembly plants. Large fleet buyers in Paraná and Rio Grande do Sul are mandating unified color-matching standards and durability warranties across multi-brand vehicle acquisitions. This purchasing consolidation favors coating suppliers with national technical service networks over regional specialists.
Brazil Automotive OEM Coatings Market Segmentation
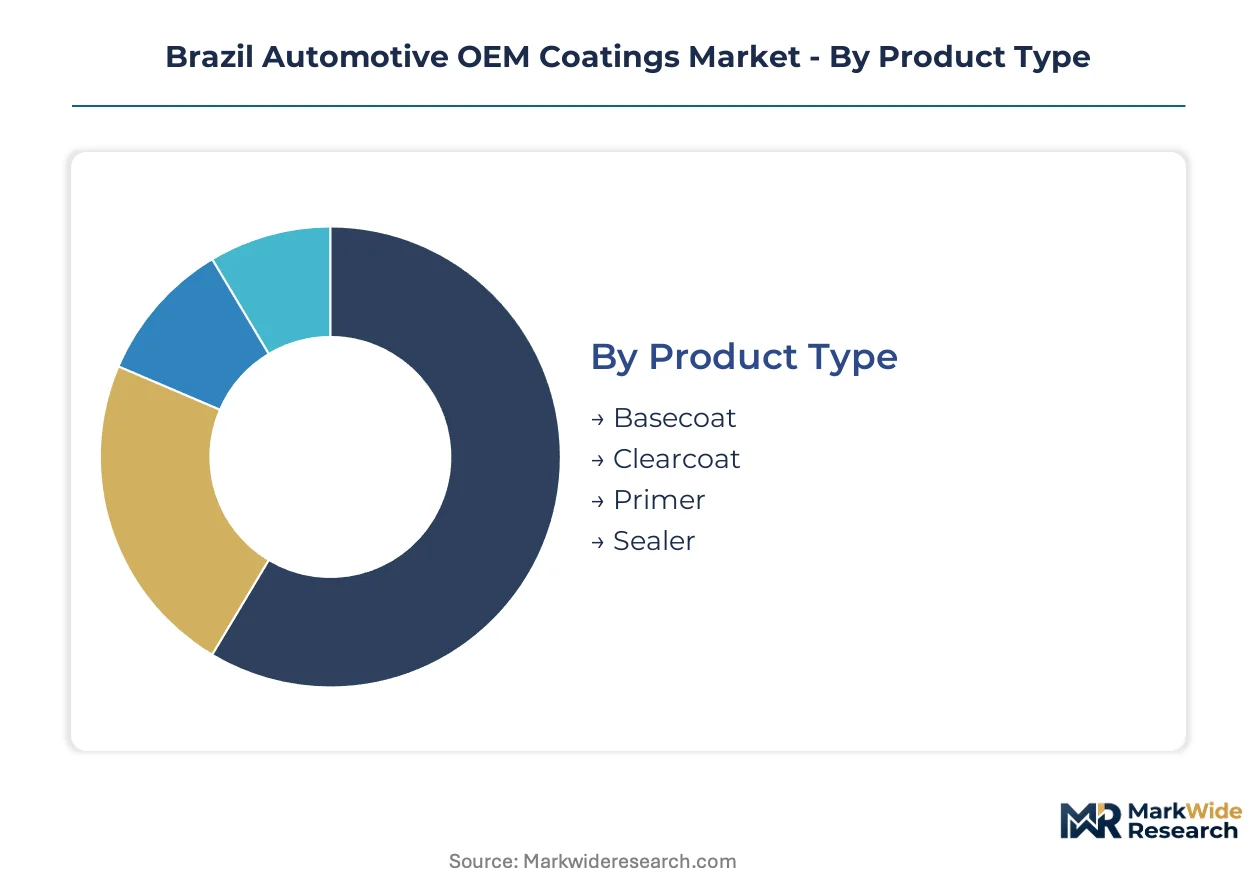
Segmentation reveals how coating procurement priorities diverge across vehicle categories and regulatory exposure zones. Technology choices and application requirements reshape supplier margins differently in São Paulo assembly corridors versus emerging Minas Gerais capacity.
Product Type:
Volume concentrates in protective layers while premium pools in aesthetic finishes across Brazilian assembly plants.
- Basecoat:Pigmented intermediate layers delivering color and metallic effects, typically 15-25 micrometres dry-film thickness. Demand clusters at ABC Paulista luxury vehicle plants where CONAMA compliance deadlines are accelerating waterborne conversion capex.
- Clearcoat:Transparent topcoat systems providing UV protection and gloss retention against tropical exposure. São Paulo and Minas Gerais high-throughput corridors justify automated application line investment for this highest-margin product tier.
- Primer:Corrosion-resistant foundation layers applied directly to pretreated metal substrates.
- Sealer:Interface coatings ensuring adhesion between primer and basecoat layers while blocking substrate imperfections.
Today's leader: Clearcoat. Tomorrow's challenger: Waterborne basecoat gaining share fastest as emission limits harden.
Technology:
Environmental compliance is fragmenting the supplier base between legacy solventborne incumbents and waterborne specialists.
- Waterborne:Acrylic and polyurethane dispersions with VOC content below CONAMA thresholds, requiring humidity-controlled spray booths. Betim and Contagem emerging assembly corridors are specifying these systems from greenfield plant design.
- Solventborne:Traditional alkyd and acrylic solutions retaining metallic effect durability advantages. Luxury vehicle lines in São Paulo state maintain this technology for color-matching precision despite regulatory pressure.
- UV-Curable:Energy-cured systems reducing bake cycle energy intensity at high-volume commercial vehicle plants.
- Powder Coating:Zero-VOC thermoset formulations penetrating commercial vehicle segments from appliance and architectural technology transfer.
Waterborne systems are expanding most quickly. Solventborne retains margin pools in effect-critical applications.
Application:
Vehicle category determines coating specification authority and warranty term negotiation leverage.
- Passenger Vehicles:High-volume production lines demanding rapid cure cycles and color consistency across multi-shift operations. Fleet procurement centralization in Paraná and Rio Grande do Sul is consolidating specification authority away from individual plants.
- Commercial Vehicles:Heavy-duty formulations prioritizing stone-chip resistance and extended durability warranties. UV-curable sealer adoption is compressing energy costs per unit at these throughput-focused facilities.
- Electric Vehicles:Specialized dielectric coatings for battery enclosure protection and thermal management substrates.
- Luxury Vehicles:Premium effect coatings with self-healing clearcoat pilot programs at Mercedes-Benz and BMW São Paulo operations.
Passenger vehicles dominate volume. Commercial vehicles offer the steepest expansion trajectory for powder and UV technologies.
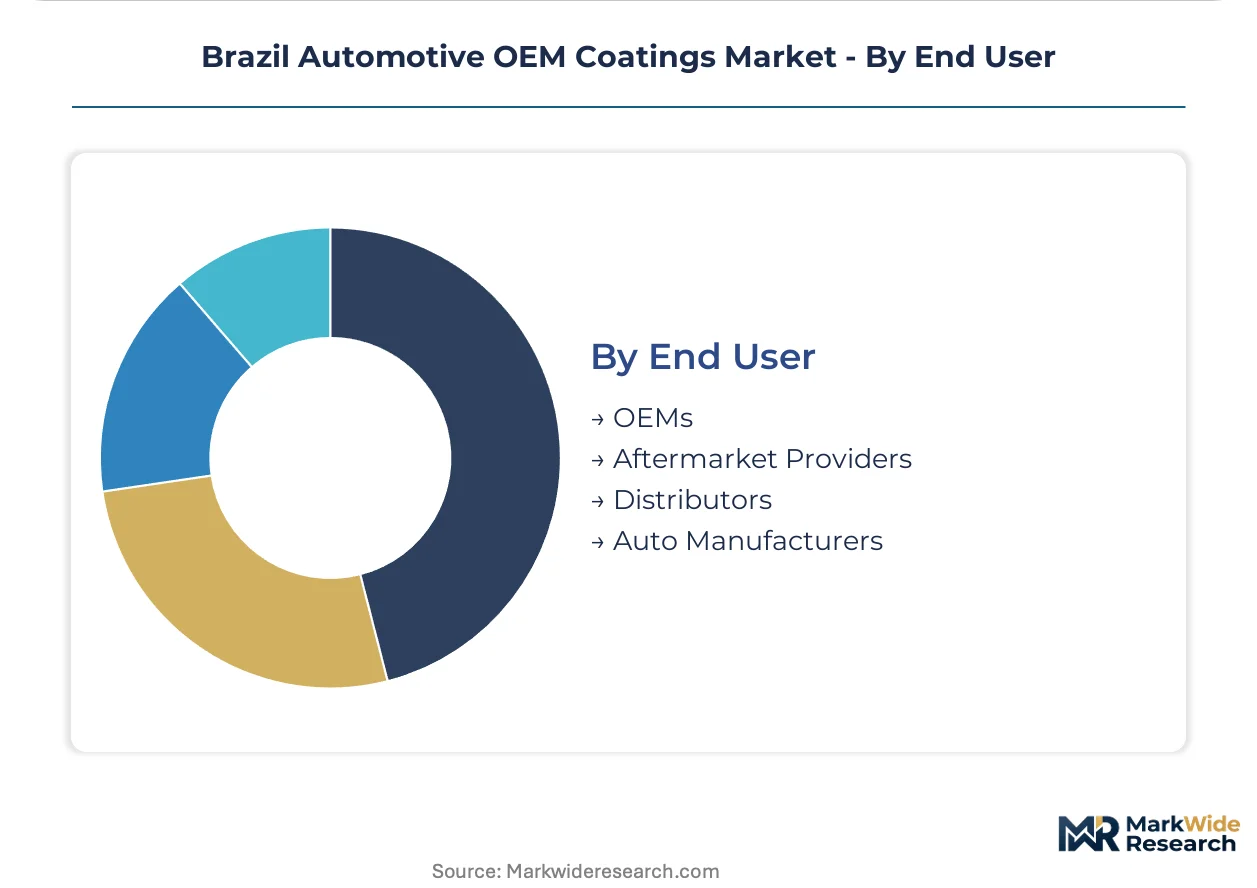
End User:
Procurement concentration varies between captive OEM supply agreements and distributed aftermarket channels.
- OEMs:Direct coating specification at assembly plants with long-term supply contracts and technical service integration. INMETRO certification requirements create compliance barriers for non-validated suppliers.
- Auto Manufacturers:Parent company procurement centralization spanning multiple assembly facilities and brand portfolios. National technical service networks are winning against regional specialists under this purchasing consolidation.
- Aftermarket Providers:Refinish and repair coating distribution serving collision repair and vehicle refurbishment channels.
- Distributors:Regional logistics networks for primer and sealer grades where Renner Herrmann SA maintains infrastructure dominance.
OEMs control premium specification. Auto manufacturers are consolidating procurement leverage fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The ABC Paulista corridor anchors coating consumption through light commercial vehicle assembly density and automated clearcoat line investment justified by production volume.
São Paulo
Light commercial vehicle production clusters at ABC Paulista assembly plants drive coating volume density that supports capital-intensive automated application infrastructure. ANVISA chemical substance registration requirements shape raw material sourcing decisions for formulators serving this corridor. Mercedes-Benz and BMW operations in the state pilot self-healing clearcoat systems for stone-chip recovery.
Minas Gerais
Betim and Contagem emerging assembly corridors specify waterborne systems from greenfield plant design, bypassing solventborne retrofit costs. CONAMA Resolution 491/2018 VOC thresholds accelerate compliance timelines for commercial vehicle producers relative to passenger car manufacturers. Regional distribution networks for primer and sealer grades remain underdeveloped relative to southeastern supply infrastructure.
Paraná
Fleet procurement centralization among rental and logistics operators consolidates coating specification authority away from individual assembly facilities. Large fleet buyers mandate unified color-matching standards across multi-brand vehicle acquisitions. National technical service networks capture specification leverage against regional specialists under this purchasing consolidation.
Rio Grande do Sul
Commercial vehicle OEMs prioritize heavy-duty formulations with extended durability warranties and stone-chip resistance specifications. UV-curable sealer adoption compresses energy costs per unit at throughput-focused facilities. Import dependency for photoinitiators and rheology modifiers exposes formulators to currency and logistics risk.
Brazil Automotive OEM Coatings Market Competitive Landscape
Global majors compete with regional champions across technology platforms and distribution reach, producing a tiered structure where captive solventborne expertise defends volume positions against waterborne conversion specialists. The market fragments between legacy petrochemical partnerships and rebuilt procurement relationships around resin supply consolidation. Two strategic archetypes dominate: integrated formulators with captive technology platforms and regional distributors with logistics infrastructure dominance. Competitive moves concentrate on spray booth reconfiguration partnerships and waterborne R&D alliances with domestic OEMs.
Among the integrated formulators, PPG Industries, Inc. occupies a position exemplifying captive solventborne technology leverage at high-volume assembly plants. Akzo Nobel N.V. anchors the waterborne conversion specialist archetype through R&D partnerships with domestic auto manufacturers. Renner Herrmann SA represents the regional distribution infrastructure model, concentrating logistics networks for primer and sealer grades across southeastern Brazil.
| Leading Market Players |
|---|
| PPG Industries, Inc. |
| Nippon Paint Holdings Co. Ltd |
| Akzo Nobel N.V. |
| Renner Herrmann SA |
| The Sherwin-Williams Company |
| Axalta Coating Systems |
| RPM International Inc. |
| Mankiewicz Gebr. & Co. |
| BASF SE |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap distributors across southeastern Brazil anchor procurement relationships that discipline pricing through long-standing credit terms and volume commitments, while their limited balance-sheet capacity constrains upstream prepayment demands from resin suppliers. This ownership pattern concentrates margin negotiation leverage at the distribution tier, forcing integrated formulators to absorb petrochemical volatility through captive supply arrangements or sacrifice share in ABC Paulista assembly corridors.
Pricing Analysis
Acrylic and polyurethane resin precursor costs pass through to coating formulators with a three-to-six-month lag, compressing margins during crude oil swings before contract renegotiation windows open. Pricing stratifies across INMETRO-certified premium tiers, volume-scaled standard contracts, and economy grades for commercial vehicle lines. Cost compression in waterborne basecoat tiers is intensifying because humidity-control infrastructure capex demands upfront investment recovery. Fleet procurement centralization in Paraná exhibits highest price sensitivity, while luxury OEMs in São Paulo state prioritize color-matching precision over unit cost.
Supply Chain Analysis
Reverse-logistics flows for solventborne waste recovery and expired coating returns concentrate at Renner Herrmann SA distribution hubs, creating secondary material streams that subsidize primary product margins. German and Japanese suppliers anchor photoinitiator and rheology modifier availability, while domestic petrochemical complexes in São Paulo and Rio de Janeiro feed acrylic resin production. Single-source vulnerability concentrates with specialty additive suppliers, exposing formulators to currency and logistics risk. Distribution runs through regional primer and sealer networks that Renner Herrmann SA dominates, with national technical service capabilities capturing specification authority from fragmented specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's CONAMA emission thresholds create a regulatory arbitrage window against Argentine and Mexican assembly corridors with looser VOC limits, positioning compliant Brazilian coating capacity for export substitution as regional OEMs face harmonization pressure.
For Market Incumbents: Anticipate waterborne conversion capex demands by securing humidity-control infrastructure partnerships with ABC Paulista plant engineering firms before retrofit queues lengthen. Anchor solventborne margin pools through exclusive effect-coating supply agreements with luxury OEMs, while building captive resin supply relationships to offset petrochemical feedstock volatility that threatens formulation economics. For New Entrants and Emerging Players: Regional distributors without established primer and sealer logistics represent the most penetrable channel archetype, particularly in Minas Gerais where Betim and Contagem greenfield corridors lack mature supply infrastructure. Target powder clearcoat specification at commercial vehicle OEMs seeking zero-VOC compliance pathways, leveraging appliance and architectural technology transfer partnerships as the go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distribution specialists with underutilized logistics infrastructure and family ownership seeking liquidity. Long-term viability hinges on waterborne conversion execution and CONAMA compliance timing across the projection horizon. Monitor ANVISA substance reclassification timelines as the inflection indicator for formulation portfolio restructuring requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne Spray Booth Retrofit Partnership | Secures captive demand at ABC Paulista plants facing CONAMA compliance deadlines. |
| Captive Resin Supply Integration | Insulates margin pools from naphtha price volatility through backward acrylic precursor control. |
| INMETRO Durability Certification Investment | Unlocks premium pricing tiers tied to extended warranty programs at OEMs. |
| Minas Gerais Distribution Network Expansion | Captures emerging Betim and Contagem assembly corridor specification authority. |
| UV-Curable Sealer Technology Licensing | Reduces bake cycle energy intensity at throughput-focused commercial vehicle plants. |
Research Methodology
Direct dialogue with OEM platform engineers, Tier 1 supplier procurement leads, coating formulator R&D directors, and regional distribution channel managers grounded qualitative assessment, cross-referenced with ANVISA substance registration databases, CONAMA resolution filings, INMETRO certification records, and vehicle production statistics from IHS Markit. Bottom-up formulation demand modeling and top-down assembly plant consumption estimates were triangulated to validate volume assumptions.
Segment-level projections across basecoat, clearcoat, primer, and sealer categories were generated through technology adoption curves, regulatory compliance timelines, and OEM capex disclosure patterns across the analysis window. Waterborne conversion rates, UV-curable sealer penetration trajectories, and powder coating technology transfer velocities served as primary forecast inputs, with CAGRs derived from regression against historical coating intensity per vehicle unit.
Revisions become necessary when ANVISA substance reclassifications, CONAMA protocol amendments, or petrochemical feedstock price shocks materialize outside modeled scenarios. Practitioners should monitor regulatory filing deadlines and crude oil derivative spreads for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Nanocoatings Market
Coatings
Global Surface Protection Films Market
Coatings
Industrial Coatings Market
Coatings
Plastic-Coated Wires Market
Coatings
Glass Coatings Market
Coatings
Physical Vapor Deposition (PVD) Coatings Market
Coatings
Marine Deck Coatings Market
Coatings
Italy Protective Coatings Market
Coatings
South Korea Automotive OEM Coatings Market
Coatings
Asia-Pacific Superhydrophobic Coating Market
Coatings
Sustained Release Coatings Market
Coatings
Italy Automotive OEM Coatings Market
Coatings
Coating Equipment Market
Coatings
Protective Coatings Market
Coatings
Global Industrial Floor Coatings Market
Coatings
Extrusion Coating Market