
 Taiwan Semiconductor Materials Market | 2026-2036
Taiwan Semiconductor Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Taiwan Semiconductor Materials Market Intelligence
Aftermarket material reclamation and recycling services is fragmenting as smaller chemical processors enter the silicon wafer recovery segment. Sino-American Silicon Products anchors polysilicon and wafer supply through backward integration into ingot pulling. United Microelectronics navigates material qualification cycles by sustaining long-term contracts with specialty chemical houses. ASE Technology differentiates through advanced packaging material portfolios that extend beyond traditional front-end substrates.
Semiconductor materials encompass high-purity substrates, photoresists, slurries, and dielectric films engineered to atomic-level tolerances for integrated circuit fabrication, with specifications typically demanding impurity levels below one part per billion and particle counts controlled to Class 1 cleanroom standards. These materials enable transistor patterning, planarization, and electrical isolation across process nodes from mature 14-20nm to leading-edge sub-7nm architectures. Silicon wafers occupy the largest value pool due to their irreplaceable role as the crystalline foundation for all chip manufacturing, though photolithography materials command premium pricing as resolution requirements tighten. CMP slurries represent the fastest-growing product category as multi-patterning and 3D stacking architectures multiply polishing steps per wafer.
Taiwan's EPA enforces hazardous substance management rules that constrain solvent formulations and mandate waste stream documentation for material suppliers operating within industrial zones. The National Development Council's net-zero transition framework pressures foundries and their material vendors to disclose carbon intensity across supply chains, reshaping procurement criteria toward lower-emission chemical synthesis routes. BIS-aligned standards for semiconductor-grade materials further gate market access for imported precursors. Stakeholders must monitor how tightening environmental compliance intersects with process node migration to avoid stranded inventory in legacy material categories.
Market Dynamics
Sub-7nm process migration at Hsinchu Science Park foundries is compressing material qualification timelines while Taiwan's EPA hazardous substance rules and National Development Council carbon disclosure mandates simultaneously tighten purity benchmarks and supply chain transparency requirements for domestic chemical suppliers.
Growth Catalysts
- Advanced packaging proliferation:Foundry demand for 3D stacking architectures multiplies polishing steps per wafer, accelerating consumption of high-purity CMP slurries and photolithography resins.
- National Development Council net-zero pathway:Carbon intensity disclosure requirements for material vendors are reshaping procurement criteria toward lower-emission chemical synthesis routes.
- Hsinchu Science Park corridor concentration:TSMC and United Microelectronics anchor procurement volume for leading-edge nodes, creating localized demand density that justifies supplier co-location investments.
Market Restraints
- High-purity precursor import dependency:BIS-aligned standards gate market access for foreign-sourced semiconductor-grade materials, constraining formulation flexibility for domestic blenders.
- Polysilicon supply concentration:Ingot pulling and wafering capacity clusters with Sino-American Silicon Products and select Japanese suppliers, creating single-source vulnerability for substrate procurement.
- Atomic-scale impurity thresholds:Sub-7nm nodes demand impurity levels below one part per billion, eliminating marginal chemical processors from qualification pools and shrinking the vendor base.
Strategic Opportunities
- Southern Taiwan Science Park expansion:Kaohsiung-based foundry greenfield projects are diversifying demand geography beyond Hsinchu, opening qualification windows for new material entrants.
- Silicon wafer recovery segment:Aftermarket reclamation services fragment as smaller chemical processors enter wafer recycling, creating service-layer value capture beyond virgin material sales.
- Carbon accounting technology convergence:Integration of process control systems with emissions tracking platforms enables real-time carbon intensity verification for EPA and NDC compliance.
Industry Challenges
- Cleanroom engineering talent scarcity:Class 1 cleanroom operations require specialized contamination control expertise that outpaces vocational training program output in Taichung and Tainan technical institutes.
- Multi-patterning capex intensity:Photolithography material qualification for EUV resists demands dedicated pilot lines that strain mid-cap chemical house balance sheets.
- Cross-border formulation documentation:EPA hazardous substance management rules mandate waste stream traceability that conflicts with supplier confidentiality practices in Japanese and Korean precursor partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiwan Semiconductor Materials Market |
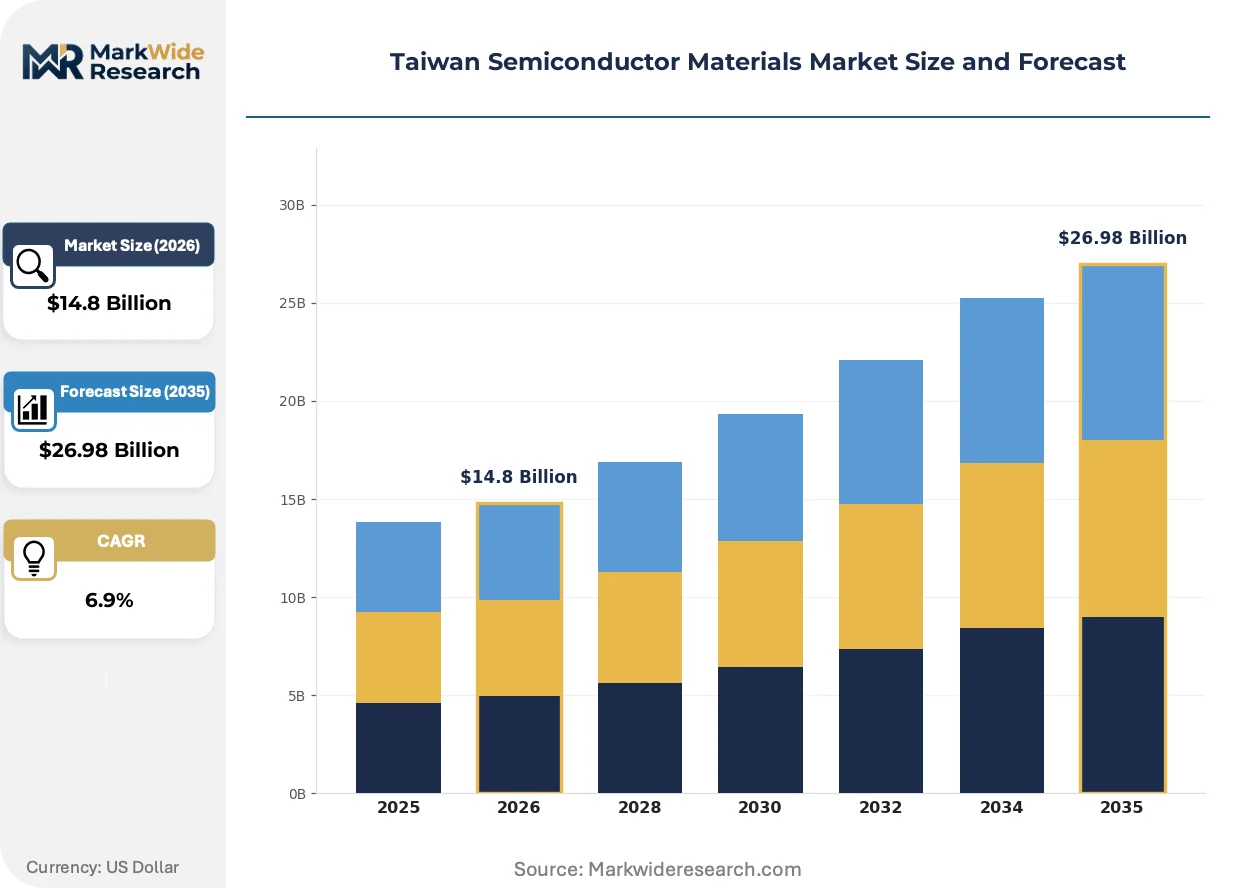
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Wafers, Photolithography Materials, CMP Slurries, Dielectrics Application: Consumer Electronics, Automotive Electronics, Industrial Automation, Medical Devices End User: Foundries, Integrated Device Manufacturers, Fabless Companies, Research Institutions Technology: Sub-7nm process, 7-10nm process, 10-14nm process, 14-20nm process |
| Companies Covered | Sino-American Silicon Products, Macronix International Co., Ltd., Taiwan Semiconductor Manufacturing Company Limited, Powerchip Semiconductor Manufacturing Corporation, Winbond, ASE Technology, Nanya Technology, Episil Technologies Inc., United Microelectronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiwan Semiconductor Materials Market Strategic Shifts & Innovations
Material synthesis and process control technologies are converging to address atomic-scale purity requirements while regulatory pressure accelerates carbon transparency integration into procurement systems.
EUV photoresist chemistry is hybridizing molecular architectures to achieve sub-14nm resolution without secondary patterning. Leading foundries in Hsinchu are qualifying these formulations for high-volume manufacturing ramps. This hybridization compresses the competitive window for legacy DUV resist suppliers unable to bridge the technology gap.
Taiwan's EPA hazardous substance management rules now mandate solvent formulation disclosure and waste stream documentation for suppliers operating within designated industrial zones. Material blenders must reconfigure reporting systems to capture batch-level chemical fate data. Specialty chemical houses serving the Hsinchu corridor face the steepest compliance cost absorption as they retrofit legacy inventory systems.
Long-term contracting behavior is consolidating procurement relationships as United Microelectronics and peer foundries extend material qualification cycles to secure supply continuity. Spot market purchasing for photolithography resins and CMP slurries contracts as buyers prioritize vendor stability over price flexibility. This pattern concentrates most visibly in sub-7nm node procurement where requalification costs deter supplier switching.
Taiwan Semiconductor Materials Market Segmentation
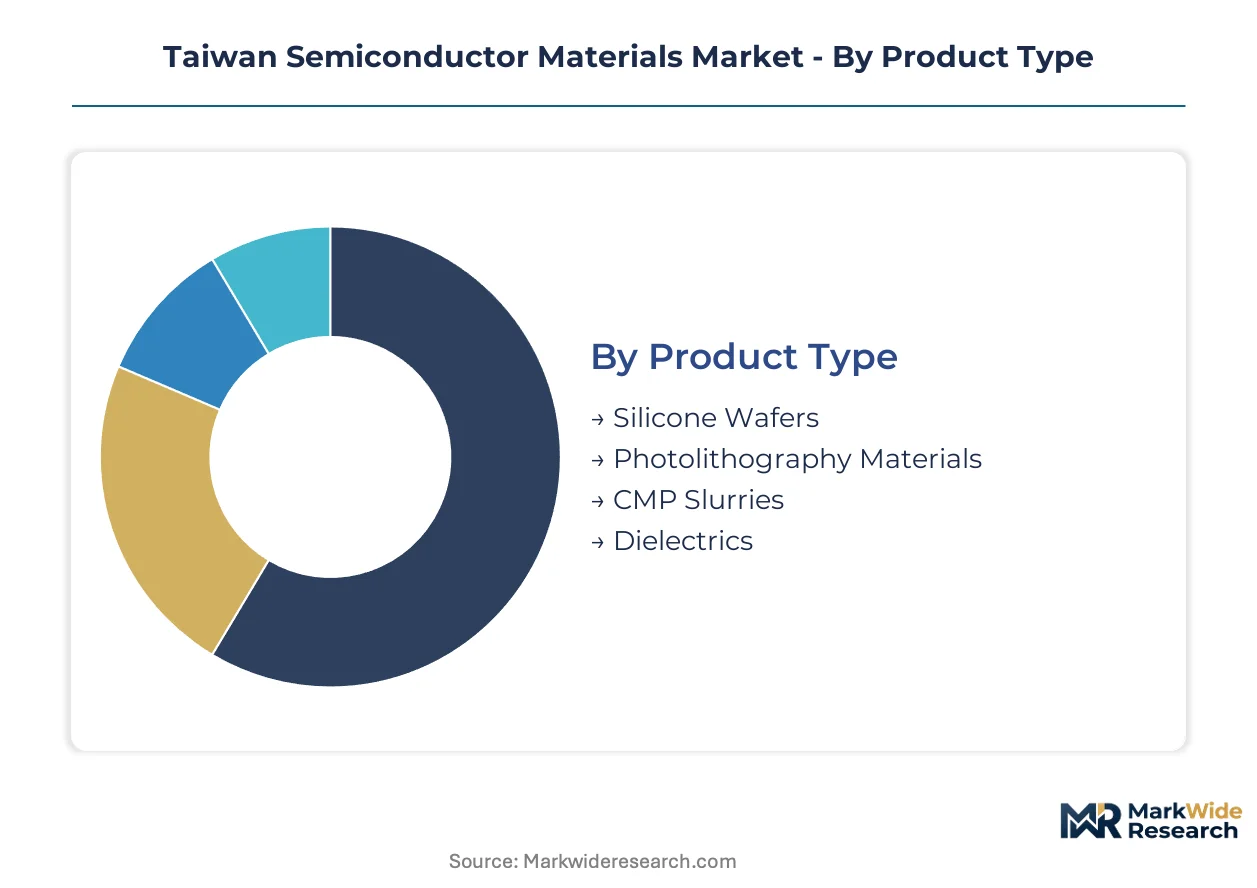
Semiconductor materials fragment across four distinct classification axes, each governing procurement behavior and margin structure differently. Product type determines purity specifications and supplier qualification barriers. Application and end-user categories dictate volume cadence and inventory turnover velocity. Technology node segmentation creates the steepest tiering in pricing and technical service intensity.
Product Type:
Inventory velocity varies dramatically across material categories, with consumables turning monthly against substrate purchases extending across quarters.
- Silicone Wafers:Single-crystal silicon ingots sliced to atomic-level flatness specifications serve as the irreplaceable structural foundation for all chip fabrication. Procurement concentrates at TSMC and United Microelectronics facilities in Hsinchu Science Park, where sub-7nm qualification cycles extend to 18 months and lock in supply continuity clauses. Sino-American Silicon Products anchors domestic ingot pulling capacity, though Japanese suppliers retain critical 300mm advanced substrate share.
- Photolithography Materials:EUV and DUV photoresists, antireflective coatings, and developers enable transistor patterning at resolution thresholds below 10 nanometers. Demand clusters at Hsinchu foundries migrating to sub-7nm nodes, where resist consumption per wafer layer multiplies with multi-patterning architectures and EPA hazardous substance documentation requirements tighten formulation disclosure.
- CMP Slurries:High-purity colloidal suspensions for chemical mechanical planarization.
- Dielectrics:Low-k and ultra-low-k interlayer films providing electrical isolation.
Silicone wafers anchor the volume base while CMP slurries gain share at the steepest rate.
Application:
End-use markets stratify by qualification rigor, with automotive and medical segments imposing the longest certification timelines.
- Consumer Electronics:Smartphones, tablets, and wearables drive the largest absolute wafer consumption through foundry outsourcing models. TSMC's Apple and Qualcomm allocations in Hsinchu concentrate demand for leading-edge photolithography materials, though volume cyclicality creates inventory volatility for slurry and resist suppliers.
- Automotive Electronics:ADAS processors, power management ICs, and sensor fusion chips demand AEC-Q100 qualification standards that extend material validation to 24 months. Foundry procurement teams in Southern Taiwan Science Park prioritize supplier longevity over spot pricing as vehicle platform lifecycles lock in substrate specifications for decade-long production runs.
- Industrial Automation:Motor controllers, PLCs, and robotics chipsets.
- Medical Devices:Imaging systems, implantable monitors, and diagnostic equipment.
Consumer electronics anchors the volume base while automotive electronics expands most quickly as EV platform semiconductor content multiplies.
End User:
Customer type determines contract structure, with foundries favoring long-term supply agreements against spot purchasing by research institutions.
- Foundries:Pure-play contract manufacturers including TSMC and United Microelectronics dominate procurement volume through consolidated Hsinchu corridor purchasing. Multi-year slurry and resist contracts with penalty clauses for supply interruption now extend through 2028 as sub-7nm node ramps consume qualification resources that deter supplier switching.
- Integrated Device Manufacturers:Vertically integrated chipmakers with captive fabrication.
- Fabless Companies:Design houses outsourcing production to foundry partners.
- Research Institutions:Universities and national laboratories.
Foundries anchor the volume base while fabless companies climb the fastest as design specialization accelerates outsourcing penetration.
Technology:
Process node migration creates the sharpest segmentation in material purity requirements and supplier technical capability thresholds.
- Sub-7nm process:Leading-edge transistor architectures at 5nm and below demand impurity levels below one part per billion and Class 1 cleanroom handling throughout the supply chain. TSMC's N3 and N2 ramps in Hsinchu Science Park concentrate global consumption of EUV photoresists and advanced CMP slurries, with National Development Council carbon disclosure mandates now layering emissions verification onto existing purity benchmarks.
- 7-10nm process:Mature leading-edge nodes for high-performance computing and networking chips.
- 10-14nm process:Mid-range mobile and consumer application processors.
- 14-20nm process:Mature nodes for IoT, display drivers, and power management.
14-20nm process nodes anchor the volume base while sub-7nm process technology gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Taiwan's Hsinchu corridor show the least price sensitivity for sub-7nm materials, while mature-node foundries in Southern Taiwan Science Park negotiate harder on CMP slurry contracts. This elasticity gradient shapes supplier investment patterns across the island's fabrication clusters.
Hsinchu Science Park
TSMC and United Microelectronics drive procurement for EUV photoresists and advanced CMP slurries at sub-7nm nodes. Taiwan's EPA hazardous substance management rules mandate solvent formulation disclosure for all suppliers operating within this zone. The corridor concentrates global consumption of atomic-purity materials as N3 and N2 process ramps absorb qualification resources.
Southern Taiwan Science Park
Kaohsiung-based foundry greenfield projects diversify demand geography beyond Hsinchu, opening qualification windows for new material entrants. The National Development Council's net-zero pathway pressures vendors here to disclose carbon intensity across supply chains. Automotive electronics procurement for EV platform chips prioritizes supplier longevity over spot pricing.
Taichung Precision Machinery Cluster
Specialized equipment and material handling systems suppliers serve the upstream chemical synthesis segment. Taiwan's vocational training institutes struggle to output sufficient Class 1 cleanroom engineering talent for operations here. The cluster supports contamination control infrastructure for wafer processing across western Taiwan.
Tainan Technology Industrial Park
Legacy node fabrication for IoT and display driver ICs sustains demand for 14-20nm process materials. EPA waste stream documentation requirements apply to chemical blenders supplying mature-node foundries. The park anchors volume-based procurement for silicon wafers and dielectric films with shorter qualification cycles.
Taiwan Semiconductor Materials Market Key Industry Players
Backward-integrated substrate specialists and specialty chemical houses split the market into distinct capability tiers. Three strategic archetypes dominate: polysilicon-to-wafer integrators controlling crystalline supply chains, photolithography material formulators with EUV chemistry portfolios, and advanced packaging material providers extending beyond front-end substrates. Competitive moves concentrate on long-term contract consolidation with foundry procurement teams and co-location investments adjacent to Hsinchu corridor demand.
Among Taiwan-based suppliers, Sino-American Silicon Products anchors polysilicon and wafer supply through captive ingot pulling capacity. ASE Technology occupies a position within the advanced packaging material tier, extending portfolios beyond traditional substrate categories. United Microelectronics represents the foundry-side procurement consolidation pattern, sustaining extended qualification cycles with specialty chemical houses to secure supply continuity through 2028.
| Leading Market Players |
|---|
| Sino-American Silicon Products |
| Macronix International Co., Ltd. |
| Taiwan Semiconductor Manufacturing Company Limited |
| Powerchip Semiconductor Manufacturing Corporation |
| Winbond |
| ASE Technology |
| Nanya Technology |
| Episil Technologies Inc. |
| United Microelectronics |
| Others |
Cost & Logistics Intelligence
The Kaohsiung-Taichung freight corridor's rising logistics costs amplify pricing power for Hsinchu-based suppliers while compressing margins for Southern Taiwan entrants. Sub-7nm material premiums widen against mature-node commoditization as TSMC procurement teams leverage volume concentration to extract service-level concessions.
Pricing Analysis
Aftermarket silicon wafer reclamation services generate recurring revenue streams that extend lifetime value beyond virgin material sales. Three-tier pricing structure across EUV-grade premium, DUV-standard, and mature-node economy levels stratifies foundry procurement contracts. Cost compression in 14-20nm slurry tiers intensifies because spot-market liquidity invites aggressive second-source bidding. Automotive electronics buyers in Southern Taiwan Science Park show least price sensitivity due to decade-long platform lock-ins, while IoT foundries in Tainan negotiate hardest on dielectric film contracts.
Supply Chain Analysis
TSMC and United Microelectronics hold captive foundry capacity that dictates upstream chemical house investment patterns. Taiwan, South Korea, and Japan anchor high-purity precursor supply, with Japanese suppliers retaining critical EUV resist share. The supply chain draws from polysilicon ingots, photoresist monomers, and colloidal silica abrasives. Single-source vulnerability clusters in 300mm advanced substrate pulling capacity. Distribution runs through direct foundry contracts with penalty clauses for supply interruption, bypassing spot-market intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Taiwan's semiconductor materials sector sits in a cyclical recovery phase as sub-7nm foundry capex rebounds from inventory digestion. Apple and Qualcomm allocation ramps at TSMC N3 drive demand inflection.
For Market Incumbents: Entrench through backward integration into ingot pulling to offset polysilicon supply concentration risk. Lock in multi-year slurry and resist contracts with carbon disclosure riders before EPA documentation requirements tighten. Priority lever rests on co-location investments adjacent to Hsinchu corridor demand density.
For New Entrants and Emerging Players: Build out aftermarket wafer reclamation capabilities in Southern Taiwan Science Park where qualification windows for greenfield foundry projects remain open. Target automotive electronics material certification where AEC-Q100 timelines deter incumbent switching. Go-to-market angle centers on real-time carbon tracking integration for NDC compliance.
For Investors and Strategic Acquirers: Specialty chemical houses with EUV resist pilot lines and EPA-compliant documentation systems represent acquisition targets with defensive moats. Long-term viability frames around 5-10 year foundry node migration roadmaps. Signal to watch: TSMC N2 ramp schedules and associated qualification resource allocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Sino-American Silicon Products' captive ingot capacity reduces substrate supply vulnerability for foundry procurement teams. |
| EUV Resist Pilot Line Investment | Dedicated qualification infrastructure enables foundry partnership tiers inaccessible to mid-cap chemical houses. |
| Carbon Accounting Platform Integration | Real-time emissions verification satisfies National Development Council disclosure mandates for Hsinchu corridor suppliers. |
| Long-term Supply Agreement Extension | Penalty-clause contracts through 2028 lock in slurry and resist volume commitments at United Microelectronics. |
| Southern Taiwan Co-location | Kaohsiung-based facilities capture automotive electronics procurement prioritizing supplier longevity over spot pricing. |
Research Approach
Operator-level perspectives from foundry procurement directors, specialty chemical R&D heads, EPA compliance officers, and cleanroom engineering managers anchored the qualitative base. Primary fieldwork combined with secondary validation from Taiwan EPA hazardous substance filings, National Development Council net-zero pathway documents, foundry capex disclosures, and semiconductor trade flow data. Bottom-up material consumption modeling triangulated against top-down foundry capacity forecasts.
Scenario-bracketing around sub-7nm node migration pace, EPA enforcement intensity, and carbon disclosure adoption curves bounded projections across the analysis window. Segmentation dimensions spanned product type purity tiers, application qualification rigor, end-user contract structures, and technology node purity thresholds. CAGRs derived from wafer start forecasts, material consumption intensity curves, and pricing tier trajectories. Foundry capital equipment spend patterns and resist layer counts per process node served as industry-specific forecast inputs.
Stress conditions across EUV adoption delays, polysilicon supply disruptions, and EPA regulatory acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about foundry node migration timelines and regulatory implementation cadence. Semiconductor cycle turns, geopolitical export controls, and cleanroom engineering talent scarcity constitute primary revision risks. Quarterly review of foundry capex guidance and EPA enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Electronic Ceramics Market
Semiconductor Material
PV Module Encapsulant Film Market
Semiconductor Material
Liquid Film Photoresist Market
Semiconductor Material
Global Inorganic Scintillators Market
Semiconductor Material
Big Size Synthetic Diamond Market
Semiconductor Material
Compound Semiconductor Materials Market
Semiconductor Material
Zinc Oxide Nanoparticles Market
Semiconductor Material
Solar Silicon Ingots Market
Semiconductor Material
Gallium Trichloride Market
Semiconductor Material
LED Materials Market
Semiconductor Material
Polymethylhydrosiloxane Market
Semiconductor Material
DCB and AMB Substrate Market
Semiconductor Material
Synthetic Single Crystal Diamond Market
Semiconductor Material
Global Semiconductor Epoxy Mold Compound Market
Semiconductor Material
Electronic Film Market
Semiconductor Material
OLED Materials Market